
 Rolled Oats Market | 2026-2036
Rolled Oats Market Size, Share, and Industry Trends Forecast 2026-2036
Rolled Oats Market Analytics
Aftermarket service revenue from oat milling equipment maintenance and spare-part contracts is reshaping profit pools across the value chain. Quaker Oats Company leverages its century-old brand equity to dominate North American retail shelf space. General Mills anchors its position through backward integration into grain sourcing and regional milling infrastructure. Bob's Red Mill Natural Foods differentiates via specialty organic certifications and stone-ground heritage processes that command premium positioning.
Rolled oats are whole oat groats steamed and flattened through steel rollers to a thickness of 0.3 to 0.5 millimeters, yielding a flake that cooks in five to fifteen minutes while retaining the bran layer and endosperm for dietary fiber content; this processing method produces the staple raw material for hot cereal, granola, and baked applications requiring structural integrity during hydration. The organic product type segment captures widening margin pools as certification premiums persist across European and North American retail channels, while conventional rolled oats sustain volume leadership in foodservice and industrial bakery procurement. Instant oats within the product type classification accelerate in Asian markets where single-serve convenience formats align with urban consumption patterns.
The FDA enforces whole-grain health claim standards and allergen labeling under FALCPA, while the USDA Organic seal governs certification thresholds that shape premium pricing architecture; the EU Green Deal's Farm to Fork strategy tightens pesticide residue limits and carbon accounting for imported grain, altering sourcing economics for European processors. Stakeholders must monitor evolving clean-label mandates and carbon-border adjustment mechanisms to secure supply continuity and defend margin structures.
Market Dynamics
Clean-label mandates from the FDA and EU Green Deal are compressing supply chains toward certified organic sourcing, forcing millers to reconfigure procurement networks and absorb certification premiums that reshape margin distribution across the value chain.
Growth Catalysts
- USDA Organic Certification Thresholds:Premium pricing architecture in North American retail channels incentivizes millers to convert conventional processing lines, widening margin pools for certified operators.
- Breakfast Cereal Manufacturers:Product line expansion into whole-grain morning options concentrates demand for structural flakes that withstand hydration without disintegration.
- Urban Asian Markets:Single-serve convenience formats accelerate instant oat adoption where compressed cooking time aligns with dense metropolitan consumption rhythms.
Market Restraints
- Grain Input Volatility:Weather-driven oat harvest fluctuations in Canada and Russia transmit price instability downstream to milling operations with limited hedge coverage.
- EU Carbon Border Adjustments:Import grain faces escalating compliance costs as the Farm to Fork strategy tightens pesticide residue limits and embedded carbon accounting.
- Gluten-Free Substitutes:Quinoa and buckwheat flakes capture label-sensitive consumers seeking alternative whole-grain textures without allergen cross-contamination risk.
Strategic Opportunities
- Stone-Ground Heritage Positioning:Premium differentiation through certified organic supply chains and artisanal processing commands shelf-space allocation in health-focused retail formats.
- Industrial Bakery Procurement:Structural flake integrity requirements in granola and energy-bar applications open volume contracts outside traditional breakfast channels.
- Foodservice Bulk Formats:Unbranded rolled oats for institutional kitchens and commercial bakeries sustain steady offtake insulated from retail promotional cycles.
Industry Challenges
- Allergen Cross-Contamination Protocols:FALCPA-mandated facility segregation imposes capital-intensive line separation and extended sanitation cycles between product runs.
- Legacy Equipment Integration:Retrofitting steel roller mills for organic certification compliance requires extended downtime and specialized mechanical expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rolled Oats Market |
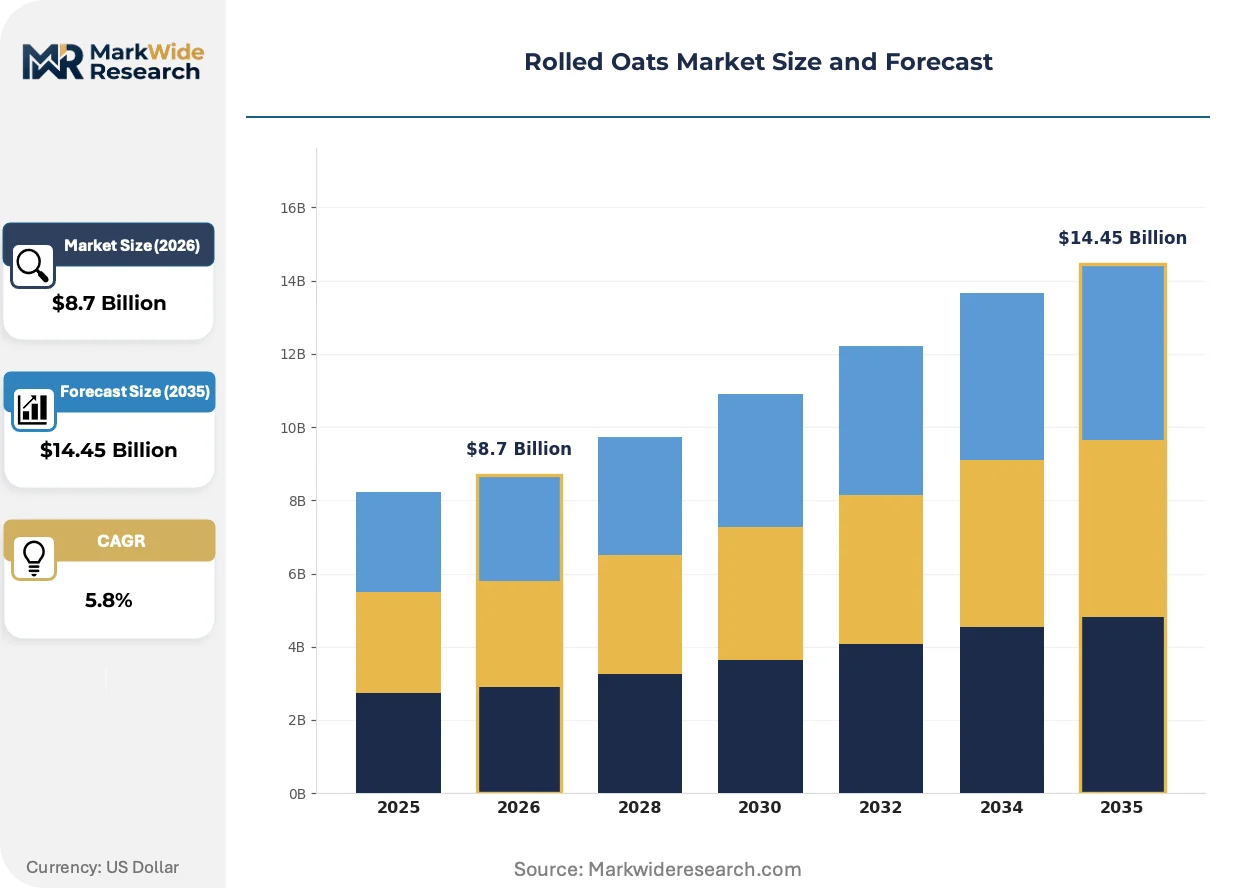
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Instant, Steel-Cut End Use: Food Industry, Bakeries, Breakfast Cereal, Snacks Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Wholesale Packaging Type: Bags, Boxes, Pouches, Bulk |
| Companies Covered | Quaker Oats Company, General Mills, The Kellogg Company, Bob's Red Mill Natural Foods, Nature's Path Foods, PepsiCo, Nestlé, Grain Millers, Avena Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rolled Oats Market Evolving Landscape
Digital traceability platforms and precision agriculture tools are penetrating oat supply chains, compressing the information asymmetry between farm gate and retail shelf while enabling real-time quality verification.
Blockchain-enabled grain provenance tracking is virtualizing the documentation layer of organic certification, eliminating paper-based audit trails. Large-scale cooperatives in the Dakotas and Saskatchewan are piloting distributed ledger systems that verify field-level pesticide application records. This technology is virtualizing compliance costs by reducing third-party auditor site visits and accelerating EU Green Deal import clearance timelines.
The EU Green Deal's Farm to Fork strategy tightens maximum residue limits for glyphosate and neonicotinoids in imported grain, forcing non-European suppliers to adopt integrated pest management protocols. European millers now face mandatory carbon footprint disclosure for supply chain scope-three emissions. Organic product lines bear the steepest compliance burden, though certification premiums partially offset traceability infrastructure investments.
Health-focused retail formats are consolidating shelf-space allocation around clean-label clusters that privilege single-ingredient whole grains. Club stores and natural-channel grocers in the United States are displacing conventional supermarkets as volume gatekeepers for premium oat positioning. This channel rotation concentrates buyer power among a handful of private-label program managers who dictate specification standards and audit frequency.
Rolled Oats Market Segmentation
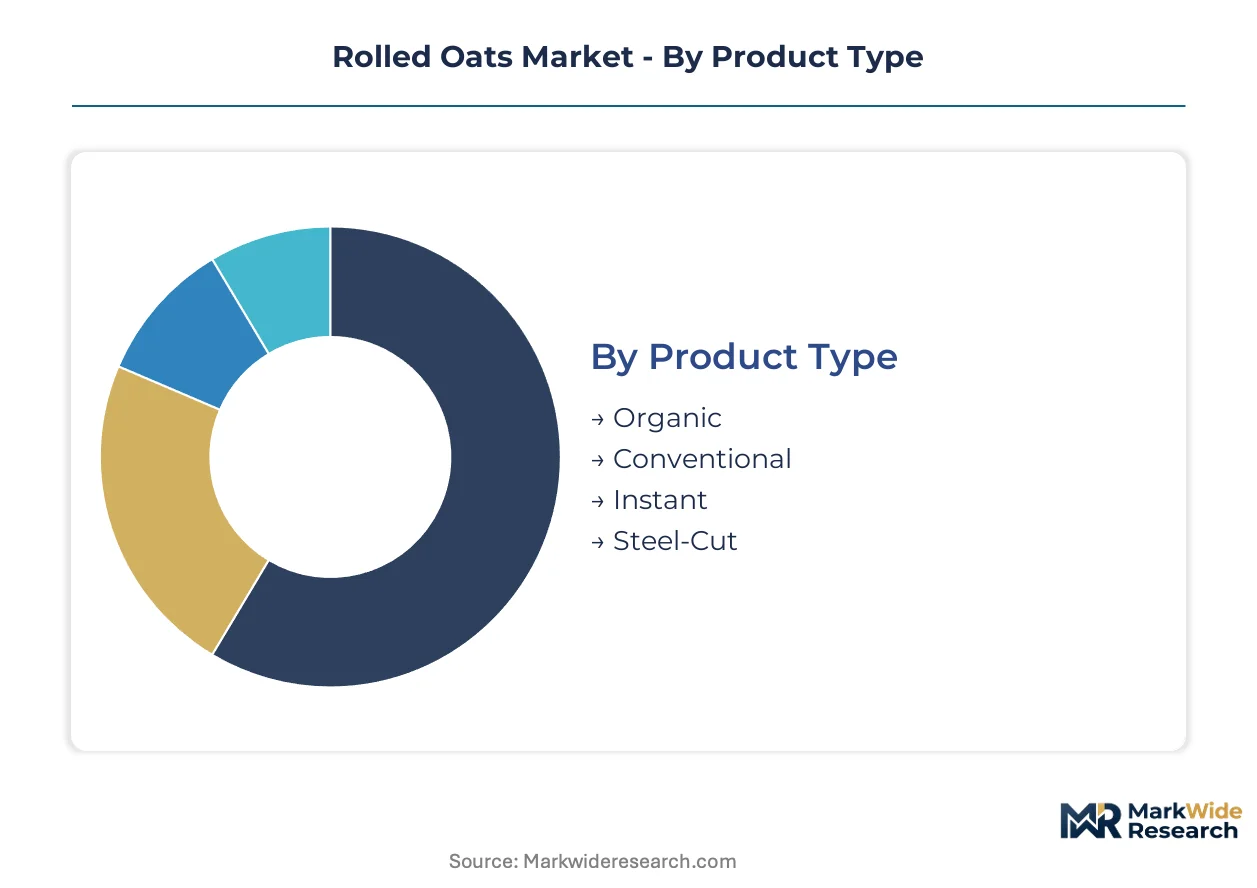
Segmentation in the rolled oats market reveals how certification premiums, convenience formats, and channel access reshape procurement patterns across consumer and industrial buyers. Understanding these divides exposes where margin pools concentrate and where volume contracts stabilize revenue.
Product Type:
Cost tier differentiation separates certified organic supply chains from conventional milling operations, with processing intensity further stratifying price positioning.
- Organic:Whole oat groats sourced from certified fields command shelf-space premiums in health-focused retail formats. USDA Organic and EU Green Deal compliance requirements concentrate demand among European and North American consumers willing to absorb certification markups.
- Conventional:Standard rolled oats sustain volume leadership through foodservice procurement and industrial bakery contracts where price sensitivity dominates specification standards.
- Instant:Pre-cooked flakes compressed for single-serve convenience accelerate in urban Asian markets where cooking time compression aligns with metropolitan consumption rhythms.
- Steel-Cut:Irregular oat pieces produced through steel blade cutting rather than rolling deliver chewier texture profiles for specialty hot cereal applications.
Conventional commands the established base. The steepest expansion runs through Instant.
End Use:
Application requirements determine flake thickness tolerances, hydration stability needs, and whether structural integrity or rapid cooking takes priority in specification standards.
- Breakfast Cereal:Hot cereal manufacturers demand flakes that withstand hydration without disintegration, requiring precise roller gap calibration during milling. Private-label penetration in the United States concentrates procurement volume among retail program managers who dictate audit frequency and specification tolerances.
- Bakeries:Granola and energy-bar applications require structural flake integrity that survives binding processes and baking temperatures without pulverization.
- Food Industry:Industrial processors source bulk formats for ingredient integration into prepared foods where oat functionality replaces modified starches.
- Snacks:Granola bars and cluster formats prioritize binding adhesion and crunch retention through controlled moisture content in raw material procurement.
Breakfast Cereal anchors volume demand. Bakery applications are climbing the fastest.
Distribution Channel:
Customer type and purchase scale determine whether branded retail packaging, unbranded bulk formats, or direct-to-consumer logistics govern fulfillment economics.
- Supermarkets:Conventional grocery retail sustains high-velocity turnover for standard rolled oat SKUs with promotional cycle dependency.
- Health Food Stores:Natural-channel grocers consolidate shelf-space allocation around clean-label clusters privileging single-ingredient whole grains and certified organic positioning.
- Online Retail:Subscription models and direct-to-consumer fulfillment enable specialty mills to bypass traditional distributor margins.
- Wholesale:Institutional procurement for commercial kitchens and foodservice operations sources unbranded bulk formats insulated from retail promotional volatility.
Supermarkets retain the volume base. Health Food Stores gain share fastest.
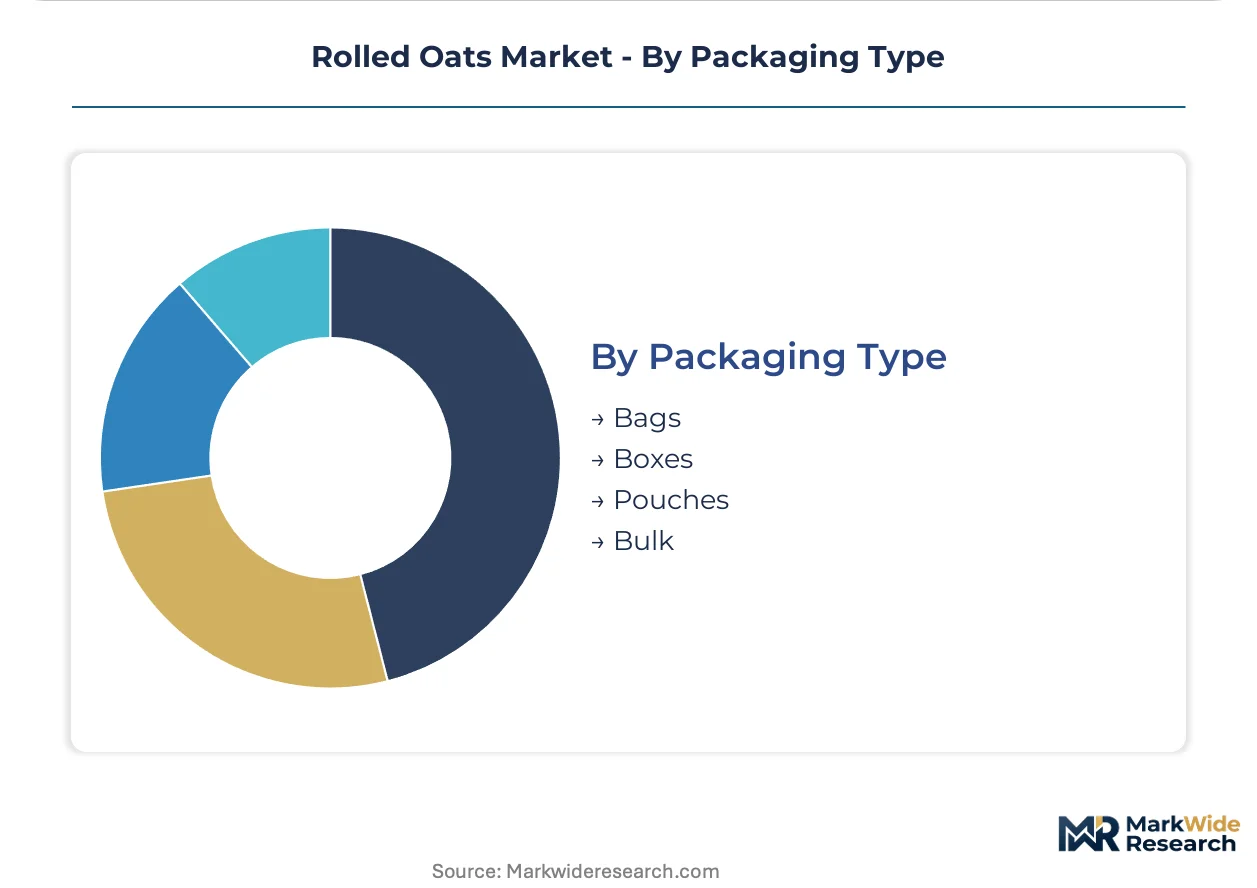
Packaging Type:
Volume scale and handling requirements separate consumer-facing retail units from foodservice and industrial procurement formats.
- Bulk:Unpackaged oats for institutional kitchens and commercial milling operations minimize per-unit packaging cost and support just-in-time inventory management.
- Bags:Flexible packaging dominates standard retail SKUs with resealability features and shelf-stable barrier properties.
- Boxes:Rigid cartons signal premium positioning in breakfast cereal aisles while protecting flake integrity through distribution handling.
- Pouches:Single-serve and small-format convenience packaging targets urban consumers with limited storage space and portion-controlled consumption patterns.
Bulk formats command industrial procurement. Pouches show the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian prairie provinces and the United States' northern tier dominate oat cultivation, concentrating milling infrastructure within a tight radius of primary grain elevators. This geographic compression shapes procurement economics for processors across North America and Europe.
United States
Private-label penetration and health-focused retail formats accelerate category velocity in the breakfast cereal aisle. The FDA enforces whole-grain health claim standards and allergen labeling under FALCPA, reshaping facility design requirements. Minneapolis-St. Paul anchors North American milling capacity with legacy infrastructure serving both branded and foodservice channels.
Canada
Weather-driven harvest fluctuations in Saskatchewan and Alberta transmit price instability downstream to milling operations with limited hedge coverage. Health Canada and PMRA regulate pesticide residue limits that govern export eligibility into European markets. Winnipeg and the Prairie Provinces concentrate grain handling infrastructure within elevator networks that supply cross-border processors.
Germany
Clean-label regulations mandate transparent ingredient sourcing and allergen disclosure, pushing mills toward certified supply chains. The EU Green Deal's Farm to Fork strategy tightens pesticide residue limits and carbon accounting for imported grain. Hamburg's port facilities serve as the primary entry point for North American oat imports destined for Central European mills.
China
Single-serve convenience formats accelerate instant oat adoption where compressed cooking time aligns with dense metropolitan consumption rhythms in Shanghai and Beijing. SAMR and GB standards govern food safety compliance for imported grain. Yangtze River Delta processors are expanding capacity to meet urban demand for Western-style breakfast options.
Australia
Structural flake integrity requirements from industrial bakery procurement open volume contracts for export-oriented milling operations. The TGA and FSANZ regulate gluten contamination thresholds that determine eligibility for health-focused retail channels. Victoria and New South Wales concentrate domestic oat production within farming regions that supply both local processors and Asian export markets.
Rolled Oats Market Competitive Landscape
Heritage-brand conglomerates and specialty organic millers split the market into distinct competitive spheres with minimal overlap in procurement channels. Consolidation pressure concentrates shelf-space allocation among three to four parent entities controlling multiple label portfolios. Strategic archetypes include backward-integrated grain originators, certified organic specialists, and private-label contract manufacturers. Dominant competitive moves involve regional milling infrastructure acquisition and clean-label certification portfolio expansion.
Within the heritage-brand tier, Quaker Oats Company and General Mills occupy positions that exemplify scale-driven distribution economics, while Bob's Red Mill Natural Foods represents the specialty-certified archetype. Quaker leverages century-old brand equity to dominate North American retail shelf space. General Mills anchors its position through upstream control over grain sourcing and regional milling infrastructure. Bob's Red Mill differentiates via specialty organic certifications and stone-ground heritage processes that command premium positioning in health-focused retail formats.
| Leading Market Players |
|---|
| Quaker Oats Company |
| General Mills |
| The Kellogg Company |
| Bob's Red Mill Natural Foods |
| Nature's Path Foods |
| PepsiCo |
| Nestlé |
| Grain Millers |
| Avena Foods |
| Others |
Value Network & Pricing Analysis
EU carbon border adjustment exposure determines both the premium-to-conventional pricing spread and the geographic reconfiguration of milling capacity toward certified supply chains. Certification premiums widen as European import compliance costs escalate, forcing procurement networks to absorb traceability investments or surrender margin to domestic competitors.
Pricing Analysis
The EU Green Deal's Farm to Fork strategy dictates the pricing tier structure across European and North American retail channels. Three-tier pricing structure across premium, standard, and economy levels separates certified organic from conventional and instant formats, with USDA Organic and EU organic seals commanding shelf-space markups. Cost compression in the conventional tier is intensifying because foodservice procurement concentrates buyer power among institutional program managers. Industrial bakery buyers exhibit the highest price sensitivity, while health-focused retail channels absorb certification premiums with minimal elasticity.
Supply Chain Analysis
Canadian prairie provinces and the United States' northern tier anchor upstream oat cultivation, with Saskatchewan, Alberta, and North Dakota concentrating grain elevator infrastructure within tight radius of primary milling operations. Steel roller equipment, organic certification audit trails, and carbon footprint disclosure systems constitute critical input dependencies. Single-source vulnerability runs through weather-driven harvest fluctuations in the Canadian prairies that transmit price instability downstream. Distribution runs through health-focused retail formats and private-label program managers who dictate specification standards and audit frequency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rolled oats market sits in early-cycle expansion as clean-label mandates penetrate foodservice procurement and industrial bakery applications beyond traditional breakfast channels. USDA Organic certification adoption and EU Green Deal compliance requirements accelerate penetration into institutional segments previously dominated by conventional supply.
For Market Incumbents: Entrench position through backward integration into certified grain sourcing in the Dakotas and Saskatchewan, securing captive supply as EU carbon border adjustments tighten. Acquire regional milling infrastructure to consolidate capacity and absorb certification premiums through scale. Quinoa and buckwheat substitutes threaten label-sensitive consumers; defend via stone-ground heritage positioning and transparent supply chain documentation. For New Entrants and Emerging Players: Urban Asian markets for instant oat formats offer the most penetrable white-space opportunity, where single-serve convenience aligns with metropolitan consumption rhythms in Shanghai and Beijing. Target industrial bakery procurement for granola and energy-bar applications requiring structural flake integrity. Bypass traditional distributor margins through direct-to-consumer subscription models and digital traceability platforms that verify field-level provenance. For Investors and Strategic Acquirers: Certified organic specialists with established EU export clearance capabilities represent the highest-conviction acquisition archetype for long-term viability across the five-to-ten-year window. Monitor carbon border adjustment implementation timelines and integrated pest management adoption rates across Canadian prairie cooperatives as inflection indicators for sourcing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Grain Sourcing | Captive supply from Saskatchewan and Dakota cooperatives secures EU Green Deal compliance and defends margin against carbon border cost escalation. |
| Stone-Ground Heritage Process Investment | Bob's Red Mill-style differentiation commands premium shelf-space allocation in health-focused retail formats displacing conventional supermarkets. |
| Blockchain-Enabled Provenance Tracking | Distributed ledger systems from Dakota cooperatives virtualize organic certification costs and accelerate EU import clearance timelines. |
| Industrial Bakery Contract Expansion | Granola and energy-bar volume contracts outside breakfast channels stabilize revenue insulated from retail promotional cycles. |
| Instant Oat Format Localization for Asian Markets | Pre-cooked flake capacity expansion in Yangtze River Delta processors captures urban convenience demand in Shanghai and Beijing. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with oat mill executives, grain elevator operators, retail category buyers, and foodservice procurement directors; and secondary validation through USDA organic certification databases, EU Farm to Fork strategy documentation, FDA FALCPA guidance filings, and Canadian grain trade statistics. Bottom-up volume modeling triangulated against top-down value estimates from customs records and retail audit data.
Forecast inputs considered product type segmentation across organic, conventional, instant, and steel-cut formats; end-use application requirements from breakfast cereal, bakery, food industry, and snack channels; and distribution channel dynamics spanning supermarkets, health food stores, online retail, and wholesale procurement. CAGRs were derived through trend extrapolation of certification adoption rates and channel rotation patterns, with oat harvest volatility and carbon border adjustment implementation timelines as sensitivity variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by quinoa and buckwheat flake specialists or accelerated EU pesticide residue limit tightening would shift outcomes beyond modeled ranges. Cross-checking against Health Canada and PMRA export eligibility data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
South Africa Grain Market
Grains
Whole-Wheat Flour Market
Grains
Grain Roller Market
Grains
United States Rice Market
Grains
Sorghum Flour Market
Grains
White Beans Market
Grains
United States Maize Market
Grains
Barley Grass Market
Grains
Asia Pacific Wheat Protein Market
Grains
Global Wheat Market
Grains
Corn Silage Market
Grains
Chickpeas Market
Grains
Millets Market
Grains
Grain Bins Market
Grains
Global Cassava Flour Market
Grains
Argentina Maize Market