
 GCC Generic Injectables Market | 2026-2036
GCC Generic Injectables Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Generic Injectables Market Intelligence
Glass-to-plastic container conversion is consolidating cost structures across the GCC Generic Injectables landscape. Fresenius Kabi leverages European manufacturing scale to supply prefilled syringe formats into Gulf hospital chains. Hikma Pharmaceuticals anchors regional production through its UAE-based sterile injectable facility. Sandoz International GmbH competes on oncology portfolio breadth, while Neopharma specializes in localized fill-finish operations for government tenders.
Generic injectables are sterile liquid or lyophilized drug products administered parenterally, requiring aseptic processing, endotoxin control, and proven bioequivalence to reference-listed drugs; they serve critical therapeutic areas where oral bioavailability is inadequate or patient compliance demands direct systemic delivery. Intravenous administration routes dominate hospital procurement volumes across the Gulf, while monoclonal antibodies represent the fastest-expanding product type as oncology biosimilars penetrate Saudi and Emirati formularies. Hormone therapies sustain stable demand through diabetes and endocrinology clinics, where patient volumes are rising alongside non-communicable disease prevalence.
The SFDA enforces bioequivalence and GMP standards for all sterile injectable registrations in Saudi Arabia, while MOHAP in the UAE mandates serialization and cold-chain validation for imported biologics. Both regulators are aligning with GCC-wide harmonization initiatives that streamline multi-country product approvals. Manufacturers must monitor evolving pharmacovigilance reporting requirements and local content thresholds that increasingly favor regional fill-finish partners over pure import models.
Market Dynamics
Government-mandated health insurance expansion across Saudi Arabia and the UAE is forcing hospital procurement departments to widen formulary access for biosimilar injectables, compressing procurement cycles and intensifying price competition among sterile product suppliers.
Growth Catalysts
- Mandatory Health Insurance Frameworks:Saudi Arabia's Council of Cooperative Health Insurance and the UAE's health authority mandates are expanding patient coverage for parenteral therapies, directly increasing hospital procurement volumes for oncology and diabetes injectables.
- SFDA Bioequivalence Harmonization:The Saudi Food and Drug Authority's tightened documentation requirements for imported sterile products are accelerating registrations of pre-qualified European and Indian manufacturers, shortening time-to-market for generic alternatives.
- Tertiary Hospital Expansion:Saudi Arabia's healthcare infrastructure investments in Riyadh and Jeddah are creating dedicated oncology centers with centralized pharmacy compounding units that favor high-volume injectable contracts.
Market Restraints
- Glass Vial Supply Concentration:European borosilicate glass manufacturers control over 70% of pharmaceutical-grade vial supply to GCC markets, exposing fill-finish operations to freight cost volatility and currency fluctuation risks.
- Cold-Chain Infrastructure Gaps:Temperature-controlled distribution networks between Dubai's Jebel Ali port and secondary cities in Oman and Bahrain remain underdeveloped, limiting biologics penetration outside major metropolitan clusters.
- MOHAP Serialization Compliance:The UAE Ministry of Health and Prevention's track-and-trace mandates for imported biologics impose IT system upgrade costs on distributors that smaller regional players cannot absorb.
Strategic Opportunities
- Kuwait and Qatar Market Entry:These markets show 40% lower biosimilar penetration than Saudi Arabia, presenting first-mover advantages for manufacturers with established GCC distribution partnerships.
- Prefilled Syringe Format Conversion:Hospital pharmacy automation investments are creating demand for ready-to-administer formats that reduce nursing time and medication error rates in high-volume infusion centers.
- Local Fill-Finish Partnerships:Saudi Arabia's local content thresholds for government tenders favor joint ventures with regional sterile manufacturing facilities over pure import models.
Industry Challenges
- Aseptic Processing Technician Shortage:GCC universities produce insufficient graduates with GMP-certified sterile manufacturing training, forcing facilities to recruit from India and Eastern Europe at premium compensation.
- Endotoxin Testing Bottlenecks:Reference laboratories in Dubai and Riyadh face month-long queues for LAL testing of imported raw materials, delaying batch releases during demand surges.
- Legacy ERP Integration:Hospital procurement systems in Bahrain and Oman lack API connectivity with supplier serialization databases, forcing manual data entry for MOHAP compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Generic Injectables Market |
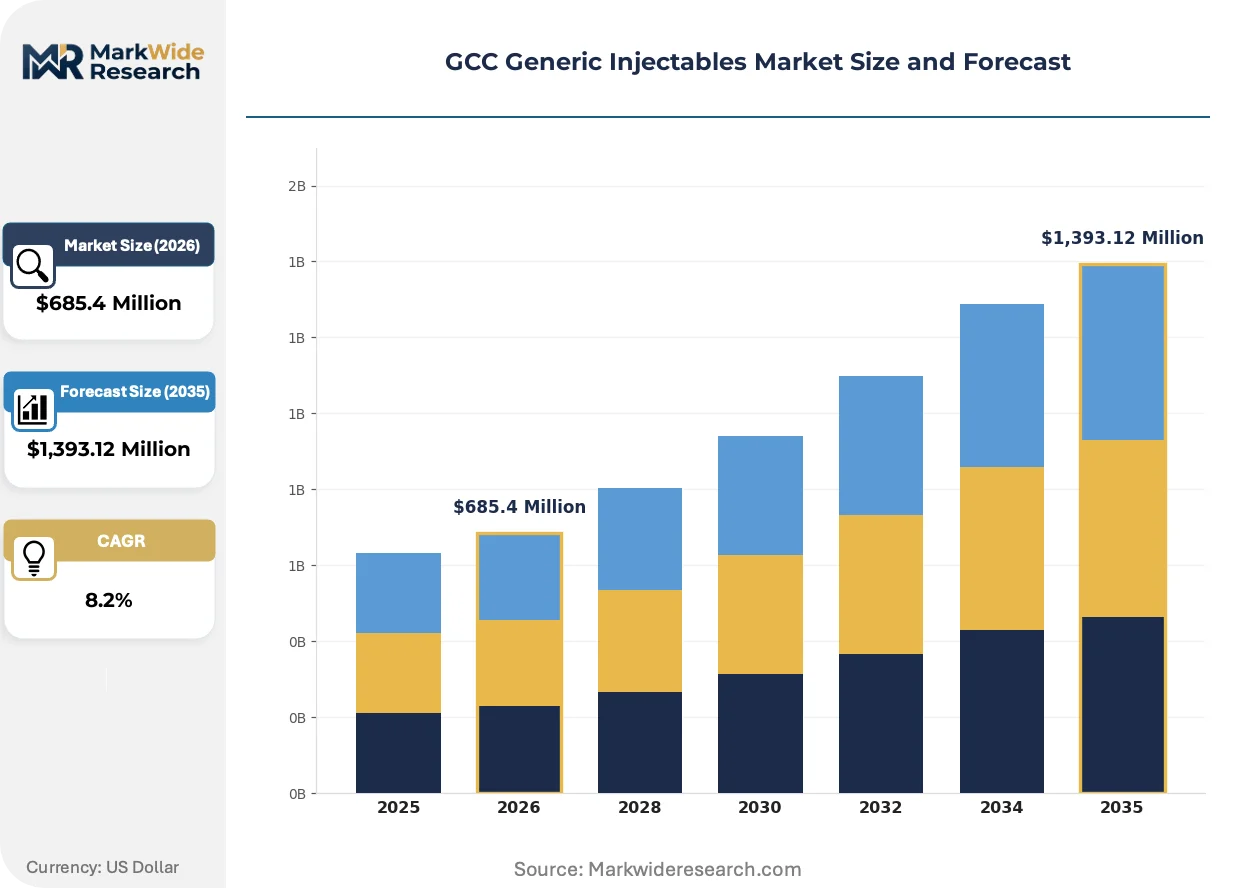
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Insulin, Hormones, Vaccines End User: Healthcare Providers, Pharmacies, Hospitals, Clinics Administration Route: Intravenous, Intramuscular, Subcutaneous, Intradermal Therapy Area: Oncology, Endocrinology, Infectious Diseases, Cardiovascular |
| Companies Covered | Aljazeera Pharmaceutical Industries, ACDIMA, Tabuk Pharmaceuticals, Fresenius Kabi, AL-Mufid Pharmaceuticals, Hikma Pharmaceuticals, Dallah Pharma, Sandoz International GmbH, Neopharma, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Generic Injectables Market Strategic Shifts & Innovations
Container material conversion and closed-system transfer devices are compressing contamination risk profiles while regulatory alignment initiatives are streamlining multi-country product approvals across the Gulf Cooperation Council.
Closed-system drug transfer devices (CSTDs) are automating hazardous drug compounding safety protocols in oncology pharmacy units. Saudi tertiary hospitals in Riyadh and Jeddah are adopting these systems at 25% annual replacement rates for open-vial techniques. This technology is automating the elimination of pharmacist exposure risks while reducing vial waste through extended beyond-use dating.
SFDA and MOHAP are converging bioequivalence documentation standards under the GCC Central Drug Registration initiative. This regulatory alignment eliminates redundant stability studies for manufacturers seeking simultaneous Saudi and Emirati approvals. Oncology biosimilars and insulin analogs are the first therapeutic categories benefiting from synchronized review timelines.
Hospital group purchasing organizations in the UAE are consolidating injectable procurement through centralized tenders that bundle oncology, anesthesia, and critical care portfolios. This buyer concentration is displacing fragmented distributor networks with direct manufacturer contracts. Dubai's private hospital chains and Saudi Arabia's National Unified Procurement Company are the primary architects of this structural shift.
GCC Generic Injectables Market Segmentation
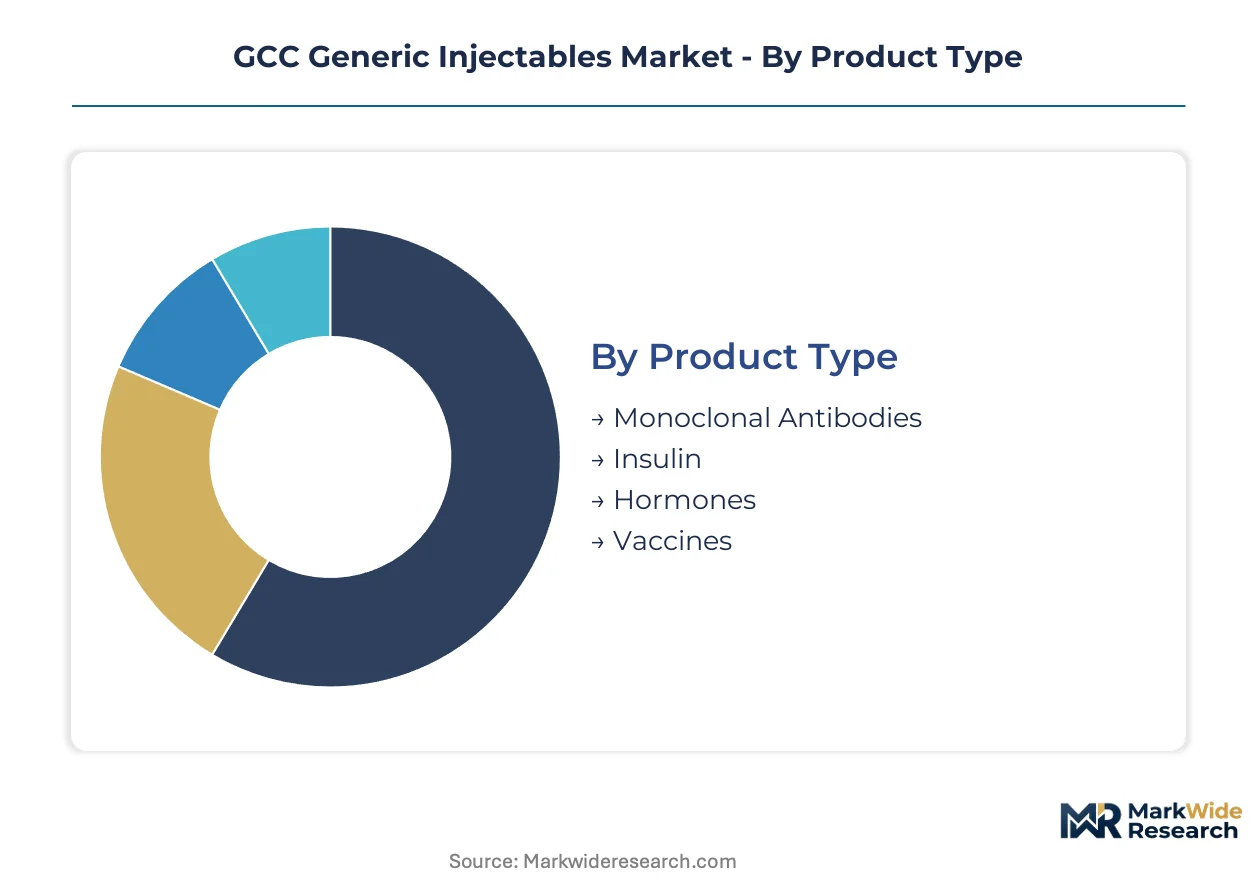
Generic injectables serve distinct clinical workflows across the GCC, from high-volume hospital infusions to specialized pharmacy-dispensed biologics. Segmentation reveals where procurement concentration, regulatory complexity, and format innovation intersect most intensely.
Product Type:
Standalone biologic injectables command dedicated cold-chain infrastructure, while embedded small-molecule formats integrate into broader therapeutic protocols across Saudi and Emirati hospital systems.
- Monoclonal Antibodies:Large-molecule biologics requiring validated cold-chain handling from European manufacturing sites through Dubai's Jebel Ali port. Oncology biosimilars are penetrating Saudi tertiary hospital formularies fastest as SFDA accelerates bioequivalence approvals for trastuzumab and rituximab alternatives.
- Insulin:Recombinant protein formulations spanning rapid-acting analogs and long-acting basal preparations. Demand concentrates in UAE diabetes clinics where MOHAP-mandated insurance coverage has expanded patient access to biosimilar glargine and aspart products.
- Hormones:Peptide and steroid injectables for endocrine replacement and reproductive therapy.
- Vaccines:Immunization products for routine and travel medicine applications.
Volume placements concentrate in insulin and hormone segments; the steepest expansion trajectory belongs to monoclonal antibodies.
End User:
Procurement scale and serialization compliance requirements separate high-volume institutional buyers from fragmented retail channels.
- Hospitals:Centralized pharmacy operations with automated compounding infrastructure and dedicated oncology infusion centers. Saudi Arabia's National Unified Procurement Company aggregates demand across Riyadh and Jeddah tertiary facilities, compressing supplier margins through bundled tender structures.
- Healthcare Providers:Integrated delivery networks and physician group practices with direct purchasing authority. Dubai's private hospital chains are displacing traditional distributors through direct manufacturer contracts for prefilled syringe formats.
- Clinics:Outpatient facilities with limited cold-chain storage capacity.
- Pharmacies:Retail dispensaries handling patient-administered subcutaneous products.
Procurement volume clusters in hospitals; healthcare providers are gaining share fastest through GPO consolidation.
Administration Route:
Route selection determines container format, nursing protocol, and error-risk profiles across GCC infusion centers.
- Intravenous:Direct vascular delivery requiring sterile compounding and prolonged infusion monitoring. Saudi oncology centers in Riyadh favor high-volume IV bags for chemotherapy protocols, driving demand for closed-system transfer devices that reduce pharmacist exposure.
- Subcutaneous:Tissue-layer injection enabling patient self-administration and outpatient therapy migration. Prefilled pen and syringe formats are displacing vial-and-needle configurations in UAE diabetes clinics where nursing time constraints favor ready-to-use designs.
- Intramuscular:Deep tissue delivery for depot formulations and certain vaccines.
- Intradermal:Superficial injection for specific diagnostic and immunization applications.
IV placements dominate hospital procurement; subcutaneous formats are climbing fastest through pharmacy automation investments.
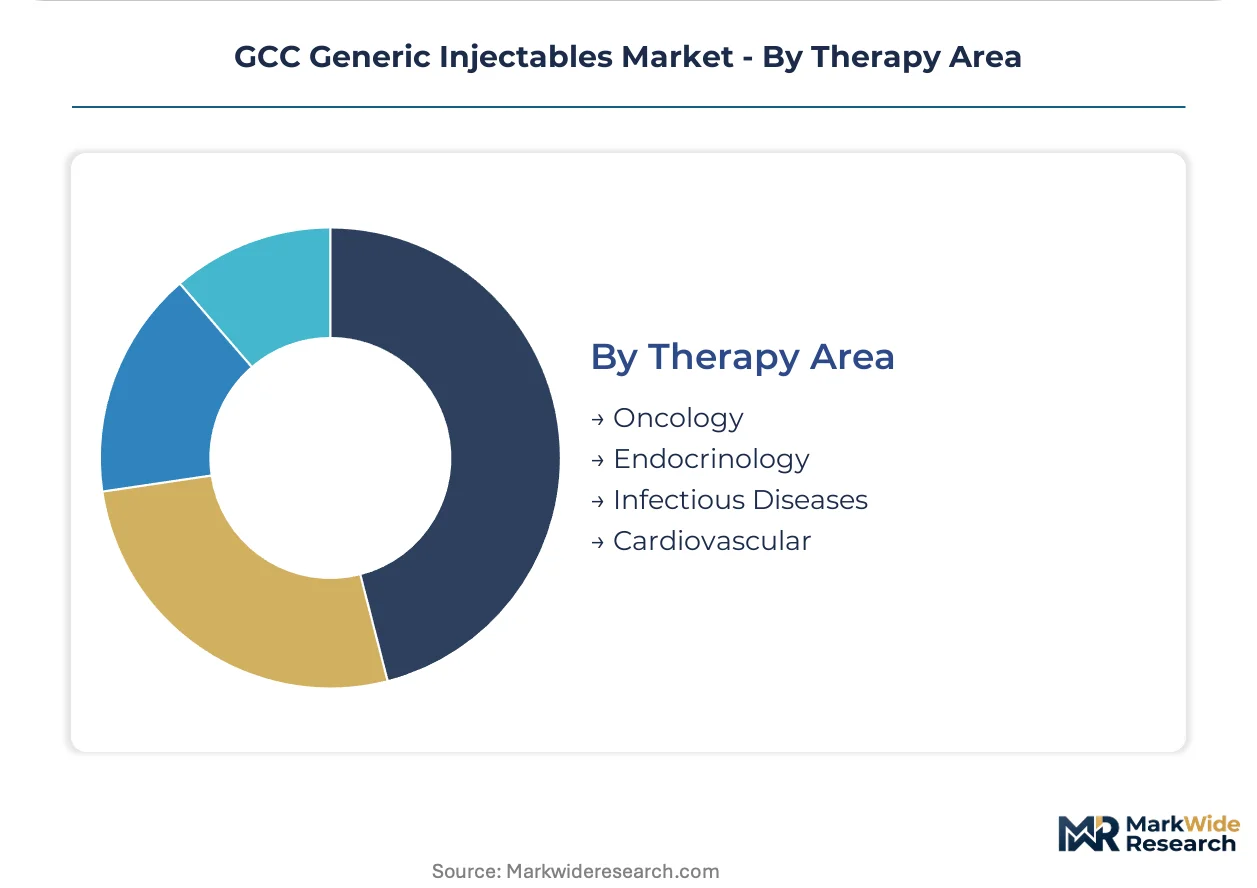
Therapy Area:
Disease prevalence and reimbursement policy create divergent growth velocities across therapeutic categories.
- Oncology:Cytotoxic and biologic agents for solid tumor and hematologic malignancies. Biosimilar trastuzumab and bevacizumab are penetrating Saudi formularies as SFDA aligns with GCC Central Drug Registration timelines, shortening multi-country approval cycles.
- Endocrinology:Insulin, GLP-1 agonists, and hormone replacement therapies. UAE mandatory insurance frameworks have expanded patient coverage for diabetes injectables, concentrating demand in Dubai and Abu Dhabi specialty clinics.
- Infectious Diseases:Antibiotic and antiviral parenterals for hospital-acquired infection protocols.
- Cardiovascular:Anticoagulant and emergency cardiac injectables for acute care settings.
Procurement volume concentrates in endocrinology; oncology is expanding most quickly through biosimilar formulary adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement volumes concentrate in Saudi Arabia and the UAE, where government-mandated health insurance expansion is accelerating biosimilar formulary adoption. Tertiary oncology centers in Riyadh and Jeddah anchor demand growth, while Dubai's private hospital chains drive format innovation toward prefilled syringes.
Saudi Arabia
Oncology and diabetes therapy volumes are climbing fastest in tertiary hospitals across Riyadh and Jeddah. The SFDA enforces tightened bioequivalence documentation requirements for imported sterile products, accelerating registrations of pre-qualified European manufacturers. The National Unified Procurement Company aggregates demand across centralized pharmacy compounding units, compressing supplier margins through bundled tender structures.
United Arab Emirates
Dubai's private hospital chains are displacing traditional distributor networks with direct manufacturer contracts for ready-to-administer formats. MOHAP mandates serialization and cold-chain validation for imported biologics, imposing IT system upgrade costs that favor larger regional players. Jebel Ali port serves as the primary entry point for European-manufactured monoclonal antibodies destined for Abu Dhabi and Dubai specialty clinics.
Kuwait
Biosimilar penetration rates run approximately 40% below Saudi Arabian levels, presenting first-mover advantages for manufacturers with established GCC distribution partnerships. The country's national pharmaceutical regulator maintains alignment with GCC Central Drug Registration timelines, streamlining multi-country approval cycles for oncology biosimilars. Kuwait City anchors demand concentration, with limited cold-chain infrastructure extending to secondary cities.
Qatar
Specialized endocrinology clinics in Doha are expanding patient access to insulin biosimilars alongside rising non-communicable disease prevalence. Government health insurance frameworks mirror UAE and Saudi mandatory coverage models, widening formulary access for parenteral therapies. Hamad Medical Corporation's centralized procurement function concentrates purchasing power for high-volume injectable contracts.
Oman
Temperature-controlled distribution networks between Dubai's Jebel Ali port and secondary Omani cities remain underdeveloped, limiting biologics penetration outside Muscat metropolitan clusters. Hospital procurement systems lack API connectivity with supplier serialization databases, forcing manual data entry for compliance. Muscat's tertiary facilities favor intravenous oncology protocols, sustaining demand for closed-system transfer devices.
GCC Generic Injectables Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers establish regional fill-finish partnerships to satisfy Saudi local content thresholds. The market structure consolidates around three distinct tiers: European multinationals leveraging manufacturing scale, regional specialists with UAE-based sterile facilities, and emerging local players capturing government tender volumes. Strategic archetypes include scale-driven format innovators, localization-focused joint venture partners, and portfolio-diversified biosimilar suppliers. M&A activity and prefilled syringe format conversion represent the two most visible competitive moves.
Among European-based manufacturers, Fresenius Kabi and Sandoz International GmbH exemplify scale-driven archetypes supplying prefilled syringe formats into Gulf hospital chains. Hikma Pharmaceuticals anchors the regional specialist tier through its UAE-based sterile injectable facility. Neopharma occupies a position within the localization-focused segment, specializing in fill-finish operations aligned with government tender requirements.
| Leading Market Players |
|---|
| Aljazeera Pharmaceutical Industries |
| ACDIMA |
| Tabuk Pharmaceuticals |
| Fresenius Kabi |
| AL-Mufid Pharmaceuticals |
| Hikma Pharmaceuticals |
| Dallah Pharma |
| Sandoz International GmbH |
| Neopharma |
| Others |
Cost & Logistics Intelligence
Backward integration into European borosilicate glass sourcing anchors both supply security and pricing power for GCC fill-finish operations, as Saudi Arabia's local content thresholds force manufacturers to choose between premium European partnerships and costlier spot-market procurement.
Pricing Analysis
High-volume hospital tenders compress margins while specialized oncology biologics sustain premium positioning. Three-tier pricing structure across European-manufactured premium, regional fill-finish standard, and Indian-sourced economy levels reflects bioequivalence certification tiers and cold-chain validation depth. Cost compression in standard-tier vials is intensifying because Saudi Arabia's National Unified Procurement Company bundles oncology and diabetes portfolios into single-source contracts. Government hospital systems exhibit highest price sensitivity; private Dubai hospital chains prioritize ready-to-administer formats over unit cost.
Supply Chain Analysis
Pharmaceutical-grade borosilicate glass supply rests on German, Italian, and French specialty manufacturers controlling over two-thirds of GCC-bound vial production. European active pharmaceutical ingredients, Indian sterile bulk drug substances, and Chinese packaging components constitute the primary input dependencies. Single-source vulnerability concentrates in glass vial supply, where freight cost volatility and euro currency fluctuation transmit directly into landed costs. Distribution runs through Dubai's Jebel Ali port as the central Gulf hub, with radiating cold-chain logistics to Saudi tertiary hospitals and UAE specialty clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where SFDA bioequivalence harmonization and MOHAP serialization mandates are forcing undercapitalized distributors and pure-import models toward exit or acquisition.
For Market Incumbents: Cement formulary lock-in through prefilled syringe format conversion aligned with Saudi hospital pharmacy automation investments. Deepen captive supply of European glass vials through long-term offtake agreements that insulate against currency volatility. Defend against emerging Indian manufacturers by accelerating GCC Central Drug Registration pre-approvals for oncology biosimilars.
For New Entrants and Emerging Players: Capture Kuwait and Qatar biosimilar whitespace where penetration trails Saudi benchmarks by substantial margins. Prioritize joint venture structures with UAE-based sterile fill-finish facilities to satisfy local content thresholds for government tenders. Lead with insulin and hormone portfolios where MOHAP-mandated insurance expansion has opened patient access fastest.
For Investors and Strategic Acquirers: Exit pathways concentrate in regional fill-finish specialists with established SFDA inspection histories and active GCC Central Drug Registration dossiers. Five-to-ten year viability hinges on backward integration into glass vial supply or captive European manufacturing partnerships. Watch SFDA bioequivalence approval velocity for trastuzumab and rituximab biosimilars as the signal indicating consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Prefilled Syringe Format Conversion | Reduces nursing time and medication error rates in Saudi oncology infusion centers. |
| Local Fill-Finish Joint Venture | Satisfies Saudi local content thresholds for National Unified Procurement Company tenders. |
| Closed-System Transfer Device Adoption | Automates hazardous drug compounding safety in Riyadh and Jeddah tertiary hospitals. |
| GCC Central Drug Registration Alignment | Eliminates redundant stability studies for simultaneous Saudi and Emirati approvals. |
| Cold-Chain Infrastructure Investment | Extends biologics penetration beyond Muscat and Bahrain metropolitan clusters. |
Research Approach
Independent corroboration across hospital procurement managers, regulatory affairs leads at SFDA-registered manufacturers, formulary directors in Saudi tertiary facilities, and sterile manufacturing executives underwrites the qualitative findings. Primary interviews with GPO contracts managers and UAE-based fill-finish operators combined with secondary validation from SFDA registration databases, MOHAP serialization compliance filings, and GCC Central Drug Registration timelines. Bottom-up demand modeling across administration routes and therapy areas triangulates against top-down market sizing from import customs data and hospital procurement disclosures.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions include product type, end user, administration route, therapy area, and regional regulatory cluster. CAGRs derive from modeled patient population growth, formulary adoption curves for biosimilars, and hospital infrastructure investment pipelines. Industry-specific forecast inputs incorporate SFDA bioequivalence approval timelines and MOHAP serialization mandate compliance costs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to glass vial supply disruptions, euro currency volatility, and GCC-wide regulatory harmonization pace. Forecasts reflect documented assumptions regarding patient population growth, insurance coverage expansion, and biosimilar substitution rates. A small set of named triggers warrants ongoing watch: SFDA inspection backlog resolution, European glass manufacturer capacity allocation shifts, and Kuwaiti national pharmaceutical regulator alignment with GCC Central Drug Registration timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Aripiprazole Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Global Travel Vaccines Market
Pharmaceuticals
Azathioprine API Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Albinism Drugs Market
Pharmaceuticals
Vasopressin Antagonists Market
Pharmaceuticals
Stye Drug Market
Pharmaceuticals
Smoking Cessation Drugs Market
Pharmaceuticals
Global Liraglutide Market
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Germany Pharmaceuticals Market
Pharmaceuticals
Intranasal Migraine Drugs Market
Pharmaceuticals
Oral Antibiotics Market
Pharmaceuticals
Global Respiratory Drug Market