
 Europe Insulin Infusion Pumps Market | 2026-2036
Europe Insulin Infusion Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Insulin Infusion Pumps Market Foresight
The Europe insulin infusion pumps landscape is pivoting between premium closed-loop systems and commodity traditional pumps as reimbursement thresholds diverge across national health systems. Medtronic leverages its integrated sensor-pump ecosystem to anchor premium positioning in Western European markets. Ypsomed competes through manufacturing scale and pharmacy channel control across German-speaking regions. Insulet Corporation specializes in tubeless patch pump design that differentiates its offering for active patient segments seeking discretion and mobility.
Europe insulin infusion pumps are electromechanical drug delivery devices that administer rapid-acting insulin subcutaneously via a cannula and tubing set or adhesive patch, typically programmed with basal rates and bolus calculators calibrated to individual glucose targets. These systems serve the primary commercial purpose of reducing glycemic variability and hypoglycemia risk for Type 1 and insulin-dependent Type 2 diabetes patients outside clinical settings. Traditional pumps retain volume leadership across the region due to established reimbursement codes and endocrinologist familiarity, while closed-loop systems capture expanding margin pools as glucose sensor integration and algorithm sophistication advance. Tubeless pumps represent the fastest-growing product configuration, particularly among pediatric and adolescent users where body image concerns and lifestyle flexibility drive preference shifts.
The EU Medical Device Regulation (MDR) and CE marking framework govern market access, with notified body capacity constraints extending certification timelines and elevating documentation burdens for pump manufacturers. EMA guidelines on drug-device combination products intersect with national health technology assessments in France, Germany, and Italy to shape reimbursement and prescribing behavior. Stakeholders must monitor evolving artificial pancreas regulatory pathways and real-world evidence requirements that will determine which technology configurations secure preferential coverage across fragmented European payer systems.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing certification timelines and elevating documentation burdens, forcing manufacturers to restructure quality management systems and notified body relationships ahead of 2027 renewal deadlines.
Growth Catalysts
- Homecare Migration:Patients across Germany, France, and the United Kingdom are relocating diabetes management from hospital endocrinology clinics to residential settings, expanding addressable pump volumes beyond institutional procurement cycles.
- Reimbursement Modernization:National health technology assessment bodies in Italy and Spain are expanding coverage codes for continuous glucose monitor-integrated pump systems, reducing out-of-pocket cost barriers for sensor-augmented therapy.
- Algorithm Sophistication:Hybrid closed-loop insulin delivery systems incorporating predictive glucose control software are capturing preference among pediatric endocrinologists seeking reduced hypoglycemia exposure for adolescent patients.
Market Restraints
- Notified Body Bottleneck:EU MDR implementation has reduced accredited certification organizations from over 80 to fewer than 30, extending technical file review timelines to 18-24 months for Class IIb active implantable devices.
- Component Supply Concentration:Precision micro-pump motors and biocompatible catheter materials depend on a limited supplier base concentrated in Switzerland and southern Germany, creating single-source vulnerability.
- Substitution by Multiple Daily Injections:Next-generation smart insulin pens with dose logging and reminder functionality are capturing price-sensitive Type 2 segments that might otherwise transition to pump therapy.
Strategic Opportunities
- Eastern European Expansion:Poland, Romania, and Czech Republic present underpenetrated addressable markets where private insurance penetration and disposable income growth are outpacing public reimbursement expansion.
- Tubeless Form Factor:Adhesive patch pump designs eliminating external tubing are creating new demand among adolescent users and athletes prioritizing body image and physical activity compatibility.
- Real-World Evidence Pathways:EMA pilot programs for medical device post-market surveillance are enabling accelerated label expansion based on registry data rather than prospective trials.
Industry Challenges
- Cybersecurity Validation:Connected pump systems require continuous software security patching against evolving threat landscapes, demanding dedicated information security teams absent at mid-tier manufacturers.
- Legacy System Interoperability:Proprietary data protocols between competing sensor and pump ecosystems prevent seamless component mixing, frustrating patients and endocrinologists seeking optimized configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Insulin Infusion Pumps Market |
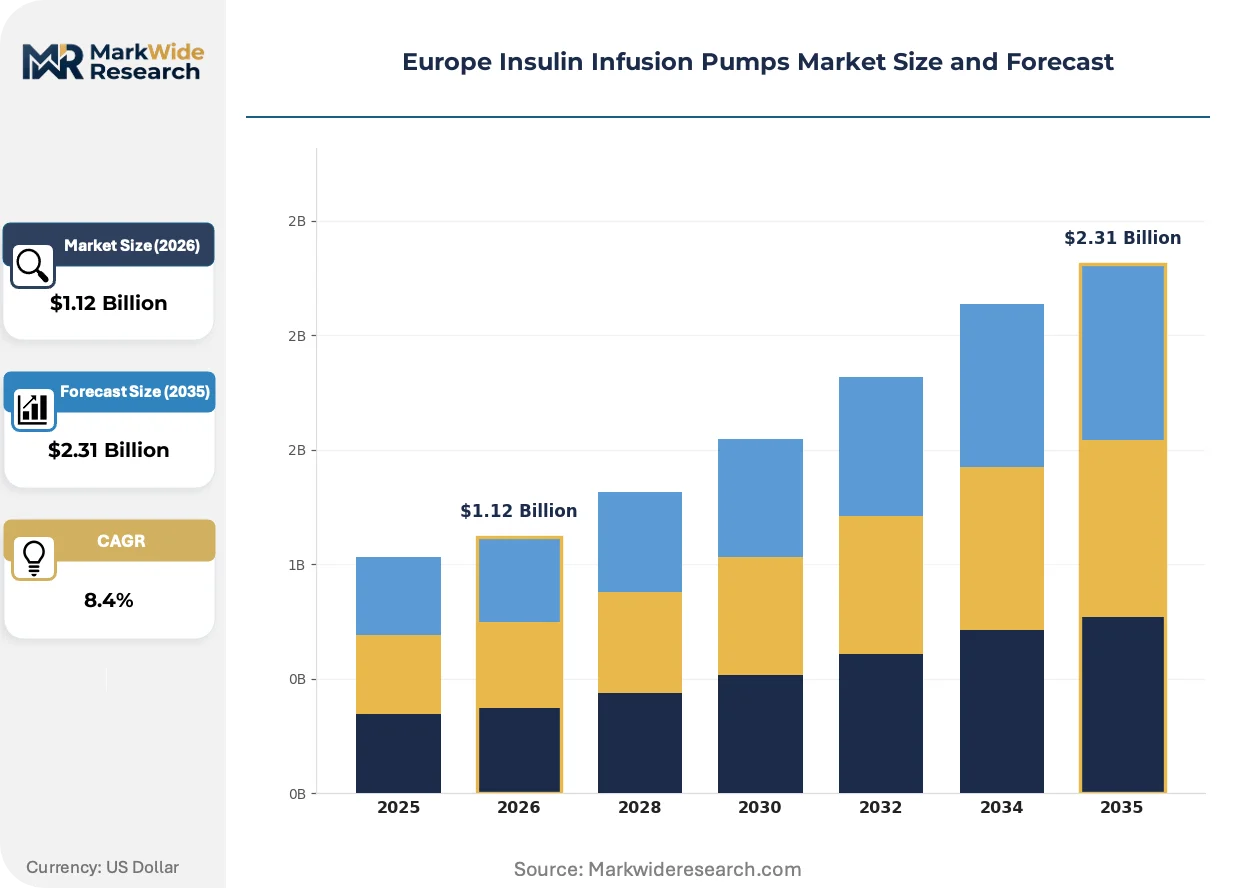
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tubeless Pumps, Traditional Pumps, Closed-loop Systems, Smart Pumps End User: Homecare Settings, Hospitals, Diabetes Clinics, Healthcare Providers Technology: Continuous Glucose Monitoring, Automated Delivery, Smartphone Integration, Connectivity Solutions Distribution Channel: Online Retail, Pharmacies, Medical Supply Stores, Direct Sales |
| Companies Covered | Roche, Terumo Corporation, Medtronic, SOOIL Developments, CeQur Simplicity, Insulet Corporation, Ypsomed, Cellnovo, Tandem Diabetes Care, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Insulin Infusion Pumps Market Shifts & Advancements
Electromechanical miniaturization and embedded artificial intelligence are converging to redefine pump architecture, shifting competitive advantage from mechanical reliability to software-driven glycemic prediction and user experience personalization.
Closed-loop algorithmic control is electrifying competitive positioning across Western European markets. These systems integrate continuous glucose sensor streams with predictive insulin dosing software to autonomously modulate basal delivery. Pediatric diabetes centers in Scandinavia and the Netherlands are adopting hybrid closed-loop configurations at accelerated rates. The technology is compressing differentiation potential for traditional open-loop pump manufacturers lacking proprietary sensor partnerships.
EMA guidance on drug-device combination products is intersecting with national health technology assessment frameworks to reshape market access pathways. The centralized regulatory pathway now requires simultaneous evaluation of insulin formulation stability and delivery mechanism precision. France's Haute Autorité de Santé and Germany's Institute for Quality and Efficiency in Health Care are applying divergent evidence standards, fragmenting launch sequencing across the region's largest reimbursement markets.
Direct-to-patient subscription models are displacing traditional durable medical equipment distribution in several European markets. Insulet Corporation and emerging competitors are bypassing hospital procurement to ship consumables directly to residential addresses. This channel innovation is most visible in the United Kingdom and Denmark, where pharmacy benefit management structures accommodate recurring delivery logistics. Endocrinology practices are responding by unbundling device training from product margin, converting to fee-for-service education models.
Europe Insulin Infusion Pumps Market Segmentation
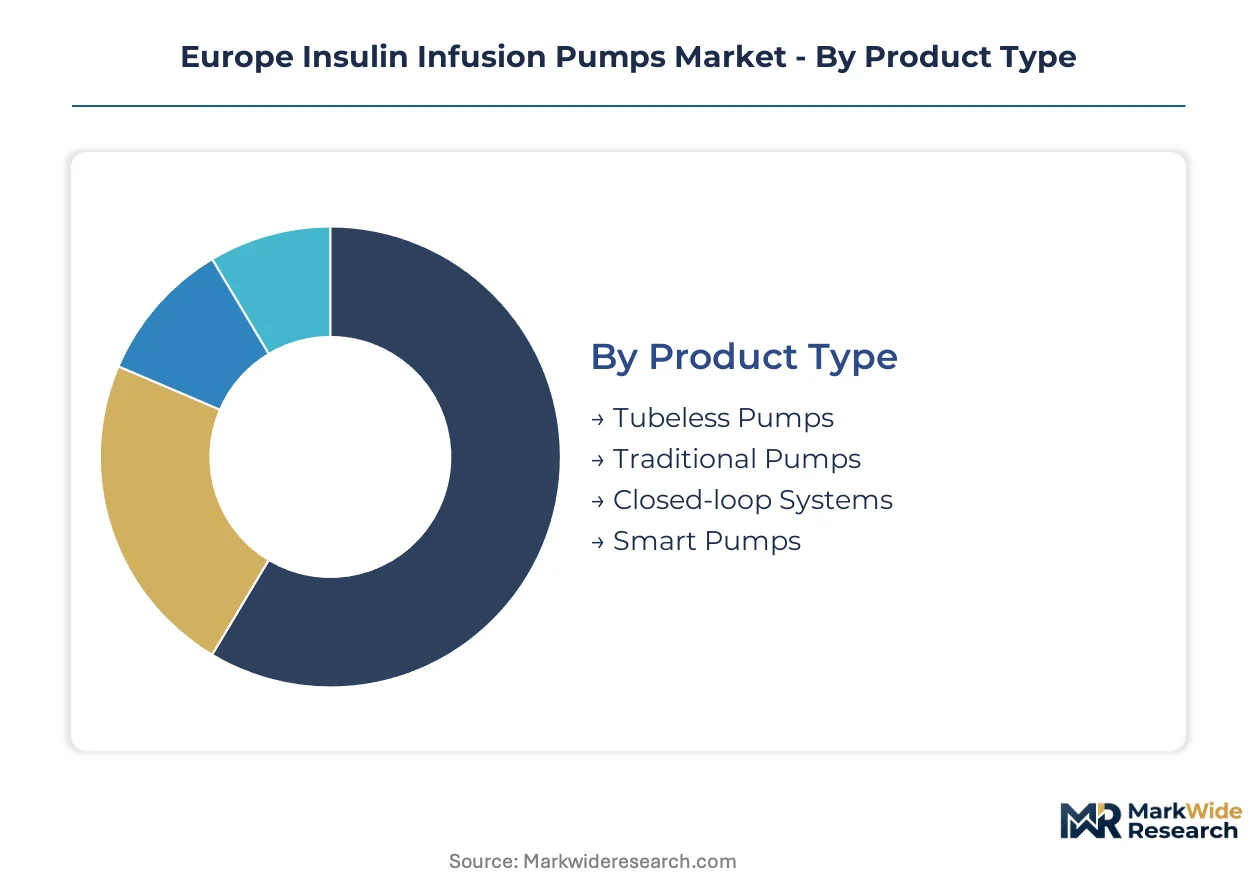
Segmentation in the Europe insulin infusion pumps market reveals divergent technology maturities and reimbursement pathways. Understanding which configurations operate as standalone devices versus integrated ecosystems shapes both procurement strategy and margin capture.
Product Type:
Standalone pump configurations dominate reimbursement catalogs, while embedded sensor-pump ecosystems command premium positioning in Western European markets.
- Traditional Pumps:Electromechanical devices with external tubing sets and programmable basal-bolus profiles. German and French hospital procurement frameworks anchor volumes through established reimbursement codes and endocrinologist training infrastructure.
- Closed-loop Systems:Sensor-integrated platforms with algorithmic insulin modulation that autonomously adjust delivery based on glucose predictions. Scandinavian pediatric centers and Dutch academic hospitals are concentrating adoption where hypoglycemia reduction justifies premium pricing.
- Tubeless Pumps:Adhesive patch designs eliminating external tubing for enhanced discretion.
- Smart Pumps:Connected devices with dose logging and remote monitoring capabilities.
Traditional pumps lead volumes today; tubeless pumps are gaining share fastest.
End User:
Cost tier stratification separates institutional procurement from patient-directed acquisition channels.
- Homecare Settings:Residential diabetes management where patients self-administer therapy with remote clinical oversight. United Kingdom and Danish reimbursement structures are expanding direct-to-patient delivery, reducing hospital dependency.
- Hospitals:Acute care and inpatient endocrinology units managing glycemic crises and perioperative insulin protocols.
- Diabetes Clinics:Specialist outpatient facilities with concentrated pump initiation and training programs.
- Healthcare Providers:General practitioner networks and community nursing services supporting decentralized care.
Homecare settings lead volumes today; diabetes clinics are expanding most quickly.
Technology:
Application focus determines whether technology serves diagnostic, therapeutic, or connectivity functions.
- Continuous Glucose Monitoring:Real-time interstitial glucose sensing with trend arrow displays and predictive alerts. Integration depth with pump hardware differentiates closed-loop from sensor-augmented therapy configurations.
- Automated Delivery:Algorithm-controlled basal modulation and predictive low-glucose suspend functionality.
- Smartphone Integration:Mobile applications for dose logging, remote monitoring, and caregiver notification.
- Connectivity Solutions:Cloud data transmission and electronic health record interoperability.
Continuous glucose monitoring leads volumes today; automated delivery is climbing the fastest.
Distribution Channel:
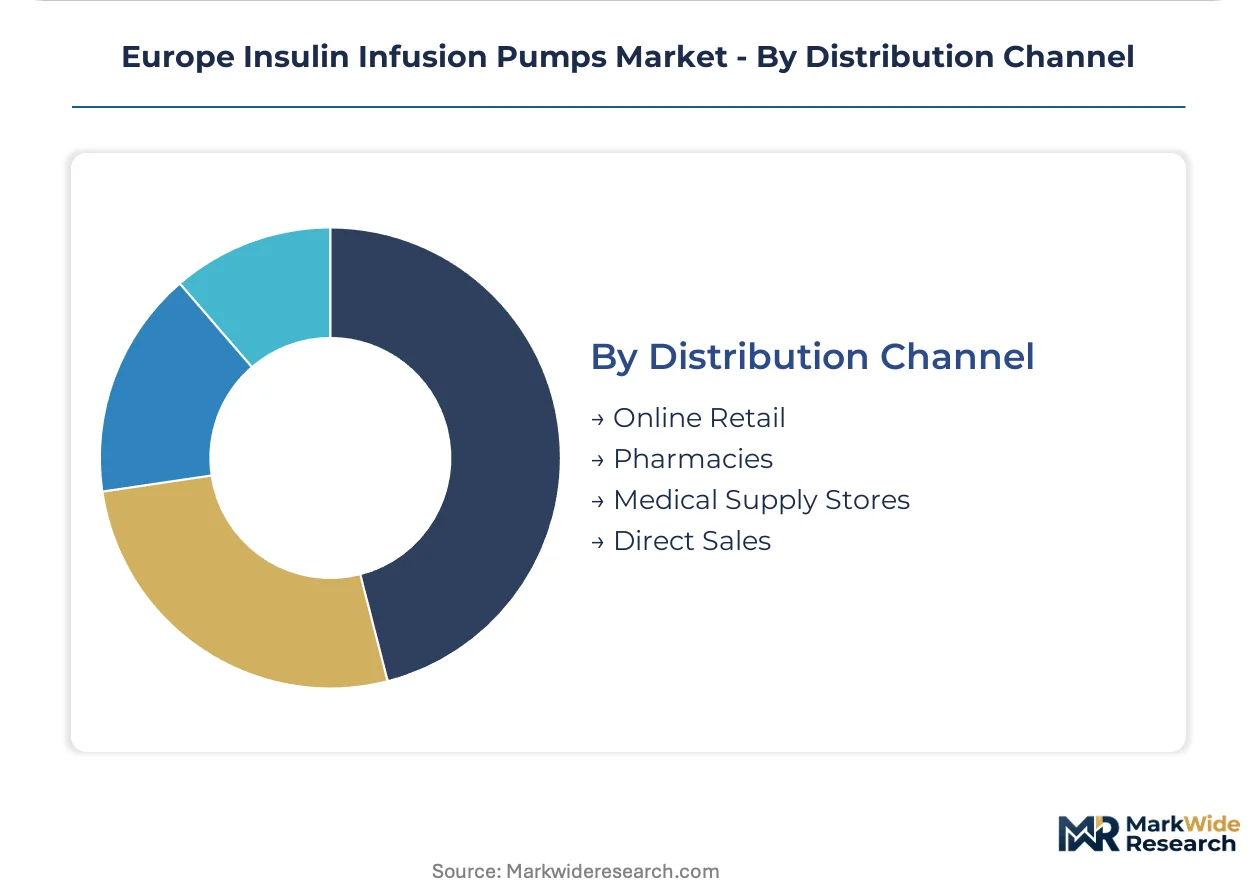
Volume concentration favors pharmacy networks, while margin capture shifts toward direct recurring revenue models.
- Pharmacies:Community and hospital-based dispensaries handling durable medical equipment procurement. German pharmacy chains and French officine networks maintain channel control through statutory distribution privileges.
- Direct Sales:Manufacturer-to-patient subscription models for consumables and device replenishment.
- Online Retail:E-commerce platforms for accessories and replacement supplies.
- Medical Supply Stores:Specialized durable medical equipment vendors with fitting and training services.
Pharmacies lead volumes today; direct sales are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands higher pump penetration rates than Italy due to denser endocrinology networks and earlier reimbursement parity for sensor-integrated systems. France sits between these extremes with accelerating adoption in pediatric centers.
Germany
Hospital procurement frameworks and statutory health insurance reimbursement codes sustain traditional pump volumes across Bavaria and North Rhine-Westphalia. The Institute for Quality and Efficiency in Health Care evaluates closed-loop evidence standards. Berlin-Brandenburg hosts concentrated diabetes technology assessment centers driving algorithm adoption.
France
Pediatric endocrinology units in Paris and Lyon are expanding closed-loop prescriptions for adolescent Type 1 patients. The Haute Autorité de Santé applies distinct health technology assessment criteria for drug-device combinations. The Île-de-France region concentrates specialist training infrastructure and pump initiation programs.
United Kingdom
National Health Service England is migrating pump procurement toward direct-to-patient subscription models outside hospital procurement cycles. NICE guidelines shape coverage thresholds for continuous glucose monitor integration. Greater Manchester and London house the densest networks of diabetes specialist nurses managing remote patient monitoring.
Italy
Regional health system fragmentation creates reimbursement gaps between northern and southern provinces for advanced pump configurations. The Italian Medicines Agency coordinates with regional payers on medical device coverage. Lombardy and Emilia-Romagna maintain higher specialist clinic density supporting pump therapy initiation.
Netherlands
Dutch academic medical centers are adopting hybrid closed-loop systems at rates exceeding European averages for pediatric populations. The Healthcare Institute evaluates cost-effectiveness evidence for integrated diabetes technologies. The Randstad conurbation concentrates university hospital research programs advancing algorithm validation.
Europe Insulin Infusion Pumps Market Competitive Landscape
Top-tier vendors anchor premium closed-loop ecosystems, while mid-scale manufacturers compete on pharmacy channel control and manufacturing scale. The vendor base stratifies across integrated sensor-pump platforms, tubeless patch specialists, and traditional electromechanical suppliers. Three archetypes dominate: vertically integrated medtech conglomerates with proprietary sensor partnerships; focused pump specialists leveraging manufacturing scale; and disruptive patch pump innovators bypassing hospital procurement. Competitive moves concentrate on M&A for sensor technology access and direct-to-patient subscription model expansion.
Among the integrated platform tier, Medtronic and Roche exemplify archetypes anchoring premium positioning through proprietary ecosystem control. Insulet Corporation occupies a position representing tubeless patch innovation and direct-to-patient channel disruption. Ypsomed sits within the manufacturing scale tier, exemplifying pharmacy channel dominance across German-speaking markets.
| Leading Market Players |
|---|
| Roche |
| Terumo Corporation |
| Medtronic |
| SOOIL Developments |
| CeQur Simplicity |
| Insulet Corporation |
| Ypsomed |
| Cellnovo |
| Tandem Diabetes Care |
| Others |
Supply & Pricing Matrix
Premium closed-loop ecosystems and commodity traditional pumps diverge across European reimbursement thresholds, compressing margin pools for mid-tier manufacturers lacking proprietary sensor partnerships while concentrating procurement leverage in German pharmacy networks and UK direct-to-patient channels. This bifurcation manifests in supply chain configurations where Swiss micro-pump motor suppliers command premium pricing for Class IIb implantable-grade components, while Asian contract manufacturers compete for consumable tubing and adhesive patch assembly.
Pricing Analysis
Capacity additions in Eastern European manufacturing zones are reshaping price floors for consumable components, though German and Swiss precision engineering retains premium positioning for electromechanical core assemblies. Subscription-based recurring revenue models dominate closed-loop system economics, while transactional pump hardware procurement persists in French and Italian hospital frameworks. Price differentiation hinges on CE marking tier under EU MDR and algorithm sophistication for predictive glucose control. Pricing pressure stems from smart insulin pen substitution in Type 2 segments. Price-sensitive buyers cluster in Southern European public procurement; least sensitivity appears in Scandinavian pediatric centers prioritizing hypoglycemia reduction.
Supply Chain Analysis
Workforce availability constraints in Swiss precision engineering hubs and southern German manufacturing clusters are elevating labor cost premiums for electromechanical assembly. Geographic supply concentration centers on Switzerland for micro-pump motors, Germany for biocompatible catheter extrusion, and Ireland for adhesive patch manufacturing. Raw material dependencies include medical-grade silicone, lithium-ion cells for patch pumps, and glucose oxidase enzyme formulations. Single-source vulnerability concentrates in Swiss motor suppliers serving Class IIb active implantable specifications. Distribution runs through German pharmacy chains, French officine networks, and emerging UK direct-to-patient subscription logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate in Eastern European private insurance expansion, where reimbursement gaps between Polish statutory coverage and Czech supplementary health plans create margin capture potential for mid-tier pump configurations.
For Market Incumbents: Anticipate algorithm commoditization pressure from smart pen ecosystems and sensor-agnostic software platforms by deepening proprietary CGM partnerships and accelerating MDR recertification timelines ahead of 2027 renewal deadlines. Defensive consolidation moves should target notified body relationship expansion to circumvent certification bottlenecks, alongside backward integration into consumable manufacturing to offset Swiss component supplier pricing power. For New Entrants and Emerging Players: Enter via tubeless patch pump white space in adolescent and athletic user segments underserved by incumbent tubing-based architectures. Most penetrable geography clusters in Poland and Romania where private insurance growth outpaces public reimbursement infrastructure. Go-to-market angle should leverage direct-to-patient subscription models bypassing hospital procurement cycles established in UK and Danish frameworks. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale manufacturers lack vertical sensor integration and face MDR compliance cost escalation exceeding standalone revenue bases. Long-term viability favors vertically integrated platforms with proprietary algorithm IP and direct channel control. Acquisition target archetype: tubeless patch specialists with CE marking progress and established pharmacy relationships. Signal to watch: EMA real-world evidence pathway adoption rates accelerating label expansion without prospective trial burdens.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Recertification Acceleration | Notified body capacity constraints under EU MDR compress timelines for Class IIb active implantable devices. |
| CGM Partnership Deepening | Proprietary sensor integration anchors premium closed-loop positioning against sensor-agnostic software competitors. |
| Direct-to-Patient Channel Buildout | UK and Danish subscription models displace hospital procurement and capture recurring consumable revenue. |
| Tubeless Patch Manufacturing Scale-Up | Adhesive patch assembly capacity addresses fastest-growing configuration demand among pediatric and adolescent users. |
| Eastern European Market Development | Poland and Romania private insurance expansion creates addressable volume beyond statutory reimbursement limitations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with endocrinologists, hospital procurement managers, biomedical engineers, and pharmacy chain category directors alongside secondary validation through EMA guidance documents, EU MDR implementation notices, national health technology assessment rulings from Germany's IQWiG and France's HAS, and hospital procurement database extracts. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored volume estimates.
Comparable historical periods anchored the forecast window across the projection horizon, with segmentation dimensions spanning product type configuration, end-user setting, technology integration depth, and distribution channel structure. CAGRs derived from regression analysis against reimbursement expansion trajectories and algorithm adoption curves, incorporating diabetes prevalence projections and sensor penetration rates as industry-specific inputs.
The model holds under stable EU MDR implementation timelines and reimbursement code expansion continuity; deviation in notified body capacity collapse or statutory coverage retrenchment would shift volume trajectories. Material deviation in MDR renewal deadlines or health technology assessment evidence requirements warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Non-Invasive Glucose Meter Market
Diabetes Care
Global Needle Free Diabetes Care Market
Diabetes Care
Spain Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Mexico Continuous Glucose Monitoring Market
Diabetes Care
Russia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Australia Continuous Glucose Monitoring Devices Market
Diabetes Care
Japan Oral Anti-Diabetic Drug Market
Diabetes Care
Global Insulin Infusion Pumps Market
Diabetes Care
Smart Glucose Monitors Market
Diabetes Care
Asia Pacific Diabetes Pen Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
Asia-Pacific Oral Anti-Diabetic Drug Market
Diabetes Care
Global Diabetic Foot Ulcer Treatment Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
France Diabetes Devices Market