
 Brazil Continuous Glucose Monitoring Market | 2026-2036
Brazil Continuous Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Continuous Glucose Monitoring Market Insights
Accuracy-grade sensor calibration is redrawing competitive expectations for reimbursement eligibility and patient outcomes in Brazil. Abbott leverages its integrated manufacturing footprint to sustain cost advantages in sensor production. Dexcom differentiates through algorithm-intensive real-time analytics that anchor premium positioning among endocrinology practices. Medtronic navigates Brazil's hybrid public-private procurement landscape by maintaining dual registration tracks with ANVISA.
Continuous glucose monitoring comprises electrochemical sensor systems that measure interstitial glucose concentrations through enzymatic reactions, typically transmitting data every one to five minutes to receivers or smartphones for insulin dosing decisions. Personal monitors occupy the largest volume tier as self-management expands beyond Type 1 diabetes into Type 2 and gestational populations, while wearable devices represent the fastest structural expansion due to smartphone integration and reduced calibration requirements. Flash glucose monitoring leads in pharmacy channel penetration where patient out-of-pocket dynamics shape adoption velocity.
ANVISA governs medical device registration and post-market surveillance, while the Ministry of Health's RENAME formulary determines public sector reimbursement eligibility for glucose monitoring supplies. ANVISA's alignment with ISO 15197 standards for glucose meter accuracy is tightening quality thresholds that filter lower-specification imports from pharmacy shelves. Stakeholders must monitor whether Brazil's forthcoming national diabetes plan expands CGM coverage through SUS or reinforces private insurance as the primary access channel.
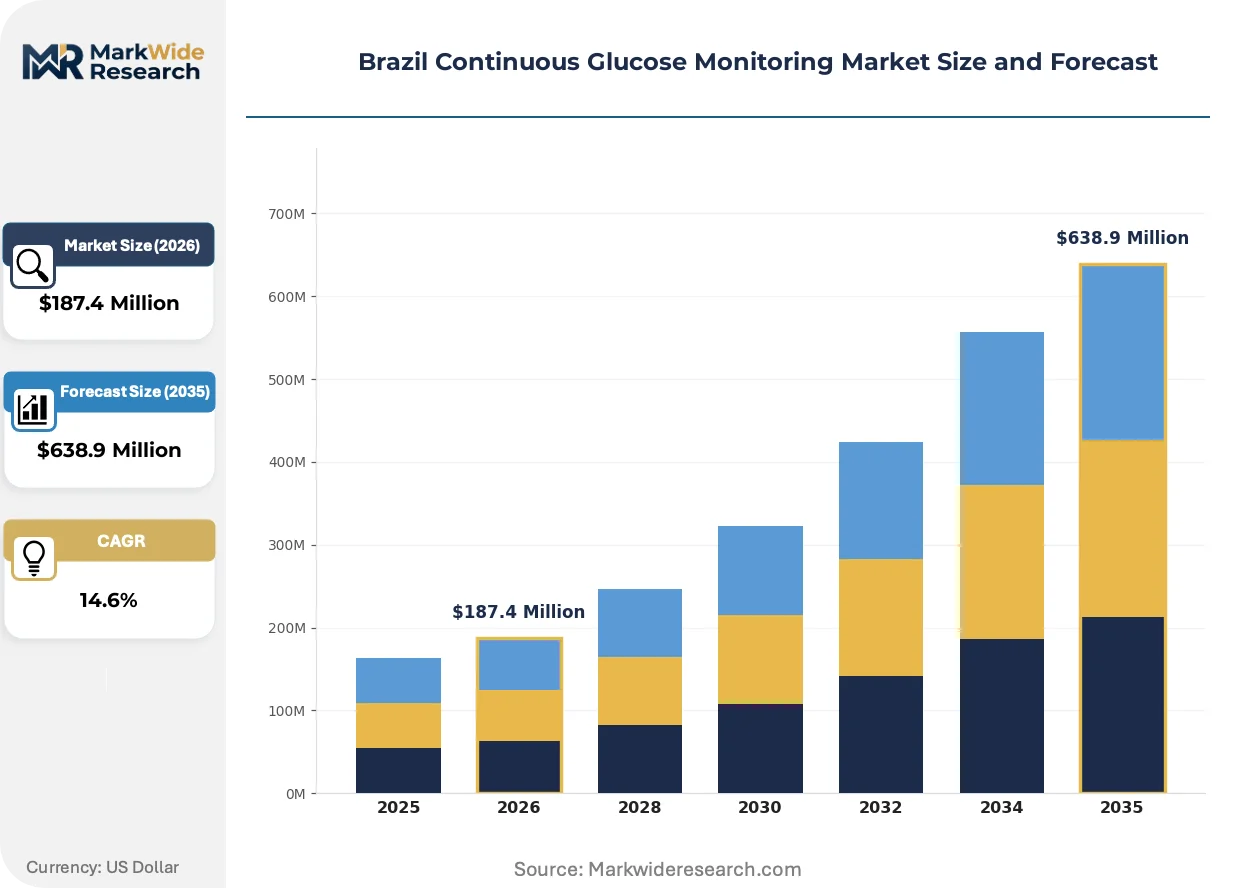
Market Dynamics
ANVISA's streamlined approval pathways for wearable glucose sensors are compressing time-to-market cycles while simultaneously tightening accuracy-grade calibration standards that filter lower-specification imports from pharmacy shelves across Brazil's public and private healthcare networks.
Growth Catalysts
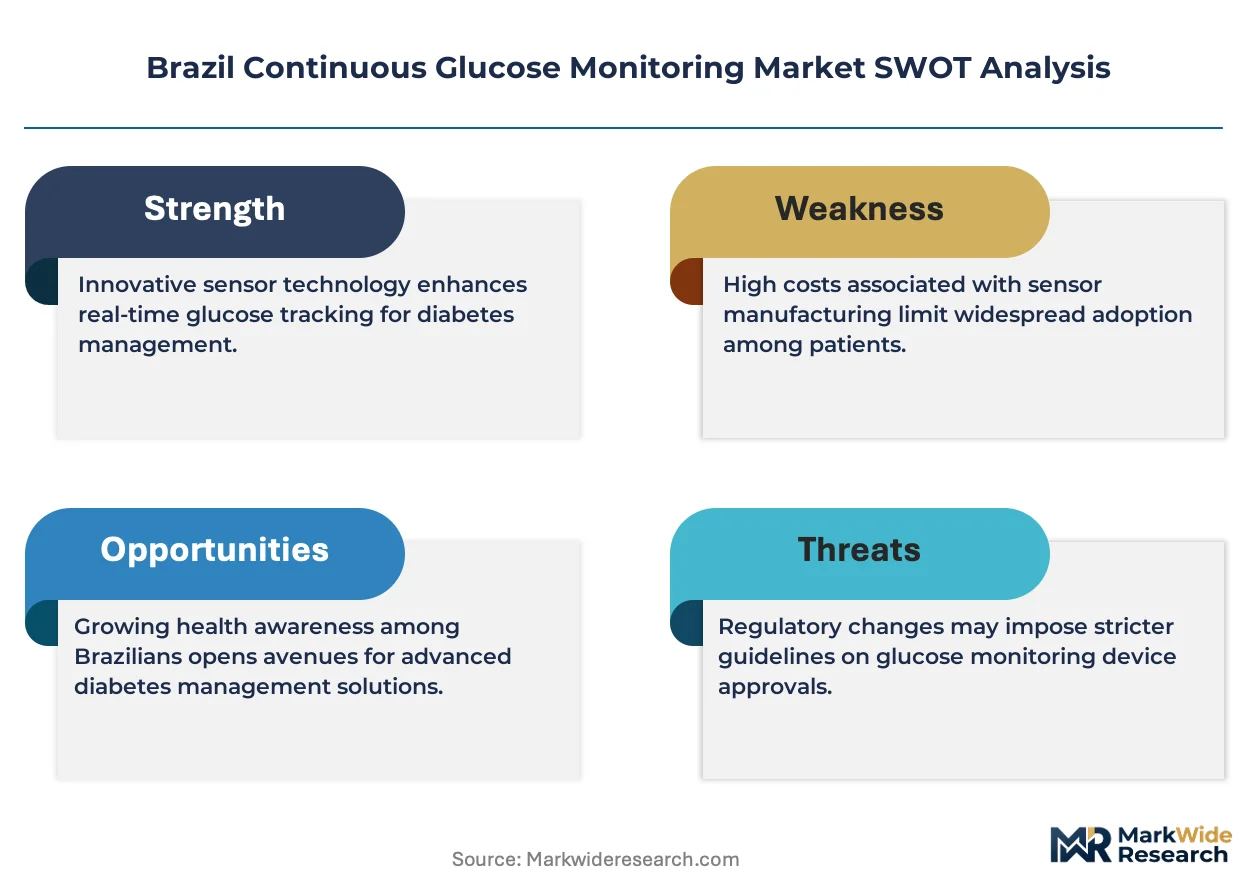
- ANVISA Regulatory Streamlining:Updated medical device regulations are accelerating registration timelines for wearable glucose sensors, enabling faster commercialization of next-generation monitoring systems.
- São Paulo Metropolitan Concentration:The convergence of diabetes prevalence and private insurance penetration within Brazil's largest health corridor is concentrating demand pull for continuous glucose monitoring adoption.
- Flash Glucose Monitoring:Reduced calibration requirements and smartphone integration are expanding self-management beyond Type 1 diabetes into Type 2 and gestational patient populations.
Market Restraints
- Electrochemical Sensor Input Costs:Enzyme and electrode material price volatility constrains margin flexibility for manufacturers assembling glucose monitoring systems within Brazil.
- Import Dependency:Concentrated supply of precision sensor substrates from Asian manufacturing hubs exposes distributors to currency fluctuation risks and extended lead times.
- ISO 15197 Alignment Friction:ANVISA's tightening quality thresholds for glucose meter accuracy are disqualifying legacy meter technologies that previously dominated pharmacy channel inventory.
Strategic Opportunities
- Northeast Brazil Penetration:Underserved state health networks outside São Paulo present expansion terrain for hospital-based continuous glucose monitoring deployment through SUS procurement channels.
- Algorithm-Intensive Analytics Convergence:Integration of machine learning-driven predictive glucose alerts with existing sensor hardware creates premium positioning among endocrinology practices.
- Pharmacy Channel Direct Distribution:Bypassing traditional medical device distributors to reach patient out-of-pocket purchasers accelerates flash glucose monitoring velocity in retail settings.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Shortage of specialists trained in electrochemical sensor calibration and wearable device firmware development constrains local manufacturing scale-up.
- Dual Registration Track Complexity:Navigating parallel ANVISA pathways for public SUS tender eligibility and private insurance reimbursement demands dedicated regulatory affairs capacity.
- Legacy Meter Integration:Hospital information systems built around intermittent fingerstick data workflows resist seamless incorporation of continuous glucose monitoring data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Continuous Glucose Monitoring Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Monitors, Professional Monitors, Transmitters, Sensors Technology: Flash Glucose Monitoring, Real-Time Glucose Monitoring, Continuous Glucose Sensing, Wearable Devices End User: Hospitals, Clinics, Homecare Settings, Pharmaceutical Companies Distribution Channel: Online Retail, Pharmacies, Direct Sales, Medical Supply Stores |
| Companies Covered | Abbott, Dexcom, Medtronic, Ascensia, GlySens, Roche, Lifescan, Arkray, Agamatrix, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Continuous Glucose Monitoring Market Trends and Innovations
Real-time glucose analytics and smartphone-native monitoring interfaces are compressing the gap between sensor hardware and clinical decision support, reshaping how Brazilian healthcare providers and patients interact with diabetes management technology.
Factory-calibrated electrochemical sensors with extended wear duration are displacing patient-dependent calibration routines that previously compromised accuracy consistency. Endocrinology practices in São Paulo and Rio de Janeiro are adopting these systems at accelerated pace for both inpatient glycemic control and ambulatory patient monitoring. The structural consequence is a compression of competitive differentiation toward algorithm performance rather than hardware specifications alone.
ANVISA's alignment with ISO 15197 accuracy standards is tightening post-market surveillance obligations for glucose monitoring device manufacturers. Industrial consequence includes mandatory adverse event reporting systems and accelerated recall protocols that elevate compliance costs for imported products. Sensor systems targeting pharmacy channel distribution face the most pronounced compliance burden, driving some distributors toward hospital-direct procurement models with more controlled traceability.
Patient self-management behavior is pivoting toward smartphone-integrated monitoring platforms that unbundle traditional clinical oversight from daily glucose tracking. Pharmacy retail channels are capturing this shift through direct-to-consumer flash glucose monitoring sales that bypass endocrinologist prescription pathways. This pattern is most visible in Brazil's private insurance corridors where out-of-pocket co-payment structures incentivize patient-driven technology selection over physician-directed device assignment.
Brazil Continuous Glucose Monitoring Market Segmentation
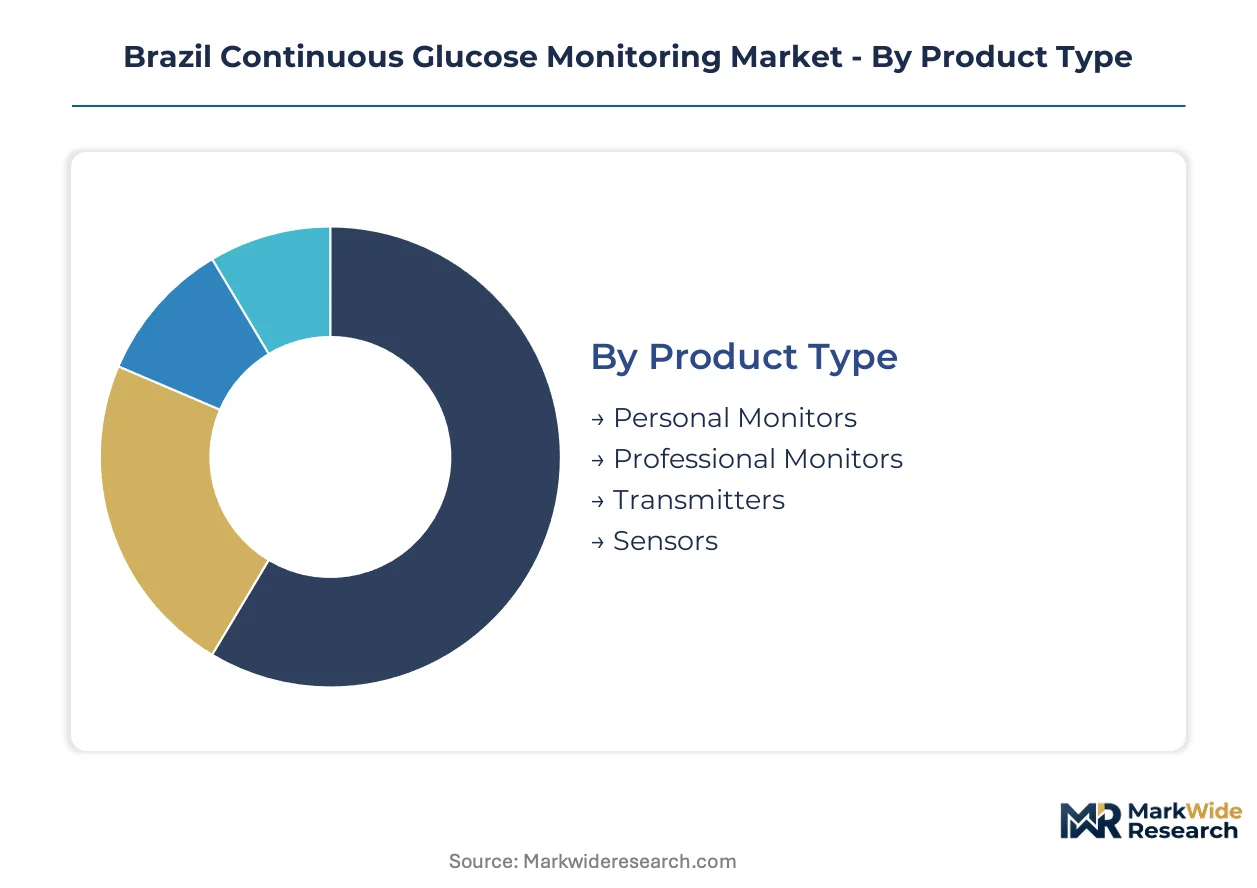
Segmentation in Brazil's continuous glucose monitoring market reveals how reimbursement pathways, patient self-management behavior, and procurement channel dynamics split demand across distinct commercial battlegrounds. Understanding where margin pools concentrate within each dimension enables manufacturers to prioritize registration investments and distribution partnerships.
Product Type:
Margin pools concentrate in consumable sensor components where recurring replacement cycles generate predictable revenue streams, while hardware margins compress under competitive pressure from integrated system bundles.
- Sensors:Electrochemical enzyme-based substrates with factory calibration dominate procurement budgets through 14-day wear cycles that lock patients into branded ecosystems. São Paulo's private insurance corridors absorb the highest sensor volumes where endocrinology practices prescribe integrated monitoring systems.
- Personal Monitors:Smartphone-integrated receivers with Bluetooth transmission capabilities anchor self-management adoption beyond Type 1 diabetes into Type 2 populations. Pharmacy channel penetration accelerates as patient out-of-pocket purchasing bypasses traditional prescription workflows.
- Transmitters:Compact radio-frequency modules that bridge sensor-to-receiver communication.
- Professional Monitors:Hospital-grade receivers with centralized data management for inpatient glycemic control.
The dominant share belongs to Sensors, while Personal Monitors are closing the gap fastest.
Technology:
Technology differentiation increasingly hinges on algorithm performance rather than hardware specifications alone, compressing competitive moats toward predictive analytics and alert accuracy.
- Flash Glucose Monitoring:Factory-calibrated systems eliminate patient-dependent calibration routines that previously compromised measurement consistency. Retail pharmacy channels capture this segment through direct-to-consumer sales that accelerate adoption velocity among Brazil's private insurance populations.
- Real-Time Glucose Monitoring:Algorithm-intensive platforms transmit glucose values every one to five minutes with predictive alerting for hypoglycemic events. Endocrinology practices in Rio de Janeiro and São Paulo anchor premium positioning for these systems in ambulatory patient monitoring.
- Continuous Glucose Sensing:Core electrochemical measurement technology underlying all integrated monitoring platforms.
- Wearable Devices:Smartphone-native form factors with reduced calibration requirements.
Flash Glucose Monitoring commands the largest volume position, though Real-Time Glucose Monitoring demonstrates the steepest expansion trajectory among technology categories.
End User:
End user segmentation tracks the divergence between institutional procurement through SUS tenders and patient-directed purchasing in private insurance corridors.
- Hospitals:Public and private healthcare networks deploy continuous glucose monitoring for inpatient glycemic control and surgical recovery protocols. ANVISA registration for hospital-grade systems demands dedicated regulatory affairs capacity to navigate dual public-private procurement tracks.
- Homecare Settings:Self-management environments where smartphone integration and reduced calibration requirements reshape patient behavior. Northeast Brazil's underserved state networks present expansion terrain as SUS procurement channels extend beyond São Paulo's metropolitan concentration.
- Clinics:Outpatient endocrinology practices with hybrid prescription and dispensing models.
- Pharmaceutical Companies:Clinical trial deployment and companion diagnostic partnerships.
Hospitals retain the dominant procurement volume, while Homecare Settings are expanding most quickly as patient-driven technology selection accelerates.
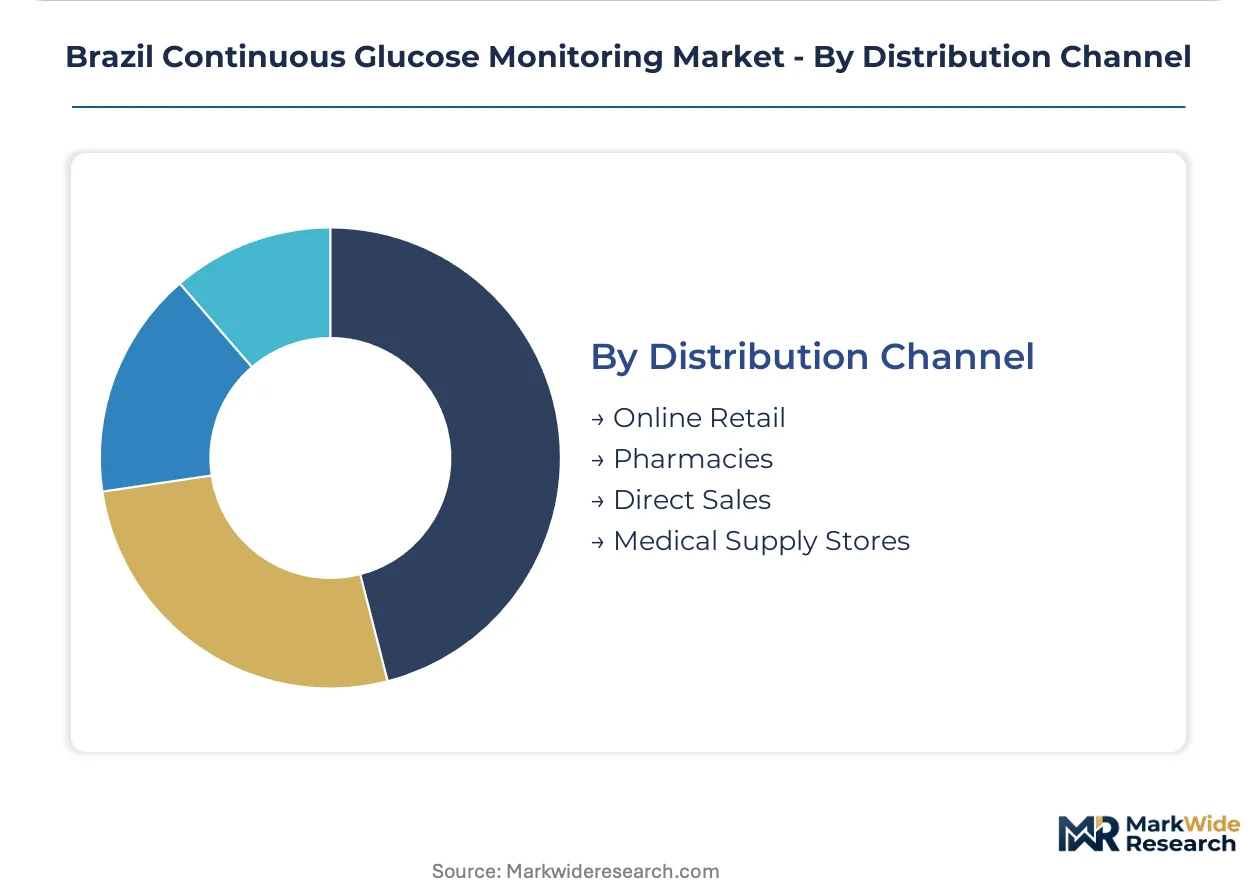
Distribution Channel:
Channel strategy determines whether manufacturers capture margin through controlled hospital-direct models or absorb compliance burdens for pharmacy retail traceability.
- Pharmacies:Retail channels capture patient out-of-pocket dynamics where flash glucose monitoring velocity exceeds hospital-direct procurement. ANVISA's tightening post-market surveillance obligations elevate compliance costs most acutely for pharmacy-distributed sensor systems.
- Direct Sales:Hospital-direct procurement models bypass traditional medical device distributors to reach institutional buyers with controlled traceability requirements. São Paulo's metropolitan health corridor concentrates direct sales activity where private insurance penetration supports premium system bundles.
- Online Retail:E-commerce platforms with regulatory compliance for medical device sales.
- Medical Supply Stores:Specialized distributors serving homecare and clinical segments.
Pharmacies hold the dominant position, while Direct Sales are gaining share fastest as manufacturers retreat from retail compliance burdens toward controlled institutional procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Private insurance corridors in Brazil's southeast absorb premium-priced continuous glucose monitoring systems with minimal price elasticity, while public sector procurement through SUS channels demands aggressive cost engineering that filters higher-specification technologies from hospital networks in the north and northeast.
São Paulo
São Paulo state's metropolitan health corridor concentrates the highest diabetes prevalence rates alongside deepest private insurance penetration, creating concentrated demand pull for factory-calibrated flash glucose monitoring systems. ANVISA's streamlined registration pathways enable faster commercialization of next-generation wearable sensors through pharmacy retail channels. The Greater São Paulo industrial cluster anchors distribution infrastructure for both hospital-direct procurement and direct-to-consumer pharmacy sales.
Rio de Janeiro
Rio de Janeiro's private healthcare networks exhibit accelerating adoption of algorithm-intensive real-time glucose monitoring platforms among endocrinology practices. ANVISA's alignment with ISO 15197 accuracy standards elevates compliance costs for imported sensor systems entering retail pharmacy channels. The Rio de Janeiro metropolitan area concentrates ambulatory patient monitoring demand where smartphone-native monitoring interfaces reshape self-management behavior.
Minas Gerais
Minas Gerais presents expansion terrain for hospital-based continuous glucose monitoring deployment as SUS procurement channels extend beyond the southeast corridor. The state's central geographic position supports distribution hub functions for northeast Brazil penetration strategies. Belo Horizonte's healthcare infrastructure anchors regional procurement networks serving underserved state health systems.
Bahia
Bahia's public health networks demonstrate pronounced price sensitivity that constrains adoption of premium continuous glucose monitoring technologies within SUS-funded institutions. ANVISA's tightening post-market surveillance obligations disproportionately burden pharmacy-distributed sensor systems in retail channels. Salvador's metropolitan health corridor concentrates limited private insurance penetration where patient out-of-pocket dynamics shape technology selection.
Rio Grande do Sul
Rio Grande do Sul maintains hybrid demand patterns split between private insurance corridors in Porto Alegre and public sector procurement through state health networks. The state's industrial base supports emerging biomedical engineering capacity for electrochemical sensor assembly. Southern Brazil's demographic profile drives steady demand for Type 2 diabetes self-management technologies through pharmacy retail channels.
Brazil Continuous Glucose Monitoring Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated manufacturing specialists sustaining margin advantages through captive sensor production while algorithm-intensive platforms command premium positioning among specialized endocrinology practices. The market structure consolidates around three strategic tiers: multinational medical device conglomerates with dual-registration regulatory capacity, mid-scale sensor specialists leveraging pharmacy channel velocity, and emerging regional assemblers targeting SUS procurement price points. Dominant competitive moves include backward integration into electrochemical substrate production and strategic partnerships with Brazilian distributors to navigate ANVISA's parallel public-private registration tracks.
Within the multinational conglomerate tier, Abbott, Dexcom, and Medtronic exemplify divergent strategic positioning. Abbott leverages integrated manufacturing footprints to sustain cost advantages in high-volume sensor production. Dexcom occupies a position emphasizing algorithm-intensive real-time analytics that anchor premium positioning among specialized endocrinology practices. Medtronic represents the archetype of dual-registration navigation, maintaining parallel ANVISA tracks for public SUS tender eligibility alongside private insurance reimbursement pathways.
| Leading Market Players |
|---|
| Abbott |
| Dexcom |
| Medtronic |
| Ascensia |
| GlySens |
| Roche |
| Lifescan |
| Arkray |
| Agamatrix |
| Others |
Pricing and Supply Chain Analysis
Ninety-day sensor substrate lead times from Asian manufacturing hubs compress pricing power for Brazilian distributors while simultaneously elevating working capital requirements that filter smaller players from pharmacy channel competition. This inventory-to-pricing dynamic concentrates procurement leverage among manufacturers with captive electrochemical production or established ANVISA registration capacity.
Pricing Analysis
Consumable sensor replacement cycles anchor lifetime value through recurring 14-day wear schedules that lock patients into branded ecosystems. Pricing stratifies across factory-calibrated flash systems, algorithm-intensive real-time platforms, and legacy intermittent meters filtered by ISO 15197 alignment. Cost compression in pharmacy-distributed tiers intensifies as ANVISA's post-market surveillance obligations elevate compliance burdens. Public SUS procurement demonstrates highest price sensitivity, while São Paulo's private insurance corridors absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Strategic stockpiling of enzyme and electrode materials dominates inventory strategy given Asian substrate concentration and currency fluctuation exposure. Precision sensor components draw from China, South Korea, and Japan, with glucose oxidase enzymes resting on specialized fermentation capacity concentrated in Western Europe and North America. Single-source vulnerability for electrochemical substrates creates tariff exposure and extended lead time risk. Distribution runs through hospital-direct procurement models and pharmacy retail channels with divergent traceability requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemical sensor calibration expertise and ANVISA dual-registration capacity constitute binding constraints that separate viable competitors from marginal participants in Brazil's continuous glucose monitoring landscape.
For Market Incumbents: Fortify algorithm-intensive analytics capabilities to sustain premium positioning among São Paulo endocrinology practices facing flash glucose monitoring commoditization. Deepen backward integration into enzyme substrate production to offset Asian supply concentration and currency volatility. Secure dedicated regulatory affairs capacity for parallel SUS-private registration tracks as ANVISA tightens post-market surveillance obligations. For New Entrants and Emerging Players: Differentiate on hospital-direct procurement models that bypass pharmacy channel compliance burdens toward controlled institutional traceability. Target Northeast Brazil state health networks outside São Paulo's metropolitan concentration where SUS procurement channels remain underserved. Pursue strategic partnerships with established Brazilian distributors to navigate ANVISA registration complexity without building captive regulatory infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue medical device play because sensor replacement cycles generate predictable consumable demand decoupled from hardware margin compression. Acquisition candidates include mid-scale sensor specialists with integrated manufacturing footprints and existing ANVISA registrations. Monitor ANVISA's alignment with international accuracy standards as the inflection signal for regulatory barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Dual Registration Investment | Parallel public-private tracks unlock SUS tender eligibility alongside private insurance reimbursement pathways. |
| Factory Calibration Technology Deployment | Eliminates patient-dependent routines that previously compromised measurement consistency in flash glucose systems. |
| Algorithm-Intensive Analytics Integration | Machine learning-driven predictive alerts create premium positioning among Rio de Janeiro and São Paulo endocrinology practices. |
| Hospital-Direct Procurement Expansion | Bypasses pharmacy retail compliance burdens toward controlled traceability with institutional buyers. |
| Electrochemical Substrate Backward Integration | Captive enzyme and electrode production offsets Asian supply concentration and currency fluctuation exposure. |
Research Methodology
Operator-level perspectives from biomedical engineers, ANVISA regulatory affairs specialists, hospital procurement committee members, and pharmacy channel distributors anchored the qualitative base. Primary interviews combined with secondary validation from ANVISA registration databases, Ministry of Health RENAME formulary records, and private insurance reimbursement filings. Bottom-up sensor volume estimates triangulated against top-down healthcare expenditure allocations across Brazil's state health networks.
Sensitivity analysis tested forecast outputs against variable ANVISA approval timeline scenarios and SUS procurement budget allocation shifts across the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user setting, and distribution channel alongside regional regulatory cluster differentiation. CAGRs derived from fitted growth curves calibrated to historical adoption patterns in comparable Latin American markets and industry-specific inputs including diabetes prevalence trajectories and private insurance penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained ANVISA regulatory streamlining or expanded SUS CGM coverage would require recalibration. Forecasts reflect documented assumptions regarding electrochemical sensor input cost stability and hospital information system integration timelines. Revision becomes warranted when ANVISA's national diabetes plan implementation crosses coverage expansion or restriction thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Diabetic Pen Cap Market
Diabetes Care
Combination Anti-Diabetes Drugs Market
Diabetes Care
Global Pet Diabetes Care Market
Diabetes Care
Type 2 Diabetes Market
Diabetes Care
Pet Diabetes Care Devices Market
Diabetes Care
Vietnam Insulin Infusion Pump Market
Diabetes Care
Global Needle Free Diabetes Care Market
Diabetes Care
Global Proliferative Diabetic Retinopathy Market
Diabetes Care
Diabetes Monitors Market
Diabetes Care
France Oral Anti-Diabetic Drug Market
Diabetes Care
Russia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Self-Monitoring Blood Glucose (SMBG) Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market
Diabetes Care
Oman Diabetes Care Devices Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
Smart Glucose Monitors Market