

OTC Glucose Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
OTC Glucose Monitors Market Insights
China is fragmenting its glucose monitor manufacturing base across Shenzhen, Hangzhou, and Suzhou industrial zones as domestic champions scale electrochemical strip production. Abbott leverages vertical integration from enzyme biosensor R&D through retail pharmacy distribution to sustain margin control across North American and European channels. Sinocare anchors the Asia-Pacific cost structure through high-volume strip manufacturing, while Dexcom competes on algorithm-intensive continuous monitoring platforms that reduce calibration frequency.
OTC glucose monitors are electrochemical or optical biosensor devices that quantify blood glucose concentration through enzyme-mediated reactions, typically employing glucose oxidase or dehydrogenase chemistry on disposable test strips or subcutaneous filaments, designed for non-clinical users to track glycemic status without healthcare supervision. Continuous glucose monitors and flash glucose monitoring systems are capturing the fastest expansion as patients shift from painful fingerstick routines to interstitial fluid sensing, while blood glucose meters retain volume leadership in price-sensitive segments and emerging markets where reimbursement structures still favor traditional formats. Smart glucose monitors that integrate with mobile health platforms are concentrating margin pools through subscription-linked data services and remote monitoring contracts with telemedicine providers.
FDA 510(k) and De Novo pathways govern premarket submission for non-prescription glucose devices in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for software-enabled monitors through notified body conformity assessment. The country's national pharmaceutical regulator in India and CDSCO are streamlining import licensing for OTC diagnostics under the Medical Devices Rules, expanding access beyond hospital-centric distribution. Stakeholders must monitor evolving software-as-medical-device classifications and cybersecurity mandates that will determine which connected monitor platforms maintain market access across jurisdictions.
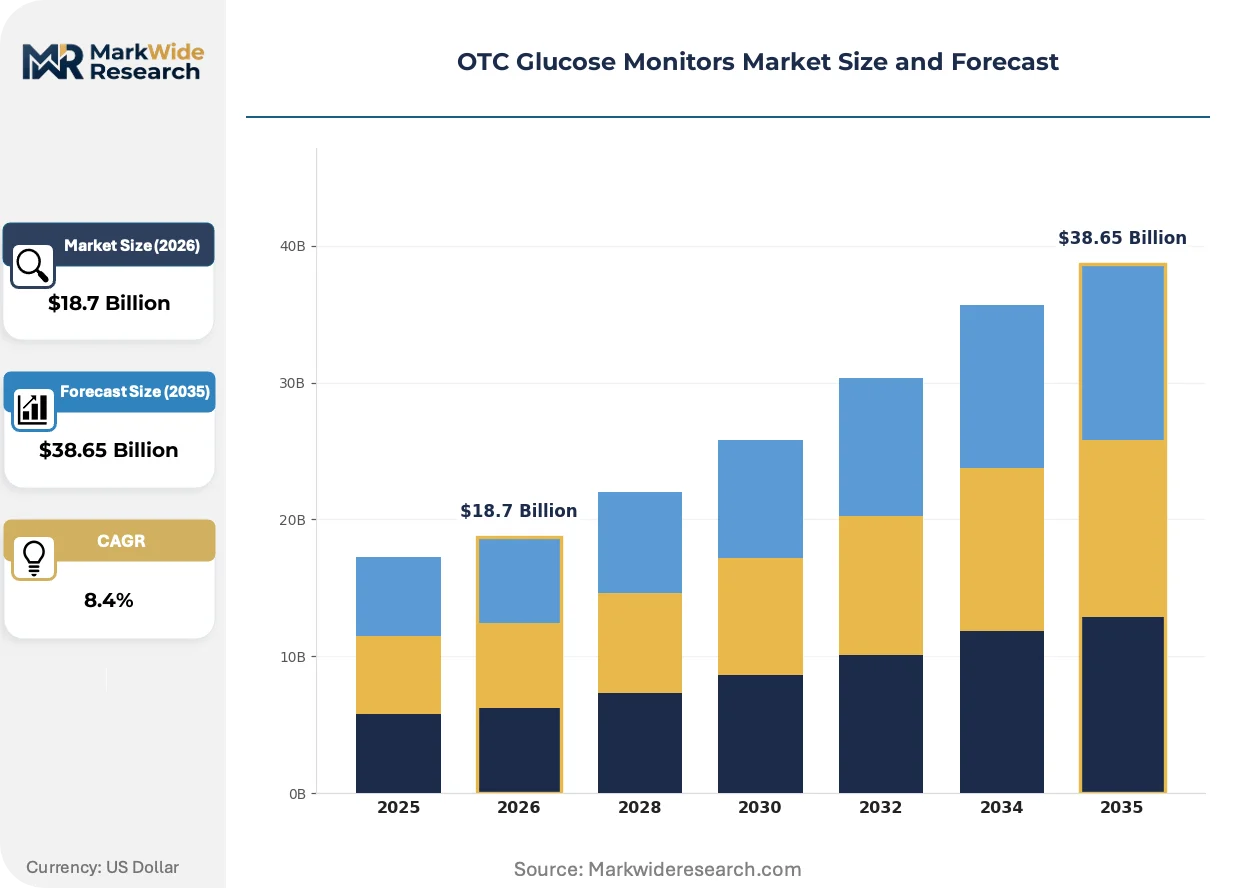
Market Dynamics
FDA De Novo clearance for non-prescription continuous glucose monitors is dissolving the prescription barrier that historically gated patient access, forcing incumbent manufacturers to restructure pricing architectures and distribution partnerships around direct-to-consumer channels.
Growth Catalysts
- Telemedicine integration:Remote patient monitoring contracts with virtual care platforms are embedding CGM data streams into chronic disease management workflows, expanding reimbursable use cases beyond traditional diabetes care.
- Enzyme biosensor advances:Improved glucose oxidase stability on electrochemical strips is extending product shelf life and reducing calibration frequency, lowering total cost of ownership for home users.
- India's CDSCO streamlining:The Medical Devices Rules framework is accelerating import licensing for OTC diagnostics, opening pharmacy-centric distribution beyond hospital procurement channels.
Market Restraints
- Precious metal input volatility:Palladium and platinum price swings in electrochemical sensor electrodes are compressing gross margins for strip manufacturers locked into fixed retail pricing contracts.
- Shenzhen supply concentration:Contract manufacturing for disposable test strips clusters in Pearl River Delta electronics corridors, creating single-point vulnerability to regional logistics disruptions or trade policy shifts.
- Interstitial fluid lag limitation:Physiological delay between blood and tissue glucose readings limits CGM accuracy during rapid glycemic swings, restricting adoption in intensive insulin therapy segments.
Strategic Opportunities
- Prediabetes screening expansion:Undiagnosed at-risk populations in the United States represent a latent demand pool as employers and payers expand wellness program glucose monitoring subsidies.
- Subscription data services:Smart monitor platforms are layering recurring revenue through AI-powered glycemic pattern analysis and personalized nutrition coaching delivered via mobile applications.
- EU MDR software classification:The Medical Device Regulation's explicit software-as-medical-device pathway is creating first-mover advantage for connected monitor vendors that pre-validate algorithm clinical evidence.
Industry Challenges
- Cybersecurity compliance timelines:FDA premarket guidance for connected glucose devices demands documented threat mitigation protocols, extending development cycles for software-enabled platforms.
- Legacy system integration friction:Hospital EHR compatibility requirements for patient-generated CGM data are forcing manufacturers to maintain multiple data exchange standards simultaneously.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OTC Glucose Monitors Market Trends and Innovations
Non-invasive optical sensing and factory-calibrated continuous monitoring platforms are compressing the technical and behavioral barriers that sustained fingerstick dominance for decades.
Photonic glucose detection using near-infrared spectroscopy and Raman scattering is collapsing the invasive sampling requirement that has defined self-monitoring since the 1980s. Prediabetic consumers and wellness-focused non-diabetics are piloting wearable ring and patch formats that bypass skin puncture entirely. This technology is collapsing the psychological resistance that previously limited monitoring adherence outside diagnosed populations.
The EU Medical Device Regulation's intensified clinical evidence requirements for software-enabled monitors is forcing manufacturers to front-load randomized trial investment before market entry. Notified body conformity assessments now explicitly evaluate algorithm validation datasets, favoring vendors with pre-existing real-world evidence repositories. High-complexity CGM platforms targeting Type 1 diabetes management are absorbing the steepest compliance cost increases, accelerating consolidation among mid-tier European challengers.
Direct-to-consumer pharmacy distribution is displacing durable medical equipment channels as the primary patient acquisition pathway. CVS, Walgreens, and Amazon storefronts are capturing CGM transactions that previously routed through endocrinology clinics and diabetes supply distributors. This channel rotation is most pronounced in the United States, where cash-pay pricing transparency and same-day fulfillment expectations are reshaping brand loyalty dynamics.
OTC Glucose Monitors Market Segmentation
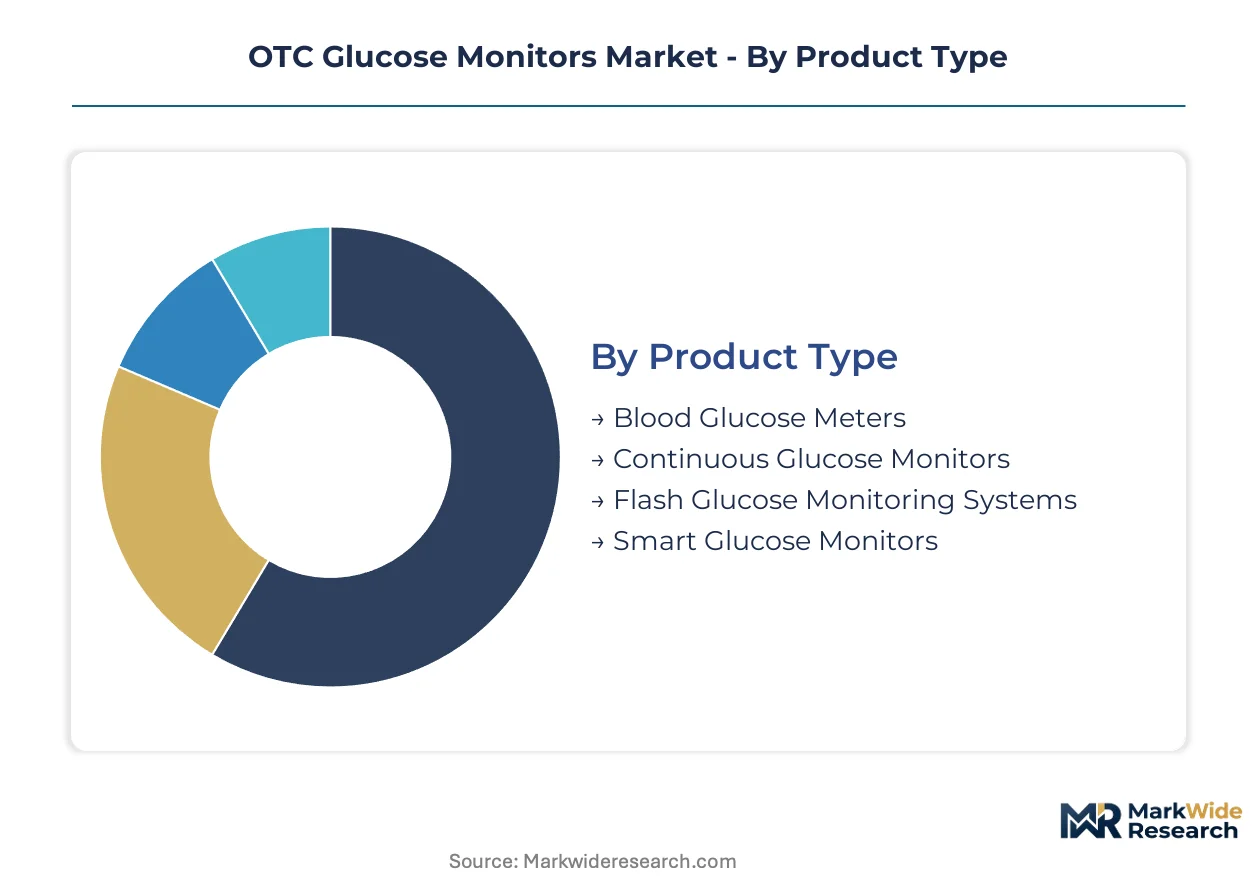
Product architecture and user workflow differences in OTC glucose monitoring create distinct margin profiles and replacement cycle dynamics. Each segment category carries unique regulatory pathways and channel dependencies that reshape competitive positioning.
Product Type:
After-sales-service intensity varies sharply across product categories, with continuous monitoring platforms demanding ongoing sensor replacement logistics while traditional meters rely on consumable strip fulfillment.
- Blood Glucose Meters:Portable electrochemical devices using disposable enzyme-coated strips remain the volume foundation in price-sensitive markets. Demand clusters in India and Southeast Asia where CDSCO-streamlined import licensing supports pharmacy-centric distribution of low-cost units.
- Continuous Glucose Monitors:Implantable filament sensors paired with transmitters deliver real-time interstitial glucose data streams. Home users in the United States drive expansion as FDA De Novo clearance for non-prescription access dissolves traditional clinic-gated distribution.
- Flash Glucose Monitoring Systems:Factory-calibrated wearable patches with on-body scanners eliminate fingerstick calibration routines.
- Smart Glucose Monitors:Connected devices integrating mobile health platforms and AI-powered pattern recognition.
Blood Glucose Meters holds the largest share; momentum sits with Continuous Glucose Monitors.
Technology:
Cost tier stratification separates premium optical platforms from commodity electrochemical production, with enzyme stability and calibration requirements determining total ownership economics.
- Electrochemical:Amperometric measurement via glucose oxidase or dehydrogenase reactions on palladium-platinum electrodes dominates strip manufacturing. Shenzhen and Suzhou industrial corridors concentrate contract production, exposing margins to precious metal price volatility.
- Optical:Near-infrared spectroscopy and Raman scattering enable non-invasive glucose quantification through skin transmittance. Wellness-focused consumers in the United States pilot wearable ring formats that bypass puncture entirely.
- Enzymatic:Biological catalyst chemistry on polymer substrates provides foundational specificity for point-of-care testing.
- Microfluidic:Lab-on-chip architectures miniaturize sample handling for ultra-low volume requirements.
- Photometric:Colorimetric endpoint detection supports visual-read alternatives in resource-limited settings.
Electrochemical platforms command the greatest installed base; Optical sensing gains share fastest.
Application:
Volume concentration reflects reimbursement structures, with employer wellness subsidies expanding prediabetes screening faster than traditional diabetes management in cash-pay channels.
- Diabetes Management:Daily glycemic tracking for diagnosed Type 1 and Type 2 patients remains the revenue core. Intensive insulin therapy segments in the United States and Germany absorb premium CGM platforms despite interstitial fluid lag limitations during rapid swings.
- Prediabetes Screening:Risk stratification for undiagnosed at-risk populations opens latent demand pools. United States employers and payers expand wellness program subsidies, embedding glucose monitoring into preventive care workflows.
- Gestational Monitoring:Pregnancy-specific glycemic surveillance protocols.
- Fitness Tracking:Metabolic optimization for athletic performance and body composition goals.
- Nutritional Assessment:Real-time dietary glucose response characterization.
Diabetes Management retains dominant share; Prediabetes Screening exhibits the steepest expansion trajectory.
End User:
Customer type determines channel configuration, with direct-to-consumer pharmacy distribution displacing durable medical equipment procurement for self-pay populations.
- Home Users:Individual consumers purchasing through retail pharmacy and e-commerce channels represent the fastest-expanding buyer segment. CVS, Walgreens, and Amazon storefronts capture transactions that previously routed through endocrinology clinics.
- Pharmacies:Brick-and-mortar and online dispensaries serve as primary acquisition points for strip refills and device upgrades. Indian pharmacy chains leverage CDSCO streamlining to expand beyond hospital-centric distribution.
- Clinics:Outpatient facilities integrating patient-generated data into care protocols.
- Remote Care Providers:Virtual health platforms embedding CGM streams into chronic disease management.
- Telemedicine Services:Digital-first care models prescribing and monitoring glucose devices remotely.
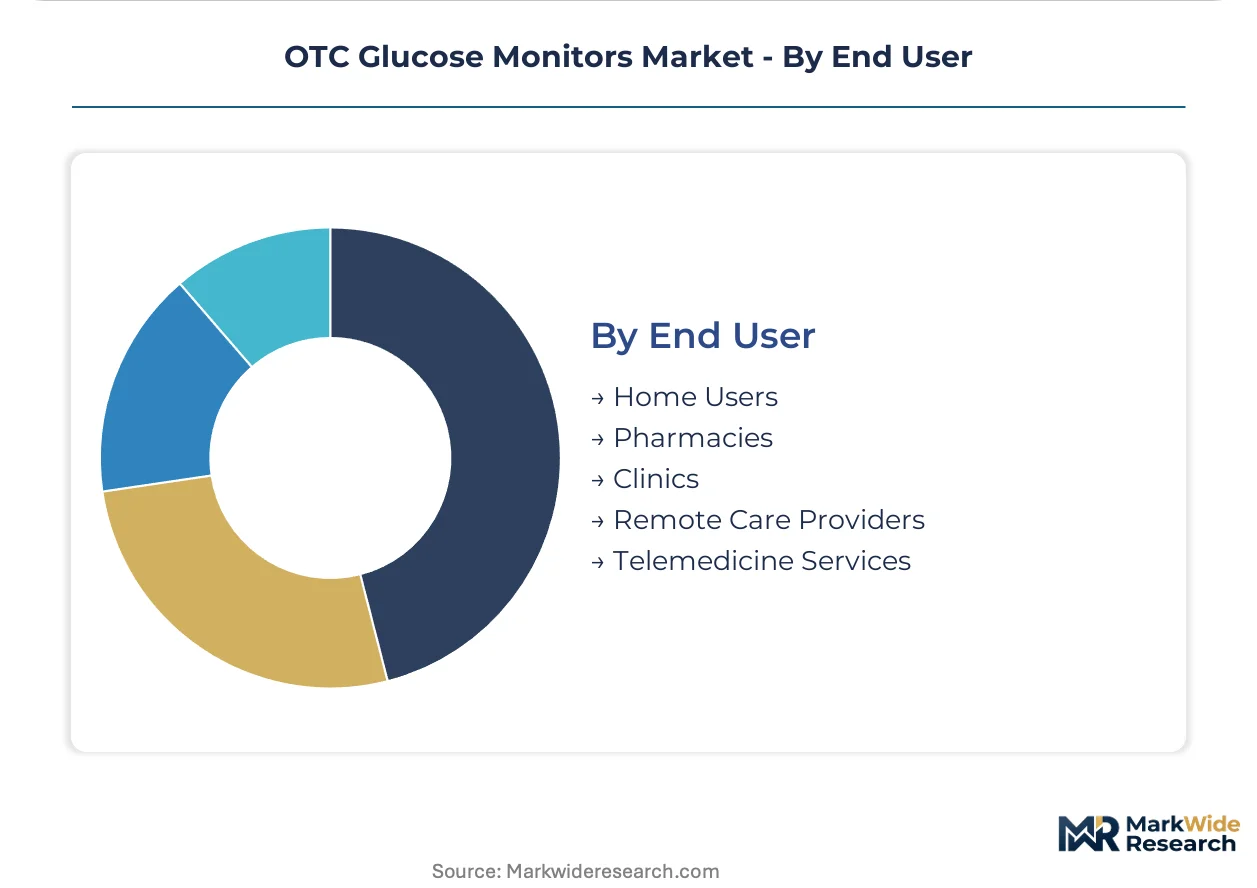
Home Users generate the greatest volume; Remote Care Providers climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA De Novo clearances for non-prescription continuous glucose monitors are dissolving prescription barriers in the United States, while CDSCO streamlining in India and EU MDR software classifications are reshaping competitive access across three distinct regulatory zones.
United States
Home users drive the fastest expansion as direct-to-consumer pharmacy distribution through CVS, Walgreens, and Amazon displaces durable medical equipment channels. FDA De Novo pathways for non-prescription CGM access are restructuring pricing architectures around cash-pay transparency. The Boston-San Diego corridor concentrates algorithm-intensive continuous monitoring R&D.
Germany
Intensive insulin therapy segments absorb premium CGM platforms despite interstitial fluid lag limitations during rapid glycemic swings. EU MDR intensified clinical evidence requirements for software-enabled monitors favor vendors with pre-existing real-world evidence repositories. The Baden-Württemberg industrial cluster anchors electrochemical sensor electrode manufacturing.
China
Shenzhen, Hangzhou, and Suzhou industrial zones fragment domestic manufacturing as champions scale electrochemical strip production. NMPA regulatory harmonization with international standards accelerates local product registration for connected monitoring platforms. The Pearl River Delta concentrates contract manufacturing for disposable test strips.
India
Pharmacy-centric distribution expands beyond hospital procurement channels as CDSCO streamlines import licensing for OTC diagnostics under Medical Devices Rules. Price-sensitive demand clusters in blood glucose meters where reimbursement structures still favor traditional formats. Maharashtra and Gujarat industrial corridors anchor domestic electrochemical strip assembly.
Japan
PMDA regulatory frameworks emphasize software-as-medical-device validation for connected monitor platforms entering preventive care workflows. Aging demographics expand home-based glucose monitoring subsidies through national health insurance adjustments. The Kanto region around Tokyo concentrates precision biosensor component manufacturing.
OTC Glucose Monitors Market Competitive Landscape
Capability concentration sits with algorithm-intensive continuous monitoring specialists; scale advantage sits with high-volume electrochemical strip manufacturers. The market structures around three tiers: vertically integrated multinationals controlling enzyme biosensor R&D through retail distribution, contract manufacturers clustered in Pearl River Delta electronics corridors, and software-enabled platform vendors layering subscription data services. Strategic moves center on FDA De Novo pathway navigation for non-prescription access and backward integration into precious metal electrode supply.
Within the vertically integrated tier, Abbott exemplifies margin control through captive enzyme biosensor development and retail pharmacy channel ownership. Dexcom occupies a position among algorithm-intensive platform vendors competing on calibration frequency reduction and telemedicine integration. Sinocare anchors the Asia-Pacific cost structure archetype through Shenzhen and Suzhou manufacturing concentration. These three represent distinct competitive positions: premium integrated systems, software-intensive continuous monitoring, and high-volume strip economics.
| Leading Market Players |
|---|
| Dexcom |
| Abbott |
| Medtronic |
| Senseonics Holdings |
| F. Hoffmann-La Roche |
| i-SENS |
| Sinocare |
| GlucoRx |
| Zhejiang POCTech |
| Others |
Pricing and Supply Chain Analysis
Palladium and platinum price volatility in electrochemical sensor electrodes compresses gross margins for strip manufacturers locked into fixed retail pricing contracts, forcing a three-tier pricing structure across premium, standard, and economy levels while concentrating contract manufacturing in Pearl River Delta electronics corridors. This input cost instability widens price spreads between factory-calibrated CGM platforms and commodity blood glucose meters, reshaping procurement patterns for pharmacy chains and remote care providers.
Pricing Analysis
United States retail pharmacy channels command 40-60% premiums over Indian pharmacy pricing for identical electrochemical meter platforms, with FDA De Novo clearance tier and telemedicine integration bundling as primary price differentiation drivers. Cost compression in economy strip segments is intensifying because Sinocare and Zhejiang POCTech scale Shenzhen manufacturing volumes, while home users in emerging markets exhibit highest price sensitivity and intensive insulin therapy patients in Germany show lowest sensitivity to CGM platform premiums.
Supply Chain Analysis
Export control restrictions on advanced biosensor fabrication equipment limit technology transfer to Chinese contract manufacturers, forcing NMPA-registered domestic champions to source lower-precision electrode deposition tools. Manufacturing gravity centers on China, Germany, and the United States, with palladium-platinum electrode substrates and glucose oxidase enzyme formulations as critical raw material dependencies. Single-source vulnerability concentrates in Shenzhen test strip contract manufacturing, while distribution runs through direct-to-consumer pharmacy channels displacing durable medical equipment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
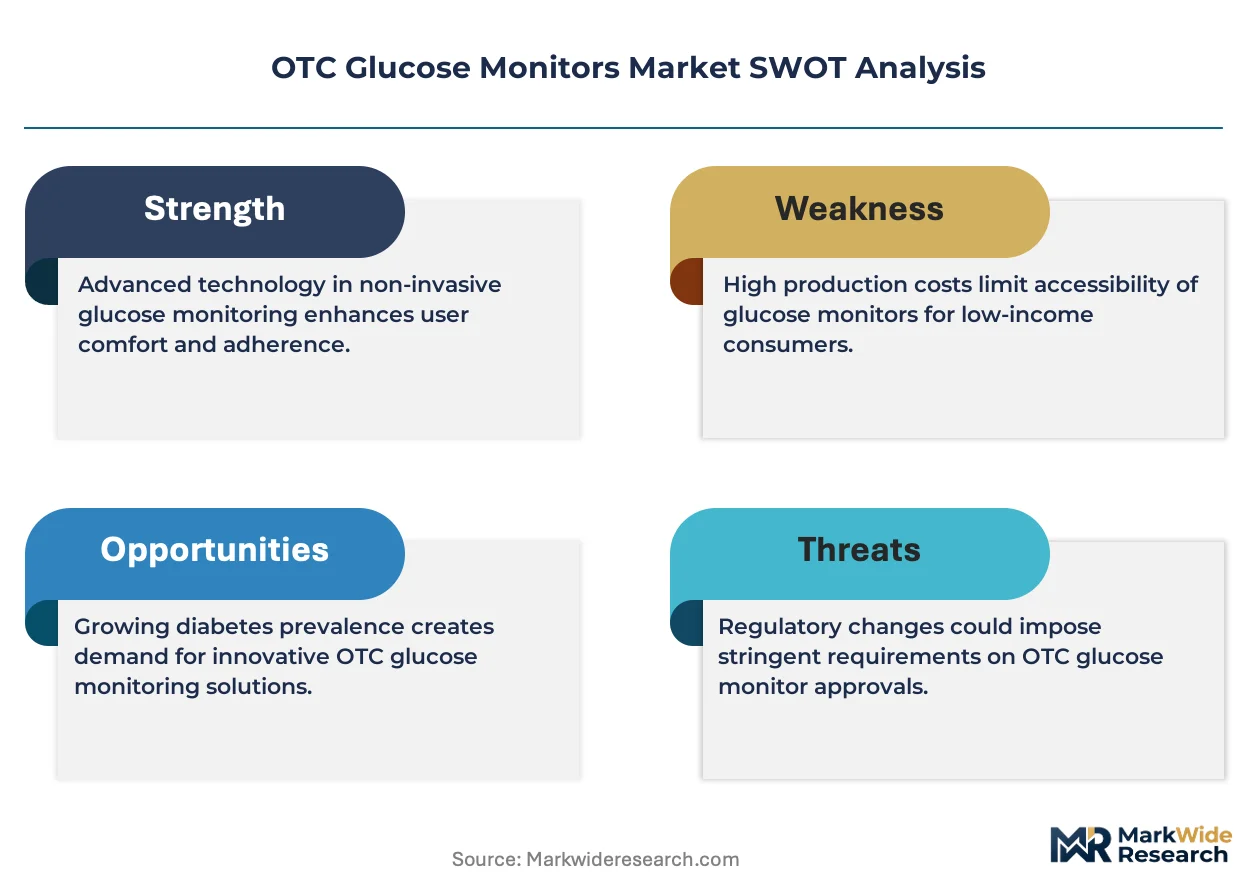
This market rewards regulatory entrenchment as the primary defensive moat, with FDA De Novo clearance pathways and EU MDR software classifications creating years-long lead times that protect incumbent positions from fast-follower erosion.
For Market Incumbents: Build data-network moats through AI-powered glycemic pattern analysis subscriptions that increase switching costs for home users already integrated with telemedicine platforms. Incumbents should deepen backward integration into enzyme biosensor R&D to defend against emerging optical sensing entrants, while pre-validating algorithm clinical evidence under EU MDR software-as-medical-device pathways to lock out mid-tier European challengers facing steepest compliance cost increases. For New Entrants and Emerging Players: Prediabetes screening workflows in United States employer wellness programs represent the most penetrable entry point, bypassing entrenched diabetes management incumbents with reimbursement-gated distribution. New entrants should target cash-pay pharmacy channels in India where CDSCO streamlining accelerates import licensing, leveraging low-cost electrochemical strip manufacturing partnerships in Gujarat industrial corridors to undercut established brand premiums through direct-to-consumer e-commerce fulfillment. For Investors and Strategic Acquirers: Algorithm-intensive continuous monitoring specialists with pre-existing real-world evidence repositories offer prime acquisition targets as EU MDR intensified clinical evidence requirements favor vendors that front-loaded randomized trial investment. Long-term viability hinges on software-enabled platform economics overtaking hardware margins, with FDA De Novo clearance for non-prescription CGM access serving as the critical inflection signal indicating which connected monitor platforms maintain sustainable competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Submission | Non-prescription CGM clearance dissolves clinic-gated distribution barriers in United States pharmacy channels. |
| EU MDR Software Validation | Pre-validated algorithm clinical evidence creates first-mover advantage against mid-tier European challengers facing compliance cost spikes. |
| Telemedicine Platform Integration | Remote patient monitoring contracts embed CGM data streams into reimbursable chronic disease management workflows. |
| Backward Integration into Enzyme Biosensor R&D | Captive glucose oxidase stability development sustains margin control across North American and European retail channels. |
| Subscription Data Service Launch | AI-powered glycemic pattern analysis generates recurring revenue through mobile health platform nutrition coaching. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with endocrinologists, hospital purchasing committee members, biomedical engineers, pharmacy chain procurement directors, and telemedicine platform executives. Secondary validation drew from FDA 510(k) and De Novo filing databases, EU MDR notified body conformity assessments, CDSCO Medical Devices Rules import licensing records, and CMS Medicare reimbursement data. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across product type, technology, application, and end user segmentation dimensions.
Calibration against historical volume trajectories anchored forward projections across the analysis window, with electrochemical strip replacement cycle dynamics and CGM sensor wear duration as industry-specific demand drivers. Segmentation modeling incorporated product architecture differences, regulatory pathway complexity, and channel configuration variations. CAGRs derived from slope-consistent growth rate fitting to validated baseline values, with software-enabled platform adoption curves and prediabetes screening penetration rates as key forecast sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in precious metal commodity prices, trade policy shifts affecting Shenzhen manufacturing corridors, or reimbursement rate changes in United States employer wellness programs would shift the trajectory. Material shifts in FDA software-as-medical-device cybersecurity guidance or EU MDR algorithm validation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.