
 Type 2 Diabetes Market | 2026-2036
Type 2 Diabetes Market Size, Share, and Industry Trends Forecast 2026-2036
Type 2 Diabetes Market Outlook
Next-generation cardiometabolic efficacy standards are unwinding traditional glycemic-only prescribing patterns across the Type 2 Diabetes landscape. Novo Nordisk leverages its integrated manufacturing footprint to secure peptide supply chains for incretin therapies. Eli Lilly and Company anchors its position through R&D intensity in dual and triple agonist pipelines. Sanofi competes by sustaining geographic dominance in basal insulin markets across Europe and emerging economies.
Type 2 diabetes constitutes a chronic metabolic disorder characterized by insulin resistance and progressive beta-cell dysfunction, measured clinically by elevated fasting plasma glucose exceeding 126 mg/dL and HbA1c thresholds above 6.5%, with therapeutic management targeting both microvascular complication prevention and macrovascular risk reduction. GLP-1 agonists command premium positioning as the fastest-expanding product type due to demonstrated cardiovascular outcome benefits and weight-loss co-efficacy. SGLT2 inhibitors occupy a parallel growth trajectory in heart failure and chronic kidney disease adjacencies. Injectable delivery modes dominate high-value biologic administration, though oral formulations in development threaten to displace share in patient populations with needle aversion.
The FDA oversees approval pathways and post-market surveillance for cardiometabolic claims, while the EMA's centralized marketing authorization shapes commercial access across European member states and the WHO prequalification program influences procurement in low-income health systems. Regulatory stringency around cardiovascular outcome trials has elevated R&D costs but simultaneously created defensible moats for sponsors with proven outcome data. Stakeholders must monitor evolving reimbursement criteria that tie coverage to demonstrated reductions in hospitalization rather than surrogate glycemic endpoints alone.
Market Dynamics
Cardiometabolic outcome requirements are compressing the traditional glycemic-only value proposition for diabetes therapeutics, forcing manufacturers to demonstrate hospitalization reduction rather than HbA1c improvement alone.
Growth Catalysts
- CVOT Data Requirements:FDA mandates for cardiovascular outcome trials have created defensible competitive moats for sponsors with proven heart failure and renal protection data.
- Integrated Delivery Networks:United States hospital systems are expanding formulary access for GLP-1 therapies through value-based contracts tied to readmission metrics.
- Peptide Manufacturing Scale-Up:Multi-ton fermentation capacity expansions across North American and European contract manufacturing organizations are resolving prior supply constraints for incretin-based therapies.
Market Restraints
- API Concentration Risk:Active pharmaceutical ingredient production for GLP-1 agonists concentrates among a limited set of European fermentation specialists, creating single-source vulnerability.
- Reimbursement Friction:CMS coverage determinations in the United States impose step-therapy requirements that delay patient access to cardiometabolic-proven therapies until generic failure.
- Needle Aversion Limitation:Injectable delivery modes exclude an estimated 30-40% of patient populations with documented trypanophobia, capping penetration in primary care settings.
Strategic Opportunities
- Oral Formulation Development:Non-injectable incretin mimetics in Phase III pipelines threaten to capture needle-averse patient segments currently served by SGLT2 inhibitors alone.
- Chronic Kidney Disease Adjacency:Regulatory approvals for renal protection indications are opening nephrology prescribing channels previously inaccessible to diabetes-focused sales forces.
- Latin America Procurement:WHO prequalification pathways are enabling tender access for biosimilar basal insulins across public health systems in Brazil, Mexico, and Argentina.
Industry Challenges
- Biostatistics Talent Scarcity:Cardiovascular outcome trial design requires specialized expertise in adaptive trial methodologies and composite endpoint construction that outpaces academic pipeline output.
- Cold Chain Complexity:GLP-1 peptide stability requirements demand continuous 2-8°C distribution infrastructure that strains last-mile capabilities in rural and emerging market settings.
- Legacy System Integration:Electronic health record interoperability gaps between pharmacy benefit managers and clinical decision support tools fragment real-world evidence collection for outcome-based contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Type 2 Diabetes Market |
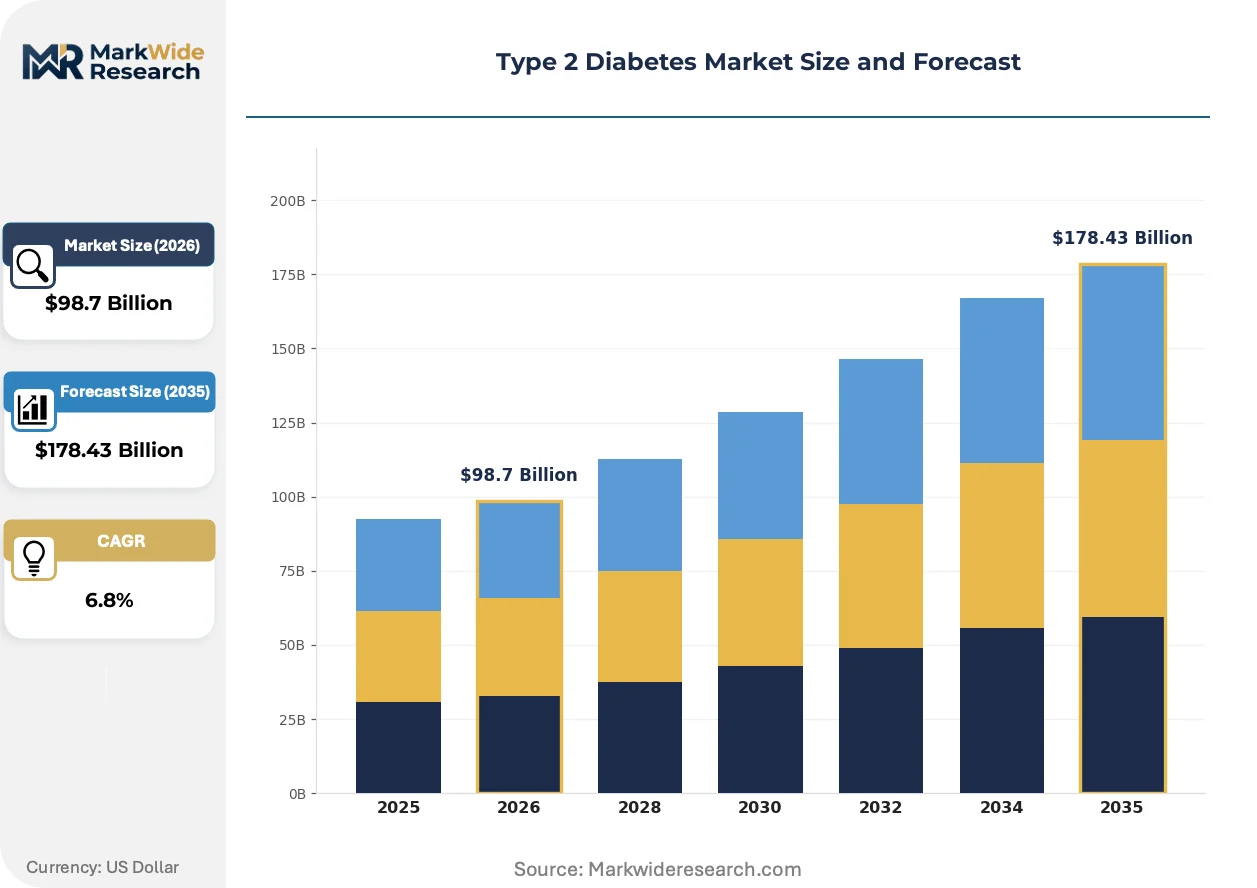
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, GLP-1 Agonists, DPP-4 Inhibitors, SGLT2 Inhibitors Therapy Area: Weight Management, Cardiovascular Health, Glycemic Control, Diabetes Prevention Delivery Mode: Injectables, Orals, Infusions, Combination Therapy End User: Clinics, Hospitals, Homecare, Pharmacies |
| Companies Covered | Novo Nordisk, Eli Lilly and Company, Sanofi, AstraZeneca, Merck & Co., Abbott Laboratories, Medtronic, Hoffmann-La Roche, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Type 2 Diabetes Market Strategic Shifts
Peptide engineering and delivery mechanism advances are converging with regulatory pressure for organ protection claims, reshaping how diabetes therapies demonstrate value beyond glucose control.
Wearable continuous glucose monitoring systems are miniaturizing from patch-based to fully implantable formats, enabling real-time dosing algorithm integration with automated insulin delivery. Endocrinology practices in the United States and Germany are adopting these closed-loop systems at accelerating replacement cycles for traditional fingerstick monitoring. This convergence is compressing the distinction between diagnostic and therapeutic device categories, forcing pharmaceutical sponsors to partner with sensor manufacturers for integrated therapy bundles.
EMA centralized marketing authorization procedures are tightening evidentiary standards for cardiovascular and renal outcome claims, requiring pre-specified hierarchical testing frameworks that extend trial duration and cost. Sponsors seeking heart failure indications must now demonstrate benefit across reduced and preserved ejection fraction subpopulations. European integrated delivery networks are responding by consolidating formulary decisions at national level, reducing physician discretion in therapy selection.
Specialty pharmacy distribution is displacing traditional retail channels for high-cost biologic diabetes therapies, concentrating patient access through limited networks with enhanced adherence monitoring capabilities. Payers in the United States are mandating exclusive distribution arrangements that capture injection data for outcome measurement. This channel consolidation is most pronounced in Medicare Part D and commercial employer segments, where pharmacy benefit managers extract rebates in exchange for preferred tier positioning.
Type 2 Diabetes Market Segmentation
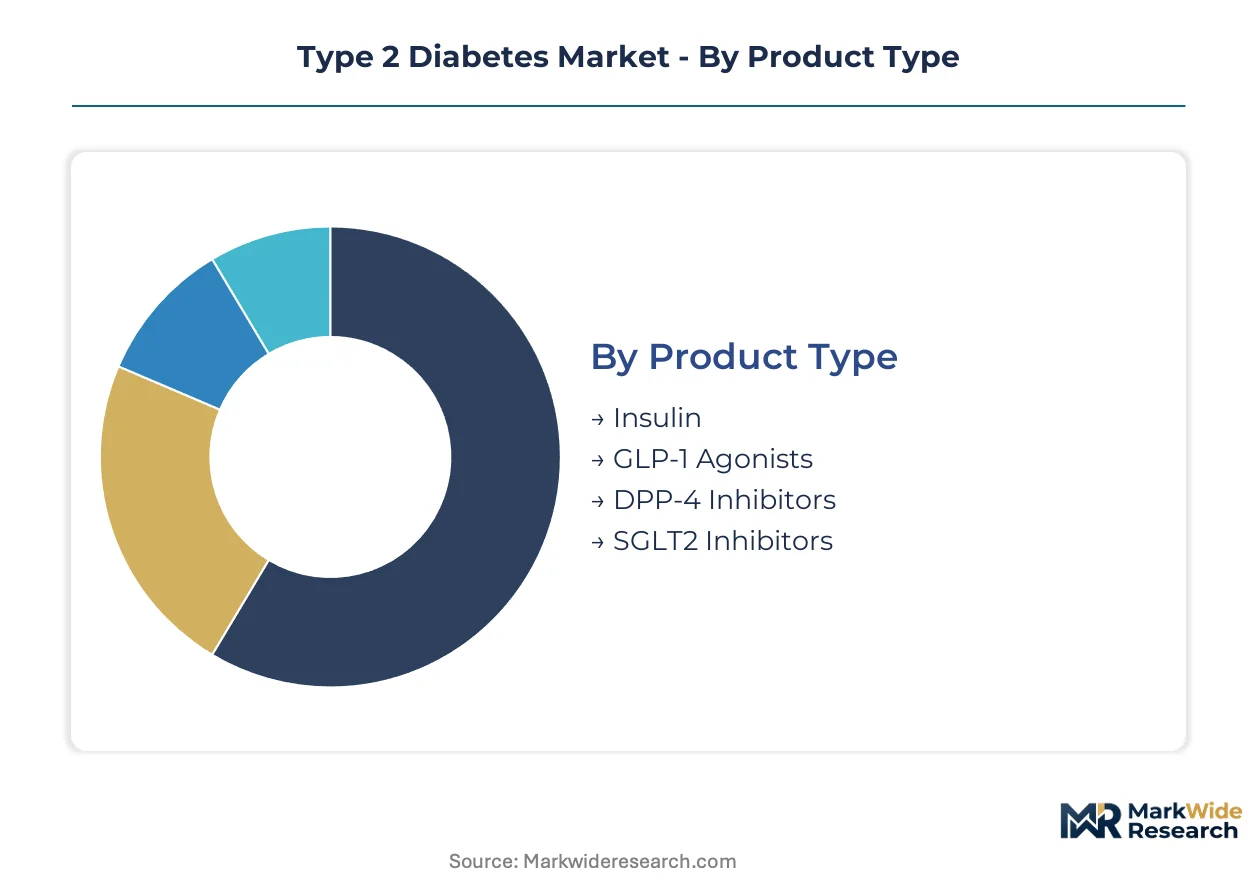
Segmentation in the Type 2 Diabetes market reveals how therapeutic substitution pressures reshape competitive boundaries across mechanism classes and care settings. Manufacturers must align portfolio investments with the divergence between hospital-driven cardiometabolic protocols and retail-accessible maintenance therapies.
Product Type:
GLP-1 agonists and SGLT2 inhibitors face the most intense substitution pressure as cardioprotective efficacy becomes the dominant prescribing criterion, eroding traditional insulin reliance.
- Insulin:Basal and prandial formulations remain essential for beta-cell failure stages, with demand concentrating in Medicare populations where prior authorization barriers delay incretin access. Manufacturing concentration among European fermentation specialists constrains pricing flexibility.
- GLP-1 Agonists:Peptide-based incretin mimetics demonstrate superior cardiovascular outcome profiles and weight-loss co-efficacy, driving United States hospital formulary expansion through value-based contracts tied to readmission reduction. Supply constraints from multi-ton fermentation scale-up limit penetration.
- DPP-4 Inhibitors:Oral gliptins face erosion as GLP-1 agonists and SGLT2 inhibitors capture cardiometabolic-proven indications, with residual demand in cost-sensitive markets requiring step-therapy compliance.
- SGLT2 Inhibitors:Small-molecule sodium-glucose cotransporter blockers extend into heart failure and chronic kidney disease adjacencies, opening nephrology prescribing channels previously inaccessible to diabetes-focused sales forces.
Insulin anchors the volume base while GLP-1 agonists gain share at the steepest rate.
Therapy Area:
Cost tier stratification separates premium cardiometabolic-proven therapies from commodity glycemic control, with reimbursement policies determining accessible indications.
- Weight Management:Anti-obesity applications of incretin therapies command premium pricing outside diabetes labeling, with United States specialty pharmacy distribution capturing injection data for outcome measurement.
- Cardiovascular Health:Heart failure and atherosclerotic risk reduction claims require FDA-mandated cardiovascular outcome trials, creating defensible moats for sponsors with proven ejection fraction benefit across reduced and preserved subpopulations.
- Glycemic Control:Traditional HbA1c-focused prescribing contracts in value-based arrangements, though EMA tightening evidentiary standards elevates trial duration and cost for glucose-only indications.
- Diabetes Prevention:Pre-diabetes pharmacologic intervention remains underpenetrated due to reimbursement friction and lifestyle intervention prioritization in public health guidelines.
Glycemic control retains the largest eligible population while cardiovascular health applications expand most quickly.
Delivery Mode:
Patient preference and adherence economics drive divergence between invasive administration and oral convenience, with needle aversion excluding 30-40% of primary care populations.
- Injectables:Pen devices and autoinjectors dominate high-value biologic administration for GLP-1 agonists and insulin, requiring continuous 2-8°C cold chain distribution that strains last-mile capabilities in rural settings.
- Orals:Small-molecule formulations in DPP-4 and SGLT2 classes capture needle-averse segments, though Phase III oral incretin mimetics threaten to displace injectable share upon approval.
- Infusions:Intravenous delivery concentrates in hospital acute care for diabetic ketoacidosis and perioperative management, with limited chronic disease application.
- Combination Therapy:Fixed-dose co-formulations reduce pill burden and improve adherence metrics, particularly in Medicare Part D populations with polypharmacy complexity.
Injectables command the revenue concentration while oral formulations climb the fastest.
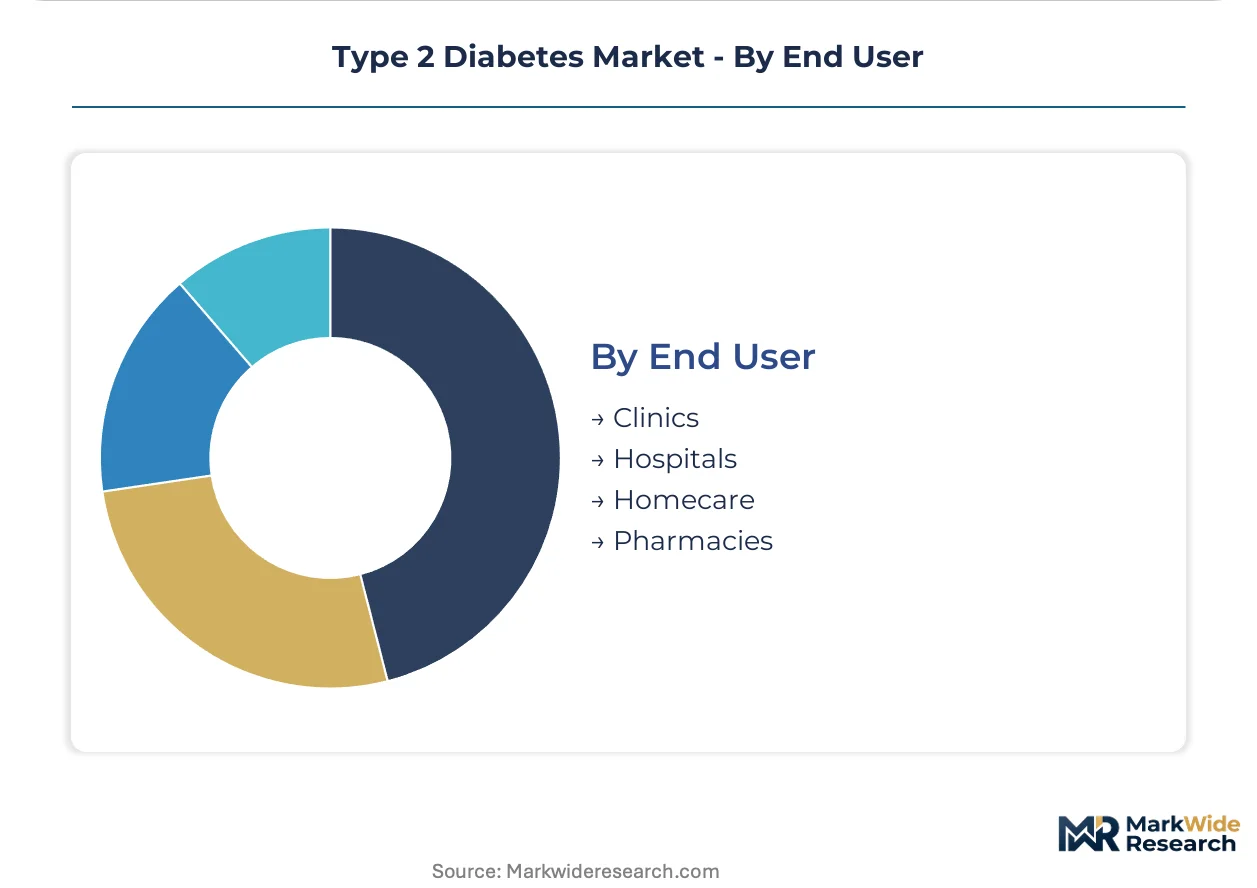
End User:
Channel consolidation into specialty pharmacy and integrated delivery networks fragments traditional retail access, with adherence monitoring capabilities determining network inclusion.
- Hospitals:Inpatient and outpatient systems negotiate value-based contracts for GLP-1 therapies, with electronic health record interoperability gaps fragmenting real-world evidence collection for outcome-based arrangements.
- Clinics:Endocrinology practices adopt closed-loop insulin delivery systems at accelerating replacement cycles, compressing diagnostic and therapeutic device categories.
- Homecare:Self-administered injection training and remote monitoring expand, though cold chain complexity limits GLP-1 peptide stability in patient home environments.
- Pharmacies:Retail channel displacement accelerates as pharmacy benefit managers mandate exclusive distribution through limited specialty networks with enhanced adherence capture.
Hospitals drive the highest-value prescribing while homecare channels expand most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for Type 2 Diabetes therapies diverges sharply across markets, with United States integrated delivery networks absorbing premium cardiometabolic-proven pricing while emerging economies prioritize cost-effective basal insulin access through public procurement channels.
United States
Hospital systems negotiate value-based contracts for GLP-1 therapies tied to readmission reduction metrics, with Medicare Part D and commercial payers mandating exclusive specialty pharmacy distribution. FDA cardiovascular outcome trial requirements create defensible moats for sponsors with proven heart failure data. The Boston-Cambridge biotech corridor anchors peptide manufacturing scale-up for incretin supply chains.
Germany
EMA centralized marketing authorization procedures tighten evidentiary standards for renal protection claims, requiring hierarchical testing frameworks across ejection fraction subpopulations. National-level formulary consolidation reduces physician discretion in therapy selection. The Rhine-Main pharmaceutical cluster concentrates fermentation capacity for active pharmaceutical ingredient production.
Japan
PMDA review pathways prioritize cardiovascular and renal outcome data for reimbursement listing, with METI industrial policy supporting domestic manufacturing of continuous glucose monitoring devices. Aging demographics expand the addressable patient population for complication-prevention therapies. The Kansai region hosts specialized biostatistics capabilities for adaptive trial design.
India
CDSCO regulatory harmonization with WHO prequalification standards enables tender access for biosimilar basal insulins across public health systems. Central government procurement schemes prioritize cost containment in step-therapy protocols. The Hyderabad-Visakhapatnam pharmaceutical belt scales fermentation infrastructure for peptide API production.
Brazil
ANVISA accelerated review pathways for cardiometabolic indications reshape clinical trial design for regional registration strategies. Federal procurement through the Unified Health System concentrates demand for cost-tier stratified therapies. The São Paulo-Rio de Janeiro corridor anchors specialty pharmacy distribution networks with cold chain capabilities for biologic storage.
Type 2 Diabetes Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Type 2 Diabetes market, with integrated fermentation specialists commanding premium positioning in peptide-based incretin therapies while diversified pharmaceutical conglomerates compete on portfolio breadth and geographic reach. Market structure consolidates around three strategic tiers: peptide manufacturing specialists with captive supply chains, cardiometabolic outcome data leaders with proven FDA-approved indications, and basal insulin incumbents defending share through emerging market access. Dominant competitive moves include backward integration into multi-ton fermentation capacity and strategic partnerships with continuous glucose monitoring device manufacturers for closed-loop system bundles.
Within the peptide manufacturing specialist tier, Novo Nordisk and Eli Lilly and Company exemplify archetypes that anchor competitive positioning through integrated supply chain control and R&D intensity in dual and triple agonist pipelines. Sanofi occupies a distinct position as a diversified European pharmaceutical company sustaining geographic dominance in basal insulin markets. These three entities represent the primary competitive anchors shaping substitution dynamics between incretin-based and insulin-dependent therapeutic pathways.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly and Company |
| Sanofi |
| AstraZeneca |
| Merck & Co. |
| Abbott Laboratories |
| Medtronic |
| Hoffmann-La Roche |
| Novartis |
| Others |
Value Chain & Pricing Dynamics
Ninety-day peptide fermentation lead times anchor pricing power for GLP-1 agonist manufacturers, concentrating margin capture among integrated European specialists while forcing hospital systems into multi-year offtake commitments. This inventory-to-pricing linkage tightens as multi-ton capacity expansions in Denmark and Germany resolve supply constraints without collapsing premium positioning.
Pricing Analysis
After-sales adherence monitoring and injection data capture drive lifetime value for specialty pharmacy networks negotiating exclusive distribution rights. Three-tier pricing structure across premium cardiometabolic-proven therapies, standard glycemic control agents, and economy basal insulins reflects FDA outcome data stratification. Pricing pressure stems from CMS step-therapy mandates delaying premium therapy access until generic failure. Medicare Part D populations exhibit highest price sensitivity, while integrated delivery networks absorb premium pricing for readmission reduction contracts.
Supply Chain Analysis
Strait of Hormuz transit vulnerability for cold-chain logistics underwrites distribution risk for peptide-based therapies requiring continuous 2-8°C stability. Active pharmaceutical ingredient production concentrates in Denmark, Germany, and Switzerland, with fermentation capacity expansion lagging demand growth by eighteen to twenty-four months. Supply chains draw from recombinant yeast strains, chromatography resins, and borosilicate vials as critical inputs. Single-source vulnerability in European fermentation specialists creates structural risk. Distribution runs through limited specialty pharmacy networks with enhanced cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized biostatistics expertise for adaptive cardiovascular outcome trial design represents the scarcest capability in this market, with academic pipeline output trailing sponsor demand by a widening margin. This talent gap constrains pipeline velocity for cardiometabolic indication expansion.
For Market Incumbents: Fortify peptide manufacturing capacity through backward integration into multi-ton fermentation facilities in Denmark and North Carolina, securing captive supply chains against API concentration risk. Defend formulary positioning by embedding continuous glucose monitoring device partnerships into closed-loop system bundles, neutralizing biosimilar basal insulin threats from emerging market entrants. For New Entrants and Emerging Players: Differentiate on oral incretin mimetic delivery mechanisms, capturing the thirty to forty percent needle-averse patient population currently served by SGLT2 inhibitors alone. Target nephrology prescribing channels for chronic kidney disease adjacencies, leveraging renal protection data requirements that favor smaller sponsors with focused trial designs. Pursue WHO prequalification pathways for biosimilar basal insulin tender access across Latin American public health systems. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across peptide manufacturing infrastructure, favoring asset-heavy integrated specialists over R&D-only platform companies. Long-term viability accrues to sponsors with captive fermentation capacity and proven cardiovascular outcome data. Acquisition target archetype: mid-cap biotech with Phase III oral incretin assets and established nephrology KOL relationships. Monitor FDA accelerated approval pathway expansion for cardiometabolic indications as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Multi-ton fermentation capacity in Denmark resolves GLP-1 supply constraints for hospital system contracts. |
| Clinical Trial Advancement | Adaptive cardiovascular outcome trial designs reduce duration for heart failure indication submissions to FDA. |
| Regulatory Approval Pathway | WHO prequalification enables tender access for biosimilar insulins across Brazil and Mexico public procurement. |
| Strategic Partnership | Continuous glucose monitoring device integration compresses diagnostic-therapeutic categories for closed-loop bundles. |
| Pipeline Diversification | Dual and triple agonist R&D programs extend cardiometabolic claims beyond glucose control endpoints. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, formulary directors at integrated delivery networks, and payer access specialists. Secondary validation drew from FDA filings, EMA centralized marketing authorization procedures, ClinicalTrials.gov cardiovascular outcome trial registrations, and hospital formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Across the analysis window, forecasts applied treatment line stratification, dosage form differentiation, administration route segmentation, and regional regulatory cluster clustering. CAGRs were derived from elasticity-adjusted volume projections and price evolution assumptions tied to reimbursement policy shifts. Forecast inputs incorporated Medicare Part D coverage determination timelines and EMA evidentiary standard tightening for renal protection claims.
Material uncertainties — regulatory pathway delays, biosimilar entry acceleration, and cold-chain infrastructure failures — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding cardiovascular outcome trial success rates and formulary expansion velocity. Practitioners should keep alternative scenarios live as CMS step-therapy policy and peptide manufacturing capacity utilization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
Vietnam Diabetes Care Devices Market
Diabetes Care
Insulin Resistance Market
Diabetes Care
Germany Continuous Glucose Monitoring Market
Diabetes Care
Oman Diabetes Drugs Market
Diabetes Care
Europe Diabetic Foot Ulcer Treatment Market
Diabetes Care
Malaysia Diabetes Care Devices Market
Diabetes Care
Disposable Insulin-Delivery Device Market
Diabetes Care
United Kingdom Continuous Glucose Monitoring Market
Diabetes Care
India Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Latin America Diabetes Care Devices Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
Glycated Albumin Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
Philippines Oral Anti-Diabetic Drug Market
Diabetes Care
Middle-East and Africa Blood Glucose Monitoring Market