
 North America Continuous Glucose Monitoring Market | 2026-2036
North America Continuous Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
North America Continuous Glucose Monitoring Market Analytics
Hospital end-use is expanding as integrated delivery networks embed glucose telemetry into perioperative and intensive care workflows. Abbott Laboratories leverages manufacturing scale across multiple sensor generations to sustain supply security for large health systems. Dexcom differentiates through software interoperability with insulin delivery platforms, while Medtronic anchors its position through backward integration into automated insulin dosing algorithms.
Continuous glucose monitoring comprises electrochemical sensor systems that measure interstitial glucose concentrations via enzymatic reactions, transmitting data to receivers or smartphones for real-time glycemic visibility. Wearable devices dominate volume shipments, though implantable sensors capture premium pricing from patients seeking extended wear durations. Real-time monitoring leads technology adoption in hospital settings, whereas flash glucose monitoring occupies the home care channel where user-initiated scanning reduces alert fatigue.
FDA software-as-a-medical-device guidance shapes product development timelines for algorithm-driven glucose prediction features, while HIPAA privacy requirements constrain cloud-based data architectures. The Centers for Medicare & Medicaid Services reimbursement determinations directly influence patient access across Medicare Advantage plans. Stakeholders must monitor FDA pre-certification pilot expansions and state-level telehealth parity laws that determine remote prescribing eligibility for CGM-integrated insulin systems.
Market Dynamics
Hospital procurement of real-time glucose monitoring systems is accelerating as integrated delivery networks in Texas, California, and New York embed glycemic telemetry into perioperative workflows. The FDA's software-as-a-medical-device framework is compressing clearance timelines for algorithm-driven prediction features, reshaping competitive positioning around interoperability rather than hardware specifications.
Growth Catalysts
- CMS Reimbursement Expansion:Medicare Advantage plans in the United States now cover CGM-integrated insulin systems, expanding patient access across aging populations with Type 2 diabetes.
- Texas Integrated Delivery Networks:Hospital systems across Dallas and Houston are deploying enterprise-wide glucose telemetry, creating template contracts that other states replicate.
- Enzymatic Sensor Miniaturization:Advances in electrochemical reaction stability are extending sensor wear durations, reducing per-patient monitoring costs for health systems.
Market Restraints
- Platinum Electrode Supply Concentration:Sensor manufacturing depends on platinum catalyst suppliers concentrated in South Africa, exposing production schedules to mining output volatility.
- HIPAA Cloud Architecture Constraints:Privacy requirements limit real-time data processing architectures, forcing vendors to maintain expensive on-premise infrastructure for hospital deployments.
- Flash Glucose Monitoring Substitution:User-initiated scanning systems capture price-sensitive home care segments, compressing margins for real-time alert-based platforms in non-critical settings.
Strategic Opportunities
- New York State Telehealth Parity Laws:Remote prescribing eligibility for CGM-integrated insulin systems is expanding, enabling virtual endocrinology practices to serve rural patient populations.
- Perioperative Glycemic Protocols:Surgical suites represent underpenetrated demand, with anesthesia departments seeking closed-loop glucose-insulin coordination for cardiac and orthopedic procedures.
- Algorithm-Artificial Pancreas Convergence:Predictive glucose forecasting is merging with automated insulin delivery, creating integrated metabolic management platforms for intensive care units.
Industry Challenges
- Biocompatibility Engineer Scarcity:Sensor development requires specialists in foreign body response mitigation, with talent concentrated at a handful of academic medical centers.
- FDA Pre-Certification Timeline Uncertainty:Pilot program expansions for software-based glucose prediction lack predictable milestones, complicating product roadmap planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Continuous Glucose Monitoring Market |
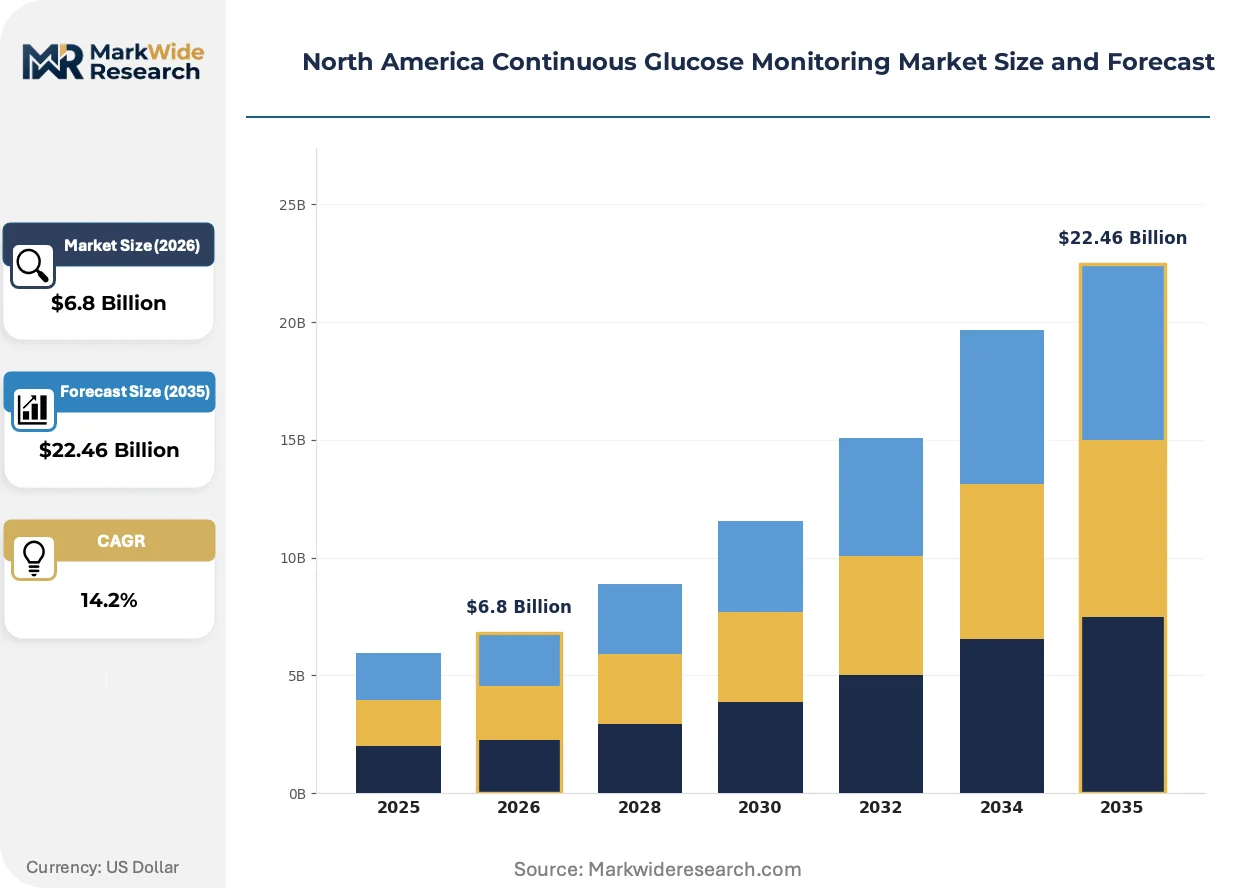
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
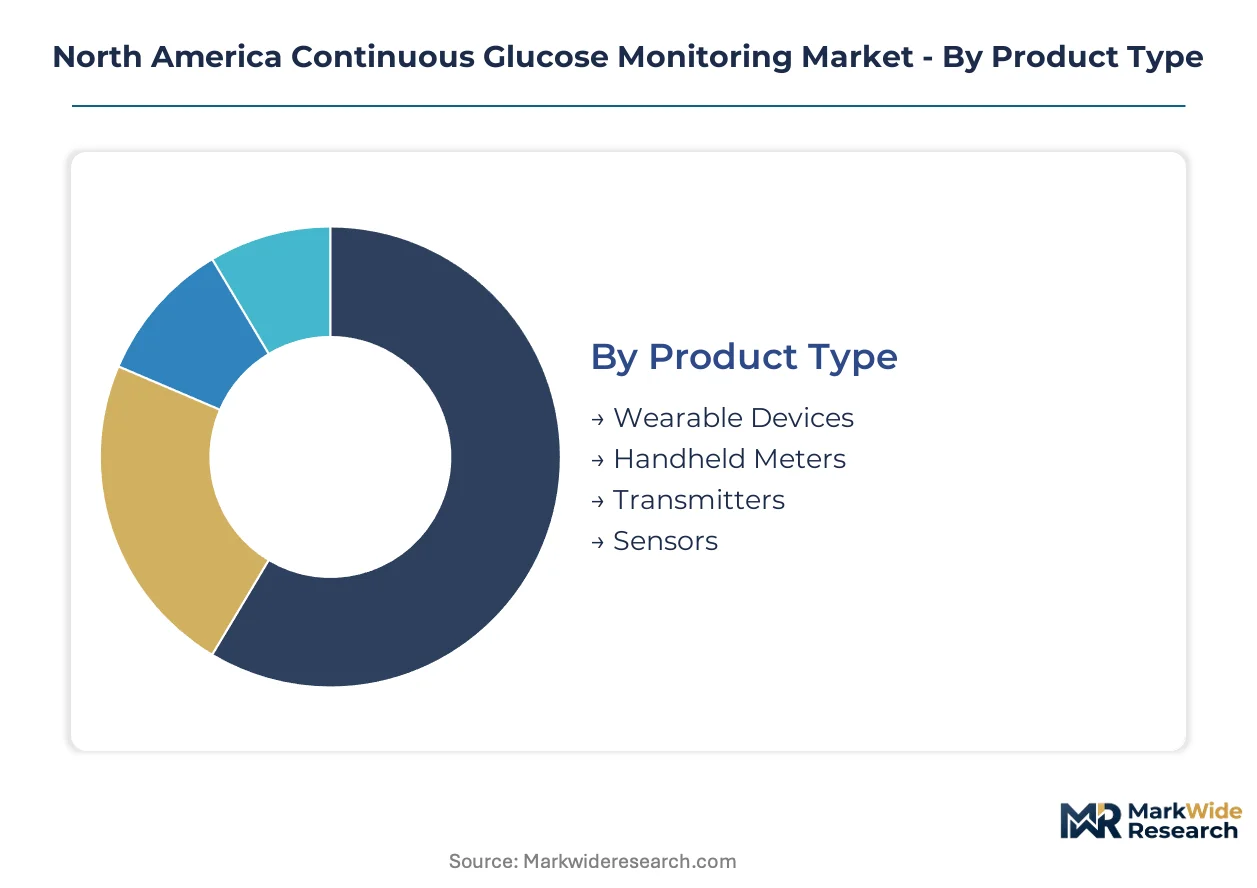
| Segmentation | Product Type: Wearable Devices, Handheld Meters, Transmitters, Sensors Technology: Real-Time Monitoring, Flash Glucose Monitoring, Implantable Sensors, Continuous Glucose Sensors End User: Hospitals, Home Care, Ambulatory Surgical Centers, Clinics Application: Diabetes Management, Research Activities, Clinical Trials, Health Monitoring |
| Companies Covered | F. Hoffmann-La Roche, Ascensia Diabetes Care, Abbott Laboratories, Novo Nordisk, MiniMed, Dexcom, Senseonics, Ypsomed, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Continuous Glucose Monitoring Market Evolving Landscape
Algorithm-driven glucose prediction is absorbing capital allocation from hardware engineering teams, with vendors prioritizing cloud-based analytics over incremental sensor form factor improvements. This shift reflects buyer demand for actionable glycemic intelligence rather than raw data streams.
Multiplexed electrochemical arrays are absorbing development resources previously dedicated to single-analyte glucose measurement. Hospital procurement teams in California are piloting these platforms for simultaneous ketone and lactate monitoring in diabetic ketoacidosis protocols. The technology is absorbing premium pricing power from conventional single-parameter systems by consolidating multiple metabolic indicators into one wearable.
FDA software-as-a-medical-device guidance is reshaping submission strategies for glucose prediction algorithms, requiring documentation of machine learning training datasets and real-world performance validation. Manufacturers are restructuring quality systems to accommodate iterative software updates without full 510(k) resubmission. Hospital customers in New York are demanding pre-certification pathway participation as a contract prerequisite, favoring vendors with established FDA relationships.
Health system procurement is consolidating around enterprise glucose telemetry contracts that bundle sensors, data platforms, and clinical decision support. Integrated delivery networks are displacing individual hospital purchasing autonomy, with Texas systems leading multi-facility standardization. This concentration is most visible in Medicare Advantage plan negotiations, where payers are demanding uniform glycemic outcome metrics across hospital networks.
North America Continuous Glucose Monitoring Market Segmentation
CGM market segmentation reveals how technology specifications, care settings, and patient populations create distinct commercial battlegrounds. Each axis demands tailored regulatory strategies and reimbursement approaches.
Product Type:
Electrochemical sensor architectures define the hardware hierarchy, with form factor and wear duration determining procurement economics across care settings.
- Wearable Devices:Enzymatic electrochemical sensors with subcutaneous needle electrodes dominate hospital telemetry contracts. Demand concentrates in Texas integrated delivery networks seeking enterprise-wide glycemic standardization, driven by perioperative protocol mandates.
- Sensors:Platinum-catalyzed glucose oxidase membranes constitute the consumable revenue engine. California health systems are consolidating sensor procurement through multi-year enterprise agreements, constrained by South African platinum supply volatility.
- Transmitters:Bluetooth Low Energy radio modules bridge sensor-to-receiver communication. HIPAA cloud architecture limitations force on-premise data infrastructure investments.
- Handheld Meters:Capillary blood validation devices serve calibration and backup functions. Home care channels in rural Medicare Advantage populations sustain residual demand.
Mature deployment sits with Sensors. Newer deployment is concentrated in Wearable Devices.
Technology:
Data generation modalities separate alert-driven clinical workflows from patient-initiated monitoring paradigms.
- Real-Time Monitoring:Automated glucose telemetry with predictive threshold alarms enables closed-loop insulin coordination. New York hospital systems embed these platforms into intensive care glycemic protocols, driven by surgical outcome metrics tied to reimbursement.
- Flash Glucose Monitoring:User-activated NFC scanning eliminates alert fatigue for stable Type 2 patients. Price-sensitive home care segments in Medicare Advantage plans favor this modality, compressing real-time platform margins in non-critical settings.
- Implantable Sensors:Long-duration subcutaneous implants with extended biocompatibility coatings command premium pricing. Patients seeking 90-day wear intervals drive niche demand.
- Continuous Glucose Sensors:Factory-calibrated electrochemical arrays reduce fingerstick dependencies. Ambulatory surgical centers adopt these for pre-operative glucose stabilization.
Established penetration centers on Real-Time Monitoring. Flash Glucose Monitoring is climbing the fastest among technology modalities.
End User:
Procurement authority and reimbursement pathways segment the customer base into institutional and consumer-directed channels.
- Hospitals:Enterprise glucose telemetry contracts bundle sensors, platforms, and clinical decision support. Integrated delivery networks in Texas, California, and New York displace individual facility purchasing autonomy.
- Home Care:Direct-to-patient distribution through durable medical equipment suppliers. Medicare Advantage coverage expansion is broadening access across aging Type 2 populations.
- Ambulatory Surgical Centers:Pre-operative glucose screening and perioperative monitoring for same-day procedures. Outpatient surgical volume growth sustains demand.
- Clinics:Endocrinology practices and primary care sites with remote monitoring capabilities. New York telehealth parity laws enable virtual prescribing eligibility.
Volume concentration rests with Hospitals. Home Care represents the steepest expansion trajectory as reimbursement broadens.
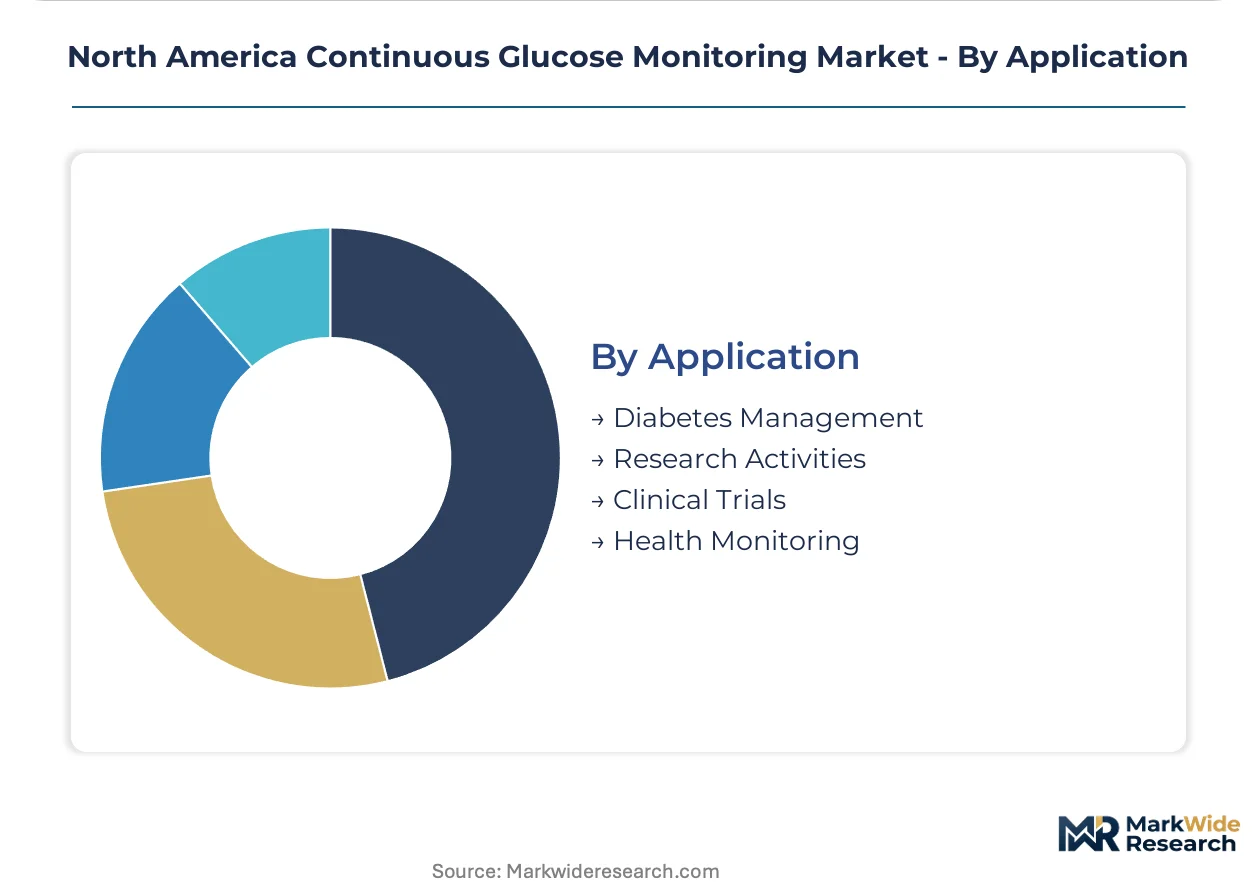
Application:
Use case specificity determines algorithm training requirements and regulatory submission pathways.
- Diabetes Management:Glycemic control for Type 1 and insulin-requiring Type 2 patients constitutes the core commercial foundation. FDA software-as-a-medical-device framework accelerates clearance for prediction algorithms.
- Clinical Trials:Continuous glucose data as pharmacokinetic endpoints for diabetes drug development. Pharmaceutical sponsors demand interoperable data formats.
- Research Activities:Metabolic physiology studies and artificial pancreas algorithm validation. Academic medical centers with biocompatibility engineering expertise anchor demand.
- Health Monitoring:Wellness-oriented glucose tracking for prediabetes and metabolic health. Direct-to-consumer channels bypass traditional reimbursement.
Revenue maturity aligns with Diabetes Management. Research Activities are gaining share fastest through artificial pancreas convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in Texas and California concentrate hospital procurement, while CMS reimbursement expansion across Medicare Advantage networks anchors patient access growth. State-level telehealth parity laws in New York enable virtual prescribing for integrated insulin systems.
United States
Integrated delivery networks in Texas, California, and New York drive enterprise glucose telemetry adoption, with Dallas and Houston health systems deploying perioperative protocols. FDA software-as-a-medical-device guidance accelerates clearance timelines for algorithm-driven prediction features. Texas Medical Center anchors hospital procurement standardization that other states replicate.
Canada
Provincial health authorities in Ontario and Quebec expand CGM coverage for Type 1 diabetes management, while Health Canada streamlines approvals for interoperable insulin delivery platforms. Health Canada guidance on software-as-a-medical-device aligns with FDA frameworks. Toronto's hospital networks pilot enterprise glucose monitoring for surgical glycemic control.
Mexico
Private hospital chains in Mexico City and Monterrey adopt real-time glucose telemetry for diabetes management in affluent patient segments. COFEPRIS regulatory pathways for medical device software lag FDA timelines, constraining algorithm-based product launches. Guadalajara's medical device distributors serve as regional logistics hubs for sensor supply.
California
Medicare Advantage penetration among aging Type 2 populations sustains home care demand, while Kaiser Permanente and Sutter Health consolidate sensor procurement through multi-year enterprise agreements. State privacy regulations exceed HIPAA requirements, complicating cloud-based data architectures for hospital deployments. Silicon Valley technology clusters absorb development resources for predictive glucose analytics.
New York
Telehealth parity laws enable virtual endocrinology practices to prescribe CGM-integrated insulin systems for rural patient populations across upstate regions. New York-Presbyterian and Northwell Health embed real-time monitoring into intensive care glycemic protocols. Buffalo and Rochester health systems replicate Texas enterprise contracting templates for multi-facility standardization.
North America Continuous Glucose Monitoring Market Competitive Landscape
Top-tier vendors anchor hospital enterprise contracts, while mid-scale specialists occupy regional home care channels. The vendor base stratifies across three tiers: integrated metabolic management platforms, sensor-hardware pure-plays, and algorithm-software developers. Two strategic archetypes dominate—backward-integrated insulin delivery systems and interoperability-focused telemetry platforms. Competitive moves concentrate on FDA pre-certification pathway participation and enterprise contract bundling.
Among diversified health technology conglomerates, Abbott Laboratories and Medtronic exemplify scale-driven supply security for large health systems, while Dexcom occupies a position within the software interoperability tier. These three anchors represent distinct competitive vectors: manufacturing scale, automated insulin dosing integration, and platform openness respectively.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Ascensia Diabetes Care |
| Abbott Laboratories |
| Novo Nordisk |
| MiniMed |
| Dexcom |
| Senseonics |
| Ypsomed |
| Medtronic |
| Others |
Value Network & Pricing Analysis
Enzymatic sensor miniaturization and factory-calibration advances are compressing per-patient monitoring costs while concentrating manufacturing scale among vendors with multi-generation sensor platforms. This dual shift simultaneously expands Medicare Advantage plan coverage economics and tightens supply security requirements for platinum-catalyzed glucose oxidase membranes sourced from South African mining operations.
Pricing Analysis
Short lead-time premiums for hospital enterprise contracts run 15-25% above standard procurement schedules, while spot inventory discounts attract price-sensitive durable medical equipment suppliers in home care channels. Three-tier pricing structure across premium, standard, and economy levels separates FDA pre-certification pathway participants from second-tier vendors and unbranded sensor alternatives. Cost compression in the economy tier is intensifying because flash glucose monitoring substitutes capture stable Type 2 patient segments. Medicare Advantage beneficiaries exhibit highest price sensitivity, whereas integrated delivery networks in Texas prioritize supply security over unit cost.
Supply Chain Analysis
Reverse logistics for transmitter refurbishment and sensor recycling are emerging cost centers as extended-wear devices accumulate in home care populations. Platinum catalyst supply draws from South Africa, sensor substrate manufacturing rests on German precision film suppliers, and final assembly concentrates in Mexico and Costa Rica for US market access. Single-source vulnerability in South African platinum mining exposes production schedules to commodity volatility. Distribution runs through GPO contracts for hospital systems and durable medical equipment suppliers for direct-to-patient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
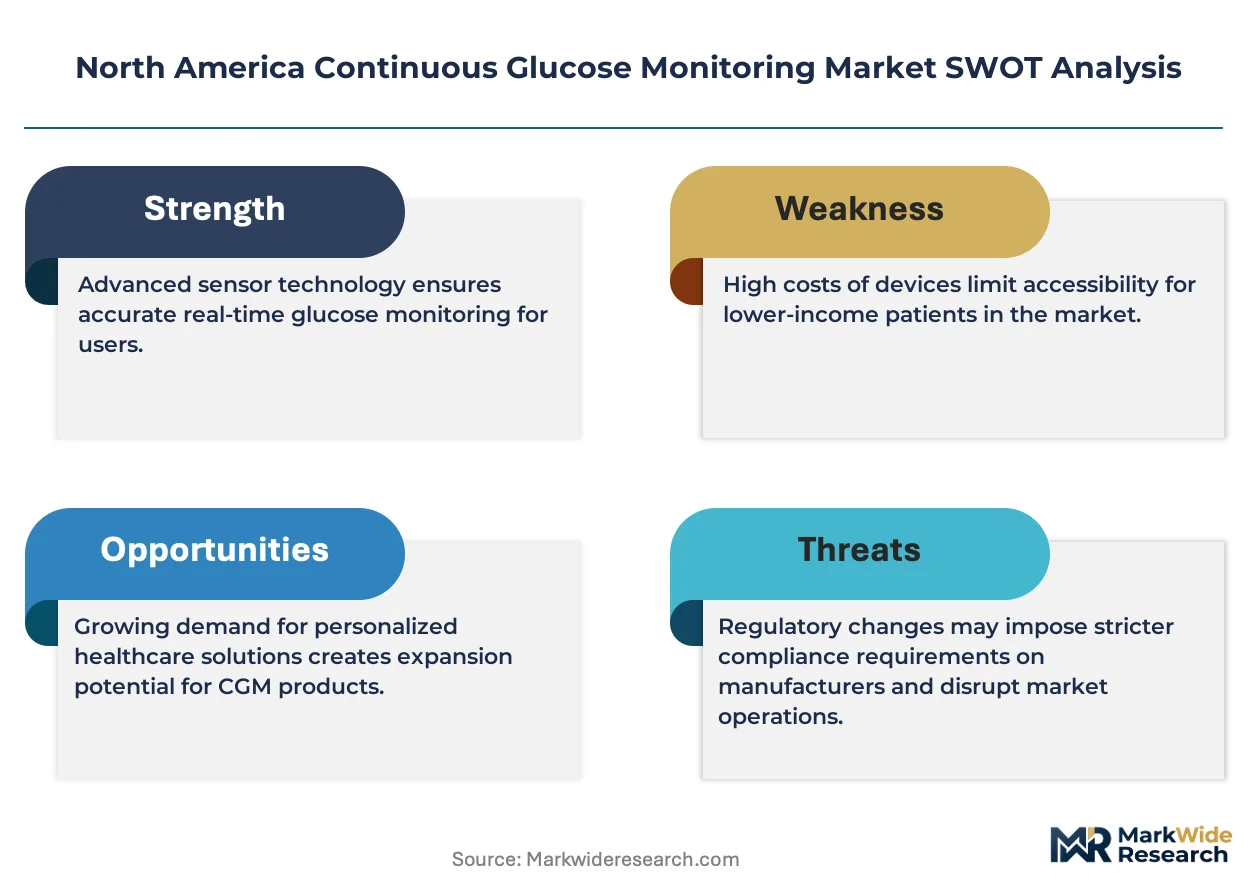
The North America Continuous Glucose Monitoring Market operates as a cost-of-compliance story where FDA software-as-a-medical-device pre-certification creates a barrier-to-entry moat favoring established vendors with iterative update capabilities.
For Market Incumbents: Acquire biocompatibility engineering talent pools concentrated at academic medical centers in California and Massachusetts. Backward integration into platinum catalyst sourcing and captive sensor membrane production defends against South African supply volatility. Investment in HIPAA-compliant on-premise data architectures preserves hospital contract eligibility against cloud-native entrants lacking infrastructure scale. For New Entrants and Emerging Players: Algorithm-first interoperability platforms with open API architectures represent the most penetrable wedge for hospital system adoption. Target ambulatory surgical centers in underserved Mountain West states where perioperative glycemic protocols remain underdeployed. Partner with virtual endocrinology practices enabled by New York telehealth parity laws to bypass entrenched GPO contracting channels. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified health technology conglomerates seeking metabolic management platform completeness. Long-term viability hinges on FDA pre-certification pathway participation and Medicare Advantage reimbursement lock-in. Monitor Texas Medical Center contracting templates as early signals of enterprise standardization waves spreading to California and New York systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway Participation | Accelerates algorithm update cycles without full 510(k) resubmission for glucose prediction features. |
| Hospital System Partnership | Texas Medical Center enterprise contracts establish template procurement terms replicated across integrated delivery networks. |
| Software Companion Development | Cloud-based analytics platforms absorb capital allocation from incremental hardware form factor engineering. |
| Reimbursement Strategy | Medicare Advantage coverage expansion determines patient access across aging Type 2 populations. |
| Backward Integration | Captive platinum catalyst sourcing mitigates South African mining output volatility exposure. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contract filings, and CMS Medicare data underwrites the qualitative findings. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and endocrinology practice administrators combined with secondary validation from FDA 510(k) filings, Health Canada guidance documents, and hospital procurement RFP archives. Bottom-up sensor shipment modeling and top-down reimbursement coverage analysis triangulate market sizing across the analysis window.
Comparable-period anchoring to historical CMS reimbursement determination timelines and FDA clearance velocity metrics structured the projection horizon. Segmentation dimensions modeled include product type, technology modality, end-user channel, and application specificity alongside state-level telehealth parity law adoption patterns. CAGRs derived from fitted growth curves applied to reimbursement expansion scenarios and hospital enterprise contract penetration rates. Industry-specific inputs incorporate platinum price volatility indices and Medicare Advantage plan coverage expansion trajectories.
Several conditions sit outside the modeled scope, including COFEPRIS regulatory pathway delays affecting Mexico market entry and unforeseen biocompatibility coating failures requiring sensor recalls. Forecasts reflect documented assumptions regarding FDA pre-certification pilot program expansion continuity and platinum supply chain stability. Practitioners should monitor Texas integrated delivery network contracting template adoption rates and New York telehealth parity law enforcement guidance for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Asia Pacific Blood Glucose Monitoring Market
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
Australia Self-Monitoring Blood Glucose Market
Diabetes Care
Philippines Oral Anti-Diabetic Drug Market
Diabetes Care
Brazil Continuous Glucose Monitoring Market
Diabetes Care
Global Type 1 Diabetes (T1D) Market
Diabetes Care
Global Smart Diabetes Management Market
Diabetes Care
France Insulin Infusion Pump Market
Diabetes Care
Global Pet Diabetes Care Market
Diabetes Care
Canada Self-Monitoring Blood Glucose Market
Diabetes Care
Japan Oral Anti-Diabetic Drug Market
Diabetes Care
Internet of Things for Diabetes Market
Diabetes Care
Antidiabetics Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Spain Self-Monitoring Blood Glucose Devices Market