
 Internet of Things for Diabetes Market | 2026-2036
Internet of Things for Diabetes Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Things for Diabetes Market Foresight
A shortage of clinical data scientists with dual expertise in endocrinology and embedded systems engineering is unwinding the pace at which IoT diabetes platforms achieve regulatory clearance and clinical validation. Dexcom leverages its vertical integration in sensor manufacturing to sustain quality consistency across production scales. Abbott anchors its competitive position through broad geographic distribution of its FreeStyle Libre platform. Medtronic differentiates via deep integration between its insulin pumps and continuous glucose monitoring ecosystems.
Internet of Things for Diabetes encompasses networked medical devices, wearable biosensors, cloud-connected insulin delivery systems, and mobile health applications that transmit glycemic data in real time, typically operating via Bluetooth Low Energy or NFC protocols with data refresh intervals under five minutes to enable closed-loop therapeutic decisions. Glucose Monitors and Wearable Devices occupy the largest addressable segments due to established reimbursement codes and patient familiarity, while Machine Learning and Cloud Computing represent the fastest-expanding technology layers as predictive algorithms reduce hypoglycemic events. Mobile Applications are emerging as a concentrated margin pool where recurring software subscriptions offset hardware commoditization pressures.
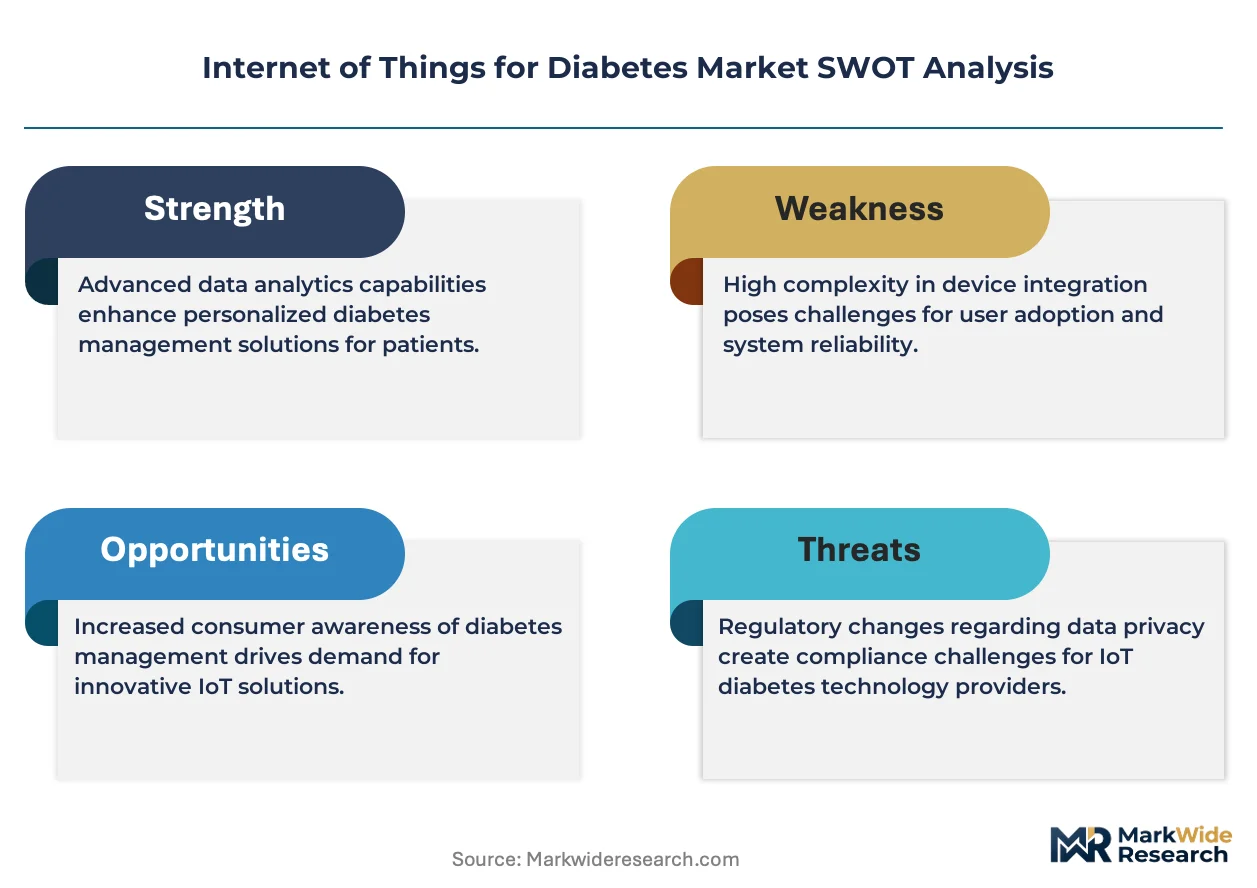
FDA premarket cybersecurity requirements and the EU MDR technical documentation standards are elevating compliance costs for connected diabetes devices while simultaneously creating barriers to entry for undercapitalized entrants. HIPAA in the United States and GDPR in Europe impose strict constraints on cross-border patient data flows, forcing vendors to architect region-specific cloud infrastructure. Stakeholders must weigh the capital requirements of multi-jurisdiction regulatory compliance against the revenue premium commanded by certified interoperability with hospital electronic health record systems.
Market Dynamics
FDA premarket cybersecurity requirements and EU MDR technical documentation standards are elevating compliance costs for connected diabetes devices while simultaneously creating barriers to entry for undercapitalized market participants.
Growth Catalysts
- Reimbursement pathway maturation:CMS coverage determinations for continuous glucose monitoring in the United States and parallel decisions by Germany's G-BA are expanding addressable patient populations beyond Type 1 diabetes into Type 2 and prediabetic cohorts.
- Bluetooth Low Energy protocol standardization:The IEEE 11073-10425 standard for personal health device communication is reducing interoperability friction between sensors, insulin pumps, and mobile health platforms.
- Home care setting migration:Post-acute care models in Japan and the Netherlands are accelerating deployment of remote patient monitoring infrastructure that integrates glucose telemetry with telemedicine workflows.
Market Restraints
- Input cost volatility:Platinum-group metal prices for electrochemical sensor electrodes and specialized polymer substrates for biocompatible adhesives are subject to supply concentration in South African and Russian mining operations.
- Regulatory friction:GDPR Article 44 restrictions on cross-border health data transfers are forcing vendors to maintain redundant cloud infrastructure across European Economic Area jurisdictions.
- Technical limitation:Enzymatic glucose oxidase sensors exhibit calibration drift in hypoxic tissue conditions, constraining accuracy during sleep or cardiovascular exercise.
Strategic Opportunities
- Underpenetrated geography:India's National Digital Health Mission credentialing framework creates regulatory tailwinds for cloud-connected diabetes management platforms targeting its 77 million diagnosed diabetic population.
- Technology convergence:Integration of non-invasive spectroscopic sensing with machine learning-based motion artifact rejection is opening pathways for wrist-worn continuous glucose monitors.
- Distribution innovation:Direct-to-consumer pharmacy channels in Brazil, bypassing traditional durable medical equipment distributors, are compressing patient acquisition costs for subscription-based sensor replenishment models.
Industry Challenges
- Clinical data science talent scarcity:Dual expertise in endocrinology and embedded systems engineering is unwinding regulatory clearance timelines as FDA and EMA demand algorithmic transparency documentation.
- Certification timeline compression:EU MDR notified body capacity constraints are extending technical documentation review periods for Class IIb connected insulin delivery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Things for Diabetes Market |
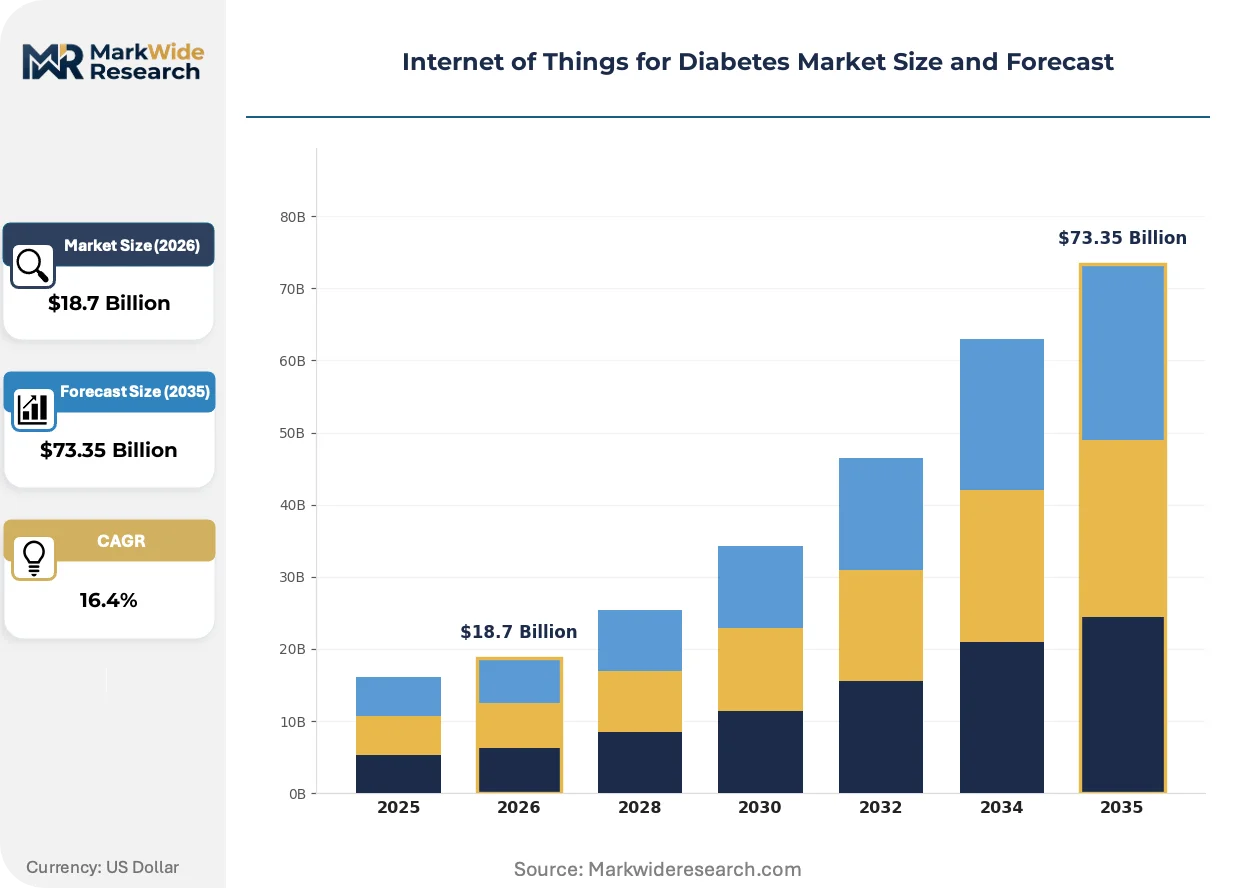
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Glucose Monitors, Insulin Pumps, Mobile Applications End User: Hospitals, Clinics, Home Care, Research Institutions Technology: Bluetooth, Cloud Computing, NFC, Machine Learning Application: Blood Sugar Monitoring, Patient Management, Data Analytics, Remote Monitoring |
| Companies Covered | Medtronic plc, Dexcom, Inc., Abbott Laboratories, Roche Diabetes Care, Insulet Corporation, Tandem Diabetes Care, Inc., Novo Nordisk, Glooko, Inc., Senseonics Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Things for Diabetes Market Shifts & Advancements
Closed-loop artificial pancreas architectures are actively decomposing the traditional separation between sensing, algorithmic decision support, and insulin delivery hardware.
Non-invasive glucose sensing technology is decomposing the market structure that has concentrated value capture in electrochemical sensor manufacturers for three decades. Academic medical centers in the United States and university hospitals in Germany are piloting multispectral and Raman spectroscopy devices for screening populations that reject fingerstick calibration routines. This technology convergence is compressing the addressable market for consumable sensor strips while expanding software and analytics revenue pools.
The EU AI Act risk classification framework is mandating conformity assessments for machine learning algorithms embedded in glucose prediction systems. Device manufacturers must now document training data provenance and algorithmic performance across demographic subgroups before CE marking. This regulatory burden falls most heavily on mid-cap vendors lacking in-house regulatory affairs infrastructure, advantaging established players with dedicated MDR transition teams.
Hospital procurement departments are unbundling after-sales service contracts from device capital purchases, compressing vendor margins on implementation and training revenue streams. This purchasing pattern change is most visible in integrated delivery networks across the United States and NHS Trusts in England, where standardization committees now mandate API accessibility for electronic health record integration as a non-negotiable evaluation criterion. Vendors responding with open-architecture platforms are capturing preference share in competitive tenders.
Internet of Things for Diabetes Market Segmentation
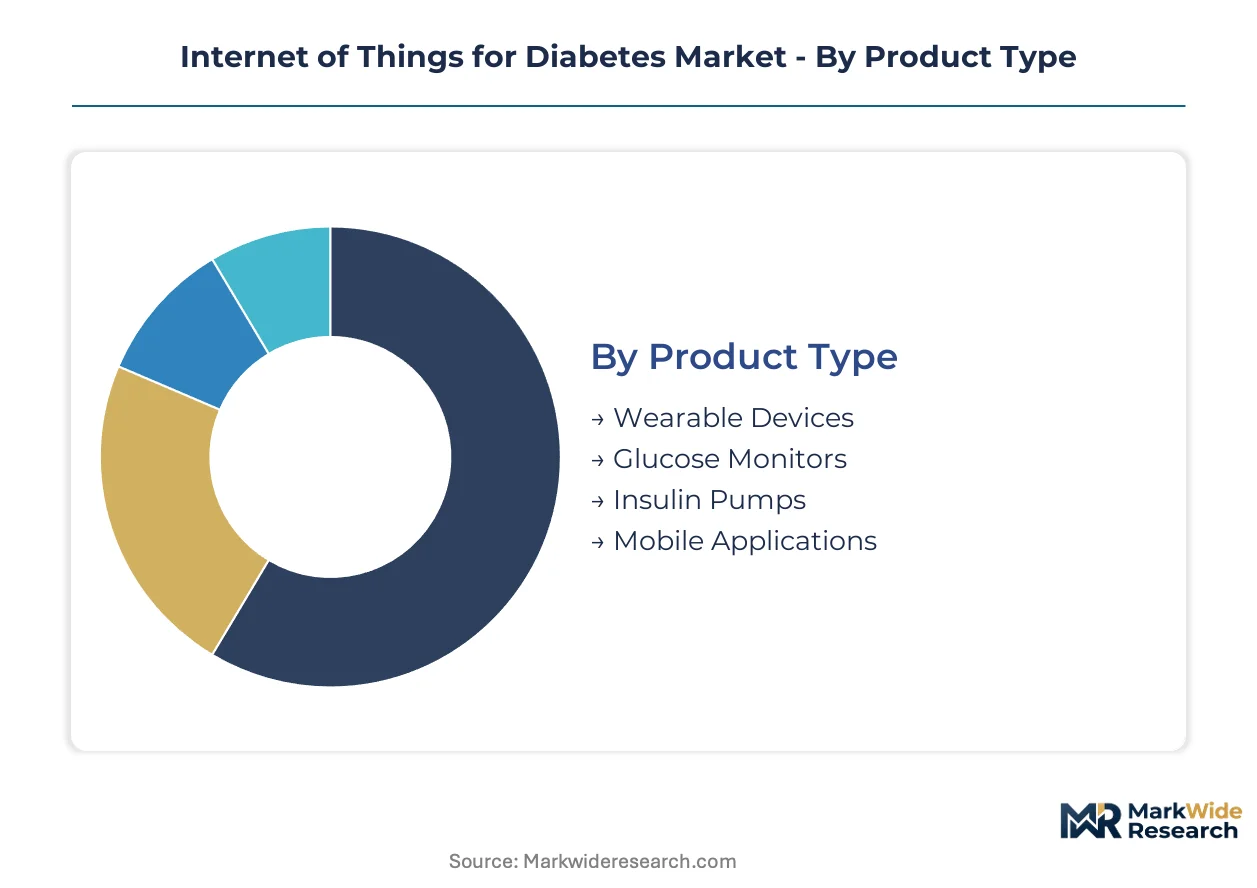
Segmentation in IoT diabetes markets reflects divergent reimbursement pathways, regulatory compliance burdens, and patient acuity levels. Product architecture choices determine whether vendors pursue hospital procurement contracts or direct-to-consumer subscription models. Technology layer decisions shape cloud infrastructure costs and cross-border data governance exposure.
Product Type:
FDA Class II device classifications and EU MDR technical documentation requirements create divergent compliance cost structures across hardware versus software-centric offerings.
- Wearable Devices:Continuous glucose monitors and smart insulin pens incorporate Bluetooth Low Energy transmitters with five-minute data refresh intervals. Demand concentrates in the United States and Germany where CMS and G-BA reimbursement codes cover Type 1 and Type 2 diabetes populations. Skin-adhesive biosensors face platinum-group metal input cost volatility from South African mining concentration.
- Glucose Monitors:Electrochemical enzymatic sensors using glucose oxidase chemistry dominate factory-calibrated systems. Japanese home care settings and Dutch remote patient monitoring programs are accelerating deployment of cloud-connected meter systems integrated with telemedicine workflows. Calibration drift in hypoxic tissue conditions remains a technical limitation during sleep or cardiovascular exercise.
- Insulin Pumps:Closed-loop systems integrate CGM data with algorithmic basal rate adjustment.
- Mobile Applications:Software platforms aggregate multi-device glycemic data for patient and clinician dashboards.
Wearable devices handle the majority of throughput; mobile applications are expanding most quickly on share.
End User:
Procurement authority and reimbursement pathway maturity determine customer acquisition economics and contract structuring.
- Home Care:Patients manage diabetes outside clinical settings using connected device ecosystems. Post-acute care models in Japan and the Netherlands favor remote monitoring infrastructure that transmits glucose telemetry directly to primary care physicians. Direct-to-consumer pharmacy channels in Brazil are compressing patient acquisition costs for subscription-based sensor replenishment.
- Hospitals:Integrated delivery networks and NHS Trusts mandate API accessibility for EHR integration as a non-negotiable tender criterion. Unbundling of after-sales service contracts from device capital purchases is compressing vendor margins on implementation and training revenue streams.
- Clinics:Outpatient endocrinology practices serve as prescription gateways for continuous monitoring systems.
- Research Institutions:Academic medical centers pilot non-invasive spectroscopic sensing technologies for populations rejecting fingerstick calibration.
Home care settings command the dominant volume position; hospitals represent the steepest expansion trajectory for closed-loop system adoption.
Technology:
Protocol standardization and algorithmic risk classification under the EU AI Act are reshaping R&D allocation and regulatory documentation burdens.
- Machine Learning:Predictive algorithms embedded in glucose forecasting systems require conformity assessments under EU AI Act risk classification frameworks. FDA and EMA demand algorithmic transparency documentation and training data provenance across demographic subgroups. Dual expertise scarcity in endocrinology and embedded systems engineering is extending regulatory clearance timelines.
- Cloud Computing:Regional data residency requirements under GDPR Article 44 force redundant infrastructure deployment across European Economic Area jurisdictions. HIPAA constraints on cross-border patient data flows similarly necessitate US-specific cloud architecture. These compliance costs advantage established vendors with dedicated regulatory affairs infrastructure.
- Bluetooth:IEEE 11073-10425 standardization reduces interoperability friction between sensors, pumps, and mobile platforms.
- NFC:Near-field communication enables tap-to-transfer glucose readings without continuous radio transmission.
Cloud computing carries the heaviest infrastructure investment load; machine learning is gaining share fastest as predictive accuracy differentiates competitive positioning.
Application:
Clinical utility and revenue model sustainability vary sharply between real-time therapeutic decision support and retrospective population health analytics.
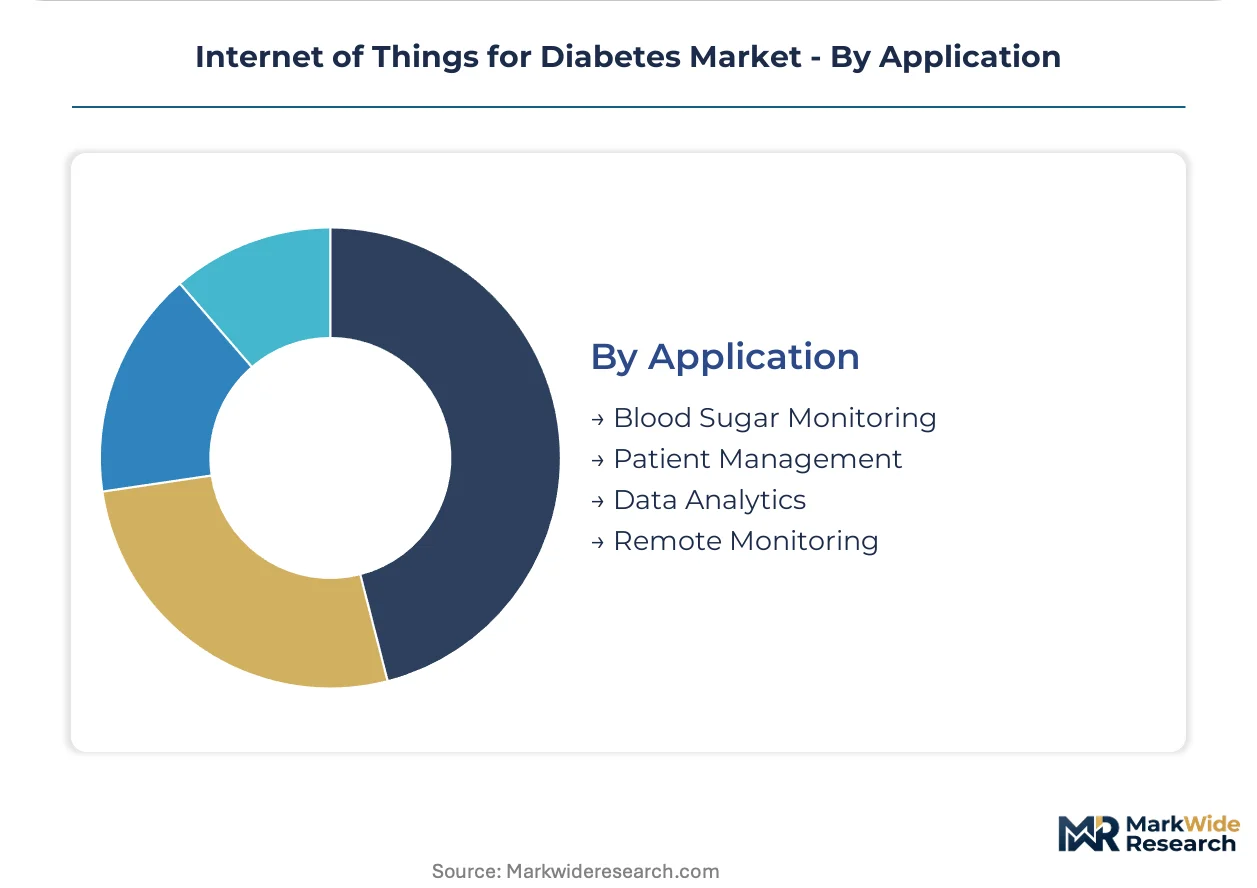
- Remote Monitoring:Continuous glucose data transmission enables proactive intervention by care teams. India's National Digital Health Mission credentialing framework creates regulatory tailwinds for cloud-connected platforms targeting its diagnosed diabetic population. GDPR cross-border transfer restrictions and HIPAA constraints shape vendor cloud architecture decisions.
- Data Analytics:Population-level glycemic pattern recognition supports payer risk stratification and pharmaceutical clinical trial recruitment. EU MDR notified body capacity constraints extend technical documentation review periods for algorithmic decision support systems.
- Blood Sugar Monitoring:Point-in-time glucose measurement remains the foundational diagnostic function.
- Patient Management:Care coordination platforms integrate medication adherence, dietary logging, and appointment scheduling.
Remote monitoring absorbs the largest deployment investment; data analytics is climbing the fastest on commercial margin contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA reimbursement determinations for continuous glucose monitoring anchor the United States as the dominant geography, while EMA cybersecurity guidance and Japan's PMDA home care integration standards reshape competitive entry requirements across their respective markets.
United States
CMS coverage expansion for Type 2 diabetes populations and integrated delivery network procurement standardization drive demand concentration. FDA premarket cybersecurity requirements for connected insulin delivery systems elevate compliance documentation burdens. The Greater Boston and San Diego biotech corridors host algorithm development clusters for predictive glucose forecasting platforms.
Germany
G-BA reimbursement pathway maturation for continuous monitoring systems and statutory health insurance contracting frameworks accelerate patient access expansion. EU MDR technical documentation standards and notified body capacity constraints extend regulatory review timelines. The Munich and Berlin metropolitan regions concentrate digital health infrastructure vendors serving hospital procurement consortia.
Japan
Post-acute care model migration toward remote patient monitoring and METI-sponsored telemedicine infrastructure investment expand addressable patient populations. PMDA quality management system requirements for software-as-medical-device platforms shape vendor market entry strategies. The Tokyo-Osaka corridor hosts the principal concentration of hospital system pilot programs for closed-loop artificial pancreas integration.
India
The National Digital Health Mission credentialing framework and 77 million diagnosed diabetic population create regulatory tailwinds for cloud-connected platform deployment. CDSCO medical device rules and data localization requirements under proposed digital health legislation force region-specific cloud architecture decisions. Bangalore and Hyderabad clusters concentrate software development capabilities for mobile health application localization.
Brazil
Direct-to-consumer pharmacy channel expansion for subscription-based sensor replenishment and ANVISA streamlined registration pathways for Class II connected devices compress patient acquisition economics. Private health plan reimbursement variability across state-level markets fragments addressable population access. São Paulo and Rio de Janeiro metropolitan areas concentrate durable medical equipment distribution infrastructure modernization efforts.
Internet of Things for Diabetes Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the connected diabetes device ecosystem. The market structure consolidates around vertically integrated sensor manufacturers, diversified medical technology conglomerates, and specialized insulin delivery system developers. Three strategic archetypes dominate: premium-platform vendors with closed-loop integration capabilities, geographic-scale players leveraging distribution density, and software-centric specialists monetizing recurring subscription revenue. Competitive dynamics center on regulatory clearance velocity and hospital electronic health record interoperability certification.
Among vertically integrated sensor manufacturers, Dexcom and Abbott anchor the premium-platform tier through manufacturing scale and geographic distribution infrastructure. Medtronic occupies a position exemplifying deep hardware-software integration archetypes across insulin pump and continuous monitoring ecosystems. These three entities represent the dominant competitive anchors against which mid-cap specialists and regional entrants benchmark compliance investment and algorithmic performance claims.
| Leading Market Players |
|---|
| Medtronic plc |
| Dexcom, Inc. |
| Abbott Laboratories |
| Roche Diabetes Care |
| Insulet Corporation |
| Tandem Diabetes Care, Inc. |
| Novo Nordisk |
| Glooko, Inc. |
| Senseonics Holdings, Inc. |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with South African platinum-group metal suppliers lock in electrochemical sensor electrode access while anchoring cost visibility for glucose oxidase biosensor manufacturers. These arrangements insulate Dexcom and Abbott from spot price volatility in palladium and rhodium markets, though they expose margins to currency fluctuation in rand-denominated settlements.
Pricing Analysis
US-Germany price spreads for continuous glucose monitoring systems exceed those for basic glucose meters by a factor reflecting reimbursement code maturity rather than manufacturing cost differentials. Three-tier pricing structure across premium closed-loop systems, standard CGM platforms, and economy fingerstick meters segments buyer archetypes by clinical acuity and insurance coverage depth. Pricing pressure stems from Brazilian direct-to-consumer pharmacy channels compressing patient acquisition economics for subscription-based sensor replenishment. Home care patients in India's National Digital Health Mission credentialing framework exhibit highest price sensitivity, while integrated delivery networks in the United States demonstrate lowest sensitivity due to bundled procurement authority.
Supply Chain Analysis
Platinum-group metal mining concentration in South Africa and Russia creates single-source vulnerability for electrochemical sensor electrode fabrication. Sensor manufacturing draws from specialized polymer substrates sourced from German chemical suppliers and biocompatible adhesives anchored in Japanese precision coating operations. Supply chain risk centers on export restriction exposure from Russian mining operations under sanctions regimes. Distribution runs through durable medical equipment distributors in mature markets and direct-to-consumer pharmacy channels in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-invasive spectroscopic glucose sensing represents a credible substitution threat that could decompose three decades of value capture concentrated in enzymatic sensor manufacturers. Incumbents must navigate this technology convergence while defending installed base economics.
For Market Incumbents: Compound regulatory clearance velocity through dedicated MDR transition teams and algorithmic transparency documentation infrastructure that addresses EU AI Act conformity assessment requirements. Deepen backward integration into platinum-group metal electrode manufacturing to defend margin position against South African mining concentration. Prioritize hospital EHR interoperability certification as a non-negotiable tender criterion in integrated delivery network procurement.
For New Entrants and Emerging Players: FDA breakthrough device designation fast-track offers regulatory pathway acceleration for wrist-worn continuous glucose monitors integrating non-invasive spectroscopic sensing with machine learning-based motion artifact rejection. Target India's National Digital Health Mission credentialing framework as the most penetrable geography, leveraging Bangalore and Hyderabad software development clusters for mobile health application localization. Pursue direct-to-consumer pharmacy channel partnerships in Brazil to compress patient acquisition costs below traditional durable medical equipment distributor economics.
For Investors and Strategic Acquirers: Algorithm development boutiques with dual expertise in endocrinology and embedded systems engineering represent the most defensible acquisition target archetype given clinical data science talent scarcity. Long-term viability frames around regulatory clearance velocity and hospital system interoperability certification rather than hardware manufacturing scale. Watch FDA premarket cybersecurity requirement enforcement consistency as the primary inflection indicator for compliance cost escalation and barrier-to-entry elevation.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified body capacity constraints extend review timelines for Class IIb connected insulin delivery systems. |
| Hospital EHR Interoperability Certification | NHS Trusts and US integrated delivery networks mandate API accessibility as non-negotiable tender evaluation criterion. |
| Non-Invasive Sensing R&D Partnership | Academic medical centers in Germany and the United States pilot multispectral and Raman spectroscopy for calibration-averse populations. |
| Regional Cloud Infrastructure Deployment | GDPR Article 44 and HIPAA constraints force redundant architecture across European Economic Area and US jurisdictions. |
| Direct-to-Consumer Channel Expansion | Brazilian pharmacy channels bypass durable medical equipment distributors to compress sensor replenishment acquisition costs. |
Research Methodology
A standing panel of biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists provided ongoing calibration throughout the research process. Primary interview data combined with secondary validation from FDA 510(k) filings, EMA CE marking databases, CMS Medicare coverage determinations, and hospital procurement contract repositories. Bottom-up device shipment modeling and top-down reimbursement pathway analysis were triangulated to produce volume and value estimates.
Consistency checks validated outputs against external benchmarks including G-BA reimbursement decisions, PMDA quality management system registrations, and CDSCO medical device rule filings. Segmentation dimensions modeled across the projection horizon encompass product architecture, end-user setting, technology layer, and application function. CAGRs were derived from patient population expansion trajectories, reimbursement code maturation curves, and technology substitution elasticity parameters specific to closed-loop system adoption.
Underlying assumptions cover CMS coverage expansion continuity, EU MDR notified body capacity recovery, and platinum-group metal supply stability, with deviation risk concentrated in sanctions regime escalation affecting Russian mining operations and GDPR cross-border enforcement variability. Practitioners should keep alternative scenarios live as non-invasive spectroscopic sensing clinical validation and FDA cybersecurity guidance evolution reshape competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Europe Insulin Infusion Pumps Market
Diabetes Care
Next Generation Diabetes Therapy and Drug Delivery Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Wearable Glucometers Market
Diabetes Care
Middle East and Africa Diabetes Market
Diabetes Care
Diabetes Monitors Market
Diabetes Care
Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
Asia-Pacific Oral Anti-Diabetic Drug Market
Diabetes Care
Global Blood Glucose Test Strip Market
Diabetes Care
Latin America Insulin Infusion Pump Market
Diabetes Care
Diabetic Pen Cap Market
Diabetes Care
Global Type 2 Diabetes Treatment Market
Diabetes Care
Philippines Diabetes Care Devices Market
Diabetes Care
Middle East and Africa Diabetes Care Devices Market
Diabetes Care
Global Needle Free Diabetes Care Market