
 Urea Cycle Disorders Treatment Market | 2026-2036
Urea Cycle Disorders Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Urea Cycle Disorders Treatment Market Outlook
Subscription-based patient monitoring and remote care coordination is rebalancing how urea cycle disorder therapies get delivered beyond the hospital. Ultragenyx Pharmaceutical leverages its rare disease infrastructure to sustain long-term patient relationships across metabolic centers. Recordati Rare Diseases anchors European distribution through specialized pharmacy networks. Bausch Health Companies Inc. competes on established hospital formulary access for acute management protocols.
Urea cycle disorders treatment encompasses pharmacological and nutritional interventions that substitute deficient enzymes, remove nitrogenous waste, or restore ammonia detoxification pathways in patients with inherited defects of the six enzymatic steps or two transport proteins of the urea cycle; sodium phenylbutyrate and glycerol phenylbutyrate remain cornerstone ammonia scavengers with defined dosing parameters tied to residual enzyme activity. Enzyme replacement via intravenous delivery dominates current clinical practice for acute hyperammonemic crises, while gene therapy approaches attract development investment as potentially curative modalities. Dietary management maintains stable baseline ammonia control in compliant patients, though margin pools increasingly shift toward hospital-based acute intervention products.
FDA orphan drug exclusivity and EMA priority medicines designation shape competitive timelines and pricing autonomy for developers in this space. The EU F-Gas Regulation and US EPA manufacturing standards constrain production chemistry choices for inhaled or aerosolized delivery formats under investigation. Stakeholders must weigh gene therapy pipeline maturity against established chronic therapy cash flows when allocating R&D capital.
Market Dynamics
Gene therapy pipeline maturation is compressing investment timelines for chronic ammonia scavenger portfolios, forcing developers to recalibrate between durable cash flows from established enzyme replacement and one-time curative modalities.
Growth Catalysts
- FDA Orphan Drug Exclusivity:Accelerated clinical trial pathways and extended market protection windows incentivize rare disease R&D commitments.
- Pediatric Metabolic Centers:Specialized treatment capacity expansion in tertiary care networks drives protocol standardization and patient funnel concentration.
- EMA Priority Medicines Designation:Fast-track regulatory review timelines compress development-to-commercialization intervals for novel nitrogen scavengers.
Market Restraints
- Plasma-Derived Enzyme Supply Concentration:Dependence on fractionation facility networks in the United States and Germany creates single-source vulnerability for intravenous replacement therapies.
- EU F-Gas Manufacturing Constraints:Aerosolized delivery format development faces chemistry restrictions under fluorinated gas phase-out mandates.
- Dietary Protein Restriction Compliance:Patient adherence failure rates in home-based nutritional management limit prophylactic therapy effectiveness and trigger acute intervention demand spikes.
Strategic Opportunities
- Japan's Rare Disease Reimbursement Framework:Premium pricing authorization for ultra-orphan indications creates attractive market entry economics for gene therapy developers.
- Subscription-Based Remote Monitoring:Continuous ammonia telemetry and telemedicine coordination models capture value beyond acute hospital episodes.
- CRISPR-Cas9 Liver-Directed Delivery:In vivo gene editing convergence with lipid nanoparticle targeting platforms promises durable enzyme restoration without bone marrow conditioning.
Industry Challenges
- Metabolic Geneticist Workforce Scarcity:Fellowship program output fails to match patient diagnostic volume expansion, creating treatment bottleneck at referral centers.
- Multi-Site Gene Therapy Manufacturing:Viral vector production scale-up requires dedicated cleanroom capex commitments that strain mid-cap developer balance sheets.
- Cross-Border Prescription Coordination:Patient mobility between United States, Germany, and Japan fragments care continuity and complicates adverse event reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urea Cycle Disorders Treatment Market |
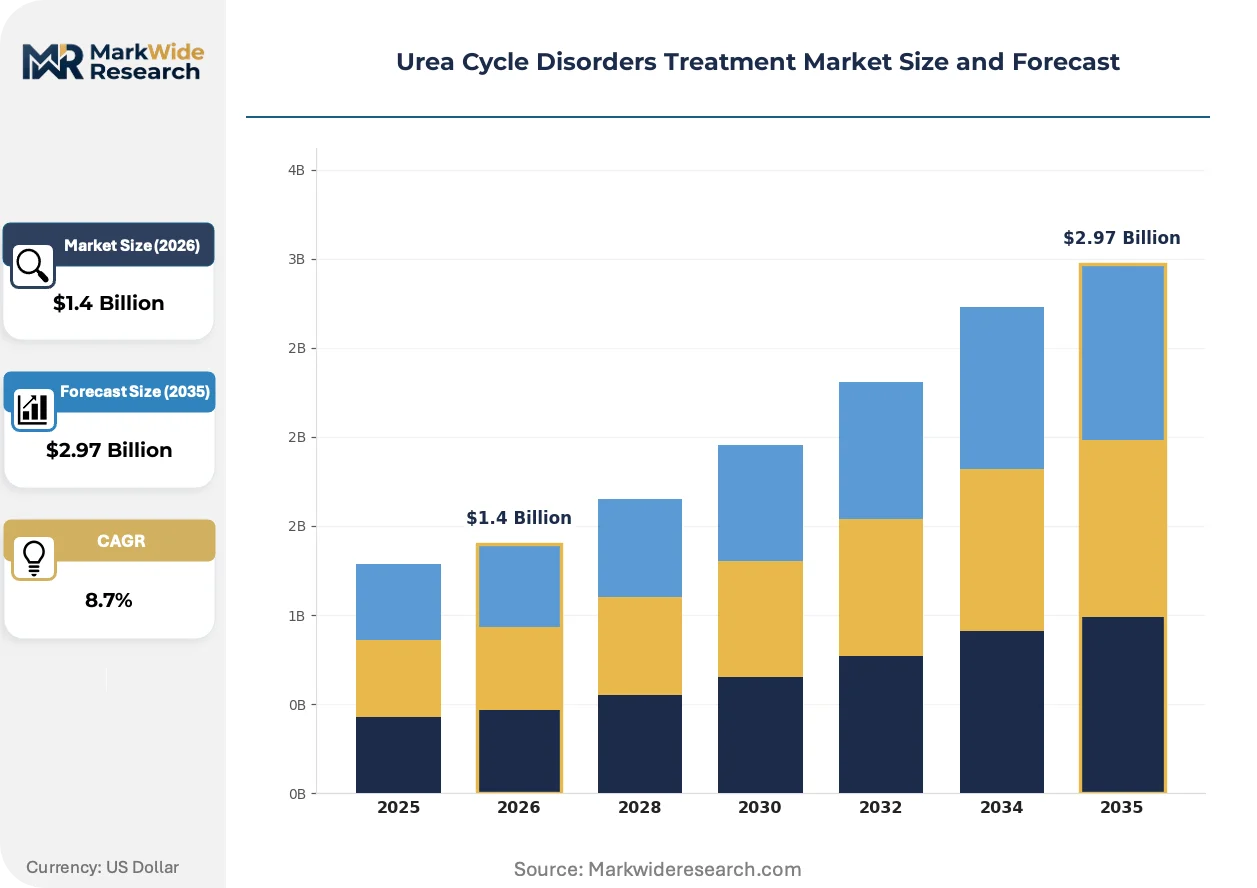
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arginine, Citrulline, Sodium Benzoate, Other Treatments End User: Pediatric Clinics, Adult Hospitals, Homecare Settings, Specialized Clinics Delivery Mode: Intravenous, Oral, Subcutaneous, Other Routes Treatment Approach: Enzyme Replacement, Dietary Management, Gene Therapy, Supportive Care |
| Companies Covered | Bausch Health Companies Inc., Ultragenyx Pharmaceutical Inc., Recordati Rare Diseases, Eurocept Pharmaceuticals Holding, Acer Therapeutics, Zevra Therapeutics, Inc., Aeglea BioTherapeutics, Arcturus Therapeutics, Inc., Orpharma Pty Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urea Cycle Disorders Treatment Market Strategic Shifts
Biological manufacturing advances and regulatory science evolution are restructuring competitive advantage around curative intent rather than chronic disease management economics.
Adeno-associated virus vector engineering is rewriting liver-directed gene therapy feasibility. Pediatric metabolic centers in Boston, Munich, and Tokyo are establishing dedicated infusion protocols for investigational programs. The technology is compressing the addressable market for lifelong phenylbutyrate regimens by targeting underlying enzyme deficiency correction.
REACH authorization requirements for novel chemical entities are tightening impurity specification thresholds for ammonia scavenger APIs. European manufacturers face reformulation costs to meet Substances of Very High Concern screening criteria. Sodium phenylbutyrate generic suppliers in Germany and the Netherlands are accelerating analytical method upgrades to maintain market access.
Hospital-at-home service unbundling is fragmenting traditional inpatient revenue capture. Acute hyperammonemia management protocols now deploy portable dialysis and scavenger infusion capabilities in residential settings. This shift concentrates fastest in United States Medicare Advantage networks and Japanese long-term care insurance frameworks.
Urea Cycle Disorders Treatment Market Segmentation
Treatment modality selection in urea cycle disorders hinges on residual enzyme activity, crisis frequency, and patient age at diagnosis. Segmentation reveals where acute intervention products command premium pricing against chronic maintenance therapies, and which delivery formats align with site-of-care migration trends.
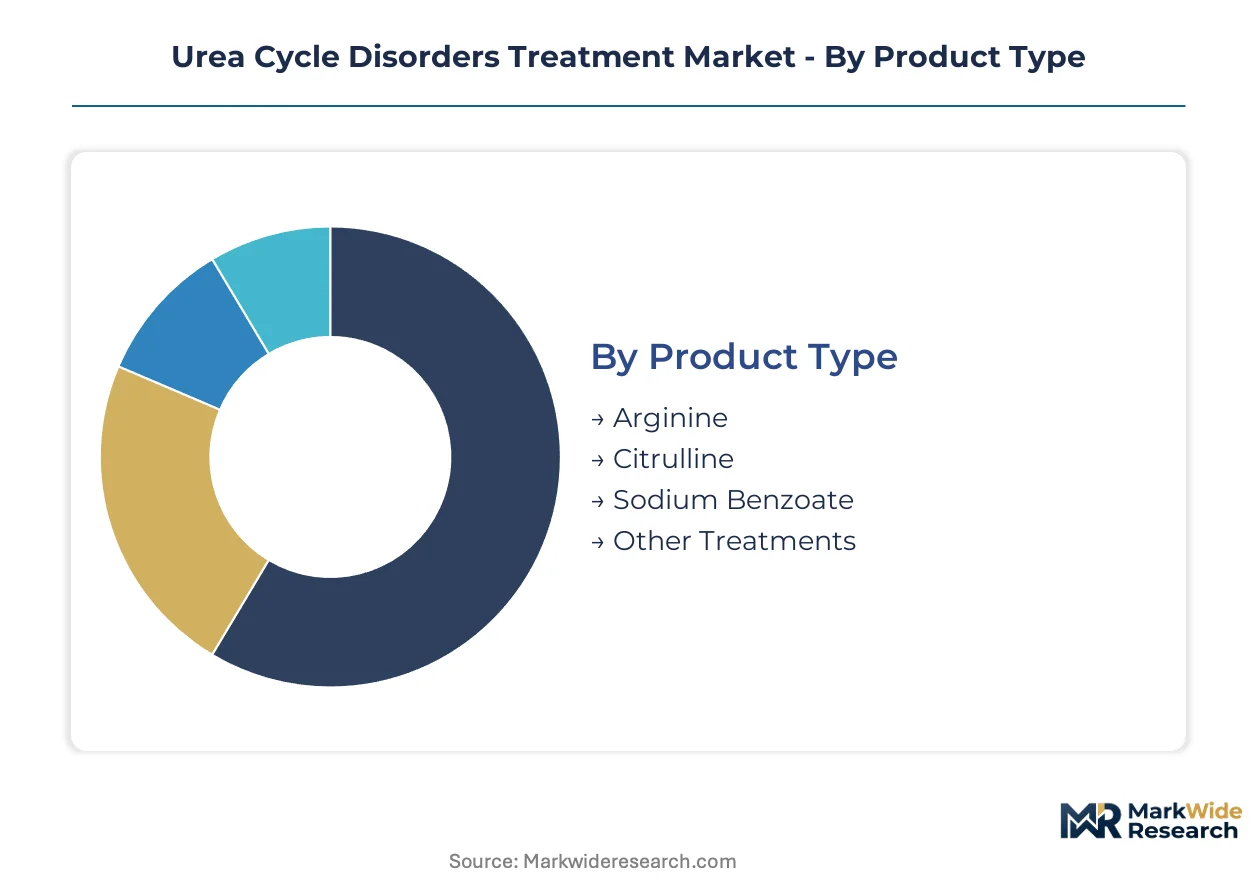
Product Type:
Cost tier separates acute rescue therapies from chronic maintenance supplements, with reimbursement intensity tracking hospital admission rates.
- Arginine:Essential amino acid supplementation restores ornithine availability for residual urea cycle flux in argininosuccinic aciduria and citrullinemia. Pediatric metabolic centers in Boston and Munich standardize arginine dosing in neonatal crisis protocols, though supply concentration among plasma fractionators creates allocation vulnerability during manufacturing disruptions.
- Citrulline:Preferred substrate for distal cycle defects bypasses proximal enzymatic blocks more efficiently than arginine in certain genotypes. Japanese long-term care insurance frameworks now cover home citrulline dispensing for stable patients, reducing tertiary center admission frequency.
- Sodium Benzoate:Conjugates with glycine to form hippurate for renal nitrogen excretion, serving as second-line scavenger when phenylbutyrate intolerance occurs.
- Other Treatments:N-carbamylglutamate for N-acetylglutamate synthase deficiency and experimental nitrogen scavengers in Phase II programs.
Volume sits with arginine; growth tilts toward citrulline.
End User:
Application context determines reimbursement pathway complexity and therapy intensity, with site-of-care shifts redistributing margin capture.
- Pediatric Clinics:Tertiary metabolic centers concentrate newborn screening follow-up and genotype-directed protocol initiation. German university hospitals in Heidelberg and Hamburg maintain dedicated urea cycle disorder day units for enzyme infusion and dietary counseling.
- Adult Hospitals:Internal medicine and hepatology services manage late-onset presentations and pregnancy-related decompensations.
- Homecare Settings:Medicare Advantage networks in the United States deploy portable ammonia monitors and nurse-administered scavenger infusions for stable patients.
- Specialized Clinics:Dedicated rare disease hubs coordinate gene therapy screening and longitudinal neurocognitive monitoring.
Patient concentration clusters at pediatric clinics; service unbundling favors homecare expansion.
Delivery Mode:
Supply concentration among sterile injectable manufacturers shapes availability for crisis management versus chronic self-administration.
- Intravenous:Rapid ammonia reduction during hyperammonemic encephalopathy requires hospital-based infusion with continuous neuro monitoring. FDA batch release testing for plasma-derived enzyme products extends lead times for US treatment centers.
- Oral:Sodium phenylbutyrate and glycerol phenylbutyrate tablets or powder enable outpatient nitrogen control, though palatability challenges reduce adolescent adherence.
- Subcutaneous:Investigational depot formulations and enzyme replacement alternatives aim to bridge hospital and home therapy gaps.
- Other Routes:Rectal and nasogastric administration for patients with altered consciousness or gastrointestinal dysfunction.
Revenue concentrates in intravenous formats; formulation innovation targets oral and subcutaneous expansion.
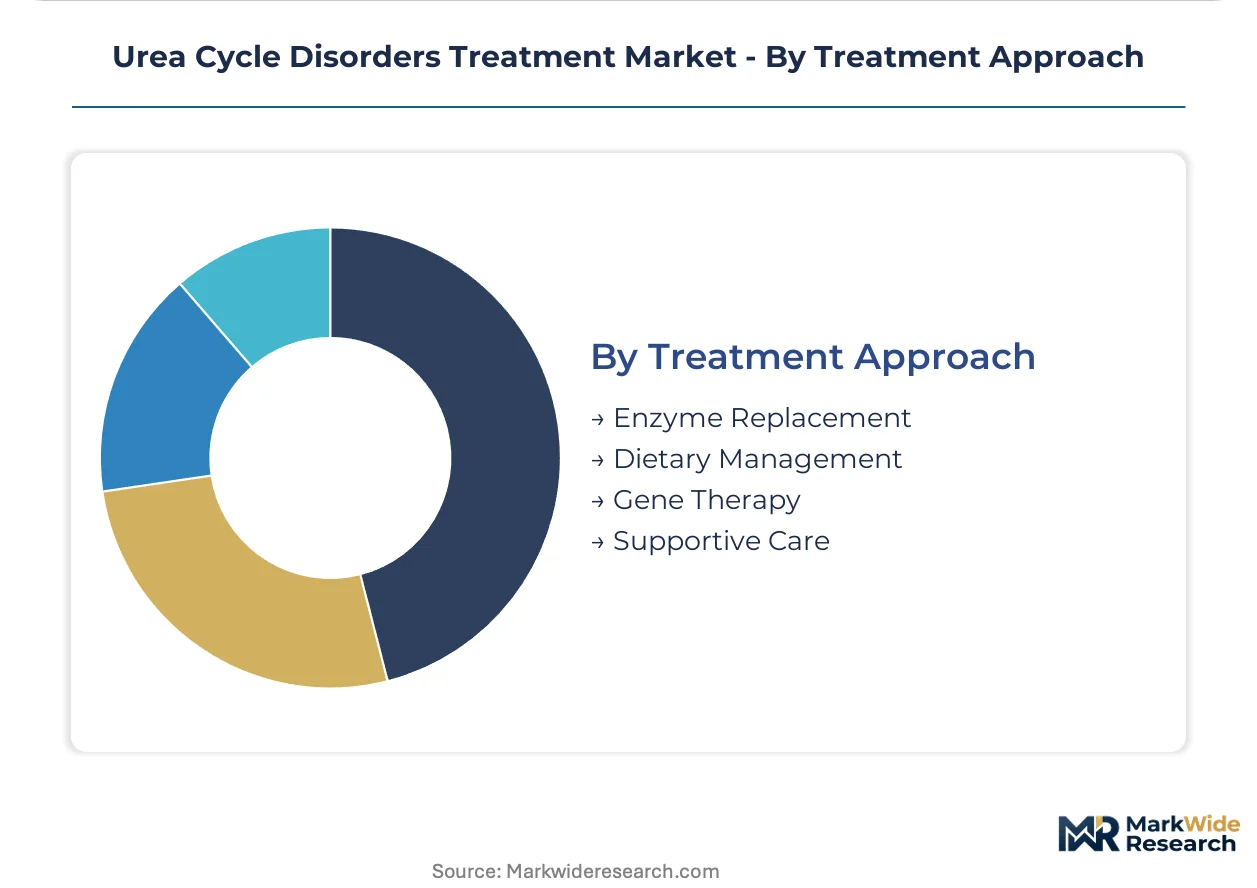
Treatment Approach:
Maturity gradient separates decades-established protocols from developmental-stage modalities, with capital allocation shifting toward curative intent.
- Enzyme Replacement:Intravenous recombinant human arginase and similar biologics substitute for defective hepatic enzymes. Viral vector manufacturing scale-up constraints limit multi-site trial activation for liver-directed programs.
- Dietary Management:Protein restriction with essential amino acid supplementation maintains baseline ammonia control in compliant patients, though adherence failure triggers acute intervention demand spikes.
- Gene Therapy:Adeno-associated virus vectors targeting hepatocytes promise durable enzyme restoration without bone marrow conditioning. EMA priority medicines designation accelerates European clinical development timelines.
- Supportive Care:Dialysis, neuroprotective measures, and transplant evaluation for refractory cases.
Established volume rests with dietary management and enzyme replacement; gene therapy claims steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of plasma-derived enzymes and recombinant biologics concentrates in the United States and Germany, while patient demand clusters in tertiary metabolic centers across Japan and Western Europe. Consumption geography is decoupling from production geography as gene therapy developers establish multi-site clinical networks.
United States
FDA orphan drug exclusivity accelerates development timelines for novel nitrogen scavengers. The EPA maintains stringent manufacturing standards for aerosolized delivery formats under investigation. Boston's pediatric metabolic centers anchor clinical trial activation for liver-directed gene therapy programs.
Germany
EMA priority medicines designation fast-tracks regulatory review for ultra-orphan indications. The EU F-Gas Regulation constrains chemistry choices for inhaled formulations. Heidelberg and Hamburg university hospitals maintain dedicated urea cycle disorder day units for enzyme infusion protocols.
Japan
PMDA's rare disease reimbursement framework authorizes premium pricing for ultra-orphan therapies. METI coordinates domestic biologics manufacturing scale-up initiatives. Tokyo's metabolic centers establish dedicated infusion protocols for investigational gene therapy candidates.
United Kingdom
NHS England's specialized commissioning framework concentrates treatment capacity in designated rare disease hubs. MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for innovative medicines. London's Great Ormond Street Hospital anchors pediatric metabolic specialist training programs.
Switzerland
Swissmedic's streamlined orphan drug procedures attract European headquarters for rare disease developers. The country's precision medicine initiatives fund longitudinal neurocognitive monitoring infrastructure. Basel's pharmaceutical cluster hosts viral vector manufacturing partnerships for gene therapy supply.
Urea Cycle Disorders Treatment Market Competitive Environment
Top-tier vendors anchor hospital formulary access for acute management protocols, while mid-cap specialists compete on rare disease infrastructure and long-term patient relationships. The vendor base stratifies across three tiers: integrated pharmaceutical conglomerates with established metabolic portfolios, rare disease pure-plays with specialized distribution networks, and gene therapy developers with curative-intent pipelines. Dominant competitive moves include strategic partnerships with pediatric metabolic centers and portfolio diversification into subscription-based remote monitoring services.
Among North American rare disease specialists, Ultragenyx Pharmaceutical Inc. and Bausch Health Companies Inc. occupy positions reflecting contrasting strategic archetypes—one exemplifying infrastructure-led patient relationship models, the other representing established hospital access pathways. Recordati Rare Diseases anchors European distribution capabilities through specialized pharmacy networks. These three entities collectively represent the competitive spectrum from acute intervention products to chronic therapy cash flow management.
| Leading Market Players |
|---|
| Bausch Health Companies Inc. |
| Ultragenyx Pharmaceutical Inc. |
| Recordati Rare Diseases |
| Eurocept Pharmaceuticals Holding |
| Acer Therapeutics |
| Zevra Therapeutics, Inc. |
| Aeglea BioTherapeutics |
| Arcturus Therapeutics, Inc. |
| Orpharma Pty Ltd. |
| Others |
Value Chain & Pricing Dynamics
Metabolic geneticist workforce scarcity in tertiary care networks widens pricing-tier spreads between acute hospital-based interventions and chronic home management protocols, as labor-cost differentials concentrate premium capture in crisis-response products.
Pricing Analysis
Margin tightening in chronic ammonia scavenger tiers reflects gene therapy pipeline maturation compressing long-term pricing power. Three-tier pricing structure across premium intravenous enzyme replacement, standard oral phenylbutyrate regimens, and economy generic sodium benzoate alternatives stratifies by residual enzyme activity and crisis frequency. Cost-down pressure on oral maintenance therapies accelerates as subscription-based remote monitoring models shift value capture toward acute episodes. Pediatric metabolic centers show least price sensitivity for rescue protocols; homecare payers demonstrate highest sensitivity to chronic therapy costs.
Supply Chain Analysis
Dual-sourcing requirements for plasma-derived enzymes mandate multi-supplier qualification across United States and German fractionation networks. Raw material dependencies center on human plasma collections, recombinant cell line substrates, and viral vector production media. Single-source vulnerability in sterile injectable manufacturing concentrates supply risk. Distribution runs through specialized pharmacy networks for chronic therapies and direct hospital contracting for acute rescue products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Viral vector manufacturing capacity scarcity props pricing for gene therapy developers, constraining multi-site trial activation and concentrating premium capture among balance-sheet-strong incumbents.
For Market Incumbents: Lock in long-term plasma supply agreements and dedicated cleanroom partnerships to defend against gene therapy substitution. Prioritize backward integration into viral vector production to capture margin from curative-intent pipeline maturation. Secure pediatric metabolic center exclusivity through integrated remote monitoring infrastructure. For New Entrants and Emerging Players: Launch via hospital-at-home service unbundling in United States Medicare Advantage networks where acute episode capture remains fragmented. Target dietary management adherence failure as the most penetrable white space, deploying nurse-administered subcutaneous depot formulations. Position against established oral phenylbutyrate through palatability-formulation differentiation. For Investors and Strategic Acquirers: Re-rating potential sits with rare disease pure-plays possessing specialized distribution infrastructure given EMA priority medicines designation acceleration. Long-term viability favors developers with dual chronic-curative portfolios spanning enzyme replacement cash flows and gene therapy optionality. Watch CRISPR-Cas9 liver-directed delivery data readouts as the signal for portfolio rebalancing toward editing platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | Dedicated cleanroom commitments in Basel and Boston anchor viral vector supply security for liver-directed programs. |
| Subscription-Based Remote Monitoring | Continuous ammonia telemetry partnerships with pediatric metabolic centers capture value beyond hospital episodes. |
| EMA Priority Medicines Pathway | Fast-track designation compresses European development timelines for novel nitrogen scavengers and gene therapies. |
| Plasma-Derived Enzyme Supply Agreements | Long-term fractionation contracts with United States and German networks reduce single-source vulnerability. |
| Hospital-at-Home Service Expansion | Portable dialysis and scavenger infusion capabilities in residential settings fragment traditional inpatient revenue. |
Study Parameters
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, supplemented by formulary database reviews and hospital procurement records. Primary interviews with metabolic geneticists, pediatric endocrinologists, rare disease formulary directors, and gene therapy manufacturing executives validated demand assumptions and pricing dynamics. Bottom-up patient population estimates and top-down revenue triangulation anchored segmentation outputs.
Historical trendline analysis across treatment modality adoption curves informed projection frameworks over the analysis window. Segmentation dimensions modeled include product type, end user, delivery mode, and treatment approach. CAGRs derived from enzyme replacement volume trajectories, gene therapy pipeline maturity timelines, and dietary management adherence patterns.
Regulatory approval delays, viral vector manufacturing scale-up failures, and gene therapy clinical setbacks are the dominant revision risks to forecast assumptions. A model refresh is warranted upon material change in liver-directed delivery platform efficacy data.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Intensity Modulated Radiation Therapy Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Purpura Treatment Market
Medical Treatment
Meningococcal Meningitis Treatment Market
Medical Treatment
Radiation Therapy Market
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
Spain Hair Transplant Market
Medical Treatment
Isovaleric Acidemia Treatment Market
Medical Treatment
Merkel Cell Carcinoma (MCC) Treatment Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Influenza Treatment Market
Medical Treatment
Pelvic Organ Prolapse Repair Market
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market