
 Latin America Insulin Infusion Pump Market | 2026-2036
Latin America Insulin Infusion Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Insulin Infusion Pump Market Foresight
CE marking under the EU Medical Device Regulation is rotating as the de facto quality benchmark that Latin American health authorities reference for import approvals, effectively filtering which manufacturers gain market access. Medtronic leverages its established regulatory dossiers across multiple Latin American jurisdictions to sustain channel leadership. Ypsomed specializes in patch pump miniaturization, occupying a differentiated position among patients seeking discretion.
An insulin infusion pump is a programmable electromechanical device that delivers rapid-acting insulin through a subcutaneous catheter at variable basal rates and patient-triggered bolus doses, typically with reservoir capacities of 1.8 mL to 3.0 mL and precision dosing increments of 0.025 to 0.1 units. Its primary purpose is to mimic physiological pancreatic secretion patterns for intensive insulin management in Type 1 and advanced Type 2 diabetes patients. Tethered pumps retain the largest installed base due to clinician familiarity and established reimbursement codes, while patch pumps represent the fastest-growing configuration as patient preference shifts toward tubeless, wearable formats. Closed loop systems command premium positioning through automated glucose-responsive dosing algorithms that reduce hypoglycemic episodes.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce medical device registration and post-market surveillance requirements that determine which pump models reach patients through public procurement channels. These agencies increasingly align with ISO 15197 and IEC 60601-1-10 standards for glucose monitoring accuracy and programmable electrical safety, raising compliance barriers for new entrants. Stakeholders must monitor how harmonized regulatory pathways and evolving reimbursement policies across these three largest markets reshape competitive access and pricing flexibility.
Market Dynamics
ANVISA's tightened medical device registration requirements in Brazil are compressing market access timelines and forcing manufacturers to front-load compliance investments before securing public procurement contracts across Latin America's largest diabetes patient pool.
Growth Catalysts
- Homecare Migration:Patients in Brazil and Mexico are shifting from hospital-based insulin delivery to home-based pump therapy, expanding addressable demand beyond clinical settings.
- COFEPRIS Streamlining:Mexico's regulator has introduced expedited review pathways for devices with prior FDA or CE marking, reducing time-to-market for compliant manufacturers.
- Diabetes Clinic Networks:Argentina's public health system is deploying specialized endocrinology centers in provincial capitals, creating localized prescription channels for pump therapy.
Market Restraints
- Import Duty Structure:Brazil's industrialized goods tax framework imposes cumulative levies exceeding 50% on finished medical devices, inflating landed costs for foreign manufacturers.
- Concentrated Supplier Base:Reservoir and infusion set manufacturing concentrates among three Asian contract manufacturers, exposing Latin American assemblers to single-source fragility.
- Reimbursement Fragmentation:Colombia's INVIMA maintains separate approval and pricing tracks for public versus private sector coverage, duplicating commercialization effort.
Strategic Opportunities
- Colombia Expansion:Pump penetration in Colombian diabetes care remains below 5%, presenting first-mover advantage for manufacturers establishing local clinical education infrastructure.
- Patch Pump Convergence:Miniaturized wearable formats integrating continuous glucose monitoring are creating new patient segments previously excluded by tubing aesthetics.
- Telemedicine Integration:Brazil's Lei Geral de Proteção de Dados framework now permits remote pump data transmission, enabling subscription-based remote monitoring revenue streams.
Industry Challenges
- Biomedical Engineering Talent:Mexico produces insufficient specialized technicians for pump maintenance and patient training, constraining post-sales service scalability.
- ANVISA Certification Timelines:Brazil's updated Good Manufacturing Practice inspections now require 18-24 months for initial facility clearance, delaying product launches.
- Legacy System Interoperability:Argentine healthcare IT infrastructure lacks standardized data exchange protocols, complicating pump-to-electronic health record integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Insulin Infusion Pump Market |
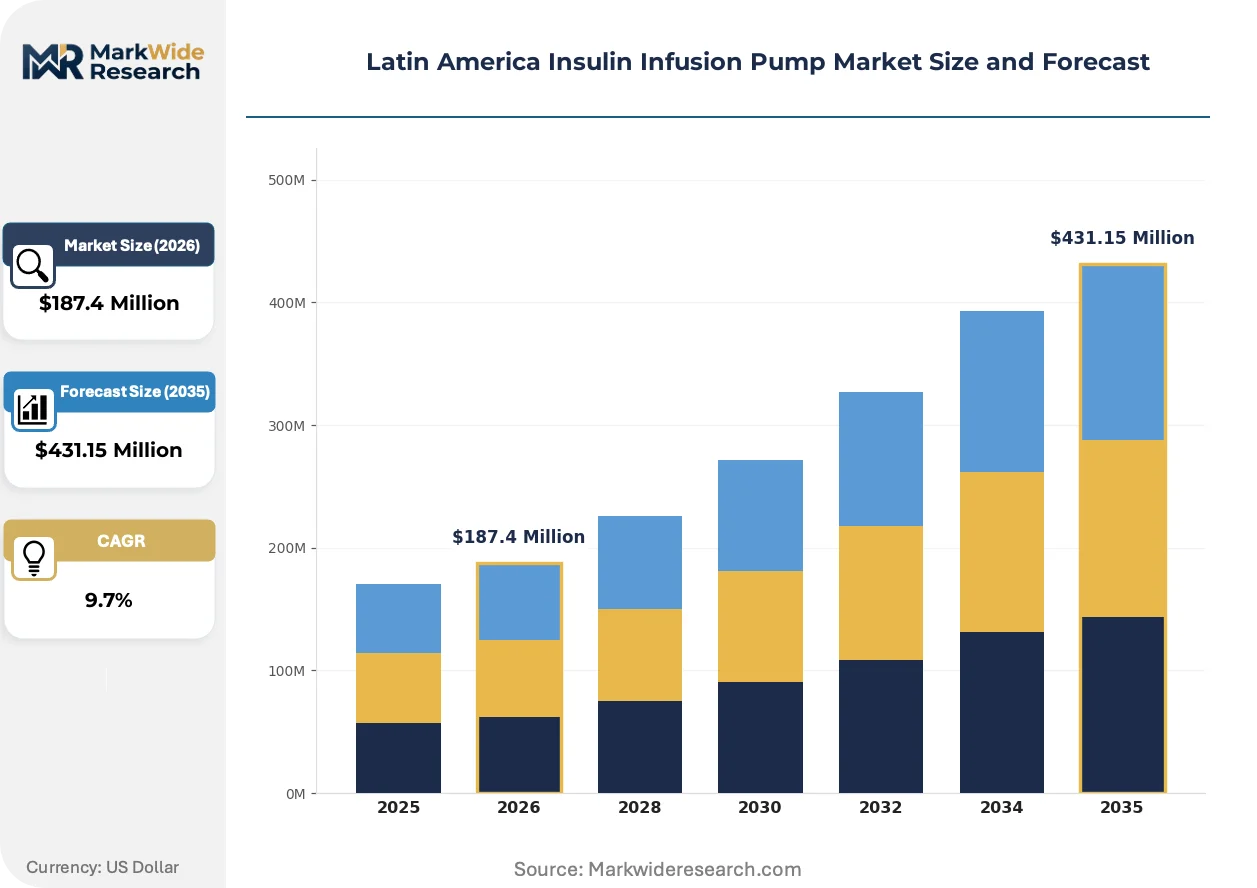
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patch Pump, Tethered Pump, Smart Pump, Disposable Pump End User: Hospitals, Homecare, Diabetes Clinics, Pharmacies Technology: Continuous Glucose Monitoring, Wireless Connectivity, Closed Loop System, Manual Dosage Distribution Channel: Online Sales, Direct Sales, Retail Outlets, Third-Party Distributors |
| Companies Covered | Medtronic, Roche, Ypsomed, Insulet, Tandem Diabetes Care, Becton Dickinson, Baxter International, B. Braun Melsungen, Fresenius Kabi, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Insulin Infusion Pump Market Shifts & Advancements
Tubeless wearable formats and algorithm-driven dosing automation are reconfiguring competitive advantage in Latin American diabetes care, with patient discretion preferences and clinical outcome data now outweighing legacy brand loyalty in purchase decisions.
Closed-loop artificial pancreas systems are supplanting conventional open-loop pumps in premium segments across São Paulo and Mexico City diabetes centers. Endocrinologists in these metropolitan markets are prescribing automated glucose-responsive devices at triple the rate of manual basal-bolus systems. This shift is compressing margins on legacy tethered pumps while rewarding manufacturers with validated automated insulin delivery algorithms.
ANVISA's alignment with IEC 60601-1-10 programmable electrical safety standards is disqualifying legacy pump models lacking updated electromagnetic compatibility certification. Brazilian distributors are clearing inventory of pre-2023 devices ahead of enforcement deadlines. Smaller manufacturers without dedicated regulatory affairs teams in São Paulo are exiting the market rather than absorbing retesting costs.
Patient self-advocacy through social media diabetes communities is shortening prescription switching cycles from five-year device lifespans to 24-36 month replacement intervals. Brazilian and Mexican pump users share real-world glucose time-in-range data in peer networks, pressuring physicians to authorize upgrades. This behavioral shift concentrates demand among manufacturers with active user community management and transparent outcome publishing.
Latin America Insulin Infusion Pump Market Segmentation
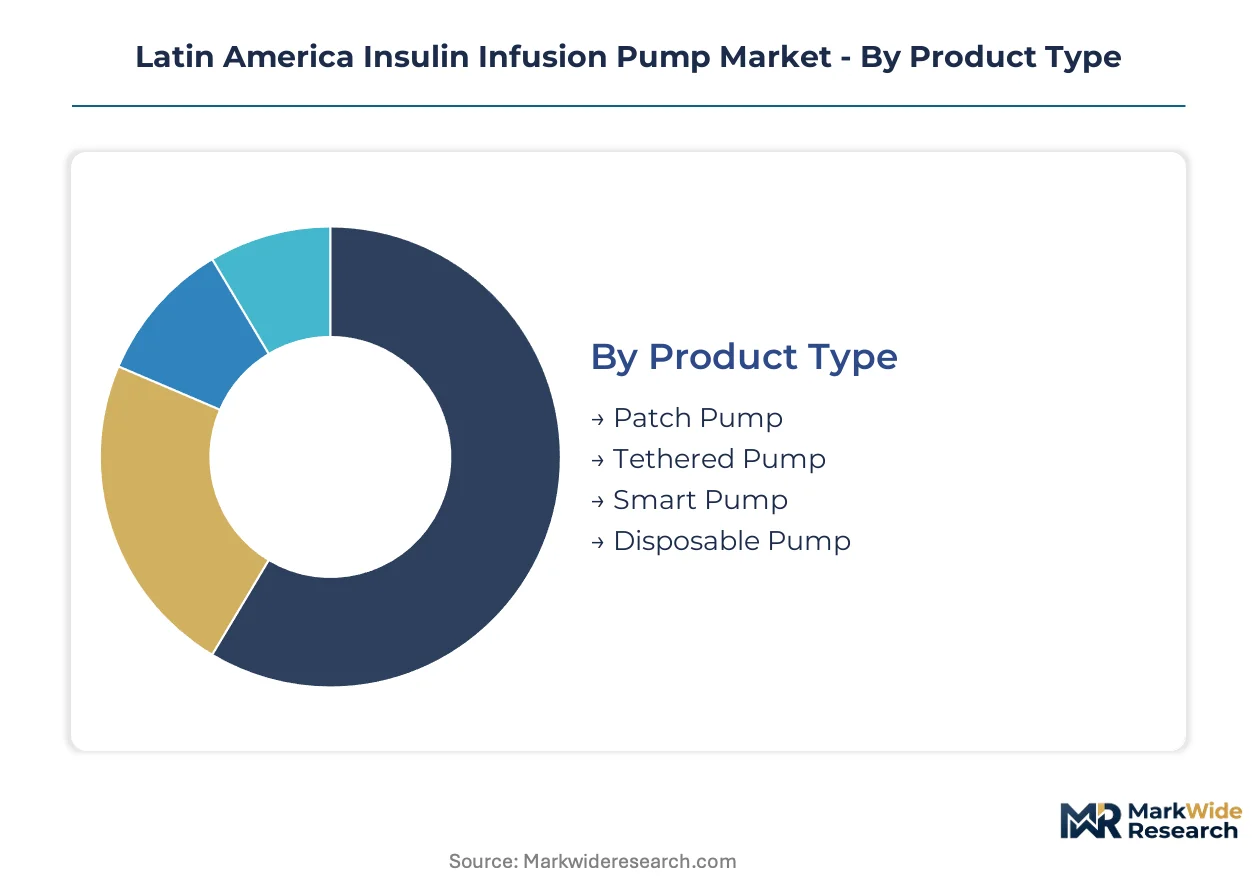
Segmentation in Latin American insulin pump markets reveals how technology adoption, reimbursement pathways, and patient self-management preferences diverge across national healthcare systems. Manufacturers configure product portfolios and channel strategies around these fracture lines to optimize regulatory investment and margin capture.
Product Type:
Brazil and Mexico absorb the majority of tethered and smart pump imports through ANVISA and COFEPRIS registration pathways, while patch pumps penetrate Argentine and Colombian markets through private-pay channels with less regulatory friction.
- Tethered Pump:Traditional tube-connected devices with external reservoirs dominate public procurement contracts in Brazil's Sistema Único de Saúde. Hospital endocrinology departments in São Paulo and Rio de Janeiro specify these systems for their established training protocols and lower per-unit acquisition cost.
- Patch Pump:Tubeless wearable formats attach directly to the skin with integrated insulin reservoirs. Mexican private diabetes clinics in Mexico City and Monterrey prescribe these for professional patients prioritizing discretion during work hours. The format is climbing the fastest as patient self-advocacy accelerates switching cycles.
- Smart Pump:Bluetooth-enabled devices with smartphone integration for dose logging and remote monitoring. Brazilian distributors leverage these for telemedicine subscription bundles under LGPD-compliant data frameworks.
- Disposable Pump:Single-use patch pumps with pre-filled insulin reservoirs for short-term therapy trials. Argentine provincial health systems deploy these in pilot programs before committing to rechargeable system investments.
Tethered pumps hold the largest share; momentum sits with patch pumps.
End User:
Cost tier stratification separates institutional purchasers seeking volume discounts from individual patients paying out-of-pocket for premium features and faster access.
- Homecare:Patients self-administering insulin through pumps in residential settings represent the primary growth vector. Brazilian families with private health plans drive replacement demand every 24-36 months as social media communities share time-in-range performance data.
- Diabetes Clinics:Specialized endocrinology centers in Buenos Aires, Mexico City, and Medellín generate concentrated prescription volume. Argentina's provincial capital expansion program creates new localized channels requiring manufacturer clinical education investment.
- Hospitals:Tertiary care facilities manage acute diabetic cases and initiate pump therapy for newly diagnosed Type 1 patients. COFEPRIS-registered devices with established reimbursement codes dominate these procurement processes.
- Pharmacies:Retail dispensaries in Colombian cities serve cash-paying patients bypassing public system wait times. INVIMA's separate private-sector pricing track complicates inventory planning for these channels.
Homecare settings command the dominant volume position; diabetes clinics are expanding most quickly.
Technology:
Application maturity separates algorithm-automated systems requiring intensive clinical validation from basic programmable devices with shorter regulatory pathways.
- Closed Loop System:Automated insulin delivery responsive to continuous glucose sensor data. São Paulo and Mexico City endocrinologists prescribe these at triple the rate of manual systems, compressing margins on open-loop alternatives.
- Continuous Glucose Monitoring:Integrated real-time glucose sensing with predictive alerts. Brazilian patients leverage these integrations for remote monitoring subscriptions permitted under updated data protection frameworks.
- Wireless Connectivity:Bluetooth or cellular transmission of pump data to caregivers and cloud platforms. Mexican telemedicine providers bundle these capabilities into chronic disease management programs.
- Manual Dosage:Patient-programmed basal rates and bolus calculations without automated adjustment. Legacy systems retain installed base among cost-constrained public health systems and older patient populations.
Manual dosage retains the largest installed base; closed loop systems show the steepest expansion trajectory.
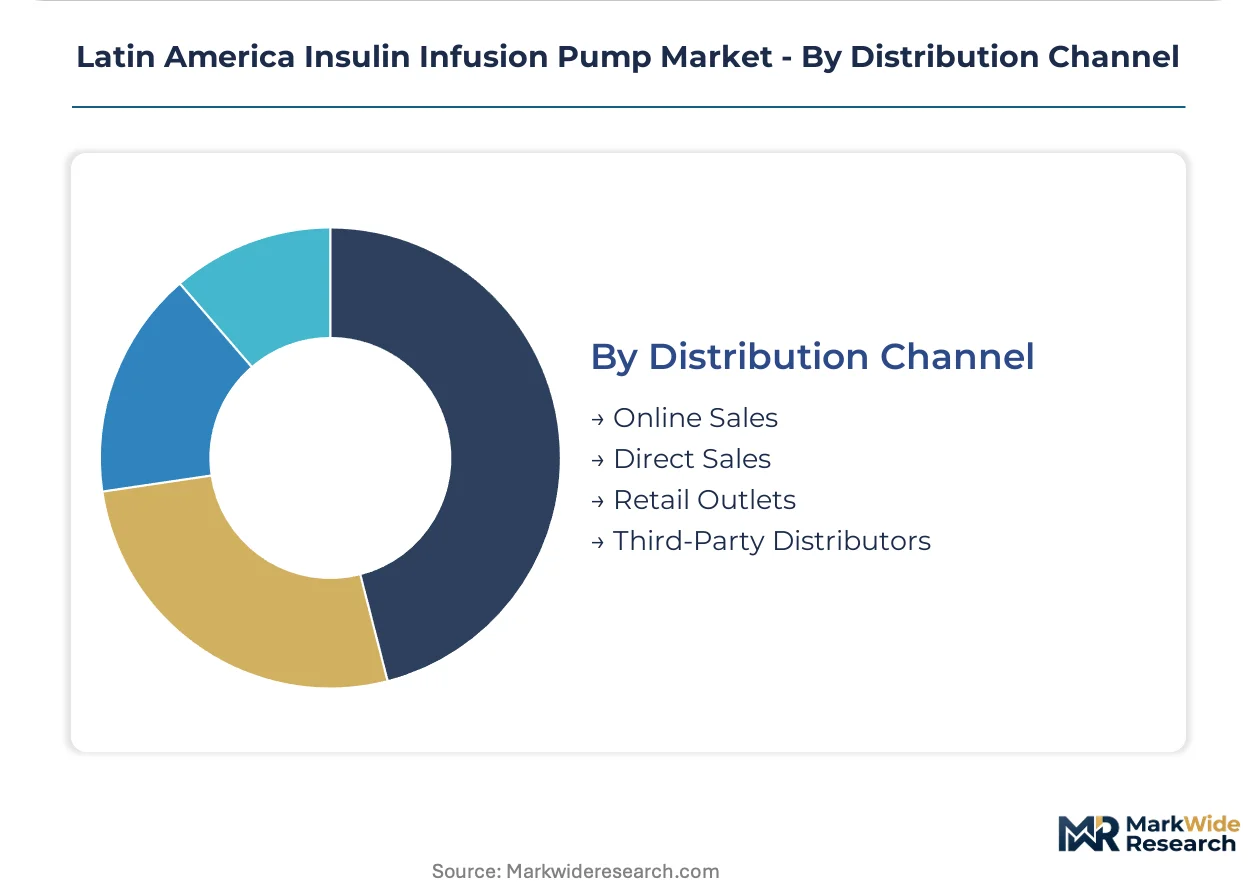
Distribution Channel:
Customer type and purchase urgency determine whether patients navigate institutional procurement delays or access devices through immediate-pay alternatives.
- Direct Sales:Manufacturer representatives contract with hospital systems and government health ministries. ANVISA registration holders maintain dedicated São Paulo teams to manage Brazilian public tender processes.
- Third-Party Distributors:Regional medical device wholesalers with established regulatory dossiers and service networks. These intermediaries absorb import duty burdens and provide local technical support.
- Online Sales:E-commerce platforms serving educated, self-directed patients with existing prescriptions. Brazilian consumers utilize these channels for accessory and supply replenishment.
- Retail Outlets:Specialized medical equipment stores in Mexican and Colombian urban centers. These locations offer same-day device pickup for patients unwilling to await shipping.
Third-party distributors handle the largest transaction volume; direct sales are gaining share fastest among premium system manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement expansions across Brazil, Mexico, and Argentina are redrawing access boundaries for insulin pump therapy. Public procurement reforms and private insurance coverage extensions now determine which patient populations transition from multiple daily injections to continuous subcutaneous insulin infusion.
Brazil
São Paulo's concentrated endocrinology infrastructure absorbs the majority of ANVISA-registered pump imports through Sistema Único de Saúde tenders. The regulator's 18-24 month Good Manufacturing Practice inspection timelines filter out manufacturers lacking dedicated Brazilian regulatory affairs teams. Rio de Janeiro's private diabetes centers drive replacement demand every 24-36 months as patient communities share time-in-range performance data.
Mexico
COFEPRIS expedited review pathways for FDA- or CE-marked devices compress time-to-market for compliant manufacturers entering Mexico City and Monterrey markets. The regulator's streamlined process rewards prior regulatory investment with faster public sector procurement access. Northern border states absorb cross-border demand from patients seeking immediate device availability.
Argentina
Provincial capital expansion of specialized endocrinology centers creates localized prescription channels beyond Buenos Aires. The national health ministry's pump therapy pilot programs deploy disposable patch formats before committing to rechargeable system investments. Córdoba and Rosario clusters concentrate private-pay demand among professional patients prioritizing discretion.
Colombia
INVIMA's separate public-private approval tracks duplicate commercialization effort while pump penetration remains below 5% nationally. Medellín's emerging diabetes care infrastructure presents first-mover advantage for manufacturers establishing clinical education programs. Bogotá's private clinics serve cash-paying patients bypassing public system wait times through retail medical equipment channels.
Chile
Santiago's integrated healthcare networks advance faster than regional counterparts in adopting telemedicine-integrated pump systems. The country's data protection framework permits remote monitoring subscriptions, enabling subscription-based revenue models. Valparaíso and Concepción clusters follow metropolitan prescribing patterns with 12-18 month lag cycles.
Latin America Insulin Infusion Pump Market Competitive Landscape
Listed leaders compete with private specialists across regulatory dossier depth and post-market service infrastructure. Market structure tilts toward consolidated channel control where ANVISA registration holders maintain dedicated São Paulo teams for public tender navigation. Three archetypes dominate: diversified medtech conglomerates with legacy insulin portfolios, pure-play pump specialists emphasizing miniaturization, and infusion therapy generalists leveraging hospital supply relationships. Competitive moves concentrate on M&A for regulatory fast-tracking and capacity expansion into Brazilian assembly to deflect import duty burdens.
Within the diversified medtech tier, Medtronic and Roche exemplify channel leadership through established multi-jurisdiction regulatory dossiers. Ypsomed occupies a differentiated position among patch pump specialists emphasizing discretion-focused miniaturization. These three anchors sit within distinct strategic vectors—comprehensive diabetes ecosystem integration, wearable format innovation, and regional service scalability—shaping how competitors configure their own market access investments.
| Leading Market Players |
|---|
| Medtronic |
| Roche |
| Ypsomed |
| Insulet |
| Tandem Diabetes Care |
| Becton Dickinson |
| Baxter International |
| B. Braun Melsungen |
| Fresenius Kabi |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four-month ANVISA Good Manufacturing Practice inspection timelines concentrate supply planning around pre-certified inventory buffers, amplifying pricing power for manufacturers with established Brazilian regulatory dossiers while compressing margins for entrants absorbing compliance lag costs.
Pricing Analysis
Certification level creates the primary spread across Latin American pump markets, with CE-marked and FDA-cleared devices commanding premium positioning against uncertified alternatives in public procurement channels. Three-tier pricing structure across premium closed-loop systems, standard tethered pumps, and economy manual devices stratifies by automation capability and after-sales service bundling. Pricing pressure stems from Brazil's cumulative import duty burdens exceeding half of landed device value, forcing foreign manufacturers to absorb tariff impacts or cede volume to local assemblers. Public hospital systems exhibit acute price sensitivity through Sistema Único de Saúde tender processes, while private diabetes clinics in São Paulo and Mexico City demonstrate willingness to pay for algorithm-automated systems with validated time-in-range outcomes.
Supply Chain Analysis
China, South Korea, and Taiwan anchor precision electromechanical component fabrication for Latin American pump assemblers, with micro-dose motors and glucose sensor substrates forming concentrated input dependencies. Reservoir and infusion set manufacturing draws from three dominant Asian contract manufacturers, exposing regional distributors to single-source fragility during logistics disruptions. Tariff exposure runs through Brazil's industrialized goods tax framework, which inflates finished device costs before customs clearance. Distribution runs through São Paulo-based third-party distributors with established ANVISA registration portfolios, who absorb import duty burdens and provide localized technical service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among Brazilian public procurement consortia and Mexican hospital group purchasing organizations, compressing vendor margins and rewarding manufacturers with scale-efficient regulatory compliance infrastructure.
For Market Incumbents: Fortify channel control through dedicated São Paulo regulatory affairs teams capable of navigating ANVISA's extended inspection timelines, while deepening backward integration into Colombian or Mexican assembly to deflect Brazil's import duty burdens. Closed-loop algorithm validation and LGPD-compliant telemedicine data infrastructure represent critical defensive moats against patch pump specialists. For New Entrants and Emerging Players: Lead with Colombia's sub-five-percent pump penetration as the most penetrable white-space geography, establishing clinical education infrastructure in Medellín before INVIMA's dual-track approval system hardens competitive access. Disposable patch pump formats offer lower regulatory friction for initial market entry, with private-pay diabetes clinics in Argentine provincial capitals providing secondary expansion channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medtech conglomerates seeking to monetize non-core diabetes device portfolios, particularly those with dormant ANVISA registrations and established Brazilian service networks. Long-term viability hinges on algorithm-automated system capabilities and telemedicine integration readiness. The signal to monitor is COFEPRIS harmonization with FDA review pathways, which would accelerate consolidation timelines for compliant asset holders.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Fast-Track | Prior regulatory investment in CE marking compresses Brazilian market access timelines for compliant manufacturers. |
| Colombia Clinical Education Buildout | First-mover infrastructure in Medellín captures underpenetrated demand before INVIMA approval tracks mature. |
| Patch Pump Miniaturization R&D | Tubeless wearable formats align with patient self-advocacy trends shortening replacement cycles to 24-36 months. |
| Telemedicine Data Platform Development | LGPD-compliant remote monitoring subscriptions enable recurring revenue streams in Brazilian homecare settings. |
| Local Assembly Capacity Expansion | Brazilian production deflects industrialized goods tax burdens while satisfying ANVISA Good Manufacturing Practice requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, engaging endocrinologists at São Paulo and Mexico City diabetes centers, biomedical engineers managing pump maintenance networks, hospital procurement officers navigating ANVISA and COFEPRIS tender processes, and third-party distributor executives with regional regulatory dossier portfolios. Secondary validation incorporated ANVISA registration databases, COFEPRIS expedited pathway filings, INVIMA public-private approval track documentation, and GPO contract repositories from Brazilian hospital consortia. Bottom-up patient population modeling and top-down device shipment triangulation anchored volume estimates.
Across the analysis window, forecasts employed segmented growth rate derivation by product type, end-user setting, technology tier, and national regulatory cluster. CAGRs were computed from annual growth factor compounding applied to base-year volume estimates. Key inputs included ANVISA inspection timeline distributions, COFEPRIS review pathway utilization rates, and provincial diabetes clinic expansion schedules from Argentine health ministry disclosures.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement expansion in Brazil's Sistema Único de Saúde or accelerated COFEPRIS-FDA harmonization would require recalibration. Forecasts reflect documented assumptions regarding regulatory inspection capacity, import duty stability, and algorithm validation timelines for closed-loop systems. Recalibration cycles align with material shifts in ANVISA enforcement deadlines, COFEPRIS pathway modifications, or provincial clinic network deployment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
France Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
France Oral Anti-Diabetic Drug Market
Diabetes Care
North America Oral Anti-Diabetic Drug Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
Philippines Diabetes Care Devices Market
Diabetes Care
Sensor Based Glucose Measuring Systems Market
Diabetes Care
Korea Continuous Glucose Monitoring Devices Market
Diabetes Care
Global Type 1 Diabetes (T1D) Market
Diabetes Care
Artificial Intelligence in Diabetes Management Market
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
Saudi Arabia Diabetes Care Devices Market
Diabetes Care
Global Non-Invasive Glucose Meter Market
Diabetes Care
Asia-Pacific Insulin Delivery Devices Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market