
 Cotinine Screening Devices Market | 2026-2036
Cotinine Screening Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cotinine Screening Devices Market Analysis
The buyer base for cotinine screening devices is broadening beyond traditional clinical laboratories toward corporate wellness administrators and occupational health departments. Abbott Laboratories leverages its established diagnostics infrastructure to serve hospital networks with integrated testing workflows. AlcoPro anchors its position in workplace safety channels where on-site rapid testing protocols dominate procurement decisions. Nano-Ditech Corp differentiates through biosensor miniaturization that supports portable screening formats for non-clinical environments.
Cotinine screening devices detect the nicotine metabolite cotinine in biological specimens through immunoassay, chromatographic, or biosensor-based methods, with detection thresholds typically ranging from 10 ng/mL in saliva to 200 ng/mL in urine depending on the intended clinical or forensic application. These devices serve smoking cessation programs, employment screening, and environmental exposure assessment by quantifying recent tobacco use with higher specificity than parent nicotine testing. Immunoassay technology occupies the largest installed base due to cost efficiency and regulatory familiarity, while biosensor platforms represent the fastest-expanding segment as semiconductor fabrication techniques enable single-use electrochemical strips at reduced unit economics. The diagnostics application commands the deepest margin pool because reimbursement codes and clinical trial protocols sustain premium pricing against occupational screening contracts.
The FDA governs premarket notification pathways for in vitro diagnostic devices under 510(k) clearance requirements, while OSHA workplace exposure standards indirectly shape employer testing frequency and documentation obligations for nicotine surveillance programs. State-level variations in employment law—particularly in California and New York where biometric privacy statutes restrict testing consent protocols—create compliance complexity that favors vendors with configurable data management platforms. Stakeholders must monitor evolving state legislation on genetic and metabolite privacy to anticipate whether cotinine testing faces expanded consent requirements or limitations on employer-mandated screening scope.
Market Dynamics
Employer-mandated nicotine testing protocols are concentrating procurement authority into corporate wellness administrators, compressing sales cycles and favoring vendors with configurable data management platforms over traditional laboratory distributors.
Growth Catalysts
- OSHA workplace surveillance standards:Documentation obligations for nicotine exposure monitoring are expanding testing frequency at manufacturing facilities and logistics hubs.
- Biosensor miniaturization:Semiconductor fabrication techniques now enable single-use electrochemical strips at reduced unit economics, opening non-clinical environments.
- United States employer mandates:Fortune 500 companies and healthcare systems are institutionalizing point-of-care testing protocols within wellness programs.
Market Restraints
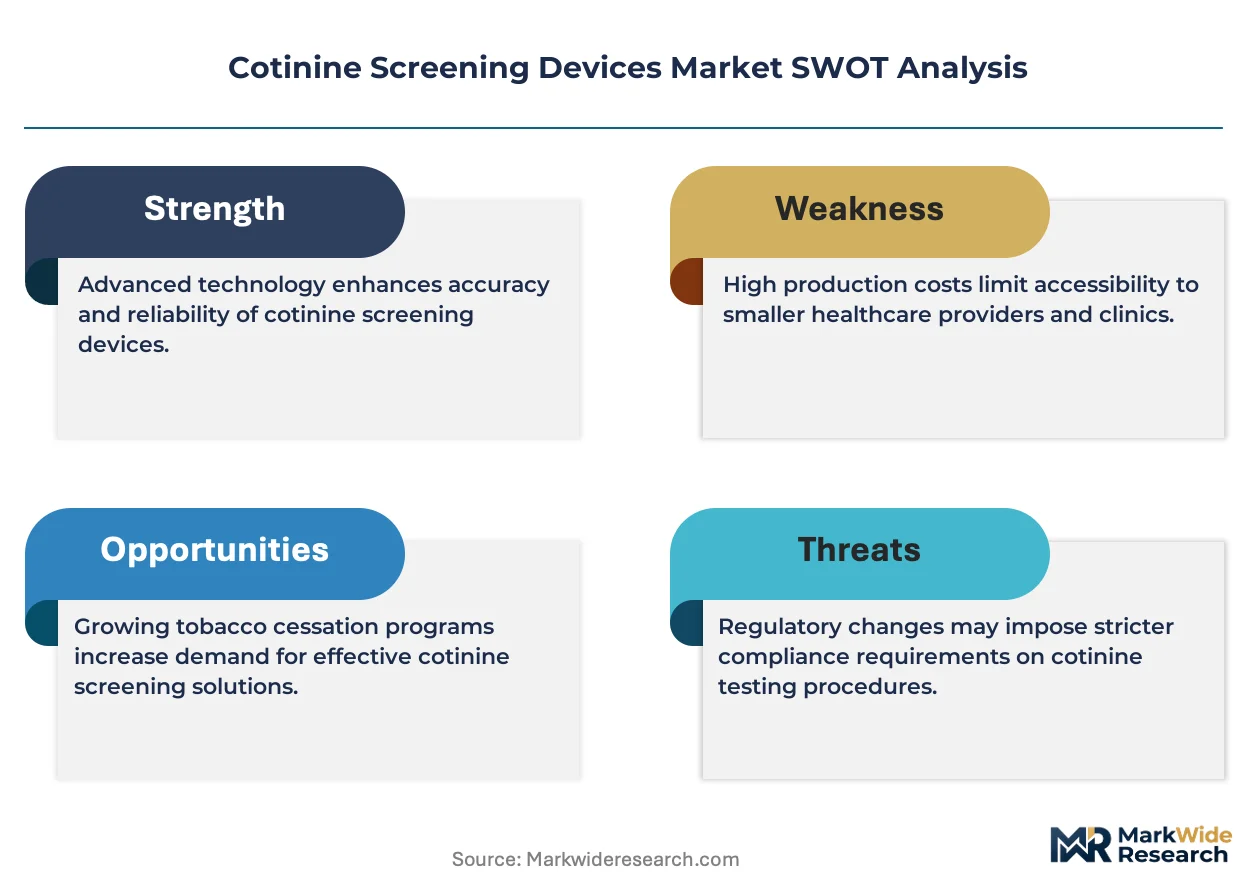
- State biometric privacy statutes:California and New York employment law variations restrict testing consent protocols, creating compliance complexity that fragments vendor addressable markets.
- Immunoassay input concentration:Antibody reagent supply chains concentrate among specialized biologics manufacturers, exposing device makers to raw material volatility.
- Saliva detection threshold limitations:The 10 ng/mL sensitivity floor for rapid screening formats generates false-negative risk in light-use detection scenarios.
Strategic Opportunities
- Environmental exposure assessment:Secondhand smoke monitoring in multi-unit housing and hospitality venues represents an underpenetrated application segment.
- EU MDR harmonization:The Medical Device Regulation's consolidated conformity assessment pathways are reducing certification friction for manufacturers seeking European market entry.
- Telehealth integration:Remote smoking cessation programs are creating demand for patient-administered screening formats with cloud-connected result transmission.
Industry Challenges
- FDA 510(k) clearance timelines:Premarket notification pathways for in vitro diagnostic devices extend product launch schedules, compressing revenue recognition windows.
- Legacy laboratory information system integration:Hospital network procurement committees prioritize seamless data interoperability, raising technical qualification barriers for emerging vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cotinine Screening Devices Market |
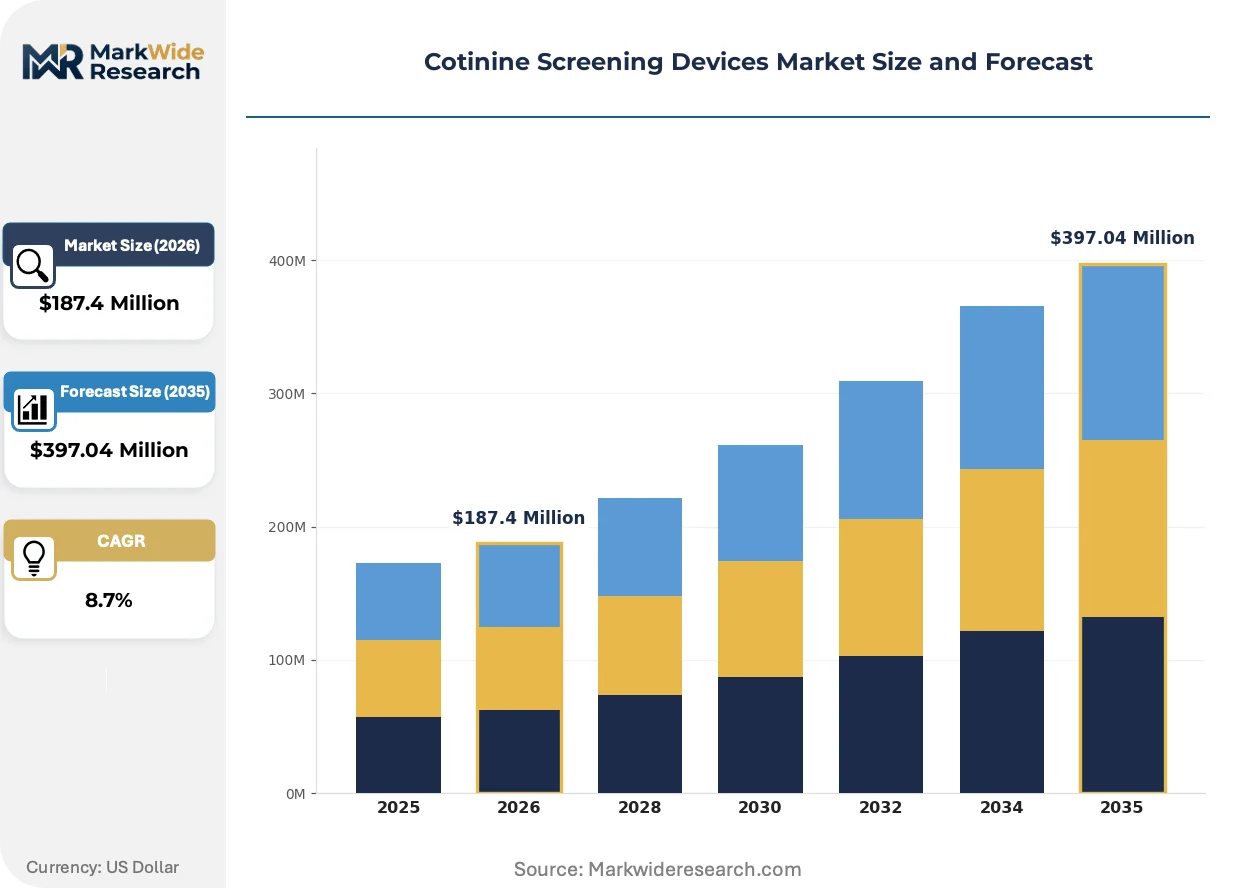
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tests, Assays, Devices, Kits Technology: Immunoassay, Chromatography, Biosensors, Spectrometry End User: Clinics, Laboratories, Hospitals, Research Institutions Application: Smoking Cessation, Environmental Monitoring, Clinical Trials, Diagnostics |
| Companies Covered | Abbott Laboratories, AlcoPro, Jant Pharmacal Corporation, Sinocare Inc., Mossman Associates, Nano-Ditech Corp, LifeSign LLC, ALFA Scientific, Ameritek USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cotinine Screening Devices Market Emerging Trajectories
Automation of sample processing workflows and convergence of electrochemical sensing with mobile health platforms are redefining competitive differentiation beyond raw detection sensitivity.
Microfluidic cartridge technology is automating specimen preparation steps that previously required trained technicians, reducing per-test labor overhead. Occupational health departments at large employers are adopting these self-contained formats to eliminate send-out laboratory dependencies. The technology is automating result turnaround from 24-48 hours to under 15 minutes, collapsing the operational case for centralized laboratory testing in high-volume screening programs.
The FDA's evolving oversight of in vitro diagnostic devices is tightening clinical validation requirements for novel biomarker claims, extending development timelines for expanded metabolite panels. Manufacturers must now demonstrate analytical performance across diverse population matrices before 510(k) clearance. Hospital network procurement committees are responding by favoring established vendors with existing regulatory dossiers over emerging entrants with unproven compliance track records.
Corporate wellness administrators are consolidating vendor relationships through multi-year enterprise agreements that bundle device supply with data analytics and program management services. This purchasing model is displacing transactional procurement of standalone testing hardware through medical distributors. The shift is most visible in the United States, where large self-insured employers are internalizing screening program ownership to capture premium differential incentives from health plans.
Cotinine Screening Devices Market Segmentation
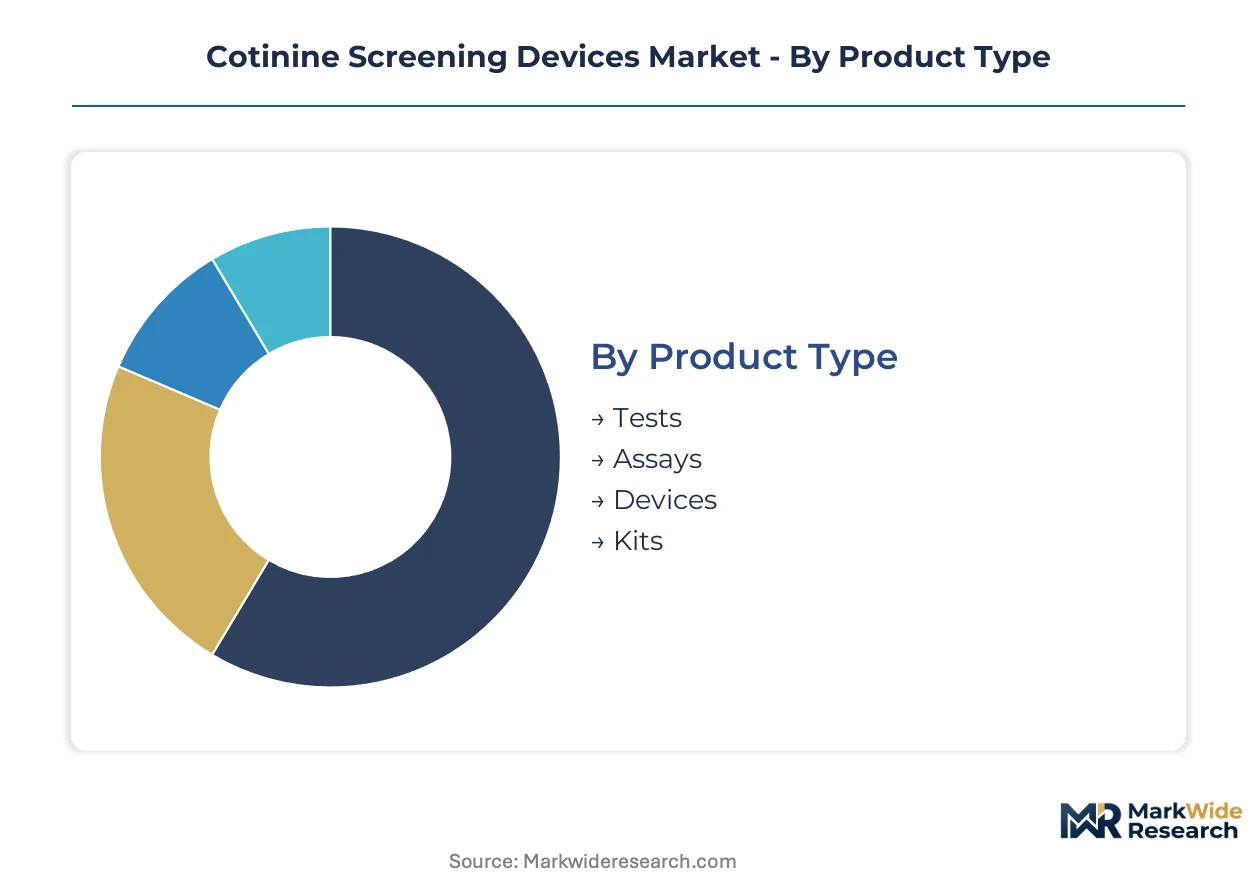
Cotinine screening devices fragment across multiple technical and commercial dimensions, with regulatory pathways and end-use economics determining which configurations capture procurement budgets. Understanding these segment boundaries clarifies where certification investments translate into sustainable revenue streams.
Product Type:
FDA 510(k) clearance requirements vary sharply across product formats, with integrated devices facing the most extensive clinical validation burdens while consumable kits navigate streamlined premarket notification pathways.
- Tests:Single-use lateral flow cassettes dominate workplace screening programs where on-site administrators require minimal training. Demand concentrates among Fortune 500 occupational health departments seeking OSHA-compliant nicotine surveillance documentation.
- Assays:Laboratory-grade reagent systems with established antibody specificity profiles anchor hospital network procurement contracts. Clinical laboratories in the United States prioritize these formats for their integration with automated immunoassay analyzers and existing LIS infrastructure.
- Devices:Handheld electrochemical readers with digital result capture serve point-of-care environments requiring immediate documentation.
- Kits:Bundled specimen collection and processing consumables reduce per-test supply chain complexity for decentralized screening programs.
Leading the category by volume: Tests. Growing fastest: Devices.
Technology:
Unit economics and technical qualification thresholds stratify the technology landscape, with mature platforms defending installed bases against semiconductor-enabled entrants.
- Immunoassay:Antibody-based detection systems with 10-200 ng/mL sensitivity ranges occupy the deepest installed base across clinical and workplace settings. United States hospital networks favor these platforms for their regulatory familiarity and reimbursement code alignment.
- Chromatography:LC-MS/MS reference methods provide definitive quantification for forensic and clinical trial applications requiring metabolite specificity. Research institutions and contract laboratories absorb these systems despite higher capital and operational overhead.
- Biosensors:Miniaturized electrochemical strips fabricated through semiconductor processes enable sub-dollar unit costs at scale.
- Spectrometry:Optical detection methods remain niche for specialized environmental monitoring applications.
Immunoassay maintains the largest revenue base. Biosensors are climbing the fastest as fabrication costs decline.
End User:
Procurement authority and technical sophistication requirements diverge sharply across customer types, with enterprise wellness administrators displacing traditional laboratory distributors in high-volume segments.
- Clinics:Federally qualified health centers and community health clinics integrate rapid cotinine testing into bundled preventive service workflows. Medicaid reimbursement sustainability drives format selection toward lowest total cost of ownership.
- Laboratories:Reference and hospital-affiliated laboratories defend margin pools through high-throughput automation and esoteric test menus. These facilities concentrate in metropolitan United States markets with dense employer and payer relationships.
- Hospitals:Integrated delivery networks prioritize seamless EHR connectivity and multi-site standardization.
- Research Institutions:Academic medical centers and CROs absorb specialized formats for protocol-specific validation requirements.
Laboratories command the deepest procurement budgets. Clinics are expanding most quickly as retail health formats proliferate.
Application:
Reimbursement availability and regulatory oversight intensity create four distinct commercial environments, from premium-priced clinical diagnostics to cost-pressured environmental surveillance.
- Smoking Cessation:Telehealth-integrated programs create demand for patient-administered screening with cloud-connected result transmission. United States employer wellness contracts increasingly bundle these services with coaching and pharmacotherapy support.
- Environmental Monitoring:Secondhand smoke exposure assessment in multi-unit housing and hospitality venues represents an emerging volume opportunity. Property management firms and public health agencies drive procurement with lower per-test budget constraints than clinical counterparts.
- Clinical Trials:Protocol-mandated biomarker verification requires documented chain of custody and analytical validation.
- Diagnostics:Reimbursed clinical testing for tobacco use disorder assessment sustains premium pricing.
Diagnostics retains the highest margin structure. Environmental Monitoring is gaining share fastest as regulatory exposure standards expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antibody reagent manufacturing clusters in the United States and Germany anchor the upstream supply base for cotinine screening devices. Semiconductor fabrication capabilities in East Asia enable electrochemical biosensor production at scale. Regulatory harmonization efforts are reshaping market access trajectories across major economies.
United States
Fortune 500 occupational health departments and healthcare systems drive procurement volume for point-of-care testing formats. FDA 510(k) clearance pathways govern premarket notification requirements for in vitro diagnostic devices, extending development timelines for novel biomarker claims. The Boston-Cambridge corridor hosts contract research organizations validating analytical performance across diverse population matrices.
Germany
Industrial employers in manufacturing and logistics sectors absorb workplace surveillance devices under expanding documentation obligations. EU MDR harmonization is consolidating conformity assessment pathways and reducing certification friction for European market entry. The Rhine-Ruhr metropolitan region concentrates reference laboratory capacity serving cross-border clinical trial protocols.
China
Domestic demand for smoking cessation monitoring is expanding through telehealth-integrated wellness programs. NMPA oversight of in vitro diagnostic devices requires clinical validation dossiers for domestic registration, favoring established manufacturers with existing regulatory track records. The Yangtze River Delta hosts semiconductor foundries fabricating electrochemical sensor strips at reduced unit economics.
Japan
Corporate wellness administrators at large manufacturers are institutionalizing nicotine screening within employee health initiatives. PMDA regulatory frameworks align with international standards for clinical diagnostic devices, streamlining approval pathways for imported technologies. The Kanto region around Tokyo anchors hospital network procurement committees prioritizing seamless EHR connectivity.
United Kingdom
Public health agencies and property management firms are piloting environmental exposure assessment programs for secondhand smoke monitoring. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while preserving independent market authorization pathways. The Greater London area concentrates occupational health service providers bundling device supply with program management services.
Cotinine Screening Devices Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue biosensor miniaturization and telehealth integration vectors. The vendor base stratifies across three tiers: multinational diagnostics conglomerates defending hospital network contracts, mid-scale workplace safety specialists anchoring occupational health channels, and semiconductor-enabled startups attacking portable screening formats. Three strategic archetypes dominate: integrated device-analytics platforms, consumable-focused reagent suppliers, and electrochemical sensor technology licensors. Competitive intensity concentrates in M&A activity consolidating data management capabilities and strategic partnerships linking device manufacturers with cloud-connected wellness platforms.
Within the multinational tier, Abbott Laboratories represents the integrated diagnostics archetype leveraging established infrastructure for hospital network penetration. AlcoPro exemplifies the workplace safety specialist model anchoring position in rapid on-site testing protocols. Nano-Ditech Corp occupies the semiconductor-enabled entrant position pursuing biosensor miniaturization for non-clinical environments. These three entities collectively illustrate the competitive vectors reshaping procurement authority toward configurable enterprise platforms.
| Leading Market Players |
|---|
| Abbott Laboratories |
| AlcoPro |
| Jant Pharmacal Corporation |
| Sinocare Inc. |
| Mossman Associates |
| Nano-Ditech Corp |
| LifeSign LLC |
| ALFA Scientific |
| Ameritek USA |
| Others |
Supply Flow & Price Mechanics
Captive antibody reagent production in the United States and Germany anchors supply security for cotinine screening device manufacturers, insulating premium-tier vendors from raw material volatility while compressing margins for competitors dependent on spot-market biologics procurement. This integration choice concentrates pricing power among established diagnostics conglomerates that control upstream monoclonal antibody supply chains.
Pricing Analysis
Warranty and calibration service bundling separates premium-tier device contracts from unbundled consumable-only procurement prevalent in workplace screening programs. Three-tier pricing structure across premium, standard, and economy levels tracks FDA certification grade and volume commitment scale. Pricing pressure stems from biosensor miniaturization enabling sub-dollar electrochemical strips at volume. Corporate wellness administrators exhibit highest price sensitivity; hospital networks with embedded LIS infrastructure demonstrate lowest.
Supply Chain Analysis
Specialized biologics manufacturing workforce availability in Massachusetts and Bavaria constrains antibody reagent expansion, tethering device makers to concentrated supplier relationships. Semiconductor fabrication in Taiwan and South Korea enables electrochemical sensor strip production at scale. Single-source vulnerability runs through monoclonal antibody suppliers for immunoassay platforms. Distribution runs through medical device distributors serving hospital networks and direct enterprise contracts for occupational health departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibody reagent manufacturing capacity constraints prop pricing premiums for vendors with captive biologics supply, sustaining margin pools despite biosensor commoditization pressures.
For Market Incumbents: Acquire cloud-connected data analytics platforms to defend hospital network contracts against semiconductor-enabled entrants attacking portable screening formats. Invest in FDA 510(k) clearance dossier expansion for expanded metabolite panels. Prioritize backward integration into monoclonal antibody production to secure raw material supply against biologics manufacturer concentration.
For New Entrants and Emerging Players: Begin with environmental exposure assessment applications in multi-unit housing and hospitality venues where regulatory standards are expanding fastest. Target property management firms with lower technical qualification barriers than hospital procurement committees. Deploy telehealth-integrated patient-administered formats with direct-to-employer sales bypassing traditional laboratory distributors.
For Investors and Strategic Acquirers: Exit pathways concentrate in enterprise wellness platform acquisitions bundling device supply with program management services. Five-to-ten year viability hinges on regulatory harmonization sustaining cross-border certification efficiency. Watch EU MDR implementation timelines as inflection indicator for European market entry friction reduction.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Expansion | Hospital network procurement committees favor established regulatory dossiers over unproven entrants. |
| Cloud-Connected Data Platform Development | Corporate wellness administrators consolidate vendor relationships through bundled analytics services. |
| Monoclonal Antibody Supply Integration | Captive biologics production insulates margin pools from specialized manufacturer concentration risk. |
| Telehealth Integration Partnership | Remote smoking cessation programs create demand for patient-administered screening formats. |
| EU MDR Harmonization Investment | Consolidated conformity assessment pathways reduce certification friction for European market entry. |
Methodological Framework
Document review covered FDA 510(k) clearance databases, OSHA workplace surveillance guidance, and EU MDR technical documentation, complemented by interviews with diagnostics manufacturing executives, occupational health department administrators, hospital procurement committee members, and GPO contracts managers. Secondary validation drew from CMS reimbursement code databases, clinical laboratory accreditation records, and employer wellness program disclosures. Bottom-up device shipment estimates and top-down healthcare expenditure allocations were triangulated.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to model expansion across product type, technology platform, end-user category, and application segment dimensions. CAGRs were derived from regression analysis of installed base growth and replacement cycle dynamics. Forecast inputs incorporated telehealth adoption curves and state-level biometric privacy statute evolution.
Underlying measurement precision varies by segment; diagnostics and clinical trials applications carry tighter precision than environmental monitoring estimates. Forecasts reflect assumptions regarding FDA clearance timeline stability and employer mandate expansion sustainability. Material deviation in state privacy legislation enforcement or antibody reagent supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Global Breath Analyzer Market
Diagnostic Devices
Breathalyzers Market
Diagnostic Devices
Biopsy Guidance System Market
Diagnostic Devices
Bronchial Biopsy Devices Market
Diagnostic Devices
Automated Visual Field Analyzer Market
Diagnostic Devices
Point of Care Blood Testing Devices Market
Diagnostic Devices
Global Real Time Polymerase Chain Reaction Systems Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Pulmonary Function Testing Devices Market
Diagnostic Devices
Navigated Biopsy Needles Market
Diagnostic Devices
Contactless Vital Sign Monitoring Device Validation Test Platforms Market
Diagnostic Devices
Skin Moisture Detectors Market
Diagnostic Devices
Pelvic Floor Diagnostics Market
Diagnostic Devices
Point-Of-Care Breathalyzer Market
Diagnostic Devices
Breath Samplers Market
Diagnostic Devices
Europe Breath Analyzer Market