
 Europe Diabetes Care Devices Market | 2026-2036
Europe Diabetes Care Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Diabetes Care Devices Market Analysis
Aftermarket consumables revenue is fragmenting across sensor replacement cycles and subscription-based glucose monitoring platforms. Dexcom, Inc. leverages its direct-to-consumer channel infrastructure to capture recurring revenue streams. Novo Nordisk A/S anchors its position through integrated insulin delivery ecosystems that bundle devices with pharmaceutical portfolios. Ypsomed Holding AG specializes in pen needle and pump delivery systems for regional European markets.
Europe diabetes care devices encompass instruments engineered for glycemic measurement and insulin administration, typically operating with electrochemical biosensor sensitivity thresholds of 20 to 600 mg/dL and wireless data transmission protocols for real-time metabolic tracking. Their primary commercial purpose centers on enabling patient self-management while reducing long-term diabetic complication burdens across ambulatory and institutional settings. Continuous glucose monitors command expanding margin pools as reimbursement shifts favor real-time data over intermittent fingerstick testing. Pen devices retain volume dominance in Type 2 diabetes applications where patient adherence depends on injection simplicity rather than pump complexity.
EMA's Medical Device Regulation and the EU AI Act are reshaping software-as-medical-device classifications for algorithm-driven glucose prediction tools, forcing manufacturers to rebuild quality management systems around post-market surveillance obligations. CE marking requirements under MDR extend clinical evidence demands to legacy devices previously approved under the Medical Device Directive, compressing timelines for technical documentation resubmission. Stakeholders must monitor how national health technology assessment bodies in France, Germany, and Italy differentially weigh cost-effectiveness evidence against patient-reported outcome measures when determining reimbursement tiers for interoperable closed-loop systems.
Market Dynamics
EMA's Medical Device Regulation is compressing approval timelines for legacy devices while simultaneously elevating clinical evidence requirements, forcing manufacturers to restructure quality management systems around post-market surveillance obligations.
Growth Catalysts
- Home Care Self-Monitoring:Patients across Germany, France, and Italy are adopting continuous glucose monitoring systems for real-time metabolic tracking outside institutional settings.
- MDR Reimbursement Alignment:National health technology assessment bodies in Germany now weight cost-effectiveness evidence for interoperable closed-loop systems more favorably than intermittent fingerstick alternatives.
- Sensor Miniaturization:Advances in electrochemical biosensor engineering enable 14-day wear durations that reduce patient burden and accelerate replacement cycle frequency.
Market Restraints
- Precious Metal Input Volatility:Platinum and palladium price swings in electrochemical sensor electrodes compress manufacturing margins for disposable components.
- Single-Source Firmware Dependencies:Algorithm-driven glucose prediction tools rely on concentrated software licensing from limited European developers, creating supply vulnerability.
- MDR Technical Documentation Resubmission:Legacy devices previously approved under the Medical Device Directive face compressed timelines for clinical evidence reconstruction.
Strategic Opportunities
- Underpenetrated Eastern European Markets:Poland, Romania, and Hungary show widening gaps between diabetes prevalence and reimbursed device access that direct-to-consumer channels can address.
- EU AI Act Algorithm Classification:Software-as-medical-device frameworks create first-mover advantage for manufacturers building post-market surveillance databases ahead of competitor submissions.
- Pharmacy Channel Integration:Retail pharmacy networks in France are expanding device dispensing authority, creating new patient touchpoints beyond traditional hospital procurement.
Industry Challenges
- Biocompatibility Certification Bottlenecks:Adhesive and sensor membrane materials face extended cytotoxicity testing timelines under updated ISO 10993 standards.
- Interoperability Protocol Fragmentation:Closed-loop insulin delivery systems struggle with data exchange standardization across competing pump and monitor platforms.
- Legacy System Integration Friction:Hospital electronic health record architectures in Italy and Spain require costly middleware development for real-time glucose data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Diabetes Care Devices Market |
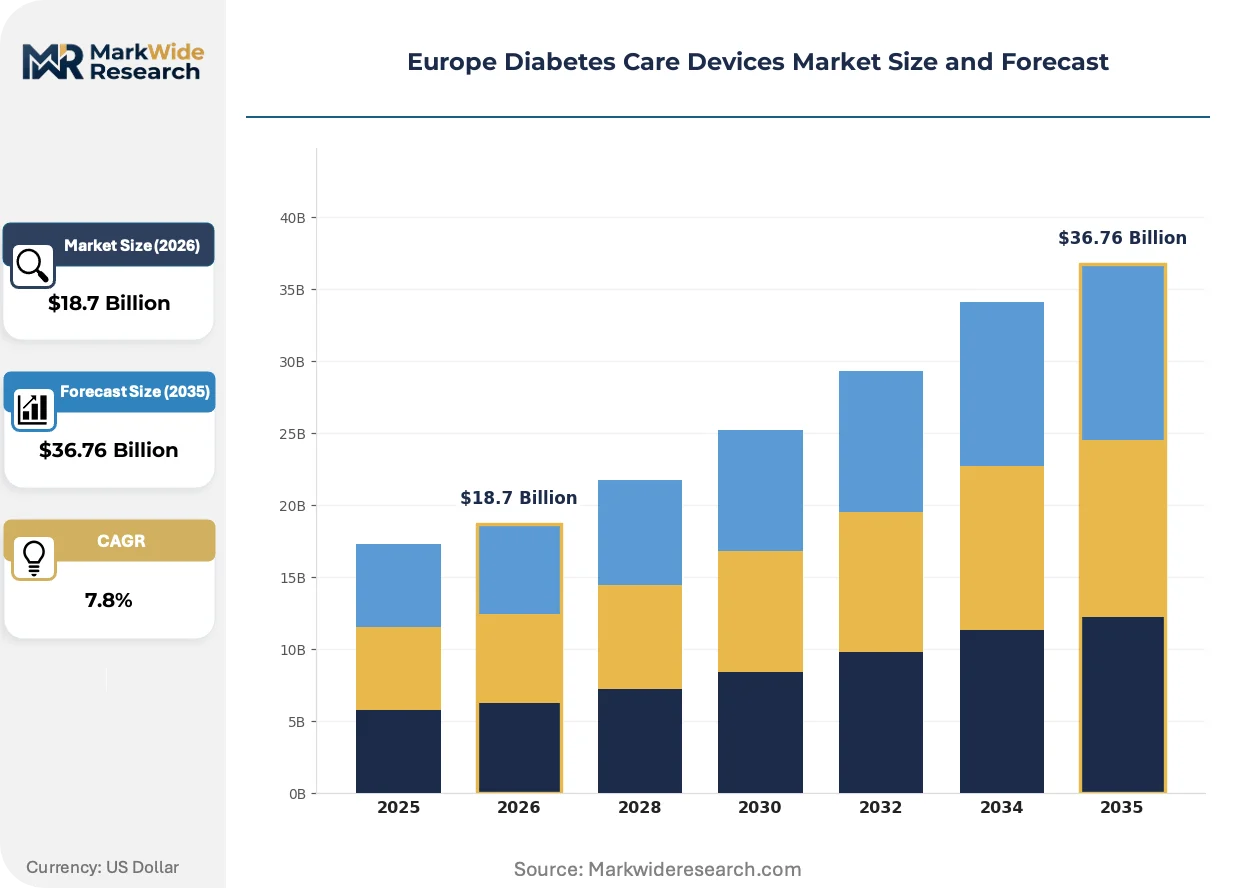
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pumps, Blood Glucose Meters, Continuous Glucose Monitors, Pen Devices Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Hypoglycemia End User: Home Care, Hospitals, Clinics, Diabetes Centers Technology: Wearable Devices, Mobile Apps, Cloud Computing, Biosensors |
| Companies Covered | Dexcom, Inc., Sanofi S.A., Medtronic plc, Novo Nordisk A/S, Insulet Corporation, Abbott Laboratories, Ypsomed Holding AG, B. Braun Melsungen AG, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Diabetes Care Devices Market Emerging Trajectories
Algorithm-driven metabolic prediction is displacing reactive glucose measurement across European ambulatory care, while regulatory software classification and channel restructuring simultaneously reshape competitive entry pathways.
Non-invasive optical glucose sensing is hybridizing with subcutaneous electrochemical validation in hybrid monitoring architectures. Early adopters in Scandinavian hospital systems are piloting dual-modality devices that reduce calibration frequency. This convergence is hybridizing the traditional boundary between consumer wellness wearables and clinical-grade diagnostic equipment, compressing reimbursement categorization debates.
EMA's Medical Device Regulation and the EU AI Act are mandating algorithm transparency documentation for glucose prediction software. Manufacturers must now submit training dataset provenance and bias assessment protocols alongside traditional safety evidence. Class IIb and III device categories face the steepest compliance burden, with German notified bodies experiencing 18-month backlog spikes.
Subscription-based sensor replacement models are displacing transactional device purchases in patient acquisition strategies. Retail pharmacy chains in the Netherlands and Belgium now bundle monthly sensor shipments with remote patient monitoring services. This shift is most visible in Type 1 diabetes populations where adherence tracking improves payer risk stratification.
Europe Diabetes Care Devices Market Segmentation
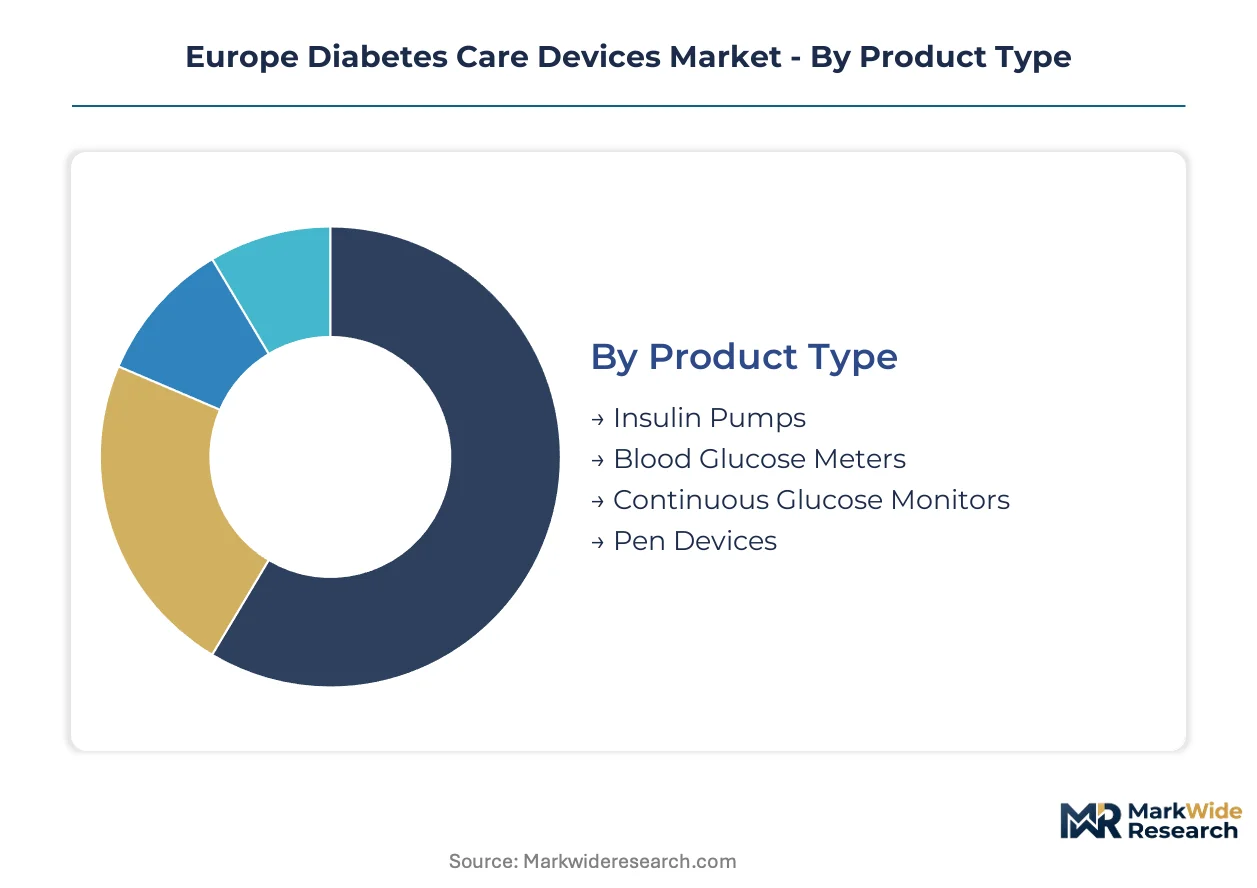
Device segmentation in European diabetes care reveals divergent margin structures across acute versus ambulatory settings. Manufacturers prioritize segments where reimbursement frameworks align with sensor replacement economics and software-enabled service models.
Product Type:
Electromechanical delivery systems span the full spectrum from disposable injection platforms to algorithm-driven closed-loop architectures.
- Insulin Pumps:Motor-driven reservoir systems deliver basal and bolus insulin through subcutaneous infusion sets. German and Dutch reimbursement pools favor patch pump form factors that eliminate tubing burden. EMA's MDR clinical evidence requirements are compressing approval timelines for next-generation closed-loop integrations.
- Continuous Glucose Monitors:Electrochemical biosensors with 20-600 mg/dL sensitivity ranges transmit real-time data via Bluetooth Low Energy protocols. French and Italian patients are driving adoption of 14-day wear duration sensors that reduce replacement frequency.
- Blood Glucose Meters:Handheld electrochemical analyzers using capillary blood samples remain prevalent in Eastern European markets where reimbursement for continuous monitoring remains limited.
- Pen Devices:Spring-loaded disposable and reusable injection platforms dominate Type 2 diabetes volumes across European pharmacy channels due to adherence simplicity.
The dominant share belongs to Pen Devices, while Continuous Glucose Monitors is closing the gap fastest.
Application:
Disease severity and treatment intensity dictate device selection across patient cohorts with divergent monitoring frequency requirements.
- Type 1 Diabetes:Absolute insulin deficiency mandates intensive monitoring and pump-based delivery. Scandinavian hospital systems are piloting dual-modality optical-electrochemical hybrid sensors to reduce calibration burden.
- Type 2 Diabetes:Progressive beta-cell dysfunction drives pen device volumes and intermittent monitoring adoption. Spanish and Portuguese payers are expanding CGM reimbursement for insulin-using Type 2 populations.
- Gestational Diabetes:Temporary hyperglycemia during pregnancy requires short-duration monitoring solutions with obstetric workflow integration.
- Hypoglycemia:Recurrent low glucose events drive demand for predictive alert systems with emergency contact protocols.
Type 1 Diabetes commands the premium tier, yet Type 2 Diabetes is expanding most quickly as reimbursement broadens.
End User:
Care setting determines device specification, with institutional procurement favoring interoperability and home care prioritizing usability.
- Home Care:Self-monitoring patients across Germany, France, and Italy are adopting subscription-based sensor replacement models bundled with remote monitoring services.
- Hospitals:Acute care facilities in Italy and Spain require costly middleware development for real-time glucose data ingestion into electronic health record architectures.
- Clinics:Outpatient endocrinology practices serve as device initiation points where reimbursement authorization workflows concentrate.
- Diabetes Centers:Specialized institutions in Belgium and the Netherlands coordinate closed-loop system training and algorithm personalization.
Home Care holds the volume lead, while Diabetes Centers are gaining share fastest through closed-loop specialization.
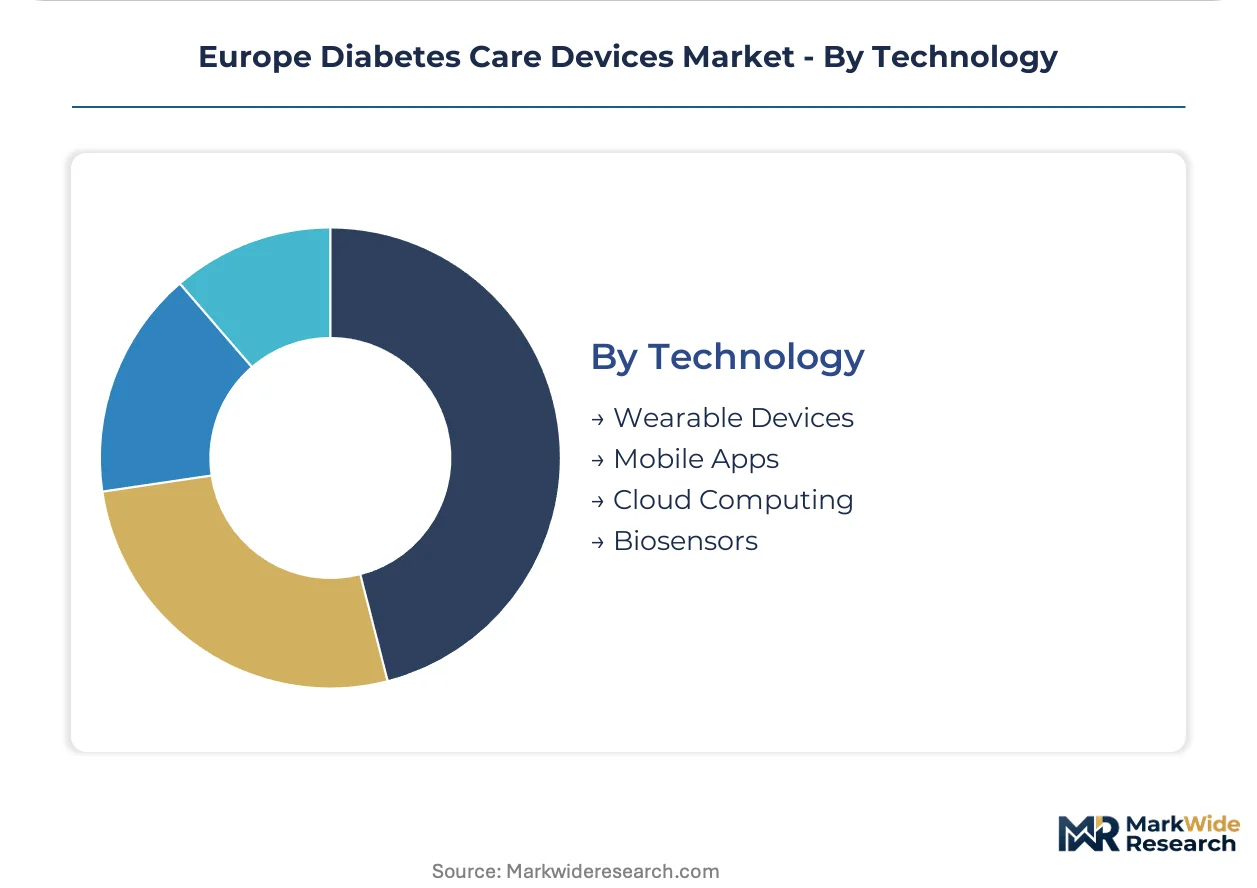
Technology:
Digital infrastructure layers are reshaping competitive entry pathways through software-as-medical-device classifications.
- Wearable Devices:Skin-adherent sensors and patch pumps integrate electrochemical measurement with wireless transmission. EMA and EU AI Act transparency mandates are forcing algorithm documentation for glucose prediction tools.
- Mobile Apps:Smartphone-based data visualization and insulin dose calculators face escalating clinical evidence requirements under MDR software classifications.
- Cloud Computing:Remote data aggregation platforms enable payer risk stratification and population health management across European healthcare systems.
- Biosensors:Enzymatic and affinity-based detection mechanisms underpin all electrochemical glucose measurement with platinum and palladium electrode dependencies.
Wearable Devices anchors current revenue, though Cloud Computing is climbing the fastest as remote monitoring services scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Europe diverge sharply between reimbursement-rich Western markets and access-constrained Eastern regions, with Germany and France prioritizing closed-loop systems while Poland and Romania rely predominantly on conventional pen devices.
Germany
German patients drive the highest per-capita adoption of continuous glucose monitoring systems in Europe, with statutory health insurers now covering real-time data platforms for Type 1 and insulin-intensive Type 2 populations. The country's national health technology assessment body, the Gemeinsamer Bundesausschuss, weights cost-effectiveness evidence for interoperable closed-loop systems more favorably than fingerstick alternatives. Manufacturing and R&D activity concentrates in the Rhine-Main region around Frankfurt, where Medtronic and Abbott maintain European operational headquarters serving coordinated care networks.
France
French diabetes care consumption tilts toward pharmacy-channel distribution models, with retail networks expanding device dispensing authority beyond traditional hospital procurement pathways. The national pharmaceutical regulator ANSM enforces EMA Medical Device Regulation compliance while coordinating with the Haute Autorité de Santé on reimbursement tiering for algorithm-driven glucose prediction tools. Industrial activity clusters in the Île-de-France region, where Sanofi S.A. anchors integrated insulin delivery ecosystem development combining pharmaceutical portfolios with delivery device engineering.
United Kingdom
UK patients access diabetes devices through the National Health Service's technology appraisal pathways, with NICE guidelines increasingly favoring subscription-based sensor replacement models over capital equipment purchases. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device oversight with retained EU MDR standards while streamlining approval for software-as-medical-device classifications. Research concentration sits in the Oxford-Cambridge-London triangle, where academic medical centers pilot dual-modality optical-electrochemical hybrid sensors to reduce calibration burden.
Italy
Italian device consumption emphasizes hospital-integrated procurement for acute care settings, though home care adoption accelerates in northern regions with stronger regional health authority reimbursement autonomy. The national pharmaceutical regulator AIFA implements EMA MDR requirements while regional health technology assessment bodies in Lombardy and Veneto differentially weigh patient-reported outcome measures against cost-effectiveness evidence. Device distribution and training infrastructure concentrates in Milan and Bologna, where diabetes centers coordinate closed-loop system personalization and algorithm calibration services.
Poland
Polish diabetes care consumption remains heavily weighted toward pen devices and intermittent blood glucose meters, with continuous monitoring access limited to private payment or selective regional reimbursement exceptions. The national pharmaceutical regulator URPL applies EMA MDR standards with notified body oversight from neighboring EU member states, compressing approval timelines for manufacturers seeking Eastern European market entry. Emerging demand concentration appears in the Warsaw and Kraków metropolitan areas, where private endocrinology clinics and direct-to-consumer channels address widening gaps between diabetes prevalence and reimbursed device access.
Europe Diabetes Care Devices Market Vendor Landscape
Capability concentration sits with integrated pharmaceutical-device conglomerates; scale advantage sits with specialized sensor and delivery system manufacturers. The European diabetes care devices market structures around three tiers: global diversified healthcare conglomerates with bundled insulin-drug portfolios, mid-cap device specialists with concentrated sensor or pump expertise, and regional European players with pharmacy-channel distribution depth. Dominant competitive moves include vertical integration into biosensor electrode manufacturing to secure platinum and palladium supply chains, and strategic partnerships with cloud computing platforms to build post-market surveillance databases ahead of EU AI Act compliance deadlines.
Within the integrated pharmaceutical-device tier, Novo Nordisk A/S and Sanofi S.A. occupy positions anchoring insulin delivery ecosystems that bundle devices with pharmaceutical portfolios. Dexcom, Inc. exemplifies the specialized sensor archetype, leveraging direct-to-consumer channel infrastructure to capture recurring revenue from subscription-based glucose monitoring platforms. Ypsomed Holding AG represents the regional European specialist model, concentrating pen needle and pump delivery systems for pharmacy-channel distribution across German-speaking and adjacent markets.
| Leading Market Players |
|---|
| Dexcom, Inc. |
| Sanofi S.A. |
| Medtronic plc |
| Novo Nordisk A/S |
| Insulet Corporation |
| Abbott Laboratories |
| Ypsomed Holding AG |
| B. Braun Melsungen AG |
| F. Hoffmann-La Roche Ltd |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese electrochemical sensor electrode manufacturing is compressing platinum and palladium input costs while German notified body backlogs extend lead times for CE-marked finished devices. This utilization asymmetry between raw material processing and regulatory-constrained final assembly is fragmenting margin capture across the value chain.
Pricing Analysis
Contract structures favor long-term offtake agreements for platinum and palladium electrodes, with spot purchasing limited to volatile periods. Pricing stratifies across premium, standard, and economy tiers based on MDR certification status and wireless data transmission protocol sophistication. Cost compression in economy-tier pen devices is intensifying because Eastern European payers limit reimbursement to intermittent fingerstick alternatives. Hospital procurement committees demonstrate lowest price sensitivity, while direct-to-consumer channels serving Polish and Romanian patients face acute margin pressure.
Supply Chain Analysis
Extended payment terms from German and French hospital procurement systems are forcing sensor manufacturers to utilize supply-chain finance facilities. Manufacturing concentrates in Germany, the Netherlands, and Switzerland for precision electrochemical assembly, while adhesive and membrane materials draw from specialized chemical producers in Belgium and Italy. Single-source vulnerability sits with concentrated firmware licensing from limited European algorithm developers. Distribution runs through pharmacy networks in France and the Netherlands, with hospital procurement remaining dominant in Italy and Spain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is expanding as national health technology assessment bodies differentially weigh patient-reported outcomes against cost-effectiveness evidence, creating reimbursement tier niches across member states.
For Market Incumbents: Harden quality management systems around post-market surveillance obligations before EU AI Act algorithm transparency mandates take full effect. Backward integration into biosensor electrode manufacturing secures platinum and palladium supply chains against precious metal input volatility. Prioritize CE marking pathway acceleration for legacy devices facing MDR technical documentation resubmission deadlines. For New Entrants and Emerging Players: Eastern European underpenetration in continuous glucose monitoring presents the most accessible white space, with Poland and Romania showing widening gaps between diabetes prevalence and reimbursed device access. Direct-to-consumer channels bypassing traditional hospital procurement offer lower regulatory friction for algorithm-driven glucose prediction tools. Pharmacy channel integration in France and Belgium provides established patient touchpoints for subscription-based sensor replacement models. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized sensor manufacturers with direct-to-consumer infrastructure and subscription-based patient acquisition strategies. Long-term viability over the coming decade rests on post-market surveillance database depth ahead of EU AI Act compliance deadlines. Watch for German notified body capacity expansion as the signal indicating regulatory bottleneck alleviation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | MDR clinical evidence requirements compress timelines for legacy device resubmissions across German notified bodies. |
| Hospital System Partnership | Italian and Spanish electronic health record middleware development creates captive demand for interoperable glucose data ingestion. |
| Software Companion Development | EU AI Act algorithm classification mandates transparency documentation for glucose prediction training datasets. |
| Reimbursement Strategy | German Gemeinsamer Bundesausschuss weighting favors closed-loop cost-effectiveness evidence over fingerstick alternatives. |
| Backward Integration | Captive platinum and palladium electrode production insulates margins from precious metal spot price volatility. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EMA MDR submission databases, hospital procurement records, and national health technology assessment publications. Conversations with biomedical engineers, GPO contracts managers, clinicians, and regulatory affairs specialists informed demand-side validation. Customs data on electrochemical sensor electrode trade flows and notified body CE marking registries provided supply-side triangulation. Bottom-up patient population modeling and top-down reimbursement expenditure analysis were cross-checked for convergence.
Forecast inputs include device replacement cycle frequency, sensor wear duration extension trajectories, and national reimbursement expansion schedules across the projection horizon. Segmentation dimensions encompass product type, application severity tier, end-user setting, and technology infrastructure layer. CAGRs were derived from fitted growth curves calibrated to historical adoption velocity and payer authorization workflow timelines. Algorithm-driven metabolic prediction displacement rates and MDR implementation pace served as scenario-weighting variables.
Practitioners should monitor German notified body capacity utilization, French pharmacy dispensing authority expansion, and Eastern European reimbursement policy shifts for early signals of trajectory revision. Forecasts embed assumptions regarding EMA MDR enforcement consistency and EU AI Act algorithm classification interpretation stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Canada Diabetes Care Drugs and Devices Market
Diabetes Care
Diabetes Care Devices Market
Diabetes Care
Glycated Albumin Market
Diabetes Care
Japan Oral Anti-Diabetic Drug Market
Diabetes Care
Wearable Glucometers Market
Diabetes Care
Iran Diabetes Care Devices Market
Diabetes Care
Global Needle Free Diabetes Care Market
Diabetes Care
Europe Insulin Infusion Pumps Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
India Oral Anti-Diabetic Drug Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
Asia Pacific Continuous Glucose Monitoring (CGM) Market
Diabetes Care
Artificial Intelligence in Diabetes Management Market
Diabetes Care
Oman Diabetes Care Devices Market
Diabetes Care
Italy Oral Anti-Diabetic Drug Market