
 Bread Maker Market | 2026-2036
Bread Maker Market Size, Share, and Industry Trends Forecast 2026-2036
Bread Maker Market Intelligence
Asian contract manufacturers is broadening output capacity for programmable and induction-heating bread maker chassis to serve Western brand demand. Panasonic Corporation leverages vertical integration in motor and heating element production to control cost structures across mid-tier and premium lines. Zojirushi Corporation anchors its position through microprocessor-controlled fermentation cycles that command loyalty in Japanese and North American households. Breville Group Limited differentiates via convection and steam-injection architectures targeting artisan bread enthusiasts.
A bread maker is an electric countertop appliance that automates dough mixing, kneading, proofing, and baking through timed thermal cycles, typically operating between 450W and 1650W with stainless steel or ceramic-lined baking chambers. Its primary purpose is to produce loaves, cakes, or dough bases without manual intervention, serving residential kitchens and small-scale commercial food preparation. Programmable bread makers and gluten-free bread makers capture expanding margin pools as consumers seek customization and dietary accommodation. Convection heating and induction heating technologies are gaining fastest traction where energy efficiency and crust consistency drive replacement purchases. Home use remains the dominant application, though boutique bakeries and culinary schools represent emerging volume channels for compact and artisan-class machines.
The EU Ecodesign Directive and REACH chemical safety standards constrain material choices and standby power thresholds for bread makers sold in Europe, while the FDA oversees food-contact surface compliance and electrical safety certification for US-bound units. Japan's METI enforces PSE marking and energy conservation labeling that shapes product development priorities for manufacturers targeting that market. Stakeholders must monitor how tightening appliance efficiency regulations and shifting flour-input costs alter the competitive economics between basic and premium machine tiers.
Market Dynamics
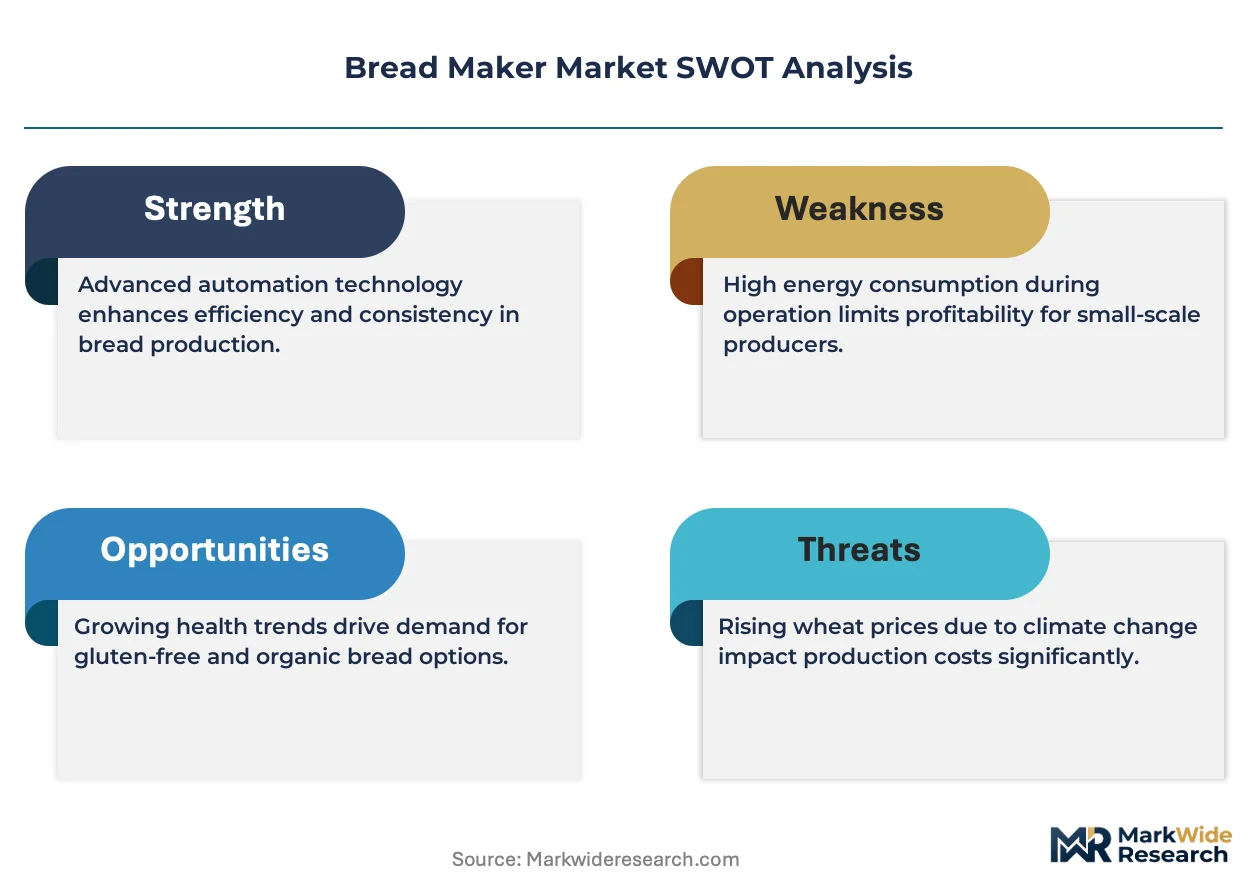
Energy-efficiency mandates under the EU Ecodesign Directive and comparable appliance standards in North America and Asia are forcing manufacturers toward programmable and induction-heating architectures, compressing margins on basic resistive-heating models while rewarding premium-tier innovation.
Growth Catalysts
- EU Ecodesign Directive:Mandates on standby power and heating efficiency push manufacturers to develop induction-based bread makers that command higher price points and faster replacement cycles in European households.
- Sourdough culture:Artisan bread enthusiasts in the United States, Germany, and Japan drive demand for machines with microprocessor-controlled fermentation cycles and customizable crust settings.
- Gluten-free formulation:Specialized programs accommodating alternative flours expand addressable demand among dietary-restricted consumers seeking home baking solutions.
Market Restraints
- Steel and copper input volatility:Baking chamber materials and heating element metals face commodity price swings that compress manufacturing margins unpredictably.
- Asian contract manufacturer concentration:Chassis and electronic control module production clusters in specific manufacturing zones create geographic supply risk for Western brands.
- Countertop appliance substitution:Multi-function devices combining bread making with pressure cooking or air frying divert consumer spending from dedicated units.
Strategic Opportunities
- Boutique bakery channel:Compact artisan-class machines for small-scale commercial food preparation remain underpenetrated relative to residential saturation in developed markets.
- Culinary education institutions:Technical schools and hospitality training programs represent emerging volume channels for durable, instruction-grade equipment.
- Steam-injection convergence:Combining convection heating with controlled moisture release enables crust textures previously achievable only in professional ovens, opening premium positioning.
Industry Challenges
- Firmware development talent:Programming sophisticated fermentation algorithms and multi-stage thermal cycles requires embedded systems expertise scarce among traditional appliance engineering teams.
- Cross-regulatory certification timelines:Simultaneous compliance with FDA food-contact standards, EU REACH chemical safety requirements, and Japan METI PSE marking extends product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bread Maker Market |
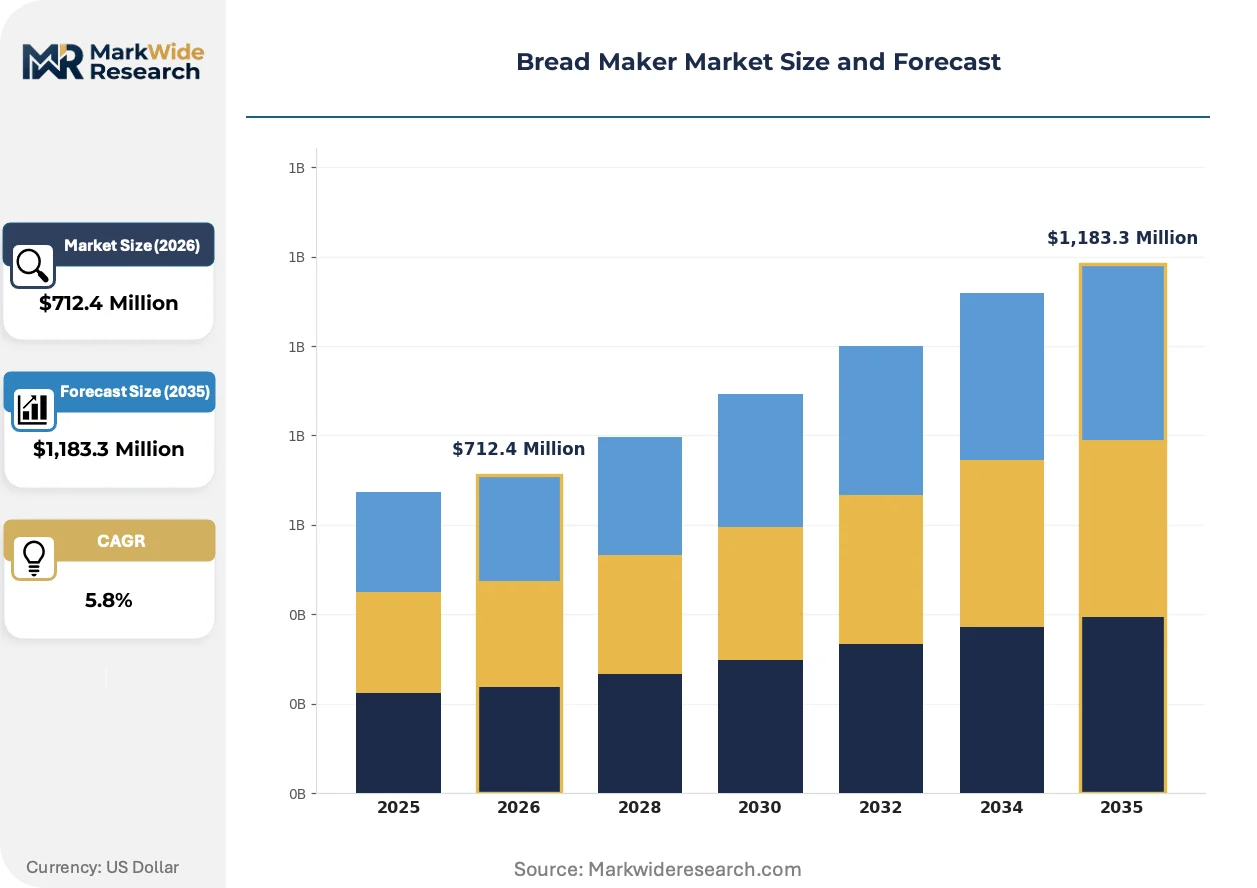
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,183.3 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic Bread Maker, Programmable Bread Maker, Artisan Bread Maker, Gluten-Free Bread Maker, Compact Bread Machine Technology: Convection Heating, Infrared Heating, Induction Heating, Dual Heating, Steam Injection Application: Home Use, Small Bakery, Specialty Food Stores, Culinary Schools, Hospitality Services Customer Type: Residential Users, Catering Companies, Food Service Providers, Culinary Professionals, Boutique Bakeries |
| Companies Covered | Panasonic Corporation, Breville Group Limited, Koninklijke Philips N.V., Zojirushi Corporation, Siroca Inc., Cuisinart Corporation, Newell Brands Inc., Spectrum Brands Holdings Inc., Stanley Black & Decker Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bread Maker Market Strategic Shifts & Innovations
Programmable control architectures and induction heating systems are rewriting competitive boundaries in bread maker design, while regulatory pressure on energy consumption and shifting buyer expectations around customization accelerate replacement cycles.
Induction heating technology is rewriting the thermal performance standards against which premium bread makers are judged. This approach delivers precise temperature control across fermentation and baking phases while reducing energy consumption versus traditional resistive elements. Home baking enthusiasts in Japan and Germany are adopting induction-equipped models at accelerating rates, compressing demand for basic programmable units and forcing mid-tier manufacturers to retool heating element supply chains.
REACH chemical safety standards constrain material choices for baking chambers and non-stick coatings sold into European markets. Manufacturers must reformulate surface treatments and validate alternative ceramic linings to maintain market access. Premium product lines targeting German and French households bear the highest compliance burden, with certification timelines now extending eighteen to twenty-four months for new surface material introductions.
Buyer preference is gravitating toward unbundled after-sales support and digital recipe ecosystems rather than bundled warranty packages. Direct-to-consumer channels and brand-owned subscription services for recipe libraries and firmware updates are displacing traditional retail warranty bundles. This pattern is most visible in United States metropolitan markets where countertop appliance buyers demonstrate higher willingness to engage ongoing digital service relationships.
Bread Maker Market Segmentation
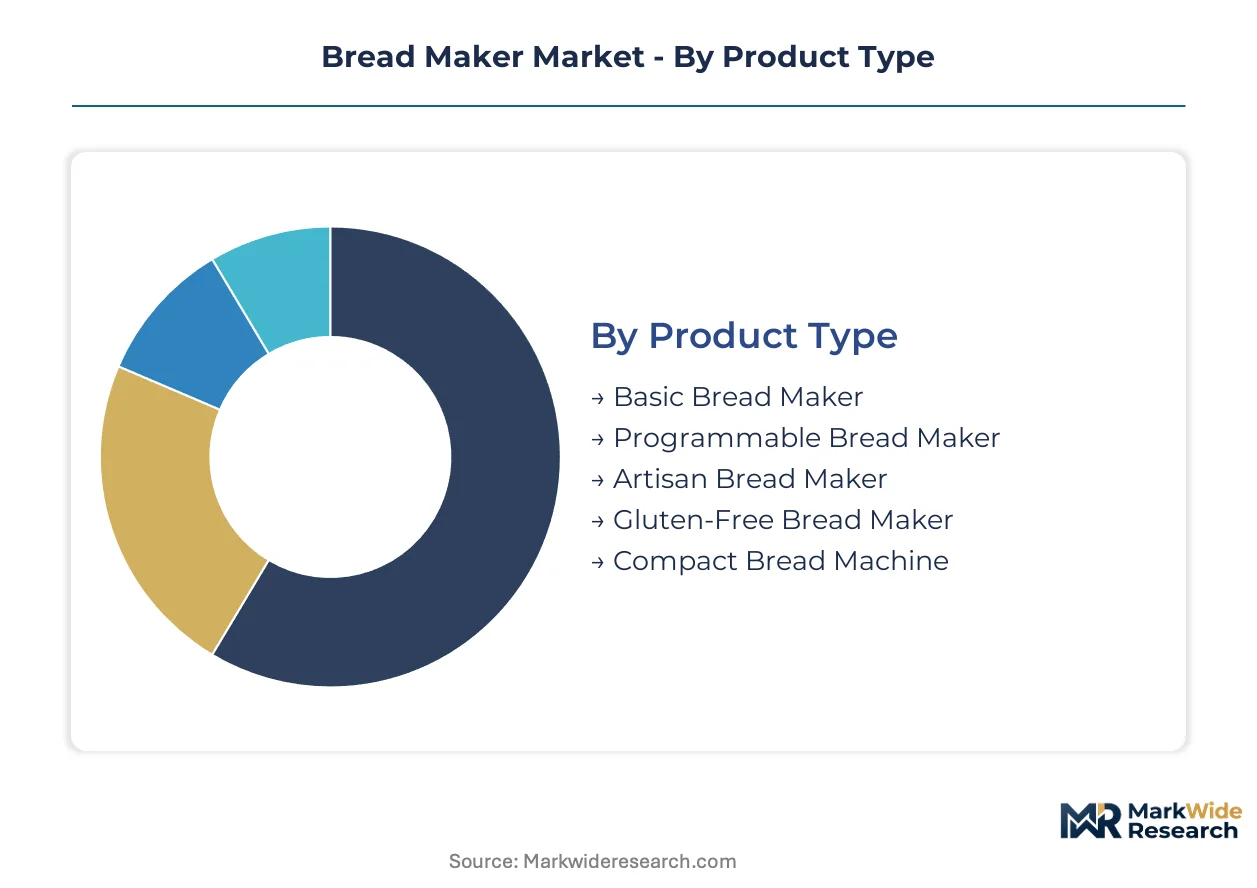
Bread maker segmentation reveals how technical sophistication and use-case specificity fragment demand across price tiers. Manufacturers align R&D budgets and distribution channels to these divisions, as each segment commands distinct margin profiles and replacement cycles.
Product Type:
Price sensitivity and feature expectations separate buyers across this dimension.
- Programmable Bread Maker:Microprocessor-controlled units enable customizable fermentation cycles and crust settings. Demand concentrates in German and Japanese households where sourdough culture drives premium appliance investment.
- Gluten-Free Bread Maker:Dedicated programs accommodate alternative flour formulations with adjusted kneading and proofing parameters. United States residential users with celiac disease or dietary preferences represent the core demand pool, with FDA food-contact compliance adding certification overhead.
- Basic Bread Maker:Fixed-cycle resistive-heating units serve cost-conscious first-time buyers.
- Artisan Bread Maker:Extended fermentation modes and larger loaf capacities target enthusiasts.
- Compact Bread Machine:Reduced footprint designs suit urban kitchens with limited counter space.
Programmable bread makers lead volumes today; gluten-free bread makers are gaining share fastest.
Technology:
Energy efficiency mandates and thermal precision requirements differentiate adoption patterns.
- Induction Heating:Electromagnetic coil systems deliver rapid, uniform temperature control with reduced standby consumption. Japanese and German buyers under METI and EU Ecodesign Directive pressure are adopting these systems at accelerating rates.
- Steam Injection:Controlled moisture release during baking creates professional-grade crust textures. Artisan bread enthusiasts in France and the United States drive niche demand for this capability.
- Convection Heating:Circulating hot air improves browning consistency across the loaf surface.
- Infrared Heating:Radiant heat elements reduce preheat times in compact chassis designs.
- Dual Heating:Combined bottom-element and top-radiant configurations balance crust and crumb development.
Convection heating dominates installed base; induction heating is climbing the fastest.
Application:
Volume scale and equipment durability requirements separate end-use categories.
- Home Use:Residential countertop operation with 450W-1650W power draws and consumer-grade duty cycles. United States, German, and Japanese households constitute the primary demand concentration.
- Culinary Schools:Instruction-grade equipment with reinforced chassis and demonstration-friendly interfaces. Technical training programs in France and Japan represent emerging procurement channels.
- Small Bakery:Light commercial duty cycles for boutique operations with limited production volumes.
- Specialty Food Stores:In-store demonstration units driving retail attachment sales.
- Hospitality Services:Hotel breakfast buffet preparation with rapid-cycle requirements.
Home use anchors current volumes; culinary schools show the steepest expansion trajectory.
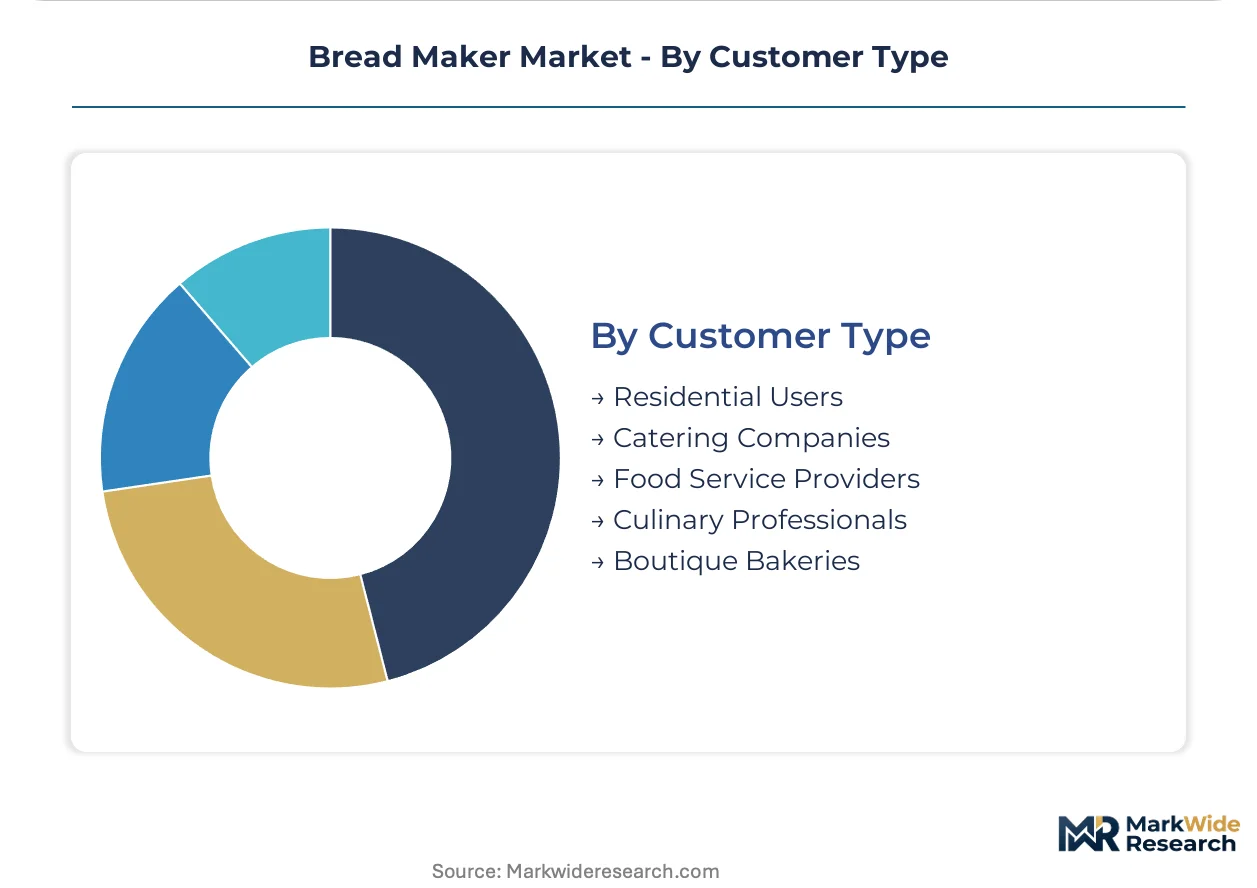
Customer Type:
Purchasing authority and technical expertise shape procurement behavior.
- Residential Users:Individual consumers selecting units through retail or direct-to-consumer channels. German and Japanese buyers demonstrate the highest willingness to invest in premium programmable and induction-heating models.
- Boutique Bakeries:Small-scale commercial operators requiring compact artisan-class machines for limited-batch production. United States urban markets show particular concentration.
- Catering Companies:Event-service providers with portable equipment needs.
- Food Service Providers:Institutional feeding operations with standardized output requirements.
- Culinary Professionals:Chef-operators seeking equipment for recipe development or teaching.
Residential users command the largest share; boutique bakeries are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between jurisdictions with divergent energy-efficiency mandates is reshaping where bread maker chassis and control modules are sourced. Manufacturers are relocating final assembly to zones with lighter standby-power compliance burdens while maintaining premium product development in markets with stringent Ecodesign or METI requirements.
United States
Artisan bread culture and sourdough enthusiasm drive premium appliance demand in coastal metropolitan markets. FDA food-contact surface compliance and electrical safety certification through NRTL programs shape product development timelines. Seattle and Portland clusters concentrate specialty kitchenware retail and direct-to-consumer brand headquarters.
Germany
EU Ecodesign Directive mandates on standby power and heating efficiency accelerate induction-heating model adoption among environmentally conscious households. REACH chemical safety standards constrain non-stick coating formulations and extend certification cycles. Stuttgart and Munich industrial zones host precision motor and heating element suppliers serving domestic manufacturers.
Japan
METI energy conservation labeling and PSE marking requirements prioritize microprocessor-controlled fermentation cycles and precise thermal management. Kansai and Chubu manufacturing corridors concentrate vertical integration in motor production and ceramic component fabrication. Osaka-based engineering teams specialize in compact chassis design for urban kitchens.
China
Contract manufacturing capacity for programmable bread maker chassis and electronic control modules clusters in Guangdong and Zhejiang provinces. GB standards for household appliance safety and emerging dual carbon goals are gradually tightening efficiency requirements for export-bound production. Shenzhen electronics corridors supply microcontrollers and induction coil assemblies to Western brands.
United Kingdom
Post-Brexit regulatory divergence from EU Ecodesign creates compliance complexity for manufacturers serving both markets. London and Southeast England concentrate boutique bakery equipment demand and culinary school procurement. Midlands manufacturing zones retain limited domestic assembly for premium artisan-class machines.
Bread Maker Market Key Industry Players
Japanese producers anchor the premium tier through vertical integration in motor and heating element production; Chinese contract manufacturers hold scale-driven supply positions for Western brand demand. The vendor base splits between consolidated appliance conglomerates with multi-category portfolios and specialized kitchen equipment firms with narrow product focus. Two strategic archetypes dominate: technology-integrated specialists leveraging microprocessor-controlled fermentation algorithms, and manufacturing-scale operators optimizing chassis cost structures. Competitive moves center on backward integration into heating component supply and geographic expansion through direct-to-consumer channels.
Among Japanese specialists, Panasonic Corporation and Zojirushi Corporation exemplify the technology-integrated archetype through captive production of precision thermal components. Breville Group Limited occupies a position within the premium-tier design-focused segment, representing Australian-origin engineering differentiation. These three companies illustrate how geographic concentration of engineering talent and component supply shapes competitive positioning across price tiers.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Breville Group Limited |
| Koninklijke Philips N.V. |
| Zojirushi Corporation |
| Siroca Inc. |
| Cuisinart Corporation |
| Newell Brands Inc. |
| Spectrum Brands Holdings Inc. |
| Stanley Black & Decker Inc. |
| Others |
Cost & Logistics Intelligence
Induction-heating premium tier divergence from basic resistive-heating commodity units manifests in both pricing power concentration and supply chain configuration. Certification timelines for EU Ecodesign compliance and Japan METI energy labeling create cost barriers that favor manufacturers with captive heating element production, while Asian contract manufacturers serve price-sensitive Western brands through standardized chassis platforms.
Pricing Analysis
Distributor margin layers compress as direct-to-consumer channels expand in United States metropolitan markets. Three-tier pricing structure across premium, standard, and economy levels separates induction-equipped models with microprocessor fermentation algorithms from fixed-cycle units. Price differentiation hinges on certification grade and after-sales digital service bundling. Pricing pressure stems from multi-function countertop appliance substitution diverting consumer spending. Residential users in Germany and Japan demonstrate lowest price sensitivity; first-time buyers in cost-conscious segments exhibit highest elasticity.
Supply Chain Analysis
Container freight volatility from Guangdong and Zhejiang provinces to Western distribution hubs amplifies landed cost unpredictability for programmable chassis assemblies. Manufacturing gravity centers on China for electronic control modules, Japan for precision motors and ceramic components, and Germany for heating element engineering. Raw material dependencies span copper for induction coils, stainless steel for baking chambers, and microcontrollers for fermentation algorithms. Single-source vulnerability concentrates in Asian contract manufacturer zones for Western brand supply. Distribution runs through kitchenware retail chains, direct-to-consumer platforms, and culinary school procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bread maker market functions as a stable compounder anchored by regulatory-driven replacement cycles and enduring home baking culture penetration. Energy-efficiency mandates across multiple jurisdictions ensure sustained premium-tier demand regardless of macroeconomic fluctuation.
For Market Incumbents: Anticipate firmware development talent scarcity by embedding embedded systems expertise within appliance engineering teams before competitive poaching intensifies. Defend against multi-function appliance substitution by deepening digital recipe ecosystem lock-in through subscription services. Prioritize backward integration into induction coil supply to capture margin compression resilience as commodity input volatility persists.
For New Entrants and Emerging Players: Boutique bakery operators in United States urban markets represent the most penetrable white-space target given underdeveloped compact artisan-class machine penetration relative to residential saturation. Culinary education institutions in France and Japan offer secondary volume channels with durable procurement cycles and demonstration-driven brand amplification. Pursue go-to-market positioning through technical school partnerships and hospitality training program accreditation rather than retail channel competition.
For Investors and Strategic Acquirers: Consolidation pressure builds where engineering talent scarcity meets fragmented contract manufacturing capacity across mid-tier Western brands. The five-to-ten year viability window favors technology-integrated specialists with microprocessor-controlled fermentation capabilities over manufacturing-scale operators dependent on commodity chassis economics. Acquisition target archetypes include regional kitchen equipment firms with established culinary school relationships and dormant brand equity. Monitor induction-heating adoption rates in German and Japanese replacement cycles as the primary inflection signal for premium-tier margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Induction Heating Technology Migration | EU Ecodesign Directive compliance unlocks premium positioning in environmentally conscious German households. |
| Digital Recipe Ecosystem Launch | Subscription-based firmware updates and recipe libraries create recurring revenue attachment in United States metropolitan markets. |
| Culinary School Channel Partnership | Technical training program accreditation builds durable procurement relationships and demonstration-driven consumer influence. |
| Backward Integration into Coil Supply | Captive induction component production insulates margin structures from copper price volatility and Asian supplier concentration. |
| Steam-Injection Capability Introduction | Controlled moisture release technology enables professional-grade crust textures previously limited to commercial ovens. |
Research Approach
Multiple input streams — primary interviews with appliance engineering directors and brand procurement managers, secondary validation through customs records and kitchenware retail audit data, and technical documentation from EU Ecodesign and Japan METI regulatory filings — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned embedded systems firmware developers, heating element component suppliers, culinary school equipment procurement officers, and direct-to-consumer brand operations executives. Secondary sources included SEC filings from listed appliance manufacturers, trade flow databases for chassis and control module imports, and certification registry data from European and Japanese regulatory bodies.
Data-stream reconciliation across the projection horizon applied analytical frameworks segmenting by product type, heating technology, application channel, and customer archetype. CAGRs were derived from modeled replacement cycle dynamics, regulatory compliance phase-in schedules, and sourdough culture penetration indices. Forecast inputs incorporated energy-efficiency mandate adoption curves, flour-input cost sensitivity parameters, and multi-function appliance substitution elasticity estimates.
Underlying measurement precision varies by segment; programmable and induction-heating categories carry tighter precision than basic resistive-heating commodity tiers given more concentrated manufacturer disclosure and certification documentation. Forecasts reflect assumptions about regulatory enforcement consistency, commodity input stability, and consumer preference durability that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Continuous Fryer Machine Market
Food Processing Equipment
Automatic Canning Machine Market
Food Processing Equipment
Nugget Ice Machines Market
Food Processing Equipment
Reflow Oven Market
Food Processing Equipment
Clean in Place Market
Food Processing Equipment
Individual Quick Freezing Market
Food Processing Equipment
Food Waste Shredder Market
Food Processing Equipment
North America Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Cookie Dropper Machine Market
Food Processing Equipment
Destemmer Market
Food Processing Equipment
Electric Chicken Scalder Market
Food Processing Equipment
Countertop Food Blenders Market
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
Food Processing Equipment Market
Food Processing Equipment
Food Automation Market
Food Processing Equipment
Spray Dryer Market