
 Electric Chicken Scalder Market | 2026-2036
Electric Chicken Scalder Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Chicken Scalder Market Foresight
Modular system bundling is hardening as the dominant procurement pattern, with buyers favoring integrated scalding-plucking-chilling packages over standalone units. Mann Lake leverages its distribution network across North American farm supply channels to sustain equipment visibility. FarmTek anchors its position through catalog-based sales to small and mid-sized operations. Zhucheng Xincheng Mingshun Machinery Co., Ltd competes on manufacturing scale for export markets, particularly automated continuous systems.
An electric chicken scalder is a heated water immersion or spray apparatus designed to loosen feather follicles prior to mechanical plucking, typically operating at temperatures between 50°C and 60°C with precise dwell-time controls to prevent skin damage while ensuring complete feather release. Batch scalder configurations retain strongholds in farm-scale and specialty processing settings where throughput flexibility outweighs speed requirements. Continuous scalder installations command premium positioning in high-volume poultry processing plants, where line integration and labor reduction justify capital intensity. Immersion scalder technology dominates supermarket and retail outlet captive processing due to simpler maintenance profiles and lower operator training thresholds.
USDA Food Safety and Inspection Service standards shape equipment design through mandated cleanability and temperature documentation requirements, while FDA HACCP protocols drive sensor integration and data-logging features. The EU Machinery Directive and CE marking impose additional safety and electromagnetic compatibility obligations for equipment sold into European processing facilities. Stakeholders must monitor evolving antimicrobial resistance regulations that could mandate scalding temperature adjustments, potentially accelerating equipment replacement cycles among existing installed bases.
Market Dynamics
USDA inspection mandates and HACCP documentation requirements are compressing equipment replacement cycles, forcing processors to retire legacy thermal systems before end-of-life. Batch-to-continuous line conversions dominate capital planning discussions among mid-sized integrators seeking labor efficiency gains.
Growth Catalysts
- Food safety mandates:USDA FSIS temperature documentation rules require sensor-integrated scalders with automated data logging, pulling replacement demand from plants operating pre-2015 equipment.
- Labor cost pressures:Poultry processing plants in the United States are automating scalding-plucking lines to reduce headcount in tight labor markets.
- Antimicrobial resistance protocols:Emerging regulatory frameworks may mandate elevated scalding temperatures, accelerating equipment turnover among existing installed bases.
Market Restraints
- Stainless steel input volatility:304-grade stainless steel price swings directly impact equipment manufacturing costs, squeezing margins for fabricators without long-term supply contracts.
- Technical limitation in retrofit compatibility:Legacy batch scalder footprints often cannot accommodate continuous system footprints without building modifications, freezing upgrade decisions.
- Substitution threat from air-scalding:Steam-based feather loosening systems are gaining trial deployments in European facilities seeking water-use reduction.
Strategic Opportunities
- Underpenetrated processing cooperatives:Farm-scale and specialty poultry operations in the United States remain underserved by automated scalding solutions optimized for sub-500 bird-per-hour throughput.
- Technology convergence:Integration of IoT temperature sensors with cloud-based HACCP documentation platforms creates premium positioning for equipment vendors.
- Distribution innovation:Direct-to-processor sales models are bypassing traditional farm supply catalog intermediaries, capturing margin and installation service revenue.
Industry Challenges
- Capex intensity for line integration:Continuous scalder installations require coordinated conveyor, plucker, and chiller investments, stretching processor balance sheets.
- Certification timeline compression:USDA equipment approval processes for modified thermal systems are extending lead times, delaying revenue recognition for manufacturers.
- Integration complexity with legacy chillers:New scalders must interface with existing immersion or air-chill infrastructure, requiring custom engineering that erodes standardization benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Chicken Scalder Market |
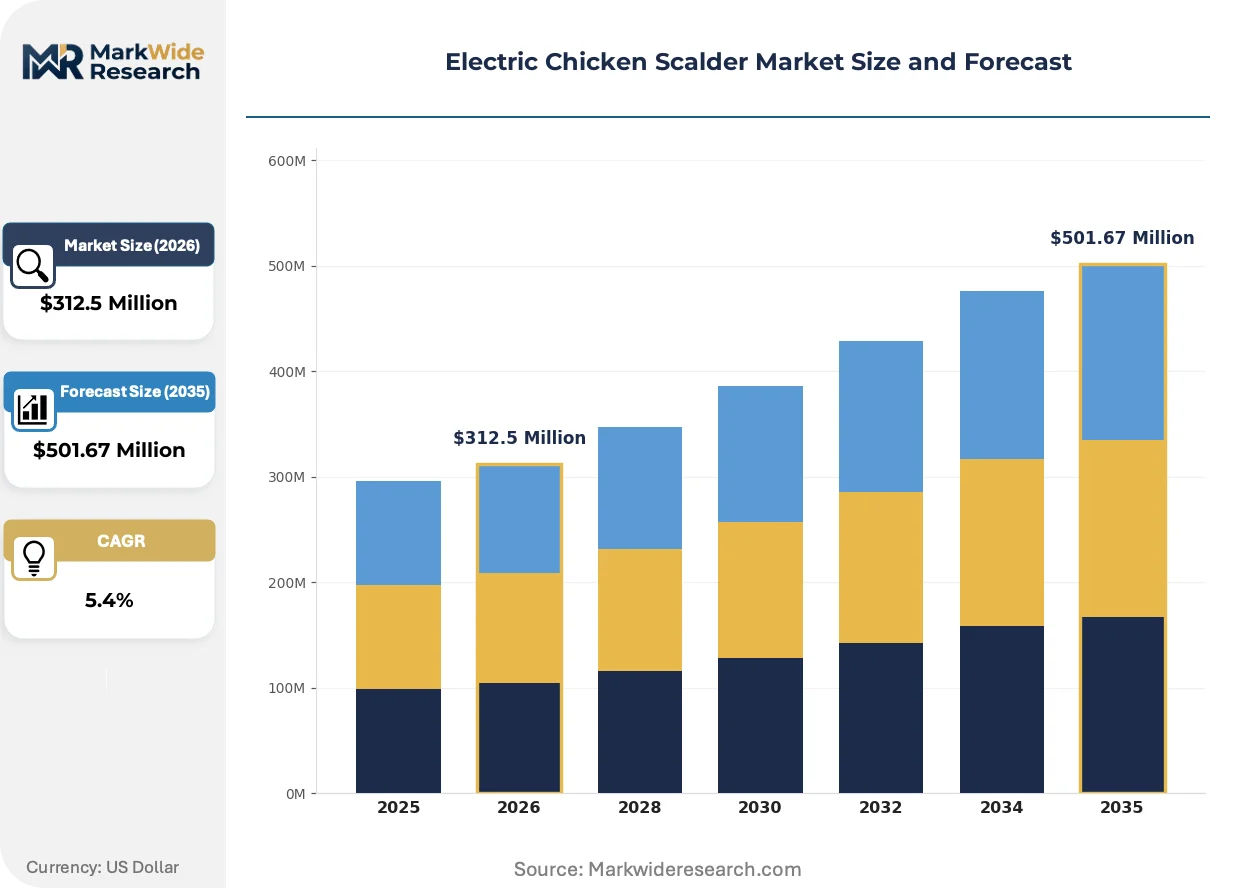
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Scalder, Continuous Scalder, Immersion Scalder, Spray Scalder End User: Poultry Processing Plants, Farms, Supermarkets, Retail Outlets Installation: Standalone, Integrated System, Mobile Unit, Fixed Installation Power Rating: Low Power, Medium Power, High Power, Ultra-High Power |
| Companies Covered | Mann Lake, FarmTek, Strombergs, Superior Poultry, Roots & Harvest, McMurray Hatchery, Farm Innovators, The Bird Nerd, Zhucheng Xincheng Mingshun Machinery Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Chicken Scalder Market Shifts & Advancements
Equipment intelligence and thermal precision are displacing mechanical reliability as the primary purchase criteria, reshaping vendor R&D priorities toward sensor integration and data architecture.
Precision temperature control systems with ±0.5°C variance tolerance are consolidating competitive positioning among premium equipment tiers. Large-scale integrators in the United States are specifying these systems for new-build plants, compressing demand for conventional thermostat-controlled units. The technology is consolidating vendor differentiation around software capabilities rather than tank fabrication quality.
EU Machinery Directive electromagnetic compatibility obligations are extending design validation timelines for equipment exported to European processing facilities. Manufacturers must now certify control panel shielding and motor drive isolation before CE marking, adding engineering overhead. Batch scalder configurations face particular scrutiny due to higher operator proximity to unguarded heating elements.
Integrated equipment procurement is displacing standalone scalder purchases across mid-sized processing operations. Buyers are bundling scalding, plucking, and chilling systems from single vendors to reduce interface risk and streamline HACCP documentation. This pattern concentrates in the United States, where integrators favor turnkey line responsibility over component sourcing.
Electric Chicken Scalder Market Segmentation
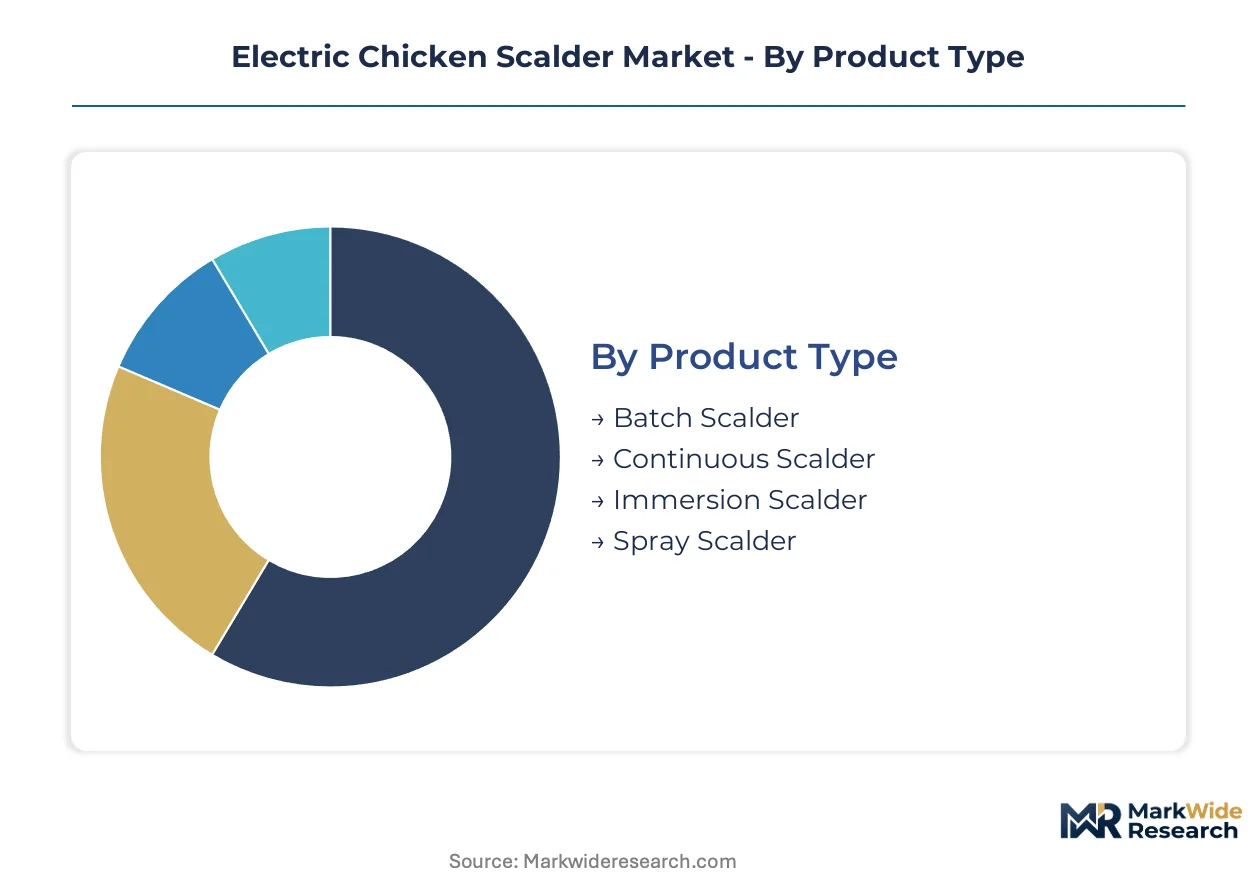
Equipment specification varies sharply across processing scales, from farm-scale batch units to industrial continuous lines. Procurement patterns diverge based on throughput requirements, regulatory documentation obligations, and integration complexity with existing plucking and chilling infrastructure.
Product Type:
Capital intensity escalates dramatically from batch configurations through continuous automated lines, with stainless steel tank fabrication and precision heating systems driving upfront equipment costs.
- Batch Scalder:Heated immersion tanks process discrete loads of 50-200 birds per cycle, with manual or semi-automated loading systems and thermostat-based temperature control. Demand concentrates among farm-scale and specialty poultry operations in the United States where throughput flexibility outweighs speed requirements, though labor intensity limits adoption among mid-sized integrators.
- Continuous Scalder:Conveyor-fed immersion or spray systems maintain constant throughput of 500-3,000+ birds per hour with automated dwell-time controls and integrated temperature logging. Large-scale poultry processing plants in the United States specify these systems for new-build facilities, where USDA HACCP documentation mandates and labor reduction targets justify capital expenditure.
- Immersion Scalder:Submersion-based feather loosening using heated water baths with agitation systems to ensure uniform heat distribution and complete follicle penetration. Supermarket captive processing operations favor this technology for simpler maintenance profiles and lower operator training thresholds.
- Spray Scalder:High-velocity heated water jets target feather follicles without full submersion, reducing water consumption and wastewater treatment loads. European processing facilities trial these systems amid tightening water-use regulations.
Most installed capacity flows through Continuous Scalder configurations. Expansion is steepest in Batch Scalder segments serving underserved farm-scale operations.
End User:
Customer sophistication and procurement authority shape equipment specification, with large integrators driving standardization while fragmented farm-scale buyers prioritize flexibility over automation.
- Poultry Processing Plants:Industrial-scale facilities processing 100,000+ birds daily with fully automated scalding-plucking-chilling lines and integrated HACCP data systems. These operations in the United States dominate premium equipment demand, specifying precision temperature controls and cloud-based documentation platforms.
- Farms:Small and mid-sized poultry operations with on-farm processing permits, typically handling 500-5,000 birds weekly using manual or semi-automated batch equipment. This segment remains underserved by equipment optimized for sub-500 bird-per-hour throughput, creating white space for specialized vendors.
- Supermarkets:Captive processing facilities serving retail chains with private-label poultry programs, emphasizing equipment cleanability and rapid changeover capabilities.
- Retail Outlets:Independent butcher shops and specialty food stores with limited processing volumes, prioritizing compact footprints and plug-and-play installation over throughput optimization.
Equipment standardization is tightest among Poultry Processing Plants. Technology adoption spreads fastest through Supermarket captive operations seeking differentiation.
Installation:
System architecture determines integration complexity and vendor service revenue potential, with bundled solutions capturing margin from component sourcing.
- Standalone:Self-contained scalding units requiring independent controls, pumps, and temperature monitoring systems, suited to operations with existing line infrastructure or limited capital budgets.
- Integrated System:Bundled scalding-plucking-chilling packages from single vendors with unified controls and consolidated HACCP documentation, reducing interface risk for mid-sized integrators in the United States.
- Mobile Unit:Trailer-mounted or skid-based configurations enabling on-farm or seasonal processing, popular among farm cooperatives and custom exempt operations.
- Fixed Installation:Permanent concrete-anchored systems with hard-piped utilities and dedicated wastewater connections, standard for large-scale processing plants.
Procurement is shifting toward Integrated System configurations. Mobile Unit demand is climbing fastest among farm cooperative processing networks.
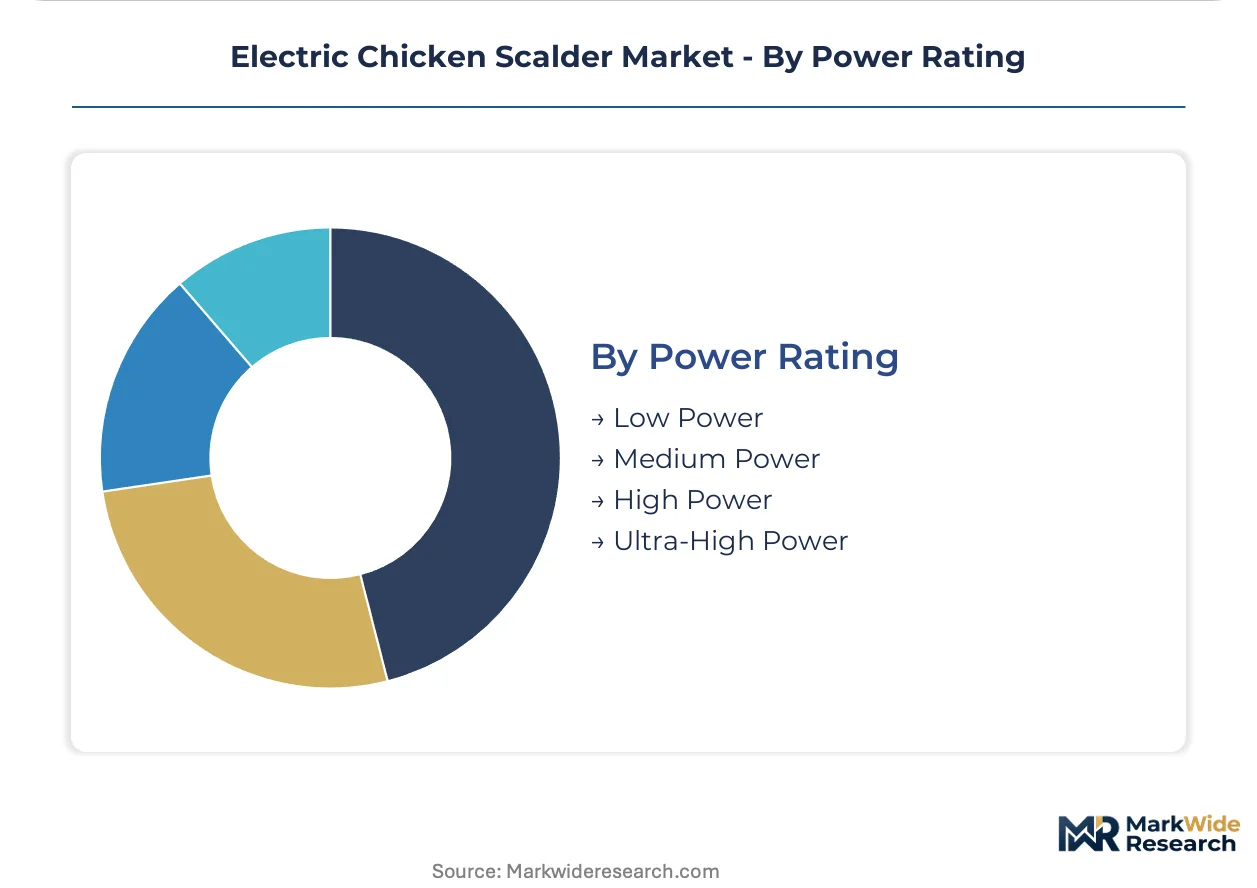
Power Rating:
Electrical infrastructure requirements and operating cost profiles stratify equipment tiers, with high-capacity systems demanding three-phase industrial connections.
- Low Power:Single-phase units under 10kW suited to farm-scale and retail applications with limited electrical service, typically heating 100-300 liter tanks.
- Medium Power:10-30kW systems serving mid-sized batch operations and small continuous lines, balancing throughput and electrical demand.
- High Power:30-75kW industrial configurations for continuous scalding lines with rapid heat recovery and precise temperature maintenance under load.
- Ultra-High Power:75kW+ systems for the largest processing plants with multiple heating zones and redundant temperature control circuits ensuring zero downtime.
High Power equipment carries the heaviest installed base. Ultra-High Power systems are gaining share fastest among new-build facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poultry processing automation originated in the United States during the mid-20th century, establishing the technical foundations that now propagate through export markets and foreign direct investment. Equipment specifications from American integrators now shape procurement patterns across multiple continents.
United States
Large-scale poultry integrators dominate processing capacity, driving demand for continuous scalding lines with integrated HACCP documentation. USDA Food Safety and Inspection Service mandates compress equipment replacement cycles, forcing upgrades to sensor-integrated thermal systems. Georgia, Arkansas, and Alabama host the densest concentrations of automated processing facilities.
China
Domestic poultry consumption expansion fuels processing plant construction, particularly in coastal provinces seeking export certification. MIIT industrial upgrading programs subsidize automation equipment procurement for mid-sized processors. Shandong Province anchors manufacturing clusters where local equipment fabricators compete on cost-adjusted throughput specifications.
Germany
EU Machinery Directive compliance requirements extend design validation timelines for scalding equipment, favoring established vendors with certification expertise. REACH chemical safety protocols influence stainless steel sourcing and surface treatment specifications. North Rhine-Westphalia processes significant poultry volumes through facilities emphasizing water-use efficiency and wastewater minimization.
Brazil
Export-oriented poultry processors invest in automated scalding lines to meet international sanitary standards for European and Middle Eastern markets. ANVISA food safety regulations align equipment specifications with destination-country requirements. Paraná and Santa Catarina states concentrate processing capacity for global chicken exports.
Netherlands
Intensive livestock processing traditions support specialized equipment engineering expertise, with Dutch firms supplying precision thermal control components internationally. EU Green Deal sustainability targets accelerate water-use reduction technologies including spray scalder trials. The Randstad region hosts engineering consultancies integrating scalding systems into complete processing lines.
Electric Chicken Scalder Market Competitive Landscape
Premium-margin players sit above commodity-margin players across precision thermal control and HACCP documentation capabilities. The vendor base stratifies between integrated line providers and standalone equipment fabricators, with consolidation pressure intensifying among mid-scale specialists. Three archetypes dominate: catalog distributors serving farm-scale buyers, industrial-scale manufacturers of continuous systems, and precision engineering specialists for temperature control subsystems. Competitive dynamics center on strategic partnerships for line integration and geographic expansion through distribution licensing.
Among North American catalog distributors, Mann Lake leverages farm supply channel relationships, while FarmTek anchors catalog-based positioning for small and mid-sized operations. Zhucheng Xincheng Mingshun Machinery Co., Ltd represents the manufacturing-scale archetype competing on automated continuous system output. These three occupy distinct tier positions without direct overlap, reducing price competition while segmenting procurement authority by operation scale.
| Leading Market Players |
|---|
| Mann Lake |
| FarmTek |
| Strombergs |
| Superior Poultry |
| Roots & Harvest |
| McMurray Hatchery |
| Farm Innovators |
| The Bird Nerd |
| Zhucheng Xincheng Mingshun Machinery Co., Ltd |
| Others |
Supply & Pricing Matrix
304-grade stainless steel price volatility cascades through equipment fabrication costs into three distinct pricing tiers, with batch scalder manufacturers absorbing margin compression while continuous line vendors pass input spikes through to large integrators locked in long-term procurement cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates precision temperature control systems with cloud-based HACCP documentation from thermostat-controlled batch units and entry-level farm-scale equipment. Price differentiation hinges on certification grade—USDA-approved sensor-integrated systems command substantial premiums over CE-marked export configurations—and volume scale, with integrators negotiating fleet discounts unavailable to fragmented farm buyers. Cost compression in the economy tier is intensifying because catalog distributors face stainless steel surcharge pass-throughs from fabricators without hedging contracts. Farm-scale operations exhibit highest price sensitivity, while poultry processing plants prioritize total cost of ownership over upfront equipment expenditure.
Supply Chain Analysis
Container freight rate fluctuations from Chinese manufacturing hubs to North American distribution centers directly impact landed costs for automated continuous systems, compressing margins for vendors without regional assembly footprints. Equipment fabrication concentrates in China, the United States, and Germany, with Shandong Province anchoring stainless steel tank production and Georgia hosting precision control panel assembly. Supply chains draw from 304-grade stainless steel coils, industrial heating elements, and PLC control modules. Single-source vulnerability in semiconductor-dependent temperature sensors creates procurement risk for sensor-integrated scalder lines. Distribution runs through farm supply catalog intermediaries for batch equipment and direct-to-processor sales teams for continuous line installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electric Chicken Scalder Market functions as a geographic-arbitrage play: EU Machinery Directive compliance costs in Germany exceed USDA equipment approval expenses in the United States by a factor that rewards vendors with dual-certification capabilities.
For Market Incumbents: Anchor market position through backward integration into stainless steel fabrication and captive supply of precision heating elements, insulating margin structures from commodity volatility. Defend against air-scalding substitution threats by accelerating IoT sensor integration that steam-based systems cannot replicate. Prioritize certification investment in dual USDA-CE marking to capture cross-Atlantic procurement consolidation among multinational integrators. For New Entrants and Emerging Players: USDA FSIS temperature documentation mandates in the United States open a window for specialized vendors targeting farm-scale and specialty poultry operations with sub-500 bird-per-hour automated batch solutions. The most penetrable segment sits among processing cooperatives in the Southeast United States lacking capital for continuous line conversions. Pursue direct-to-processor sales models that bypass catalog intermediaries, capturing installation service revenue and recurring HACCP software subscriptions. For Investors and Strategic Acquirers: Asymmetric upside sits with precision temperature control subsystem specialists possessing FDA-validated sensor architectures applicable to adjacent food processing equipment categories. Long-term viability favors vendors with software-defined product roadmaps over mechanical fabricators dependent on tank construction expertise. Acquisition targets should demonstrate installed base data-logging capabilities that enable recurring revenue streams. Monitor antimicrobial resistance regulatory drafts as the critical inflection signal—mandated temperature adjustments would force replacement cycles across pre-2020 installed bases.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Integration Investment | USDA FSIS data-logging mandates pull replacement demand from pre-2015 thermal systems lacking automated documentation. |
| Backward Integration into Heating Elements | In-house production of precision immersion heaters reduces exposure to 304-grade stainless steel price volatility. |
| Farm-Scale Product Line Expansion | Underserved cooperative processing networks in the Southeast United States lack capital for continuous line conversions. |
| Dual Certification Pathway | CE marking alongside USDA approval captures procurement consolidation among multinational integrators seeking unified line sourcing. |
| Cloud-Based HACCP Platform Development | Integration with IoT temperature sensors creates recurring software revenue streams from large-scale poultry processing plants. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at poultry processing facilities, procurement leads at equipment distributors, regulatory affairs specialists at USDA FSIS, and aftermarket service heads at industrial fabricators with secondary validation against SEC filings from publicly traded protein processors, customs records for stainless steel equipment imports, and equipment certification databases maintained by UL and Intertek. Bottom-up unit economics triangulated against top-down protein production forecasts.
Historical reference periods anchored volume and value projections across the modeling period, with analytical frameworks segmenting by equipment configuration, power rating tier, installation architecture, and end-user scale. CAGRs derived from installed base turnover rates, regulatory replacement cycle compression, and automation penetration curves across farm-scale versus industrial processing operations. Forecast inputs incorporated labor cost indices for poultry processing regions and stainless steel price volatility assumptions.
Revisions become necessary when antimicrobial resistance protocols mandate scalding temperature adjustments, when 304-grade stainless steel price spikes exceed historical volatility bands, or when air-scalding technology achieves commercial scale in water-stressed processing regions. Forecasts reflect documented assumptions about regulatory timelines and commodity input trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Non-Thermal Pasteurization Market
Food Processing Equipment
Fish Feed Pellet Making Machine Market
Food Processing Equipment
Dough Processing System Market
Food Processing Equipment
Glass Processing Equipment Market
Food Processing Equipment
Oven Market
Food Processing Equipment
North America Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Food Processing Machinery Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Ice Cream Equipment Market
Food Processing Equipment
Pet Food Extrusion Market
Food Processing Equipment
Residential Food Waste Disposer Market
Food Processing Equipment
Ribbon Blenders Market
Food Processing Equipment
Global Starch Recovery Systems Market
Food Processing Equipment
North America Food and Beverage Filling and Capping Machines Market
Food Processing Equipment
Industrial Graters Market
Food Processing Equipment
North America Cold Storage Market