
 North America Walk-In Refrigerators and Freezers Market | 2026-2036
North America Walk-In Refrigerators and Freezers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Walk-In Refrigerators and Freezers Market Analytics
Multi-source procurement for insulated panel assemblies is pivoting toward vertically integrated domestic suppliers as lead times and freight costs destabilize cross-border supply chains. Hussmann Corporation leverages its manufacturing scale to control distribution across the Midwest and Southeast. Carrier Global Corporation anchors its position through captive component production and nationwide service infrastructure. Kolpak competes aggressively on custom-engineered solutions for regional food processors.
Walk-in refrigerators and freezers are prefabricated cold storage enclosures built from interlocking insulated panels with urethane or polystyrene cores, designed to maintain temperatures from approximately fifty degrees Fahrenheit down to negative ten degrees Fahrenheit for commercial food preservation. Multi-panel systems dominate new construction for their thermal efficiency and modular assembly, while smart systems integration represents the fastest-growing technology segment as operators seek remote monitoring and energy optimization. Permanent installations command the largest share of current revenue, though portable units are gaining traction among catering operations and temporary foodservice expansion.
The EPA's SNAP program and the AIM Act refrigerant phase-down rules are forcing operators to replace legacy equipment ahead of scheduled end-of-life, directly stimulating replacement demand across the United States. Health Canada and the PMRA enforce parallel cold chain standards that shape cross-border equipment specifications for Canadian operators. Stakeholders must monitor refrigerant transition timelines and energy efficiency tier upgrades to avoid stranded asset risk in their installed base.
Market Dynamics
Refrigerant phase-down mandates under the EPA's AIM Act are compressing replacement cycles and forcing capital redeployment across foodservice and cold chain logistics operators.
Growth Catalysts
- AIM Act refrigerant restrictions:The EPA's hydrofluorocarbon phase-down rules are accelerating equipment turnover as operators retire R-404A and R-507A systems ahead of schedule.
- Ghost kitchen proliferation:Restaurant operators are expanding dedicated cold storage footprints to support off-premise meal production and third-party delivery consolidation.
- Southeast distribution hub construction:New food logistics facilities near Atlanta, Dallas, and Miami are generating concentrated demand for large-format walk-in installations.
Market Restraints
- Steel and aluminum price volatility:Insulated panel manufacturers face margin pressure from fluctuating metal input costs that resist full pass-through to end-users.
- Canadian cross-border friction:Health Canada and PMRA cold chain certification requirements create specification divergence that complicates unified North American product lines.
- Technical labor scarcity:Qualified refrigeration technicians for complex system installation and commissioning remain concentrated in legacy Midwest manufacturing corridors.
Strategic Opportunities
- Mexico cold chain modernization:Underdeveloped perishable logistics infrastructure presents white space for standardized modular walk-in systems in produce distribution.
- Smart monitoring convergence:Integration of IoT sensors with predictive maintenance platforms enables remote temperature compliance and energy optimization for multi-unit operators.
- USDA bio-preferred procurement:Federal foodservice contracts increasingly specify environmental product declarations, favoring suppliers with verified low-global-warming-potential insulation systems.
Industry Challenges
- Refrigerant transition complexity:Technicians must master A2L mildly flammable refrigerant handling protocols while maintaining legacy system service capabilities.
- Panel-to-system integration:Modular enclosure vendors struggle to coordinate thermal performance warranties with third-party refrigeration equipment providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Walk-In Refrigerators and Freezers Market |
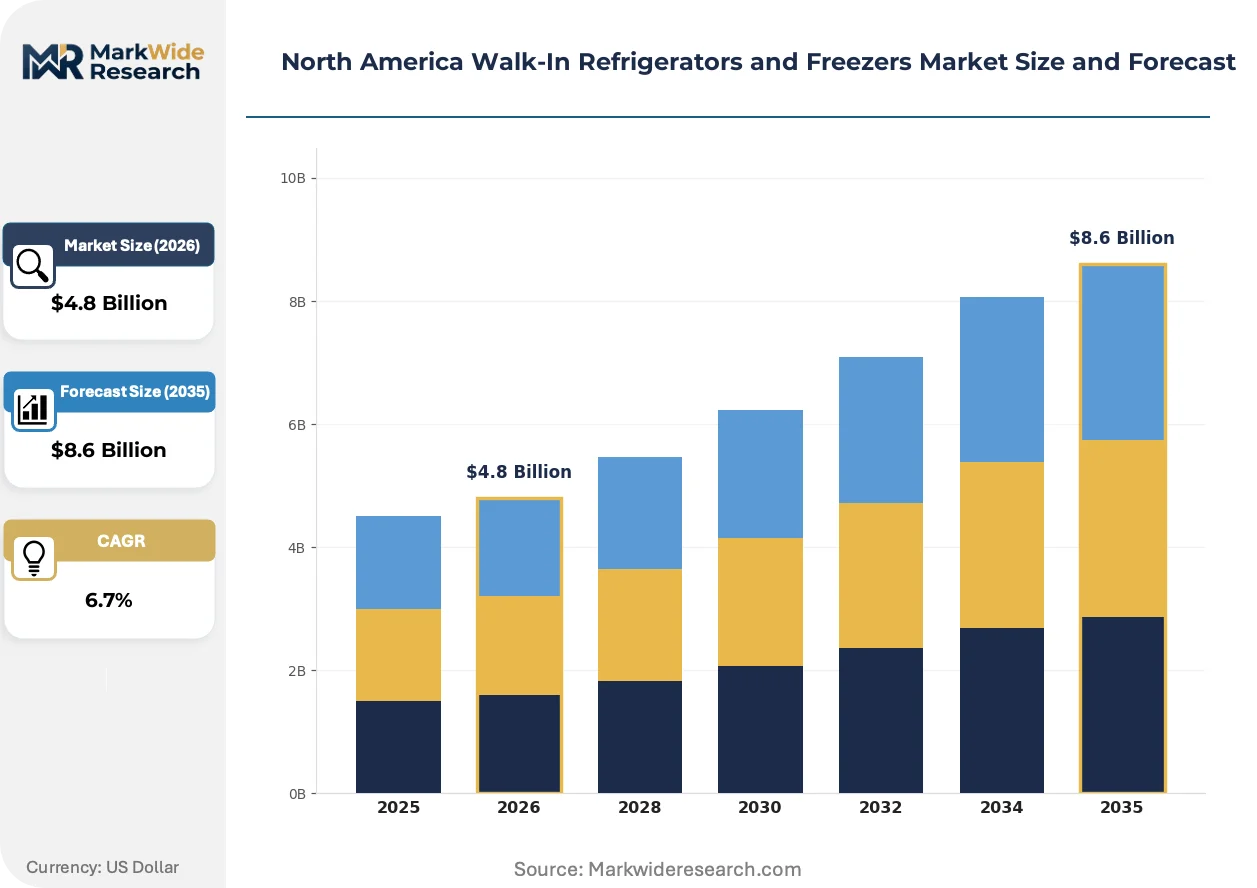
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Panel, Multi-Panel, Reach-In, Custom End User: Restaurants, Supermarkets, Convenience Stores, Food Distributors Installation Type: Indoor, Outdoor, Portable, Permanent Technology: Refrigeration, Freezing, Variable Speed, Smart Systems |
| Companies Covered | Nor-Lake, Kolpak, Hussmann Corporation, Arctic Walk-in Coolers & Walk-in Freezers, American Panel, Carrier Global Corporation, Master-Bilt Products, Imperial Brown, Bally Refrigerated Boxes, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Walk-In Refrigerators and Freezers Market Evolving Landscape
Digitalization of cold chain compliance and modular construction methods are compressing project timelines while raising performance expectations for temperature integrity and energy transparency.
Polyurethane-injected panel systems with high-pressure foaming equipment are overtaking traditional laminated board construction in new commercial foodservice installations. Quick-service chains and institutional cafeterias are specifying these systems for their superior R-value consistency and reduced field assembly time. The technology is overtaking conventional panel methods by enabling faster envelope completion and tighter thermal bridging control.
The EPA's SNAP program and state-level building electrification mandates are reshaping equipment specification criteria across the United States. Operators in California and New York face additional constraints from state refrigerant management regulations that exceed federal minimums. Cold storage developers in these jurisdictions are prioritizing transcritical CO2 and ammonia secondary systems to preempt compliance risk.
Foodservice buyers are consolidating vendor relationships and demanding lifecycle service bundles that combine installation, monitoring, and preventive maintenance. Regional restaurant groups and institutional buyers are displacing transactional equipment purchases with multi-year service agreements. This pattern concentrates most visibly in the southeastern United States where rapid chain expansion favors standardized fleet management approaches.
North America Walk-In Refrigerators and Freezers Market Segmentation
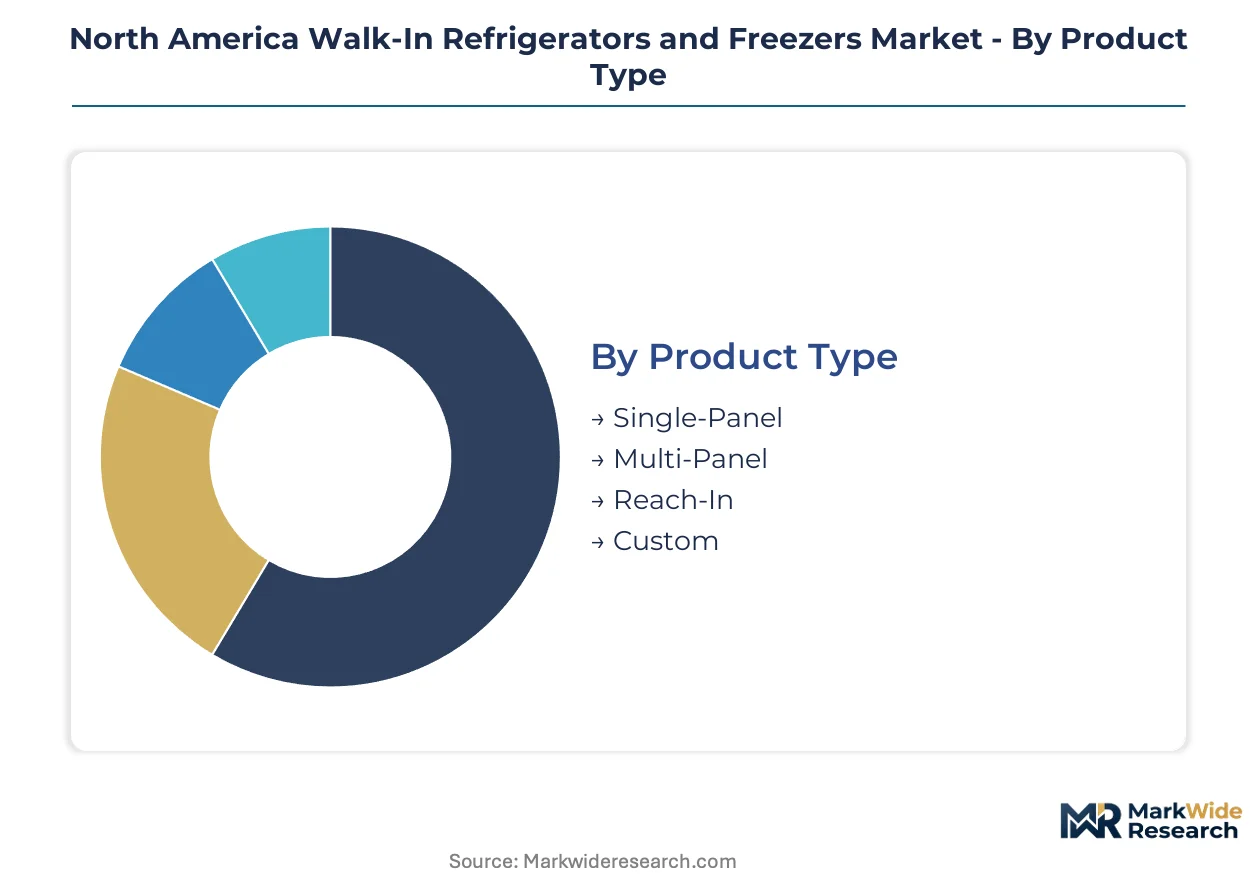
Walk-in refrigeration equipment spans diverse thermal performance requirements and regulatory compliance tiers across the North American foodservice and logistics sectors. Segment boundaries reflect divergent certification burdens from the EPA's SNAP program and Health Canada cold chain standards.
Product Type:
EPA SNAP refrigerant approvals and USDA bio-preferred procurement criteria apply unevenly across panel construction methods, with multi-panel systems facing tighter thermal bridging documentation.
- Multi-Panel:Interlocking insulated panels with urethane or polystyrene cores dominate new commercial construction. Demand concentrates in southeastern distribution hubs near Atlanta and Dallas where rapid envelope completion reduces project timelines. The EPA's AIM Act refrigerant phase-down accelerates replacement of legacy single-panel installations with these thermally efficient modular systems.
- Single-Panel:Monolithic construction suited for smaller footprints and retrofits where structural load limits prevent multi-panel assembly. Regional food processors in legacy Midwest manufacturing corridors specify these for custom-engineered solutions with shorter lead times.
- Reach-In:Hybrid configurations bridging walk-in and reach-in refrigeration for limited-access cold storage in convenience stores and small-format restaurants.
- Custom:Engineered-to-order enclosures for irregular architectural constraints or extreme temperature requirements in pharmaceutical and specialty food applications.
Leading the category by volume: Multi-Panel. Expanding most quickly: Custom solutions for ghost kitchen configurations.
End User:
Capital deployment intensity and cold chain compliance scrutiny vary sharply across operator types, with food distributors facing the most stringent Health Canada and FDA dual-jurisdiction requirements.
- Food Distributors:Large-format installations serving regional logistics networks require continuous temperature documentation for FDA and USDA compliance. New construction concentrates near Miami, Dallas, and Atlanta distribution corridors where perishable throughput demands redundant refrigeration capacity.
- Restaurants:Ghost kitchen proliferation and meal-kit prep operations are expanding dedicated cold storage footprints. Third-party delivery consolidation drives demand for modular systems with rapid deployment timelines.
- Supermarkets:Full-service grocery operations with back-of-house receiving and preparation areas requiring integration with existing refrigeration infrastructure.
- Convenience Stores:Limited-space installations prioritizing energy efficiency and remote monitoring capabilities for multi-unit fleet management.
Food Distributors command the highest average transaction value. Restaurants are gaining share fastest through off-premise dining infrastructure expansion.
Installation Type:
Permanent installations face stricter state-level building electrification mandates in California and New York, while portable units navigate lighter regulatory burdens for temporary deployments.
- Permanent:Fixed concrete-pad or building-integrated installations commanding the largest revenue share. California and New York state refrigerant regulations exceeding federal minimums drive specification of transcritical CO2 and ammonia secondary systems.
- Portable:Self-contained modular units on casters or skids gaining traction among catering operations and temporary foodservice expansion. Catering companies in the southeastern United States deploy these for rapid market entry without permanent construction.
- Indoor:Climate-controlled building envelope installations with reduced weatherproofing requirements and lower operating cost profiles.
- Outdoor:Weather-resistant enclosures with enhanced insulation and corrosion protection for loading dock and remote facility applications.
Permanent installations dominate current revenue. Portable configurations show the steepest expansion trajectory from catering and pop-up foodservice models.
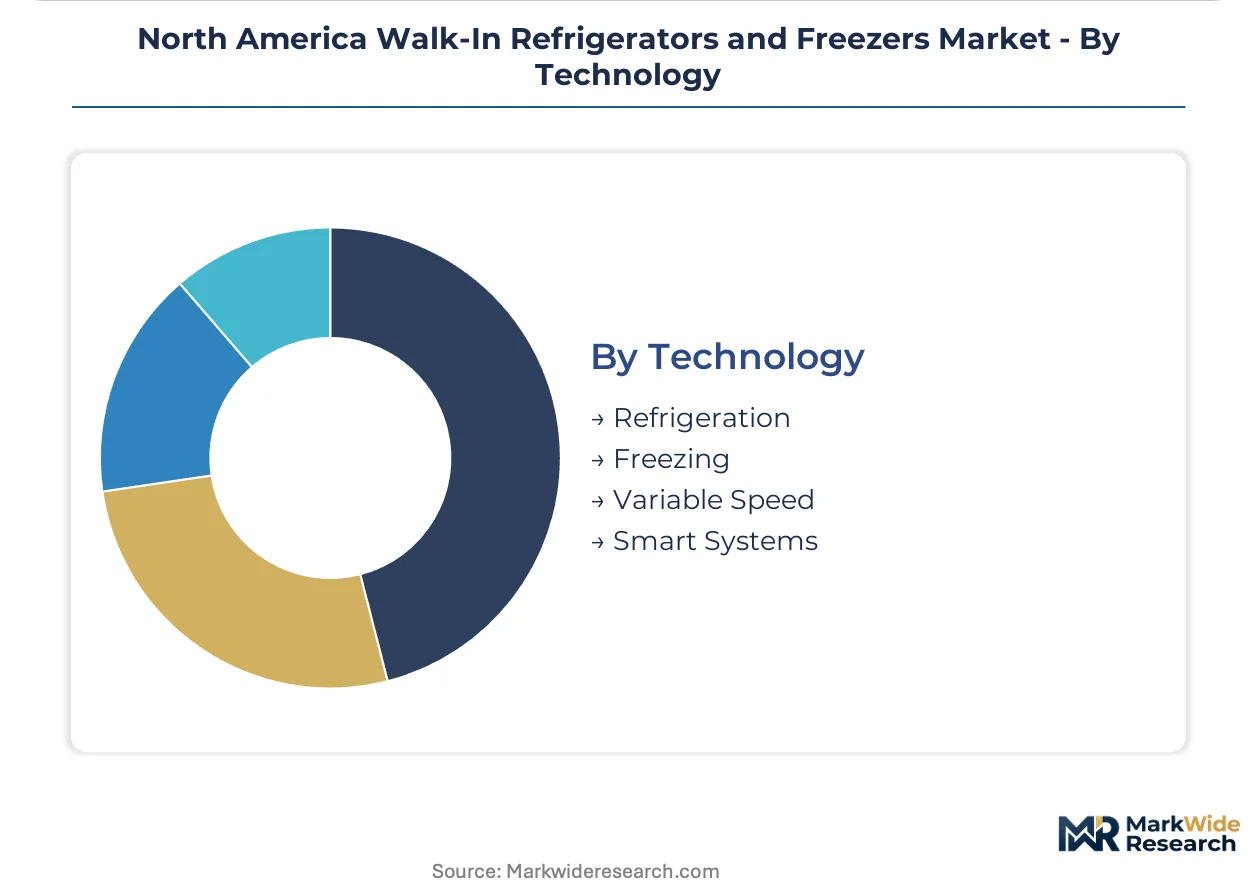
Technology:
Smart systems integration and variable speed compression face overlapping efficiency mandates from the EPA's AIM Act and state-level building performance standards.
- Smart Systems:IoT-enabled remote monitoring platforms with predictive maintenance capabilities represent the fastest-growing technology segment. Multi-unit restaurant operators in the southeastern United States specify these for centralized fleet temperature compliance and energy optimization.
- Variable Speed:Modulating compressor technology reducing energy consumption through partial-load operation. Cold storage developers in California prioritize these to meet state efficiency tiers exceeding federal minimums.
- Refrigeration:Standard mechanical cooling maintaining temperatures from approximately fifty degrees Fahrenheit down to thirty-two degrees Fahrenheit for fresh food preservation.
- Freezing:Low-temperature systems maintaining negative ten degrees Fahrenheit for frozen inventory storage with higher insulation and compressor performance requirements.
Refrigeration technology holds the largest installed base. Smart systems are climbing the fastest on foodservice digitalization investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel and aluminum feedstock availability from Great Lakes manufacturing corridors anchors North American walk-in refrigeration production capacity. Cold chain infrastructure deployment concentrates in distribution-heavy sub-regions where perishable logistics networks command premium refrigeration assets.
United States
Ghost kitchen proliferation and meal-kit prep operations drive dedicated cold storage expansion across metropolitan foodservice clusters. The EPA's AIM Act refrigerant phase-down rules compress equipment replacement cycles nationwide. Southeast distribution corridors near Atlanta, Dallas, and Miami generate concentrated demand for large-format modular installations serving regional logistics hubs.
Canada
Cross-border cold chain standardization pressures Canadian operators to align with evolving US refrigerant protocols. Health Canada and the PMRA enforce parallel temperature integrity requirements that shape equipment specifications for domestic food processors. Ontario and Quebec food distribution networks maintain dual-jurisdiction compliance infrastructure for transcontinental perishable shipments.
Mexico
Underdeveloped perishable logistics infrastructure creates white space for standardized modular walk-in systems in produce distribution networks. The country's national agricultural regulator maintains evolving cold chain protocols for export-grade fruit and vegetable shipments. Northern border states concentrate initial equipment deployment for cross-border supply chain integration with US distribution networks.
Southeast United States
Rapid chain restaurant expansion favors standardized fleet management approaches for multi-unit cold storage deployment. State-level building codes in Florida and Georgia accommodate accelerated permitting for food logistics facilities. Miami, Atlanta, and Dallas metropolitan areas anchor the continent's fastest-growing concentration of third-party delivery consolidation infrastructure.
North America Walk-In Refrigerators and Freezers Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and service network density. The vendor base clusters around three strategic tiers: integrated conglomerates with captive component production, mid-scale specialists emphasizing custom engineering capabilities, and regional fabricators competing on lead-time compression. Dominant competitive moves include backward integration into insulated panel manufacturing and geographic expansion through distributor network acquisition.
Among scale-driven integrated manufacturers, Carrier Global Corporation and Hussmann Corporation exemplify the conglomerate archetype through captive supply chain control and nationwide service infrastructure. Kolpak occupies a position within the custom-engineering specialist tier, while Nor-Lake represents regional fabrication expertise concentrated in specific geographic corridors.
| Leading Market Players |
|---|
| Nor-Lake |
| Kolpak |
| Hussmann Corporation |
| Arctic Walk-in Coolers & Walk-in Freezers |
| American Panel |
| Carrier Global Corporation |
| Master-Bilt Products |
| Imperial Brown |
| Bally Refrigerated Boxes |
| Others |
Value Network & Pricing Analysis
Polyurethane-injected panel systems with high-pressure foaming equipment are displacing traditional laminated board construction across southeastern distribution corridors, compressing field assembly timelines while concentrating procurement leverage with domestic suppliers capable of captive urethane production. This manufacturing transition simultaneously elevates upfront capital requirements for tier-one suppliers and erodes price competitiveness of regional fabricators dependent on imported panel assemblies.
Pricing Analysis
Warranty and service bundling separates premium-tier suppliers from transactional equipment vendors, with multi-year maintenance agreements commanding substantial price premiums over unbundled hardware transactions. Three-tier pricing structure across premium, standard, and economy levels reflects divergence in thermal performance certification, EPA SNAP refrigerant compliance tier, and geographic service network density. Cost compression in the standard tier is intensifying because steel and aluminum input volatility resists full pass-through to end-users. Regional restaurant groups exhibit highest price sensitivity, while food distributors with FDA dual-jurisdiction requirements demonstrate lowest sensitivity due to compliance-driven specification rigidity.
Supply Chain Analysis
Single-source vulnerability sits with Great Lakes manufacturing corridors for steel feedstock and Gulf Coast petrochemical complexes for urethane precursor chemicals. Panel assembly draws from domestic Midwest fabrication facilities, Mexican metal forming operations, and Canadian insulation material suppliers. Tariff exposure on cross-border steel and aluminum shipments presents structural risk to margin stability across integrated manufacturers. Distribution runs through authorized dealer networks with captive installation capabilities, supplemented by direct procurement relationships for large-format food logistics facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified refrigeration technician scarcity concentrated in legacy Midwest manufacturing corridors props pricing power for service-capable incumbents, constraining supply response to demand surges in southeastern expansion markets.
For Market Incumbents: Deepen backward integration into urethane core production to insulate margin structures from petrochemical price volatility and capture EPA SNAP refrigerant transition premiums. Consolidate distributor networks in Atlanta, Dallas, and Miami corridors to preempt emerging regional fabricators from securing third-party delivery consolidation infrastructure. Threat of custom-engineered specialists like Kolpak displacing standardized fleet contracts demands channel control investment. For New Entrants and Emerging Players: Digital-channel routes through IoT-enabled remote monitoring platforms offer lowest-friction entry into multi-unit restaurant operator procurement processes. White-space targets include portable modular systems for catering operations in southeastern metropolitan areas and standardized configurations for Mexico produce distribution networks. Most penetrable segment: convenience store chains with limited-space installations prioritizing energy efficiency and fleet management capabilities. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale specialists possessing Health Canada and PMRA dual-certification infrastructure given cross-border cold chain standardization catalyst. Long-term viability hinges on refrigerant transition service capabilities and smart systems integration depth. Acquisition target archetype: regional fabricators with southeastern geographic concentration and untapped aftermarket service revenue. Signal to watch: EPA AIM Act enforcement acceleration prompting accelerated replacement cycle demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Urethane Core Production | Captive supply of insulation materials insulates margins from petrochemical volatility and secures EPA SNAP compliance documentation. |
| Smart Systems Platform Development | IoT-enabled remote monitoring addresses FDA temperature documentation requirements for food distributors and enables predictive maintenance revenue. |
| Southeast Distribution Network Acquisition | Control of Atlanta, Dallas, and Miami dealer infrastructure preempts competitors from third-party delivery consolidation market entry. |
| Health Canada Dual-Certification Investment | PMRA cold chain standard alignment opens transcontinental perishable logistics procurement for Ontario and Quebec food processors. |
| Mexico Cold Chain Infrastructure Partnership | Standardized modular walk-in deployment addresses underdeveloped produce distribution networks in northern border states for export-grade shipments. |
Research Methodology
Independent corroboration across equipment manufacturer sales executives, foodservice procurement directors, and refrigeration contractor field operations underwrites the qualitative findings on replacement cycle compression. Primary interviews with EPA regulatory affairs specialists, Health Canada cold chain compliance officers, and cold storage facility engineering consultants combined with secondary validation from USDA bio-preferred procurement databases, AIM Act refrigerant phase-down filings, and southeastern state building permit records. Bottom-up unit demand estimates triangulated against top-down construction spending data across food logistics categories.
Comparable-period anchoring to historical equipment replacement patterns and refrigerant regulatory milestone dates established the forecast window baseline. Segmentation modeling spanned product construction method, end-user operator type, installation permanence, and technology integration level across the projection horizon. CAGRs derived from installed base turnover rates, new construction permit flows, and regulatory compliance deadline proximity. Industry-specific inputs included EPA SNAP approval timelines and state-level building electrification mandate adoption curves.
The model holds under steady refrigerant phase-down enforcement and stable steel-aluminum input cost bands; deviation in tariff policy or accelerated A2L technician certification requirements would shift replacement demand timing. Forecasts reflect documented assumptions regarding ghost kitchen proliferation rates and cross-border cold chain standardization progress. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
China Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
North America Commercial Sous Vide Machine Market
Food Processing Equipment
Food Processing and Handling Equipment Market
Food Processing Equipment
Cereal Rolling Machine Market
Food Processing Equipment
Commercial Food Refrigeration Equipment Market
Food Processing Equipment
Food Extruder Market
Food Processing Equipment
Food Ultrasound Market
Food Processing Equipment
Sorbitol Production Equipment Market
Food Processing Equipment
Nigeria Cocoa Processing Market
Food Processing Equipment
Sous Vide Cooking Appliances Market
Food Processing Equipment
Microbrewery Equipment Market
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Food Ingredients Sterilization Market
Food Processing Equipment
Hand Blender Market
Food Processing Equipment
Refrigerated Vending Machines Market