
 De-Agglomerating Equipment Market | 2026-2036
De-Agglomerating Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
De-Agglomerating Equipment Market Outlook
CE marking under the EU Machinery Directive is collapsing the supplier base for European pharmaceutical buyers. NETZSCH leverages its precision grinding heritage to dominate high-shear mechanical systems for active pharmaceutical ingredient processing. Hosokawa Micron Group anchors its position through captive manufacturing of classifier mills integrated with containment solutions. Quadro Engineering specializes in conical milling configurations that sustain premium positioning in OSD formulation lines.
De-agglomerating equipment refers to industrial machinery designed to break down particle clusters into discrete, flowable units through mechanical shear, thermal stress, chemical dispersion, or acoustic cavitation, typically achieving particle size distributions below 500 microns for downstream processing efficiency. Mechanical systems lead installed capacity due to their established reliability in high-throughput pharmaceutical and food processing environments, while ultrasonic configurations represent the fastest-growing product category as manufacturers seek non-thermal alternatives for heat-sensitive biologics. Inline installations concentrate margin pools in continuous manufacturing transitions, whereas batch operational modes retain dominance in validated pharmaceutical workflows where process analytical technology integration remains partial.
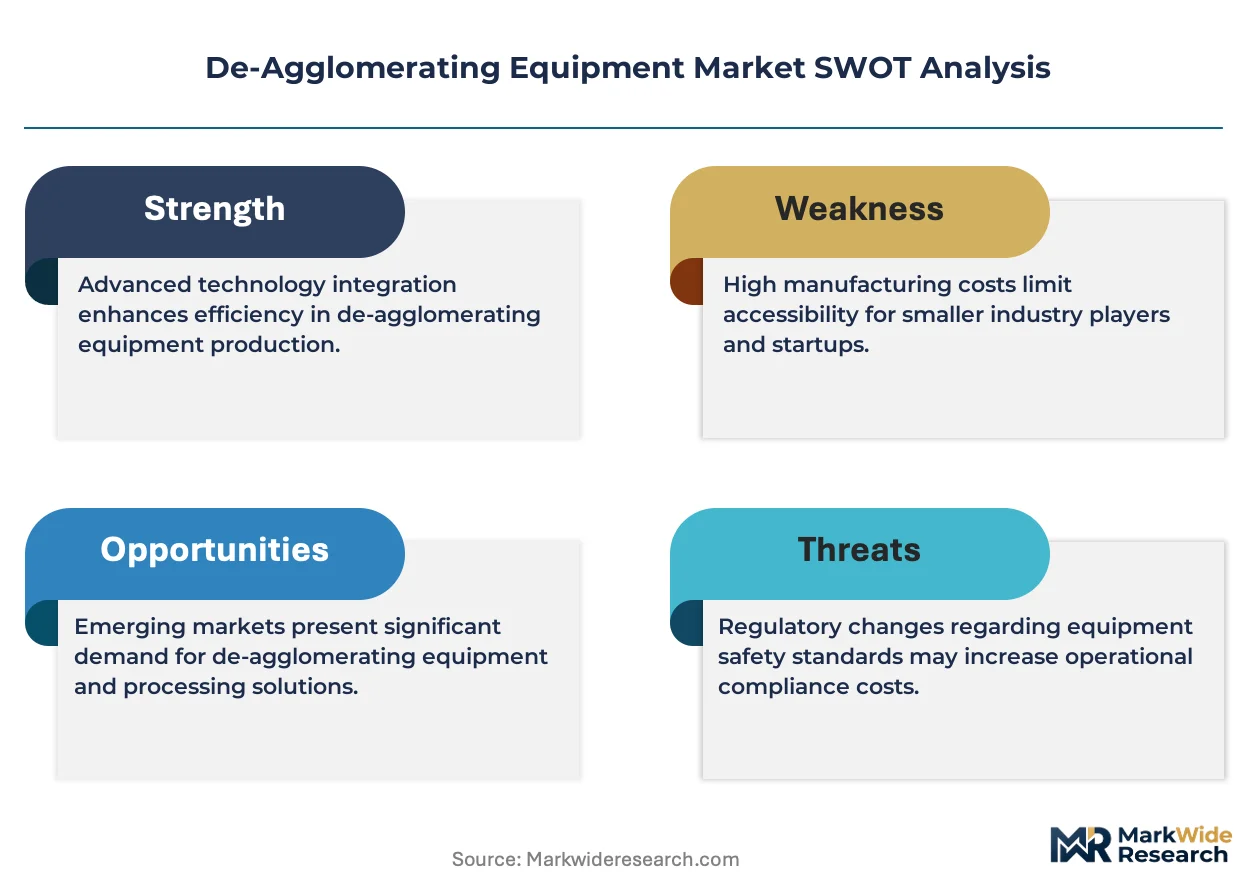
FDA cGMP guidelines and EU GMP Annex 1 revisions are forcing equipment redesigns toward contained, cleanable architectures with single-use contact surfaces. REACH compliance through ECHA and RoHS directives through national EU member state authorities further constrain material selection for chemical-contact components, elevating stainless steel grade specifications and surface finish requirements. Stakeholders must monitor evolving containment integrity standards and decide between retrofitting legacy mechanical platforms or migrating to integrated continuous processing architectures before qualification protocols harden.
Market Dynamics
Continuous manufacturing architectures are compressing batch validation cycles and forcing equipment suppliers to redesign de-agglomerating systems for real-time process analytical technology integration rather than end-point testing protocols.
Growth Catalysts
- EU GMP Annex 1 Containment Mandates:Pharmaceutical manufacturers in Germany and Switzerland are retrofitting mechanical de-agglomerating lines with isolator-integrated configurations to satisfy revised contamination control requirements for sterile active pharmaceutical ingredient processing.
- Biologics Heat Sensitivity:Ultrasonic cavitation systems are capturing replacement demand from thermal mechanical mills as manufacturers of monoclonal antibodies and mRNA formulations seek non-degradative particle size reduction below 200 microns.
- Food Processing Hub Concentration:Western European dairy and infant nutrition clusters in the Netherlands and Denmark are consolidating powder handling capacity, driving replacement cycles for high-shear mechanical de-agglomerators with clean-in-place architectures.
Market Restraints
- Stainless Steel Grade Volatility:REACH compliance through ECHA and RoHS national implementations are constraining 316L and 904L stainless sourcing for chemical-contact surfaces, elevating material qualification timelines for European equipment fabricators.
- Supplier Base Concentration:CE marking collapse under the EU Machinery Directive has eliminated mid-tier mechanical system suppliers, leaving pharmaceutical buyers dependent on a narrowed pool of precision grinding heritage manufacturers with extended lead times.
- Ultrasonic Scale-Up Limitations:Acoustic cavitation systems face throughput ceilings in high-volume oral solid dosage lines where mechanical classifier mills maintain established reliability above 500 kilograms per hour.
Strategic Opportunities
- India Pharmaceutical Manufacturing:CDSCO and PLI scheme incentives for active pharmaceutical ingredient localization are creating demand for contained de-agglomerating systems as multinational sponsors dual-source supply away from single-geography dependencies.
- Single-Use Surface Integration:Convergence of disposable contact surfaces with mechanical shear platforms is enabling rapid product changeover in multi-purpose contract manufacturing organizations serving fragmented biotech pipelines.
- Process Analytical Technology Mandates:FDA cGMP guideline enforcement on real-time release testing is accelerating inline de-agglomerating installations that bypass traditional batch sampling protocols and accelerate time-to-market for abbreviated new drug applications.
Industry Challenges
- Containment Engineering Talent Scarcity:Qualified specialists in isolator-integrated mechanical design remain concentrated among heritage precision grinding firms, constraining expansion capacity for emerging equipment suppliers.
- Legacy Validation Protocol Rigidity:Pharmaceutical quality assurance departments resist migrating from established batch operational modes to continuous architectures due to incomplete process analytical technology integration and requalification cost uncertainty.
- Cross-Regulatory Divergence:Misalignment between FDA cGMP containment expectations and EU GMP Annex 1 technical interpretations forces dual-design engineering for suppliers serving both regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | De-Agglomerating Equipment Market |
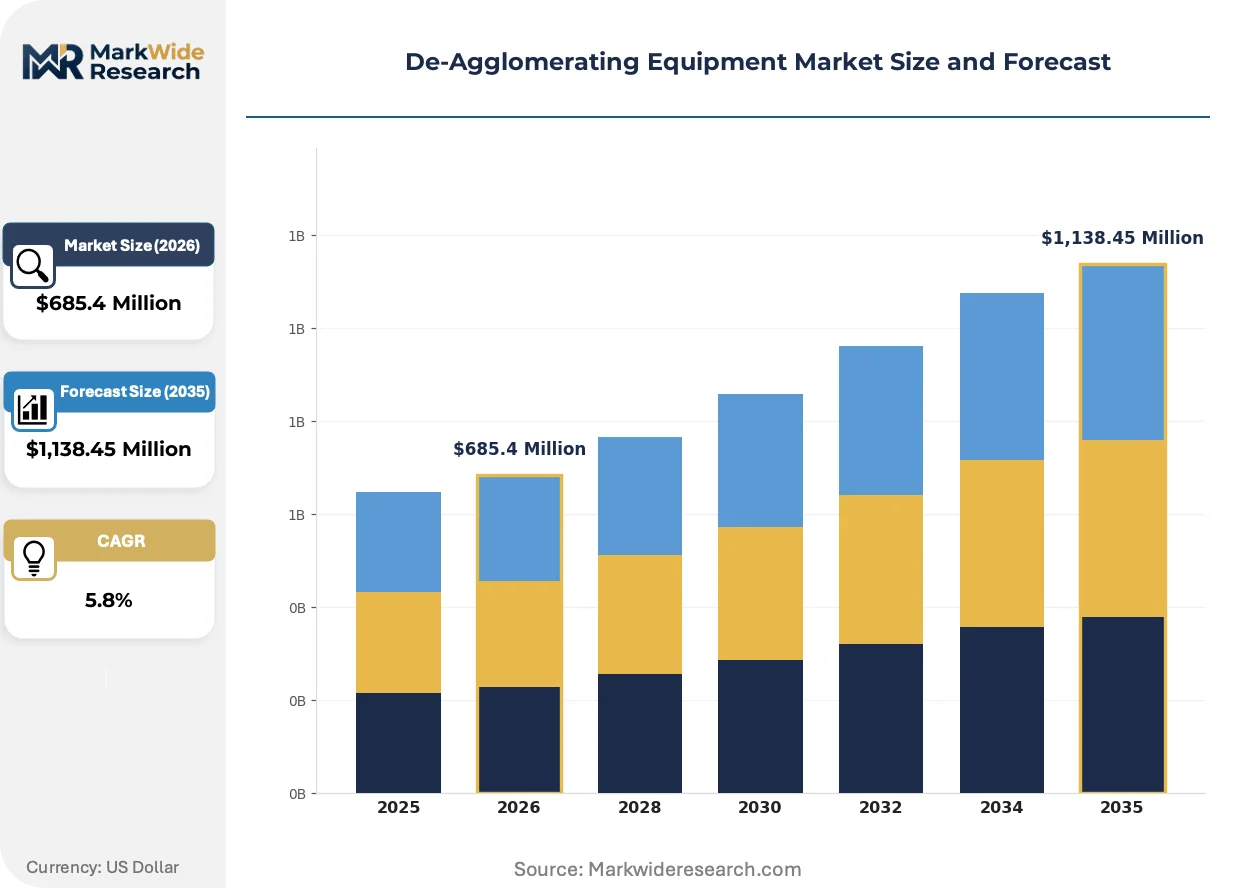
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Thermal, Chemical, Ultrasonic End User: Pharmaceuticals, Food Processing, Plastics, Chemicals Installation Type: Standalone, Inline, Portable, Mobile Operational Mode: Batch, Continuous, Semi-Automatic, Fully Automatic |
| Companies Covered | NETZSCH, Quadro Engineering, Hosokawa Micron Group, Munson Machinery, Schenck Process, Bühler Group, Fitzpatrick Company, FREWITT, GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
De-Agglomerating Equipment Market Strategic Shifts
Equipment architectures are pivoting from standalone mechanical platforms toward integrated continuous processing nodes that embed particle size reduction within closed material flow circuits rather than discrete unit operations.
Ultrasonic cavitation de-agglomeration is supplanting thermal mechanical milling in heat-sensitive biologics processing. Contract development and manufacturing organizations serving early-phase biotech sponsors are adopting acoustic systems at accelerated procurement cycles. This technology is supplanting established high-shear configurations in monoclonal antibody formulation lines where protein denaturation risk outweighs throughput optimization.
EU GMP Annex 1 revisions are mandating contained, cleanable equipment architectures with demonstrated isolation integrity for sterile processing. Pharmaceutical manufacturers in Germany and Switzerland are redesigning facility layouts to accommodate isolator-integrated mechanical mills with single-use contact surfaces. Active pharmaceutical ingredient processing lines face the most acute compliance pressure, driving replacement demand ahead of patent cliff exposures.
After-sales service unbundling is fragmenting traditional equipment procurement bundles across North American pharmaceutical buyers. Original equipment manufacturers are separating hardware supply from validation support and spare parts contracts, forcing facility engineering departments to negotiate discrete service level agreements. This pattern is most visible among mid-cap generic drug manufacturers consolidating oral solid dosage capacity in New Jersey and Puerto Rico manufacturing clusters.
De-Agglomerating Equipment Market Segmentation
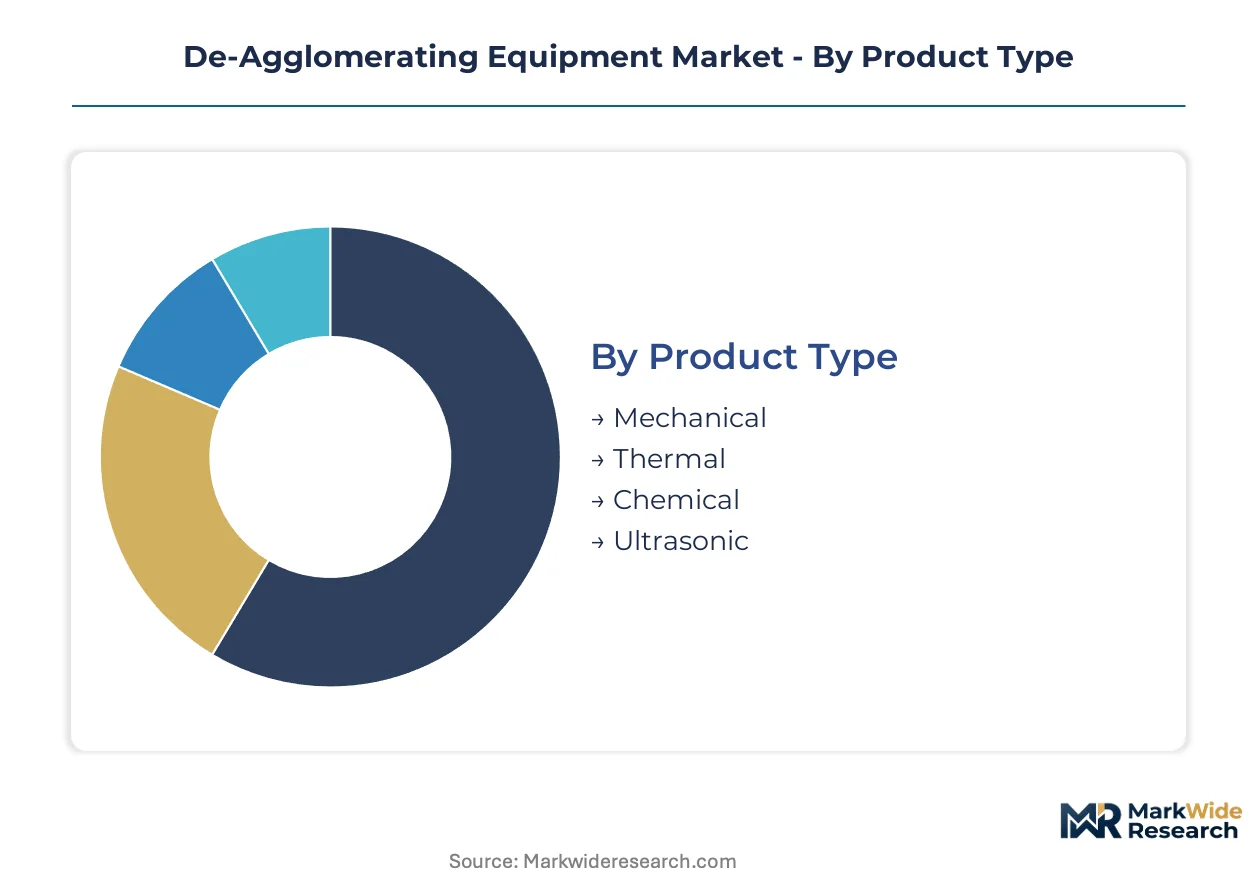
De-agglomerating equipment segmentation reveals distinct procurement patterns across pharmaceutical validation protocols and food processing throughput requirements. Equipment specifications diverge sharply between sterile active pharmaceutical ingredient containment and high-volume powder handling applications.
Product Type:
German and Swiss pharmaceutical fabricators concentrate export demand for precision mechanical systems, while domestic European food processors source thermal configurations from regional suppliers.
- Mechanical:High-shear mills and classifier systems dominate validated pharmaceutical workflows through established reliability above 500 kilograms per hour. German manufacturers retrofit isolator-integrated configurations to satisfy EU GMP Annex 1 contamination control mandates for sterile active pharmaceutical ingredient processing.
- Ultrasonic:Acoustic cavitation technology achieves non-thermal particle size reduction below 200 microns for heat-sensitive biologics. Monoclonal antibody and mRNA formulation lines in Switzerland and Denmark are capturing replacement demand from thermal mechanical mills as protein denaturation risk outweighs throughput optimization.
- Thermal:Heat-based dispersion systems retain installed base in Western European dairy powder clusters requiring flowability restoration without shear-induced amorphization.
- Chemical:Surfactant-assisted de-agglomeration serves niche applications in pigment and coating industries where surface chemistry modification precedes downstream dispersion.
Mechanical systems command the established base. The steepest expansion runs through ultrasonic configurations.
End User:
Cost tier stratification separates contained pharmaceutical specifications from standard food-grade architectures, with plastics and chemicals occupying mid-tier pricing bands.
- Pharmaceuticals:Active pharmaceutical ingredient processing and oral solid dosage formulation drive premium equipment specifications with single-use contact surfaces and isolator integration. FDA cGMP guidelines and EU GMP Annex 1 revisions are forcing redesigns toward contained, cleanable architectures with demonstrated isolation integrity.
- Food Processing:Infant nutrition and dairy powder clusters in the Netherlands and Denmark consolidate handling capacity around clean-in-place mechanical systems. Western European hubs are driving replacement cycles for high-shear de-agglomerators with validated hygienic design.
- Plastics:Masterbatch and compound producers require intermediate containment for pigment dispersion without pharmaceutical-grade isolation overhead.
- Chemicals:REACH compliance through ECHA constrains material selection for chemical-contact surfaces, elevating stainless steel grade specifications in specialty chemical applications.
Pharmaceuticals anchor premium positioning. Food Processing is gaining share fastest through consolidation-driven replacement demand.
Installation Type:
Volume concentration favors inline architectures in continuous manufacturing transitions, while standalone systems retain dominance in validated batch workflows.
- Inline:Real-time process analytical technology integration enables continuous material flow circuits that bypass traditional batch sampling protocols. Inline installations concentrate margin pools as manufacturers migrate from discrete unit operations toward integrated processing nodes.
- Standalone:Discrete mechanical platforms retain procurement priority in multi-purpose contract manufacturing organizations requiring equipment mobility between product campaigns.
- Portable:Skid-mounted configurations serve pilot-scale operations and technology transfer activities between development and commercial facilities.
- Mobile:Trailer-based systems address temporary capacity needs in construction materials and mining applications outside core pharmaceutical and food processing markets.
Standalone units command the established base. Inline configurations are expanding most quickly through continuous manufacturing adoption.
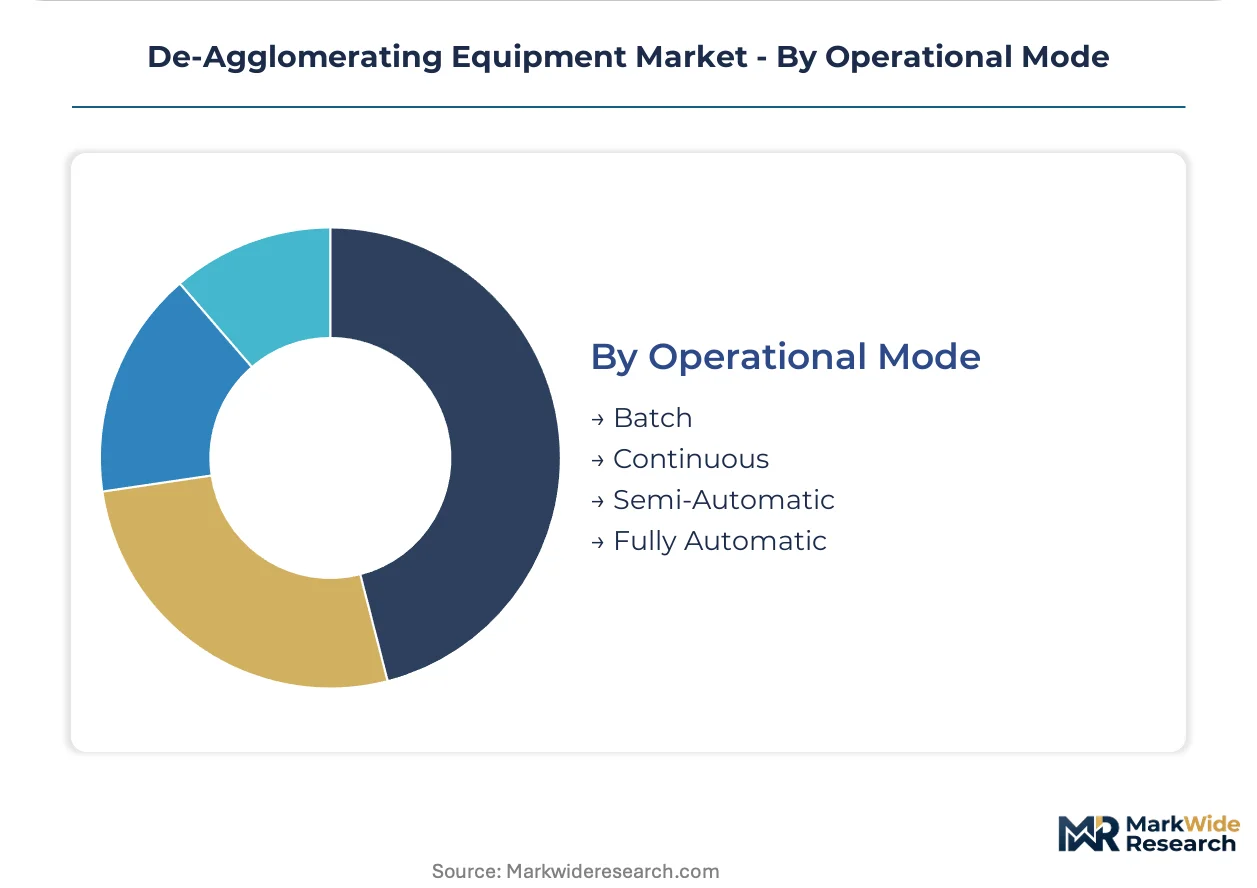
Operational Mode:
Customer type bifurcation separates validated pharmaceutical batch protocols from food processing automation trajectories.
- Batch:End-point testing protocols and established validation documentation retain dominance in pharmaceutical quality assurance departments resisting migration due to requalification cost uncertainty. Batch operational modes sustain procurement priority where process analytical technology integration remains partial.
- Continuous:Real-time release testing architectures compress validation cycles and accelerate time-to-market for abbreviated new drug applications. FDA cGMP guideline enforcement is accelerating inline installations that embed particle size reduction within closed material flow circuits.
- Semi-Automatic:Hybrid configurations serve mid-cap generic drug manufacturers consolidating oral solid dosage capacity with partial automation investment.
- Fully Automatic:Complete process control integration targets high-volume food processing hubs with standardized product portfolios and extended production runs.
Batch modes command the established base. Continuous architectures are climbing the fastest through regulatory pressure on real-time release testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's bulk handling infrastructure underwrites Western Europe's dominance in powder processing equipment trade, connecting German and Dutch manufacturing clusters to global pharmaceutical supply chains.
Germany
Active pharmaceutical ingredient manufacturers in Baden-Württemberg and Bavaria are retrofitting mechanical de-agglomerating lines with isolator-integrated configurations. The country's national pharmaceutical regulator enforces EU GMP Annex 1 containment standards through state-level inspection authorities. The Rhine-Main pharmaceutical corridor around Frankfurt sustains replacement demand for precision grinding systems ahead of patent cliff exposures.
Switzerland
Monoclonal antibody and mRNA formulation facilities in Basel and Zurich are capturing ultrasonic cavitation systems for non-thermal particle size reduction below 200 microns. Swissmedic mandates demonstrated isolation integrity for sterile processing equipment through technical interpretation bulletins. The Basel biotech cluster drives premium equipment specifications as protein denaturation risk outweighs throughput optimization.
United States
Mid-cap generic drug manufacturers in New Jersey and Puerto Rico are consolidating oral solid dosage capacity around semi-automatic hybrid configurations. FDA cGMP guideline enforcement on real-time release testing accelerates inline installation procurement. The New Jersey pharmaceutical corridor fragments traditional equipment bundles through after-sales service unbundling.
India
Contract manufacturing organizations in Maharashtra and Gujarat are localizing active pharmaceutical ingredient production under CDSCO and PLI scheme incentives. The country's national pharmaceutical regulator mandates contained processing architectures for sterile API manufacturing. The Hyderabad-Visakhapatnam corridor attracts multinational sponsors seeking dual-source supply away from single-geography dependencies.
Netherlands
Infant nutrition and dairy powder clusters in Friesland and North Brabant are consolidating handling capacity around clean-in-place mechanical systems. The country's national food safety authority enforces validated hygienic design standards through dairy sector inspection protocols. The Randstad food processing hub drives replacement cycles for high-shear de-agglomerators with flowability restoration specifications.
De-Agglomerating Equipment Market Competitive Environment
Listed leaders compete with private specialists across precision grinding heritage and containment engineering capability. The supplier base concentrates around German and Swiss fabricators with multi-decade mechanical processing expertise, while mid-tier competitors face elimination under tightened CE marking requirements. Three archetypes dominate: precision grinding heritage manufacturers with isolator integration capabilities, diversified industrial conglomerates with food-pharma crossover portfolios, and ultrasonic technology specialists capturing biologics replacement demand. Competitive moves center on strategic partnerships for process analytical technology integration and geographic expansion into Indian pharmaceutical manufacturing corridors.
Among heritage precision grinding specialists, NETZSCH, Hosokawa Micron Group, and Quadro Engineering occupy positions representing distinct competitive vectors. NETZSCH exemplifies the precision grinding archetype with multi-generational mechanical processing expertise. Hosokawa Micron Group anchors the diversified industrial position through captive classifier mill manufacturing. Quadro Engineering sits within the specialized milling configuration tier, representing premium positioning in oral solid dosage formulation lines. These three fabricators collectively illustrate how European mechanical processing heritage translates into isolator-integrated system supply under tightened regulatory qualification protocols.
| Leading Market Players |
|---|
| NETZSCH |
| Quadro Engineering |
| Hosokawa Micron Group |
| Munson Machinery |
| Schenck Process |
| Bühler Group |
| Fitzpatrick Company |
| FREWITT |
| GEA Group |
| Others |
Value Chain & Pricing Dynamics
Ultrasonic cavitation systems displacing thermal mechanical mills in Swiss and Danish biologics facilities simultaneously redraws component sourcing maps from German precision grinding clusters toward acoustic transducer suppliers and compresses price premiums for non-thermal configurations as procurement volumes scale.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates isolator-integrated pharmaceutical systems from clean-in-place food-grade architectures and basic thermal configurations. Price differentiation hinges on CE marking compliance tier and stainless steel grade specification, with 316L and 904L material costs elevating qualification timelines. Cost compression in economy-tier thermal systems is intensifying because REACH compliance constraints are narrowing the supplier base. Contract manufacturing organizations serving fragmented biotech pipelines exhibit highest price sensitivity, while sterile active pharmaceutical ingredient processors accept premium positioning for demonstrated isolation integrity.
Supply Chain Analysis
Germany and Switzerland anchor precision mechanical fabrication for high-shear mills and classifier systems serving pharmaceutical containment mandates. Component sourcing draws from Italian stainless steel foundries for chemical-contact surfaces and Danish ultrasonic transducer specialists for acoustic cavitation modules. Single-source vulnerability concentrates in heritage precision grinding firms with isolator integration capabilities. Distribution runs through Rotterdam bulk handling infrastructure connecting German manufacturing clusters to global pharmaceutical supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
De-agglomerating equipment procurement fragments across regulatory jurisdictions and end-use specifications, creating specialized niches as continuous manufacturing architectures displace batch validation protocols in pharmaceutical workflows.
For Market Incumbents: Shield market position by deepening captive manufacturing of classifier mill components to offset stainless steel grade volatility, and accelerate process analytical technology integration partnerships before FDA cGMP enforcement hardens qualification protocols. Vertical integration into transducer supply for ultrasonic configurations mitigates acoustic specialist encroachment on biologics replacement demand. For New Entrants and Emerging Players: Anchor in Indian pharmaceutical manufacturing corridors where CDSCO and PLI scheme incentives are localizing active pharmaceutical ingredient production, and target contract manufacturing organizations seeking rapid product changeover through single-use surface integration. A validation-support bundling go-to-market angle bypasses entrenched relationships between heritage fabricators and established pharmaceutical quality assurance departments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed precision grinding specialists possessing isolator engineering capabilities but limited ultrasonic technology portfolios. Long-term viability over a five-to-ten year horizon favors targets with cross-technology coverage spanning mechanical shear and acoustic cavitation platforms. Watch FDA cGMP guideline enforcement intensity on real-time release testing as the inflection signal for continuous manufacturing adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Integration Partnership | EU GMP Annex 1 compliance mandates contained architectures for sterile active pharmaceutical ingredient processing. |
| Ultrasonic Technology Licensing | Acoustic cavitation patents enable non-thermal particle size reduction for monoclonal antibody formulation lines. |
| India Manufacturing Footprint | CDSCO and PLI scheme incentives localize supply for multinational sponsors seeking dual-source dependencies. |
| Single-Use Surface Development | Disposable contact materials accelerate product changeover in multi-purpose contract manufacturing organizations. |
| Process Analytical Technology Integration | Real-time release testing bypasses batch sampling protocols for abbreviated new drug applications. |
Study Parameters
A standing panel of pharmaceutical plant engineers, food processing maintenance directors, OEM procurement specialists, and aftermarket service heads provided ongoing calibration against secondary validation from FDA cGMP guidance documents, EU GMP Annex 1 technical interpretations, ECHA REACH compliance bulletins, and customs trade data on powder processing equipment flows. Bottom-up equipment shipment tallies and top-down end-use demand estimates underwent iterative reconciliation.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product type, end user industry, installation architecture, and operational mode alongside regional regulatory cluster differentiation. CAGRs were derived from fitted growth curves applied to base-year market sizing, with inputs spanning patent cliff exposures, containment mandate implementation timelines, and continuous manufacturing transition velocities.
Decision-makers should treat outputs as directional under assumptions of sustained EU GMP Annex 1 enforcement and uninterrupted REACH compliance pathways; material deviation would warrant model refresh. Specific risks that could revise forecasts include regulatory divergence between FDA and EU containment interpretations, stainless steel supply disruptions, and ultrasonic scale-throughput breakthroughs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Dispensing Systems and Equipment Market
Food Processing Equipment
Salmon Fish Scaling Machine Market
Food Processing Equipment
Brewery Heat Exchanger Market
Food Processing Equipment
Food Processing Equipment Market
Food Processing Equipment
Middle East and Africa Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Holding and Proofing Cabinet Market
Food Processing Equipment
Homogenizers Market
Food Processing Equipment
Dough Processing System Market
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
China Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Ice Cream Machine Market
Food Processing Equipment
Walk-In Refrigerator Market
Food Processing Equipment
Deep Fryer Oil Filtration Market
Food Processing Equipment
Destemmer Market
Food Processing Equipment
Pasty Products Filling Machine Market
Food Processing Equipment
Global Powder Processing Equipment Market