
 Sourdough Market | 2026-2036
Sourdough Market Size, Share, and Industry Trends Forecast 2026-2036
Sourdough Market Analysis
Consolidation among café and food-service chains is repositioning procurement power toward national buyers who negotiate directly with sourdough suppliers. Puratos Group leverages its global fermentation expertise to serve these consolidated accounts across multiple geographies. Lesaffre International anchors its position through yeast and starter culture R&D intensity. Dave's Killer Bread differentiates via brand strength in organic and whole-grain sourdough segments.
Sourdough is a fermented dough produced through the metabolic action of lactic acid bacteria and wild yeasts, typically requiring 12 to 24 hours of fermentation at controlled temperatures to develop acidity, flavor complexity, and leavening structure. Its primary commercial purpose centers on producing breads with distinctive tang, extended shelf life, and reduced phytic acid content for consumer and food-service applications. Artisan bread commands the dominant value share due to premium positioning and consumer willingness to pay for traditional methods. Online retail represents the fastest-expanding distribution channel, though bakery shops retain the highest margin pools through direct consumer relationships and freshness premiums.
FDA food safety standards and USDA organic certification requirements shape product formulation and labeling for sourdough marketed in the United States, while EU regulations on clean-label claims and additive restrictions influence formulation trends across European supply chains. The EU Green Deal's agricultural sustainability targets further redirect grain sourcing and fermentation energy use. Stakeholders must monitor evolving definitions of "authentic" sourdough as regulators in multiple jurisdictions consider stricter standards on starter culture disclosure and fermentation time claims.
Market Dynamics
Café chain consolidation is concentrating procurement power into fewer national buyers who negotiate directly with fermentation suppliers, compressing margin pools for traditional distributors while rewarding scaled producers with R&D depth.
Growth Catalysts
- EU Green Deal agricultural targets:Sustainability mandates redirect grain sourcing toward regenerative farms, creating certified supply pipelines that command shelf-space premiums in German and French retail.
- Controlled-temperature fermentation:Advances in climate-controlled proofing systems reduce batch-to-batch variability, enabling industrial bakers to replicate artisan flavor profiles at volume scale.
- Café chain menu differentiation:Third-wave coffee concepts deploy sourdough as a signature element, locking in multi-year supply contracts with dedicated starter culture providers.
Market Restraints
- Wheat and rye price volatility:Input cost swings of 20-40% in key grain markets compress margins for small-to-mid bakeries lacking forward-contract coverage.
- Starter culture supply concentration:Commercially viable wild yeast strains remain concentrated among three European biotechnology suppliers, creating single-source vulnerability for new market entrants.
- Fermentation time requirements:The 12-to-24-hour minimum cycle limits throughput in high-rent urban production facilities, constraining site selection to lower-cost exurban zones.
Strategic Opportunities
- Online direct-to-consumer channels:Frozen sourdough subscription models bypass retail slotting fees while capturing recurring revenue from home bakers seeking consistent starter quality.
- USDA organic certification expansion:Premium positioning through certified organic grain sourcing opens placement in natural grocery chains with above-category margin structures.
- Clean-label convergence with functional nutrition:Reduced phytic acid content and improved mineral bioavailability align sourdough with gut-health positioning in preventive wellness segments.
Industry Challenges
- Master baker talent scarcity:The specialized skill set for maintaining live starter cultures across variable environmental conditions commands wage premiums that strain unit economics.
- FDA fermentation safety compliance:Pathogen control documentation for ambient-temperature processes extends product development timelines by 8-14 months versus conventional bread.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sourdough Market |
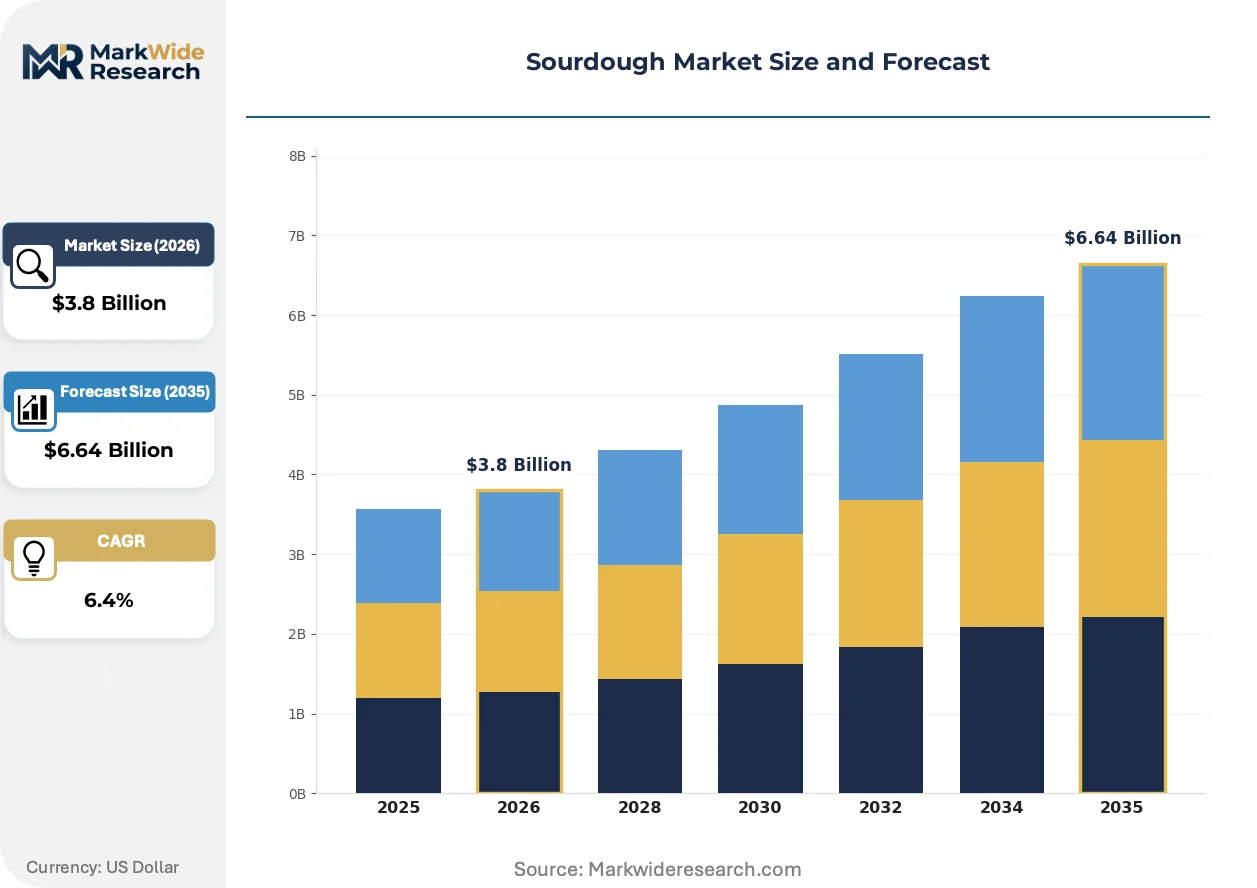
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artisan Bread, Gluten-Free Sourdough, Rye Sourdough, White Sourdough Distribution Channel: Bakery Shops, Supermarkets, Online Retail, Specialty Stores End User: Households, Cafés, Restaurants, Food Service Packaging Type: Bags, Boxes, Bulk Packaging, Vacuum-Sealed |
| Companies Covered | IREKS GmbH, Boudin Bakery, Puratos Group, Gold Coast Bakeries, Truckee Sourdough Company, Lesaffre International, Ernst Böcker GmbH, Dave's Killer Bread, Lallemand Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sourdough Market Emerging Trajectories
Fermentation technology and distribution infrastructure are undergoing simultaneous recalibration, with automation, regulatory precision, and channel fragmentation converging to redefine competitive advantage.
Precision fermentation monitoring systems are modularizing quality control across distributed production networks. Industrial bakeries deploy IoT-enabled pH and temperature sensors that transmit real-time acidity data to central operations centers. This architecture compresses technical staffing requirements at individual plants while centralizing expertise retention.
EU EFSA additive restriction frameworks are tightening permissible ingredient declarations for products labeled "authentic sourdough." The regulation disqualifies chemical acidifiers and rapid-rise yeast adjuncts from clean-label claims. German and Italian producers have accelerated investment in certified traditional process documentation to maintain retail positioning.
Café procurement teams are consolidating supplier relationships around full-service bakery programs that bundle frozen dough, par-baked loaves, and technical training. This behavior displaces fragmented purchasing across multiple commodity bread vendors. The shift is most visible in US coastal metropolitan markets where labor costs drive outsourcing of in-house baking operations.
Sourdough Market Segmentation
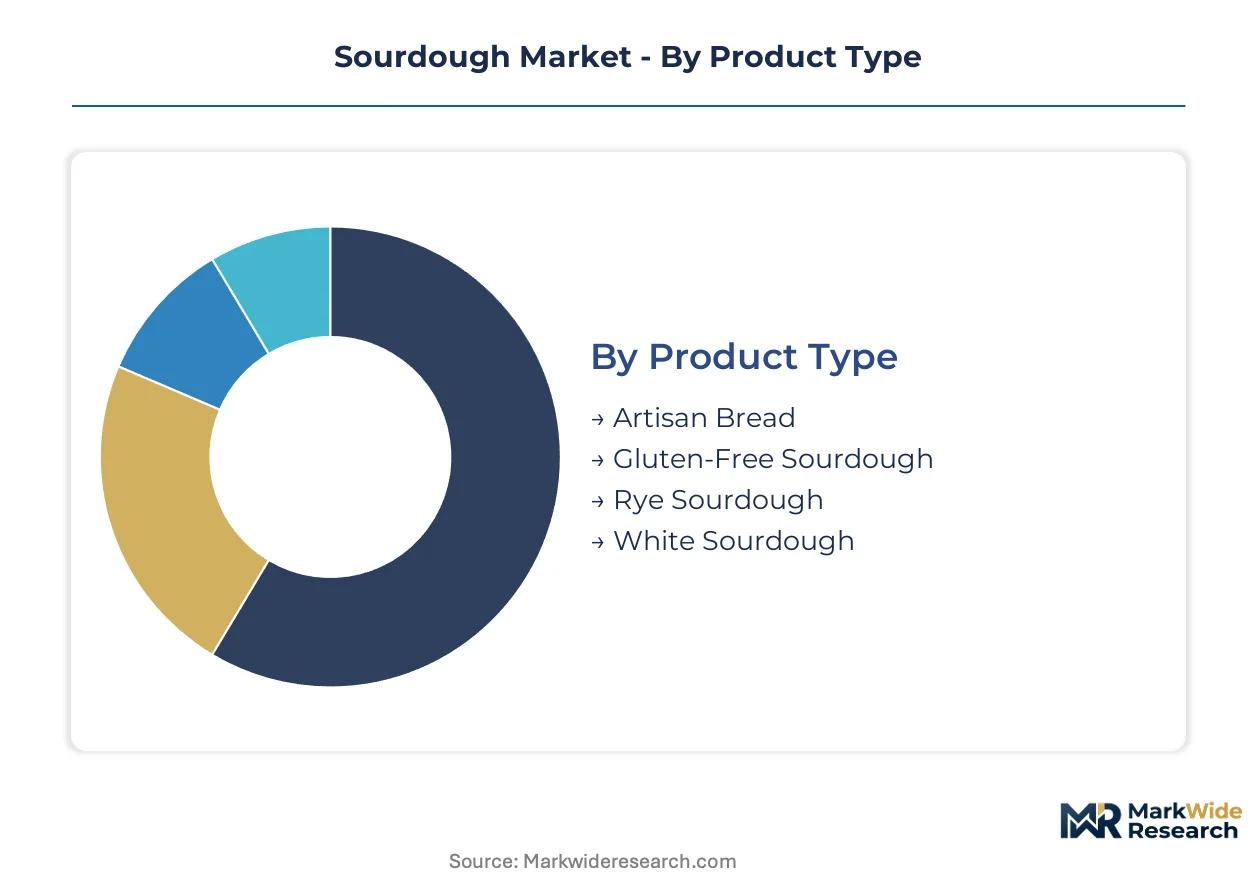
Sourdough market segmentation reveals distinct capital requirements across production formats, with fermentation infrastructure and distribution scale determining competitive positioning. Understanding these structural differences enables targeted resource allocation and margin capture strategies.
Product Type:
Capital intensity peaks in segments requiring extended fermentation cycles and specialized climate control systems.
- Artisan Bread:Traditional long-fermentation loaves demand 12-to-24-hour proofing rooms with precise temperature and humidity regulation. Café chains in Germany and France negotiate multi-year supply contracts for consistent starter-derived flavor profiles, locking in premium positioning.
- Gluten-Free Sourdough:Alternative grain formulations require dedicated production lines to prevent cross-contamination. Household demand concentrates in North American and Australian markets where celiac awareness drives certified product placement in natural grocery channels.
- Rye Sourdough:German bakeries anchor regional demand through deeply rooted consumption traditions.
- White Sourdough:Milder flavor profiles suit industrial-scale production for food-service accounts.
Artisan bread absorbs the bulk of installed capacity; gluten-free sourdough is expanding most quickly.
Distribution Channel:
Margin capture varies sharply by channel control, with direct consumer relationships commanding price premiums over intermediated retail.
- Bakery Shops:Fresh-daily positioning enables full margin retention and starter culture transparency storytelling. German craft bakeries leverage direct relationships to justify 40-60% price premiums over supermarket equivalents.
- Online Retail:Frozen sourdough subscription models bypass slotting fees while building recurring revenue. US coastal metropolitan markets show strongest traction among home bakers seeking consistent starter quality without maintenance burden.
- Supermarkets:Mass-market penetration requires par-baked or fully baked formats with extended shelf-life engineering.
- Specialty Stores:Curated assortments target organic and whole-grain positioning in natural food channels.
Bakery shops retain the highest margin pools; online retail shows the steepest expansion trajectory.
End User:
Volume concentration and customization requirements diverge significantly across buyer types, reshaping production scheduling and formulation flexibility.
- Households:Individual consumers prioritize convenience formats and clear fermentation-time labeling for authenticity verification. EU clean-label regulations drive preference for products with disclosed starter culture origins.
- Cafés:Third-wave coffee concepts deploy sourdough as menu differentiation, requiring consistent supply and technical training support. US West Coast chains consolidate procurement around full-service bakery programs.
- Restaurants:Fine-dining accounts demand customizable loaf sizes and crust characteristics for plate presentation.
- Food Service:Institutional buyers prioritize cost efficiency and frozen dough stability for labor-constrained kitchens.
Cafés concentrate the fastest-growing demand segment; food service represents the largest volume absorption.
Packaging Type:
Preservation technology investment separates segments by shelf-life extension capability and premium positioning potential.
- Vacuum-Sealed:Oxygen-exclusion technology extends ambient shelf life from 3-5 days to 14-21 days, enabling broader distribution radius. German and Dutch retail chains specify vacuum formats for private-label sourdough lines.
- Bulk Packaging:Food-service accounts in France and Italy accept unwrapped loaves for same-day consumption, minimizing packaging cost.
- Bags:Standard retail formats balance breathability with moisture retention for 5-7 day shelf life.
- Boxes:Premium gift and subscription formats emphasize unboxing experience and starter culture provenance documentation.
Bags dominate current packaging volume; vacuum-sealed formats gain share fastest in extended distribution channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, where traditional rye sourdough maintains deep consumer loyalty, while the United States and France follow as high-value markets driven by café chain expansion and artisan positioning. Regulatory divergence between EU clean-label mandates and US organic certification requirements shapes distinct competitive entry paths across these geographies.
Germany
Traditional rye sourdough consumption and EU Green Deal agricultural targets drive certified regenerative grain sourcing. EFSA additive restriction frameworks disqualify chemical acidifiers from clean-label claims. Bavarian craft bakeries leverage direct consumer relationships to justify 40-60% price premiums over supermarket equivalents.
United States
Third-wave coffee concepts deploy sourdough as menu differentiation, consolidating procurement around full-service bakery programs. FDA food safety standards and USDA organic certification requirements shape product formulation and labeling. West Coast metropolitan markets show strongest traction for frozen sourdough subscription models among home bakers.
France
Artisan bread traditions and café chain consolidation create demand for consistent starter-derived flavor profiles. EU EFSA additive restriction frameworks tighten permissible ingredient declarations for "authentic sourdough" claims. Parisian and Lyon-based producers accelerate investment in certified traditional process documentation to maintain retail positioning.
Italy
Clean-label convergence with Mediterranean diet positioning drives consumer preference for disclosed fermentation times and starter culture origins. EU Green Deal sustainability mandates redirect grain sourcing toward regenerative farms. Northern Italian industrial bakeries deploy IoT-enabled pH monitoring systems to replicate artisan profiles at volume scale.
United Kingdom
Online retail expansion and specialty store placement in natural food channels accelerate gluten-free and organic sourdough adoption. UK Food Standards Agency labeling requirements intersect with EU-influenced clean-label expectations. London-based bakery chains negotiate multi-year supply contracts for frozen dough and par-baked formats to reduce in-house labor costs.
Sourdough Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription models and certified organic positioning. The market exhibits tiered concentration, with scaled fermentation technology suppliers serving consolidated café accounts while regional craft bakeries retain margin through direct consumer relationships. Three archetypes dominate: global ingredient-technology conglomerates with starter culture R&D depth, national bakery brands leveraging organic and whole-grain differentiation, and specialized regional producers anchored in traditional methods. Competitive moves center on multi-year supply contract lock-ins with café chains and backward integration into certified grain sourcing.
Within the global ingredient-technology tier, Puratos Group and Lesaffre International exemplify scaled producers with fermentation expertise spanning multiple geographies. Puratos Group occupies a position serving consolidated national accounts through distributed production networks, while Lesaffre International anchors its market presence through yeast and starter culture research intensity. Among North American bakery brands, Dave's Killer Bread represents organic and whole-grain sourdough positioning, leveraging brand strength to command placement in natural grocery channels with above-category margin structures.
| Leading Market Players |
|---|
| IREKS GmbH |
| Boudin Bakery |
| Puratos Group |
| Gold Coast Bakeries |
| Truckee Sourdough Company |
| Lesaffre International |
| Ernst Böcker GmbH |
| Dave's Killer Bread |
| Lallemand Inc. |
| Others |
Supply Flow & Price Mechanics
Wheat and rye futures volatility cascades through the sourdough supply chain, compressing margins for small-to-mid bakeries lacking forward-contract coverage while concentrating pricing power with scaled producers who anchor long-term supply agreements with café chains. German craft bakeries leverage direct consumer relationships to justify substantial price premiums over supermarket equivalents, creating a bifurcated market where fermentation expertise commands margin protection.
Pricing Analysis
Volume absorption concentrates in food-service accounts where cost efficiency drives procurement, while margin capture peaks in bakery shops and direct-to-consumer channels. Three-tier pricing structure across premium artisan, standard industrial, and economy par-baked levels reflects certification grade and fermentation time disclosure. Cost compression in the standard tier is intensifying because grain price swings of 20-40% strain bakeries without hedging programs. Household consumers in natural grocery channels show lowest price sensitivity; institutional food-service buyers exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with three European biotechnology suppliers who control commercially viable wild yeast strains, creating bottleneck risk for new market entrants. Germany, France, and Italy anchor grain milling and starter culture production, while the United States concentrates café chain procurement and frozen dough manufacturing. The supply chain draws from wheat and rye commodities, fermentation monitoring equipment, and vacuum-sealing packaging technology. Tariff exposure on European grain imports threatens US-based artisan producers. Distribution runs through consolidated national buyers who negotiate directly with fermentation suppliers, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation monitoring systems are displacing legacy ambient-temperature proofing methods, creating a technology-transition window where IoT-enabled quality control separates scaled producers from craft competitors.
For Market Incumbents: Cement multi-year supply contract lock-ins with consolidating café chains before procurement power concentrates further among national buyers. Invest in certified organic grain sourcing to defend placement in natural grocery channels with above-category margin structures. Backward integration into regenerative farm certification pipelines addresses EU Green Deal agricultural targets and creates shelf-space premiums. For New Entrants and Emerging Players: Frozen sourdough subscription models offer a technology-first wedge into US coastal metropolitan markets where home bakers seek consistent starter quality without maintenance burden. Target gluten-free alternative grain formulations in North American and Australian channels where celiac awareness drives certified product demand. Deploy direct-to-consumer digital marketing to bypass retail slotting fees and capture recurring revenue. For Investors and Strategic Acquirers: The window for entry favors regional craft bakeries with documented traditional process certification and established direct consumer relationships. Long-term viability hinges on acquisition targets with locked-in starter culture supply agreements and proven fermentation expertise retention. Watch for EFSA regulatory tightening on "authentic sourdough" definitions as the inflection signal that will separate compliant from non-compliant production assets.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Supply Contract Lock-In | Café chain consolidation rewards scaled producers with fermentation R&D depth across German and US markets. |
| Certified Organic Grain Sourcing | USDA certification opens placement in natural grocery channels with premium margin structures. |
| IoT Fermentation Monitoring Deployment | Real-time pH and temperature data transmission compresses technical staffing at distributed plants. |
| Direct-to-Consumer Subscription Launch | Frozen sourdough models bypass retail slotting fees while building recurring revenue in metropolitan markets. |
| Traditional Process Documentation Investment | EU EFSA additive restrictions disqualify rapid-rise yeast adjuncts from clean-label claims. |
Methodological Framework
Multi-period observation of fermentation technology adoption rates and café chain procurement consolidation anchored the trend analysis, supplemented by interviews with master bakers, café procurement directors, and starter culture R&D leads at biotechnology suppliers. Secondary validation drew from EU EFSA additive restriction frameworks, USDA organic certification databases, FDA food safety guidance documents, and customs records on grain trade flows. Bottom-up segment sizing triangulated against top-down market value estimates.
Segment-weighting across product type, distribution channel, end user, and packaging format determined value allocation throughout the projection horizon. CAGRs were derived from modeled volume trajectories and price evolution assumptions across artisan, gluten-free, rye, and white sourdough categories. Forecast inputs incorporated EU Green Deal agricultural sustainability targets and FDA fermentation safety compliance timelines.
Several conditions sit outside the modeled scope, including extreme weather events affecting grain harvests, abrupt regulatory reclassification of starter cultures as novel ingredients, and pandemic-scale disruptions to food-service demand. Forecasts reflect documented assumptions about technology adoption curves and procurement consolidation rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Pizza Dough Balls Market
Bakery Products
Cake Base Discs Market
Bakery Products
Fondant Market
Bakery Products
Packaged Bread Market
Bakery Products
Diabetic Bakery Products Market
Bakery Products
Qatar Bakery Product Market
Bakery Products
Tunnel Bakery Oven Market
Bakery Products
Cookies Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
Bread Improver Market
Bakery Products
Global Cakes Market
Bakery Products
Vegan Baking Mix Market
Bakery Products
Bakers Yeast Market
Bakery Products
South America Ice Cream Market
Bakery Products
Specialty Bakery Market
Bakery Products
Low Fat Bran Muffins Market