
 Germany Countertop Ice Makers Market | 2026-2036
Germany Countertop Ice Makers Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Countertop Ice Makers Market Insights
Subscription-based filter replacement and descaling services is broadening what German countertop ice maker vendors actually sell beyond the hardware unit. Hegel Kältetechnik leverages its domestic manufacturing footprint to sustain rapid fulfillment for commercial kitchen operators. Wessamat anchors its position through specialized engineering for high-output bullet and nugget ice formats. Ziegra competes on modular system architecture that accommodates tight counter spaces in urban gastronomy settings.
Countertop ice makers are compact, self-contained refrigeration appliances that freeze water into discrete ice forms—typically bullet, nugget, or cube geometries—using compressor-driven vapor-compression cycles with integrated water reservoirs, operating at ambient temperatures between 10°C and 43°C with production capacities ranging from 10 to 150 kilograms per day. These units serve foodservice operators and residential consumers who require localized, on-demand ice generation without dedicated plumbing infrastructure. Portable units lead residential sales in German urban apartments where installation flexibility outweighs volume requirements. Energy Efficient technology captures growing attention as operators face escalating electricity tariffs and Ecodesign compliance deadlines. Smart-connected variants remain nascent but attract premium positioning among tech-forward restaurant chains.
Germany's Federal Ministry for Economic Affairs and Climate Action enforces Ecodesign Directive implementations through national ordinances that mandate minimum energy performance indices for refrigeration equipment. KBA-aligned product safety certifications and CE marking under EU machinery directives govern electrical and refrigerant containment standards for commercial deployment. Stakeholders must monitor forthcoming F-Gas Regulation phase-down schedules that will restrict hydrofluorocarbon refrigerants and accelerate compressor technology transitions.
Market Dynamics
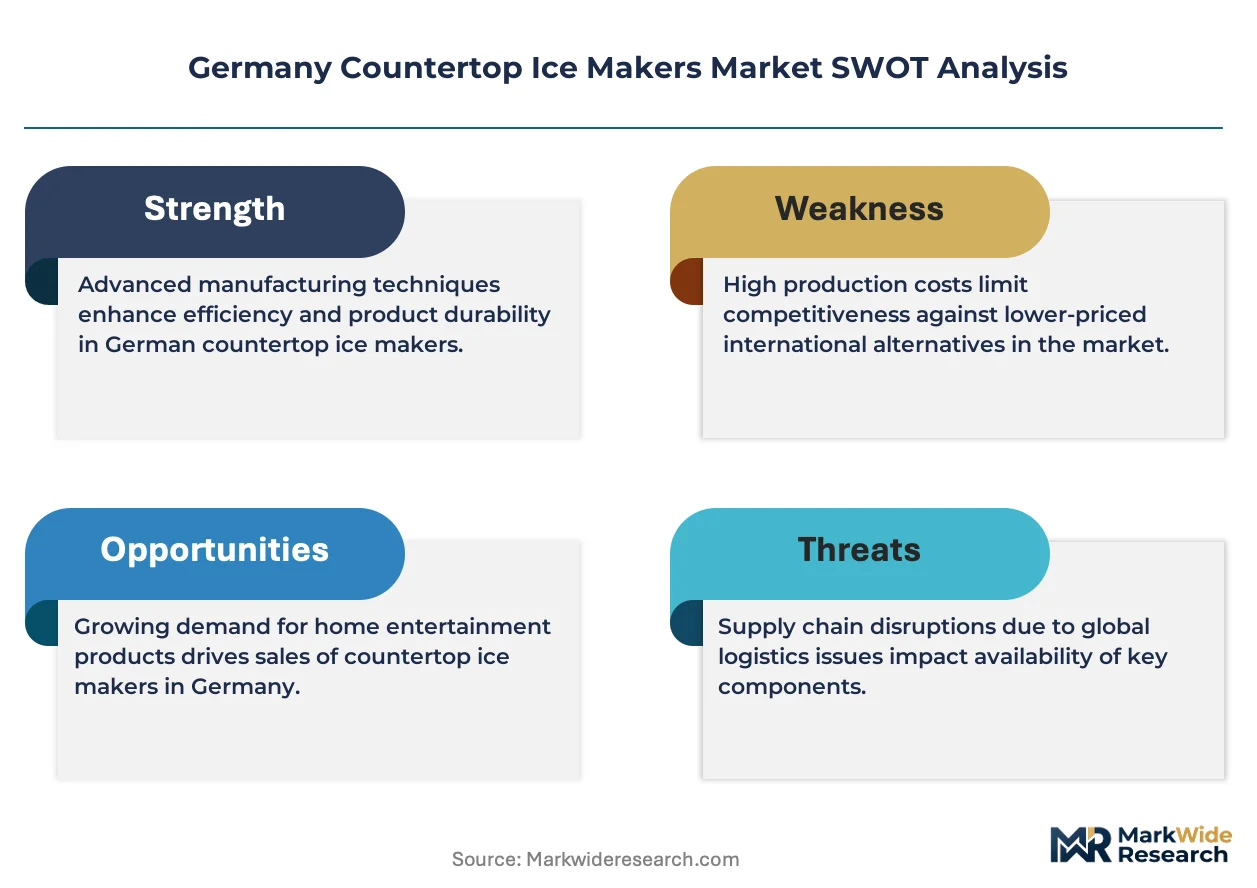
Germany's countertop ice maker sector faces structural pressure from the F-Gas Regulation phase-down, which forces refrigerant transitions and compressor redesigns ahead of Ecodesign Directive efficiency deadlines. Southern German gastronomy clusters drive volume concentration, while energy tariff volatility compresses operating margins for foodservice operators.
Growth Catalysts
- Berlin-Munich hospitality expansion:Small-format venues in these metropolitan clusters prioritize compact, plumbed-free ice production for flexible kitchen layouts.
- Ecodesign Directive efficiency thresholds:National ordinances from the Federal Ministry for Economic Affairs and Climate Action accelerate replacement cycles for aging refrigeration stock.
- Nugget ice format preference:Premium cocktail bars and specialty coffee chains specify chewable ice geometries that command higher equipment price points.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger materials face commodity price swings that compress manufacturer margins without corresponding pricing power.
- Compressor supply concentration:German OEMs depend on a narrow supplier base in Austria and northern Italy for variable-speed refrigeration compressors.
- HFC refrigerant phase-down friction:The F-Gas Regulation creates certification bottlenecks for hydrocarbon and CO₂ alternative systems.
Strategic Opportunities
- Rhineland-Palatinate wine tourism corridor:Vineyard restaurants and tasting rooms remain underpenetrated for on-premise ice production versus bottled alternatives.
- Filter subscription bundling:Aftermarket service contracts create recurring revenue streams that hardware-only vendors cannot capture.
- Heat pump convergence:Integration of ice maker waste heat recovery with building HVAC systems opens commercial kitchen energy optimization projects.
Industry Challenges
- Refrigeration technician shortage:Germany's dual vocational training pipeline produces insufficient F-Gas certified installers to match equipment deployment timelines.
- CE marking documentation burden:KBA-aligned safety certifications and machinery directive compliance create 4-6 month product launch delays for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Countertop Ice Makers Market |
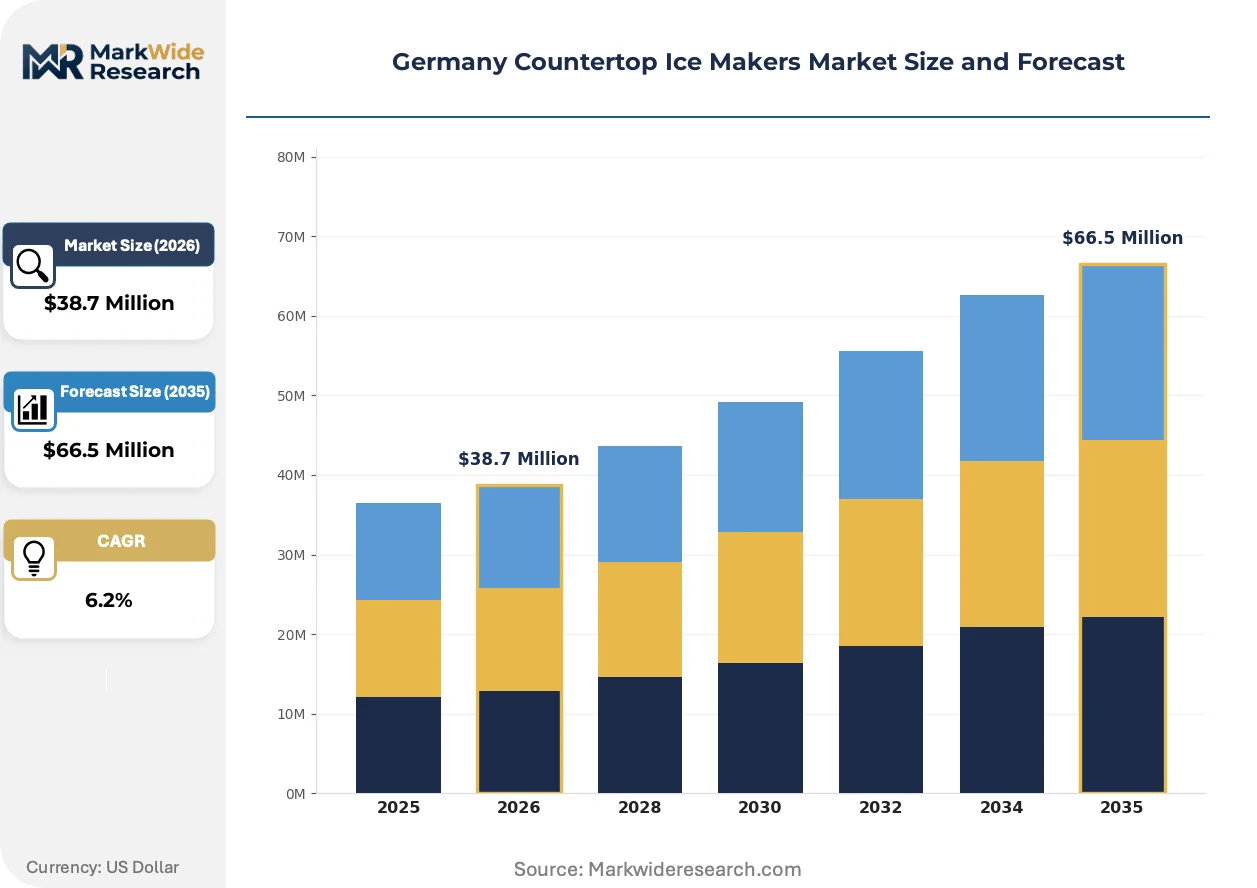
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $66.5 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Built-in, Undercounter, Commercial Technology: Manual, Automatic, Smart, Energy Efficient End User: Residential, Restaurants, Bars, Catering Services Installation: Freestanding, Countertop, Integrated, Custom Built |
| Companies Covered | Hegel Kältetechnik, Wessamat, Ziegra, Hoshizaki, Scotsman, Electrolux, Danfoss, Ecozy, ITV Ice Makers Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Countertop Ice Makers Market Trends and Innovations
Connected diagnostics and predictive maintenance capabilities are penetrating German commercial kitchen equipment, reshaping service relationships from break-fix to uptime-guarantee models. Three developments define current competitive positioning.
Sensor-enabled water quality monitoring is automating descaling cycles and filter replacement alerts. Mid-size restaurant chains in Hamburg and Stuttgart deploy these systems to reduce unplanned downtime. The technology is automating service dispatch decisions that previously required manual operator intervention.
The EU F-Gas Regulation's hydrofluorocarbon quotas tighten each production cycle. Equipment manufacturers accelerate hydrocarbon and transcritical CO₂ compressor trials. Southern German operators face the steepest compliance costs due to higher ambient temperature requirements.
Leasing and equipment-as-a-service contracts displace outright purchase for urban gastronomy startups. Berlin's dense restaurant ecosystem shows the fastest contract penetration. This model transfers capital burden to distributors while locking operators into multi-year filter and maintenance commitments.
Germany Countertop Ice Makers Market Segmentation
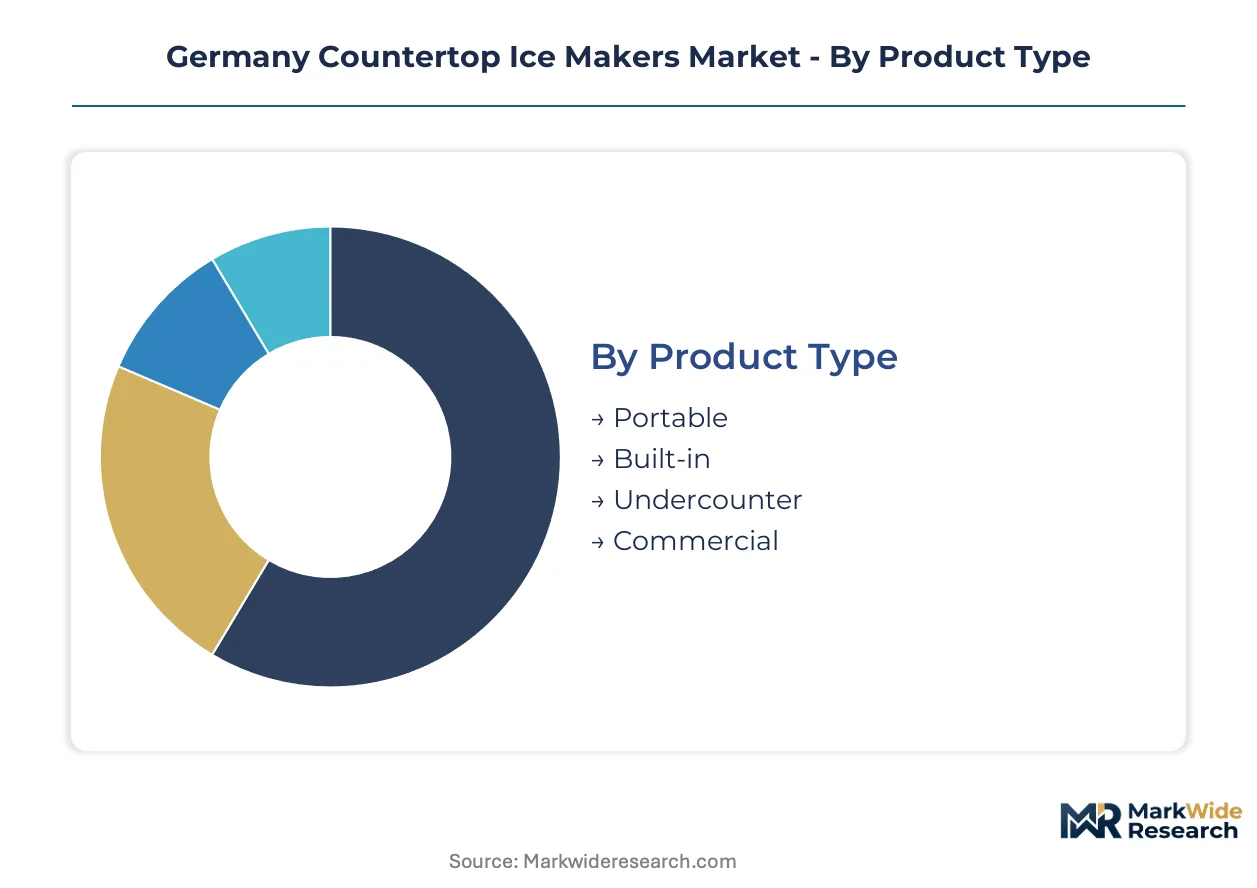
Countertop ice maker procurement in Germany diverges sharply across operator scale and technical sophistication. Equipment specification reflects kitchen footprint constraints, Ecodesign compliance deadlines, and ice format requirements that vary by beverage program complexity.
Product Type:
Operator mobility requirements and plumbing infrastructure availability separate buyers into distinct hardware categories.
- Portable:Self-contained units with manual water filling and no drainage connection dominate Berlin and Munich apartment kitchens where installation flexibility outweighs daily volume needs. Operators in temporary pop-up venues and food trucks favor these units for rapid deployment without building modifications.
- Built-in:Cabinet-integrated systems with dedicated water lines serve permanent installations in restaurant chains and hotel breakfast operations. Southern German gastronomy clusters in Stuttgart and Frankfurt specify these for seamless counter aesthetics and higher daily throughput.
- Undercounter:Floor-mounted units with front ventilation suit compact commercial kitchens with limited vertical space.
- Commercial:High-capacity modular systems with remote condensing options target institutional foodservice and event catering operations.
Volume sits with Built-in installations; growth tilts toward Portable units as small-format hospitality expands.
Technology:
Automation level and connectivity integration determine capital outlay and operating cost trajectories for German buyers.
- Energy Efficient:Variable-speed compressors and optimized heat exchangers meet Ecodesign Directive thresholds enforced by the Federal Ministry for Economic Affairs and Climate Action. Restaurant operators facing electricity tariff volatility prioritize these units for lifecycle cost control despite 15-20% purchase premiums.
- Smart:WiFi-enabled diagnostics and automated descaling alerts attract tech-forward chains in Hamburg and Cologne seeking predictive maintenance capabilities. The segment commands premium positioning though penetration remains limited to early adopters.
- Manual:Basic electromechanical controls without automated cycles serve price-sensitive residential buyers.
- Automatic:Timer-based production scheduling without connectivity bridges mid-market commercial needs.
Revenue concentrates in Energy Efficient variants; Smart systems are gaining share fastest among multi-location operators.
End User:
Ice consumption patterns and quality specifications vary substantially across buyer categories.
- Restaurants:Full-service establishments in Bavaria and Baden-Württemberg require consistent cube or nugget output for beverage programs. KBA-aligned safety certifications and CE marking under EU machinery directives govern procurement specifications for these commercial deployments.
- Bars:Premium cocktail venues specify chewable nugget ice and rapid recovery cycles for high-peak service. Berlin's dense bar ecosystem drives concentrated demand for compact, high-output units with specialized ice geometries.
- Residential:Urban apartment dwellers prioritize footprint and noise levels over production speed.
- Catering Services:Mobile event operators need transportable units with generator compatibility.
Restaurants generate the largest installed base; Bars show the steepest expansion trajectory as specialty beverage culture deepens.
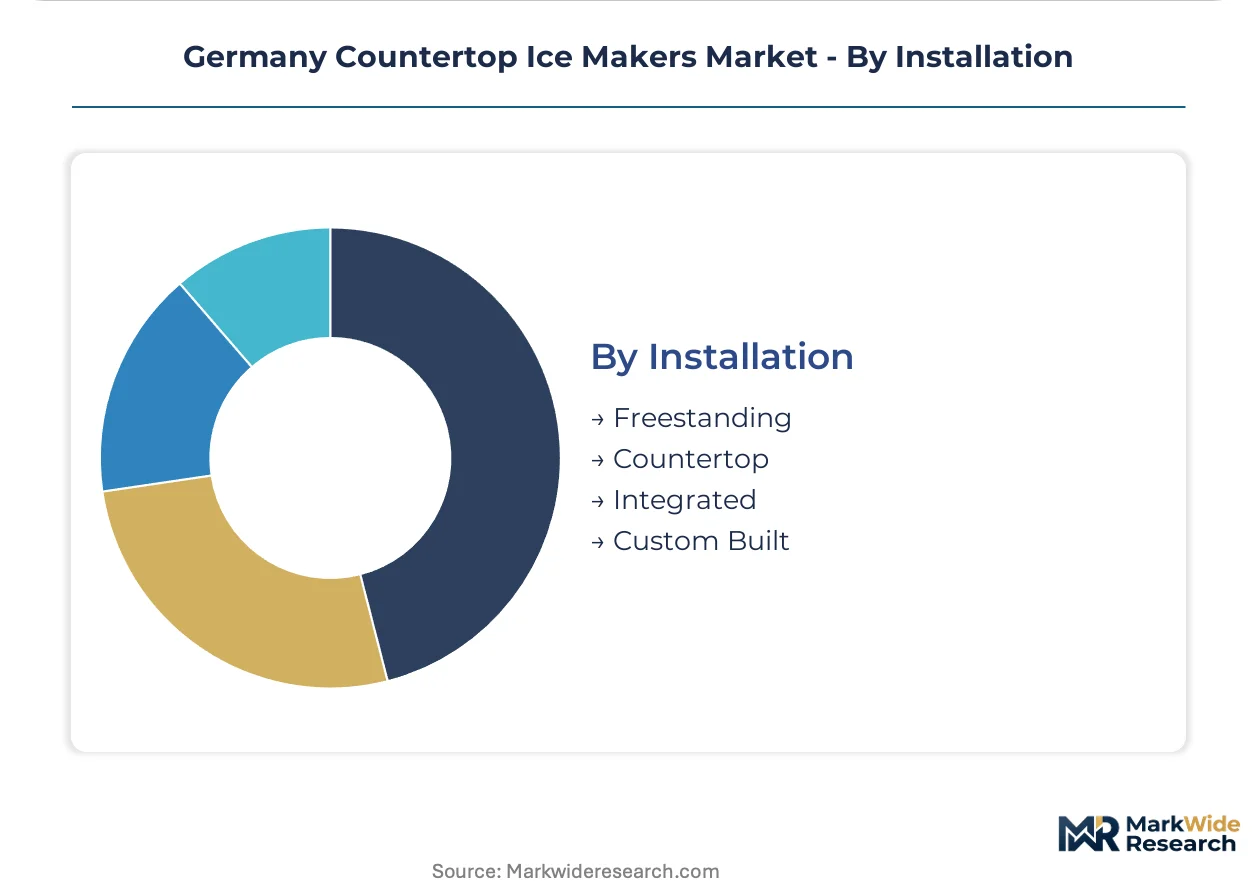
Installation:
Physical integration requirements and permanence of placement shape specification decisions.
- Countertop:Surface-mounted units with rear or side ventilation dominate urban gastronomy where lease terms preclude structural modifications. Munich's small-format venue expansion sustains demand for these plug-and-produce configurations.
- Freestanding:Portable placement with caster mobility serves temporary and seasonal operations in Rhineland-Palatinate wine tourism corridors.
- Integrated:Flush-mounted within custom millwork suits high-end hotel and corporate dining installations.
- Custom Built:Bespoke dimensions and finish matching target luxury hospitality developments.
Countertop configurations hold the greatest deployment volume; Integrated systems are climbing fastest in premium hotel renovations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German countertop ice maker production concentrates in southern industrial corridors while consumption spreads across metropolitan hospitality clusters. Manufacturing capacity clusters near Stuttgart and Munich, where refrigeration component suppliers and compressor technology firms maintain dense supplier networks. Demand absorption follows restaurant density and tourism traffic patterns rather than production geography.
Bavaria
Munich's small-format venue expansion drives concentrated demand for compact, plumbed-free ice production units. The Federal Ministry for Economic Affairs and Climate Action enforces Ecodesign Directive thresholds that accelerate replacement cycles for aging refrigeration stock in Nuremberg foodservice operations. The Munich-Stuttgart gastronomy corridor sustains premium equipment procurement as cocktail bar density and specialty coffee chains multiply.
North Rhine-Westphalia
Cologne and Düsseldorf restaurant operators prioritize energy-efficient variants to manage electricity tariff volatility in commercial kitchens. KBA-aligned safety certifications and CE marking under EU machinery directives govern procurement specifications for these deployments. The Rhineland industrial belt supports component manufacturing while Düsseldorf's dense bar ecosystem commands specialized nugget ice geometries.
Baden-Württemberg
Stuttgart's automotive-adjacent precision manufacturing culture translates into exacting equipment specifications for commercial kitchen operators. The F-Gas Regulation phase-down forces refrigerant transitions and compressor redesigns ahead of efficiency deadlines. The Stuttgart-Heidelberg restaurant cluster exhibits steepest adoption of smart-connected diagnostics among tech-forward multi-location operators.
Berlin-Brandenburg
Berlin's dense restaurant ecosystem shows fastest penetration of leasing and equipment-as-a-service contracts for urban gastronomy startups. National energy labeling requirements tighten efficiency thresholds that reshape procurement decisions in Potsdam hospitality developments. The capital's pop-up venue culture sustains portable unit demand where installation flexibility outweighs daily volume requirements.
Hamburg
Hamburg's port-adjacent logistics infrastructure supports rapid fulfillment for commercial kitchen equipment distributors serving northern German markets. The Ecodesign Directive's minimum energy performance indices mandate variable-speed compressor adoption in Elbe riverfront hotel renovations. The city's mid-size restaurant chains deploy sensor-enabled water quality monitoring to automate descaling cycles and reduce unplanned downtime.
Germany Countertop Ice Makers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across distinct capability tiers in German refrigeration equipment. Domestic manufacturing footprints sustain rapid fulfillment advantages for commercial kitchen operators facing tight deployment timelines. Three strategic archetypes define positioning: integrated refrigeration specialists with captive component production, modular system architects optimizing for spatial constraints, and scale-driven international brands leveraging global supply chains. Competitive moves concentrate on geographic expansion into underpenetrated wine tourism corridors and backward integration into compressor technology to secure supply continuity.
Within the domestic specialist tier, Hegel Kältetechnik and Wessamat anchor differentiated positioning through engineering depth and format specialization. Hegel Kältetechnik exemplifies the integrated manufacturer archetype with its German production footprint enabling rapid response to commercial operator requirements. Wessamat occupies a position emphasizing specialized ice format engineering for high-output bullet and nugget geometries. Ziegra represents the modular system architect archetype, competing on configurable architectures that accommodate tight counter spaces in urban gastronomy settings. These three firms collectively illustrate how domestic engineering capabilities translate into sustained positioning against international scale players.
| Leading Market Players |
|---|
| Hegel Kältetechnik |
| Wessamat |
| Ziegra |
| Hoshizaki |
| Scotsman |
| Electrolux |
| Danfoss |
| Ecozy |
| ITV Ice Makers Inc. |
| Others |
Pricing and Supply Chain Analysis
Small-format hospitality operators in Berlin and Munich concentrate procurement decisions, locking the market into subscription-tied hardware pricing that bundles filter services with equipment leases. This buyer concentration forces manufacturers to absorb commodity volatility while competing on lifecycle cost guarantees rather than upfront unit margins.
Pricing Analysis
Margin tightening in mid-tier equipment reflects copper and aluminum heat exchanger cost swings that manufacturers cannot pass through to price-sensitive urban gastronomy startups. Three-tier pricing structure across premium, standard, and economy levels separates Ecodesign-certified variable-speed units from basic electromechanical models, with smart-connected variants commanding placement premiums. Pricing pressure intensifies as electricity tariff volatility shifts buyer focus toward total cost of ownership calculations. Residential apartment dwellers exhibit highest price sensitivity, while premium cocktail bars prioritize ice format quality over capital outlay.
Supply Chain Analysis
Workforce availability constraints in Austria and northern Italy compressor manufacturing clusters constrain German OEM output timelines. Component supply draws from Austrian variable-speed compressor specialists, Italian heat exchanger fabricators, and domestic Stuttgart-area refrigeration controller assembly. Aluminum and copper sourcing faces commodity price volatility risk without long-term offtake hedging. Distribution runs through Hamburg port-adjacent logistics hubs serving northern German commercial kitchen equipment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German countertop ice maker consolidation accelerates as F-Gas Regulation compliance costs eliminate sub-scale engineering capabilities. The Ecodesign Directive threshold enforcement compresses margins for manufacturers lacking captive compressor technology or modular system architectures.
For Market Incumbents: Anchor market position through backward integration into hydrocarbon and transcritical CO₂ compressor trials, securing supply continuity ahead of refrigerant phase-down deadlines. Invest in KBA-aligned certification pipelines to accelerate product launch timelines against international scale competitors. Defend against leasing-model disruptors by bundling predictive maintenance capabilities that transfer uptime risk from operators to manufacturers. For New Entrants and Emerging Players: Begin with Rhineland-Palatinate wine tourism corridor penetration, where vineyard restaurants and tasting rooms remain dependent on bottled ice alternatives. Target portable unit specifications for Berlin pop-up venue operators prioritizing installation flexibility over daily throughput. Pursue equipment-as-a-service contract structures that transfer capital burden to distributors while capturing multi-year filter and maintenance commitments. For Investors and Strategic Acquirers: The window for entry favors modular system architects with configurable architectures addressing tight urban gastronomy counter spaces. Long-term viability hinges on acquisition targets possessing F-Gas certified technician training pipelines or proprietary heat pump convergence intellectual property. Watch for refrigerant transition bottlenecks as inflection indicator for distressed asset availability among compliance-lagged competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Technology | Austrian and northern Italian supplier concentration creates single-source vulnerability for German OEMs. |
| Filter Subscription Bundling | Recurring revenue streams from aftermarket services displace hardware-only margin capture. |
| Ecodesign Certification Pipeline Investment | KBA-aligned safety documentation accelerates product launches against 4-6 month compliance delays. |
| Heat Pump Convergence Development | Integration of waste heat recovery with building HVAC systems opens commercial kitchen energy optimization projects. |
| Wine Tourism Corridor Geographic Expansion | Rhineland-Palatinate vineyard restaurants remain underpenetrated versus metropolitan hospitality clusters. |
Research Methodology
Document review covered Federal Ministry for Economic Affairs and Climate Action ordinances, KBA safety certification databases, and EU F-Gas Regulation implementation schedules, complemented by interviews with commercial kitchen equipment distributors, restaurant chain procurement directors, and refrigeration technician training program administrators. Secondary validation drew from Ecodesign Directive compliance filings, CE marking documentation, and southern German gastronomy cluster expansion permits. Bottom-up equipment deployment estimates triangulated against top-down hospitality sector refrigeration spend analysis.
Installed base projections and revenue forecasts emerged from segmented modeling across product type, technology tier, end-user vertical, and installation configuration dimensions throughout the forecast period. CAGRs derived from replacement cycle analysis tied to Ecodesign Directive efficiency threshold enforcement and F-Gas Regulation refrigerant transition timelines. Compressor supply concentration indices and electricity tariff volatility scenarios informed margin compression sensitivity testing.
Refrigerant phase-down acceleration, copper and aluminum commodity spikes, and technician certification pipeline bottlenecks are the dominant revision risks to deployment timelines. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and hospitality sector capital expenditure continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Commercial Panini Grills Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Freestanding Large Cooking Appliance Market
Food Service Equipment
Commercial Foodservice Equipment Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Commercial Ice Equipment and Supplies Market
Food Service Equipment
Back Bar Coolers Market
Food Service Equipment
Commercial Kitchen Knife Market
Food Service Equipment
Commercial Griddles and Flat Top Grills Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
Beverage Refrigeration Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Global Roti Maker Market
Food Service Equipment
Commercial Cookers Market