
 Cookie Dropper Machine Market | 2026-2036
Cookie Dropper Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Cookie Dropper Machine Market Analytics
Specialty equipment distribution is tilting toward integrated foodservice solution providers rather than standalone machinery dealers. POLIN sustains strong positioning through its heritage in industrial baking systems and European manufacturing footprint. Bralyx differentiates via concentrated R&D in compact depositor designs for artisan producers. Electrolux Professional leverages its broad commercial kitchen portfolio to bundle cookie droppers within full-line bakery installations.
A cookie dropper machine is a precision portioning device that extrudes, deposits, or cuts consistent dough weights onto baking surfaces, typically achieving tolerances within two grams and operating at speeds exceeding 200 cycles per minute in industrial configurations. The equipment serves commercial bakeries and food manufacturers seeking uniform product geometry, reduced waste, and labor automation in high-volume cookie, biscuit, and confectionery production. Automatic pneumatic systems dominate throughput-intensive installations where continuous operation and minimal operator intervention prove critical, while semi-autlectric configurations occupy the mid-market by balancing capital efficiency with programmable recipe flexibility. Robotic deposition technology represents the fastest-expanding segment as vision-guided systems enable complex shape patterns and rapid changeover between SKUs.
The FDA's Food Safety Modernization Act mandates sanitary design principles for food-contact surfaces, directly influencing stainless steel specifications and clean-in-place architecture in equipment sold to US bakeries. The EU Machinery Directive and CE marking requirements enforce interlock standards and ergonomic safety protocols that shape control panel layouts and guarding systems across European supply chains. ISO 22000 food safety management certification increasingly functions as a market access prerequisite for manufacturers targeting multinational food processors. Stakeholders must monitor evolving allergen control regulations and energy efficiency benchmarks as these criteria increasingly filter procurement decisions and equipment replacement cycles.
Market Dynamics
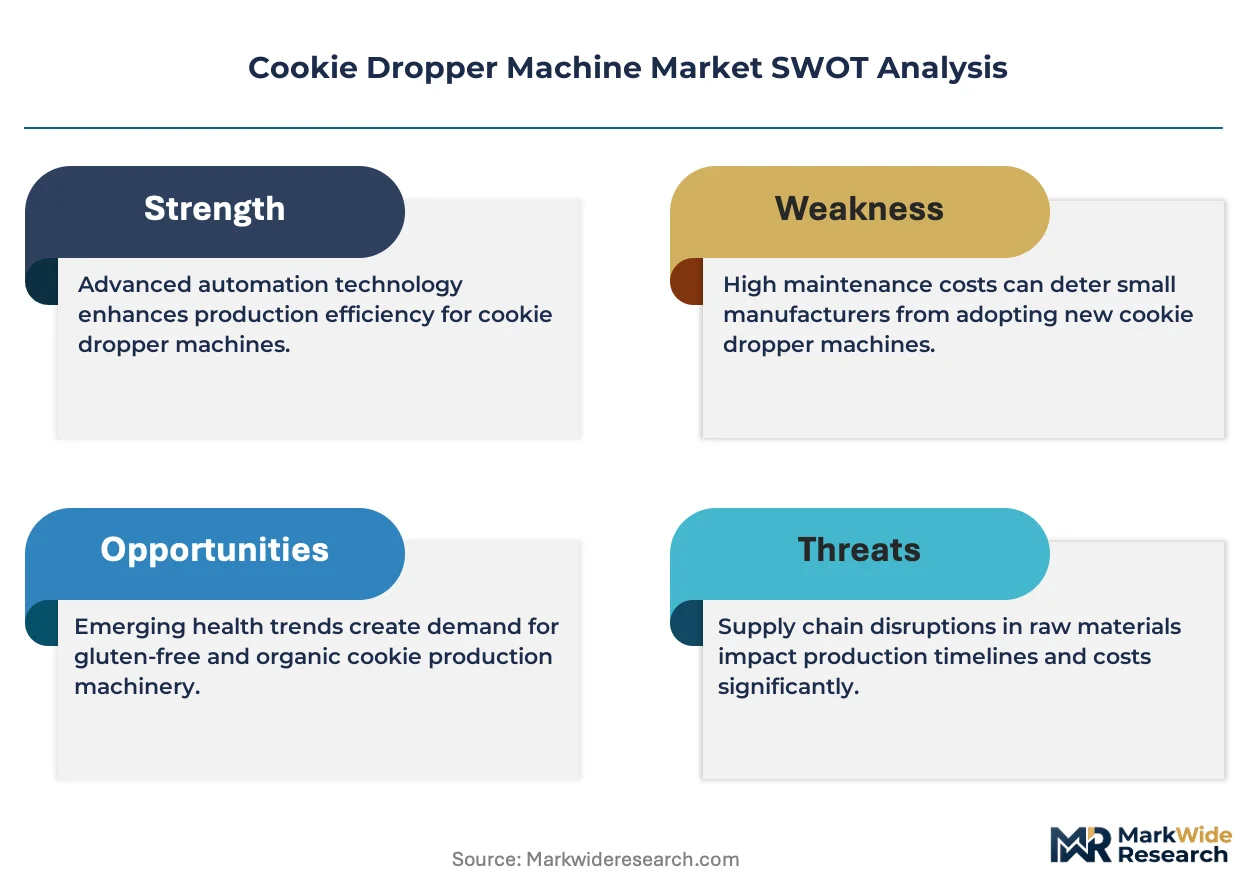
Sanitary design mandates from the FDA and EU Machinery Directive are forcing capital-intensive equipment upgrades across commercial baking operations, compressing replacement cycles and favoring stainless steel architectures with clean-in-place capabilities.
Growth Catalysts
- Clean-label production mandates:Artisan bakeries in Germany and the United States require automated portioning to eliminate manual handling contamination risks while maintaining batch traceability.
- FSMA sanitary design enforcement:The FDA's Food Safety Modernization Act mandates specific stainless steel grades and sloped surfaces for food-contact equipment, accelerating replacement of legacy aluminum-depositor installations.
- Robotic vision integration:Vision-guided deposition systems enable rapid SKU changeover for seasonal cookie varieties, attracting specialty manufacturers seeking flexible automation without dedicated lines.
Market Restraints
- Stainless steel input volatility:Grade 316L stainless steel price swings compress equipment margins and extend quotation validity periods for European manufacturers.
- Pneumatic component supply concentration:Precision servo motors and pneumatic valves concentrate among German and Japanese suppliers, exposing lead time risks for North American equipment assemblers.
- Manual bench-top substitution:Small-scale artisan producers in emerging markets retain hand-scooping methods for batch sizes below 50 kilograms, capping addressable market penetration.
Strategic Opportunities
- India artisan bakery automation:FSSAI food safety standard harmonization and PLI scheme incentives create first-mover positioning for compact semi-automatic depositors in Mumbai and Bangalore clusters.
- Cloud-connected predictive maintenance:IoT-enabled deposition systems with remote diagnostics command service-contract premiums and reduce unplanned downtime for 24-hour industrial operations.
- EU Green Deal energy retrofit incentives:Member-state subsidies for energy-efficient equipment upgrades accelerate replacement of pneumatic systems with electric servo-driven alternatives in France and Italy.
Industry Challenges
- Mechatronics technician scarcity:Servo calibration and vision system programming skills lag equipment complexity, extending commissioning timelines and forcing manufacturer-led training investments.
- ISO 22000 certification timelines:Multinational food processors require 12-18 month validation cycles for new equipment vendors, freezing market access for unproven entrants.
- Legacy line integration complexity:Retrofitting robotic depositors into 1990s-era tunnel oven configurations demands custom mechanical interfaces and control system bridging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cookie Dropper Machine Market |
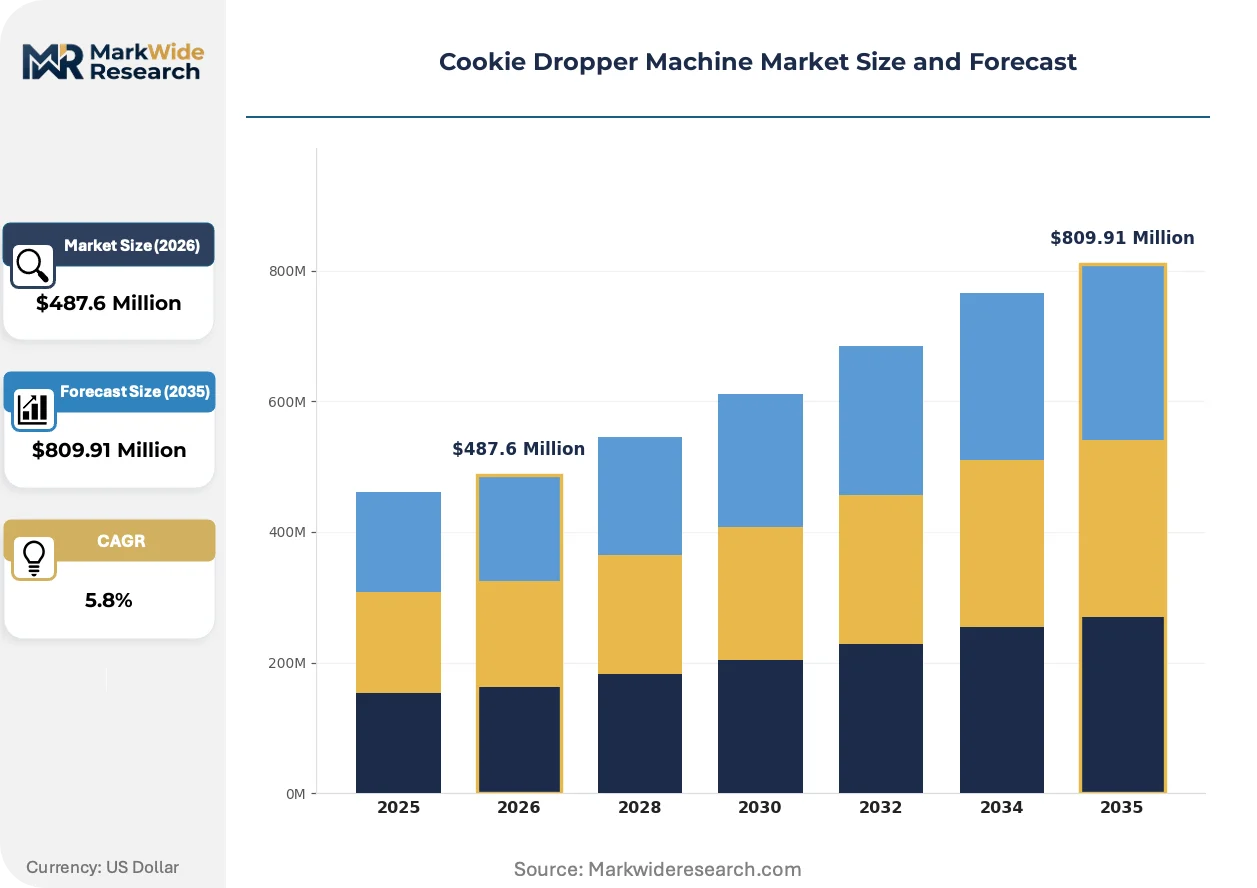
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Robotic End User: Bakeries, Restaurants, Cafes, Food Processors Technology: Pneumatic, Electric, Hydraulic, Mechanical Size: Small, Medium, Large, Industrial |
| Companies Covered | Bralyx, POLIN, Erika Baking Equipment, Electrolux Professional, Porlanmaz, Wilton Brands, Silikomart, Nordic Ware, PME Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cookie Dropper Machine Market Evolving Landscape
Deposition technology is collapsing the trade-off between throughput flexibility and portion precision, enabling industrial bakeries to run multiple SKUs on shared lines without mechanical changeover downtime.
Vision-guided robotic deposition is collapsing the traditional separation between high-speed dedicated lines and flexible artisan production. Specialty cookie manufacturers in the United States deploy six-axis robotic arms with 3D dough profiling to execute complex holiday shapes at 180 cycles per minute. This convergence eliminates the capital redundancy of maintaining separate equipment for standard and decorative product runs.
The EU Machinery Directive's 2023 update to interlock and ergonomic safety protocols forces redesign of guarding systems and HMI panel positioning. Equipment vendors serving France and Germany now integrate light-curtain safety systems as standard rather than optional configurations. Mid-market bakeries respond by prioritizing CE-marked machines over non-certified alternatives regardless of price differential.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts. Large food manufacturers in Germany negotiate component-level service agreements directly with servo motor and pneumatic valve suppliers, bypassing original equipment manufacturer service networks. This disintermediation compresses service margins for machinery vendors while accelerating response times for critical downtime events.
Cookie Dropper Machine Market Segmentation
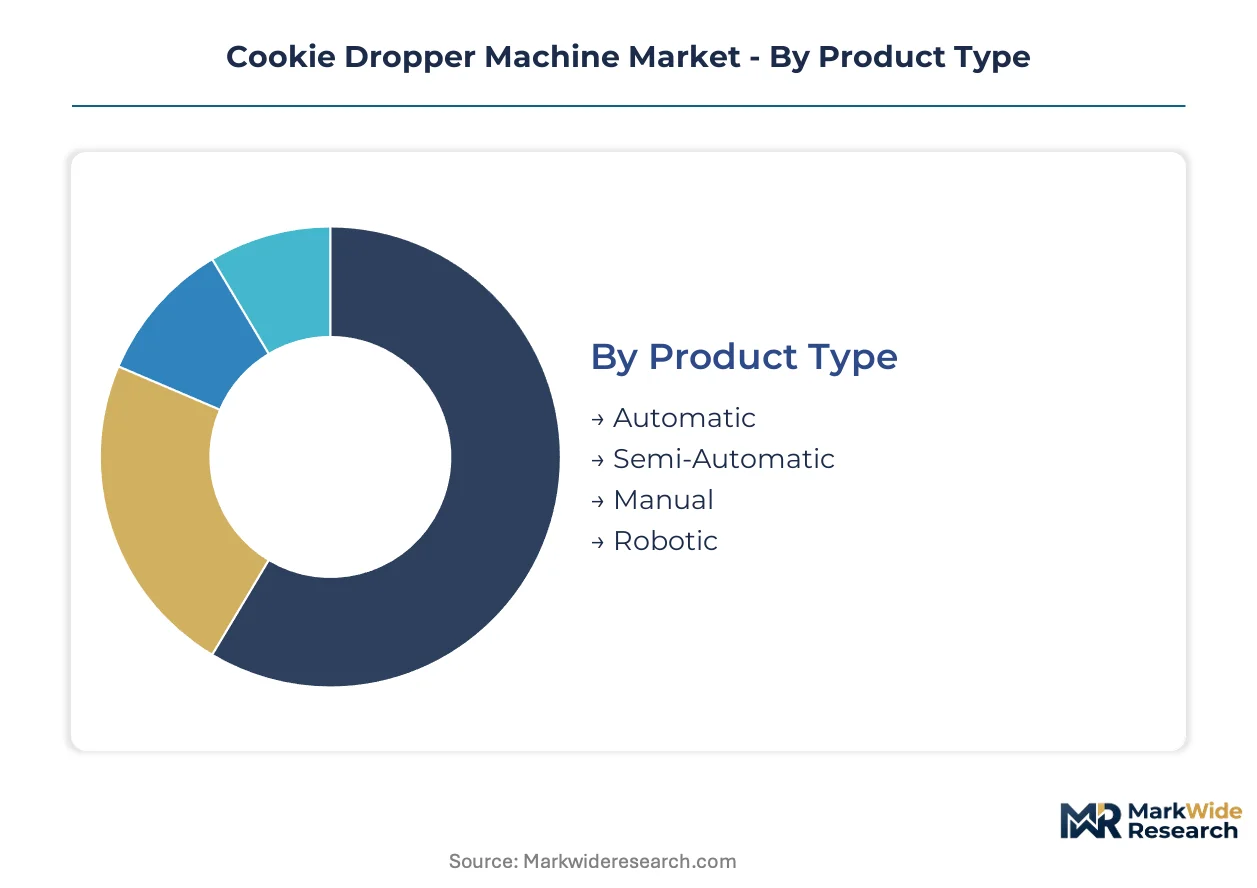
Segmentation in the cookie dropper machine market reveals distinct equipment specifications across production scales, with technology choices and size configurations directly determining throughput ceilings and regulatory compliance pathways for end users.
Product Type:
Mature pneumatic architectures dominate high-throughput installations while emerging robotic platforms reshape flexibility expectations.
- Automatic:Continuous-cycle pneumatic systems achieve speeds exceeding 200 cycles per minute with minimal operator intervention. Industrial bakeries in Germany's baking corridor deploy these for 24-hour operations where labor costs and FSMA sanitary mandates drive capital allocation toward clean-in-place stainless architectures.
- Robotic:Six-axis vision-guided deposition enables complex shape patterns and sub-60-second SKU changeover. Specialty manufacturers in the United States adopt these systems to collapse the redundancy of maintaining separate lines for standard and seasonal decorative runs.
- Semi-Automatic:Programmable recipe flexibility balances capital efficiency for mid-market artisan producers.
- Manual:Bench-top scooping persists in emerging markets for batch sizes below 50 kilograms.
Automatic systems handle the majority of throughput; Robotic is the fastest mover on share.
End User:
Customer type stratification follows volume thresholds and regulatory exposure, with food processors facing the most stringent certification requirements.
- Food Processors:Multinational operations demand ISO 22000-certified equipment with 12-18 month validation cycles. These buyers negotiate component-level service agreements directly with servo motor and pneumatic valve suppliers, bypassing OEM service networks.
- Bakeries:Artisan and industrial bakeries in North America and Western Europe scale automated portioning to meet clean-label production mandates while maintaining batch traceability.
- Restaurants:Front-of-house dessert preparation drives compact footprint requirements.
- Cafes:Limited production volumes favor semi-automatic configurations with rapid recipe switching.
Food Processors command the highest equipment specifications; Bakeries represent the broadest addressable base.
Technology:
Actuation method selection hinges on energy efficiency benchmarks and precision tolerances, with electric servo systems gaining traction under EU Green Deal retrofit incentives.
- Pneumatic:Compressed-air systems deliver consistent extrusion force for high-viscosity doughs. French and Italian industrial bakeries accelerate replacement of these systems with electric alternatives to capture member-state subsidies for energy-efficient upgrades.
- Electric:Servo-driven deposition achieves tighter weight tolerances within two grams and reduces energy consumption versus pneumatic equivalents. The EU Machinery Directive's ergonomic safety protocols favor electric actuation for reduced noise exposure.
- Hydraulic:High-force applications for dense cookie doughs require specialized maintenance protocols.
- Mechanical:Cam-driven systems persist in legacy installations with limited IoT connectivity.
Pneumatic technology retains installed base dominance; Electric actuation is expanding most quickly in European replacement cycles.
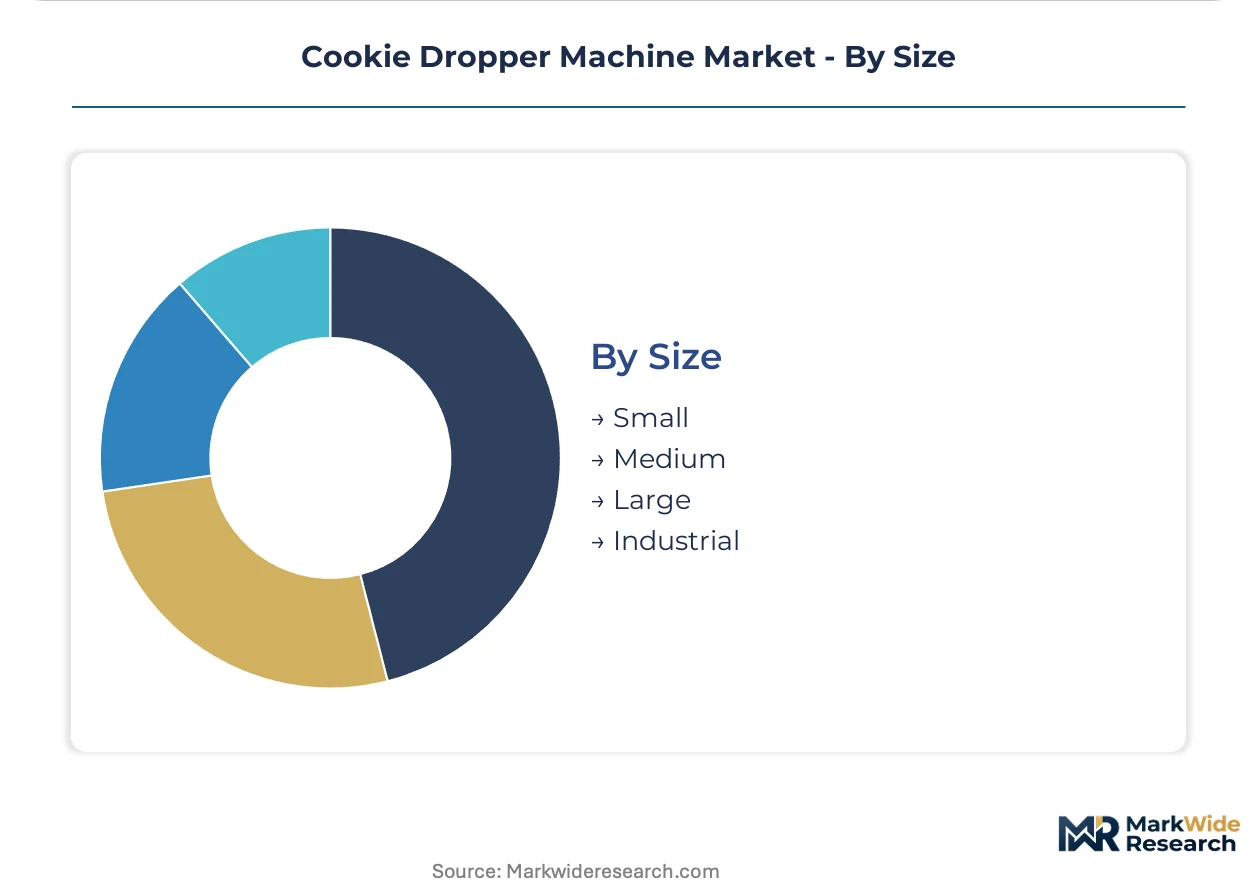
Size:
Equipment footprint correlates with production batch minimums and facility constraints, with industrial-scale machines requiring dedicated line integration engineering.
- Industrial:Tunnel oven-integrated configurations demand custom mechanical interfaces and control system bridging for 1990s-era production lines. These systems anchor capacity planning for Germany's industrial baking corridor and the United States' specialty cookie manufacturing belt.
- Large:Standalone floor units serve regional bakery chains with multi-shift operations and centralized commissary models.
- Medium:Compact designs from Bralyx target artisan producers in Mumbai and Bangalore clusters where FSSAI standard harmonization creates first-mover positioning.
- Small:Countertop depositors occupy niche applications for pilot production and R&D facilities.
Industrial size commands the premium pricing tier; Medium units are gaining share fastest in emerging market automation waves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment commands pricing premiums against United States alternatives due to tighter CE marking compliance costs and heritage brand positioning. Indian and Chinese manufacturers undercut both on base hardware while sacrificing service network density. This asymmetry shapes procurement patterns across four distinct national markets.
United States
Specialty cookie manufacturers in Chicago and Philadelphia drive automated portioning demand for seasonal SKU flexibility. FDA Food Safety Modernization Act enforcement accelerates replacement of legacy aluminum depositors with 316L stainless architectures. The Pennsylvania Dutch baking corridor anchors industrial-scale installations serving national retail chains.
Germany
Artisan bakeries in Munich and Hamburg scale compact depositors to meet clean-label production mandates without manual handling contamination risks. EU Machinery Directive interlock standards force redesign of guarding systems and HMI panel positioning. The industrial baking corridor between Hanover and Magdeburg concentrates 24-hour pneumatic system deployments.
India
FSSAI food safety standard harmonization triggers automation waves among Mumbai and Bangalore artisan clusters. PLI scheme incentives for manufacturing equipment reduce capital barriers for semi-automatic depositor adoption. Compact footprint designs from specialized vendors capture first-mover positioning in these emerging production hubs.
Italy
EU Green Deal member-state subsidies accelerate replacement of pneumatic systems with electric servo-driven alternatives in Turin and Bologna bakeries. Energy efficiency benchmarks increasingly filter procurement decisions for equipment replacement cycles. The Emilia-Romagna confectionery belt leads continental adoption of vision-guided robotic deposition for complex holiday shapes.
France
CE marking requirements and ergonomic safety protocols from the 2023 EU Machinery Directive update reshape control panel layouts across Lyon and Lille installations. Light-curtain safety systems integrate as standard rather than optional configurations. Mid-market bakeries prioritize certified machines over non-certified alternatives regardless of price differential.
Cookie Dropper Machine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in pneumatic valves and servo motors. The vendor base stratifies across three tiers: heritage European manufacturers with full-line bakery portfolios, mid-market specialists in compact artisan equipment, and Asian fabricators competing on base hardware cost. Consolidation pressure concentrates among mid-market players as multinational food processors negotiate direct component-level service agreements. Two dominant competitive moves define current positioning: geographic expansion into Indian automation waves and technology licensing for cloud-connected predictive maintenance capabilities.
Within the heritage industrial tier, POLIN exemplifies European manufacturing footprint advantages and full-system integration capabilities. Bralyx occupies a specialist position concentrated in compact depositor designs for artisan-scale producers. Electrolux Professional anchors the platform-integrator archetype through commercial kitchen portfolio breadth enabling bundled bakery installations. These three represent distinct strategic postures without implying specific market share or revenue claims.
| Leading Market Players |
|---|
| Bralyx |
| POLIN |
| Erika Baking Equipment |
| Electrolux Professional |
| Porlanmaz |
| Wilton Brands |
| Silikomart |
| Nordic Ware |
| PME Ltd |
| Others |
Value Network & Pricing Analysis
Grade 316L stainless steel mills in Germany and Japan anchor upstream material costs, concentrating margin capture with specialized foundries while compressing equipment assemblers' pricing flexibility. This feedstock concentration forces downstream vendors to absorb volatility or extend quotation validity periods, reshaping how pneumatic and electric actuator tiers compete on landed cost.
Pricing Analysis
Configured-to-order pricing for tunnel oven-integrated industrial units commands premiums of 35-50% above standard floor models, reflecting custom mechanical interfaces and control system bridging requirements. Pricing stratifies across CE-certified premium tiers, FSMA-compliant stainless architectures, and non-certified economy alternatives. Cost compression in mid-market pneumatic configurations is intensifying because Asian fabricators undercut European heritage brands on base hardware. Food processors with ISO 22000 mandates exhibit lowest price sensitivity, while emerging market artisan bakeries in India negotiate aggressively on compact semi-automatic units.
Supply Chain Analysis
Precision servo motors and pneumatic valves draw from concentrated supplier bases in Germany and Japan, creating single-source vulnerability for North American equipment assemblers. Raw material dependencies center on 316L stainless steel, food-grade pneumatic tubing, and vision system optical components. Tariff exposure runs through transatlantic component shipments for European vendors serving United States bakeries. Distribution runs through integrated foodservice solution providers rather than standalone machinery dealers, with aftermarket service increasingly disintermediated by direct component supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against manual bench-top scooping methods that retain 40-50% cost advantages for batch sizes below 50 kilograms. Incumbents must automate value propositions beyond throughput alone to justify capital premiums.
For Market Incumbents: Pre-empt Asian cost competition by embedding cloud-connected predictive maintenance capabilities that command service-contract premiums and lock in 24-hour industrial operations. Consolidate component-level service agreements before multinational food processors bypass OEM networks entirely. Vertical integration into servo motor calibration capabilities defends against mechatronics technician scarcity extending commissioning timelines.
For New Entrants and Emerging Players: Establish a beachhead in India's Mumbai and Bangalore artisan clusters where FSSAI harmonization and PLI scheme incentives reduce capital barriers for compact semi-automatic depositors. Target mid-market bakeries seeking programmable recipe flexibility without industrial-scale throughput requirements. Lead with rapid installation and commissioning capabilities to exploit incumbent technician bottlenecks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-market specialists holding concentrated R&D positions in compact depositor designs. Five-to-ten year viability hinges on robotic vision integration capabilities displacing pneumatic legacy installed bases. Watch EU Green Deal member-state subsidy disbursement velocity as inflection indicator for electric servo-driven replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Vision Integration | Vision-guided deposition enables sub-60-second SKU changeover for seasonal cookie manufacturers. |
| Cloud-Connected Predictive Maintenance | IoT-enabled systems reduce unplanned downtime for 24-hour German industrial baking corridor operations. |
| CE Marking and FSMA Compliance Investment | Stainless steel sanitary design certification unlocks multinational food processor procurement pipelines. |
| Compact Depositor Geographic Expansion | Footprint-optimized designs capture first-mover positioning in India's emerging automation clusters. |
| Component-Level Service Agreement Bypass | Direct servo motor supplier relationships accelerate response times for critical downtime events. |
Research Methodology
The analysis maps pneumatic, robotic, and semi-automatic depositor sub-sectors, each validated through plant engineers at industrial bakeries, OEM procurement teams at multinational food processors, and aftermarket service heads at integrated solution providers. Primary interviews with maintenance directors and technical R&D directors at heritage European manufacturers combined with secondary validation from FDA Food Safety Modernization Act guidance documents, EU Machinery Directive technical standards, customs records for 316L stainless steel trade flows, and SEC filings from commercial kitchen equipment conglomerates. Bottom-up unit economics triangulate against top-down addressable market sizing across the projection horizon.
Assumption sets held regulatory enforcement timelines and stainless steel price volatility bands fixed while varying artisan bakery automation adoption curves and EU Green Deal subsidy disbursement rates. Segmentation dimensions modeled include actuation technology, equipment size tier, end-user category, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and greenfield capacity additions. Industry-specific forecast inputs incorporate FSSAI standard harmonization progress and mechatronics technician training pipeline expansion.
Sensitivities concentrate around stainless steel input cost spikes, pneumatic component lead time extensions, and ISO 22000 certification timeline compressions for new equipment vendors. Cross-checking against industrial bakery capital expenditure surveys and food processor equipment procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Potato Processing Market
Food Processing Equipment
Oven Market
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
Global Snack Pellet Equipment Market
Food Processing Equipment
Edible Collagen Casing Market
Food Processing Equipment
Global Food and Beverage Coding and Marking Equipment Market
Food Processing Equipment
Bottled Water Processing Equipment Market
Food Processing Equipment
Food Industry Vacuum Cooling Equipment Market
Food Processing Equipment
Frozen Food Processing Machinery Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Nut Processing Machine Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
Edible Oil Extracting Machine Market
Food Processing Equipment
Hygienic Easy to Clean Food Processing Equipment Market
Food Processing Equipment
Cereal Rolling Machine Market
Food Processing Equipment
Food Waste Composting Machine Market