
 Automatic Canning Machine Market | 2026-2036
Automatic Canning Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Canning Machine Market Insights
Multi-source equipment procurement is expanding across mid-sized beverage and food packaging operations. Krones Group leverages integrated rotary filling lines to dominate high-volume brewery installations. Wild Goose Filling specializes in compact canning systems tailored to craft beverage producers. PneumaticScaleAngelus sustains its position through legacy pneumatic seaming technology trusted by legacy food processors.
An automatic canning machine integrates depalletizing, filling, seaming, and labeling functions into continuous rotary or linear configurations operating at speeds from 15 to 2,000 cans per minute. Servo motor technology commands the fastest expansion among drive systems due to precision indexing and energy recovery capabilities. Rotary machine types anchor the installed base in large-scale beverage bottling plants where throughput requirements exceed 500 cans per minute. PLC controlled architectures are displacing legacy relay-based systems as manufacturers pursue recipe-driven changeovers and remote diagnostics.
FDA food-contact substance regulations and EU machinery safety directives shape sanitary design requirements and stainless steel specifications across export-bound equipment. China's GB standards for food machinery and SAMR certification protocols govern market access for imported canning lines. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and state-level deposit return schemes in the United States that will alter container material preferences and machine compatibility requirements.
Market Dynamics
Servo motor architectures and PLC-driven recipe management are compressing changeover times and enabling remote diagnostics across beverage packaging lines, fundamentally altering how producers balance flexibility against throughput economics.
Growth Catalysts
- EU Machinery Safety Directives:Tightening CE marking requirements for sanitary stainless steel specifications are accelerating equipment replacement cycles in legacy European food processing facilities.
- Craft Brewing Cluster Expansion:Mid-sized beverage producers in Germany and the United States are scaling automated canning lines to capture ready-to-drink market share.
- Servo Drive Technology:Precision indexing capabilities with energy recovery are displacing pneumatic systems in new rotary filling installations.
Market Restraints
- Stainless Steel Input Volatility:Grade 304 and 316L price fluctuations compress margin visibility for equipment fabricators serving FDA-regulated food-contact applications.
- Component Supply Concentration:Specialized seaming chuck and roll suppliers cluster in German and Japanese precision manufacturing regions, creating single-source vulnerability.
- Technical Integration Limits:Legacy pneumatic seaming systems resist seamless PLC integration, forcing hybrid architectures that increase commissioning complexity.
Strategic Opportunities
- Deposit Return Scheme Expansion:State-level container deposit frameworks in the United States are altering aluminum can specifications, creating retrofit demand for compatible seaming heads.
- Extended Producer Responsibility:EU packaging waste regulations are mandating traceability systems that integrate with canning line PLCs for batch-level tracking.
- Convergence of Vision Inspection and Filling:Machine learning-enabled defect detection combined with servo-driven fill-level control is opening premium contract packaging niches.
Industry Challenges
- Controls Engineering Talent Scarcity:Recipe-driven PLC programming for multi-format canning lines requires specialized expertise that outpaces vocational training pipeline output.
- SAMR Certification Timelines:China's food machinery import protocols extend equipment validation cycles for export-bound manufacturers.
- Legacy System Integration Friction:Retrofitting servo indexing into existing rotary architectures demands custom mechanical couplings that delay project commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Canning Machine Market |
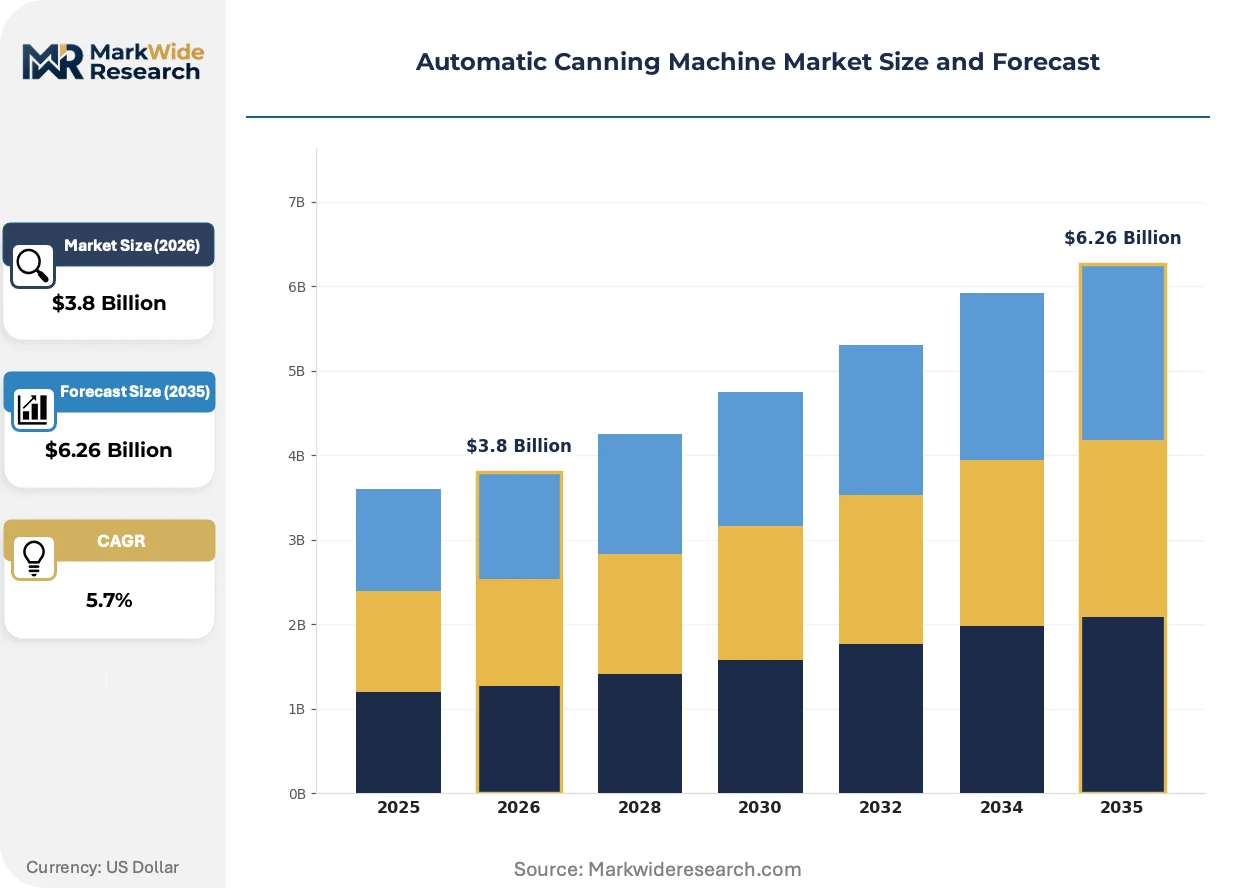
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
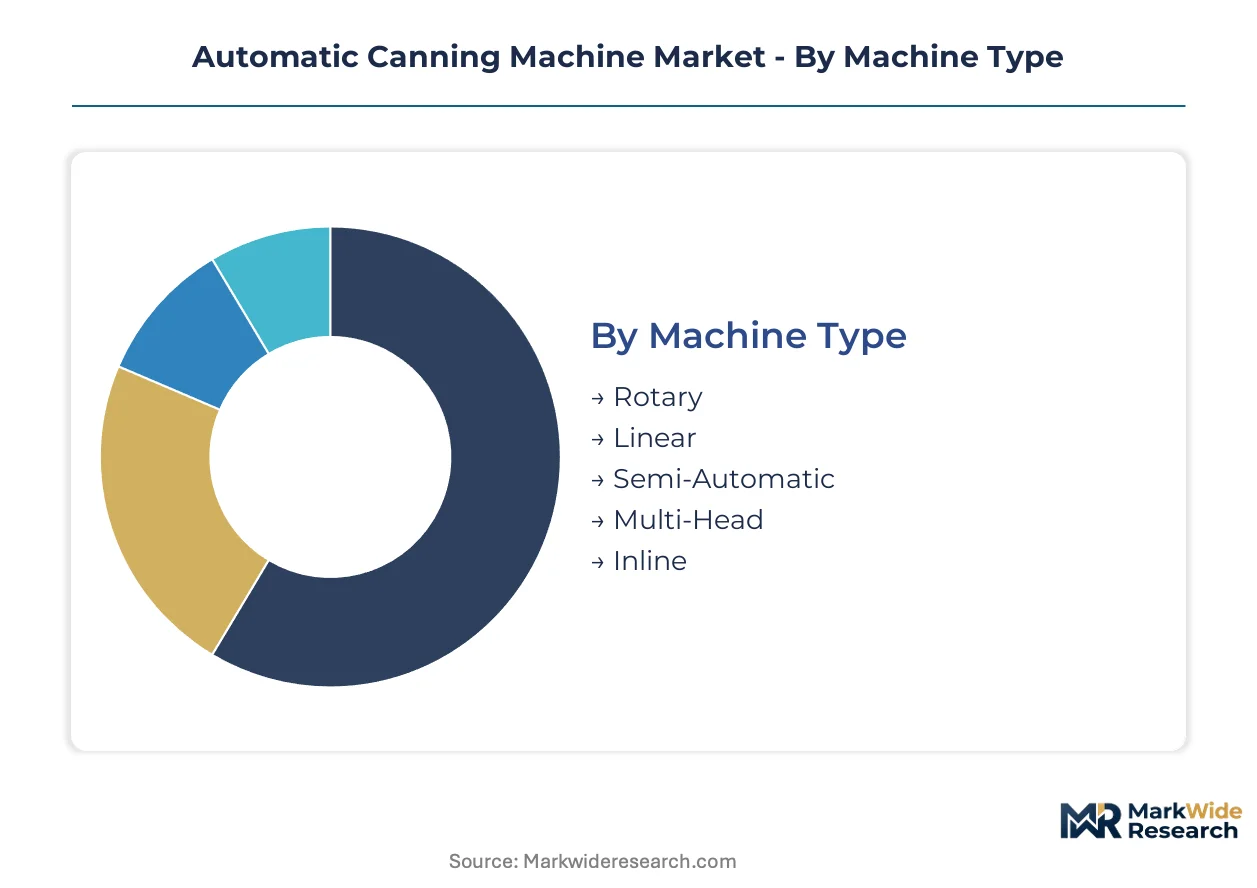
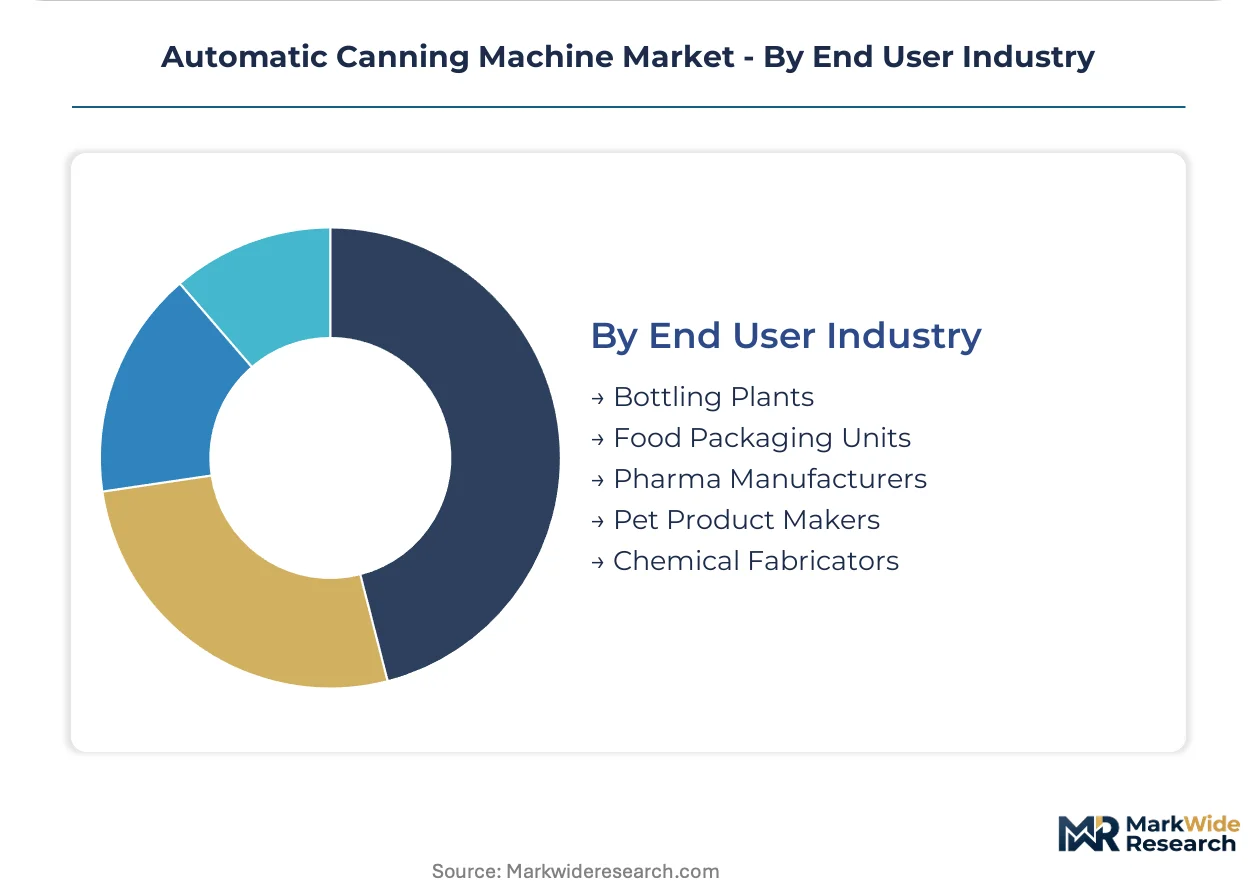
| Segmentation | Machine Type: Rotary, Linear, Semi-Automatic, Multi-Head, Inline Technology: Servo Motor, Pneumatic, Electro-Mechanical, Hydraulic, PLC Controlled Application: Beverages, Food Processing, Pharmaceuticals, Pet Food, Chemicals End User Industry: Bottling Plants, Food Packaging Units, Pharma Manufacturers, Pet Product Makers, Chemical Fabricators |
| Companies Covered | Krones Group, Wild Goose Filling, PneumaticScaleAngelus, Levapack, ABE Equipment, American Canning, Cask Global Canning Solutions, CFT Group, Tetra Pak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Canning Machine Market Trends and Innovations
Digital thread technologies and predictive maintenance architectures are redefining how canning line operators manage uptime, quality consistency, and energy consumption across distributed production networks.
Machine vision systems integrated at the filling and seaming stations are automating real-time defect detection and rejection protocols. Craft beverage producers with batch sizes below 10,000 units are adopting these systems fastest to minimize product loss without dedicated quality labor. The technology is automating the shift from statistical process control toward zero-defect production targets in mid-volume operations.
China's SAMR certification protocols and GB standards for food machinery safety are tightening documentation requirements for imported canning equipment. Manufacturers must now submit complete material traceability records for all food-contact surfaces before market authorization. European and North American exporters are responding by embedding digital material passports into equipment specifications to accelerate regulatory review.
Contract packaging operators are unbundling after-sales service from equipment purchase contracts, favoring subscription-based remote monitoring and spare parts availability. This procurement evolution displaces traditional capital expenditure models with operating expense structures tied to output volume. The shift is most visible in the United States craft brewing sector where capital constraints favor performance-guaranteed service agreements over ownership risk.
Automatic Canning Machine Market Segmentation
Canning machine procurement decisions pivot on throughput requirements, changeover flexibility, and regulatory compliance profiles. Distinct operational demands across beverage, food, and pharmaceutical verticals create divergent specification priorities that shape equipment design and vendor selection.
Machine Type:
Supply concentration in high-speed rotary systems has compressed lead times for premium configurations while extending availability for specialized linear formats.
- Rotary:Continuous circular indexing platforms achieve speeds exceeding 500 cans per minute through synchronized filling, seaming, and labeling stations. Large-scale beverage bottling plants in Germany and the United States anchor demand as ready-to-drink production scales.
- Linear:Straight-line configurations accommodate slower speeds with modular expansion capability and smaller footprints. Craft brewing clusters in Colorado and Bavaria favor these systems for batch flexibility below 50,000 units.
- Semi-Automatic:Operator-assisted loading and unloading suits pilot production lines and seasonal capacity supplements.
- Multi-Head:Parallel filling stations increase throughput without rotary mechanics for mid-volume processors.
- Inline:Space-efficient arrangements integrate depalletizing through labeling in confined production environments.
Rotary systems absorb the bulk of installed capacity; linear configurations are expanding most quickly among craft beverage entrants.
Technology:
Cost tier differentiation separates precision servo architectures from legacy pneumatic alternatives, with electro-mechanical hybrids occupying intermediate price-performance positions.
- Servo Motor:Closed-loop position control enables recipe-driven indexing with energy recovery during deceleration cycles. FDA-regulated food processors in California and Illinois specify these drives for fill-level accuracy within 0.5 millimeters.
- Pneumatic:Compressed air actuation dominates legacy installations where capital constraints resist full control system replacement. Japanese precision component suppliers maintain concentrated production of specialized seaming chucks for these architectures.
- Electro-Mechanical:Hybrid drive systems blend motor precision with mechanical simplicity for mid-tier throughput requirements.
- Hydraulic:High-force actuation persists in heavy-container chemical canning applications.
- PLC Controlled:Programmable logic architectures enable remote diagnostics and recipe storage across all drive types.
Pneumatic technology retains the largest installed base; servo motor systems are climbing the fastest as energy efficiency mandates tighten.
Application:
Volume concentration in beverage canning has pulled vendor R&D investment toward aluminum compatibility and carbonation handling specifications.
- Beverages:Carbonated soft drinks, beer, and ready-to-drink formulations require counter-pressure filling and foam control systems. China's SAMR certification protocols impose material traceability documentation for all food-contact surfaces in these lines.
- Food Processing:Retort-compatible seam specifications and vacuum filling distinguish canned vegetables, meats, and ready meals. EU machinery safety directives mandate stainless steel 316L for acidic food contact.
- Pharmaceuticals:Aseptic filling isolators and SIP/CIP protocols govern parenteral and oral dosage canning.
- Pet Food:High-fat content handling and odor containment shape equipment specifications.
- Chemicals:Corrosion-resistant coatings and explosion-proof electrical enclosures address hazardous material containment.
Beverage applications command the greatest equipment volume; food processing is gaining share fastest as shelf-stable meal formats expand.
End User Industry:
Customer type stratification separates capital-constrained contract packagers from integrated manufacturers with captive engineering capabilities.
- Bottling Plants:Dedicated beverage packaging facilities operate 24-hour schedules with changeover intervals below 30 minutes. German brewery cooperatives and American craft brewing collectives drive specification standardization.
- Food Packaging Units:Multi-format processors require quick-release tooling and washdown-compatible construction. Extended producer responsibility frameworks in the European Union are mandating batch-level traceability integration.
- Pharma Manufacturers:Validation documentation and IQ/OQ/PQ protocols dominate procurement criteria.
- Pet Product Makers:Moisture retention and palatability preservation guide filling temperature specifications.
- Chemical Fabricators:UN-certified container testing and hazardous area classifications constrain supplier pools.
Bottling plants deploy the majority of new capacity; food packaging units are expanding most rapidly as private-label sourcing concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel supply corridors in Germany and Japan anchor precision component sourcing for canning equipment fabricators. These metallurgical networks feed rotary seaming head production and servo drive assemblies across export markets. Regulatory divergence between FDA food-contact rules and EU machinery safety directives shapes regional specification patterns.
United States
Craft brewing clusters in Colorado and North Carolina drive demand for compact linear canning systems with rapid changeover capability. State-level container deposit schemes in California, Oregon, and New York are tightening aluminum can specification requirements. Chicago-area food packaging facilities are retrofitting legacy pneumatic lines with PLC-controlled servo architectures to meet FDA traceability mandates.
Germany
Bavarian brewery cooperatives and Baden-Württemberg precision engineering firms anchor European rotary system production. CE marking requirements under EU machinery safety directives are accelerating stainless steel 316L specification adoption. The Rhine-Ruhr industrial corridor hosts concentrated seaming chuck fabrication serving legacy food processors across the continent.
China
Ready-to-drink beverage producers in Guangdong and Zhejiang provinces are scaling automated aluminum canning lines for domestic consumption. SAMR certification protocols and GB standards for food machinery safety impose extended documentation timelines on imported equipment. Yangtze River Delta contract packagers are integrating vision inspection systems to meet tightening batch-level traceability requirements.
Japan
Precision component suppliers in Aichi and Osaka prefectures maintain concentrated production of specialized seaming rolls and indexing mechanisms. METI energy efficiency guidelines are driving servo motor adoption in retrofit installations. Kanto region pharmaceutical canning facilities are specifying aseptic isolator compatibility for parenteral dosage lines.
India
Maharashtra and Karnataka beverage processors are importing semi-automatic canning systems for seasonal capacity expansion. FSSAI food safety regulations and BIS machinery standards are tightening sanitary design documentation for imported lines. Gujarat-based contract packagers are piloting subscription-based remote monitoring arrangements to circumvent capital expenditure constraints.
Automatic Canning Machine Market Competitive Landscape
Global majors compete with regional champions across technology tiers and price-performance positioning. The vendor base separates into three distinct strata: integrated rotary line specialists serving high-volume breweries, compact system fabricators targeting craft producers, and pneumatic legacy maintainers anchored in food processing. Consolidation pressure concentrates at the mid-tier where servo-PLC integration capabilities determine competitive viability. Strategic moves center on geographic licensing partnerships and backward integration into precision seaming component production.
Within the integrated systems tier, Krones Group and Tetra Pak exemplify scale-driven rotary line dominance. Cask Global Canning Solutions and American Canning occupy positions among North American craft-focused specialists. PneumaticScaleAngelus anchors the legacy pneumatic maintenance segment. These archetypes reflect divergent capital intensity thresholds and customer relationship models across beverage, food, and pharmaceutical end-use verticals.
| Leading Market Players |
|---|
| Krones Group |
| Wild Goose Filling |
| PneumaticScaleAngelus |
| Levapack |
| ABE Equipment |
| American Canning |
| Cask Global Canning Solutions |
| CFT Group |
| Tetra Pak |
| Others |
Pricing and Supply Chain Analysis
Captive in-house production of precision seaming components anchors both supply security and pricing power for rotary system fabricators serving high-volume beverage bottlers. Backward integration into servo drive assemblies and stainless steel machining insulates tier-one vendors from Grade 304 volatility while compressing margin leakage to specialized chuck suppliers in Aichi and Osaka prefectures.
Pricing Analysis
Warranty and after-sales service bundling separates capital expenditure models from subscription-based remote monitoring arrangements. Three-tier pricing structure across premium, standard, and economy levels tracks servo-PLC integration depth and FDA certification tier. Pricing pressure stems from stainless steel input volatility compressing fabricator margins on fixed-price contracts. Contract packagers exhibit highest price sensitivity; integrated bottling plants with captive engineering tolerate premium positioning for changeover flexibility.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale brewery demand while regional distributors serve craft producers with semi-automatic configurations. Precision component sourcing concentrates in Germany, Japan, and China for seaming rolls, servo motors, and PLC architectures. Grade 304 and 316L stainless steel, specialized seaming chucks, and energy-recovery servo systems constitute critical input dependencies. Single-source vulnerability in Japanese precision manufacturing regions threatens continuity. Distribution runs through authorized service networks with localized spare parts warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
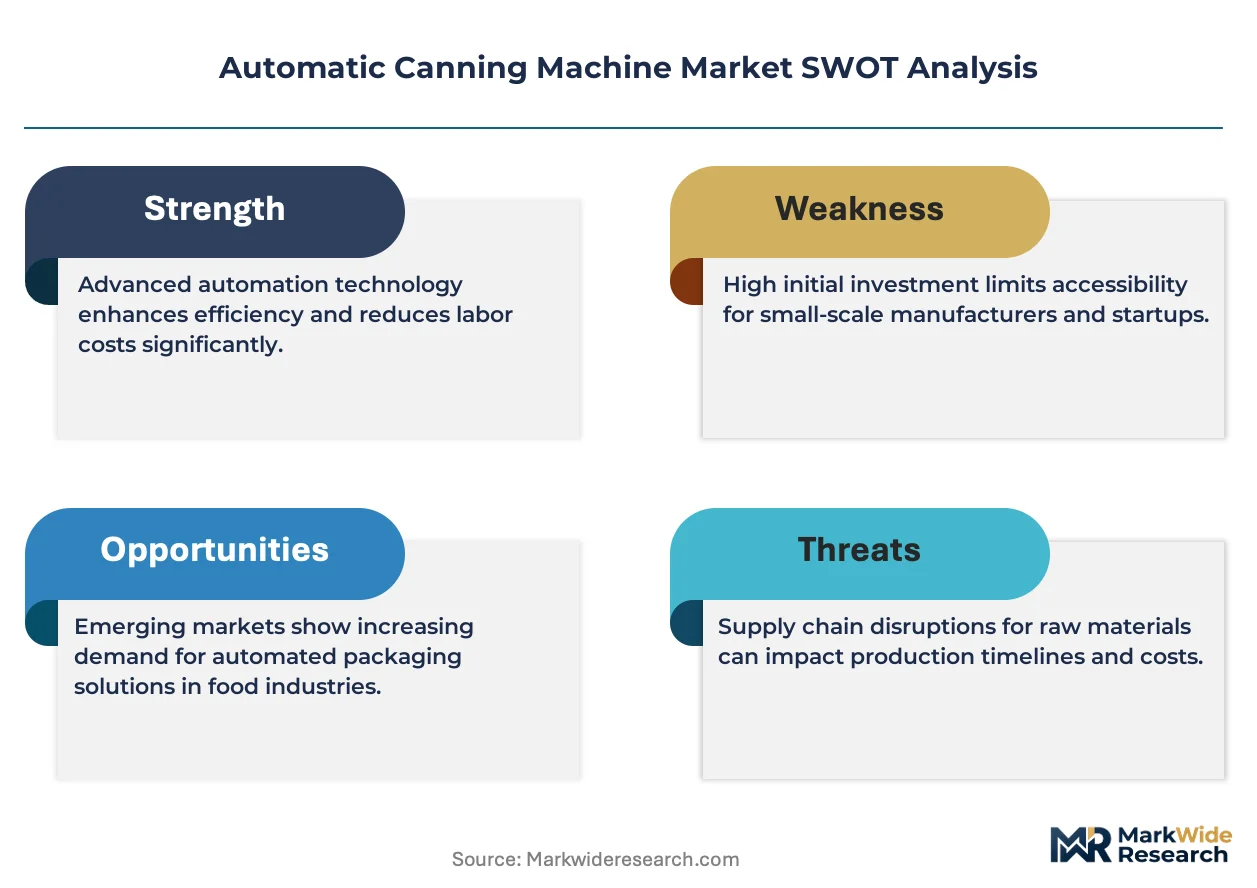
Vertical integration into precision seaming component production defines competitive viability as vendors race to control servo-PLC integration bottlenecks and compress lead times for export-bound equipment.
For Market Incumbents: Hedge against pneumatic legacy erosion by accelerating servo architecture R&D while locking long-term stainless steel offtake agreements. Chinese SAMR certification complexity favors incumbents with established documentation infrastructure. Backward integration into seaming chuck production defends margin position against Japanese supplier concentration. For New Entrants and Emerging Players: EU machinery safety directives tightening CE marking requirements open a window for sanitary design specialists targeting legacy European food processor retrofits. Unbundled subscription service models penetrate capital-constrained craft brewing clusters fastest. Target compact linear configurations for batch-flexible producers below 50,000-unit runs. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated packaging conglomerates seeking servo-PLC capabilities. Five-to-ten-year viability hinges on regulatory compliance infrastructure depth. Acquisition target archetype: mid-tier fabricators with SAMR-validated lines and installed base in Yangtze River Delta contract packaging. Watch deposit return scheme expansion across U.S. states as aluminum specification inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaming Components | Captive production of precision chucks insulates margin from Japanese supplier concentration and compresses lead times. |
| Servo-PLC Architecture Development | Recipe-driven indexing capabilities capture retrofit demand from legacy pneumatic installations in FDA-regulated facilities. |
| SAMR Certification Pre-validation | Complete material traceability documentation accelerates Chinese market access for export-bound rotary systems. |
| Subscription Service Model Launch | Performance-guaranteed remote monitoring converts capital-constrained craft brewers from ownership to operating expense structures. |
| Deposit Return Scheme Compatibility Investment | Retrofit-ready seaming heads capture aluminum specification shifts in California, Oregon, and New York state frameworks. |
Research Methodology
Independent corroboration across OEM procurement directors, plant engineers at beverage bottling facilities, aftermarket service heads, and precision component suppliers underwrites the qualitative findings. Primary interviews with maintenance directors and OEM procurement teams at Krones Group, Wild Goose Filling, and PneumaticScaleAngelus customer sites combined with secondary validation from FDA food-contact substance filings, EU machinery safety directive documentation, SAMR certification protocols, and SEC equipment manufacturer disclosures. Bottom-up equipment shipment analysis and top-down beverage production capacity modeling triangulate volume estimates.
Comparable-period anchoring to historical rotary and linear system deployment rates across the projection horizon structured the forecast framework. Segmentation dimensions modeled include machine type, drive technology, application vertical, and end-user industry scale. CAGRs derived from equipment replacement cycle analysis and greenfield capacity expansion pipelines. Stainless steel price indices and servo motor adoption curves informed cost trajectory assumptions.
Caveats apply where SAMR certification timeline extensions, EU extended producer responsibility framework acceleration, or U.S. state-level deposit return scheme proliferation could materially shift the outlook. Periodic stress-testing of base assumptions against regulatory implementation pace and stainless steel commodity volatility is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Ice Cream Freezer Market
Food Processing Equipment
Water Cooled Cube Ice Machines Market
Food Processing Equipment
Coffee Processing Machine Market
Food Processing Equipment
Global Food Dehydrators Market
Food Processing Equipment
North America Commercial Sous Vide Machine Market
Food Processing Equipment
Industrial Fryers Market
Food Processing Equipment
Granular Ice Machine Market
Food Processing Equipment
Aseptic Processing Market
Food Processing Equipment
Dual-Ovenable Cook Trays Market
Food Processing Equipment
Food-Grade Mixing Tank Market
Food Processing Equipment
Wine Bottling Machine Market
Food Processing Equipment
Commercial Oven for Bakery Market
Food Processing Equipment
Destemmer Market
Food Processing Equipment
Craft Brewery Equipment Market
Food Processing Equipment
Flakes Making Machine Market
Food Processing Equipment
Brewing Boiler Market