
 Food Waste Shredder Market | 2026-2036
Food Waste Shredder Market Size, Share, and Industry Trends Forecast 2026-2036
Food Waste Shredder Market Foresight
Germany's industrial equipment corridor is narrowing the supply gap for high-torque food waste processing systems. Emerson Electric Co. leverages its motor-drive integration to dominate heavy-duty shredding applications. Oklin International anchors its position through compact commercial units designed for space-constrained hospitality environments. BioHiTech Global differentiates via cloud-connected digesters that pair shredding with real-time waste analytics.
Food waste shredders are electromechanical reduction systems employing hardened steel blades or grinding mechanisms to comminute organic refuse into pumpable slurry or compost-ready particulate, typically operating at 1,500–3,000 RPM with throughput capacities from 50 kg to 5,000 kg per hour. Electric shredders lead installed base volumes due to consistent torque delivery and lower operator fatigue, while rotary shredding technology commands premium positioning in food processing plants handling fibrous agricultural residues. The hospitality sector represents the fastest-growing end-user pool as hotels and restaurant chains face escalating organic waste diversion mandates.
The EPA's food recovery hierarchy and the EU's Waste Framework Directive shape equipment specifications by mandating source-separated organic processing, while OSHA guidelines govern operator safety around high-speed cutting assemblies. China's SAMR enforces GB standards for electrical safety and electromagnetic compatibility in kitchen-grade shredding equipment. Stakeholders must monitor evolving blade-material regulations and biogas feedstock quality standards to align product roadmaps with downstream anaerobic digestion requirements.
Market Dynamics
Municipal composting mandates across the European Union are compressing replacement cycles for commercial kitchen equipment, forcing food service operators to upgrade legacy shredding infrastructure ahead of scheduled depreciation timelines.
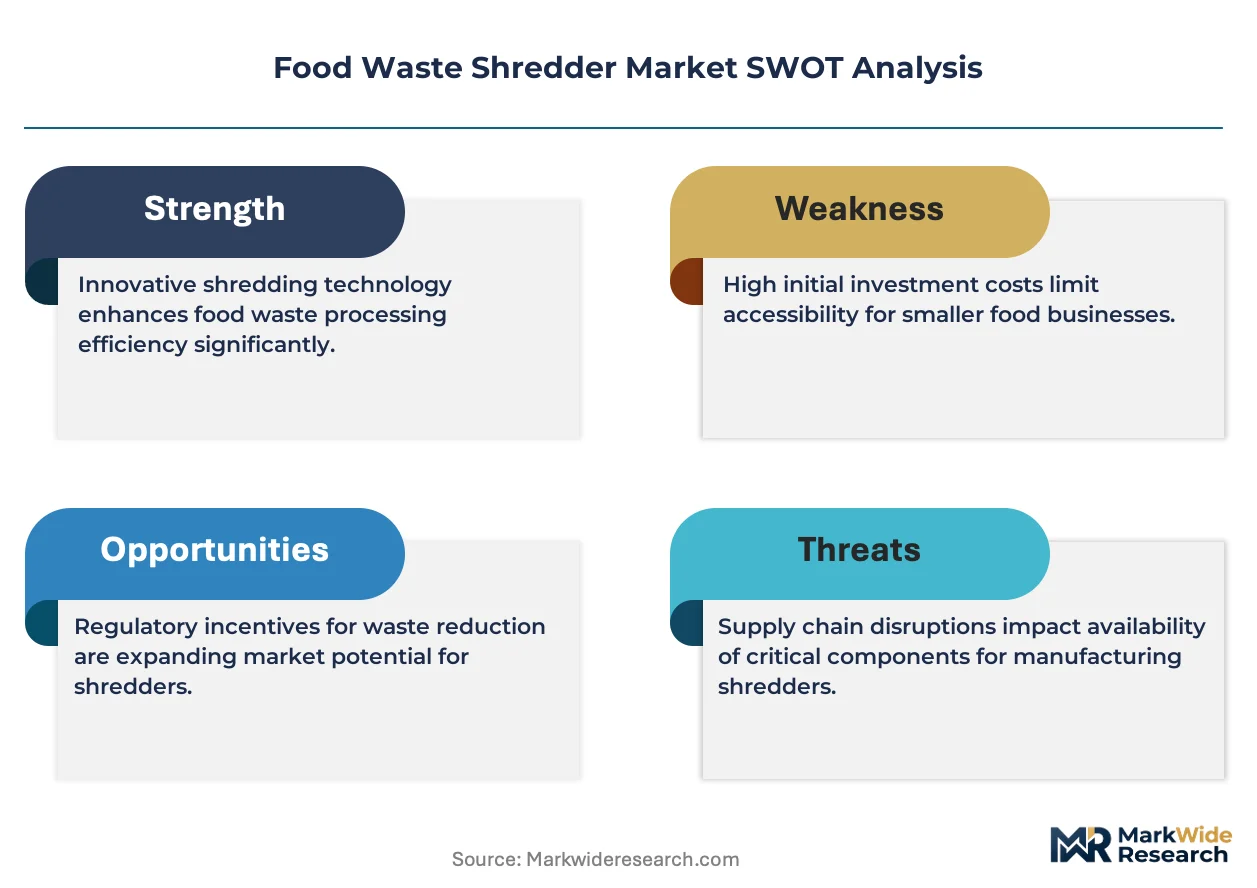
Growth Catalysts
- EU Waste Framework Directive:Source-separated organic processing requirements in Germany, France, and Italy are mandating commercial kitchens install certified shredding systems to achieve landfill diversion targets.
- High-torque rotary shredding:Food processing plants handling fibrous agricultural residues in Spain and Poland are adopting premium rotary mechanisms to process crop waste into anaerobic digestion feedstock.
- Hospitality sector concentration:Hotel and restaurant chains in the Netherlands face escalating organic waste diversion mandates, driving bulk procurement of compact commercial units.
Market Restraints
- Hardened steel blade costs:Volatility in specialty alloy prices constrains margin flexibility for mid-tier equipment manufacturers serving price-sensitive municipal buyers.
- Electrical safety certification backlog:China's SAMR enforcement of GB standards for electromagnetic compatibility creates extended approval timelines for imported kitchen-grade equipment.
- Batch composting substitution:On-site aerobic digesters without shredding stages compete for hospitality contracts in space-constrained urban environments.
Strategic Opportunities
- Cloud-connected waste analytics:Integration of shredding hardware with real-time monitoring platforms opens recurring revenue streams in contract food service management.
- Rural biogas feedstock supply:Agricultural cooperatives in Romania and Bulgaria seek decentralized shredding capacity to supply regional anaerobic digestion facilities.
- CE marking harmonization:Streamlined conformity assessment procedures for electromechanical reduction systems reduce cross-border friction for equipment vendors.
Industry Challenges
- High-speed cutting assembly safety:OSHA blade-guard specifications and EU machinery directives require specialized technician training that outpaces vocational program updates.
- Legacy kitchen retrofit integration:Space-constrained hospitality environments in historic European city centers face structural barriers to installing 1,500–3,000 RPM shredding systems.
- Downstream anaerobic digestion compatibility:Biogas plant operators impose evolving particulate size standards that force blade redesign cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Waste Shredder Market |
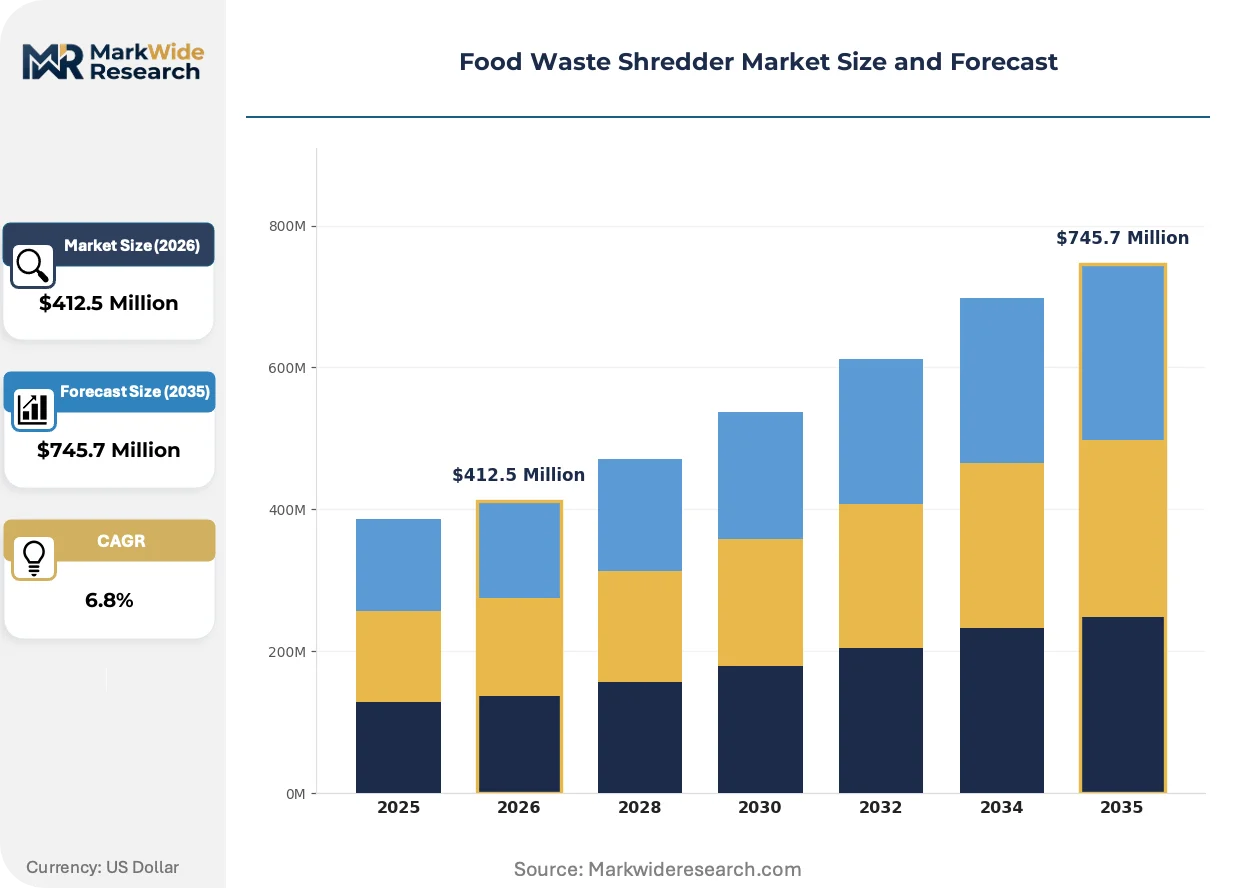
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Shredder, Electric Shredder, Commercial Shredder, Industrial Shredder Application: Residential Kitchens, Restaurants, Food Processing Plants, Catering Services, Agricultural Waste Management Technology: Blade Shredding, Grinder Mechanism, Hydraulic Press, Pulverizing Technology, Rotary Shredding End User: Households, Hospitality Sector, Food Manufacturers, Waste Management Companies |
| Companies Covered | Emerson Electric Co., Oklin International, Enic Co. Limited, Hungry Giant Recycling, Bhor Engineering Company, InSinkErator, Whirlpool Corporation, BioHiTech Global, IMC WasteStation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Waste Shredder Market Shifts & Advancements
Equipment manufacturers are converging mechanical reduction with digital monitoring layers, transforming standalone shredders into data-generating nodes within integrated waste management ecosystems.
Magnetic torque vectoring drives are rendering obsolete conventional fixed-speed motors in heavy-duty food processing applications. Large-scale agricultural waste handlers in Denmark and Sweden are retrofitting existing shredding lines with variable-frequency drive systems that modulate blade speed based on feedstock density. This electromechanical advancement is rendering obsolete the binary on-off operational models that previously dominated fibrous residue processing.
The EU's Corporate Sustainability Reporting Directive now mandates granular waste stream disclosure for large food service operators. This regulatory pressure forces procurement departments to specify shredders with integrated weighing and material-classification sensors. German hospital and university cafeteria networks are most affected, rewriting tender specifications to require ISO-compliant data export capabilities.
After-sales service unbundling is fragmenting traditional equipment sales models. Independent service providers in France and Belgium now offer blade-sharpening subscriptions and predictive maintenance analytics separate from original manufacturer contracts. This channel restructuring concentrates margin capture in specialized technical service firms rather than capital-equipment vendors.
Food Waste Shredder Market Segmentation
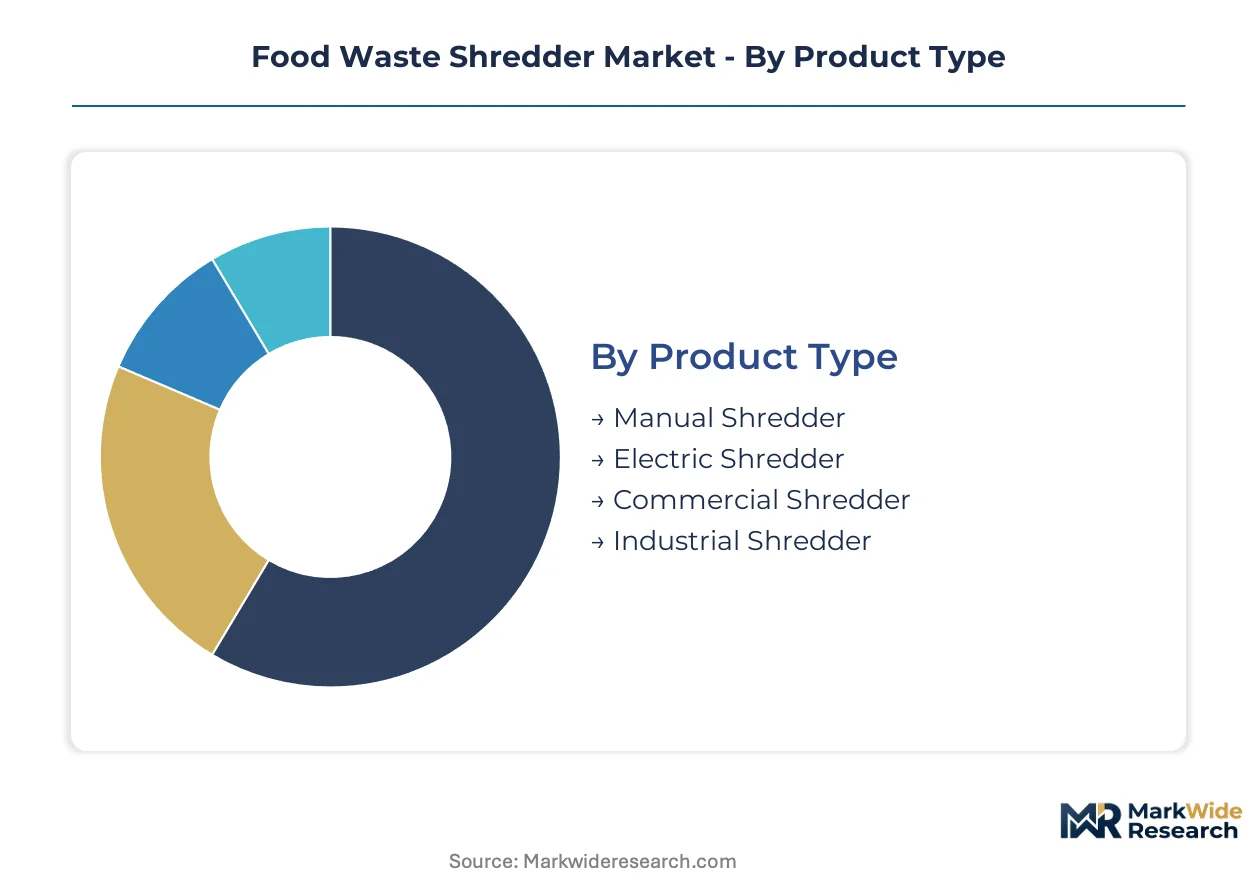
Equipment specification varies sharply across deployment contexts, with blade durability and torque requirements diverging between intermittent household use and continuous industrial operation. Procurement patterns in this market track directly to downstream waste stream obligations, creating distinct service intensity profiles that reshape vendor economics.
Product Type:
After-sales service intensity escalates dramatically with motor complexity and throughput rating, positioning electric and industrial units for multi-year maintenance contracts while manual systems rely on consumables.
- Electric Shredder:These systems deploy hardened steel cutting assemblies powered by 1,500–3,000 RPM induction motors, delivering consistent torque for commercial kitchens in Germany facing landfill diversion mandates. Demand concentrates in mid-scale food service operators requiring certified equipment under EU Waste Framework Directive compliance timelines.
- Industrial Shredder:Heavy-duty rotary mechanisms process 500–5,000 kg hourly through variable-frequency drive systems, serving agricultural cooperatives in Romania supplying regional anaerobic digestion facilities. High-torque applications command premium positioning due to fibrous residue processing requirements.
- Manual Shredder:Hand-cranked units with stainless steel augers serve space-constrained residential environments where electrical infrastructure is limited.
- Commercial Shredder:Compact electromechanical systems bridge hospitality sector needs between household scale and industrial throughput.
Electric shredders hold the largest share; momentum sits with industrial units as biogas feedstock standards tighten.
Application:
Volume concentration and particulate specification requirements create tiered procurement patterns, with food processing plants demanding precision engineering while hospitality prioritizes footprint reduction.
- Food Processing Plants:These facilities require rotary shredding technology to reduce fibrous agricultural residues into pumpable slurry meeting anaerobic digestion feedstock standards. Spain and Poland lead adoption as crop waste valorization accelerates under EU circular economy frameworks.
- Restaurants:Compact blade shredding systems dominate procurement as Dutch and Belgian chains face escalating organic waste diversion mandates. Space constraints in historic European city centers favor units under 500 kg hourly throughput.
- Residential Kitchens:Small-format electric or manual units address household source separation requirements.
- Catering Services:Mobile shredding capacity serves event-based waste generation with intermittent duty cycles.
- Agricultural Waste Management:Decentralized shredding infrastructure supports regional biogas supply chains in Bulgaria.
Food processing plants command the highest equipment values; restaurants are expanding most quickly as municipal mandates proliferate.
Technology:
Mechanical design choices directly determine blade replacement frequency and energy consumption, with implications for total cost of ownership across deployment scales.
- Rotary Shredding:High-torque drum mechanisms with hardened alloy cutters process dense fibrous materials at variable speeds, serving Denmark's agricultural waste handlers retrofitting existing lines with magnetic torque vectoring drives. Premium positioning reflects superior durability in continuous operation.
- Blade Shredding:Counter-rotating hardened steel assemblies operating at fixed 1,500–3,000 RPM deliver standardized particulate output for commercial composting compliance. German hospital and university cafeteria networks specify these systems for ISO-compliant data integration.
- Grinder Mechanism:Shear plate designs reduce soft organic matter through compression and cutting action.
- Hydraulic Press:High-pressure extrusion systems dewater shredded material for reduced transport costs.
- Pulverizing Technology:Hammer mill configurations achieve fine particulate sizing for specialized biogas applications.
Blade shredding dominates installed volumes; rotary shredding gains share fastest as agricultural residue processing scales.
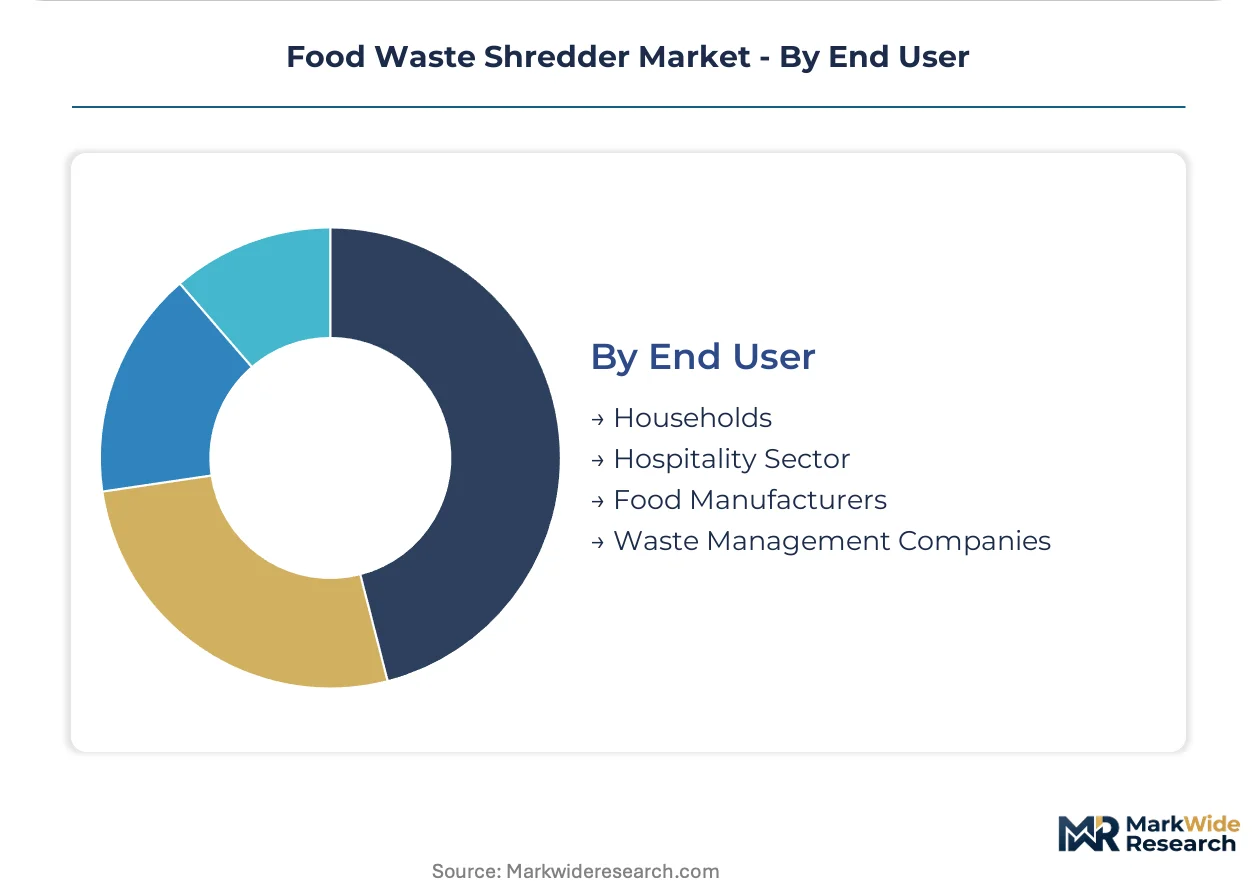
End User:
Procurement sophistication varies from household discretionary purchase to corporate sustainability mandates with integrated weighing and classification sensor requirements.
- Hospitality Sector:Hotels and restaurant chains in the Netherlands and France specify compact commercial units with cloud-connected analytics platforms. EU Corporate Sustainability Reporting Directive obligations force tender rewrites requiring granular waste stream disclosure capabilities.
- Waste Management Companies:These operators deploy industrial shredding infrastructure as centralized preprocessing for municipal composting and anaerobic digestion facilities, with blade redesign cycles triggered by evolving particulate size standards.
- Households:Individual consumers purchase small-scale systems for residential organic waste reduction.
- Food Manufacturers:Production-integrated shredding addresses processing line waste and packaging contamination.
Hospitality sector holds the largest share; waste management companies show steepest expansion trajectory as regional biogas infrastructure develops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial equipment corridors supply the bulk of high-torque shredding systems, with component fabricators clustering around Stuttgart and Düsseldorf. This supply-side density shortens lead times for commercial kitchens across Northern Europe facing compressed compliance deadlines.
Germany
Landfill diversion targets for the food service sector are tightening in Baden-Württemberg and Bavaria. The EU Waste Framework Directive mandates source-separated organic processing for commercial kitchens above defined volume thresholds. Stuttgart's industrial equipment corridor hosts multiple hardened steel blade fabricators serving hospital and university cafeteria networks.
Netherlands
Hotel and restaurant chains in Amsterdam and Rotterdam face escalating organic waste diversion mandates from municipal authorities. The EU Corporate Sustainability Reporting Directive forces granular waste stream disclosure for large food service operators. Randstad procurement departments now specify compact commercial units with integrated weighing sensors.
United States
The EPA's food recovery hierarchy shapes equipment specifications for food processing plants in California and the Midwest. OSHA guidelines govern operator safety around high-speed cutting assemblies in commercial kitchen deployments. Chicago and Los Angeles food service operators are upgrading legacy shredding infrastructure ahead of municipal organic waste mandates.
China
SAMR enforcement of GB standards for electromagnetic compatibility creates extended approval timelines for imported kitchen-grade equipment. The country's dual carbon goals accelerate biogas infrastructure development in agricultural provinces. Yangtze River Delta manufacturing clusters are domesticating torque vectoring drive production for regional food processing applications.
France
Independent service providers in Paris and Lyon now offer blade-sharpening subscriptions separate from original manufacturer contracts. CE marking harmonization for electromechanical reduction systems reduces cross-border friction for equipment vendors. Île-de-France hospital networks are rewriting tender specifications to require ISO-compliant data export capabilities.
Food Waste Shredder Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in blade alloys and motor-drive assemblies. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with motor integration capabilities, compact equipment specialists targeting space-constrained hospitality environments, and cloud-connected analytics providers bundling hardware with recurring software revenue. Dominant competitive moves include backward integration into blade manufacturing and geographic expansion through CE marking harmonization.
Among diversified industrial conglomerates, Emerson Electric Co. exemplifies platform integration through motor-drive capabilities. Oklin International occupies a position within the compact commercial equipment tier, representing specialization for hospitality sector footprint constraints. BioHiTech Global anchors the cloud-connected analytics archetype, sitting at the intersection of mechanical reduction and real-time waste monitoring platforms.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Oklin International |
| Enic Co. Limited |
| Hungry Giant Recycling |
| Bhor Engineering Company |
| InSinkErator |
| Whirlpool Corporation |
| BioHiTech Global |
| IMC WasteStation |
| Others |
Supply & Pricing Matrix
Overcapacity in China's Yangtze River Delta motor-drive manufacturing clusters is compressing supplier margins while simultaneously lowering input costs for European equipment assemblers, creating divergent pricing postures across the value chain.
Pricing Analysis
The EU Waste Framework Directive dictates the pricing tier structure for commercial kitchen equipment, separating certified shredding systems from uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects blade alloy grade, CE marking status, and after-sales service bundling. Cost compression in the mid-tier is intensifying because Chinese manufacturers are absorbing GB standard certification delays to maintain European market access. Municipal buyers in Southern Europe exhibit the highest price sensitivity, while German hospital networks prioritize ISO-compliant data integration capabilities over unit cost.
Supply Chain Analysis
Export control restrictions on high-torque magnetic torque vectoring drives limit technology flows from Denmark and Sweden to non-EU manufacturing partners. Component fabrication draws from Germany's hardened steel blade corridors, China's induction motor clusters, and Italy's precision gearbox specialists. Single-source vulnerability concentrates in specialty alloy supply for rotary cutting assemblies. Distribution runs through OEM-direct channels for industrial units and specialized food service equipment distributors for commercial hospitality deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated contract food service management companies, which now specify cloud-connected analytics as mandatory tender requirements rather than optional upgrades.
For Market Incumbents: Pre-empt blade-material substitution threats by securing captive supply of hardened alloy feedstock through backward integration into specialty steel sourcing. Invest in CE marking harmonization capabilities to compress cross-border approval timelines before regional competitors replicate Stuttgart's industrial equipment corridor density. For New Entrants and Emerging Players: Establish a beachhead in Romania and Bulgaria's agricultural cooperative segment, where decentralized biogas feedstock supply chains lack established shredding infrastructure. Target mobile shredding capacity for catering services as the most penetrable application, leveraging intermittent duty cycle requirements to bypass continuous-operation engineering barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-connected analytics providers bundling hardware with real-time waste monitoring platforms. Long-term viability favors vendors with integrated sensor-to-software architectures capable of adapting to evolving biogas particulate standards. The signal to watch is municipal mandate acceleration in secondary European cities, which would trigger replacement cycle compression and expand addressable installed base.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blade Manufacturing | Secures hardened alloy supply chains against specialty steel price volatility affecting mid-tier margins. |
| Cloud-Connected Analytics Platform Launch | Enables recurring revenue streams from Dutch and German hospital cafeteria networks facing CSRD disclosure mandates. |
| CE Marking Harmonization Investment | Reduces cross-border friction for equipment vendors targeting compressed compliance deadlines in Northern Europe. |
| Rural Biogas Feedstock Partnership | Positions shredding capacity as critical preprocessing infrastructure for Romanian and Bulgarian anaerobic digestion facilities. |
| Predictive Maintenance Service Unbundling | Captures margin concentration in blade-sharpening subscriptions separate from capital equipment sales. |
Research Methodology
Initial hypotheses were tested against primary input from maintenance directors at food processing plants, procurement leads at hospital cafeteria networks, aftermarket service heads, and OEM engineering teams, and refined through secondary validation against EU Waste Framework Directive implementation timelines, SAMR GB standard enforcement records, and OSHA blade-guard specification updates. Bottom-up equipment shipment estimates triangulated with top-down waste stream obligation modeling.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeled by technology type, end-user sophistication tier, and downstream anaerobic digestion compatibility requirements. CAGRs derived from equipment replacement cycle compression rates and municipal mandate propagation patterns. Industry-specific inputs included blade redesign frequency tied to biogas particulate standards and cloud-connected sensor adoption curves in contract food service management.
Macroeconomic conditions sit as an overlay; deviation in specialty alloy commodity prices or EU circular economy funding allocation would shift the trajectory. Forecasts reflect documented assumptions regarding mandate enforcement consistency and certification timeline stability. Material shifts in OSHA blade-guard specifications or biogas feedstock quality standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Pizza Scissors Market
Food Processing Equipment
Spray Drying Equipment Market
Food Processing Equipment
Bottled Water Processing Equipment Market
Food Processing Equipment
Aseptic Processing Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Deep Fryer Oil Filtration Market
Food Processing Equipment
Coconut Crushers Market
Food Processing Equipment
Spiral Cooler Market
Food Processing Equipment
North America Multi Cooker Market
Food Processing Equipment
Multiple Unit Pellet Systems Market
Food Processing Equipment
Deep Fryer Machine Market
Food Processing Equipment
Brewing Chiller Market
Food Processing Equipment
Global Food Dehydrators Market
Food Processing Equipment
Convection Ovens Market
Food Processing Equipment
Wine Crusher Market
Food Processing Equipment
Residential Food Waste Disposer Market