
 Commercial Convection Ovens Market | 2026-2036
Commercial Convection Ovens Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Convection Ovens Market Outlook
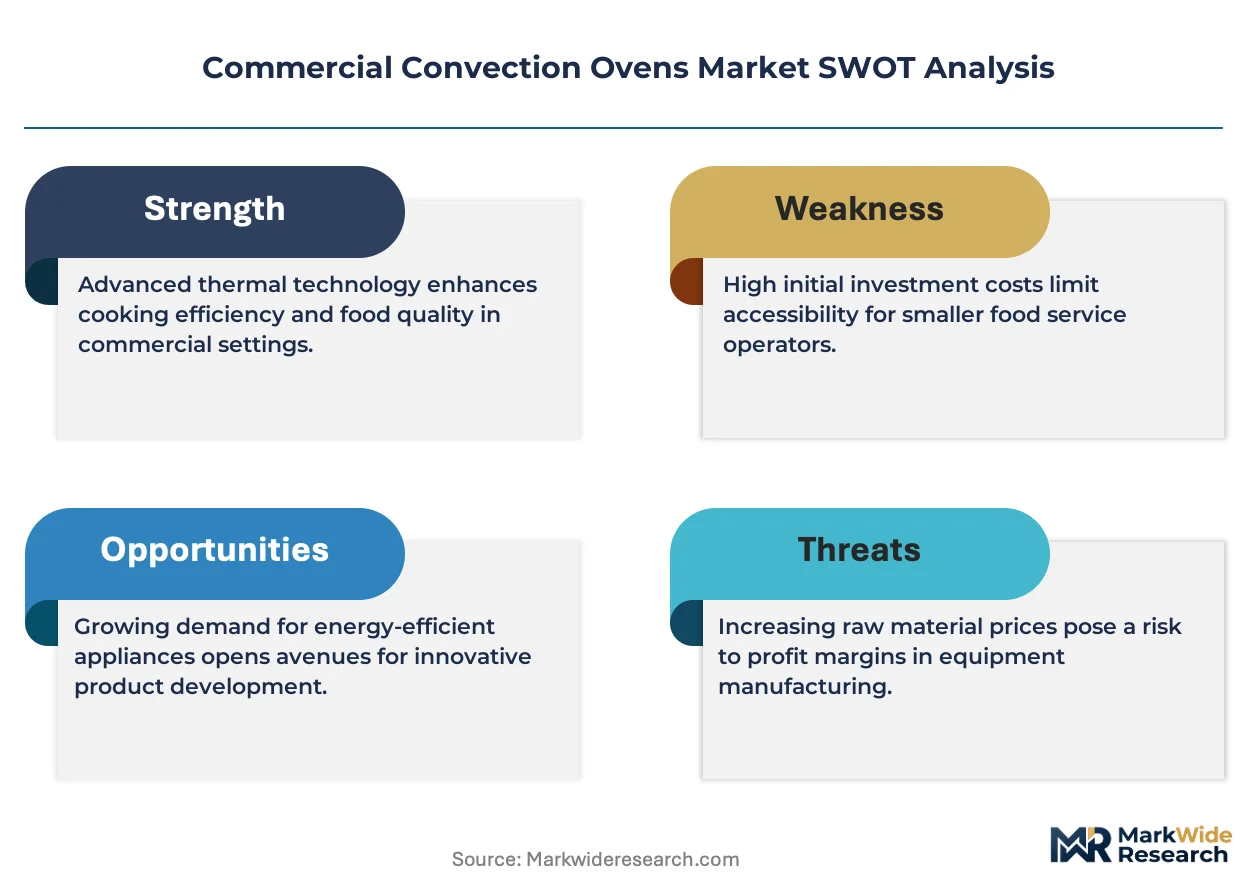
NSF/ANSI Standard 4 certification for commercial cooking equipment is redrawing the competitive landscape by mandating splash, spill, and food-zone sanitation benchmarks that smaller fabricators struggle to meet. Blodgett sustains its position through deep manufacturing scale in heavy-duty floor-standing platforms for institutional kitchens. TurboChef differentiates via high-speed impingement technology that compresses cook times for quick-service operators. Vulcan anchors the gas-powered segment with broad distribution through foodservice dealer networks.
Commercial convection ovens are enclosed, fan-assisted baking chambers designed to circulate heated air uniformly at temperatures typically ranging from 150°F to 550°F, enabling faster cook times and consistent browning across multiple rack positions for high-volume food preparation. The floor-standing category dominates installed base value in hotels and central commissaries where batch throughput governs equipment selection. High-speed units represent the fastest-growing product type as drive-thru and delivery-focused restaurants prioritize ticket-time reduction. Electric technology leads new specification in cafes and catering operations where utility incentives and ventilation constraints favor plug-and-play installation over gas line infrastructure.
The U.S. Department of Energy sets minimum cooking efficiency standards under 10 CFR 431, while NSF International administers food equipment sanitation certification that gates placement in regulated foodservice environments; both frameworks elevate compliance costs but protect incumbents with established testing protocols. The EPA's ENERGY STAR program for commercial ovens creates procurement preference in institutional and chain accounts where sustainability scorecards influence vendor selection. Stakeholders must monitor evolving state-level electrification mandates and utility rebate structures that are tilting new-build specifications away from gas combustion toward digital-controlled electric platforms.
Market Dynamics
The commercial convection ovens market is experiencing structural pressure from electrification mandates and utility rebate programs that are systematically displacing gas-fired units in new construction and replacement cycles across foodservice operations.
Growth Catalysts
- 10 CFR 431 efficiency standards:The U.S. Department of Energy's updated minimum cooking efficiency thresholds are accelerating replacement of legacy gas and electric units in institutional kitchens and chain restaurants.
- Ghost kitchen buildouts:Delivery-optimized commissary facilities are specifying high-throughput convection platforms to maximize output per square foot of back-of-house space.
- Impingement technology maturation:High-speed forced-air systems are compressing ticket times for quick-service operators competing on drive-thru velocity.
Market Restraints
- Stainless steel price volatility:Input cost swings for 304-grade sheet metal and component-grade aluminum are compressing fabrication margins for mid-tier equipment producers.
- NSF/ANSI Standard 4 compliance costs:Third-party food-zone sanitation certification and splash-test validation are creating capital barriers for smaller regional fabricators.
- Ventilation infrastructure lock-in:Existing gas-line infrastructure and Type I hood investments in legacy facilities are slowing electric conversion timelines despite operating cost advantages.
Strategic Opportunities
- Utility electrification incentives:State-level rebate programs and demand-response partnerships are creating procurement preference for connected electric platforms in California, New York, and Massachusetts.
- Cloud kitchen vertical integration:Real estate and logistics operators are specifying captive equipment fleets for multi-brand delivery facilities in urban infill locations.
- IoT-enabled predictive maintenance:Sensor-integrated ovens with remote diagnostics are opening recurring revenue streams through subscription-based service contracts.
Industry Challenges
- Certification timeline compression:NSF International's evolving test protocols for splash and spill resistance are extending product validation cycles for new platform launches.
- Controls integration complexity:Digital temperature management systems must interface with legacy kitchen display systems and enterprise resource planning platforms across heterogeneous operator technology stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Convection Ovens Market |
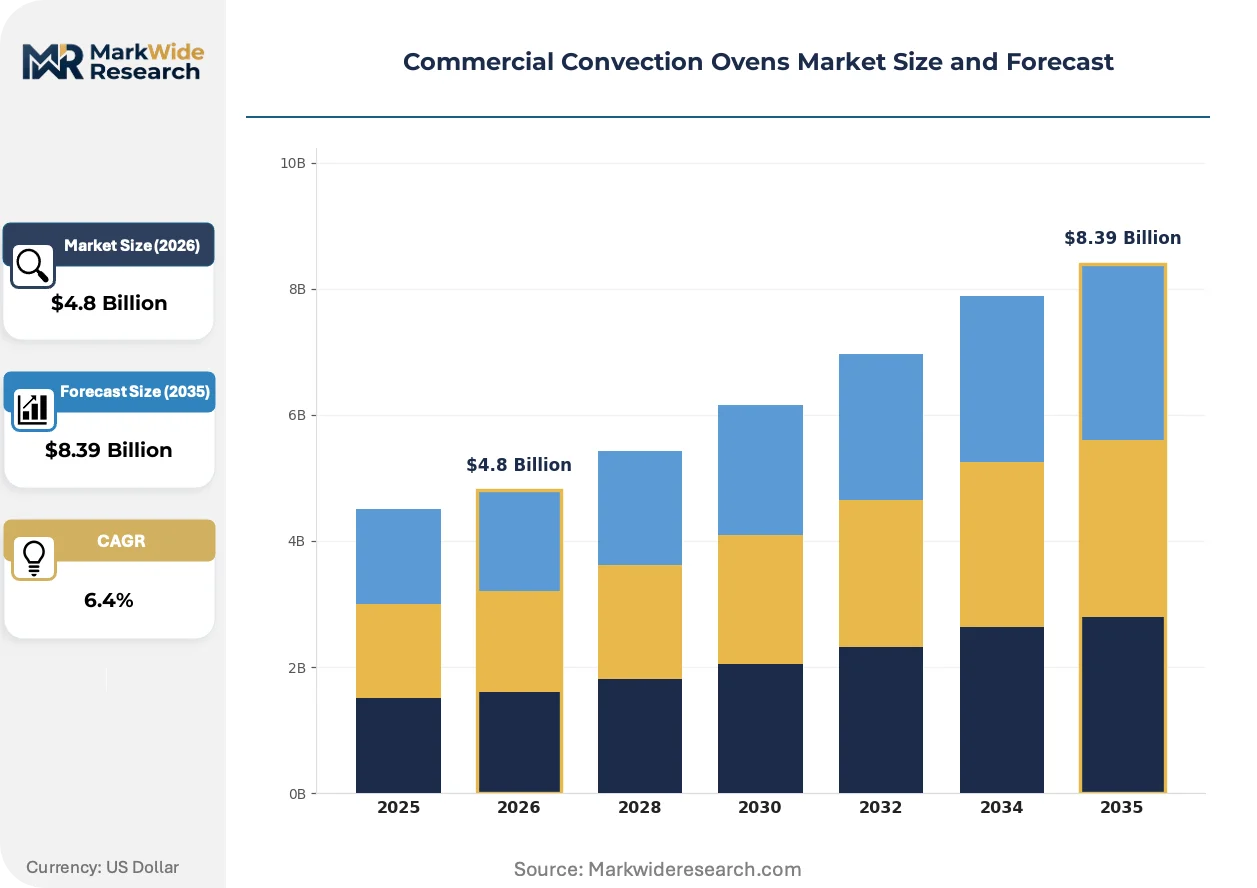
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Floor-Standing, Combi, High-Speed End User: Restaurants, Hotels, Catering Services, Cafes Technology: Electric, Gas, Digital Control, Steam Injection Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | TurboChef, VEVOR, Blodgett, Southbend, Avantco, Vulcan, Cadco, Moffat, Hobart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Convection Ovens Market Strategic Shifts
Equipment specification is pivoting toward connected platforms and accelerated cooking technologies that compress operational footprint while satisfying tightening energy performance thresholds.
Impingement oven technology is miniaturizing. High-speed forced-air platforms with jet-array configurations now achieve 50% faster cook times than conventional convection. Quick-service chains with drive-thru dependency are standardizing these units for protein and bakery applications. The technology is miniaturizing footprint requirements, enabling back-of-house reconfiguration in urban locations where real estate costs constrain kitchen layout.
ENERGY STAR certification for commercial ovens is hardening procurement criteria. The EPA's efficiency benchmarking program now gates vendor selection in institutional accounts with sustainability scorecards. Chain operators with net-zero commitments are specifying qualified units to satisfy scope-three emissions reporting. Foodservice dealers are prioritizing ENERGY STAR portfolios to maintain access to corporate and educational accounts.
Equipment-as-a-service models are displacing capital purchase structures. Multi-unit operators are shifting toward bundled lease arrangements that wrap maintenance, certification, and technology refresh into per-unit monthly fees. Ghost kitchen operators and emerging franchisees with constrained balance sheets are driving adoption. This financing structure is most visible in the United States, where equipment finance markets and dealer networks support complex leasing arrangements.
Commercial Convection Ovens Market Segmentation
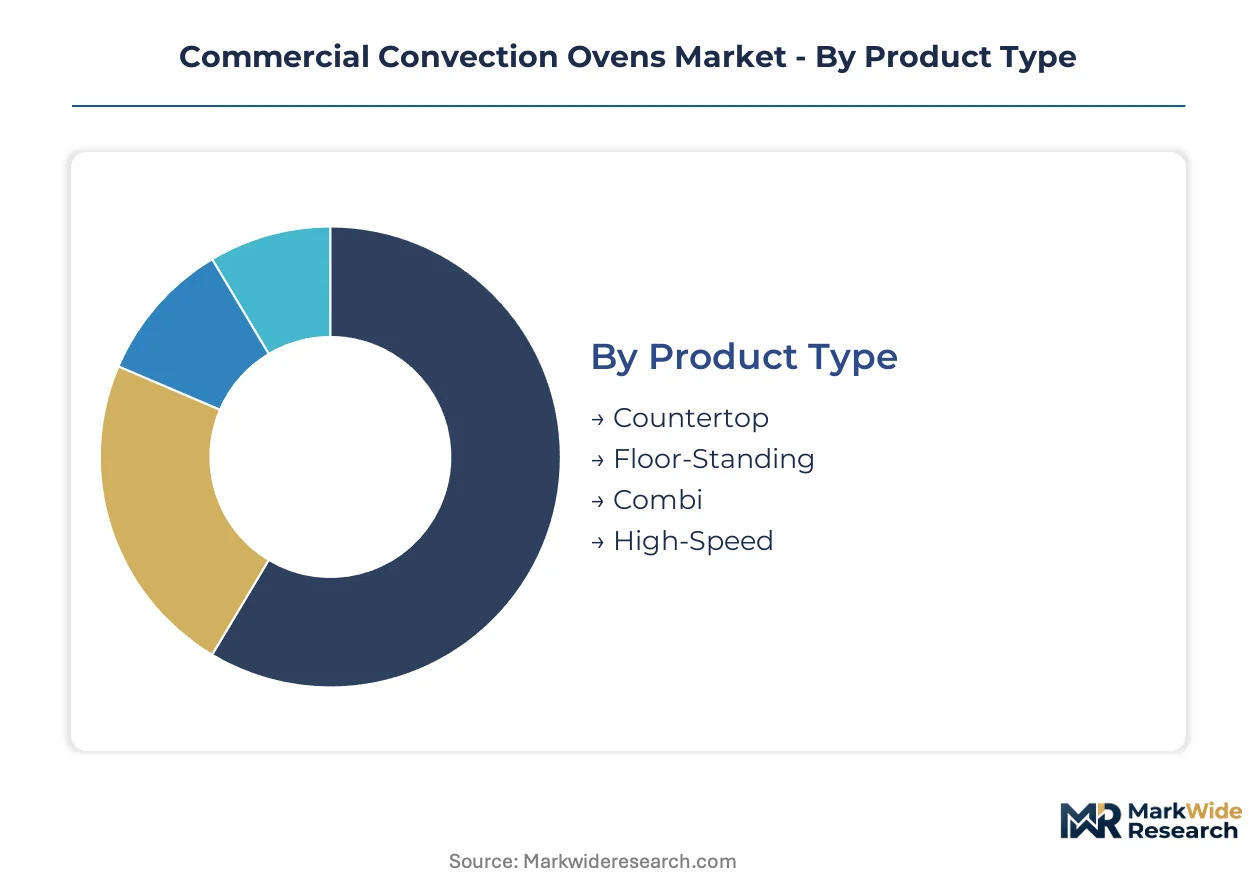
Commercial convection ovens segment across four distinct dimensions that shape procurement patterns and margin capture. Product type and technology classifications govern equipment specification, while end-user verticals and capacity tiers determine volume concentration and service requirements.
Product Type:
Margin pools concentrate in floor-standing and high-speed platforms where throughput premiums justify higher equipment spend.
- Floor-Standing:Heavy-duty enclosed baking chambers mounted on integrated bases, designed for institutional kitchens and central commissaries processing high batch volumes. Hotels and full-service restaurant chains in the United States specify these units for durability and multi-rack capacity, though stainless steel input costs compress fabrication margins.
- High-Speed:Impingement ovens with jet-array forced-air configurations achieving accelerated cook times through concentrated heat transfer. Quick-service operators with drive-thru dependency prioritize these platforms for ticket-time reduction, particularly in ghost kitchen buildouts where output per square foot governs equipment selection.
- Countertop:Compact fan-assisted units for limited-space operations requiring plug-and-play installation flexibility.
- Combi:Hybrid platforms integrating convection circulation with steam injection for moisture-controlled cooking across protein and bakery applications.
The dominant share belongs to floor-standing equipment, while high-speed units are gaining share fastest.
End User:
Application concentration varies by throughput intensity and capex cycle timing across foodservice verticals.
- Restaurants:Full-service and quick-service operators constitute the primary specification channel, with chain capex programs and franchise buildouts driving replacement demand. Ghost kitchen operators within this segment prioritize high-speed and electric platforms to maximize output density in delivery-optimized facilities.
- Hotels:Institutional kitchens with banquet and room-service operations specify floor-standing units for batch consistency across high-volume service windows.
- Catering Services:Mobile and commissary-based operators requiring equipment portability and rapid temperature recovery for off-premise events.
- Cafes:Limited-menu operators favoring countertop electric units where utility incentives and ventilation constraints limit gas infrastructure investment.
Restaurants command the largest installed base, though catering services are expanding most quickly as event volume rebounds.
Technology:
Specification momentum is tilting toward electric and digitally controlled platforms under regulatory pressure and utility incentive structures.
- Electric:Resistance-heated or induction-based platforms with fan-assisted circulation, dominating new-build specifications in California, New York, and Massachusetts where state-level electrification mandates and rebate programs displace gas combustion. Cafes and catering operations favor these units for plug-and-play installation without hood infrastructure requirements.
- Digital Control:Sensor-integrated temperature management systems with programmable recipe storage and remote diagnostics capability. Chain operators specify these platforms for consistency across multi-unit footprints and integration with kitchen display systems.
- Gas:Natural gas or propane-fired burners with forced-air circulation, retaining share in legacy facilities with existing line infrastructure and Type I hood investments.
- Steam Injection:Auxiliary moisture delivery systems for combi applications, specified by institutional accounts for protein retention and bakery crust management.
Electric technology holds the leading position in new specifications, while digital control platforms are climbing the fastest as connectivity becomes standard.
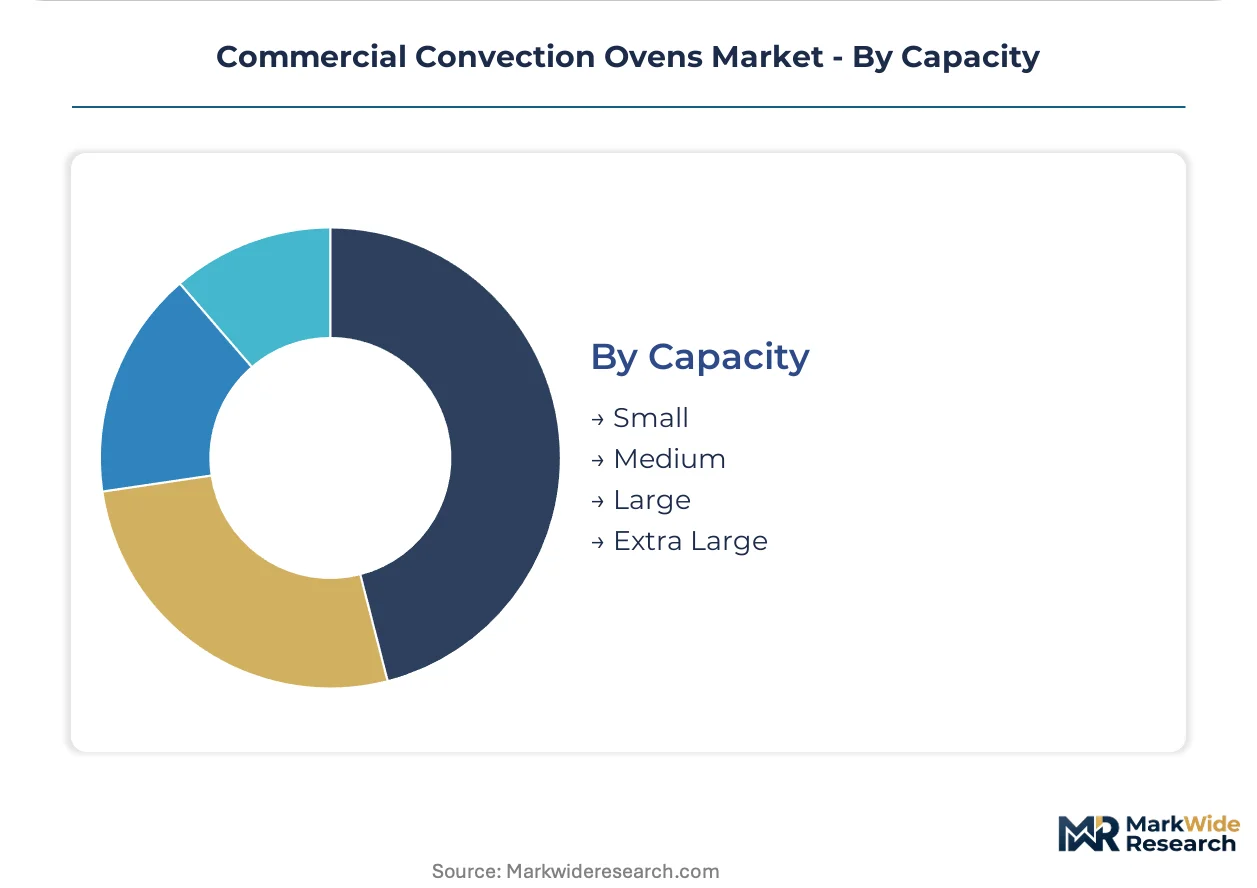
Capacity:
Equipment sizing follows kitchen footprint constraints and peak throughput requirements across operator types.
- Large:Multi-rack platforms with cavity volumes exceeding standard institutional thresholds, specified by hotels and central commissaries for banquet batch processing. These units command premium pricing but face longer sales cycles due to ventilation and electrical infrastructure requirements.
- Medium:Mid-tier cavity configurations balancing throughput and spatial efficiency, dominating independent restaurant and cafe procurement where back-of-house square footage is constrained.
- Small:Compact single or dual-rack units for limited-menu operators and front-of-house display cooking applications.
- Extra Large:Custom-configured platforms for industrial-scale food production facilities and military base feeding operations.
Large capacity equipment generates the highest revenue per unit, though medium capacity segments are expanding most quickly across independent operator channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level electrification rebates and federal efficiency mandates are redrawing equipment procurement patterns across foodservice-dense geographies, concentrating replacement demand in jurisdictions with the most aggressive decarbonization timelines.
United States
Chain restaurant capex programs and ghost kitchen buildouts in Atlanta, Dallas, and Phoenix are accelerating convection oven replacement cycles. The Department of Energy's 10 CFR 431 standards tighten minimum cooking efficiency thresholds for electric and gas units alike. Los Angeles and New York City clusters see electric specification dominance as local ordinances restrict new gas hookups in commercial construction.
Germany
Institutional catering operations and hotel kitchen renovations in Berlin and Munich drive floor-standing equipment demand. The EU F-Gas Regulation and national Energiewende targets elevate electric platform preference in new-build specifications. The Rhine-Ruhr industrial corridor hosts fabrication capacity serving central European foodservice dealer networks.
United Kingdom
Quick-service expansion and delivery kitchen proliferation in Greater London and Manchester concentrate high-speed oven procurement. The UK Net Zero Strategy and impending gas boiler phase-out timelines pressure operators toward electric conversion. Birmingham's foodservice equipment distribution hub channels specification influence across mid-market independent restaurants.
Japan
Compact kitchen footprints in Tokyo and Osaka favor countertop and medium-capacity convection platforms for cafe and convenience store chains. METI's Top Runner program sets escalating efficiency benchmarks for commercial cooking equipment. The Nagoya manufacturing belt supplies precision-controlled digital platforms to domestic and export markets.
Canada
Hotel banquet operations and central commissaries in Toronto and Vancouver sustain demand for large-capacity floor-standing units. Natural Resources Canada's ENERGY STAR specification alignment and provincial rebate programs in British Columbia and Quebec tilt new specifications toward electric technology. Montreal's foodservice equipment distribution network channels specification influence across Atlantic Canada.
Commercial Convection Ovens Market Competitive Environment
Player mix skews toward diversified foodservice equipment conglomerates with captive distribution networks, creating tiered competitive dynamics where scale-driven fabricators compete against specialized high-technology developers. The vendor base stratifies across three archetypes: heavy-duty institutional specialists, high-speed impingement innovators, and value-oriented countertop suppliers. Consolidation pressure mounts as NSF/ANSI Standard 4 compliance costs and DOE efficiency testing requirements raise capital barriers. Dominant competitive moves include vertical integration into dealer networks and technology licensing partnerships for accelerated cooking platforms.
Among North American fabricators, Blodgett and Vulcan occupy positions within the heavy-duty institutional tier, while TurboChef exemplifies the high-speed impingement archetype. Blodgett's manufacturing scale in floor-standing platforms serves hotel and commissary operators requiring batch throughput reliability. Vulcan anchors gas-powered segment presence through foodservice dealer network penetration. TurboChef's jet-array forced-air configurations command specification preference among quick-service operators competing on drive-thru velocity metrics.
| Leading Market Players |
|---|
| TurboChef |
| VEVOR |
| Blodgett |
| Southbend |
| Avantco |
| Vulcan |
| Cadco |
| Moffat |
| Hobart |
| Others |
Value Chain & Pricing Dynamics
Long-term equipment lease arrangements with bundled maintenance clauses lock in supply access for multi-unit operators while capping price volatility exposure across the analysis window. California and New York foodservice chains favor these structures to navigate state-level electrification mandates without bearing full capital risk on rapidly evolving efficiency standards.
Pricing Analysis
NSF/ANSI Standard 4 certification tier creates the primary spread between premium fabricators and value-tier competitors in this market. Three-tier pricing structure across NSF-certified premium, standard commercial-grade, and uncertified economy levels governs procurement decisions. Price differentiation rests on splash-test validation investment and food-zone sanitation engineering. Cost compression in mid-tier fabrication is intensifying because 304-grade stainless steel input swings compress margins. Ghost kitchen operators and emerging franchisees exhibit highest price sensitivity, while institutional hotel chains prioritize certification compliance over unit economics.
Supply Chain Analysis
Inventory lead times for control systems and fan-motor assemblies have extended as semiconductor allocation prioritizes automotive and consumer electronics. Manufacturing concentration centers on the United States, Germany, and China, with the Rhine-Ruhr corridor and Nagoya belt hosting precision fabrication capacity. Component sourcing draws from Mexican metal-stamping operations for chassis fabrication and Chinese PCB assembly for digital control platforms. Single-source vulnerability in high-temperature alloy supply creates exposure to commodity price volatility. Distribution runs through captive foodservice dealer networks and direct-specification channels to chain accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment specification increasingly hinges on integrated digital control engineering and NSF certification testing capabilities that only a handful of fabricators have built in-house. This capability scarcity concentrates margin capture among incumbents with validated testing protocols and dealer network lock-in.
For Market Incumbents: Fortify certification testing infrastructure and backward integration into stainless steel component fabrication to defend against emerging high-speed impingement specialists. Expand captive dealer network coverage in Atlanta, Dallas, and Phoenix where ghost kitchen buildouts concentrate demand. Prioritize ENERGY STAR portfolio breadth to maintain access to institutional accounts with sustainability scorecards. For New Entrants and Emerging Players: NSF/ANSI Standard 4 fast-track certification programs offer entry pathways for regional fabricators targeting catering services and independent cafe segments. The countertop electric category remains most penetrable given ventilation constraints and utility incentive alignment in California and Massachusetts. Pursue equipment-as-a-service financing partnerships to bypass capital-purchase barriers among emerging franchisees. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier fabricators with dormant certification capabilities and established regional dealer relationships that can be activated through testing investment. Long-term viability favors platforms with electric technology roadmaps and IoT connectivity architectures. Monitor state-level gas hookup restriction ordinances as inflection signals for electric specification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certification Fast-Track Investment | Accelerates market entry for regional fabricators targeting institutional procurement channels. |
| Backward Integration into Control Systems | Reduces dependency on semiconductor allocation volatility and protects margin capture. |
| Equipment-as-a-Service Platform Launch | Captures ghost kitchen operators with constrained balance sheets and high replacement velocity. |
| High-Speed Impingement Technology Licensing | Enables quick-service ticket-time compression without captive R&D investment. |
| Utility Rebate Partnership Programs | Locks in specification preference in California, New York, and Massachusetts electrification markets. |
Study Parameters
A standing panel of foodservice equipment procurement directors, commercial kitchen design consultants, NSF certification testing engineers, and chain restaurant capex planners provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with these stakeholders and secondary validation against DOE 10 CFR 431 filings, EPA ENERGY STAR qualification databases, NSF International certification registries, and foodservice dealer inventory records. Bottom-up unit shipment modeling and top-down value chain triangulation anchored volume and value estimates.
Consistency checks against external benchmarks validated projection outputs across the modeling period. The analytical framework segmented by product type, technology platform, end-user vertical, and capacity tier, with regional regulatory cluster as an additional dimension. CAGRs were derived from installed base replacement cycle analysis and new-build specification trend extrapolation. Forecast inputs incorporated utility incentive program budgets, state electrification mandate timelines, and stainless steel price index trajectories.
The analysis sits within stated boundaries; outcomes outside assumed utility rebate continuity and NSF protocol stability would require recalibration. Forecasts reflect documented assumptions about electrification policy trajectory and commodity input cost normalization. Supply chain disruption, tariff regime shifts, or accelerated efficiency standard tightening could materially revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Popcorn Machine Market
Food Service Equipment
Commercial Slush Machine Market
Food Service Equipment
Commercial Refrigerated Display Cabinet Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Commercial Electric Restaurant Ranges Market
Food Service Equipment
Commercial Foodservice Equipment Market
Food Service Equipment
Global QSR Food Service Equipment Market
Food Service Equipment
Commercial Ventless Cooking Equipment Market
Food Service Equipment
Food Thermos Market
Food Service Equipment
Europe Walk-In Refrigerators and Freezers Market
Food Service Equipment
Multi Cooker Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Specialty Commercial Deep Fryers Market
Food Service Equipment
Meal Delivery Carts and Racks Market
Food Service Equipment
Reach-In Refrigerators Market
Food Service Equipment
Portable Cooler Market