
 Food Automation Market | 2026-2036
Food Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Food Automation Market Intelligence
Revenue from software and AI-driven analytics is tilting the profit pool away from traditional hardware sales. Rockwell Automation leverages its extensive software portfolio to offer integrated factory solutions connecting production and enterprise systems. Siemens AG competes by embedding digital twin technology into its process automation platforms for simulation and optimization. FANUC Corporation sustains its market position through leadership in high-precision robotic arms for delicate food handling.
Food automation involves deploying robotic, control, and software systems to manage repetitive tasks in food processing and packaging. These systems often employ computer vision with high-speed cameras and specialized lighting to detect defects at speeds exceeding human capability. The primary purpose is to enhance production efficiency, ensure stringent hygiene, and provide detailed traceability data. Robotic systems for end-of-line palletizing represent a mature application, while AI-enhanced quality inspection systems are attracting significant new investment from food processing plants.
Regulations such as the FDA's Food Safety Modernization Act in the United States and the EU's General Food Law require stringent traceability, directly promoting automated data logging. Compliance with hygienic design standards from organizations like EHEDG further influences equipment selection and facility layout. The critical decision for end-users is whether to invest in integrated single-vendor ecosystems or build modular systems using open, interoperable technologies for future scalability.
Market Dynamics
The convergence of AI-driven analytics with stringent regulatory mandates for food traceability is the central force shaping the market. This dual pressure compels food processors to invest in integrated systems that connect factory floor operations with enterprise-level data platforms.
Growth Catalysts
- Regulatory Mandates:The FDA's Food Safety Modernization Act and EU's General Food Law require automated data logging, driving investment in compliant systems.
- Predictive Maintenance:Machine learning adoption for analytics reduces unplanned downtime, a critical metric for high-volume food and beverage manufacturers.
- Beverage Sector Throughput:Beverage producers are investing in high-speed automation to increase production volume and ensure consistent quality across batches.
Market Restraints
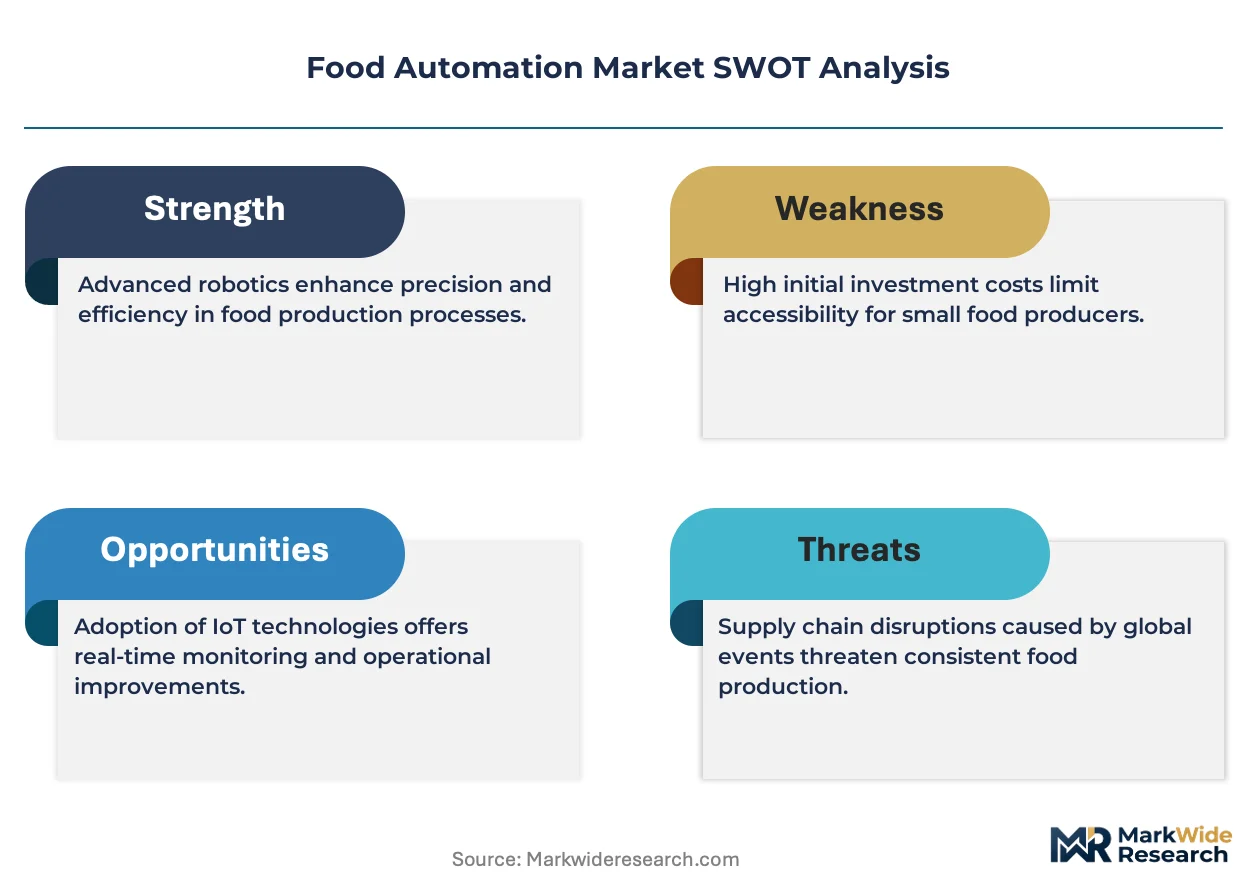
- High Capital Costs:The significant initial investment for integrated robotic systems is a primary barrier for small and medium-sized food processors.
- Product Handling Limits:Automation struggles with delicate, non-uniform items like fresh produce, restricting its use in certain processing segments.
- Component Concentration:Supply of critical parts like high-precision robotic arms is concentrated among a few vendors, creating sourcing risks.
Strategic Opportunities
- AI-Powered Inspection:AI-enhanced quality inspection using computer vision is a key growth area, moving beyond mature end-of-line applications.
- Indian Market Penetration:India's food processing sector, backed by government PLI schemes, offers a substantial opportunity for automation providers.
- Digital Twin Services:Integrating digital twin technology with automation platforms enables virtual commissioning, creating new service-based revenue.
Industry Challenges
- Specialized Skills Gap:A shortage of technicians skilled in food science and mechatronics hinders effective implementation and maintenance of automated systems.
- Legacy System Integration:Integrating new automation with older production lines creates significant software and hardware compatibility challenges for food processors.
- Hygienic Design Compliance:Adhering to EHEDG standards requires specialized, costlier equipment, complicating system design and validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Automation Market |
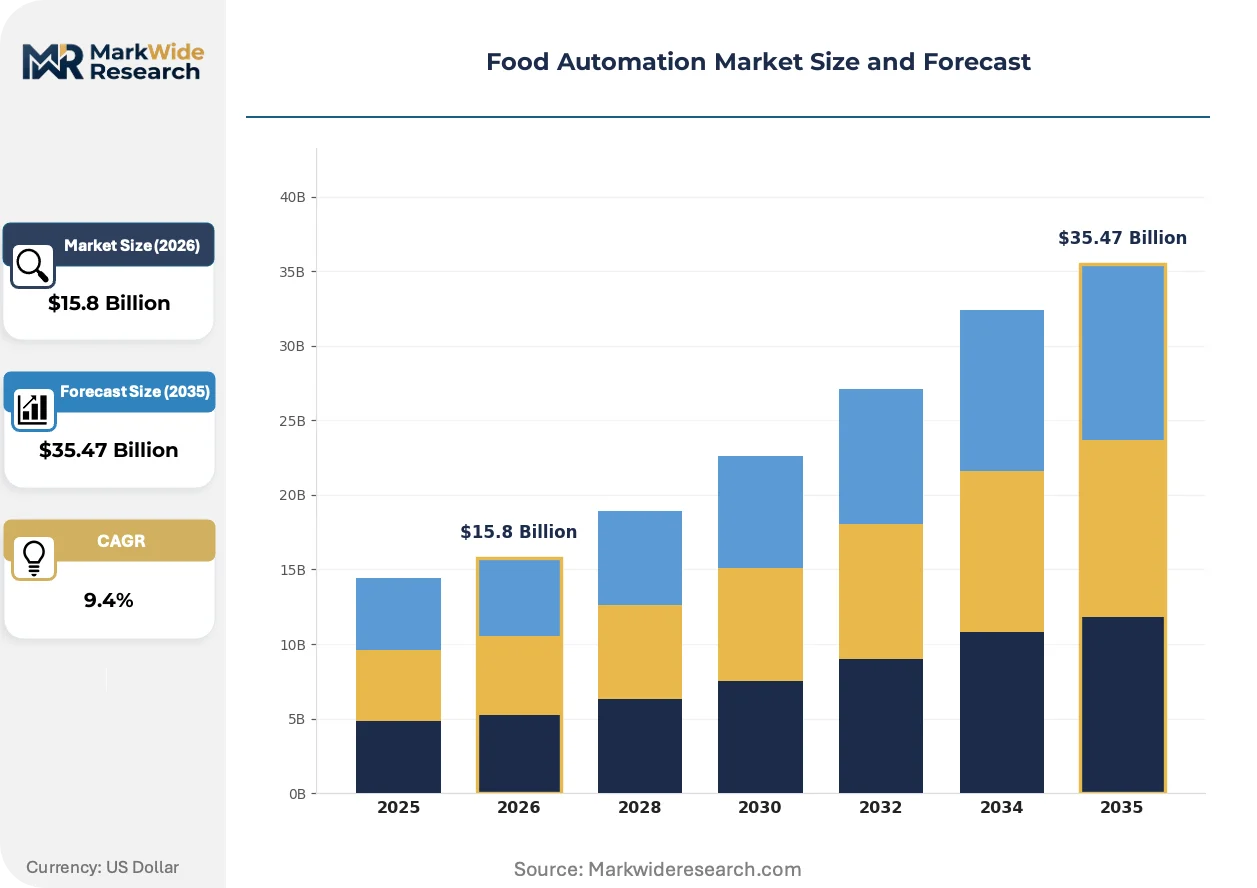
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $35.47 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
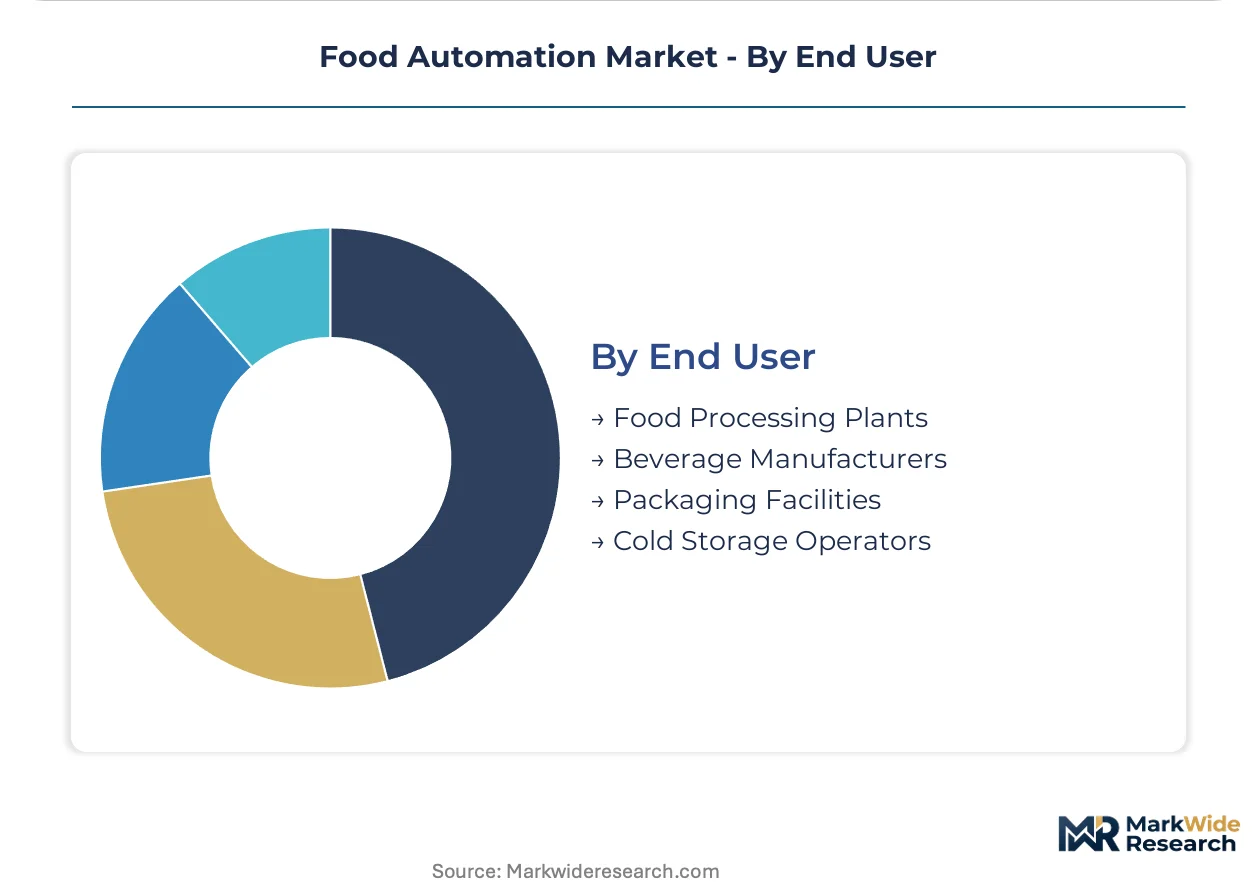
| Segmentation | Product Type: Robotic Systems, Conveyor Systems, Vision Systems, Automated Packaging, Dispensing Machines Technology: Artificial Intelligence, Machine Learning, Internet of Things, Computer Vision, Sensor Technology Application: Sorting, Filling, Labeling, Quality Inspection, Palletizing End User: Food Processing Plants, Beverage Manufacturers, Packaging Facilities, Cold Storage Operators |
| Companies Covered | GEA Group, Yaskawa Electric Corporation, Rockwell Automation, Emerson Electric Co., KUKA AG, Siemens AG, FANUC Corporation, JBT Corporation, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Automation Market Strategic Shifts & Innovations
The market's evolution is defined by a fundamental shift from hardware-centric sales to software-defined, data-driven operational models. This transition merges operational technology on the factory floor with enterprise-level IT systems for advanced analytics and control.
Digital twin technology creates a real-time, virtual replica of a physical food production line. Major beverage and packaged food manufacturers are adopting this for process simulation and operator training. This technology is virtualizing the commissioning and optimization lifecycle, reducing physical trial-and-error and accelerating time-to-market.
The European Union's proposed AI Act introduces risk-based classifications for artificial intelligence systems used in industrial settings. This regulation will impose new validation and documentation requirements on AI-driven quality control and predictive maintenance software. Automation software providers are consequently embedding auditable data logging and explainability features into their platforms.
End-users are shifting from large, upfront capital purchases toward flexible, subscription-based models for automation software. This "Automation-as-a-Service" approach is displacing traditional equipment sales, especially for AI-driven analytics and predictive maintenance modules. The trend is most visible in North America, where processors convert capital into operating expenses.
Food Automation Market Segmentation
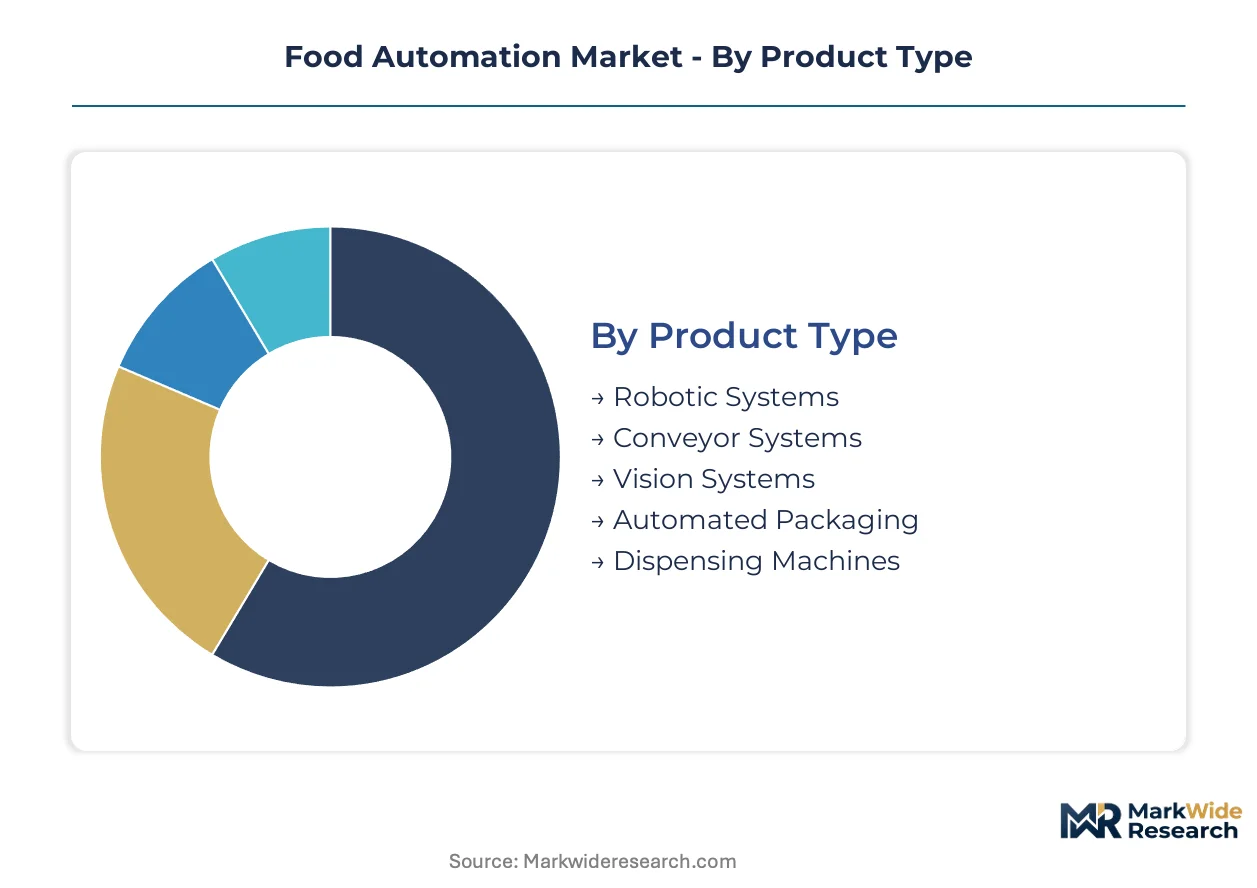
Understanding the segmentation within the food automation market is critical for identifying areas of concentrated investment and technological advancement. This analysis dissects the market by product type, underlying technology, specific application, and end-user categories, revealing distinct growth patterns and operational priorities.
Product Type:
The product type segmentation reveals a spectrum from mature, standardized solutions to emerging, highly specialized systems.
- Robotic Systems:These automated machines, often articulated or collaborative, perform precise, repetitive tasks like picking, placing, and assembly in food processing environments. Demand is concentrating among beverage manufacturers seeking high-speed, consistent product handling for increased throughput.
- Automated Packaging:Systems for automated packaging encompass primary, secondary, and tertiary packaging operations, including filling, sealing, labeling, and carton erection. This segment sees significant investment from large food processing plants aiming to reduce labor costs and ensure packaging integrity under stringent hygiene standards.
- Conveyor Systems:These mechanical systems transport food products and packaging materials through various stages of processing and packaging lines.
- Vision Systems:Utilizing high-speed cameras and specialized lighting, vision systems perform automated inspection and quality control tasks, detecting defects at high speeds.
- Dispensing Machines:Automated dispensing machines accurately measure and deliver ingredients or finished products, ensuring consistency in formulation and portion control.
Conveyor Systems handle the majority of throughput; Robotic Systems are the fastest mover on share.
Technology:
Technology adoption within food automation is heavily influenced by the complexity of data processing and real-time decision-making requirements.
- Artificial Intelligence:AI-driven algorithms power advanced decision-making in quality inspection, predictive maintenance, and process optimization by analyzing vast datasets. AI-enhanced quality inspection systems are attracting significant new investment from food processing plants, moving beyond mature applications.
- Machine Learning:A subset of AI, machine learning enables systems to learn from data without explicit programming, improving performance over time in tasks like pattern recognition and anomaly detection. Its adoption for predictive maintenance significantly reduces unplanned production downtime for high-volume food and beverage manufacturers.
- Internet of Things:IoT involves interconnected sensors, devices, and systems that collect and exchange data across the food production environment.
- Computer Vision:This technology enables machines to interpret and understand visual information from images or videos, crucial for defect detection and object recognition.
- Sensor Technology:Sensors gather real-time data on parameters such as temperature, pressure, humidity, and product characteristics, forming the foundation for automated control.
Sensor Technology provides foundational data; Artificial Intelligence solutions are driving the highest value creation.
Application:
Application segments are differentiated by the specific operational challenges they address, ranging from high-speed processing to meticulous quality control.
- Quality Inspection:Automated quality inspection systems use technologies like computer vision and AI to identify defects, foreign objects, or inconsistencies in food products. AI-enhanced quality inspection systems are attracting significant new investment from food processing plants for their ability to detect subtle flaws.
- Palletizing:Robotic palletizing systems automate the stacking of packaged products onto pallets for storage and transportation, representing a mature application in end-of-line automation. This application is widespread among beverage and packaged food manufacturers due to its efficiency and labor-saving benefits.
- Sorting:Automated sorting systems separate food items based on various criteria such as size, color, shape, or quality using vision systems and robotic manipulators.
- Filling:Automated filling machines accurately dispense liquids, powders, or solids into containers, ensuring consistent product volume and weight.
- Labeling:Robotic and automated labeling systems apply labels to food packages, ensuring compliance with regulatory requirements and brand presentation.
Palletizing applications represent significant installed capacity; Quality Inspection systems are experiencing the steepest expansion trajectory.
End User:
End-user segments are characterized by varying scales of operation and distinct regulatory compliance needs.
- Food Processing Plants:These facilities handle raw food materials through various stages of preparation, cooking, and preservation before packaging. The massive food processing sector in China, supported by government industrial upgrades, represents a strong demand center for integrated automation solutions.
- Beverage Manufacturers:Companies producing alcoholic and non-alcoholic beverages utilize automation for high-speed filling, sealing, and packaging lines. Beverage manufacturers are investing in high-speed automation to increase production volume and ensure consistent quality across batches.
- Packaging Facilities:Dedicated packaging facilities specialize in the final stages of product packaging, including secondary and tertiary operations for various food products.
- Cold Storage Operators:These operators manage temperature-controlled warehouses, employing automation for efficient material handling, inventory management, and order fulfillment in chilled or frozen environments.
Food Processing Plants constitute the largest customer base; Beverage Manufacturers are demanding the most advanced high-throughput solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The food automation market exhibits distinct consumption patterns across geographies, with some regions prioritizing efficiency gains in high-volume production while others focus on quality and safety compliance. Automation adoption reflects regional economic development, labor costs, and the maturity of food processing industries. Government initiatives and regulatory frameworks significantly influence investment decisions in integrated systems.
United States
Demand for food automation in the United States stems from labor shortages and the need for enhanced food safety. The FDA's Food Safety Modernization Act mandates stringent traceability, compelling processors to adopt automated data logging solutions. Major food processing clusters in the Midwest, particularly around Chicago and Minneapolis, are investing heavily in robotic systems for improved efficiency and compliance.
China
China represents a significant demand center for integrated automation solutions, driven by its massive food processing sector and government support for industrial upgrades. The Chinese government's "Made in China 2025" initiative promotes advanced robotics and smart manufacturing in food production. Industrial parks in the Yangtze River Delta are seeing rapid deployment of AI-enhanced quality inspection systems and automated packaging lines.
Germany
Germany's food automation market is characterized by a strong emphasis on precision engineering and advanced process control. Compliance with the EU's General Food Law drives investment in automated data logging and hygiene-focused equipment. The Bavaria region, with its robust manufacturing base, leads in the adoption of digital twin technology for process simulation and optimization in beverage production.
India
India's food processing sector offers substantial opportunities for automation providers, backed by government Production Linked Incentive (PLI) schemes. These schemes encourage domestic manufacturing and technology adoption in food and beverage production. Food processing hubs in Maharashtra and Gujarat are emerging as key areas for investment in automated sorting and packaging solutions.
Japan
Japan's food automation market prioritizes high-precision robotics and advanced sensor technology due to an aging workforce and stringent quality standards. METI initiatives support the development of smart factory solutions for food production. The Kanto region, including Tokyo, sees strong adoption of sophisticated robotic arms for delicate food handling and end-of-line palletizing.
Food Automation Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered market structure. The food automation market features a mix of established industrial automation giants and specialized robotics firms. Strategic archetypes include diversified automation providers, niche robotic specialists, and software-centric analytics companies. Dominant competitive moves involve strategic partnerships for integrated solutions and continuous portfolio diversification into AI-driven analytics.
Within the diversified automation provider tier, Siemens AG offers integrated factory solutions connecting production and enterprise systems, leveraging its extensive software portfolio. FANUC Corporation sustains its market position through leadership in high-precision robotic arms for delicate food handling. ABB occupies a position as a leading supplier of industrial robots and automation technologies across various food processing applications.
| Leading Market Players |
|---|
| GEA Group |
| Yaskawa Electric Corporation |
| Rockwell Automation |
| Emerson Electric Co. |
| KUKA AG |
| Siemens AG |
| FANUC Corporation |
| JBT Corporation |
| ABB |
| Others |
Cost & Logistics Intelligence
Shipping costs along major global corridors like the Suez Canal directly influence the landed cost of food automation components, thereby shaping supply concentration and downstream price differentiation in the market.
Pricing Analysis
Long-term project-based contracts dominate the high-value food automation segment, especially for integrated systems. Price differentiation stems from the level of customization required and the depth of after-sales service bundles offered. Pricing pressure from high initial capital costs is significant for small and medium-sized food processors. Large beverage manufacturers, seeking advanced high-throughput solutions, exhibit lower price sensitivity compared to smaller general food processing plants.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are increasingly critical for component procurement from Asian manufacturers. Geographic supply concentration for key components exists in countries like China, Germany, and Japan. The market draws from specialized raw materials such as high-precision robotic arms and advanced vision system sensors. Single-source vulnerability for critical parts like AI chips poses a structural supply chain risk. Distribution of food automation solutions primarily occurs through direct sales channels and specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food automation market presents a fragmentation opportunity, driven by the specialized demand for AI-enhanced quality inspection systems creating new niches.
For Market Incumbents: Pre-empt emerging software-centric analytics companies by aggressively expanding proprietary software portfolios and integrating AI capabilities into existing hardware platforms. Form strategic partnerships with niche AI firms to counter the threat from specialized software providers. Invest heavily in R&D for digital twin technology to offer virtual commissioning services. Enhance channel control through comprehensive training and certification programs for system integrators.
For New Entrants and Emerging Players: Pursue underpenetrated application areas like AI-enhanced quality inspection in fresh produce processing, where existing automation struggles. Target India's food processing sector with modular, scalable solutions, leveraging government PLI schemes. Develop subscription-based Automation-as-a-Service models to lower upfront capital barriers for small and medium-sized processors. Focus on open, interoperable technologies to facilitate easier integration with legacy systems.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial automation conglomerates seeking to divest non-core food-specific software divisions. Long-term viability rests on sustained demand for production efficiency and stringent traceability. Specialized AI software firms with proven computer vision capabilities represent an attractive acquisition archetype. The signal to watch is the increasing regulatory clarity and adoption rates of the EU's proposed AI Act for industrial applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Proprietary Software Portfolio | Deepens customer lock-in and shifts revenue to higher-margin software services. |
| Invest in AI-Enhanced Inspection R&D | Addresses a key growth area and differentiates offerings beyond mature applications. |
| Form Strategic Partnerships | Expands market reach and integrates specialized capabilities quickly into solutions. |
| Develop Automation-as-a-Service Models | Lowers entry barriers for end-users, converting capital expenditure to operational expenditure. |
| Target India Market Penetration | Capitalizes on government support and a rapidly expanding food processing sector. |
Research Approach
Initial hypotheses were tested against primary input from food processing plant managers, automation engineers, regulatory compliance officers, and equipment procurement specialists, then refined through iterative feedback. This primary research was validated against secondary sources including government industrial reports, company annual reports, and industry association publications. A combination of bottom-up and top-down triangulation ensured data accuracy.
Demand-supply balance modeling formed the core of the quantitative framework, projecting market evolution across the analysis window. Segmentation dimensions included product type, technology, application, end-user, and regional adoption rates. Compound Annual Growth Rates were derived from historical data trends and projected technological advancements. Key industry-specific forecast inputs included global food consumption patterns and labor cost inflation rates.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or industrial capital expenditure would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and technological progression. Geopolitical instability or significant supply chain disruptions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Non-Thermal Food Processing Market
Food Processing Equipment
Edible Collagen Casing Market
Food Processing Equipment
Homogenizers Market
Food Processing Equipment
Ice-Cream Maker Market
Food Processing Equipment
Global Industrial Bakery Processing Equipment Market
Food Processing Equipment
Shawarma Grill Machine Market
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
Deaeration Machine Market
Food Processing Equipment
Food Industry Pulsed Electric Field (PEF) Systems Market
Food Processing Equipment
Middle East and Africa Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Fluidized Bed Dryer Market
Food Processing Equipment
Spray Drying Equipment Market
Food Processing Equipment
Mobile Bottling Line Market
Food Processing Equipment
Aseptic Processing Market
Food Processing Equipment
Dual-Ovenable Cook Trays Market
Food Processing Equipment
Blast Chillers Market