
 Continuous Fryer Machine Market | 2026-2036
Continuous Fryer Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Fryer Machine Market Outlook
Buyer concentration among quick service restaurant chains is hardening as top operators standardize equipment specs across thousands of locations. Heat and Control leverages its integrated processing systems to capture multi-site contracts, while Middleby Corporation sustains broad kitchen equipment portfolios that span fryers through final assembly. JBT Corporation anchors its position through advanced thermal processing technologies that reduce oil degradation rates.
A continuous fryer machine is an industrial cooking system that submerges food products in heated oil on a conveyorized belt, typically operating at temperatures between 175°C and 190°C with oil turnover rates engineered to preserve product quality and extend frying media life. Its primary purpose is to deliver uniform, high-volume cooking for breaded proteins, potato products, and extruded snacks in automated food manufacturing environments. Gas fryers retain cost advantages in regions with pipeline infrastructure, while high-efficiency fryers are gaining share where energy tariffs and carbon accounting intensify. Modular installation configurations dominate greenfield plant designs, though inline systems command premium positioning in facilities optimizing linear product flow.
The U.S. FDA and USDA impose strict oil quality and food safety standards that shape equipment design, filtration integration, and documentation capabilities for domestic manufacturers. In Europe, EFSA guidelines and EU Green Deal energy-efficiency directives push vendors toward reduced thermal loss and alternative heating architectures. Stakeholders must monitor how regulatory divergence between North American and European safety frameworks influences R&D allocation and certification costs for cross-border equipment suppliers.
Market Dynamics
Quick service restaurant chains are consolidating equipment specifications across multi-site rollouts, forcing continuous fryer vendors to design for standardized filtration, temperature logging, and remote diagnostics that satisfy corporate procurement mandates.
Growth Catalysts
- FSMA Preventive Controls:The U.S. FDA's updated rules on preventive controls for human food mandate integrated oil monitoring and documentation systems. Food processors are retrofitting lines with automated filtration to achieve compliance.
- Snack Processing Automation:Large-scale potato and extruded snack facilities in the United States are modernizing legacy batch fryers with continuous systems to hit throughput targets above five metric tons per hour.
- Electrification Infrastructure:High-efficiency electric heating architectures are gaining share in regions where energy tariffs and carbon accounting intensify, displacing legacy gas-fired units in greenfield plant designs.
Market Restraints
- Stainless Steel Input Volatility:Grade 304 and 316 stainless steel price swings compress fabrication margins for equipment builders, particularly those sourcing from concentrated Asian mill networks.
- Filtration Media Supply Concentration:Specialized filter paper and activated carbon for oil regeneration concentrate among a handful of European and Japanese suppliers, creating single-source vulnerability.
- Combustion Efficiency Ceilings:Gas-fired fryers face thermodynamic limits on heat transfer efficiency that electric and induction alternatives are beginning to breach, threatening their long-term positioning in carbon-regulated markets.
Strategic Opportunities
- India Snack Processing:India's organized savory snack sector is underpenetrated by continuous frying technology, with most operations still running batch kettles that offer retrofit potential for automated lines.
- EU Green Deal Thermal Efficiency:The EU Green Deal's energy-efficiency directives create regulatory tailwinds for fryer designs with reduced thermal loss and waste heat recovery systems.
- Induction-Electric Convergence:The pairing of induction heating with precision temperature control is opening white space in premium poultry and seafood processing where oil degradation must be minimized.
Industry Challenges
- Controls Engineering Talent Gap:Vendors struggle to hire PLC programmers and thermal process engineers capable of integrating IoT-enabled diagnostics with legacy plant SCADA architectures.
- UL and CE Certification Timelines:Dual certification for cross-border equipment suppliers stretches validation cycles, delaying revenue recognition on orders destined for multi-national QSR rollouts.
- Legacy Line Integration Complexity:Brownfield snack and poultry plants require custom conveyor interfaces and oil management retrofits that erode margin on otherwise standard equipment sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Fryer Machine Market |
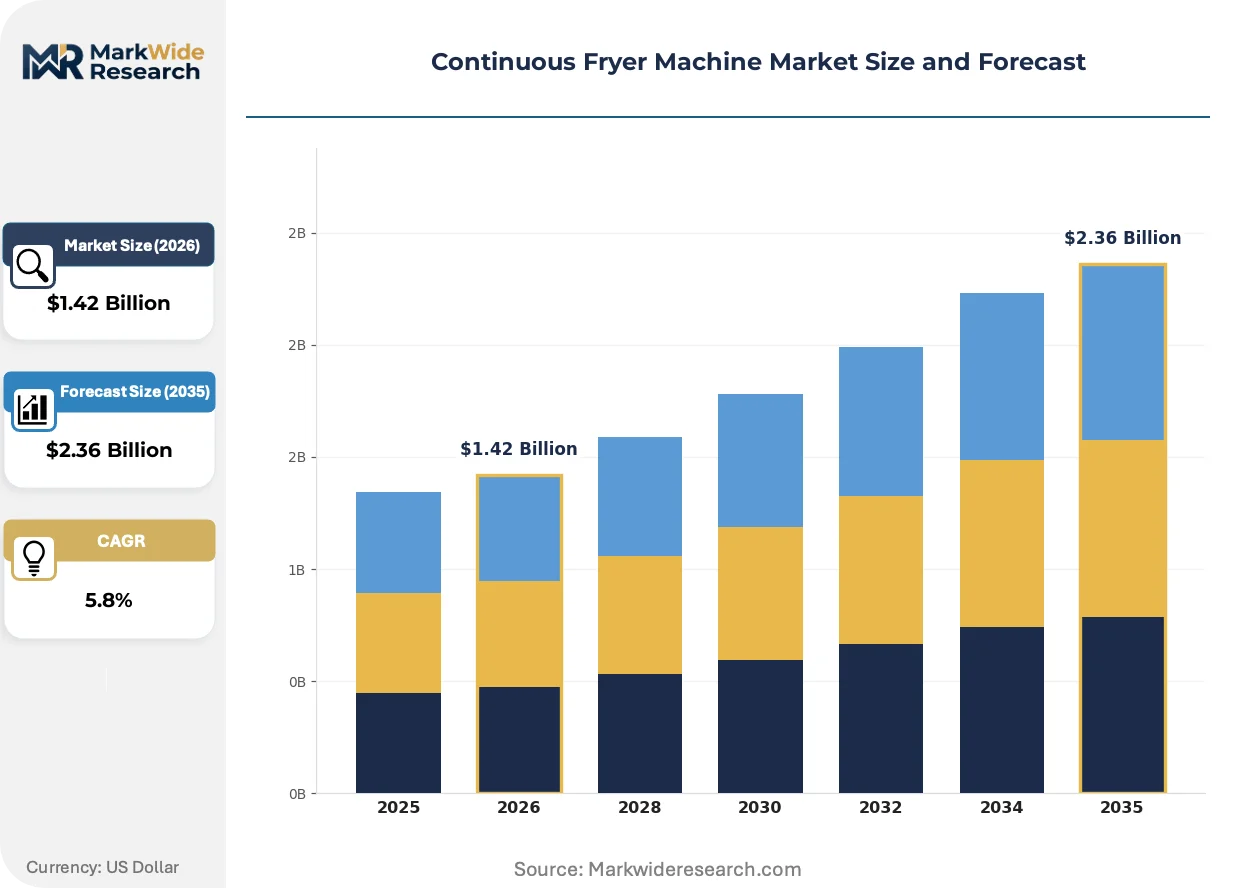
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical Fryers, Gas Fryers, High-Efficiency Fryers, Multi-Product Fryers End User: Food Processing Plants, Quick Service Restaurants, Catering Services, Snack Manufacturers Installation Type: Modular, Inline, Floor-Mounted, Countertop Frying Technology: Convection Frying, Deep-Frying, Continuous Operation, Vacuum Frying |
| Companies Covered | Heat and Control, TNA Australia, Middleby Corporation, JBT Corporation, GEA Group, Ali Group, Frymaster, Electrolux Professional, Kiremko, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Fryer Machine Market Strategic Shifts
Automation architectures in continuous frying are converging on predictive maintenance and closed-loop oil quality management, reshaping how processors justify capital expenditure and operational technology investments.
Induction heating systems are expanding into high-volume protein processing by delivering precise temperature control that reduces oil polymerization and extends frying media life. Poultry processors in the United States and Western Europe are piloting these units at 15-20% premium over gas equivalents. The technology is expanding into premium product categories where oil degradation directly impacts finished goods quality and brand reputation.
The EU F-Gas Regulation and parallel EPA SNAP program are restricting hydrofluorocarbon use in refrigeration-linked oil cooling systems, forcing fryer builders to specify natural refrigerants or dry cooling alternatives. Equipment vendors serving trans-Atlantic markets must now engineer dual-compliant thermal management architectures. Snack processors in Germany and the Netherlands are absorbing the highest compliance costs as they retrofit ammonia-based cooling into existing plant footprints.
Corporate procurement teams at major QSR chains are unbundling equipment purchase from aftermarket service, negotiating multi-year oil management and parts contracts separately from capital outlays. This disintermediation compresses vendor margins on the initial sale while locking in recurring revenue streams for service-capable suppliers. The pattern is most visible in the United States, where three national chicken chains have standardized this bifurcated contracting model across their franchise networks.
Continuous Fryer Machine Market Segmentation
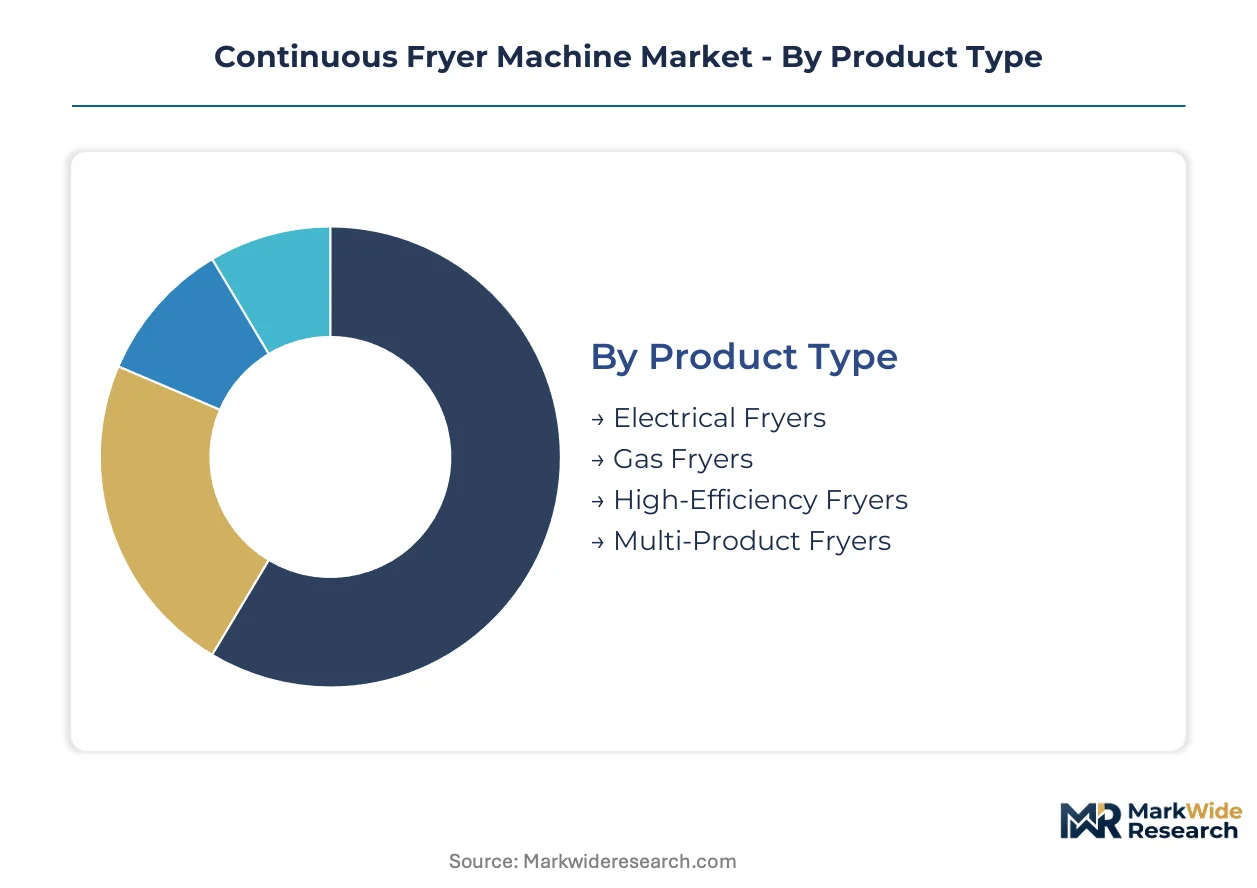
Continuous fryer configurations vary sharply by thermal architecture, operational scale, and integration complexity. Procurement teams weigh capital outlay against energy tariffs, throughput requirements, and retrofit feasibility when segmenting vendor shortlists.
Product Type:
Standardization dominates at the commodity end, while premium tiers demand bespoke thermal engineering and control system integration.
- Gas Fryers:These units deploy direct-fired burners beneath the oil reservoir, achieving rapid heat recovery between product batches. Pipeline infrastructure in the United States and Gulf states sustains demand, though carbon accounting pressures are narrowing their addressable market in regulated jurisdictions.
- High-Efficiency Fryers:Advanced insulation, heat exchanger recovery loops, and precision burner modulation cut energy consumption versus conventional designs. European snack processors facing EU Green Deal compliance deadlines are prioritizing these units despite 20-30% capital premiums.
- Electrical Fryers:Resistive or induction heating elements eliminate combustion emissions and suit facilities lacking gas hookups.
- Multi-Product Fryers:Programmable temperature zones and adjustable conveyor speeds accommodate breaded proteins, extruded snacks, and battered seafood on shared lines.
Most installed capacity flows through gas-fired units. Expansion is steepest in high-efficiency electric architectures.
End User:
Volume scale and technical sophistication diverge sharply between industrial processors and foodservice operators.
- Snack Manufacturers:Continuous systems running above five metric tons per hour dominate potato chip and extruded snack production. United States facilities are modernizing legacy batch kettles to hit throughput targets and reduce labor exposure to hot oil handling.
- Quick Service Restaurants:Corporate procurement teams standardize equipment specs across franchise networks, mandating integrated filtration, temperature logging, and remote diagnostics. Three national chicken chains have bifurcated capital purchase from aftermarket service contracts.
- Food Processing Plants:Integrated lines for breaded poultry and seafood require USDA-compliant sanitation protocols and oil regeneration systems.
- Catering Services:Smaller footprint units with rapid oil heat-up satisfy intermittent production schedules and mobile kitchen constraints.
Snack manufacturers deploy the largest individual units. QSR chains are driving standardization fastest.
Installation Type:
Greenfield flexibility contrasts with brownfield constraints across facility vintages.
- Modular:Self-contained sections ship separately and bolt together on-site, reducing crane requirements and construction timelines. New plant designs in the United States favor this approach for phased capacity expansion.
- Inline:Linear conveyor alignment with upstream forming and downstream cooling maximizes product flow efficiency. Premium poultry processors pay configuration premiums to minimize handling damage.
- Floor-Mounted:Heavy-duty frames anchor to plant slabs, supporting oil reservoirs above 500 liters and withstanding vibration from adjacent forming equipment.
- Countertop:Compact electric units serve demonstration kitchens, test facilities, and small-batch product development labs.
Modular systems claim the majority of new orders. Inline configurations command the highest per-meter pricing.
Frying Technology:
Thermal transfer mechanisms determine oil degradation rates, product moisture retention, and energy intensity.
- Deep-Frying:Full submersion in 175°C-190°C oil delivers the Maillard reactions and crust formation central to breaded protein and potato snack quality. FDA preventive control rules are pushing processors toward automated oil monitoring on these lines.
- Vacuum Frying:Reduced-pressure environments lower boiling points, preserving heat-sensitive nutrients and enabling lower-temperature processing of fruit chips and premium snacks. European health-positioned brands are piloting these systems for differentiated product lines.
- Convection Frying:Forced oil circulation improves temperature uniformity across the product bed and accelerates heat transfer to irregular shapes.
- Continuous Operation:Uninterrupted product flow with automated loading and discharge maximizes labor efficiency and throughput consistency.
Deep-frying retains the largest installed base. Vacuum frying is climbing the fastest among premium snack applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled thermal process engineers and PLC programmers concentrate in industrial clusters around Chicago, Stuttgart, and Shanghai, anchoring equipment innovation and aftermarket service capacity.
United States
Snack manufacturers in the Midwest and Southeast are modernizing legacy batch kettles to hit throughput targets above five metric tons per hour. The FDA's Food Safety Modernization Act preventive controls mandate integrated oil monitoring and documentation systems. Chicago anchors the largest concentration of equipment fabricators and thermal processing engineering talent.
Germany
European snack processors facing EU Green Deal energy-efficiency deadlines are prioritizing high-efficiency fryer designs despite capital premiums. The EU F-Gas Regulation restricts hydrofluorocarbon use in refrigeration-linked oil cooling systems, forcing ammonia-based retrofits. The Stuttgart industrial corridor hosts precision heating equipment specialists and filtration media engineering centers.
China
Domestic savory snack production is scaling automated lines to replace manual batch operations in coastal provinces. The country's national food safety regulator enforces increasingly stringent oil quality standards for processed foods. The Yangtze River Delta concentrates contract equipment fabricators serving both domestic processors and export markets.
India
Organized savory snack sector expansion is creating retrofit demand for continuous frying technology in Gujarat and Maharashtra. The Food Safety and Standards Authority of India is tightening enforcement on oil reuse practices in commercial food manufacturing. Ahmedabad and Mumbai host emerging equipment distributors and aftermarket service networks.
Netherlands
Premium potato processing facilities are piloting vacuum frying systems for differentiated health-positioned product lines. EFSA guidelines and EU Green Deal directives push vendors toward reduced thermal loss architectures. The Eindhoven region concentrates food technology research institutes and thermal process engineering consultancies.
Continuous Fryer Machine Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base clusters around three strategic archetypes: integrated processing system houses, broad kitchen equipment portfolios, and advanced thermal technology specialists. Consolidation pressure intensifies as quick service restaurant chains standardize specifications across multi-site rollouts. Dominant competitive moves include strategic partnerships for aftermarket service contracts and technology licensing for induction-electric heating architectures.
Among integrated system houses, Heat and Control and JBT Corporation exemplify the premium-tier positioning anchored by thermal processing specialization. Middleby Corporation occupies a diversified portfolio position spanning fryers through final assembly equipment. These three names represent the competitive tension between focused engineering depth and broad kitchen equipment coverage that defines procurement negotiations with large-scale snack and poultry processors.
| Leading Market Players |
|---|
| Heat and Control |
| TNA Australia |
| Middleby Corporation |
| JBT Corporation |
| GEA Group |
| Ali Group |
| Frymaster |
| Electrolux Professional |
| Kiremko |
| Others |
Value Chain & Pricing Dynamics
Induction-electric heating convergence in premium poultry processing simultaneously compresses fabrication margins and concentrates supply relationships among certified thermal component specialists. This technology shift forces equipment builders to absorb 15-20% capital premiums while locking in long-term contracts with induction coil and precision control system suppliers.
Pricing Analysis
The bundled-versus-unbundled service split now defines transaction structures across quick service restaurant procurement teams. Three-tier pricing structure across premium, standard, and economy levels separates induction-electric systems with predictive maintenance from gas-fired baseline units and refurbished legacy lines. Price differentiation hinges on UL/CE dual certification status and aftermarket service contract duration. Cost compression in standard gas-fired tiers is intensifying because stainless steel input volatility erodes builder margins. Snack manufacturers in the United States exhibit the highest price sensitivity, while premium poultry processors absorb technology premiums to minimize oil degradation.
Supply Chain Analysis
UL and CE certification gating concentrates qualified fabrication capacity among established vendors with validated thermal management architectures. Stainless steel feedstock draws from Chinese, Japanese, and South Korean mill networks, while specialized filter paper and activated carbon for oil regeneration sources from European and Japanese suppliers. Single-source vulnerability in filtration media creates procurement risk for equipment builders assembling integrated lines. Distribution runs through direct OEM sales teams for large-scale processors and regional distributor networks for mid-tier foodservice operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The continuous fryer machine market offers margin-expansion pathways through aftermarket service unbundling and premium-tier induction system adoption. Energy tariff differentials and carbon accounting mandates justify technology premiums that offset input cost pressures.
For Market Incumbents: Cement multi-site service contracts with quick service restaurant chains by standardizing remote diagnostics and predictive maintenance modules across franchise networks. Invest in backward integration into induction heating component supply to defend margin position against stainless steel volatility and specialized filter media concentration. Prioritize UL/CE dual certification capacity to accelerate revenue recognition on trans-Atlantic orders.
For New Entrants and Emerging Players: Digital channel partnerships with regional equipment distributors offer lower-friction entry into India's organized savory snack retrofit market. Target vacuum frying system white space in European health-positioned snack segments where EFSA guidelines and EU Green Deal directives accelerate premium equipment replacement cycles. Lead with modular installation configurations that reduce crane requirements and construction timelines for greenfield plant designs.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play thermal processing specialists with captive aftermarket service networks and induction-electric technology licensing positions. The five-to-ten-year viability window favors acquisitions of equipment fabricators with validated UL/CE dual certification pathways and established relationships with European filtration media suppliers. Monitor FSSAI enforcement intensity in India as the primary signal for retrofit demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Aftermarket Service Unbundling | QSR procurement teams now negotiate multi-year oil management contracts separately from capital sales, locking recurring revenue for capable suppliers. |
| Induction-Electric Technology Licensing | Precision temperature control reduces oil polymerization rates, extending frying media life for premium poultry and seafood processors. |
| Dual Certification Capacity Expansion | UL and CE validation cycles stretch revenue recognition timelines; certified fabricators capture multi-national QSR rollout orders faster. |
| Backward Integration into Filtration Media | European and Japanese supplier concentration creates single-source vulnerability; captive supply secures margin and delivery reliability. |
| Modular System Configuration Standardization | Self-contained sections reduce crane requirements and construction timelines, accelerating greenfield plant commissioning in the United States. |
Study Parameters
Coverage spans the United States, Germany, China, India, and the Netherlands, with primary inputs from each market cluster combining equipment fabricator interviews and secondary validation. Plant engineers at snack and poultry processing facilities, OEM procurement teams, aftermarket service heads, and thermal process engineering consultants provided qualitative demand and technology adoption perspectives. Secondary sources include FDA preventive control guidance documents, EU Green Deal energy-efficiency directive texts, FSSAI enforcement circulars, customs and trade flow data, and equipment vendor SEC filings. Bottom-up unit economics and top-down market sizing triangulate volume and value estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include thermal architecture, operational scale, installation configuration, and frying technology type, with regional regulatory cluster as an industry-specific overlay. CAGRs derive from fitted growth curves applied to base-year estimates, cross-checked against equipment shipment data and capacity expansion announcements. Energy tariff trajectories and carbon accounting policy intensity serve as scenario-weighting inputs.
Stainless steel price volatility, filtration media supply disruption, and regulatory divergence between FDA preventive controls and EFSA guidelines are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in EU Green Deal enforcement timelines or FSSAI oil reuse regulation stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Destemmer Market
Food Processing Equipment
Commercial Oven Market
Food Processing Equipment
Semi-Auto Egg Tart Forming Machine Market
Food Processing Equipment
Freeze-Drying Market
Food Processing Equipment
Microbrewery Equipment Market
Food Processing Equipment
Global Food Sterilization Machines Market
Food Processing Equipment
Hot Food Processing Equipment Market
Food Processing Equipment
Mixer Settler Market
Food Processing Equipment
Tortilla Machine Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Ice Cream Processing Equipment Market
Food Processing Equipment
Residential Food Waste Disposer Market
Food Processing Equipment
Global Carbonated Beverage Processing Equipment Market
Food Processing Equipment
India Household Flour Milling Machines Market
Food Processing Equipment
Spray Dryer Market
Food Processing Equipment
Automatic Fish Scaling Machine Market