
 Reflow Oven Market | 2026-2036
Reflow Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Reflow Oven Market Analytics
Skilled thermal process engineers is rotating from legacy semiconductor fabs toward automotive electronics suppliers, tightening talent pools for oven commissioning and recipe optimization. Heller Industries leverages its North American service infrastructure to sustain long-term contracts with tier-one PCB assemblers. REHM anchors European demand through precision convection platforms designed for high-mix medical and industrial electronics. Jintuo competes aggressively on cost-engineered benchtop systems for emerging Asian contract manufacturers.
A reflow oven is a thermal processing system that heats printed circuit boards in controlled temperature zones to melt solder paste and form permanent electrical connections, typically operating across preheat, soak, reflow peak, and cooling stages with nitrogen inerting options for oxide reduction. Its primary purpose is to enable high-throughput, repeatable solder joint formation in surface mount technology assembly lines. Inline reflow ovens command the largest installed base due to conveyorized throughput demands from high-volume electronics manufacturers, while vapor phase soldering technology captures premium positioning for complex aerospace electronics and thick-board applications where delta-T control is critical. Benchtop reflow ovens serve prototype and low-volume segments with compressed footprints, though margin pools remain thin against scaled inline alternatives.
FCC equipment authorization rules in the United States govern electromagnetic emissions from oven control systems, while RoHS and REACH in the European Union restrict hazardous substances in solder alloys and oven construction materials, directly shaping replacement demand and design specifications. China's GB standards and MIIT directives on electronics manufacturing energy efficiency create compliance thresholds for imported and domestically produced equipment. Stakeholders must monitor how evolving automotive functional safety standards and regional carbon accounting frameworks reshape capital allocation between retrofit upgrades and full oven replacements.
Market Dynamics
Lead-free soldering mandates under RoHS and REACH compel systematic replacement of legacy thermal processing equipment across European automotive electronics supply chains, while contract manufacturers in Vietnam and Mexico scale automated surface mount capacity to serve regional demand clusters.
Growth Catalysts
- Automotive Powertrain Electrification:PCB reliability standards for electric vehicle inverters and battery management systems require precision thermal profiling that drives oven commissioning demand.
- REACH Substance Restrictions:European Union hazardous substance mandates accelerate replacement cycles for reflow equipment constructed with legacy materials and solder alloys.
- Vietnam Electronics Manufacturing:Contract electronics manufacturers scale automated surface mount lines to capture regional consumer electronics and automotive component demand.
Market Restraints
- Nitrogen Infrastructure Costs:Inert atmosphere soldering requires captive nitrogen generation or bulk gas supply contracts that elevate operational expenditure for mid-scale assemblers.
- Specialized Thermal Engineer Scarcity:Skilled process engineers rotate from legacy semiconductor fabrication toward automotive electronics suppliers, tightening commissioning and recipe optimization capacity.
- Vapor Phase Equipment Premium:Delta-T control technology for aerospace and thick-board applications commands capital expenditure multiples that exclude cost-sensitive contract manufacturers.
Strategic Opportunities
- Mexico Nearshoring Expansion:Electronics manufacturers relocate surface mount assembly capacity to serve North American automotive and industrial OEMs with reduced logistics exposure.
- Medical Device High-Mix Production:Precision convection platforms address low-volume, high-reliability PCB assembly for diagnostic and implantable device manufacturers.
- Carbon Accounting Integration:EU Green Deal disclosure requirements create preference for energy-efficient oven retrofits with verified thermal performance metrics.
Industry Challenges
- Thermal Recipe Transfer Complexity:Migration between oven platforms requires revalidation of solder paste reflow profiles, extending new equipment qualification timelines.
- Legacy Control System Integration:Modern thermal profiling software must interface with existing manufacturing execution systems, creating middleware development burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reflow Oven Market |
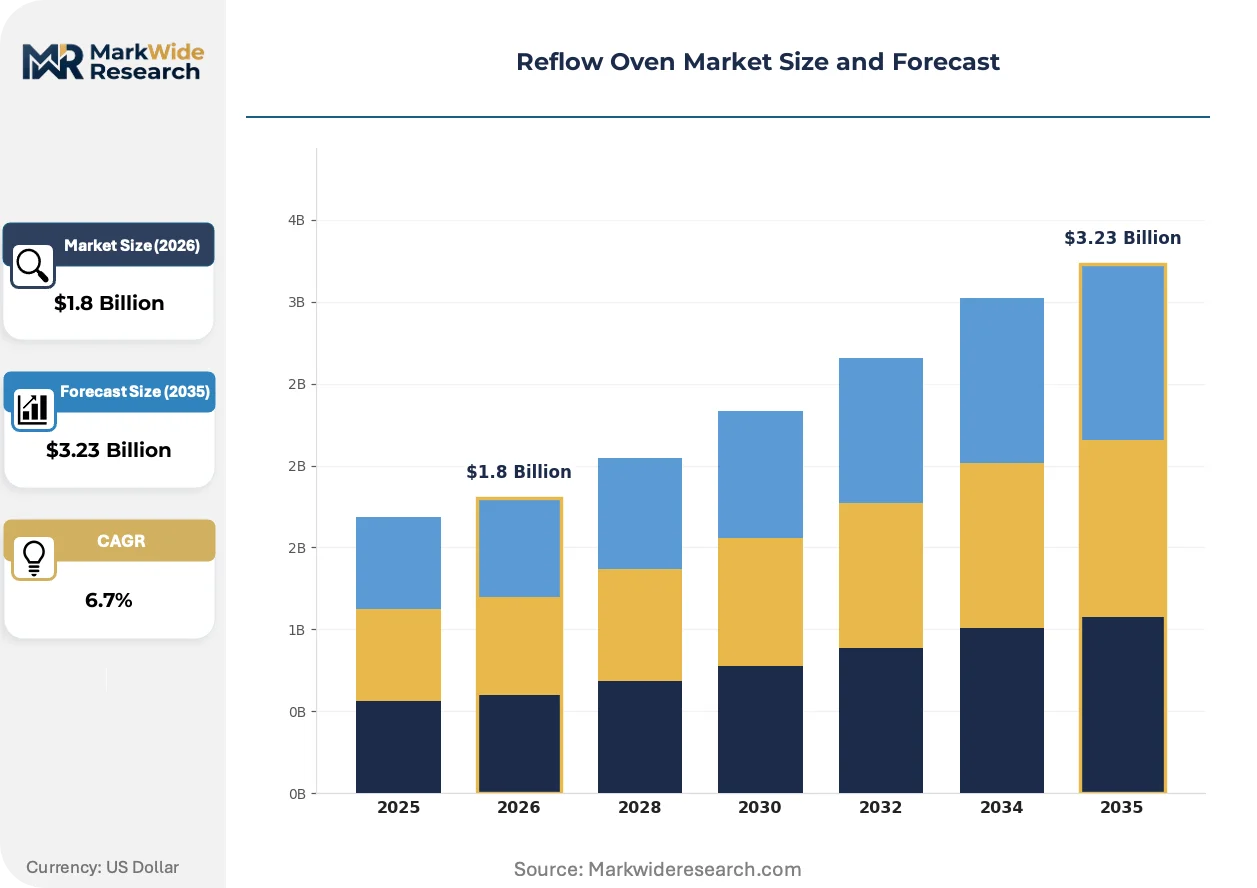
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Reflow Ovens, Inline Reflow Ovens, Benchtop Reflow Ovens, Lead-Free Reflow Ovens End User: Electronics Manufacturers, PCB Assemblers, Contract Electronics Manufacturers, Automotive Component Suppliers Technology: Infrared Heating, Convection Heating, Vapor Phase Soldering, Laser Soldering Application: Surface Mount Technology, Integrated Circuit Packaging, Semiconductor Packaging, Aerospace Electronics |
| Companies Covered | BTU, Jintuo, Kurtz Ersa, Nordson Corporation, SunEast, Heller Industries, Vitronics Soltec, KIC Thermal, REHM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reflow Oven Market Evolving Landscape
Reflow oven technology is fragmenting across multiple thermal processing modalities as end-use requirements diverge between high-throughput consumer electronics and precision-controlled aerospace applications.
Vapor phase soldering technology is fragmenting the premium thermal processing segment through superior delta-T control for complex multilayer boards and heat-sensitive components. Aerospace electronics manufacturers and medical device assemblers adopt this modality despite throughput limitations. The technology is fragmenting competitive positioning between convection-dominant high-volume suppliers and specialized vapor phase equipment vendors.
China's GB standards and MIIT directives on electronics manufacturing energy efficiency establish compliance thresholds for both imported and domestically produced thermal processing equipment. These regulations compress allowable power consumption per board processed, forcing redesign of heating element configurations and insulation systems. Equipment suppliers targeting the Chinese market must certify to these efficiency benchmarks or face procurement exclusion from state-influenced electronics manufacturers.
Automotive electronics suppliers are compressing thermal process validation cycles as functional safety standards tighten solder joint reliability requirements. Tier-one PCB assemblers now demand real-time thermal profiling data integration with statistical process control systems, displacing post-process inspection-dependent procurement models. This behavioral shift is most visible in German and Japanese automotive component supply chains, where OEMs mandate traceable thermal history for powertrain electronics.
Reflow Oven Market Segmentation
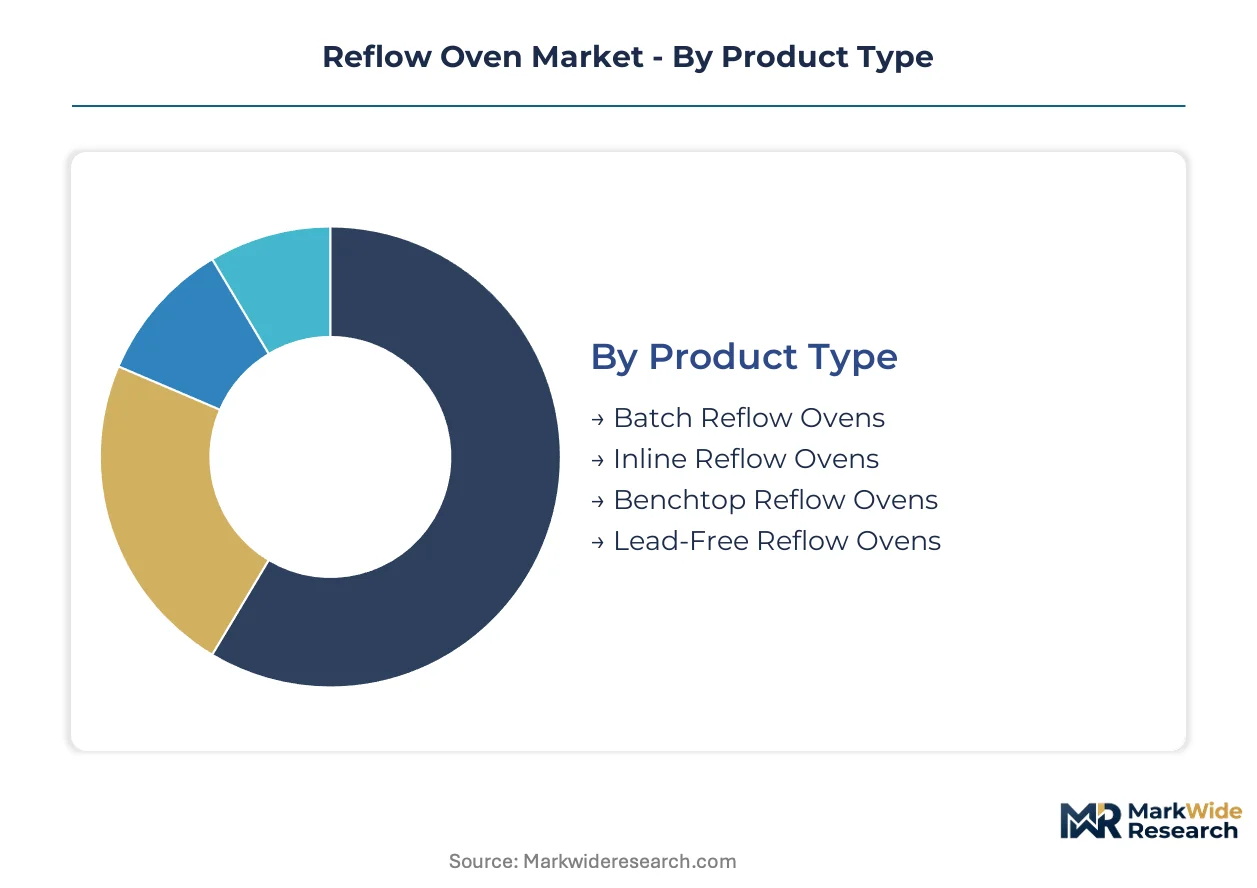
Reflow oven segmentation reveals how thermal processing equipment fragments across throughput scales, precision requirements, and regulatory compliance tiers. Equipment buyers prioritize different performance attributes depending on whether they serve high-volume consumer electronics or reliability-critical automotive and aerospace applications.
Product Type:
Margin pools concentrate in conveyorized systems serving high-throughput electronics manufacturers, while benchtop configurations compete on compressed capital expenditure for prototype operations.
- Inline Reflow Ovens:Conveyorized thermal processing systems integrate continuous PCB transport across multiple heated zones for mass production environments. Electronics manufacturers in Vietnam and Mexico deploy these systems to serve regional automotive component demand clusters with automated surface mount lines.
- Batch Reflow Ovens:Chamber-based systems process multiple boards simultaneously in discrete thermal cycles rather than continuous flow. Medical device manufacturers in Germany leverage batch configurations for low-volume, high-reliability PCB assembly where traceable thermal history is mandatory.
- Benchtop Reflow Ovens:Compact footprint systems serve prototype development and low-volume production with reduced nitrogen consumption.
- Lead-Free Reflow Ovens:Purpose-built thermal platforms accommodate higher peak temperatures required for lead-free solder alloys under RoHS mandates.
The dominant share belongs to Inline Reflow Ovens, while Benchtop Reflow Ovens is closing the gap fastest among emerging Asian contract manufacturers.
End User:
Procurement authority concentrates with tier-one PCB assemblers who specify thermal profiling requirements downstream through automotive supply chains.
- Automotive Component Suppliers:Tier-one electronics manufacturers serving electric powertrain OEMs demand precision thermal profiling with real-time data integration. German and Japanese automotive supply chains mandate traceable thermal history for battery management system PCBs, displacing inspection-dependent procurement models.
- Contract Electronics Manufacturers:Scaled assembly operations in Vietnam and Mexico balance equipment utilization across multiple customer programs. These operators favor inline convection platforms with rapid recipe changeover capabilities to accommodate high-mix production schedules.
- Electronics Manufacturers:Captive production facilities for consumer electronics brands prioritize throughput metrics and energy efficiency certifications.
- PCB Assemblers:Independent board shops serving fragmented industrial and medical device demand clusters.
Automotive Component Suppliers command the largest equipment investment per line, while Contract Electronics Manufacturers is expanding installed capacity most aggressively.
Technology:
Technology selection hinges on delta-T control requirements versus throughput economics, with premium modalities capturing aerospace and medical applications.
- Convection Heating:Forced hot air circulation across PCB assemblies delivers uniform temperature distribution for standard surface mount applications. REHM anchors European demand through precision convection platforms designed for high-mix medical and industrial electronics production.
- Vapor Phase Soldering:Condensing vapor transfer achieves superior thermal uniformity for complex multilayer boards and heat-sensitive components. Aerospace electronics manufacturers adopt this modality despite throughput limitations and capital expenditure premiums that exclude cost-sensitive contract manufacturers.
- Infrared Heating:Radiant energy transfer enables rapid thermal response for specialized component configurations.
- Laser Soldering:Selective energy deposition addresses localized joint formation for miniature component footprints.
Convection Heating retains the broadest installed base, though Vapor Phase Soldering commands the steepest expansion trajectory in aerospace and medical reliability applications.
Application:
Application segmentation tracks how thermal processing requirements diverge between high-volume surface mount assembly and precision packaging for semiconductor and aerospace environments.
- Surface Mount Technology:Mass solder paste reflow for component mounting dominates equipment utilization across consumer and automotive electronics. Inline convection systems process millions of boards annually through preheat, soak, reflow peak, and cooling stages with optional nitrogen inerting for oxide reduction.
- Aerospace Electronics:Thick-board and high-reliability applications demand delta-T control that vapor phase technology uniquely delivers. US and European aerospace contractors specify thermal processing equipment with extensive qualification documentation and traceable calibration records.
- Integrated Circuit Packaging:Advanced packaging thermal processing for system-in-package and fan-out configurations.
- Semiconductor Packaging:Back-end assembly thermal steps for die attach and encapsulation curing operations.
Surface Mount Technology accounts for the majority of equipment operating hours, yet Aerospace Electronics is gaining share fastest as defense and commercial aviation electronics procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German precision-equipment suppliers serving automotive certification requirements, while Vietnamese contract manufacturers compress procurement costs through aggressive vendor consolidation.
United States
FCC equipment authorization rules govern electromagnetic emissions from oven control systems serving aerospace electronics contractors in Southern California. Tier-one PCB assemblers in Austin and Detroit mandate real-time thermal profiling data integration for electric powertrain electronics.
Germany
REACH substance restrictions and RoHS mandates accelerate replacement cycles for legacy reflow equipment across automotive supply chains. Bavarian industrial electronics clusters demand precision convection platforms with traceable thermal history documentation.
China
MIIT directives on electronics manufacturing energy efficiency establish compliance thresholds for imported thermal processing equipment. Yangtze River Delta contract manufacturers scale automated surface mount lines while domestic suppliers compete on cost-engineered benchtop systems.
Vietnam
Contract electronics manufacturers in Ho Chi Minh City and Hanoi expand automated surface mount capacity to serve regional consumer electronics demand. Electronics manufacturing zones near Hai Phong attract Korean and Japanese component suppliers seeking labor cost advantages.
Mexico
Nearshoring electronics manufacturers relocate surface mount assembly to Nuevo León and Baja California to serve North American automotive OEMs with reduced logistics exposure. Tijuana and Monterrey industrial parks concentrate contract manufacturing capacity for powertrain electronics.
Reflow Oven Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. European precision-equipment specialists command premium positioning through convection platforms designed for high-mix medical and automotive applications. Asian benchtop manufacturers compete aggressively on compressed capital expenditure for emerging contract manufacturers. Dominant competitive moves include geographic expansion into Vietnam and Mexico manufacturing zones, plus strategic partnerships with tier-one PCB assemblers seeking long-term service contracts.
Among German-based precision-equipment fabricators, REHM anchors European demand through medical and industrial electronics specialization. Heller Industries leverages North American service infrastructure to sustain contracts with tier-one assemblers. Jintuo occupies the cost-engineered tier, competing on benchtop systems for emerging Asian contract manufacturers.
| Leading Market Players |
|---|
| BTU |
| Jintuo |
| Kurtz Ersa |
| Nordson Corporation |
| SunEast |
| Heller Industries |
| Vitronics Soltec |
| KIC Thermal |
| REHM |
| Others |
Value Network & Pricing Analysis
Nitrogen inerting retrofits replacing standard convection configurations simultaneously shift component sourcing toward German and Japanese gas-system suppliers while compressing margin pools for mid-scale assemblers unable to amortize captive generation infrastructure. Lead-free alloy mandates under RoHS and REACH compound this dynamic by forcing equipment replacement cycles that concentrate procurement authority with tier-one PCB assemblers commanding volume discounts.
Pricing Analysis
Configured-to-order pricing for precision convection platforms with real-time thermal profiling integration commands substantial premiums over standard inline systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with automotive-qualified systems bearing the steepest markups. Cost compression in benchtop segments intensifies because emerging Asian contract manufacturers consolidate vendor relationships. Contract electronics manufacturers in Vietnam exhibit the highest price sensitivity, while German automotive component suppliers prioritize traceability documentation over unit economics.
Supply Chain Analysis
Extended lead times for precision heating elements and nitrogen-compatible conveyor systems strain inventory management across European and North American equipment fabricators. Component sourcing concentrates in Germany, Japan, and China, with ceramic heating elements and high-temperature insulation systems drawing from specialized suppliers in Bavaria and Nagoya. Single-source vulnerability for vapor phase heat transfer fluids creates exposure to REACH substance restriction revisions. Distribution runs through authorized service partners who bundle installation commissioning with long-term maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reflow oven procurement is shifting toward platform-ecosystem models where thermal profiling software interoperability with manufacturing execution systems determines vendor selection, compressing standalone equipment margins while expanding recurring revenue pools for integrated solution providers.
For Market Incumbents: Fortify service infrastructure lock-in by embedding predictive maintenance algorithms within thermal profiling platforms, countering the threat of Asian benchtop manufacturers acquiring European software specialists. Prioritize backward integration into nitrogen generation systems to capture operational expenditure streams from automotive electrification capacity buildouts. For New Entrants and Emerging Players: Differentiate on carbon-accounting integration by certifying energy-efficient retrofits to EU Green Deal disclosure frameworks, targeting Mexican nearshoring clusters where North American automotive OEMs mandate verified thermal performance metrics. Pursue white-label partnerships with Vietnamese contract manufacturers seeking rapid recipe changeover capabilities without premium European pricing. For Investors and Strategic Acquirers: The market sits at a replacement-cycle acceleration phase that favors precision-equipment specialists with automotive certification depth and captive service networks. Long-term viability hinges on software-defined thermal process control rather than hardware throughput specifications. Monitor REACH substance restriction expansion timelines as the critical signal for vapor phase technology displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Software Integration | Real-time thermal profiling data feeds into statistical process control systems at German automotive tier-one suppliers. |
| Service Network Expansion | Authorized commissioning partnerships in Nuevo León capture Mexican nearshoring electronics manufacturing demand. |
| Energy Efficiency Certification | MIIT compliance thresholds enable procurement access to Yangtze River Delta state-influenced electronics manufacturers. |
| Nitrogen System Backward Integration | In-house gas generation equipment captures operational expenditure from mid-scale assemblers avoiding bulk supply contracts. |
| Medical Device Specialization | Precision batch configurations address German diagnostic and implantable device manufacturers requiring traceable thermal history. |
Research Methodology
A spread of perspectives from thermal process engineers, tier-one PCB assembler procurement directors, automotive electronics quality managers, and reflow oven service technicians converged on the working assumptions shaping demand projections. Primary fieldwork combined structured interviews with secondary validation against SEC filings from capital equipment manufacturers, ECHA substance restriction databases, and MIIT energy efficiency compliance registries. Bottom-up triangulation of equipment shipment data against top-down electronics manufacturing capacity buildouts anchored volume estimates.
Segmentation dimensions modeled span product type, end user category, heating technology modality, and application environment across the projection horizon. CAGRs derived from equipment replacement cycle analysis, regional manufacturing capacity expansion announcements, and regulatory mandate implementation timelines. Forecast inputs incorporated nitrogen infrastructure penetration rates and automotive functional safety standard adoption curves.
Forecasts assume regulatory continuity in REACH substance restrictions and MIIT efficiency directives; material policy shifts would require re-modeling equipment qualification timelines and replacement demand profiles. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Hand Blender Market
Food Processing Equipment
Smart Bread Machine Market
Food Processing Equipment
Tortilla Machine Market
Food Processing Equipment
Fish Filleting Machine Market
Food Processing Equipment
Ice-Cream Maker Market
Food Processing Equipment
Deep Fryer Machine Market
Food Processing Equipment
Mixing Vessels Market
Food Processing Equipment
Ice Cream Machine Market
Food Processing Equipment
Cookers and Ovens Market
Food Processing Equipment
Europe Commercial Sous Vide Machine Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Countertop Food Blenders Market
Food Processing Equipment
Holding and Proofing Cabinet Market
Food Processing Equipment
Industrial Fryers Market
Food Processing Equipment
Wine Processing Equipment Market