
 Ice Cream Making Machine Market | 2026-2036
Ice Cream Making Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Cream Making Machine Market Analytics
Equipment leasing and managed-service contracts are reshaping competitive dynamics in frozen dessert equipment. Carpigiani leverages its Italian manufacturing heritage to sustain premium positioning in artisan batch freezer segments. Taylor Company anchors the North American soft-serve installed base through extensive distributor networks and proprietary refrigeration technology. Gseice competes aggressively on price in the electric countertop machine tier, targeting independent operators with compact footprint designs.
An ice cream making machine is a refrigerated mechanical system designed to aerate, freeze, and extrude dairy or non-dairy mixes into finished frozen desserts, typically operating at cylinder temperatures between -6°C and -8°C with overrun control between 30% and 80% depending on product type. Batch freezers dominate margin pools in the premium artisan segment where operators prioritize texture control and flavor flexibility. Soft serve machines represent the largest installed base across quick-service restaurants and convenience stores, while electric countertop units are gaining traction in cafes seeking dual-use beverage and dessert capability without dedicated floor space.
The FDA enforces Current Good Manufacturing Practice regulations for frozen dessert processing equipment under 21 CFR Part 110, while NSF International certifies sanitation and materials safety for commercial ice cream machines sold in the United States. These frameworks elevate compliance costs for new market entrants but reinforce brand loyalty toward established manufacturers with certified product portfolios. Stakeholders must monitor evolving energy-efficiency standards and refrigerant phase-down schedules as regulatory pressure intersects with operator demands for lower utility costs and reduced environmental liability.
Market Dynamics
The FDA's updated Food Safety Modernization Act requirements for frozen dessert processing equipment are accelerating manufacturer investment in automated sanitation systems and certified materials compliance, compressing margins for non-compliant suppliers while reinforcing incumbent positions.
Growth Catalysts
- Artisan Gelateria Expansion:Independent gelaterias across California, Texas, and New York are driving replacement cycles for premium batch freezers with precise overrun control. These operators prioritize texture flexibility over throughput speed.
- Fast-Casual Chain Equipment Fleets:Boutique dessert chains are expanding soft-serve and frozen yogurt installations to capture afternoon and evening traffic. Their procurement favors compact electric countertop units with dual-use beverage capability.
- NSF International Certification Mandates:Commercial ice cream machines sold in the United States must meet NSF sanitation and materials safety standards. This regulatory pressure filters out uncertified imports and elevates brand loyalty toward established manufacturers.
Market Restraints
- Refrigerant Phase-Down Schedules:EPA regulations targeting hydrofluorocarbon reduction are forcing equipment redesigns and retrofit costs. Operators face uncertainty over which refrigerant technologies will achieve long-term regulatory acceptance.
- Italian Manufacturing Concentration:Premium batch freezer production concentrates in Emilia-Romagna and surrounding industrial clusters. Supply disruptions from this geographic concentration create lead time volatility for North American distributors.
- Energy-Efficiency Standard Escalation:Rising utility costs and emerging state-level efficiency mandates are compressing margins on legacy equipment designs. Operators delay replacement purchases when efficiency gains cannot justify capital outlay.
Strategic Opportunities
- Managed-Service Contract Penetration:Equipment leasing bundled with preventive maintenance and sanitation compliance is displacing outright purchase models. This shift reduces operator capital burden while locking in long-term supplier relationships.
- Cafe Dual-Use Applications:Electric countertop machines with beverage and dessert capability are penetrating independent coffee shops seeking revenue diversification without dedicated floor space allocation.
- Automated Clean-in-Place Systems:FDA sanitation requirements are creating white space for equipment with integrated CIP cycles. Manufacturers embedding automated compliance reduce operator labor and inspection risk simultaneously.
Industry Challenges
- Refrigeration Technician Scarcity:Specialized service capacity for commercial ice cream machine repair concentrates with authorized distributor networks. Independent operators face extended downtime when proprietary refrigeration systems require intervention.
- 21 CFR Part 110 Compliance Timelines:Current Good Manufacturing Practice documentation and NSF certification processes extend product development cycles. New entrants struggle to achieve market-ready status before design standards evolve again.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Cream Making Machine Market |
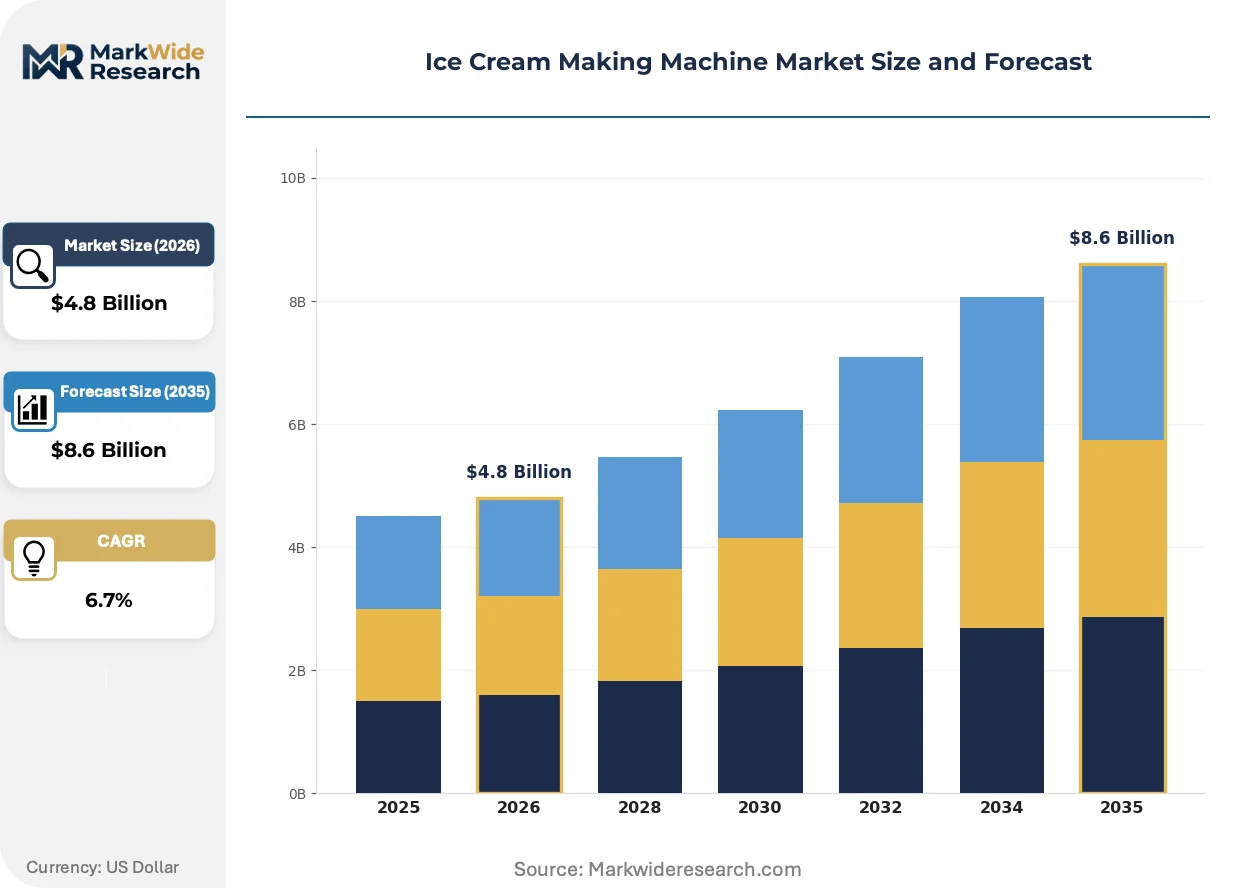
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Freezers, Soft Serve Machines, Countertop Machines, Commercial Ice Cream Makers End User: Restaurants, Ice Cream Shops, Cafes, Catering Services Technology: Manual Ice Cream Makers, Electric Ice Cream Makers, Gelato Machines, Turbo Freeze Machines Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Nissei, Tetra Pak Processing Equipment, Carpigiani, Gseice, Gel Matic, Taylor Company, Gram Equipment, Oceanpower, Electro Freeze, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Cream Making Machine Market Evolving Landscape
Precise temperature control algorithms and connected equipment monitoring are reshaping how operators manage texture consistency and energy consumption across frozen dessert production environments.
Variable-speed compressor technology with real-time viscosity sensing is rendering obsolete traditional fixed-cycle batch freezer operation. Artisan gelaterias in premium markets are adopting these systems to achieve repeatable texture profiles across small production runs. The technology compresses skill requirements while elevating output consistency, reducing operator training burdens.
REACH restrictions on per- and polyfluoroalkyl substances are forcing gasket and seal material substitutions in equipment sold across European Union markets. Manufacturers reformulating component specifications face validation delays but gain competitive positioning in export markets requiring compliant supply chains. The F-Gas Regulation's refrigerant phase-down schedules are accelerating R&D investment in natural refrigerant architectures.
After-sales service unbundling from equipment purchase is fragmenting traditional distributor relationships. Quick-service restaurant chains are sourcing maintenance through third-party facilities management providers rather than manufacturer-authorized networks. This procurement evolution concentrates service purchasing power with large multi-unit operators in California and Texas, pressuring distributor margin structures.
Ice Cream Making Machine Market Segmentation
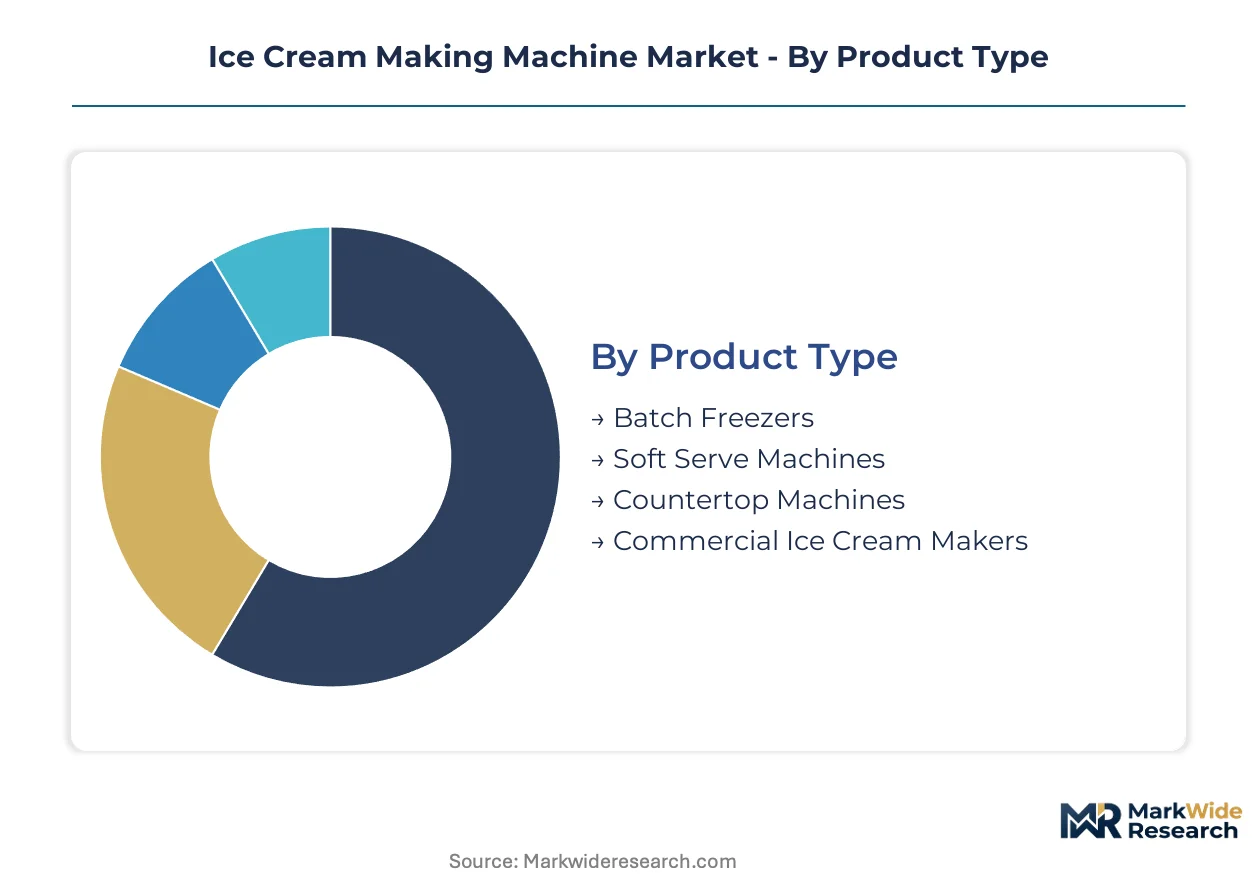
Segmentation in ice cream making machines determines service contract structures, refrigerant compliance pathways, and distributor margin allocation. Equipment complexity varies sharply across product tiers, with premium batch freezers requiring specialized technician networks that reshape channel economics.
Product Type:
After-sales service intensity escalates with refrigeration system sophistication and overrun control precision, fragmenting distributor economics across equipment tiers.
- Batch Freezers:These units employ horizontal or vertical freezing cylinders with dasher mechanisms operating at variable speeds between 60 and 200 RPM, enabling precise air incorporation and texture modulation. Demand concentrates in California and New York independent gelaterias where operators prioritize flavor flexibility over throughput. Artisan shops accept extended lead times for Italian-manufactured units with certified NSF sanitation systems.
- Soft Serve Machines:Gravity-fed or pump-fed systems maintain cylinder temperatures at -6°C to -8°C with continuous dispensing capability and overrun control between 30% and 60%. Fast-casual chains across Texas deploy these in high-traffic configurations, favoring compact footprints with automated clean-in-place cycles to reduce FDA inspection risk.
- Countertop Machines:Compact electric units with 1.5 to 6 quart capacity target space-constrained operators.
- Commercial Ice Cream Makers:High-volume production systems with batch capacities exceeding 20 liters serve central kitchen and manufacturing applications.
By volume, Soft Serve Machines leads. By growth pace, Countertop Machines is ahead.
End User:
Capital deployment thresholds and regulatory exposure diverge sharply across operator categories, with multi-unit chains extracting preferential service terms unavailable to independent buyers.
- Restaurants:Full-service and fast-casual operators integrate dessert equipment into broader kitchen workflows, prioritizing NSF-certified sanitation and interoperability with existing ventilation systems. Procurement concentrates with facilities management providers in California and Texas rather than manufacturer-direct channels.
- Ice Cream Shops:Dedicated operators maximize equipment utilization rates and demand premium texture control capabilities. These buyers concentrate replacement cycles in New York and California, where gelateria expansion drives batch freezer demand with precise overrun specifications.
- Cafes:Coffee-focused operators seek dual-use countertop units for beverage and dessert production without dedicated floor space allocation.
- Catering Services:Mobile and event-based operators prioritize portability and rapid setup capability over production volume.
Restaurants dominates absolute unit volume. Ice Cream Shops expands most quickly.
Technology:
Refrigerant architecture choices and compressor efficiency ratings determine compliance timelines under evolving EPA phase-down schedules, compressing product development cycles for electric configurations.
- Electric Ice Cream Makers:Compressor-driven systems with thermostatic control and automatic shutoff dominate residential and light commercial applications. Demand concentrates in cafe segments across Texas seeking dual-use beverage capability without specialized installation requirements.
- Gelato Machines:Specialized batch freezers with slower dasher speeds and warmer cylinder temperatures produce denser, lower-overrun product distinct from American-style ice cream. Artisan operators in New York and California prioritize these units for texture authenticity and flavor intensity.
- Manual Ice Cream Makers:Hand-cranked or pre-frozen bowl systems serve residential and novelty applications with minimal service infrastructure.
- Turbo Freeze Machines:High-velocity cooling systems accelerate production cycles for high-volume commercial environments.
Electric Ice Cream Makers leads in installed base. Gelato Machines gains share fastest.
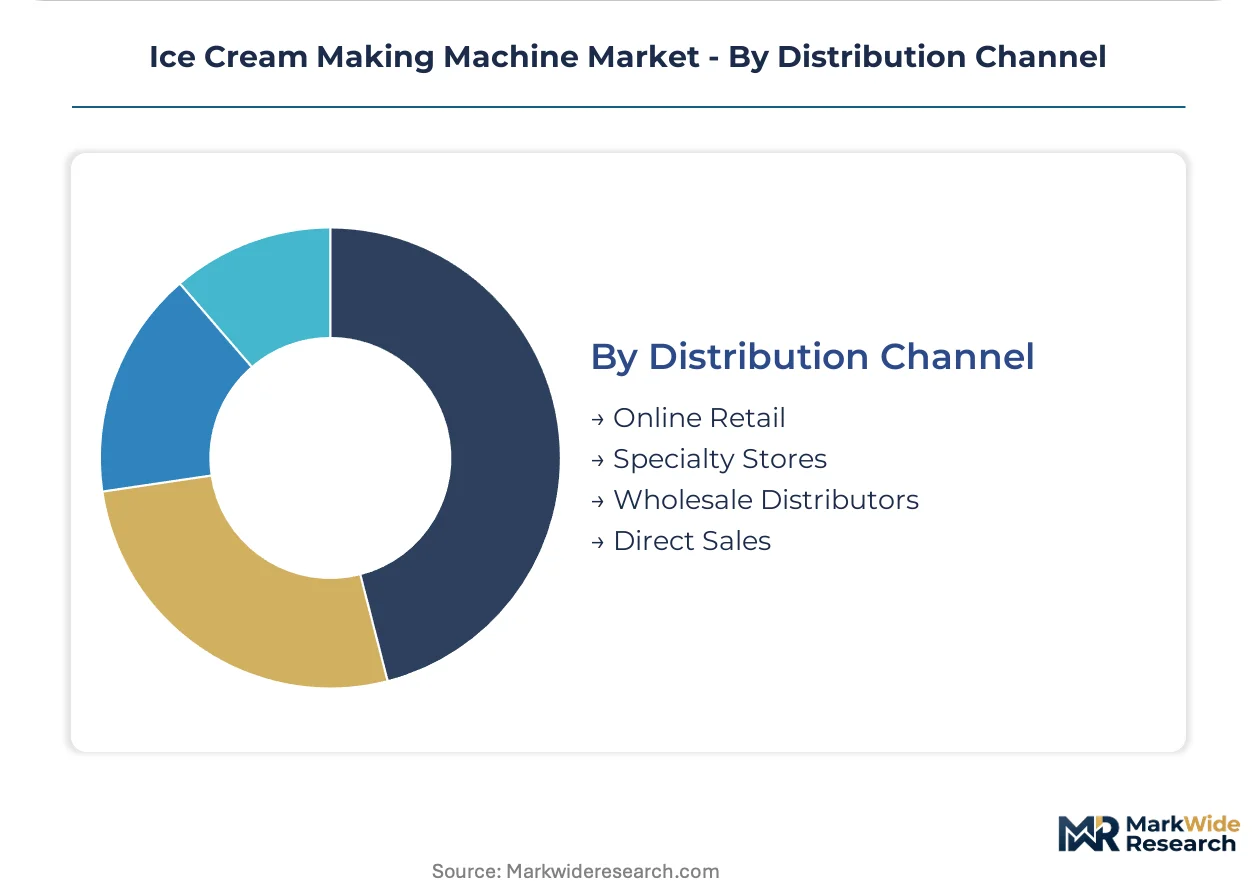
Distribution Channel:
Channel selection determines warranty validity, refrigerant handling compliance, and technician dispatch priority during equipment failure events.
- Wholesale Distributors:Authorized networks with factory-trained technicians provide installation, preventive maintenance, and EPA-compliant refrigerant handling. These channels dominate commercial sales in California, Texas, and New York, where FDA sanitation documentation requirements elevate preference for certified service relationships.
- Direct Sales:Manufacturer-direct procurement serves large multi-unit chains with sufficient volume to justify dedicated account management and customized service level agreements. Quick-service operators in Texas leverage this channel to unbundle maintenance from equipment purchase.
- Online Retail:E-commerce platforms serve countertop and residential segments with limited service bundling.
- Specialty Stores:Physical retail with demonstration capability targets small commercial and serious residential buyers.
Wholesale Distributors leads in commercial revenue. Direct Sales climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Independent gelaterias and fast-casual chains in the United States, Italy, Germany, Japan, and Australia concentrate equipment procurement, with each market exhibiting distinct regulatory and operational priorities that reshape distributor economics.
United States
California, Texas, and New York drive replacement cycles for premium batch freezers and soft-serve installations. FDA enforcement of 21 CFR Part 110 sanitation standards elevates preference for NSF-certified equipment with automated clean-in-place capability. Independent operators in Los Angeles and Dallas face extended lead times when sourcing Italian-manufactured units compliant with evolving refrigerant phase-down schedules.
Italy
Emilia-Romagna anchors global production of artisan batch freezers, with Bologna and surrounding industrial clusters supplying North American gelateria expansion. REACH restrictions on per- and polyfluoroalkyl substances force gasket material substitutions in equipment destined for European Union markets. Domestic demand concentrates in Milan and Rome, where traditional gelaterias prioritize texture authenticity over throughput speed.
Germany
Industrial equipment fabricators in Bavaria and Baden-Württemberg serve central kitchen and manufacturing applications with high-volume production systems. F-Gas Regulation compliance timelines accelerate R&D investment in natural refrigerant architectures for export-bound machines. Operators in Berlin and Hamburg favor energy-efficient electric configurations as utility costs escalate and state-level efficiency mandates tighten.
Japan
Tokyo and Osaka metropolitan areas sustain demand for compact countertop units with precise temperature control algorithms. METI efficiency standards and refrigerant transition policies compress product development cycles for domestic manufacturers. Premium soft-serve installations in convenience store chains favor connected equipment monitoring to manage texture consistency across high-traffic locations.
Australia
Sydney and Melbourne cafe operators adopt dual-use electric machines for beverage and dessert production without dedicated floor space allocation. Import compliance with AS/NZS refrigeration safety standards filters out uncertified equipment, reinforcing distributor relationships with established brands. Seasonal demand volatility in Queensland and Western Australia complicates fleet utilization planning for catering services.
Ice Cream Making Machine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Consolidation pressures concentrate around authorized distributor networks with factory-trained technician capacity, while fragmentation persists among compact electric unit suppliers. Two strategic archetypes dominate: Italian heritage manufacturers leveraging artisan batch freezer positioning, and North American incumbents anchoring soft-serve installed base through proprietary refrigeration technology. Competitive moves center on managed-service contract penetration and refrigerant architecture redesigns to meet EPA phase-down compliance.
Within the heritage-manufacturing tier, Carpigiani and Gel Matic exemplify Italian-origin positioning sustained through premium batch freezer specialization. Taylor Company occupies a channel-controlling position in North American soft-serve distribution. Among scale-driven fabricators, Tetra Pak Processing Equipment represents industrial-systems anchoring, while Gram Equipment sits within the high-volume production equipment segment serving central kitchen applications.
| Leading Market Players |
|---|
| Nissei |
| Tetra Pak Processing Equipment |
| Carpigiani |
| Gseice |
| Gel Matic |
| Taylor Company |
| Gram Equipment |
| Oceanpower |
| Electro Freeze |
| Others |
Value Network & Pricing Analysis
Refrigerant phase-down regulatory chokepoints determine both pricing tier spreads and supply chain shape across the ice cream making machine market. EPA-mandated hydrofluorocarbon reductions force equipment redesign costs that concentrate in premium batch freezer tiers while compressing margins on legacy electric countertop units.
Pricing Analysis
Cost-plus contracts with stainless steel and compressor component indexation dominate procurement between Italian manufacturers and North American distributors. Three-tier pricing structure across premium artisan batch freezers, mid-market soft-serve systems, and economy electric countertop units reflects NSF certification grade and after-sales service bundling. Pricing pressure stems from energy-efficiency standard escalation as operators delay replacement when efficiency gains cannot justify capital outlay. Independent gelaterias in California and New York exhibit highest price sensitivity, while fast-casual chains in Texas prioritize automated sanitation compliance over unit cost.
Supply Chain Analysis
Supplier-financing through extended payment terms and supply-chain finance facilities enables Emilia-Romagna manufacturers to maintain distributor relationships across North American markets. Manufacturing concentrates in Italy, Germany, and Japan, with component sourcing drawing from Chinese electrical assemblies and German compressor systems. Single-source vulnerability from Italian batch freezer production creates lead time volatility when REACH restrictions force gasket material substitutions. Distribution runs through authorized wholesale networks with factory-trained technician capacity in California, Texas, and New York.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected equipment monitoring and automated clean-in-place interoperability are shifting this market toward platform-economics dynamics where data-enabled service contracts displace transactional equipment sales.
For Market Incumbents: Build certification moats through accelerated NSF documentation and EPA refrigerant compliance ahead of phase-down deadlines. Incumbents should secure exclusive distributor technician networks in Texas and California to lock out emerging competitors, while investing in backward integration into compressor component supply to offset stainless steel volatility from tariff-exposed sourcing.
For New Entrants and Emerging Players: Mid-market cafes in Texas and New York seeking dual-use beverage and dessert capability without dedicated floor space allocation represent the most penetrable entry point. New entrants should target electric countertop units with simplified installation requirements, pursuing direct online retail channels to bypass wholesale distributor margin extraction and authorized service bundling.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors service-integrated equipment platforms over pure manufacturing plays. Long-term viability hinges on recurring revenue from managed-service contracts rather than one-time equipment sales. Investors should monitor EPA refrigerant technology approvals as the signal indicating which supplier architectures will achieve regulatory acceptance across the analysis window.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Clean-in-Place Integration | FDA sanitation compliance reduces operator labor and inspection risk simultaneously. |
| Natural Refrigerant Architecture Development | EPA phase-down schedules force R&D investment to maintain market access. |
| Managed-Service Contract Expansion | Equipment leasing with preventive maintenance locks in long-term supplier relationships. |
| Authorized Distributor Network Consolidation | Factory-trained technician scarcity in California and Texas creates channel control value. |
| Dual-Use Countertop Platform Launch | Cafe operators in Texas seek revenue diversification without floor space allocation. |
Research Methodology
Initial hypotheses were tested against primary input from gelateria operators, fast-casual chain procurement directors, equipment distributor service managers, and NSF certification specialists and refined through secondary validation. Primary fieldwork combined structured interviews with aftermarket service heads and OEM procurement teams at frozen dessert equipment manufacturers. Secondary sources included FDA 21 CFR Part 110 documentation, EPA refrigerant phase-down schedules, NSF certification databases, and customs trade records for Italian machinery imports. Bottom-up unit shipment estimates triangulated against top-down market value assessments across product type and end-user segmentation.
Demand-supply balance modeling anchored forecasts across the projection horizon, with volume and value outputs reflecting analytical triangulation between equipment replacement cycle analysis and new installation demand from gelateria expansion. Segmentation dimensions modeled include product type complexity tier, end-user capital deployment threshold, refrigerant architecture compliance pathway, and regional distributor density. CAGRs were derived from fitted growth curves applied to baseline shipment data. Industry-specific inputs incorporated EPA regulatory timeline assumptions and Italian manufacturing lead time volatility.
Practitioners should monitor refrigerant technology approval delays, REACH material restriction expansions, and energy-efficiency mandate escalations for early signals of forecast deviation. Forecasts reflect documented assumptions regarding replacement cycle timing and distributor network stability. Macroeconomic contraction affecting independent operator capital expenditure, regulatory acceleration of refrigerant phase-downs, or breakthrough natural refrigerant architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Soft Serve Ice Cream Machines Market
Dairy Processing Machinery
Cream Separator Market
Dairy Processing Machinery
Milk Pasteurization Machines Market
Dairy Processing Machinery
Global Milk Tank Cooling System Market
Dairy Processing Machinery
Milk Chiller Market
Dairy Processing Machinery
Milk Clarifier Market
Dairy Processing Machinery
Modified Milk Powder Market
Dairy Processing Machinery
Whey Protein Microparticulation Systems Market
Dairy Processing Machinery
Milk Homogenizer Machine Market
Dairy Processing Machinery
Commercial Milkshake Machine Market
Dairy Processing Machinery
Dairy Filtration Systems Market
Dairy Processing Machinery
Dairy Products Membrane Filtration Equipment Market
Dairy Processing Machinery
Dairy Processing Equipment Market
Dairy Processing Machinery
Milk Processing Systems Market
Dairy Processing Machinery
Yogurt Cup Market
Dairy Processing Machinery
Multi-Spindle Milkshake Machine Market