
 Individual Quick Freezing Market | 2026-2036
Individual Quick Freezing Market Size, Share, and Industry Trends Forecast 2026-2036
Individual Quick Freezing Market Intelligence
Demand from large-scale food processing units is consolidating purchasing power for freezing equipment. JBT Corporation leverages its extensive portfolio in spiral and blast freezers to serve these industrial accounts. GEA Group competes by offering fully integrated processing lines that include IQF systems. Meanwhile, Linde plc specializes in the supply of cryogenic gases, a critical consumable for certain freezing applications.
Individual Quick Freezing is a process that rapidly freezes small, discrete food items by conveying them through a stream of cold air or cryogenic gas. This method, often achieving temperatures of -30°C, prevents the formation of large ice crystals and ensures products do not clump together. Spiral freezers constitute a major equipment segment for high-volume processing. The ready meals and seafood preservation applications represent significant areas for new equipment deployment.
Food safety regulations from bodies like the US FDA and the European Food Safety Authority (EFSA) dictate stringent material and design standards for equipment. In parallel, standards from China's NMPA influence market access and local manufacturing requirements. Equipment suppliers must balance compliance with these varied international standards against the need for improved energy efficiency and refrigerant management.
Market Dynamics
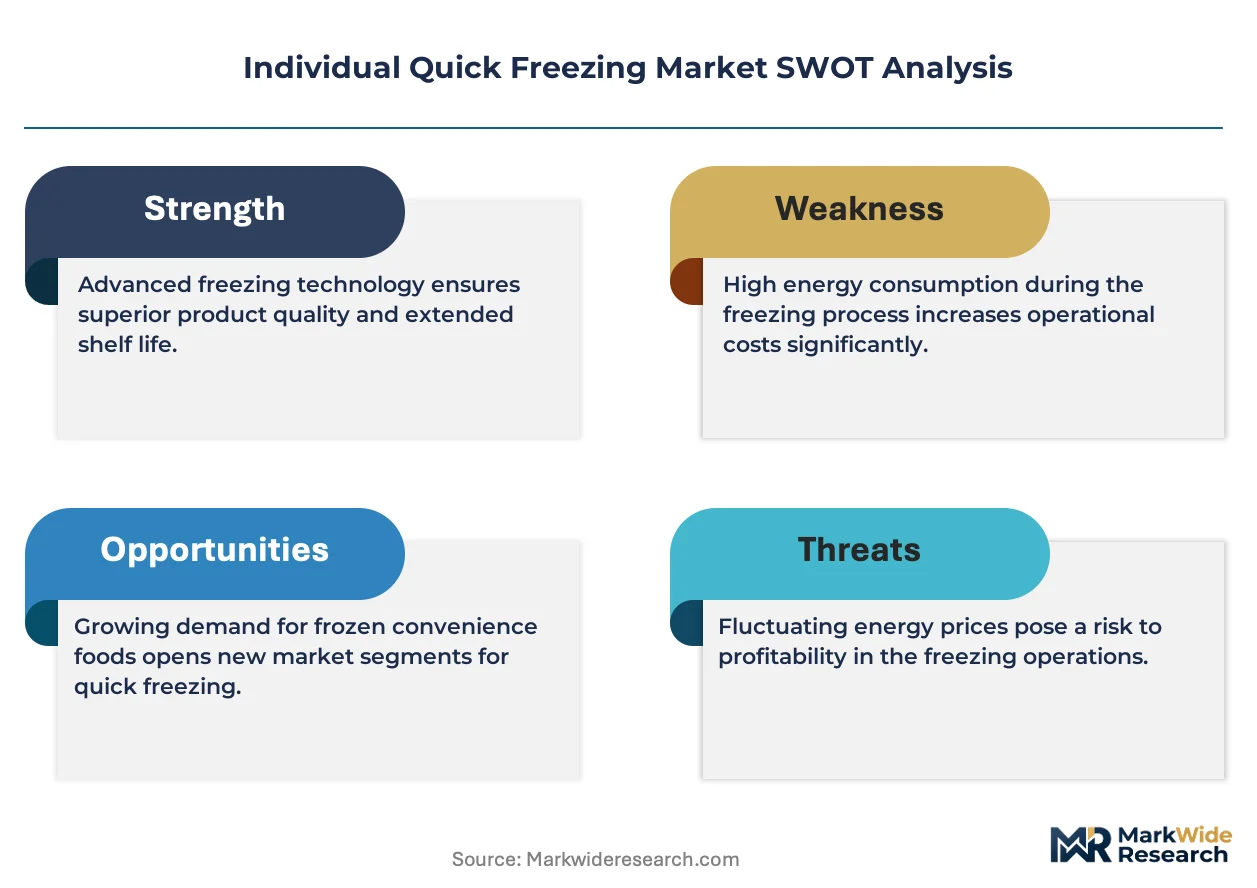
The central dynamic shaping the Individual Quick Freezing market is the tension between increasingly stringent international food safety regulations and the operational imperative for greater energy efficiency. Equipment design must simultaneously satisfy compliance mandates from bodies like the US FDA and EFSA while reducing energy consumption and managing refrigerant use.
Growth Catalysts
- Ready Meal Expansion:Consumer preference for convenience foods is driving significant investment in IQF capacity within the ready meals sector, particularly for freezing individual components like vegetables, pasta, and proteins to maintain quality in final assembled products.
- Cryogenic Technology Adoption:The use of liquid nitrogen and carbon dioxide for cryogenic freezing is expanding. This method's ability to preserve the texture and nutritional value of high-value, delicate items like berries and shrimp appeals to premium food processors.
- Food Industry Modernization in China:China's focus on upgrading its food processing infrastructure and enhancing its cold chain logistics creates substantial demand for new IQF installations. This is part of a national strategy to improve food safety and reduce waste.
Market Restraints
- High Capital Investment:The initial acquisition cost for large-scale IQF systems, especially advanced spiral and impingement freezers, represents a significant capital barrier for small and medium-sized enterprises (SMEs) in the food processing industry.
- Refrigerant and Cryogen Cost Volatility:Operational expenditures are heavily influenced by the fluctuating prices of industrial-grade refrigerants and cryogenic gases like liquid nitrogen. This price instability creates margin pressure for food processors.
- Stringent Environmental Regulations:Policies such as the EU's F-Gas Regulation and the EPA's SNAP program in the US restrict or phase out certain high global warming potential (GWP) refrigerants, forcing costly equipment retrofits or replacements.
Strategic Opportunities
- Plant-Based Food Applications:The rapidly growing plant-based meat and dairy alternative market presents a new application frontier. IQF technology can be adapted to freeze these novel products, preserving their often-delicate textures and structures.
- Modular Systems for Niche Producers:There is an opportunity to develop smaller, modular IQF units. These systems can serve the needs of artisanal producers, test kitchens, and ghost kitchens that require flexibility and a smaller footprint than industrial-scale equipment.
- Integration of AI and IoT:Incorporating artificial intelligence and IoT sensors into IQF lines allows for predictive maintenance, real-time process optimization, and energy management, creating a value proposition centered on operational intelligence and efficiency.
Industry Challenges
- Navigating Global Compliance:Equipment suppliers face the challenge of designing systems that comply with a patchwork of international food contact material standards, including those from the EFSA in Europe, the FDA in the US, and China's NMPA.
- Skilled Technician Scarcity:A shortage of technicians with the expertise to install, operate, and service complex mechanical and cryogenic freezing systems poses an operational risk, particularly in regions with newly developing food processing sectors.
- Energy Efficiency Optimization:Maintaining optimal energy consumption while processing diverse food products with varying moisture contents and densities is a persistent operational challenge for end-users trying to control production costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Individual Quick Freezing Market |
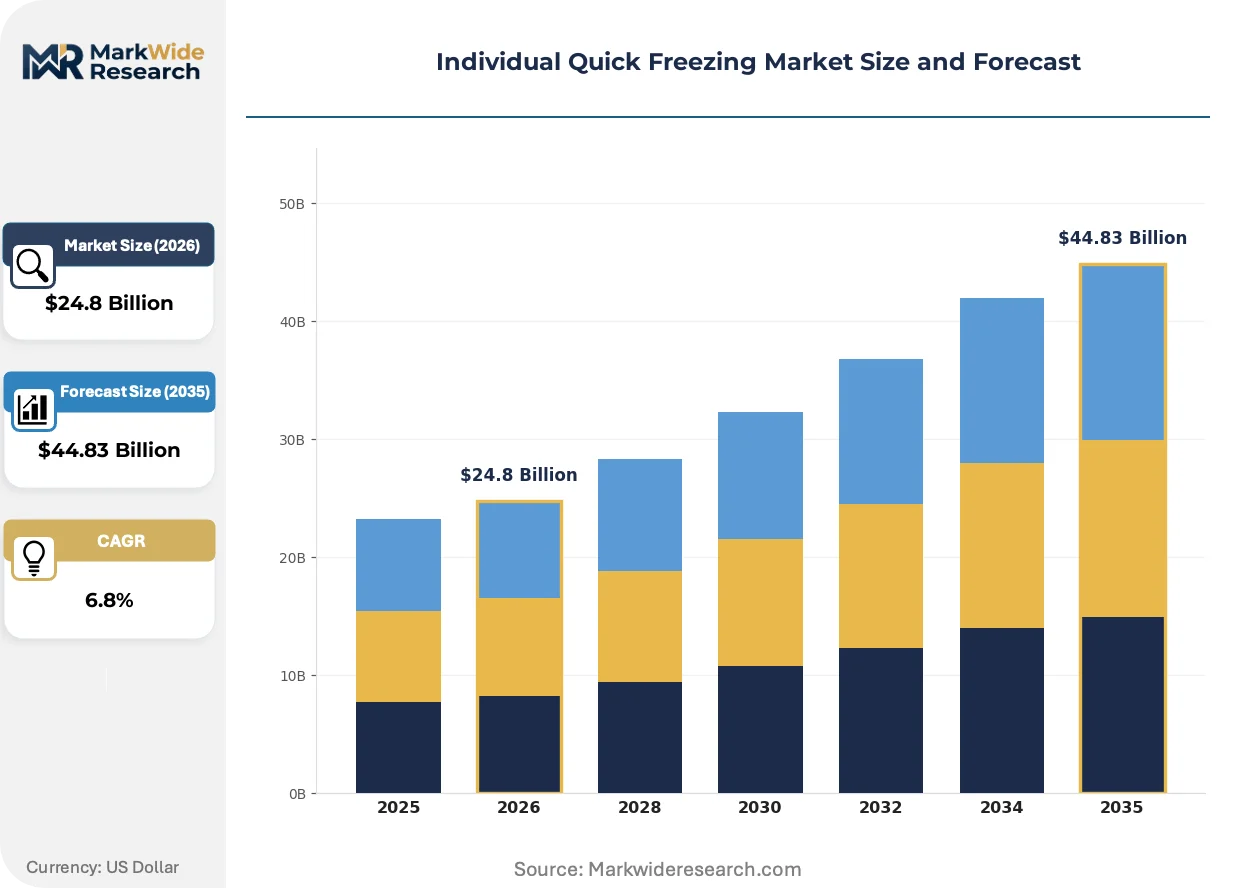
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $44.83 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blast Freezers, Cryogenic Freezers, Plate Freezers, Spiral Freezers Application: Seafood Preservation, Meat Processing, Vegetable Storage, Ready Meals, Bakery Products End User: Food Processing Units, Cold Storage Facilities, Catering Services, Food Distributors Deployment: On-Premise, Mobile Units, Contract Freezing Services, Centralized Freezing Plants |
| Companies Covered | JBT Corporation, GEA Group, Linde plc, Air Liquide, Messer Group, Air Products and Chemicals, SPX FLOW, OctoFrost Group, Cryogenic Systems Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Individual Quick Freezing Market Strategic Shifts & Innovations
Equipment evolution in the Individual Quick Freezing market is defined by the dual pressures of environmental sustainability and the integration of digital process controls. This drives innovation toward systems that minimize energy and refrigerant use while maximizing throughput and food quality through automation.
Advanced cryogenic freezing, utilizing liquid nitrogen or carbon dioxide, provides ultra-rapid temperature reduction to preserve the cellular structure in delicate foods. Processors of high-value seafood, fruits, and premium ready-to-eat meals are adopting this technology to enhance product quality and command higher prices. This shift toward cryogenic methods is absorbing investment that previously went to purely mechanical freezing, especially where product integrity justifies higher operational costs.
European Union F-Gas Regulation mandates a significant phase-down of hydrofluorocarbons, which are common refrigerants in many existing mechanical freezers. This policy is forcing equipment manufacturers to engineer new systems that utilize natural refrigerants like ammonia or CO2. The prepared foods and bakery sectors in Europe are most affected, accelerating their transition to compliant, albeit often more complex, freezing technologies.
A demand-side shift toward full supply chain traceability is compelling food processors to invest in IQF systems with integrated data logging and monitoring capabilities. This moves purchasing decisions beyond simple throughput, prioritizing equipment that can provide an auditable data trail for food safety compliance. This trend is most pronounced in the infant nutrition and export-oriented seafood segments, where proof of process control is a market access requirement.
Individual Quick Freezing Market Segmentation
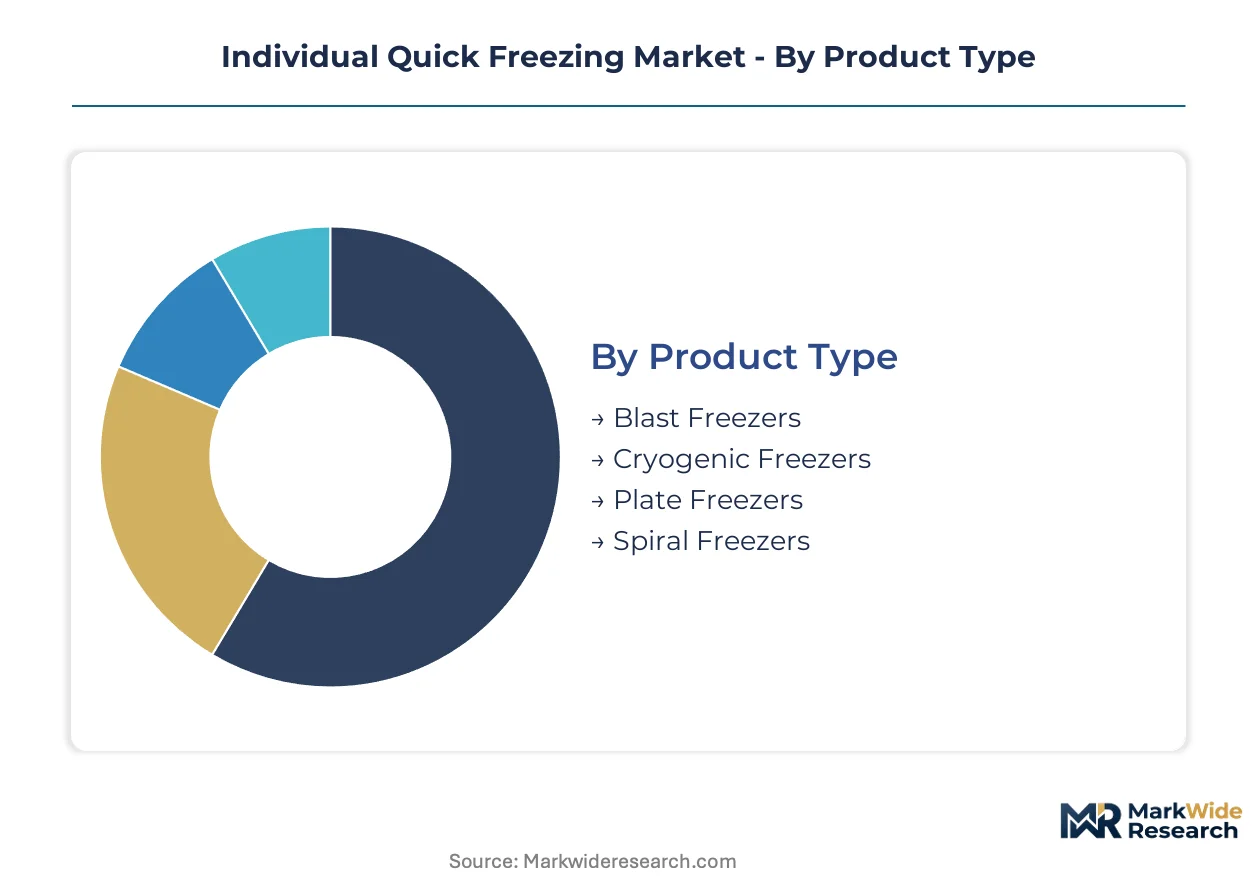
Individual Quick Freezing market segmentation provides a granular view of how diverse product types, applications, and end-user requirements shape demand for freezing solutions. Understanding these distinct segments helps manufacturers tailor equipment design and service offerings to specific operational needs and regulatory environments.
Product Type:
The lifespan and upgrade cycles of existing freezing equipment significantly influence purchasing decisions within the Individual Quick Freezing market.
- Spiral Freezers:These systems utilize a continuous belt that spirals upwards, maximizing freezing capacity within a compact footprint, ideal for high-volume, continuous processing of products like poultry, seafood, and bakery items. JBT Corporation offers extensive spiral freezer solutions for industrial accounts.
- Cryogenic Freezers:Employing liquid nitrogen or carbon dioxide, these freezers achieve ultra-rapid freezing, preserving cellular structure and moisture content in delicate or high-value products such as berries, shrimp, and premium ready meals. Linde plc specializes in supplying the critical cryogenic gases for these systems.
- Blast Freezers:Batch-oriented systems that use high-velocity cold air to rapidly freeze products placed on racks or trolleys, commonly used for larger cuts of meat or prepared dishes before packaging.
- Plate Freezers:These freezers use direct contact with refrigerated plates to freeze flat, packaged products, ensuring uniform freezing and efficient use of space, often found in seafood and processed meat packaging lines.
Volume placements concentrate in Spiral Freezers; the faster expansion belongs to Cryogenic Freezers.
Application:
Demand for Individual Quick Freezing systems is concentrating across diverse food processing applications, each with distinct quality and throughput requirements.
- Ready Meals:IQF technology is critical for freezing individual components like vegetables, pasta, and proteins separately to maintain texture and quality before final assembly in convenience meals. This application is a significant growth catalyst in China and Europe.
- Seafood Preservation:Rapid freezing prevents ice crystal formation, crucial for maintaining the texture, flavor, and nutritional integrity of high-value seafood products like shrimp, fish fillets, and shellfish for global export markets. This segment faces stringent food safety regulations from the US FDA and EFSA.
- Meat Processing:IQF systems are used for freezing diced meat, poultry pieces, or sausages, preventing clumping and facilitating portion control and efficient packaging for retail and foodservice channels.
- Vegetable Storage:Freezing individual vegetable pieces ensures they remain loose, preventing block freezing and allowing for easy portioning, which is vital for both consumer packs and industrial ingredient supply.
- Bakery Products:IQF is applied to freeze dough, pastries, and baked goods, extending shelf life and allowing for flexible production schedules and distribution to various retail outlets.
Seafood Preservation and Ready Meals applications collectively drive the largest share of new equipment deployments, with Ready Meals showing the steepest expansion trajectory.
End User:
The operational scale and specific logistical needs of end-users dictate the type and capacity of Individual Quick Freezing solutions procured.
- Food Processing Units:Large-scale industrial operations that integrate IQF systems directly into their production lines for high-volume processing of various food products. These units often consolidate purchasing power for advanced equipment.
- Cold Storage Facilities:Warehouses equipped to store vast quantities of frozen food products, sometimes incorporating IQF capabilities for incoming goods that require immediate individual freezing.
- Catering Services:Businesses that prepare and deliver meals for events or institutions, using IQF to preserve ingredients or pre-prepared components, ensuring quality and extending shelf life.
- Food Distributors:Companies involved in the supply chain of food products, increasingly adopting IQF solutions to enhance product quality and extend the shelf life of goods before distribution to retailers or foodservice clients.
Food Processing Units represent the primary end-user segment for high-capacity IQF systems, while Food Distributors are increasingly integrating smaller-scale freezing capabilities.
Deployment:
Deployment models for Individual Quick Freezing technology vary significantly, reflecting different capital expenditure strategies and operational flexibilities for food processors.
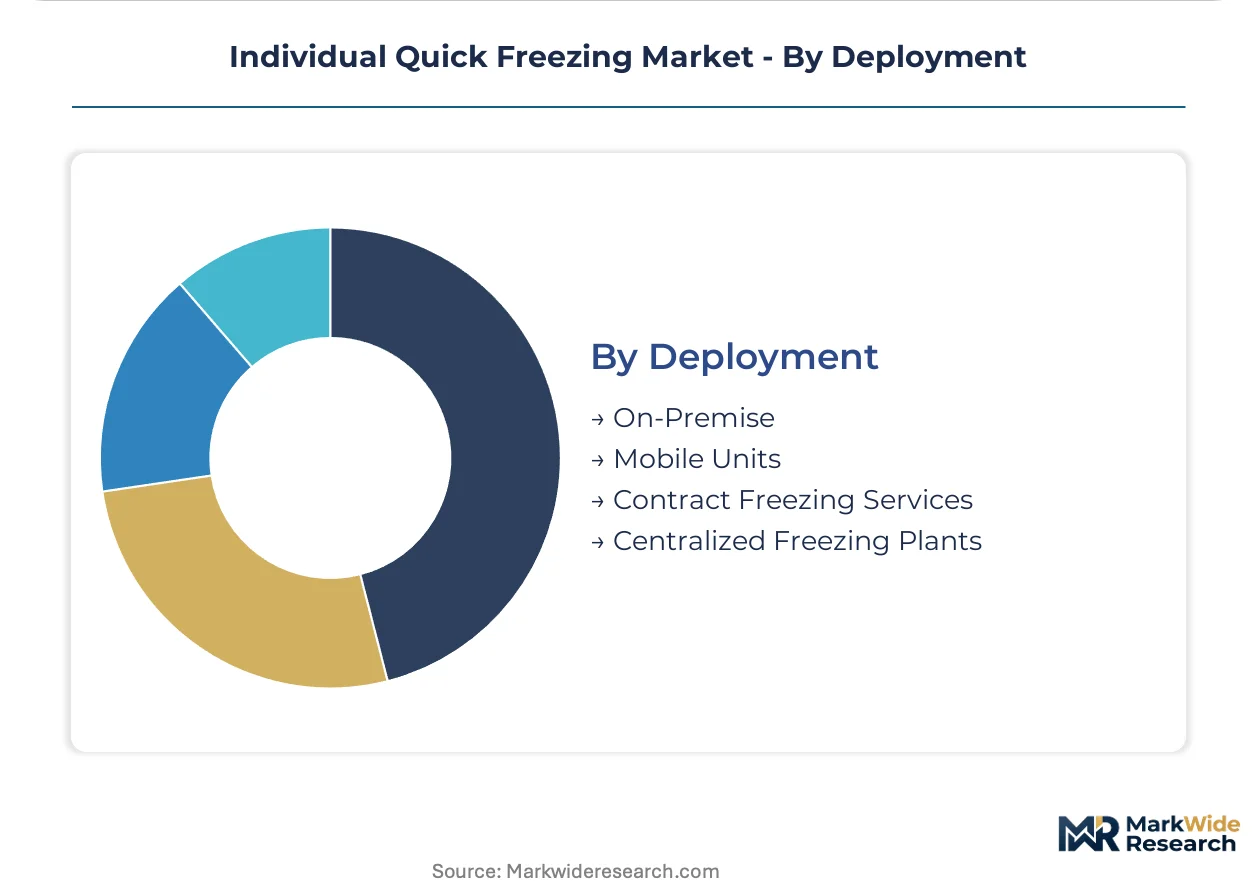
- On-Premise:IQF systems installed directly within a food processing facility, offering full operational control and integration with existing production lines. This model is typical for large-scale food manufacturers.
- Centralized Freezing Plants:Large facilities dedicated solely to freezing food products for multiple clients, often serving as a hub for regional food processing and cold chain logistics. China's food processing industry modernization supports this model.
- Contract Freezing Services:Third-party providers offering IQF services to food manufacturers who prefer to outsource their freezing needs, avoiding high capital investment and operational complexities.
- Mobile Units:Portable IQF systems designed for flexibility, allowing processors to freeze products directly at the source, such as harvesting sites or remote processing locations, reducing transit time.
On-Premise installations remain the most prevalent deployment method, though Contract Freezing Services are gaining share due to their flexibility for smaller producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for Individual Quick Freezing systems is evident in key global food processing hubs, driven by evolving consumer preferences and stringent food safety requirements. These regional dynamics shape investment in advanced freezing technologies and influence equipment design standards. China's expanding food processing industry, for instance, represents a significant area of growth for new IQF installations.
China
China's food processing industry modernization creates substantial demand for new IQF installations, particularly for ready meals and seafood. The NMPA's influence on market access and local manufacturing requirements drives compliance efforts among equipment suppliers. Major food industrial parks in cities like Shanghai and Guangzhou are integrating advanced IQF systems to enhance food safety and reduce waste.
United States
The United States market exhibits strong demand for IQF solutions in the ready meals and seafood preservation sectors, fueled by convenience trends. US FDA regulations dictate stringent material and design standards for food processing equipment. Key food processing clusters in California and the Midwest are investing in high-volume spiral and cryogenic freezers to meet domestic and export demand.
Germany
Germany's prepared foods and bakery sectors are significantly affected by the EU's F-Gas Regulation, necessitating a transition to natural refrigerants in IQF systems. EFSA standards guide equipment design for food contact materials and hygiene. Industrial regions such as Bavaria and North Rhine-Westphalia are adopting advanced IQF technologies to improve energy efficiency and product quality.
India
India's burgeoning food processing sector and improvements in cold chain logistics are driving investment in IQF technology. The FSSAI mandates food safety and quality standards for frozen products, influencing equipment procurement. Food parks in states like Maharashtra and Gujarat are expanding their IQF capabilities to cater to both domestic consumption and export markets for fruits, vegetables, and seafood.
Brazil
Brazil's substantial meat processing and agricultural export industries generate significant demand for IQF systems, especially for poultry, beef, and fruits. ANVISA regulations govern food safety and hygiene in processing plants, impacting equipment specifications. Key processing hubs in São Paulo and Minas Gerais are adopting IQF technology to enhance product quality and extend shelf life for international markets.
Individual Quick Freezing Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue niche applications in plant-based foods and modular systems. The market structure is tiered, with a few large players dominating high-volume industrial accounts and numerous smaller specialists serving specific segments. Strategic archetypes include integrated solution providers, specialized equipment manufacturers, and cryogenic gas suppliers. Dominant competitive moves involve portfolio diversification and technology innovation, particularly in energy efficiency and automation.
Integrated solution providers like GEA Group exemplify the trend toward offering fully integrated processing lines that include IQF systems. Meanwhile, JBT Corporation represents a specialist archetype, leveraging its extensive portfolio in spiral and blast freezers to serve industrial accounts. Linde plc anchors the consumable supply segment, specializing in the supply of critical cryogenic gases for advanced freezing applications.
| Leading Market Players |
|---|
| JBT Corporation |
| GEA Group |
| Linde plc |
| Air Liquide |
| Messer Group |
| Air Products and Chemicals |
| SPX FLOW |
| OctoFrost Group |
| Cryogenic Systems Equipment |
| Others |
Cost & Logistics Intelligence
The significant divergence between premium cryogenic freezing and standard mechanical systems shapes both equipment pricing and supply chain configurations. This distinction reflects technological sophistication and operational costs, impacting procurement strategies for food processors.
Pricing Analysis
Volume-driven mechanical freezers operate on per-unit transactional pricing, while advanced cryogenic systems often employ project-based contracts. Price differentiation stems from stringent food safety certifications like US FDA compliance and the level of integrated after-sales service. Pricing softness for commodity equipment arises from intense competition among manufacturers. Large food processing units are less price-sensitive for high-capacity systems, whereas smaller producers prioritize upfront capital expenditure.
Supply Chain Analysis
Workforce availability in key manufacturing geographies like China and Germany influences production capacity for IQF equipment. The supply chain relies on specialized components such as compressors from global suppliers and industrial-grade refrigerants like liquid nitrogen. A structural risk involves commodity price volatility for these refrigerants and cryogenic gases. Equipment distribution runs through a network of direct sales teams and regional distributors to food processing units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Individual Quick Freezing market is in a technology-transition phase, with advanced cryogenic freezing systems displacing older mechanical freezers for high-value applications.
For Market Incumbents: Extend existing customer relationships by offering upgrade pathways to energy-efficient systems, mitigating the threat from stringent environmental regulations like the EU's F-Gas Regulation. Invest in R&D for natural refrigerant compatibility and integrate IoT for predictive maintenance, leveraging established service networks. This also helps counter emerging entrants focusing on niche applications.
For New Entrants and Emerging Players: Modular, plant-based food freezing technologies present a technology-first wedge for new entrants. Target artisanal producers and ghost kitchens requiring flexible, smaller-footprint IQF solutions. A go-to-market angle involves offering bundled services that include equipment leasing and cryogen supply, penetrating underserved segments and avoiding high capital investment barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by larger industrial players seeking portfolio diversification. The market offers long-term viability over a 5-10 year window, driven by global food processing modernization. Acquisition targets include specialized manufacturers of cryogenic systems or software providers integrating AI into IQF lines. A signal to watch is the increasing patent activity in natural refrigerant technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop natural refrigerant IQF systems | Mitigates compliance risks from EU F-Gas Regulation for European markets. |
| Integrate AI for process optimization | Enhances energy efficiency and reduces operational costs for end-users. |
| Expand modular IQF product lines | Captures demand from smaller producers and ghost kitchens globally. |
| Strengthen cold chain logistics partnerships | Ensures reliable delivery of cryogenic gases to remote processing sites. |
| Target plant-based food processors | Diversifies application portfolio into a rapidly expanding food segment. |
Research Approach
Multi-period observation of equipment deployment rates and cryogen consumption anchored the trend analysis, supplemented by interviews with food processing plant managers, equipment engineers, and cold chain logistics directors. Secondary validation drew from US FDA guidelines, EFSA reports, and company annual filings. The approach integrated both bottom-up market sizing and top-down validation.
Segment-weighting across product types, applications, and end-user categories formed the quantitative framework. This analytical model projected growth throughout the forecast period, considering raw material costs and regional regulatory shifts. CAGRs derived from historical data extrapolation and forward-looking market drivers. Key inputs included global food production volumes and cold chain infrastructure investment.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events or radical shifts in global trade policies. Forecasts reflect assumptions regarding technological stability and consistent regulatory enforcement. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Ice Cream Equipment Market
Food Processing Equipment
Global Food Sterilization Machines Market
Food Processing Equipment
Pasta Machine Market
Food Processing Equipment
Softgel Encapsulation Machine Market
Food Processing Equipment
Cookers and Ovens Market
Food Processing Equipment
Shawarma Grill Machine Market
Food Processing Equipment
Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Ice Cream Freezer Market
Food Processing Equipment
Global Shawarma Machines Market
Food Processing Equipment
Pan Feeder Market
Food Processing Equipment
Global Food Dehydrators Market
Food Processing Equipment
Cider Brewing Equipment Market
Food Processing Equipment
Commercial Mixer Market
Food Processing Equipment
Yogurt Makers Market
Food Processing Equipment
Cookie Dropper Machine Market
Food Processing Equipment
Ice-Cream Maker Market