
 Gluten-Free Bread Market | 2026-2036
Gluten-Free Bread Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten-Free Bread Market Outlook
Single-serve and mini-loaf bundling is recalibrating how households trial gluten-free options without committing to full-sized loaves. Udi's Gluten Free leverages its frozen-distribution muscle to dominate mainstream retail channels. King Arthur Baking Company anchors its reputation on premium ingredient transparency and direct-to-consumer education. Schär competes through dedicated gluten-free manufacturing facilities that eliminate cross-contamination risk entirely.
Gluten-free bread denotes baked products formulated without wheat, barley, or rye proteins, typically using rice flour or tapioca starch as structural bases with xanthan gum or psyllium husk to replicate gluten's binding and elasticity functions, produced through modified fermentation and proofing protocols to achieve comparable crumb texture and shelf stability for retail and foodservice applications. Loaf bread occupies the largest volume position but carries thinner margins due to commodity-like competition among mass-market brands. Almond flour formulations command premium positioning within ingredient-type segmentation, reflecting consumer willingness to pay for higher protein and lower carbohydrate profiles. Online retailers represent the fastest-expanding distribution channel, though supermarkets still control the majority of purchase occasions through dedicated shelf-space allocations.
The FDA enforces its gluten-free labeling standard at 20 parts per million maximum, while EFSA coordinates with national EU food safety agencies to harmonize enforcement across member states, and Australia's FSANZ maintains parallel thresholds that shape export qualification requirements for multinational producers. These frameworks elevate compliance costs for smaller bakeries while creating market access barriers that favor scaled manufacturers with dedicated analytical laboratories. Stakeholders must monitor evolving allergen thresholds and novel protein labeling debates that could force reformulation cycles or channel restructuring before the forecast horizon closes.
Market Dynamics
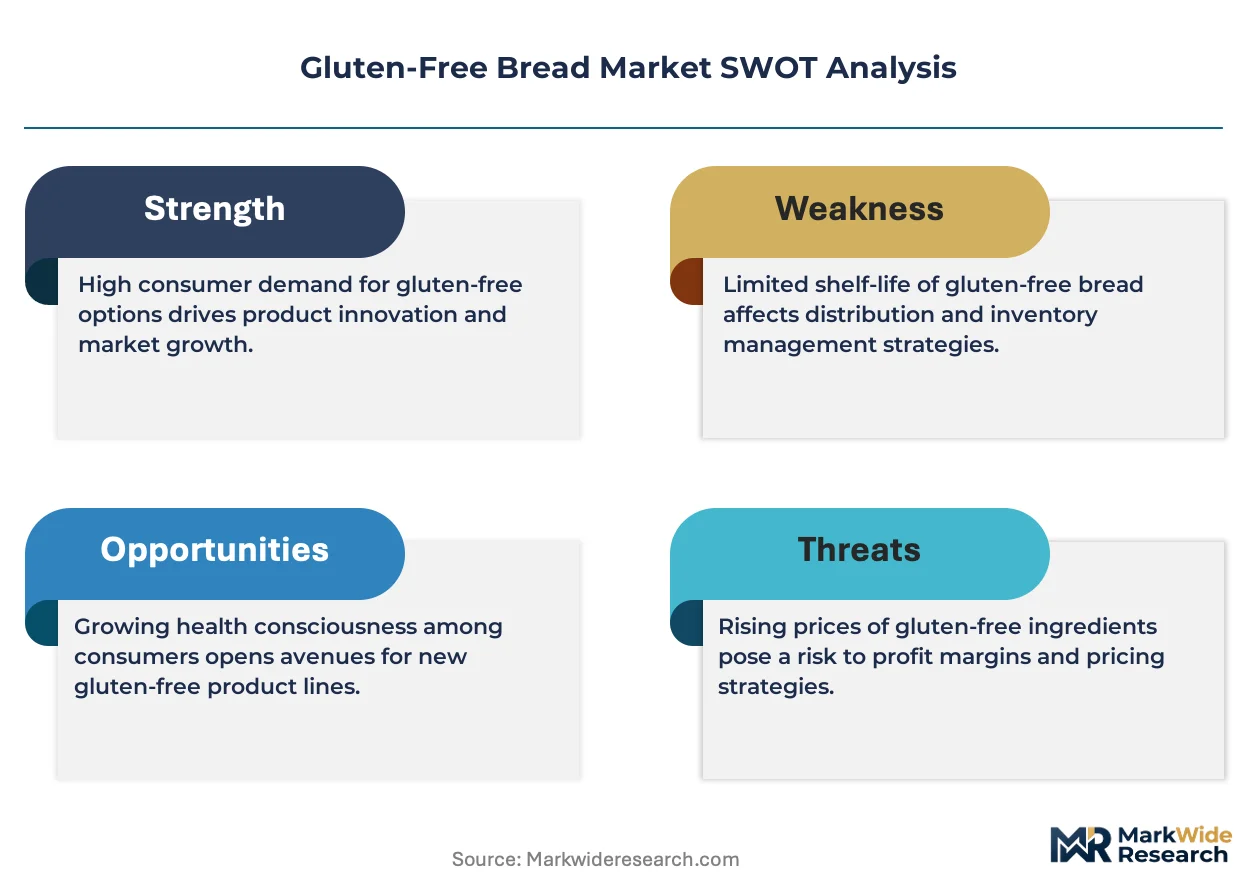
The FDA's 20 parts per million gluten-free labeling threshold and parallel EFSA enforcement protocols are compressing formulation flexibility while elevating analytical compliance costs across all production scales.
Growth Catalysts
- Celiac disease diagnostic expansion:Rising physician screening rates in the United States and Germany are expanding the addressable patient population requiring certified gluten-free products.
- EFSA harmonization protocols:Cross-border enforcement alignment is reducing regulatory fragmentation for manufacturers operating across multiple EU member states.
- Sorghum and teff flour adoption:Alternative grain sourcing is diversifying structural bases beyond rice and tapioca, improving nutritional density and sensory profiles.
Market Restraints
- Xanthan gum supply concentration:Fermentation-derived hydrocolloid production clusters in China, creating input cost volatility and qualification bottlenecks for Western bakeries.
- Cross-contamination facility requirements:Dedicated gluten-free manufacturing lines demand capital outlays that exclude smaller regional bakeries from certification eligibility.
- Almond flour price premium:Nut-based formulations remain structurally expensive compared to commodity starch alternatives, capping mass-market penetration.
Strategic Opportunities
- Australia FSANZ export alignment:Harmonized thresholds with US and EU standards position Australian manufacturers for multi-jurisdiction supply contracts.
- Direct-to-consumer subscription channels:Frozen mini-loaf delivery models bypass retail slotting fees while capturing recurring revenue from diagnosed households.
- Psyllium husk and flaxseed gum convergence:Fiber-based binding systems are converging with gut-health positioning to command premium shelf placement in functional food aisles.
Industry Challenges
- ELISA testing technician scarcity:Analytical laboratories face recruitment gaps for gluten quantification specialists, extending batch release timelines.
- Legacy equipment retrofitting:Conventional bakeries must reconfigure mixing and proofing systems to handle non-wheat dough rheology without cross-contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten-Free Bread Market |
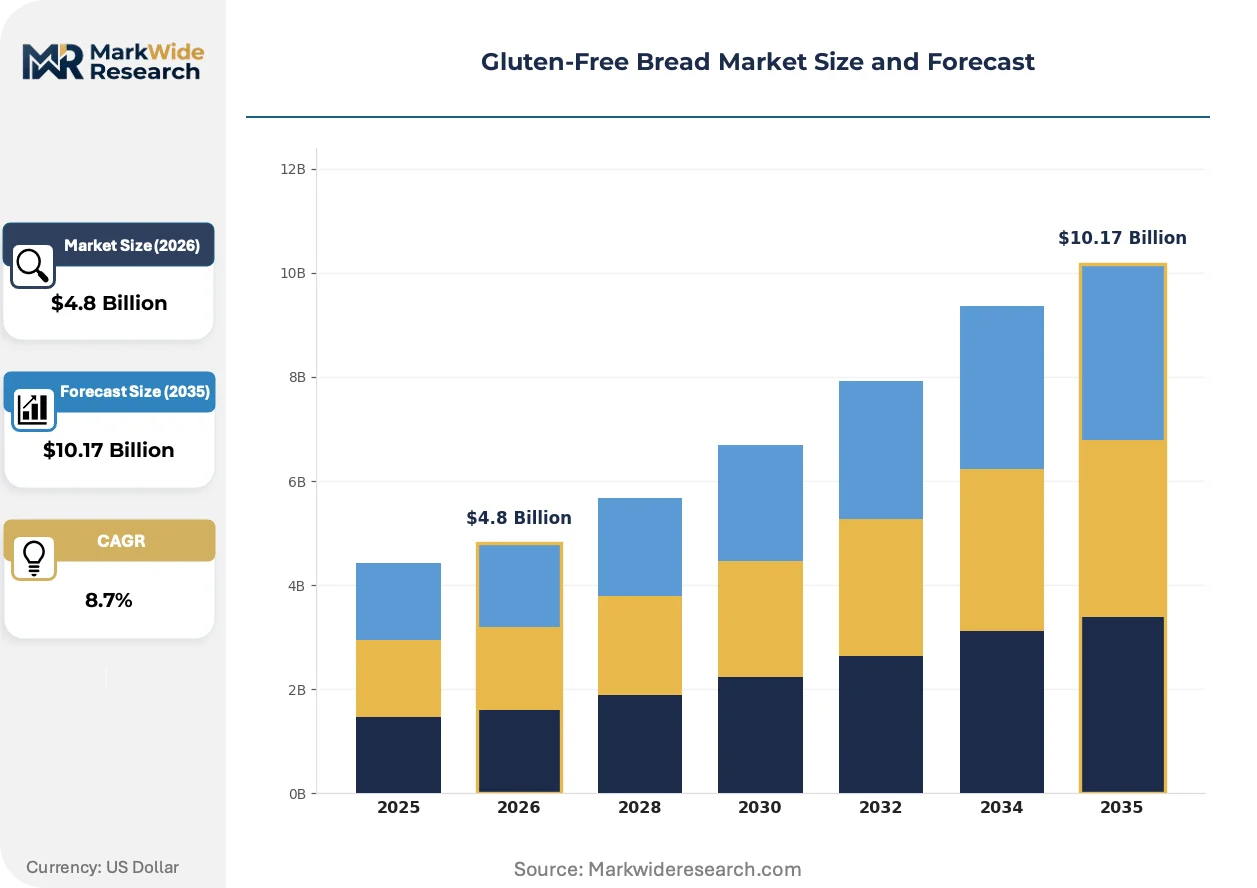
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loaf Bread, Buns, Tortillas, Muffins Ingredient Type: Rice Flour, Almond Flour, Coconut Flour, Tapioca Starch Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Stores End User: Consumers, Foodservice, Bakeries, Cafés |
| Companies Covered | Udi's Gluten Free, King Arthur Baking Company, General Mills, Inc., Canyon Bakehouse, Glutino, Grupo Bimbo, Flowers Foods, Genius Gluten-Free, Schär, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten-Free Bread Market Strategic Shifts
Fermentation science and ingredient biotechnology are rewriting texture benchmarks for gluten-free bread, compressing the sensory gap with conventional wheat products while regulatory precision tightens around allergen thresholds.
Sourdough starter cultures adapted for rice and millet bases are converging with extended fermentation protocols to generate organic acids that strengthen crumb structure without wheat gluten. Artisan bakeries in San Francisco and Copenhagen are adopting these methods to produce loaves with chew comparable to wheat equivalents. The structural outcome is converging with premium positioning that commands price multiples over commodity gluten-free sandwich bread.
REACH chemical safety registration requirements are extending scrutiny to processing aids and enzyme formulations used in gluten-free dough conditioning. Manufacturers must now document full supply chain substance safety for European market access. Small and mid-sized bakeries without dedicated regulatory affairs staff are outsourcing compliance to specialized consultancies, adding fixed cost layers.
Retail buyers are consolidating gluten-free SKUs into dedicated planogram sections rather than dispersing products across conventional bread aisles. This clustering is compressing brand discovery for new entrants while reinforcing incumbent visibility in supermarkets. The United Kingdom and Netherlands display the most advanced shelf-space segregation, with dedicated freezer doors for frozen gluten-free lines separate from conventional frozen bread.
Gluten-Free Bread Market Segmentation
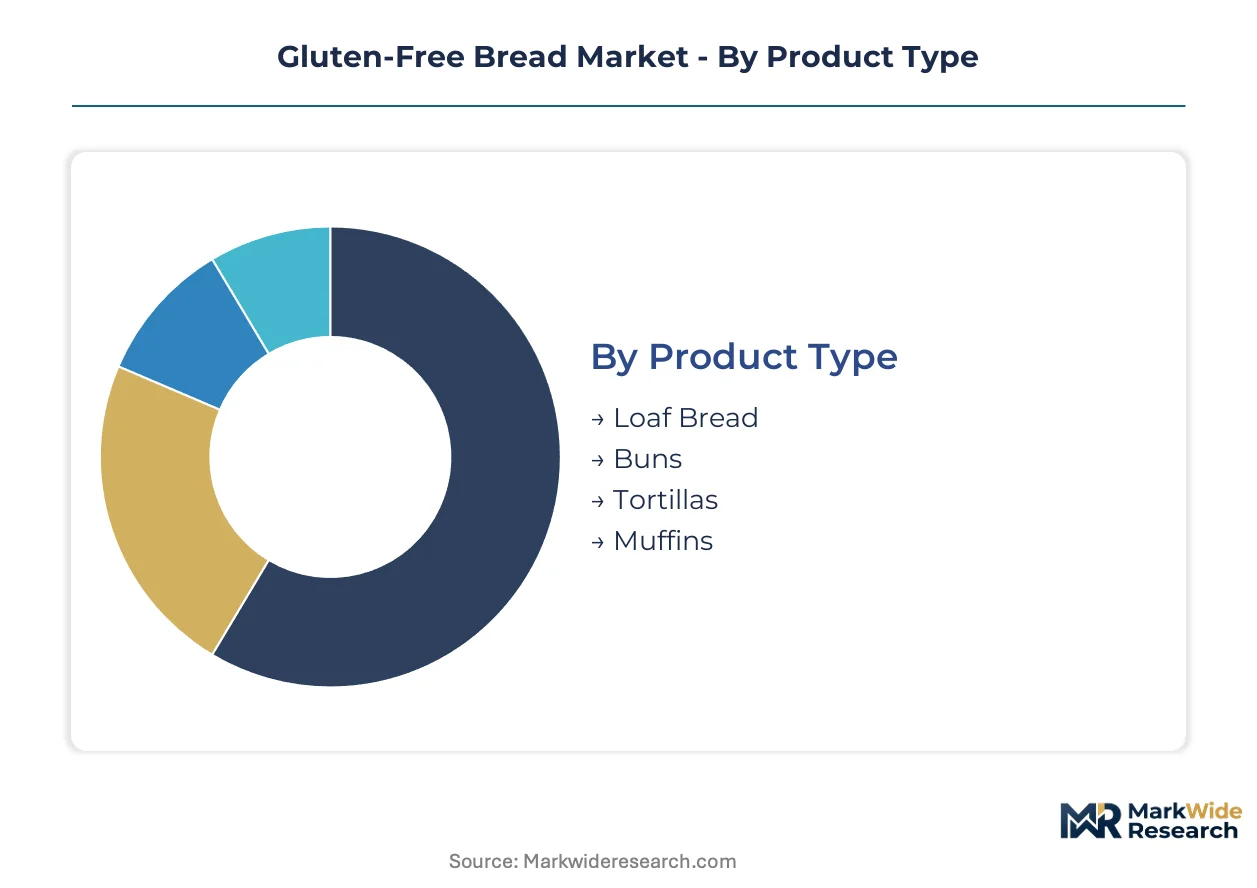
Gluten-free bread segmentation reveals how formulation choices, channel access, and end-use requirements fragment demand across distinct commercial battlegrounds. Each category exposes different margin structures and regulatory exposure that shape competitive positioning.
Product Type:
Volume concentration and margin profile diverge sharply across formats, with household trial behavior and foodservice throughput driving divergent production economics.
- Loaf Bread:Standard sandwich formats dominate household purchase frequency but suffer commodity-like margin compression from mass-market brand proliferation. United States retail chains allocate dedicated shelf space that reinforces incumbent visibility while constraining new entrant discovery.
- Buns:Hamburger and hot dog configurations command premium positioning through foodservice contracts with quick-service chains seeking gluten-free menu parity. Germany's gastropub sector drives specialized bun demand that outpaces loaf growth in commercial channels.
- Tortillas:Wrap formats leverage tapioca-starch flexibility for pliability without wheat gluten, serving Mexican-inspired fast-casual expansion.
- Muffins:Single-serve breakfast formats capture grab-and-go occasions with higher per-unit margins than sliced bread alternatives.
Loaf bread leads volumes today; buns are gaining share fastest through foodservice contract expansion.
Ingredient Type:
Raw material cost tiers and nutritional positioning claims create stratified competitive arenas that separate premium players from commodity producers.
- Rice Flour:The baseline structural ingredient for mass-market formulations offers functional familiarity but limited protein content. Australia's FSANZ labeling requirements favor rice-based products for export qualification simplicity.
- Almond Flour:Nut-based formulations command price multiples through keto and paleo dietary alignment, though California drought cycles inject supply volatility. Health-conscious consumers in Germany pay steep premiums for lower-carbohydrate profiles.
- Coconut Flour:High-fiber tropical sourcing appeals to gut-health positioning but requires hydration-intensive formulation adjustments.
- Tapioca Starch:Cassava-derived binding provides neutral flavor and stretchable texture for tortilla and flatbread applications.
Rice flour anchors volume production; almond flour climbs the fastest on premium nutrition positioning.
Distribution Channel:
Channel selection determines regulatory compliance burden, slotting fee exposure, and customer acquisition cost structures for gluten-free brands.
- Supermarkets:Mainstream retail controls the majority of purchase occasions through dedicated planogram sections, though consolidation into segregated freezer doors compresses discovery for new entrants. United Kingdom grocers display the most advanced shelf-space segregation.
- Online Retailers:Direct-to-consumer frozen delivery bypasses slotting fees while capturing recurring revenue from diagnosed celiac households seeking subscription convenience.
- Health Food Stores:Specialty retail offers curated discovery for emerging brands with clean-label credentials and transparent supply chains.
- Specialty Stores:Dedicated gluten-free boutiques provide education-intensive environments for newly diagnosed consumers navigating dietary transitions.
Supermarkets dominate transaction volume; online retailers expand most quickly on subscription model adoption.
End User:
Final demand splits between household consumption with strict allergen avoidance requirements and commercial foodservice seeking operational flexibility.
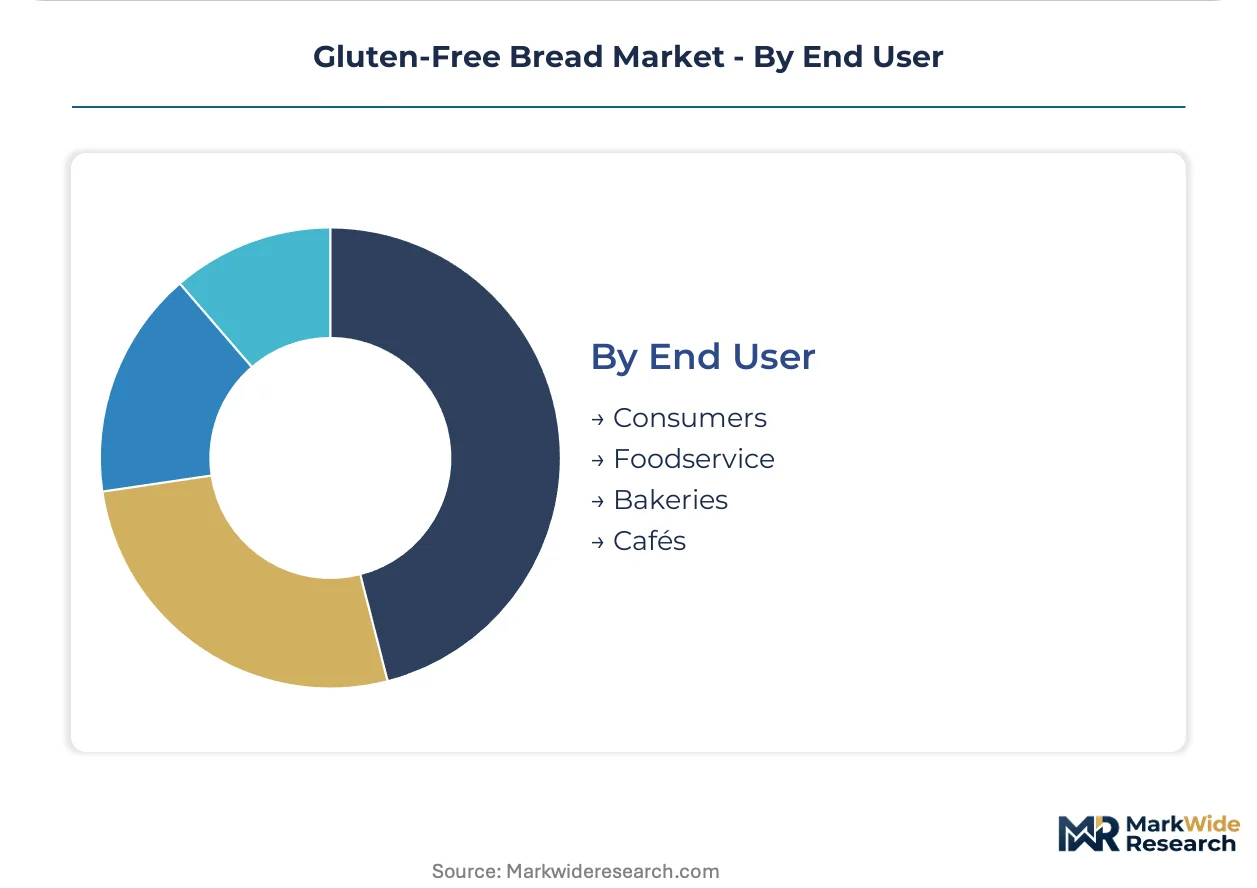
- Consumers:Household purchasers prioritize certified safety thresholds and sensory parity with wheat bread, driving single-serve trial formats that reduce commitment risk for skeptical buyers.
- Foodservice:Restaurant and institutional kitchens demand consistent supply reliability and extended holding stability for line-speed service, with cross-contamination protocols that favor dedicated gluten-free supplier relationships.
- Bakeries:Artisan producers seek differentiated ingredient bases like teff and sorghum for premium positioning in farmers' market and direct-sale channels.
- Cafés:Coffee shop chains require thaw-and-serve efficiency for breakfast sandwich applications with minimal preparation labor.
Consumer households generate the largest revenue base; foodservice contracts deliver the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gluten-free bread commercialization traces its industrial roots to Italian and German bakeries that first scaled rice-flour formulations for diagnosed celiac populations during the 1990s. These European origins established the quality benchmarks and certification protocols that now govern multinational production. Demand has since dispersed across distinct national healthcare systems and retail infrastructures.
United States
Physician screening rates for celiac disease have climbed steadily, expanding the diagnosed patient base requiring certified gluten-free products. The FDA enforces its 20 parts per million labeling threshold through periodic facility inspections and analytical verification. Austin, Texas anchors a cluster of dedicated gluten-free bakeries that supply both regional retail chains and direct-to-consumer frozen delivery services.
Germany
Gastropub sector expansion drives specialized bun demand that outpaces loaf growth in commercial channels. EFSA coordination with Germany's Federal Office of Consumer Protection and Food Safety harmonizes enforcement across EU member states. Munich and Berlin host concentrated artisan bakery networks that experiment with teff and sorghum bases for premium farmers' market positioning.
Australia
Health-conscious consumers overlap densely with diagnosed gluten-intolerant populations in Sydney and Melbourne metropolitan corridors. FSANZ maintains parallel gluten thresholds that align with US and EU standards, simplifying export qualification for domestic manufacturers. Queensland's specialty grain processors supply sorghum flour to both local bakeries and Asian market exporters.
United Kingdom
Retail buyers have advanced shelf-space segregation most aggressively, clustering gluten-free SKUs into dedicated planogram sections. REACH chemical safety registration extends scrutiny to processing aids used in dough conditioning for European market access. London's foodservice distributors maintain separate gluten-free supply lines for restaurant chain contracts requiring cross-contamination protocols.
Canada
Health Canada and PMRA administer parallel allergen thresholds that shape import requirements for US and European suppliers. Toronto and Vancouver concentrate retail innovation, with supermarket chains testing dedicated freezer door configurations for frozen gluten-free lines. Prairie province grain handlers are diversifying into gluten-free oat and pulse flour milling for domestic bakery supply.
Gluten-Free Bread Market Competitive Environment
Premium-margin players sit above commodity-margin players across ingredient transparency and certification credibility dimensions, creating a tiered structure where dedicated gluten-free manufacturing commands price multiples over conventional bakery line conversions. The competitive terrain separates scaled manufacturers with analytical laboratory infrastructure from regional artisans dependent on third-party testing. Three archetypes dominate: frozen-distribution specialists leveraging retail channel muscle, premium ingredient-transparent bakers emphasizing direct-to-consumer education, and dedicated-facility operators eliminating cross-contamination risk entirely. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players seek to secure compliant supply chains for alternative flours and binding hydrocolloids.
Within the frozen-distribution archetype, Udi's Gluten Free and Canyon Bakehouse occupy positions that exemplify retail channel dominance through mainstream supermarket penetration. King Arthur Baking Company anchors the premium-education tier, while Schär represents the dedicated-facility model with complete manufacturing separation. These three patterns illustrate how competitive positioning stratifies across operational choices rather than product differentiation alone.
| Leading Market Players |
|---|
| Udi's Gluten Free |
| King Arthur Baking Company |
| General Mills, Inc. |
| Canyon Bakehouse |
| Glutino |
| Grupo Bimbo |
| Flowers Foods |
| Genius Gluten-Free |
| Schär |
| Others |
Value Chain & Pricing Dynamics
Xanthan gum fermentation capacity concentrated in Chinese industrial clusters feeds directly into three-tier pricing stratification across premium, standard, and economy gluten-free bread tiers, with hydrocolloid cost volatility compressing margins most severely at the commodity end while certified dedicated-facility products maintain pricing power through supply security guarantees.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates gluten-free bread, with certification grade and ingredient transparency as primary price differentiation drivers. Pricing pressure stems from almond flour supply volatility driven by California drought cycles, compressing margins in nut-based premium tiers. Economy rice-flour segments show highest buyer price sensitivity, while diagnosed celiac households demonstrate lowest sensitivity due to strict allergen avoidance requirements.
Supply Chain Analysis
Direct-to-retail frozen distribution channels handle mainstream supermarket demand, while direct-to-consumer subscription models serve diagnosed households. Raw material sourcing draws from China for xanthan gum, the United States for almond flour, and Australia for sorghum. Supply chain risk centers on single-source vulnerability for fermentation-derived hydrocolloids. Distribution runs through dedicated gluten-free warehouse segments to prevent cross-contamination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gluten-free bread market compounds steadily as celiac diagnostic expansion creates irreversible demand from medically mandated consumers. This structural patient base insulates volume trajectories from discretionary spending volatility.
For Market Incumbents: Extend analytical laboratory infrastructure to accelerate batch release timelines and reduce compliance cost per unit. ELISA testing technician scarcity threatens throughput expansion; automated gluten quantification systems offset recruitment gaps. Backward integration into alternative grain milling secures teff and sorghum supply against commodity price swings.
For New Entrants and Emerging Players: Capture foodservice contract white space in Germany's gastropub sector and Australia's café chain expansion, where gluten-free menu parity demands outpace incumbent supply capacity. Direct-to-consumer frozen mini-loaf subscriptions offer the most penetrable entry vector, bypassing retail slotting fees while building recurring revenue foundations.
For Investors and Strategic Acquirers: Consolidation pressure builds where smaller regional bakeries face capital barriers to dedicated gluten-free facility certification. Long-term viability favors scaled manufacturers with captive analytical infrastructure and multi-jurisdiction regulatory expertise. Watch FSANZ-EFSA-FDA threshold harmonization progress as the signal indicating export-ready acquisition targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Dedicated Facility Certification | Eliminates cross-contamination risk and unlocks premium pricing tiers through FDA-compliant labeling. |
| Alternative Grain Backward Integration | Captures sorghum and teff supply security while differentiating nutritional profiles from commodity rice bases. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting fees and builds recurring revenue from diagnosed celiac households. |
| Foodservice Contract Expansion | Secures volume commitments from quick-service chains seeking gluten-free menu parity. |
| Analytical Laboratory Infrastructure | Reduces batch release timelines and compliance costs per unit through in-house ELISA capabilities. |
Study Parameters
Multiple input streams — primary interviews with bakery operations directors, regulatory affairs specialists at gluten-free manufacturers, supermarket category buyers, and foodservice procurement managers; secondary validation through FDA enforcement reports, EFSA guidance documents, FSANZ standards, and trade data from customs records — were reconciled through bottom-up production volume aggregation and top-down demand validation.
Data-stream reconciliation across the projection horizon applied segmentation modeling across product format, ingredient base, distribution channel, and end-use application dimensions. CAGRs derived from historical trajectory analysis and forward-looking capacity expansion announcements. Forecast inputs included celiac diagnostic rate projections, alternative grain harvest forecasts, and hydrocolloid fermentation capacity utilization.
Underlying measurement precision varies by segment; loaf bread and rice-flour categories carry tighter precision than emerging teff-based artisan formats. Forecasts reflect assumptions regarding regulatory threshold stability and diagnostic screening expansion rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Cake Base Discs Market
Bakery Products
Europe Sourdough Market
Bakery Products
Specialty Frozen Bakery Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
Baking Molds and Trays Market
Bakery Products
Pastry Dough Market
Bakery Products
On-The-Go Breakfast Products Market
Bakery Products
Ezekiel Bread Market
Bakery Products
Aerating Cake Emulsifier Market
Bakery Products
Bakery Premixes Market
Bakery Products
Asia-Pacific Baked Food and Cereals Market
Bakery Products
Low Fat Oatmeal Cookies Market
Bakery Products
Canada Frozen Bakery Market
Bakery Products
Vegan Donuts Market
Bakery Products
North America Sweet Biscuits Market