
 Spray Dryer Market | 2026-2036
Spray Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Spray Dryer Market Outlook
Aftermarket service revenue is narrowing as original equipment manufacturers bundle predictive maintenance contracts with new unit sales. GEA Group leverages its installed base across European dairy processing to lock in long-term service agreements. SPX FLOW anchors its competitive stance through backward integration into atomizer nozzle manufacturing. Yamato Scientific specializes in compact pilot-scale systems that sustain premium positioning among Japanese pharmaceutical contract manufacturers.
A spray dryer is a convective drying apparatus that atomizes liquid feed into dispersed droplets through rotary, pressure, or pneumatic nozzles, then contacts them with heated air at inlet temperatures typically ranging from 150°C to 300°C to produce free-flowing powder. The equipment serves industries requiring precise control over particle size distribution, moisture content, and bulk density for downstream handling or bioavailability. Centrifugal spray dryer configurations occupy the largest installed base due to their flexibility across viscosities and feed rates, while pressure spray dryer systems capture expanding share in ceramic and catalyst applications where narrow particle size bands command specification premiums. Continuous flow technology segments attract capital allocation as batch processing incurs higher labor and cleaning validation costs in regulated environments.
FDA 21 CFR Part 110 and EMA GMP Annex 15 impose equipment surface finish, cleanability, and documentation requirements that elevate stainless steel construction standards and qualification protocols for pharmaceutical spray dryer installations. EPA National Emission Standards for Hazardous Air Pollutants constrain thermal oxidizer designs and exhaust treatment configurations in US chemical processing facilities. REACH registration obligations and EU Green Deal decarbonization targets are reshaping European buyer specifications toward heat recovery integration and reduced nitrogen oxide emissions. Stakeholders must monitor how evolving energy efficiency codes and carbon border adjustment mechanisms alter total cost of ownership calculations across regional procurement decisions.
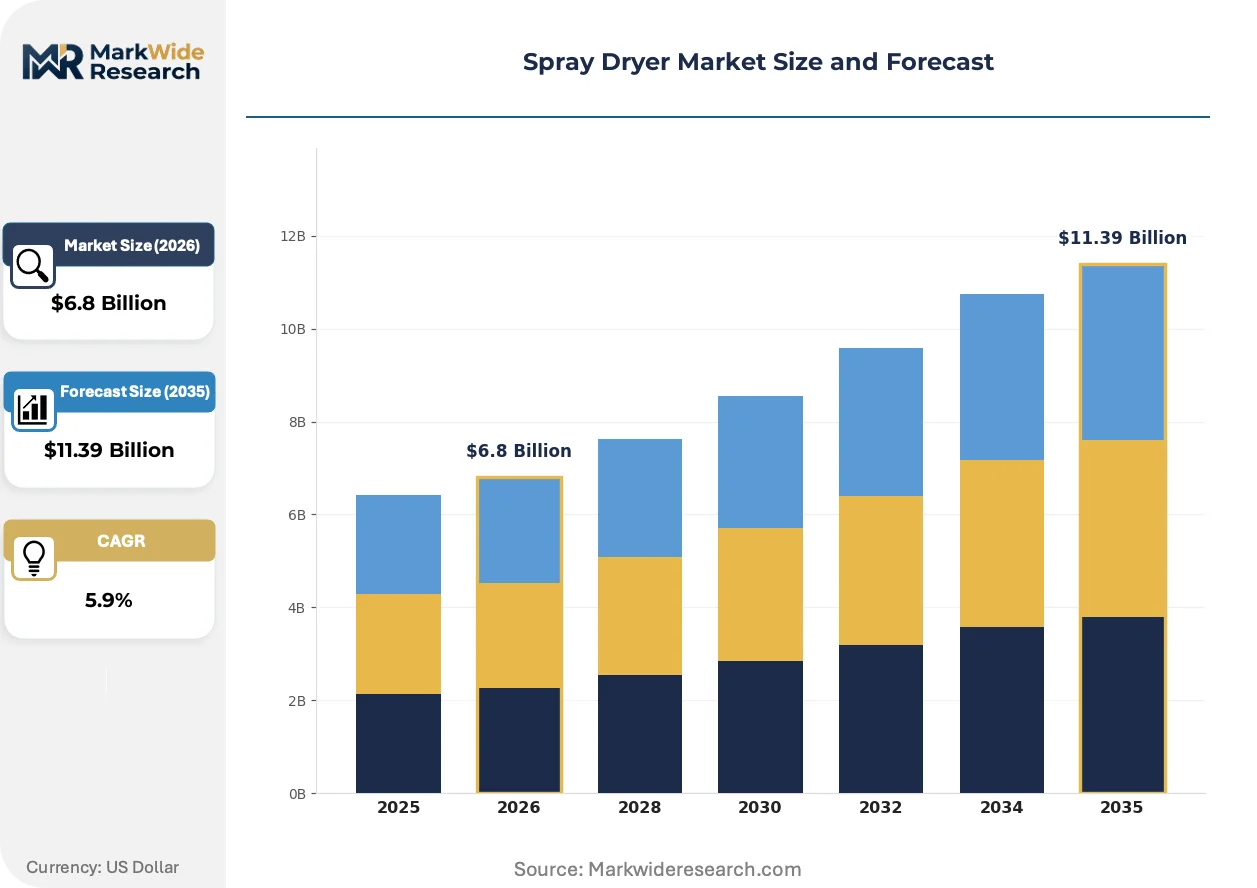
Market Dynamics
Pharmaceutical purity mandates and energy efficiency codes are forcing simultaneous equipment upgrades across installed bases, compressing replacement cycles and reshaping vendor-customer contracting structures toward bundled service models.
Growth Catalysts
- API Localization Mandates:India's CDSCO production-linked incentive schemes accelerate domestic active pharmaceutical ingredient manufacturing capacity, directly expanding demand for GMP-compliant drying systems.
- Particulate Purity Standards:FDA 21 CFR Part 110 and EMA GMP Annex 15 impose surface finish and cleanability requirements that disqualify legacy carbon steel installations and trigger replacement demand.
- Nozzle Atomization Advances:Pressure nozzle technologies reduce specific energy consumption per kilogram of evaporated water, improving operating economics for high-volume dairy and chemical processors.
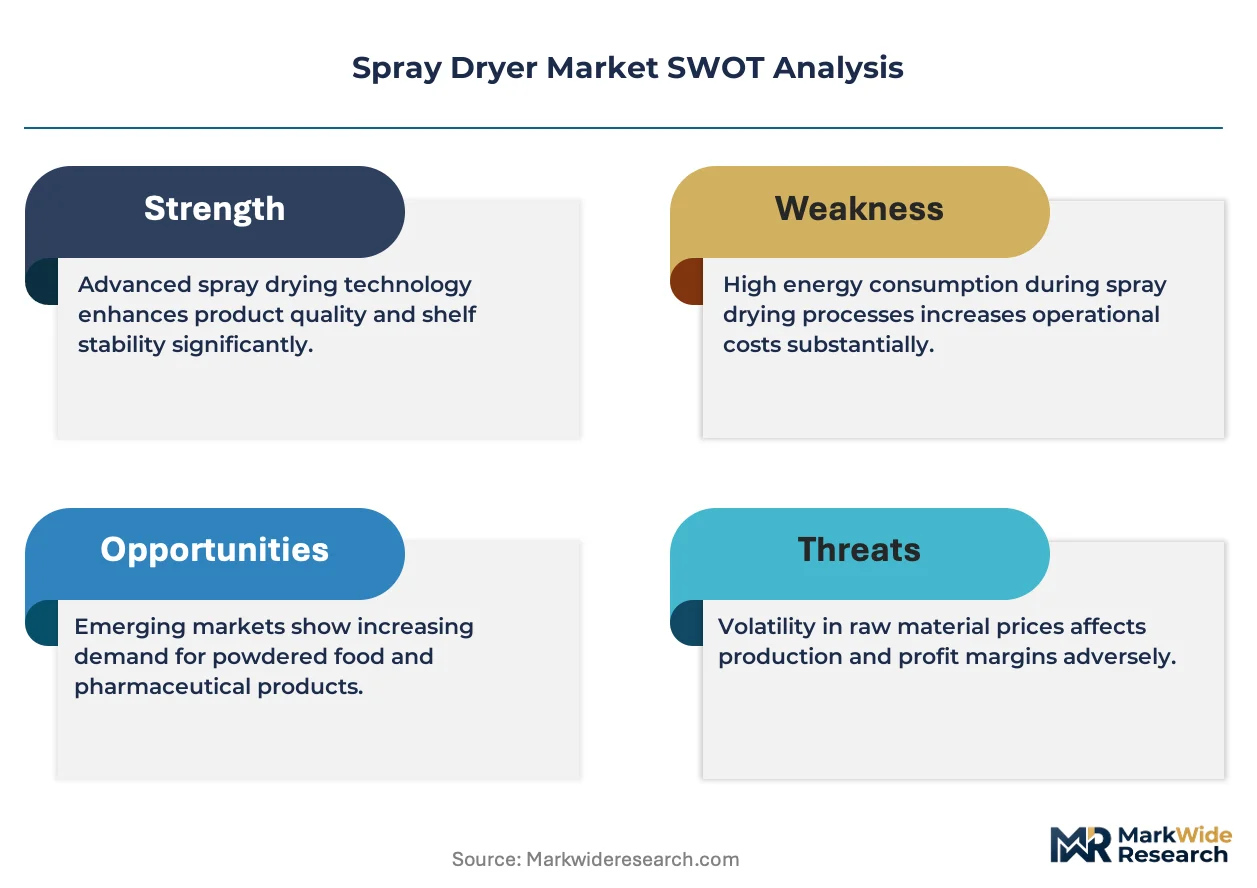
Market Restraints
- Stainless Steel Input Volatility:Grade 316L and 904L alloy pricing fluctuations compress fabrication margins and extend quotation validity periods for custom pharmaceutical units.
- Regional Supply Concentration:Atomizer nozzle manufacturing clusters in Germany and Japan create single-source dependencies for precision-engineered components serving high-specification installations.
- Thermal Oxidizer Constraints:EPA National Emission Standards for Hazardous Air Pollutants limit exhaust treatment configurations and extend permitting timelines for US chemical processing facilities.
Strategic Opportunities
- Heat Recovery Integration:EU Green Deal decarbonization targets and REACH obligations create specification pull for closed-loop thermal systems that capture exhaust enthalpy for preheating inlet air.
- Pilot-Scale Contract Manufacturing:Japanese pharmaceutical CMOs and European biotech clusters generate demand for compact, rapid-cleaning systems that support multi-product campaigns with minimal validation downtime.
- Continuous Flow Technology:Batch processing labor and cleaning validation costs in FDA-regulated environments drive capital allocation toward continuous spray drying architectures that reduce operator exposure and documentation burden.
Industry Challenges
- Qualification Timeline Compression:Installation Qualification and Operational Qualification protocols for pharmaceutical spray dryers extend project delivery schedules and strain commissioning engineer availability.
- Cross-Contamination Prevention Expertise:Multi-product facilities require specialized engineering knowledge for containment strategies and cleaning validation that outpaces current training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spray Dryer Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flash Dryer, Centrifugal Spray Dryer, Pressure Spray Dryer, Low-Pressure Spray Dryer End User: Food Processing, Pharmaceuticals, Chemicals, Biotechnology Material: Amino Acids, Dairy Products, Polymers, Inorganic Salts Technology: Traditional Methods, Advanced Methods, Continuous Flow, Batch Processing |
| Companies Covered | GEA Group, SPX FLOW, Büchi Labortechnik AG, Dedert Corporation, Tetra Pak Group, European Spraydry Technologies, Yamato Scientific, Shandong Tianli Drying Technology, Swenson Technology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spray Dryer Market Strategic Shifts
Equipment architectures and commercial models are converging around predictive capability integration and regulatory compliance automation, reducing lifecycle cost exposure for operators in validated environments.
Advanced process analytical technology is migrating from laboratory validation to production-scale deployment. Pharmaceutical manufacturers embed in-line particle size analyzers and moisture sensors to enable real-time release testing. This instrumentation compression is eliminating offline QC bottlenecks and reducing batch rejection rates in FDA-inspected facilities.
REACH registration obligations and EU Green Deal nitrogen oxide emission limits are reshaping European procurement specifications. Buyers now mandate heat recovery exchangers and low-NOx burner configurations as baseline requirements rather than optional upgrades. German dairy processors and Dutch ingredient manufacturers lead this specification tightening, extending payback period calculations to capture carbon border adjustment exposure.
Service contracting patterns are fragmenting across end-use verticals. Dairy processors in Denmark and the Netherlands negotiate predictive maintenance bundles tied to throughput guarantees, while Indian API manufacturers favor time-and-material arrangements due to capital constraints. This divergence forces vendors to maintain parallel commercial structures rather than standardized global service frameworks.
Spray Dryer Market Segmentation
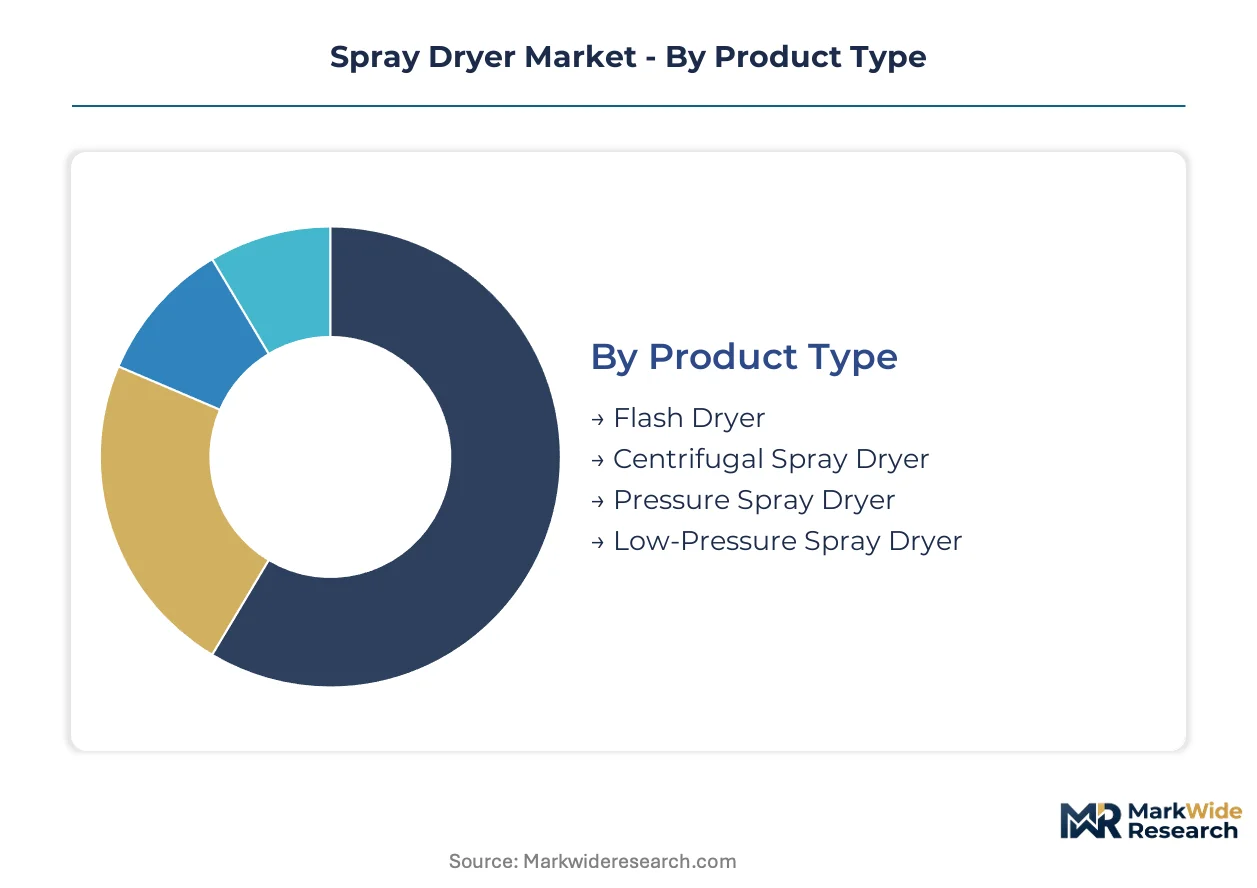
Spray dryer procurement patterns diverge sharply across product configurations and end-use verticals, with pharmaceutical buyers prioritizing qualification documentation while food processors emphasize throughput economics. Equipment specification decisions cascade through material compatibility requirements and regulatory compliance burdens that vary by installed geography.
Product Type:
After-sales service intensity varies dramatically across atomization architectures, with centrifugal systems demanding specialized rotor balancing expertise and pressure nozzle configurations requiring precision component replacement programs.
- Flash Dryer:Direct-contact pneumatic systems achieve rapid moisture removal through high-velocity hot gas streams without atomization stages. Chemical processors in Germany favor these units for heat-sensitive inorganic salts where thermal degradation risks outweigh particle morphology control needs.
- Centrifugal Spray Dryer:Rotary disc atomization handles viscosity variations across 10-10000 cP without nozzle replacement, sustaining the broadest installed base. Indian dairy cooperatives deploy these systems for milk powder production where feedstock composition fluctuates seasonally, though energy intensity per kilogram of evaporated water exceeds pressure alternatives.
- Pressure Spray Dryer:Forced liquid through precision-engineered orifices yields narrow particle size distributions critical for ceramic catalyst substrates. Japanese automotive emission control manufacturers specify these systems for washcoat powder production.
- Low-Pressure Spray Dryer:Reduced atomization energy suits thermally labile biotechnology extracts where protein denaturation thresholds constrain inlet air temperatures. Swiss contract manufacturers favor these configurations for monoclonal antibody formulation.
Centrifugal spray dryer configurations hold the largest share; momentum sits with pressure spray dryer systems as ceramic and catalyst applications expand.
End User:
Customer procurement sophistication stratifies across verticals, with pharmaceutical buyers embedding total cost of ownership models that extend 15-year equipment lifecycles while food processors optimize for capital recovery periods under 5 years.
- Food Processing:Dairy powder, infant formula, and instant coffee applications prioritize hygienic design and CIP (clean-in-place) compatibility. Dutch ingredient manufacturers drive specification tightening around nitrogen oxide emission limits and heat recovery integration.
- Pharmaceuticals:FDA 21 CFR Part 110 and EMA GMP Annex 15 compliance mandates elevate surface finish requirements to Ra 0.8 micrometers and impose extensive Installation Qualification protocols. Indian API manufacturers under CDSCO production-linked incentive schemes represent expanding demand concentration.
- Chemicals:Catalyst support materials and specialty pigment production require corrosion-resistant alloy construction. EPA National Emission Standards for Hazardous Air Pollutants constrain thermal oxidizer configurations for US installations.
- Biotechnology:Monoclonal antibody and vaccine adjuvant drying demands aseptic processing capability and rapid product changeover validation. Massachusetts and North Carolina biotech clusters generate concentrated demand for compact pilot-scale systems.
Food processing commands the greatest installed base; biotechnology is climbing the fastest as personalized medicine pipelines mature.
Material:
Feedstock thermal properties dictate atomization method selection and drying kinetics, with hygroscopic materials requiring integrated fluidized bed second-stage drying and crystalline substances tolerating simpler single-stage configurations.
- Amino Acids:Nutraceutical and pharmaceutical-grade lysine, methionine, and tryptophan production requires precise moisture control to prevent caking during storage. Chinese feed additive manufacturers represent substantial volume concentration.
- Dairy Products:Skim milk, whole milk, and whey protein concentrates demand gentle processing to preserve nutritional integrity and solubility indices. New Zealand and Irish processors lead capacity deployment.
- Polymers:Water-soluble packaging films and pharmaceutical excipients require controlled particle morphology for downstream extrusion or tableting performance. German specialty chemical producers drive specification development.
- Inorganic Salts:Detergent builders, ceramic precursors, and fertilizer components tolerate aggressive drying conditions with minimal quality degradation. Russian and Moroccan phosphate derivative processors sustain regional demand clusters.
Dairy products maintain dominant share; polymers are gaining share fastest as biodegradable packaging mandates expand across European retail supply chains.
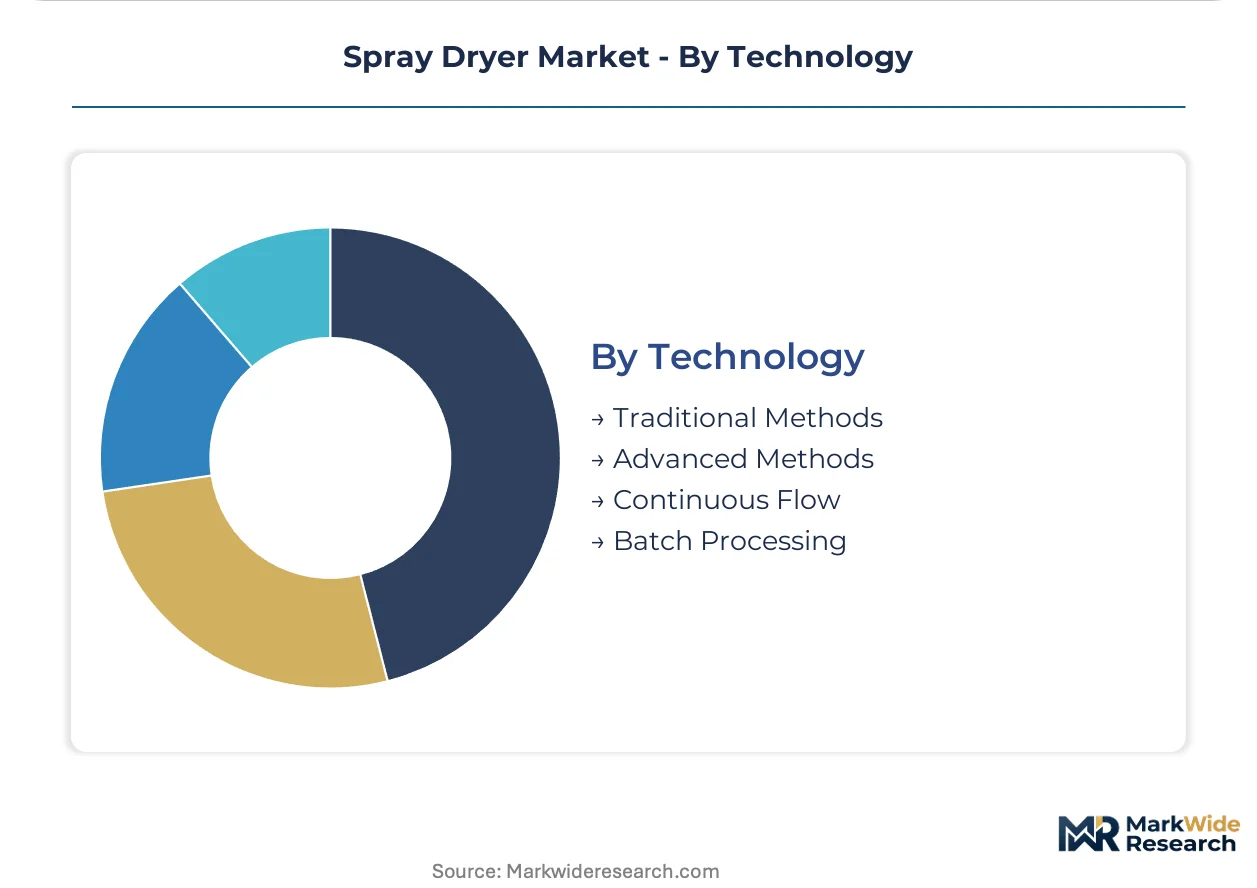
Technology:
Capital allocation patterns reveal divergent risk tolerances, with established processors defending batch processing investments against continuous flow adoption that demands upstream process reconfiguration and extended validation timelines.
- Traditional Methods:Open-cycle atmospheric systems with basic temperature and airflow control serve cost-sensitive commodity applications. Brazilian and Indonesian food processors sustain this segment through equipment life extension programs.
- Advanced Methods:Closed-loop nitrogen drying and integrated spray-freeze technologies enable oxygen-sensitive and ultra-thermolabile material processing. Swiss and Danish pharmaceutical manufacturers anchor demand for these premium configurations.
- Continuous Flow:Elimination of batch boundaries reduces operator exposure and documentation burden in FDA-regulated environments. Irish and Singaporean pharmaceutical contract manufacturers are deploying these architectures for high-volume generic API production.
- Batch Processing:Campaign flexibility and lower initial capital outlay sustain relevance for multi-product facilities with frequent changeovers. Indian and Vietnamese emerging pharmaceutical manufacturers favor this approach despite higher labor intensity.
Batch processing retains the largest installed base; continuous flow technology represents the steepest expansion trajectory as labor cost escalation and validation efficiency pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Indian pharmaceutical manufacturers prioritize GMP-compliant batch systems for API production, while European dairy processors specify heat recovery integration and low-emission burners as baseline requirements.
United States
Biotechnology clusters in Massachusetts and North Carolina drive demand for compact pilot-scale spray dryers. FDA 21 CFR Part 110 mandates surface finish and cleanability standards that disqualify legacy carbon steel installations. EPA National Emission Standards constrain thermal oxidizer configurations, extending permitting timelines for chemical processing facilities in Texas and Louisiana.
Germany
Dairy cooperatives and ingredient manufacturers anchor European heat recovery specification tightening. EU Green Deal decarbonization targets and REACH obligations reshape procurement toward closed-loop thermal systems. The Ruhr industrial corridor and Bavarian chemical clusters lead deployment of low-NOx burner configurations as standard rather than optional upgrades.
India
CDSCO production-linked incentive schemes accelerate domestic active pharmaceutical ingredient manufacturing capacity. Pharmaceutical spray dryer installations concentrate in Maharashtra and Gujarat, where contract manufacturers upgrade from legacy equipment to stainless steel systems. BIS and CDSCO mandates compress replacement cycles for export-oriented facilities.
Japan
Pharmaceutical contract manufacturers in the Kanto and Kansai regions generate concentrated demand for rapid-cleaning pilot-scale systems. METI industrial efficiency codes and PMDA GMP requirements elevate qualification documentation burdens. Compact system specialists serve multi-product campaigns with minimal validation downtime.
Switzerland
Contract manufacturers for monoclonal antibody formulations favor low-pressure spray dryer configurations. Swissmedic and EMA-aligned standards impose stringent containment and cross-contamination prevention protocols. Basel and Zurich biotech clusters sustain premium positioning for thermally labile biotechnology extract processing.
Spray Dryer Market Competitive Environment
Capability concentration sits with precision atomization specialists; scale advantage sits with diversified process equipment conglomerates. The vendor base stratifies across three tiers: integrated dairy and pharmaceutical process line suppliers, standalone drying equipment fabricators, and compact pilot-scale system specialists. Strategic moves center on backward integration into atomizer nozzle manufacturing and predictive maintenance contract bundling.
Among European diversified process equipment groups, GEA Group and Tetra Pak Group exemplify scale-driven positions anchored by installed base leverage. SPX FLOW occupies a position emphasizing upstream control over precision components. Büchi Labortechnik AG represents the compact specialist archetype serving laboratory and pilot-scale validation environments. Yamato Scientific sits within the premium-tier Japanese specialist segment. Shandong Tianli Drying Technology exemplifies Chinese equipment fabricators expanding regional presence.
| Leading Market Players |
|---|
| GEA Group |
| SPX FLOW |
| Büchi Labortechnik AG |
| Dedert Corporation |
| Tetra Pak Group |
| European Spraydry Technologies |
| Yamato Scientific |
| Shandong Tianli Drying Technology |
| Swenson Technology, Inc. |
| Others |
Value Chain & Pricing Dynamics
The Ruhr industrial corridor's atomizer nozzle fabrication capacity anchors European supply, with precision-engineered component shortages translating directly into extended quotation validity periods and elevated pricing power for German and Japanese manufacturers serving pharmaceutical installations.
Pricing Analysis
Long-term service bundling dominates contract structures, with original equipment manufacturers embedding predictive maintenance into new unit sales to capture recurring revenue streams. Pricing stratifies across premium, standard, and economy tiers based on surface finish certification grade and after-sales service inclusion. Cost compression in economy-tier carbon steel systems is intensifying because Indian API manufacturers prioritize capital recovery periods under five years. Dairy processors in the Netherlands and Denmark exhibit lowest price sensitivity due to throughput guarantee requirements, while emerging pharmaceutical manufacturers in Vietnam and Indonesia drive spot-market volatility.
Supply Chain Analysis
Contract manufacturing concentration sits with GEA Group and Tetra Pak Group in Germany and Denmark, SPX FLOW in the United States, and Yamato Scientific in Japan. Grade 316L and 904L stainless steel draws from Finnish and Swedish metallurgical suppliers, while precision atomizer nozzles rest on German and Japanese machining clusters. Single-source vulnerability concentrates in ceramic nozzle orifice manufacturing for pressure spray dryer configurations. Distribution runs through direct OEM sales teams for pharmaceutical installations and regional equipment distributors serving food processing commodity buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment interoperability standards and predictive analytics platforms are creating ecosystem lock-in effects, with vendor-specific sensor architectures and data formats raising switching costs for operators in validated environments.
For Market Incumbents: Build installed base moats through backward integration into atomizer nozzle manufacturing and captive aftermarket service networks. GEA Group's dairy processing leverage across Europe demonstrates how long-term service agreements defend against SPX FLOW's precision component control. Incumbents should prioritize heat recovery integration R&D to capture EU Green Deal specification tightening before challengers achieve certification.
For New Entrants and Emerging Players: Establish a beachhead in compact pilot-scale systems for biotechnology contract manufacturing, where Swiss and Massachusetts clusters generate concentrated demand with minimal incumbent saturation. White-space opportunities concentrate in rapid-cleaning architectures for multi-product campaigns and continuous flow technology for high-volume generic API production. A go-to-market angle emphasizing qualification documentation support addresses the training pipeline gap in cross-contamination prevention expertise.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity arbitrage play because FDA and EMA qualification burdens create durable barriers against commoditization. Acquisition targets should display precision atomization engineering capability and established IQ/OQ protocol libraries. The signal to watch is CDSCO production-linked incentive scheme expansion into continuous flow technology subsidies, which would accelerate replacement cycles beyond current batch-processing dominance.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nozzle Manufacturing | SPX FLOW's upstream control over precision components anchors competitive differentiation against diversified conglomerates. |
| Heat Recovery System Integration | EU Green Deal nitrogen oxide limits and REACH obligations reshape German and Dutch procurement toward closed-loop thermal architectures. |
| Predictive Maintenance Contract Bundling | GEA Group's service revenue capture across European dairy installations demonstrates recurring revenue model viability. |
| Continuous Flow Technology Deployment | Irish and Singaporean pharmaceutical contract manufacturers reduce labor costs and validation documentation through batch-eliminating architectures. |
| Pilot-Scale System Specialization | Yamato Scientific's compact configurations serve Japanese CMO multi-product campaigns with minimal validation downtime requirements. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing pharmaceutical plant engineers, dairy processing maintenance directors, chemical procurement leads, and aftermarket service heads at OEMs. Secondary validation drew from FDA 21 CFR Part 110 filings, EMA GMP Annex 15 guidance documents, CDSCO production-linked incentive scheme notifications, and EU Green Deal decarbonization target disclosures. Bottom-up unit economics and top-down market sizing were triangulated to establish segmentation boundaries.
Calibration against historical replacement cycle data and regulatory mandate implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include atomization architecture, end-use vertical, material thermal properties, and technology deployment mode. CAGRs were derived from equipment shipment volumes, capacity expansion announcements, and qualification timeline compression trends. Forecast inputs incorporated stainless steel alloy price volatility indices and regional energy efficiency code adoption curves.
Sensitivities concentrate around CDSCO subsidy expansion rates, REACH enforcement intensity, and carbon border adjustment mechanism implementation scope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and commodity input price stabilization. Quarterly review of Indian API manufacturing capacity utilization, EU thermal oxidizer emission limit revisions, and Grade 316L alloy futures pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Chewing Gum Machine Market
Food Processing Equipment
Commercial Oven Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Spiral Cooler Market
Food Processing Equipment
Global Wine Tanks Market
Food Processing Equipment
North America Cold Storage Market
Food Processing Equipment
Food Processor Market
Food Processing Equipment
Small Continuous Fryer Market
Food Processing Equipment
Smart Bread Maker Market
Food Processing Equipment
Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Global Commercial Food Dehydrators Market
Food Processing Equipment
Cake Cutting Machines Market
Food Processing Equipment
Food Industry Vacuum Cooling Equipment Market
Food Processing Equipment
Canada Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Spray Dried Food Market
Food Processing Equipment
Nut Processing Machine Market