
 Food Processing Equipment Market | 2026-2036
Food Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
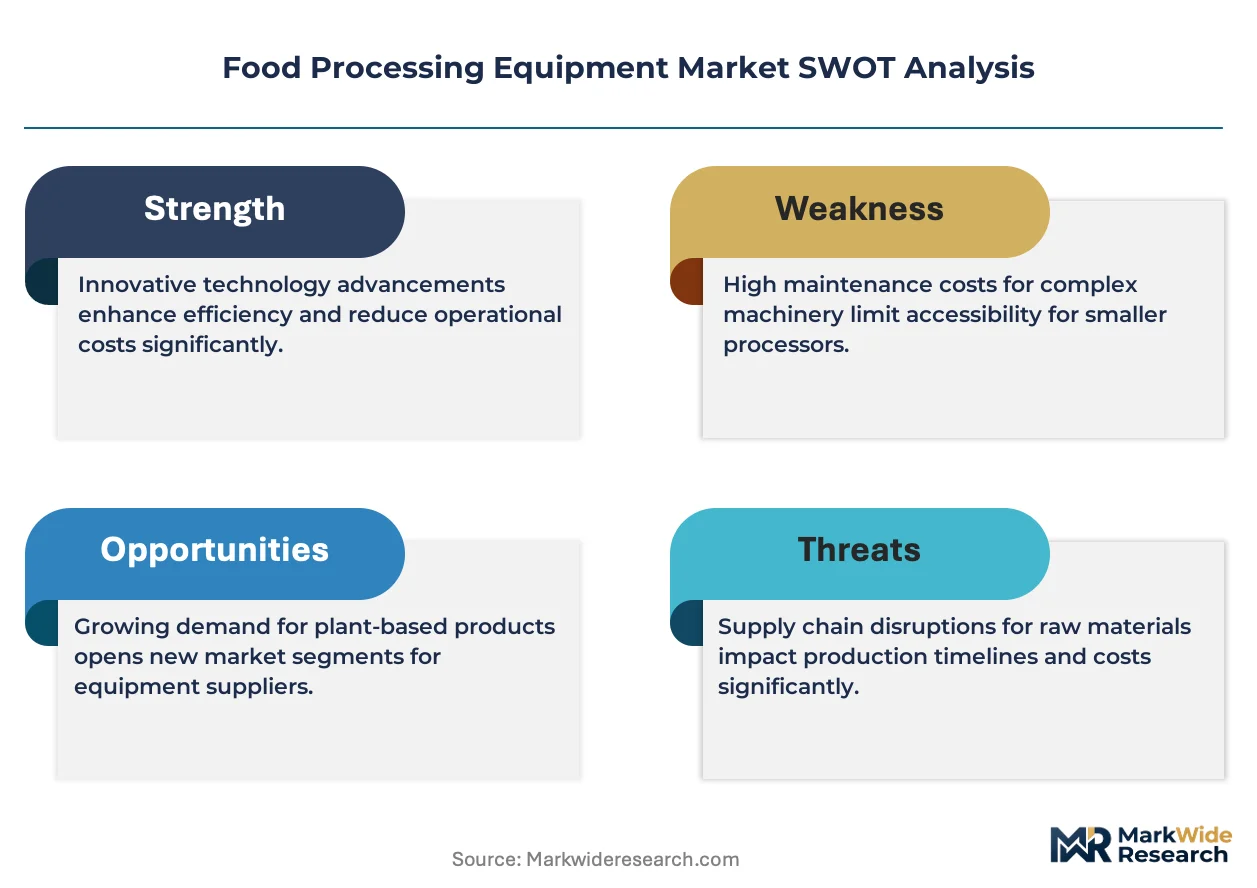
Food Processing Equipment Market Analysis
Skilled technician availability for automated food processing lines is collapsing across mature manufacturing economies, forcing equipment buyers to favor simpler, self-diagnosing machinery. GEA Group leverages its deep aftermarket service network to capture recurring revenue from maintenance-starved plants. Tetra Pak International anchors its position through captive aseptic technology that few competitors can replicate. Marel sustains leadership in protein processing by dominating sensor-integrated cutting and sorting systems.
Food processing equipment encompasses industrial machinery designed to transform raw agricultural inputs into packaged consumer goods through mechanical, thermal, or chemical operations, typically operating at throughput rates from 500 kg to 50 tonnes per hour and constructed from food-grade stainless steel to meet sanitation protocols. Mixers and grinders constitute mature, high-volume categories where margin pools have compressed, while ovens—especially hybrid thermal systems—are absorbing disproportionate R&D investment due to energy efficiency mandates. Automatic technology leads capital deployment among food manufacturers seeking labor substitution, whereas semi-automatic equipment retains strongholds in catering services and mid-size bakeries where batch flexibility outweighs throughput maximization.
The FDA's Food Safety Modernization Act and the EU's Machinery Directive (2006/42/EC) impose stringent hygienic design and traceability requirements that elevate compliance costs for market entrants while rewarding incumbents with certified product portfolios. China's SAMR enforces GB standards for food contact materials that diverge from Western norms, fragmenting equipment specification for multinational suppliers. Stakeholders must monitor how divergent energy efficiency regulations across the US, Europe, and China reshape equipment design priorities and factory location decisions.
Market Dynamics
Ready-to-eat meal manufacturers are accelerating capital deployment on automated processing lines as labor availability collapses across mature manufacturing economies, forcing equipment architecture toward self-diagnosing machinery with reduced technician dependency.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is mandating natural refrigerant-based systems, compelling equipment replacement cycles across cold-chain processing facilities in Germany and France.
- Precision engineering clusters:Germany's concentrated supplier ecosystems for advanced bakery and dairy equipment are shortening procurement lead times for European food manufacturers seeking hygienic design certification.
- Sensor-integrated cutting systems:Protein processors are adopting machine-vision-guided portioning equipment to optimize yield rates and reduce giveaway in high-volume slaughtering operations.
Market Restraints
- Food-grade stainless steel volatility:Nickel and chromium price swings are compressing margin pools for mixer and grinder manufacturers operating on fixed-price contracts with institutional buyers.
- Technician scarcity:The collapse of skilled maintenance labor availability in Japan and South Korea is extending equipment downtime periods and elevating total cost of ownership for automated lines.
- Regulatory fragmentation:China's SAMR enforces GB standards for food contact materials that diverge from FDA and EFSA protocols, forcing multinational suppliers to maintain parallel certification inventories.
Strategic Opportunities
- India's PLI scheme for food processing:Production-linked incentives for cold chain infrastructure are creating first-mover advantages for refrigeration equipment makers establishing local assembly operations.
- Hybrid thermal oven convergence:Combining infrared and convection heating technologies is opening premium positioning for energy-efficient baking systems targeting EU Green Deal compliance deadlines.
- Direct-to-manufacturer digital channels:Mid-size bakeries and catering services are bypassing traditional distributor networks through equipment-as-a-service platforms with embedded predictive maintenance.
Industry Challenges
- Sanitation protocol certification timelines:FDA Food Safety Modernization Act compliance documentation is extending equipment validation periods by four to six months for aseptic filling system deployments.
- Legacy system integration friction:Brownfield plants with 1990s-era SCADA architectures face protocol incompatibility when retrofitting IoT-enabled sensors for real-time quality monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Processing Equipment Market |
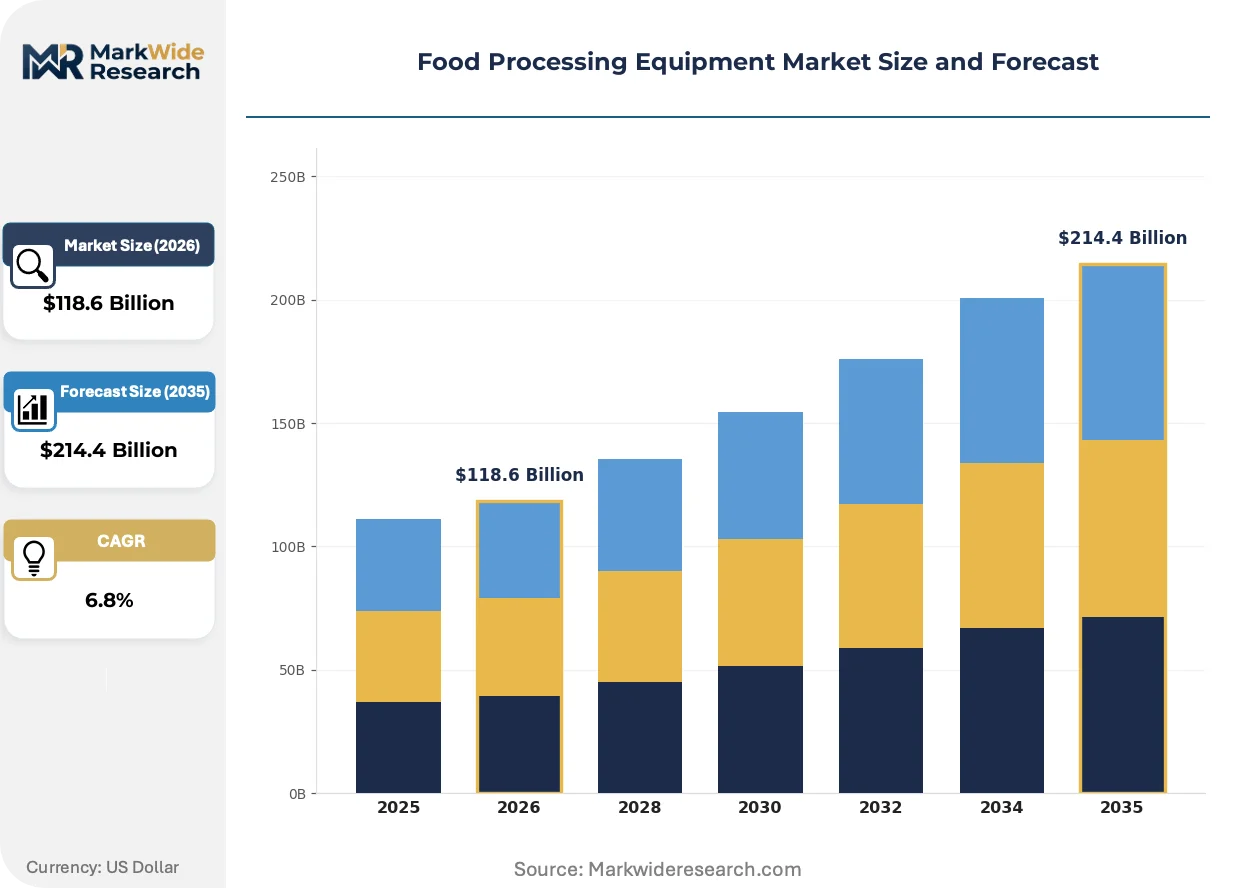
| Market Size in 2026 | $118.6 Billion |
| Market Size in 2035 | $214.4 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mixers, Choppers, Grinders, Ovens Application: Beverages, Dairy, Bakery, Seafood End User: Restaurants, Food Manufacturers, Catering Services, Supermarkets Technology: Automatic, Semi-Automatic, Manual, Hybrid |
| Companies Covered | JBT Corporation, Marel, Tetra Pak International, SPX Flow, Krones AG, GEA Group, Alfa Laval, Provisur Technologies, Bühler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Processing Equipment Market Emerging Trajectories
Equipment architecture is pivoting from throughput maximization toward energy efficiency and autonomous operation as energy costs and labor scarcity simultaneously intensify across production geographies.
Electromagnetic heating technology is supplanting conventional gas-fired thermal systems in hybrid oven designs. Artisan bakeries and industrial croissant manufacturers in Denmark and Belgium are piloting these systems to achieve precise temperature zoning. The shift is compressing energy consumption benchmarks and enabling real-time thermal profile adjustment without combustion lag.
REACH chemical substance restrictions are tightening specifications for lubricants and coatings used in food-contact equipment surfaces. European manufacturers must now reformulate bearing greases and conveyor belt coatings to eliminate SVHC candidates. Dairy processing equipment suppliers are responding by accelerating biobased lubricant qualification programs ahead of 2025 authorization deadlines.
Buyer preference is rotating toward outcome-based equipment performance guarantees rather than capital purchase models. Protein processors in Brazil and Australia are demanding throughput-commitment contracts with vendors absorbing yield risk. This restructures revenue recognition for cutting and sorting system suppliers toward recurring service fee structures with embedded hardware refresh obligations.
Food Processing Equipment Market Segmentation
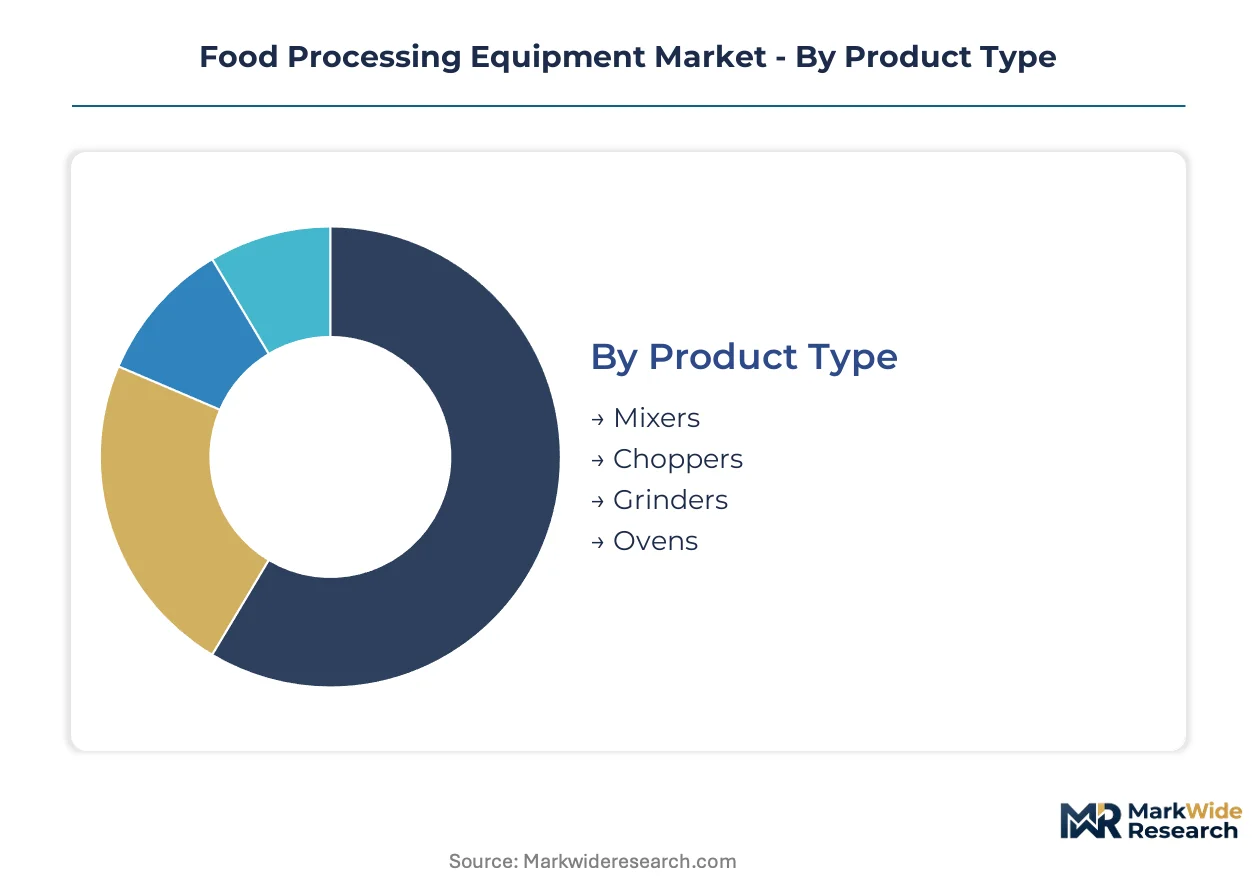
Equipment specification diverges sharply across end-use intensity and regulatory exposure, forcing suppliers to maintain parallel product architectures. Segmentation reveals where margin pools concentrate versus where volume throughput dominates procurement decisions.
Product Type:
Domestic demand in Germany and France absorbs precision-engineered thermal systems, while export-led shipments of mixing and grinding equipment flow from Chinese and Indian assembly hubs to emerging market processors.
- Mixers:Planetary and spiral configurations dominate high-volume dough processing, with bowl capacities scaling from 20 to 600 liters. German bakery chains are retrofitting legacy lines with energy-recovery bowl jackets to meet EU Green Deal thermal efficiency mandates. Margin compression is acute due to nickel-price volatility in food-grade stainless steel supply contracts.
- Ovens:Hybrid thermal systems combining infrared and convection heating are absorbing disproportionate R&D investment. Danish and Belgian artisan manufacturers are piloting electromagnetic heating variants that eliminate combustion lag and enable real-time zoning adjustments. Energy efficiency certification now gates access to public procurement channels across Northern Europe.
- Choppers:Bowl cutters and vertical blade systems process meat and vegetable matrices at throughputs exceeding 3,000 kg per hour. Brazilian beef processors are the dominant export destination for mid-tier configurations.
- Grinders:Single-screw and twin-screw extrusion systems reduce particle size for sausage emulsion and pet food applications. Fixed-price contracts with US institutional buyers have compressed supplier margins during chromium price spikes.
Ovens command the established base. The steepest expansion runs through hybrid thermal configurations.
Application:
Cost tier stratification separates premium aseptic dairy systems from standardized bakery equipment, with seafood processing occupying a narrow mid-tier characterized by seasonal demand volatility.
- Dairy:Ultra-high-temperature pasteurizers and aseptic filling systems operate at sterilization temperatures above 135°C with holding times under four seconds. German precision engineering clusters supply turnkey lines to European cooperatives facing F-Gas Regulation compliance deadlines for natural refrigerant conversion. Tetra Pak's captive aseptic technology limits competitive replication.
- Bakery:Lamination and proofing equipment handles croissant and viennoiserie production at throughputs exceeding 50,000 units per hour. Belgium and Denmark are piloting electromagnetic oven retrofits that compress energy consumption benchmarks by eliminating thermal mass lag. REACH restrictions on food-contact lubricants are accelerating biobased bearing grease qualification programs.
- Beverages:Carbonation and blending systems process soft drinks and functional beverages at line speeds exceeding 60,000 bottles per hour. Brazilian and Australian protein processors are demanding throughput-commitment contracts with yield-risk absorption by vendors.
- Seafood:Gutting and filleting lines process whitefish and salmon at rates scaling with seasonal catch volumes. Japanese and South Korean technician scarcity is extending downtime periods for automated portioning systems.
Dairy commands the established base. The steepest expansion runs through bakery equipment with hybrid thermal integration.
End User:
Customer type determines automation depth, with food manufacturers pursuing full-line integration while catering services and mid-size bakeries prioritize batch flexibility over throughput maximization.
- Food Manufacturers:Integrated processing lines operate at throughputs from 500 kg to 50 tonnes per hour with SCADA-linked quality monitoring. Ready-to-eat meal specialists in Germany and France are accelerating capital deployment as labor availability collapses, favoring self-diagnosing machinery with reduced technician dependency. FDA Food Safety Modernization Act validation timelines are extending equipment deployment by four to six months.
- Catering Services:Semi-automatic batch equipment supports menu rotation with rapid changeover protocols. Mid-size European operators are bypassing distributor networks through equipment-as-a-service platforms embedding predictive maintenance.
- Restaurants:Compact countertop mixers and convection ovens serve back-of-house operations with footprint constraints below two square meters. India's PLI scheme for cold chain infrastructure is creating first-mover advantages for refrigeration equipment makers establishing local assembly.
- Supermarkets:In-store bakery and prepared meal sections require equipment meeting open-kitchen visibility standards with reduced noise emissions. Brownfield integration friction with 1990s-era SCADA architectures is blocking IoT sensor retrofits for real-time monitoring.
Food manufacturers command the established base. The steepest expansion runs through catering services adopting subscription-based equipment access.
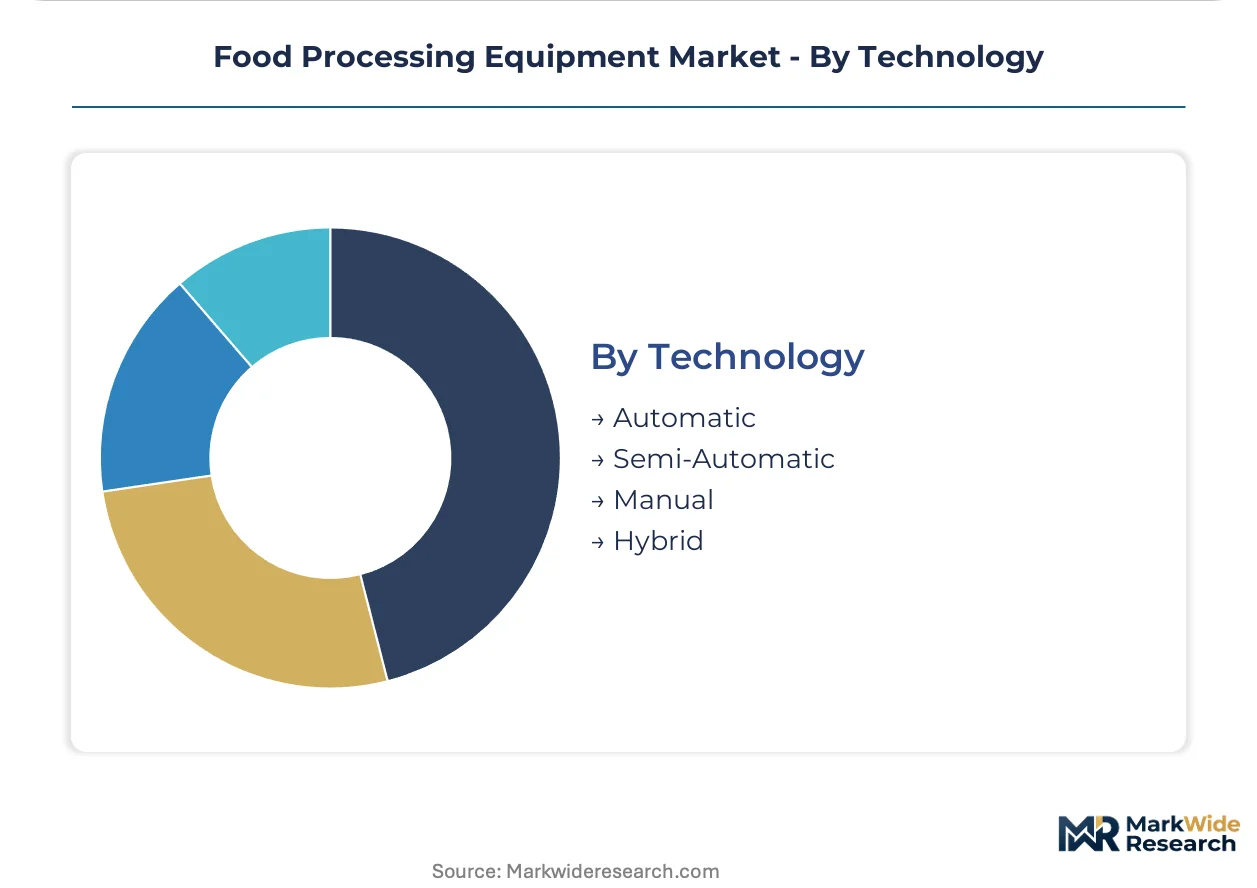
Technology:
Volume concentration favors automatic systems in protein and dairy processing, while manual and semi-automatic equipment retains strongholds where batch customization outweighs labor substitution economics.
- Automatic:Machine-vision-guided portioning and sensor-integrated cutting systems optimize yield rates in high-volume slaughtering operations. Marel dominates protein processing through real-time sorting algorithms that reduce giveaway. Technician scarcity in Japan and South Korea is elevating total cost of ownership for maintenance-starved plants.
- Hybrid:Electromagnetic-convection combinations enable precise thermal profiling without combustion infrastructure. EU Green Deal compliance deadlines are accelerating replacement cycles for gas-fired legacy systems in German industrial bakeries.
- Semi-Automatic:Operator-supervised batch processing supports mid-volume production with recipe flexibility. China's SAMR enforces GB standards for food contact materials that diverge from FDA and EFSA protocols, fragmenting equipment specification for multinational suppliers.
- Manual:Hand-fed grinders and mixers serve artisan producers and regulatory-exempt micro-enterprises with outputs below 100 kg per hour. Precision engineering clusters in Southern Germany supply hygienic design certification for export to Swiss and Austrian alpine dairies.
Automatic systems command the established base. The steepest expansion runs through hybrid configurations bridging efficiency and flexibility requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany absorbs precision-engineered thermal systems for industrial bakeries, while Brazil and Australia drive protein processing equipment with yield-optimization contracts. China and India concentrate mixing and grinding exports from cost-optimized assembly hubs serving emerging market processors.
Germany
Industrial bakeries in Baden-Württemberg and Bavaria retrofit legacy lines with energy-recovery bowl jackets to meet EU Green Deal thermal efficiency mandates. The F-Gas Regulation compels cold-chain facilities to replace hydrofluorocarbon systems with natural refrigerant alternatives by 2030. Precision engineering clusters around Stuttgart and Munich shorten procurement lead times for hygienic design certification.
United States
Ready-to-eat meal manufacturers accelerate capital deployment on automated processing lines as labor availability collapses in Midwestern protein processing corridors. The FDA Food Safety Modernization Act extends equipment validation periods by four to six months for aseptic filling system deployments. Brownfield plants in Nebraska and Iowa face SCADA protocol incompatibility when retrofitting IoT-enabled sensors.
Brazil
Beef processors dominate export demand for bowl cutters and vertical blade systems processing meat matrices at throughputs exceeding 3,000 kg per hour. ANVISA enforces sanitary inspection protocols that elevate compliance documentation for foreign equipment suppliers. São Paulo-based cooperatives demand throughput-commitment contracts with vendors absorbing yield risk in high-volume slaughtering operations.
China
Domestic assembly hubs in Shandong and Jiangsu provinces export standardized mixing and grinding equipment to Southeast Asian and African processors. SAMR enforces GB standards for food contact materials that diverge from FDA and EFSA protocols, fragmenting equipment specifications for multinational suppliers. The dual carbon goals policy accelerates electromagnetic heating pilot programs in industrial food manufacturing.
India
The PLI scheme for food processing creates first-mover advantages for refrigeration equipment makers establishing local assembly operations in Maharashtra and Gujarat. FSSAI mandates diverge from Codex Alimentarius frameworks on food contact surface specifications. Cold chain infrastructure investments concentrate around Mumbai and Ahmedabad dairy cooperatives facing post-harvest loss reduction targets.
Food Processing Equipment Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding captive technology and aftermarket service networks. The middle tier fragments across regional equipment fabricators with limited cross-border certification capabilities. Three archetypes dominate: full-line integrators with proprietary aseptic systems, sensor-integrated protein processing specialists, and precision thermal equipment engineers. Competitive moves concentrate on strategic partnerships for refrigerant technology transition and geographic expansion into PLI-subsidized Indian assembly.
Within the integrated leader tier, Tetra Pak International and GEA Group exemplify divergent defensive strategies—one through captive aseptic technology, the other through deep aftermarket service networks. Marel occupies a distinct position in protein processing archetypes. Among European precision engineering clusters, Krones AG and Bühler Group represent heritage fabricators with concentrated regional certification authority. Alfa Laval and SPX Flow sit within the thermal and fluid processing specialist tier, while JBT Corporation and Provisur Technologies exemplify protein and packaging equipment consolidation plays.
| Leading Market Players |
|---|
| JBT Corporation |
| Marel |
| Tetra Pak International |
| SPX Flow |
| Krones AG |
| GEA Group |
| Alfa Laval |
| Provisur Technologies |
| Bühler Group |
| Others |
Supply Flow & Price Mechanics
Natural refrigerant substitution for hydrofluorocarbon systems is simultaneously relocating equipment assembly toward German precision engineering clusters and compressing margin pools for cold-chain manufacturers locked into fixed-price contracts with institutional buyers.
Pricing Analysis
Long-term offtake contracts dominate procurement between European dairy cooperatives and turnkey line suppliers, while spot purchasing persists for standardized mixing components from Chinese assembly hubs. Three-tier pricing structure across premium, standard, and economy levels separates aseptic filling systems with captive technology from modular batch equipment and manual grinders. Cost compression in mid-tier thermal systems is intensifying because nickel-price volatility in food-grade stainless steel supply contracts has eroded supplier margins. Mid-size bakeries and catering services exhibit highest price sensitivity, whereas protein processors absorbing yield-risk contracts show lowest sensitivity due to throughput-commitment structures.
Supply Chain Analysis
Food-grade stainless steel refining capacity in Germany, China, and India anchors upstream material flows for hygienic equipment fabrication. Sensor-integrated cutting systems draw from precision machining clusters in Denmark and Belgium, while natural refrigerant compressor production rests on captive technology held by a narrow supplier set. Single-source vulnerability in aseptic filling valve assemblies creates procurement risk for dairy line integrators facing FDA validation timelines. Distribution runs through OEM-direct channels for large food manufacturers and equipment-as-a-service platforms for mid-tier catering operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food processing equipment sits in early-cycle expansion as labor scarcity across mature manufacturing economies accelerates capital deployment toward self-diagnosing automated lines.
For Market Incumbents: Compound aftermarket service network density to capture recurring revenue from maintenance-starved plants in Japan and South Korea. Deepen captive aseptic technology moats against emerging refrigeration equipment specialists exploiting India's PLI scheme subsidies. Prioritize certification investment for EU F-Gas Regulation compliance ahead of natural refrigerant conversion deadlines. For New Entrants and Emerging Players: Lead with equipment-as-a-service platforms targeting mid-size European bakeries and catering services bypassing traditional distributor networks. India's cold chain infrastructure subsidies represent the most penetrable geography for refrigeration assembly localization. Deploy predictive maintenance bundling as the primary go-to-market angle against incumbent capital-sales models. For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors precision thermal engineering specialists with electromagnetic heating patent positions. Long-term viability hinges on energy efficiency certification authority across EU Green Deal compliance windows. Acquisition targets should demonstrate backward integration into food-grade stainless steel fabrication or sensor-integrated control systems. Watch F-Gas Regulation enforcement intensity as the inflection signal for natural refrigerant equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Technology Transition | EU F-Gas Regulation mandates equipment replacement cycles across German and French cold-chain facilities. |
| Electromagnetic Heating Patent Development | Danish and Belgian artisan manufacturers pilot systems eliminating combustion lag for EU Green Deal compliance. |
| Equipment-as-a-Service Platform Launch | Mid-size European catering operators bypass distributor networks through subscription-based predictive maintenance access. |
| Precision Engineering Cluster Expansion | Stuttgart and Munich supplier ecosystems shorten procurement lead times for hygienic design certification. |
| Biobased Lubricant Qualification Program | REACH chemical restrictions force reformulation of bearing greases ahead of authorization deadlines. |
Methodological Framework
Cross-validation between regulatory filing analysis and equipment procurement databases anchors the qualitative findings on compliance cost structures. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads combined with secondary validation from FDA 510(k) filings, EU Machinery Directive compliance registries, SEC 10-K equipment supplier disclosures, and customs trade data. Bottom-up segmentation modeling and top-down macroeconomic triangulation ensure coverage consistency across the analysis window.
Sensitivity analysis on nickel-price volatility and labor-availability scenarios frames the quantitative projections. The forecast framework models equipment type, application intensity, automation technology tier, and end-user scale across the projection horizon. CAGRs derive from regression analysis against capital expenditure patterns and regulatory compliance deadlines. Industry-specific inputs include F-Gas Regulation phase-down schedules and India's PLI scheme disbursement trajectories.
The analysis sits within stated boundaries; outcomes outside sustained metal price volatility or accelerated refrigerant transition timelines would require recalibration. Forecasts reflect documented assumptions on technician scarcity persistence and energy efficiency mandate enforcement. Practitioners should keep alternative scenarios live as EU Green Deal compliance deadlines and China's dual carbon goals policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Meat Mixer Market
Food Processing Equipment
Hydrostatic Steam Blancher Market
Food Processing Equipment
Shawarma Grill Machine Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
North America Cold Storage Market
Food Processing Equipment
Pasta Machine Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Mill Mixer Market
Food Processing Equipment
Mooncake Production Line Market
Food Processing Equipment
Food Processing Machinery Market
Food Processing Equipment
Sorbitol Production Equipment Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market
Food Processing Equipment
Nigeria Cocoa Processing Market
Food Processing Equipment
Micro Winery Equipment Market
Food Processing Equipment
Nugget Ice Machines Market
Food Processing Equipment
Brining Systems Market