
 Specialty Feed Additives Market | 2026-2036
Specialty Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Feed Additives Market Analysis
Commercial livestock integrators are rotating toward precision-formulated additive programs that improve feed conversion ratios and reduce environmental nitrogen load. Cargill, Incorporated leverages its captive grain origination network to secure cost-advantaged substrate positions for amino acid fermentation. Evonik Industries AG anchors its methionine franchise through backward integration into petrochemical precursors. BASF SE competes on vitamin synthesis scale, operating multi-step chemical plants with dedicated intermediate streams.
Specialty feed additives comprise biologically active compounds—amino acids, enzymes, vitamins, and probiotics—formulated at parts-per-million to percent inclusion rates to modify digestive efficiency, nutrient absorption, or metabolic function in production animals. Industrial production relies on submerged fermentation, chemical synthesis, or spray-dried cultivation followed by stabilization against pH and thermal degradation during feed pelleting. Amino acids command the largest value pool due to lysine and methionine inclusion in monogastric rations, while probiotics represent the fastest-expanding category as antibiotic growth promoter bans proliferate. Enzyme applications in corn-soy and wheat-based diets sustain premium pricing through documented phytase and xylanase efficacy in phosphorus release and viscosity reduction.
The European Food Safety Authority mandates full toxicological dossiers and environmental fate assessments for novel additives under Regulation 1831/2003, extending approval timelines and favoring incumbents with regulatory infrastructure. The FDA's Center for Veterinary Medicine enforces Good Manufacturing Practice standards for medicated and non-medicated feed additives in the United States, while China's Ministry of Agriculture and Rural Affairs implements GB standard compliance for imported enzyme and probiotic strains. Stakeholders must monitor evolving residue testing protocols and strain registration requirements to preserve market access across jurisdictions.
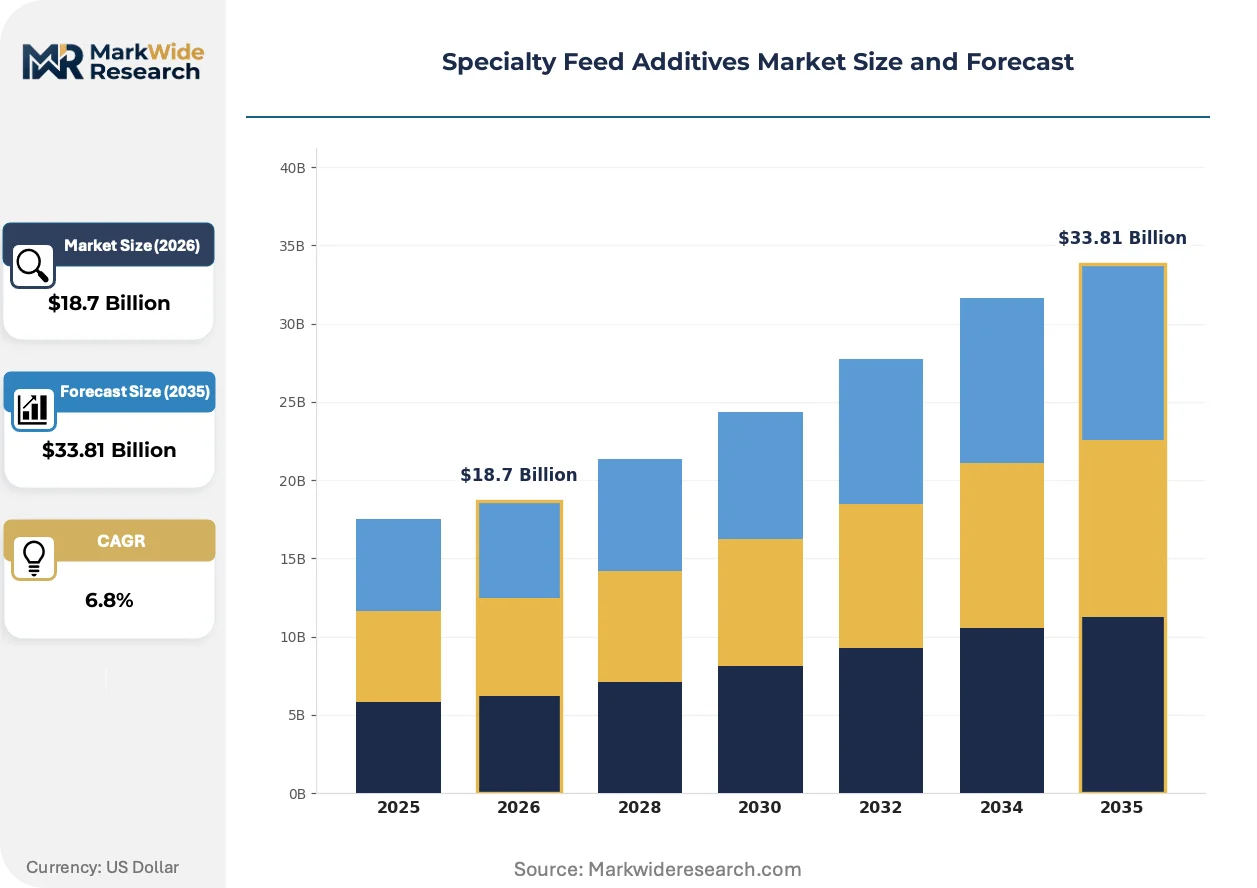
Market Dynamics
Precision fermentation infrastructure and regulatory chemistry mandates are compressing formulation margins while forcing additive producers toward captive substrate control and multi-jurisdictional dossier management.
Growth Catalysts
- Antibiotic-free mandates:Brazil's ANVISA enforcement of growth promoter restrictions drives probiotic inclusion in integrated poultry operations. Feed conversion documentation requirements accelerate microbiome-targeted additive adoption.
- F-Gas Regulation compliance:The European Union's fluorinated gas phase-down reshapes vitamin synthesis energy profiles. Producers retrofit fermentation plants with heat recovery systems to preserve margin structure.
- Phytase efficacy documentation:Corn-soy diet phosphorus release standards in US swine operations sustain enzyme premium positioning. Phytase inclusion rates climb as environmental discharge permits tighten.
Market Restraints
- Petrochemical precursor volatility:Methionine synthesis depends on propylene and methyl mercaptan supply concentrated in Gulf Coast crackers. Price spikes transmit directly to amino acid cost curves.
- Strain registration concentration:China's SAMR and Ministry of Agriculture maintain dual approval tracks for imported probiotic cultures. Registration timelines extend eighteen to thirty-six months.
- Enzyme thermal degradation limits:Pelleting temperatures above eighty-five degrees Celsius inactivate xylanase and β-glucanase activity. Stabilization coatings add three to seven percent to enzyme delivered cost.
Strategic Opportunities
- Ruminant microbiome modulation:Methane inhibitor additives for dairy and beef cattle remain underpenetrated outside European trial herds. Voluntary carbon credit frameworks in Australia and California create payment pathways.
- Direct-fed microbial expansion:Bacillus subtilis and Lactobacillus strains for aquaculture gain regulatory traction in Vietnam and Indonesia. Shrimp integrators seek alternatives to antibiotic prophylaxis.
- Enzyme-carbohydrate convergence:Multi-enzyme complexes combining phytase, xylanase, and protease activity displace single-ingredient formulations. Blended products command formulation service premiums.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiologists with submerged culture expertise command premium compensation. Academic pipeline output lags biopharma sector competition.
- EFSA dossier preparation complexity:Novel additive toxicological packages require two to four years of study execution. Environmental fate modeling for enzyme proteins lacks standardized methodology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Feed Additives Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Enzymes, Vitamins, Probiotics Application: Poultry, Ruminants, Swine, Aquaculture Form: Liquid, Powder, Granular, Premix End User: Farmers, Animal Nutrition Companies, Feed Manufacturers, Research Institutions |
| Companies Covered | Cargill, Incorporated, ADM, International Flavors & Fragrances Inc., Evonik Industries AG, BASF SE, Kemin Industries, Adisseo, Novonesis Group, Nutreco N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Feed Additives Market Emerging Trajectories
Bioprocess intensification and regulatory chemistry substitution are compressing traditional synthesis pathways while opening formulation white space in methane mitigation and precision microbiome targeting.
Continuous fermentation technology for amino acid production is fragmenting the batch-reactor incumbent base. Chinese and Southeast Asian producers deploy single-use bioreactor trains with real-time metabolite monitoring. Scale economics favor thirty-thousand-liter vessels over legacy ten-thousand-liter stainless installations, compressing capital recovery periods for new entrants.
REACH authorization requirements for chemical synthesis intermediates are forcing vitamin producers toward bio-based feedstock substitution. ECHA's sunset date scheduling for hazardous substances accelerates retinol and cholecalciferol pathway redesign. European producers absorb compliance costs while Asian competitors gain temporary arbitrage on grandfathered processes.
Integrated livestock operators now specify outcome-based additive contracts tied to feed conversion and mortality metrics. Traditional ingredient procurement through distributor networks loses share to direct formulation partnerships. This contractual evolution concentrates most visibly in Brazil's Santa Catarina and Paraná poultry belts, where margin transparency demands compress intermediary roles.
Specialty Feed Additives Market Segmentation
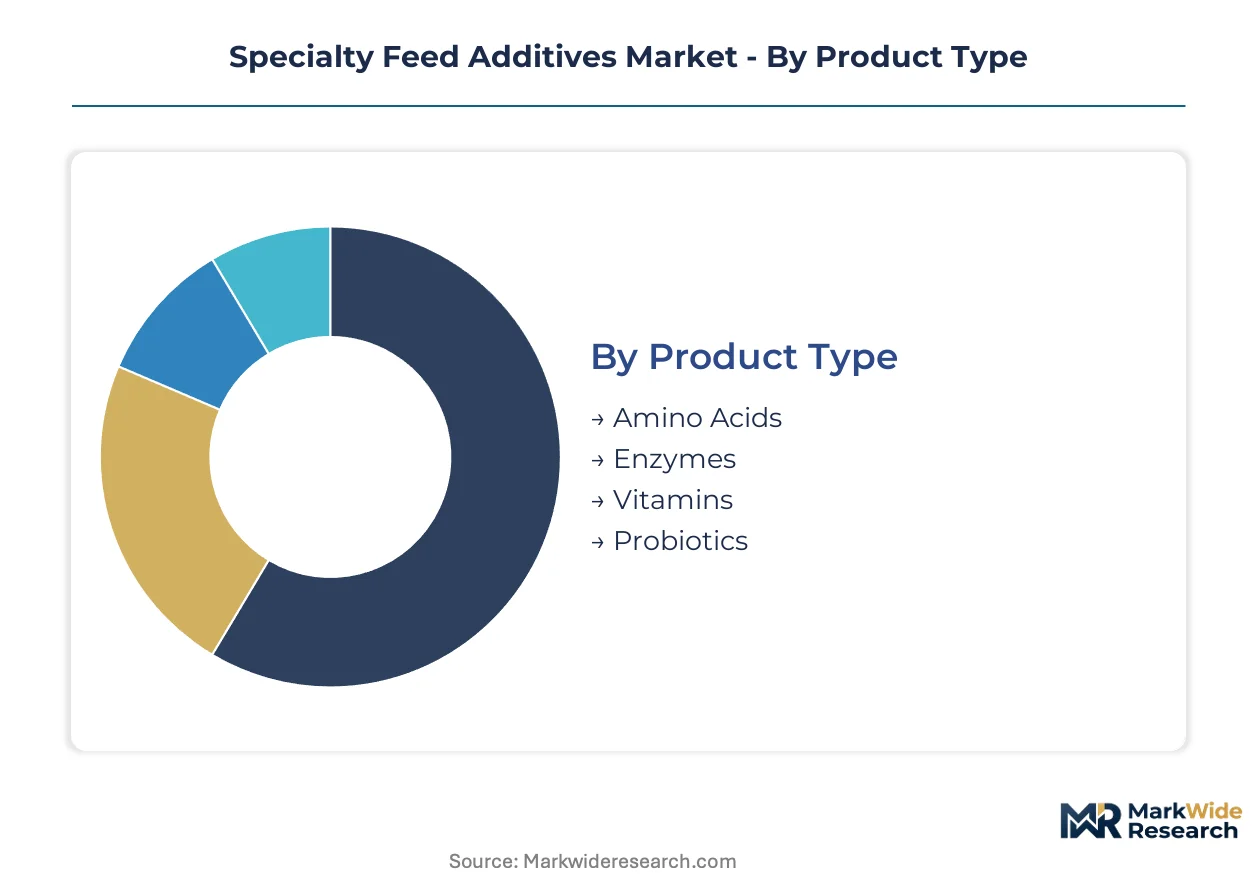
Segmentation in specialty feed additives reveals how formulation chemistry, delivery mechanisms, and customer procurement patterns diverge across livestock systems. Understanding these fractures exposes where margin pools concentrate and which technical specifications command premium positioning.
Product Type:
Amino acids and enzymes flow predominantly through export channels to integrated poultry and swine operations in Brazil and Southeast Asia, while probiotic strains face heavier domestic registration burdens that favor regional fermentation bases.
- Amino Acids:Lysine and methionine produced via submerged fermentation dominate monogastric ration formulations. Brazilian integrators in Santa Catarina and Paraná drive bulk procurement of lysine HCl for corn-soy diets, constrained by propylene precursor volatility from Gulf Coast crackers.
- Enzymes:Phytase, xylanase, and protease complexes modify digestive kinetics in wheat and corn-based feeds. US swine operations in Iowa and North Carolina sustain phytase premiums through phosphorus discharge permit tightening.
- Vitamins:Retinol, cholecalciferol, and tocopherol synthesis faces REACH authorization pressure for chemical intermediates. European producers absorb ECHA compliance costs while Asian competitors exploit grandfathered process arbitrage.
- Probiotics:Bacillus subtilis and Lactobacillus strains target antibiotic-free growth promotion. China's SAMR and Ministry of Agriculture impose eighteen to thirty-six month dual approval tracks that concentrate demand in domestic fermentation capacity.
Amino acids command the established base. The steepest expansion runs through probiotics.
Application:
Cost tier stratification separates commodity protein production from specialty aquaculture and methane mitigation trials, with ruminant applications occupying an intermediate position pending carbon credit monetization.
- Poultry:Broiler and layer operations in Brazil's expanding belt integrate precision-formulated additive programs. ANVISA enforcement of growth promoter restrictions accelerates probiotic and enzyme inclusion in integrated operations.
- Ruminants:Dairy and beef cattle present underpenetrated terrain for methane inhibitor additives. Voluntary carbon credit frameworks in Australia and California create nascent payment pathways for microbiome modulation trials.
- Swine:Phytase efficacy documentation in US operations sustains enzyme premium positioning. Environmental discharge permits tighten phosphorus release standards, climbing inclusion rates.
- Aquaculture:Shrimp integrators in Vietnam and Indonesia seek alternatives to antibiotic prophylaxis. Direct-fed microbial strains gain regulatory traction as disease pressure mounts in intensive pond systems.
Poultry anchors volume concentration. Aquaculture delivers the most rapid share gains.
Form:
Volume economics favor powder and granular delivery for bulk feed manufacturing, while liquid and premix forms capture formulation service premiums through precision inclusion and thermal stability engineering.
- Liquid:Pumpable lysine and methionine solutions suit automated dosing in large-scale feed mills. Thermal degradation risks during pelleting above eighty-five degrees Celsius limit enzyme applicability in liquid suspension.
- Powder:Spray-dried amino acids and vitamins constitute the baseline specification for international trade. Brazilian and US feed manufacturers standardize on powder delivery for blending flexibility.
- Granular:Coated enzyme granules resist pelleting heat but add three to seven percent to delivered cost. Stabilization technology separates premium suppliers from commodity producers.
- Premix:Custom-blended micro-ingredient concentrates target small-to-mid scale farmers and regional feed manufacturers. Formulation service integration captures margin beyond commodity ingredient supply.
Powder forms dominate transaction volumes. Premix structures are climbing fastest on service integration.
End User:
Procurement concentration shifts from distributor networks toward direct partnerships as integrated livestock operators specify outcome-based contracts tied to feed conversion and mortality metrics.
- Farmers:Small and mid-scale operations purchase through cooperative and distributor channels. Price transparency pressures intermediary margins in fragmented procurement systems.
- Animal Nutrition Companies:Cargill and integrated multinationals leverage captive grain origination to secure cost-advantaged substrate positions for amino acid fermentation. Direct additive partnerships displace traditional ingredient procurement.
- Feed Manufacturers:Regional mills specify enzyme and vitamin inclusion rates based on diet formulation software. Phytase and xylanase efficacy documentation drives supplier selection.
- Research Institutions:Universities and trial stations validate novel probiotic strains and methane inhibitors. EFSA dossier preparation for novel additives requires toxicological collaboration with academic partners.
Animal nutrition companies concentrate procurement leverage. Research institutions are expanding fastest as regulatory dossier demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos grain terminal expansion underwrites Brazil's central role in amino acid distribution corridors serving South American poultry integrators.
United States
Iowa and North Carolina swine operations drive phytase enzyme procurement through tightened EPA phosphorus discharge permits. The FDA Center for Veterinary Medicine enforces Good Manufacturing Practice standards for medicated feed additives. Corn Belt feed manufacturers in Des Moines and Sioux City specify multi-enzyme complexes for corn-soy diet optimization.
Germany
REACH authorization requirements for chemical synthesis intermediates reshape vitamin production economics. ECHA sunset date scheduling accelerates retinol and cholecalciferol pathway redesign toward bio-based feedstocks. Industrial chemical clusters in Ludwigshafen absorb compliance costs while maintaining multi-step vitamin synthesis operations.
China
Dual carbon goals and GB standard compliance redirect fermentation capacity expansion toward energy-efficient single-use bioreactor trains. SAMR and Ministry of Agriculture impose eighteen to thirty-six month dual approval tracks for imported probiotic strains. Shandong Peninsula amino acid producers deploy real-time metabolite monitoring at thirty-thousand-liter scale.
Brazil
ANVISA enforcement of antibiotic growth promoter restrictions accelerates probiotic inclusion in Santa Catarina and Paraná poultry belts. Integrated producers specify outcome-based additive contracts tied to feed conversion metrics. Port of Santos grain terminals channel lysine and methionine bulk shipments to domestic feed mill networks.
Netherlands
Randstad-based nutrition companies leverage proximity to EFSA headquarters for novel additive dossier preparation. The F-Gas Regulation phase-down drives fermentation plant retrofit with heat recovery systems. Wageningen University research partnerships anchor toxicological study execution for enzyme protein environmental fate modeling.
Specialty Feed Additives Market Vendor Landscape
Concentration sits with diversified chemical conglomerates and captive grain processors that control substrate supply chains. The vendor base spans three tiers: integrated multinationals with backward integration into petrochemical precursors, regional fermentation specialists with single-use bioreactor scale, and formulation service providers bundling micro-ingredient premixes. Dominant competitive moves include capacity expansion in Southeast Asian fermentation corridors and strategic partnerships between enzyme developers and integrated livestock operators.
Within the integrated multinational tier, Cargill, Incorporated and Evonik Industries AG exemplify divergent substrate control strategies. Cargill leverages captive grain origination networks for cost-advantaged fermentation feedstock positions. Evonik anchors methionine supply through upstream integration into petrochemical precursor streams. BASF SE occupies a position in vitamin synthesis scale, operating dedicated intermediate plants that compete on multi-step chemical efficiency. ADM and Kemin Industries represent the mid-tier formulation specialists, with ADM's agricultural processing footprint and Kemin's micro-ingredient service model illustrating alternative paths to customer proximity.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| ADM |
| International Flavors & Fragrances Inc. |
| Evonik Industries AG |
| BASF SE |
| Kemin Industries |
| Adisseo |
| Novonesis Group |
| Nutreco N.V. |
| Others |
Supply Flow & Price Mechanics
Propylene-to-methionine substitution chemistry simultaneously reshapes supply geography toward Gulf Coast petrochemical corridors and compresses pricing economics for amino acid producers as propylene volatility transmits directly to methionine cost curves. Buyers in Brazil's Santa Catarina poultry belt and Iowa swine operations face divergent procurement pressures depending on their exposure to fermentation-based versus chemical synthesis pathways.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates coated enzyme granules with thermal stabilization from uncoated powder formulations and commodity amino acid bulk shipments. Certification grade under EFSA and FDA Center for Veterinary Medicine standards commands fifteen to twenty percent premia over baseline specifications. Cost compression in standard-tier lysine is intensifying because Chinese single-use bioreactor scale-up erodes legacy stainless vessel economics. Small-to-mid scale farmers exhibit highest price sensitivity, while integrated livestock operators prioritize outcome-based contracts over unit cost minimization.
Supply Chain Analysis
China and Southeast Asian producers anchor submerged fermentation capacity for amino acids and enzymes, while Germany and the Netherlands concentrate vitamin synthesis and regulatory dossier expertise. Raw material flows draw from Gulf Coast propylene crackers for methionine precursors, Shandong Peninsula grain origination for fermentation substrates, and Ludwigshafen chemical clusters for vitamin intermediates. Single-source vulnerability concentrates in China's SAMR strain registration chokepoint for imported probiotic cultures. Distribution runs through Port of Santos grain terminals for South American poultry integrators and direct formulation partnerships displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibiotic-free mandate enforcement across Brazil and Southeast Asia creates a high-growth disruption as precision microbiome targeting displaces legacy growth promoter chemistries. Regulatory chemistry substitution under REACH and F-Gas Regulation protocols accelerates capital redeployment toward bio-based synthesis pathways.
For Market Incumbents: Secure captive substrate positions through backward integration into grain origination networks or petrochemical precursor streams to defend margin structure against propylene volatility. Cargill's fermentation feedstock control and Evonik's methyl mercaptan integration illustrate defensive moats. Capacity addition in Vietnam and Indonesia addresses direct-fed microbial demand growth while SAMR registration timelines protect domestic Chinese producers from import competition.
For New Entrants and Emerging Players: Differentiate on ruminant methane inhibitor efficacy documentation to access voluntary carbon credit payment pathways in Australia and California. The most penetrable terrain sits with dairy and beef cattle operations outside European trial herds where microbiome modulation remains underdeployed. Aquaculture direct-fed microbial strains for Vietnamese shrimp integrators offer regulatory traction with lower strain registration burdens than probiotic entry into poultry or swine.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated multinationals with regulatory infrastructure and captive supply chains over standalone fermentation specialists. Long-term viability across the five-to-ten year window hinges on EFSA dossier preparation capabilities and multi-jurisdictional compliance infrastructure. Acquisition targets should demonstrate established toxicological study partnerships with Wageningen University or equivalent academic collaborators. The signal to watch is F-Gas Regulation phase-down acceleration forcing fermentation plant retrofit investments that strain mid-tier balance sheets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Precursors | Evonik's methyl mercaptan control insulates methionine margins from Gulf Coast cracker volatility. |
| Single-Use Bioreactor Scale-Up | Thirty-thousand-liter Chinese vessels compress capital recovery periods versus legacy stainless installations. |
| EFSA Dossier Preparation Partnership | Wageningen University collaborations accelerate novel additive toxicological package execution timelines. |
| Direct Formulation Partnerships | Outcome-based contracts with Brazilian integrators displace traditional distributor intermediary roles. |
| Heat Recovery System Retrofit | F-Gas Regulation compliance preserves fermentation margin structure in European vitamin synthesis plants. |
Methodological Framework
Cross-validation between primary interviews with plant managers at fermentation facilities and secondary validation through EFSA additive approval databases anchors the qualitative findings. Technical R&D directors at enzyme developers, procurement leads at integrated livestock operators, distribution channel partners in Brazilian feed mill networks, and regulatory affairs specialists managing REACH compliance contributed structured input. Bottom-up triangulation against customs and trade data, SEC filings from diversified chemical conglomerates, and GB standard compliance records from China's Ministry of Agriculture completed the data architecture.
Sensitivity analysis around propylene price volatility, strain registration timeline extensions, and pelleting temperature degradation thresholds stress-tests the projection framework. Segmentation dimensions modeled include product type chemistry, livestock application system, delivery form specification, and end-user procurement concentration across the analysis window. CAGRs derive from production capacity expansion announcements, regulatory approval pipeline velocity, and feed conversion ratio documentation trends in integrated operations. Industry-specific inputs incorporate phytase efficacy trial data and methane inhibitor carbon credit monetization pilots.
Material uncertainties — SAMR approval track delays, REACH sunset date acceleration, and Gulf Coast petrochemical supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions around continued antibiotic-free mandate enforcement and single-use bioreactor technology diffusion. Recalibration cycles align with material shifts in EFSA novel additive approval velocity and voluntary carbon credit framework adoption in livestock sectors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Egg Phosphatidylcholine Market
Ingredients
Asia-Pacific Dairy Ingredients Market
Ingredients
Asia-Pacific Plant Protein Ingredients Market
Ingredients
Camelina Oil Market
Ingredients
Middle East and Africa Dairy Protein Ingredients Market
Ingredients
Insect-Based Ingredients Market
Ingredients
Freeze-Dried Pea Isolates Market
Ingredients
Global Fruits and Vegetables Ingredients Market
Ingredients
Africa Fats and Oil Market
Ingredients
Casein Hydrolysate Market
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
Hydrolyzed Vegetable Protein Market
Ingredients
US Choline Bitartrate Market
Ingredients
Fucoidan Extract Market
Ingredients
Cooking Oil Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market