
 Brake Hoses Market | 2026-2036
Brake Hoses Market Size, Share, and Industry Trends Forecast 2026-2036
Brake Hoses Market Outlook
Asset-light leasing models for hydraulic assembly equipment is fragmenting the competitive landscape for tier-two brake hose manufacturers. Continental AG leverages captive polymer compounding to sustain margin control across European OEM supply agreements. Gates Corporation anchors its position through backward integration into synthetic rubber formulation for high-pressure applications. Nichirin Co. Ltd. specializes in multi-layer braided architectures that dominate motorcycle brake line specifications across Asian export markets.
Brake hoses are flexible reinforced conduits engineered to transmit hydraulic fluid under operating pressures typically ranging from 1450 to 2900 psi, constructed from elastomeric inner tubes, braided fiber or steel reinforcement layers, and abrasion-resistant outer covers designed to maintain volumetric expansion stability across temperature extremes from minus forty to one hundred fifty degrees Celsius. Rubber hoses retain the largest installed base in passenger car assemblies though PTFE hoses are displacing legacy materials in performance motorcycle and racing applications where reduced volumetric expansion improves pedal feel precision. Aftermarket channels carry elevated inventory velocity for commercial vehicle brake hose replacements driven by mandatory periodic inspection intervals, while OEM supply contracts concentrate volume around metallic hose variants for heavy machinery where crush resistance and UV degradation tolerance outweigh cost sensitivity.
DOT FMVSS 106 governs hydraulic brake hose construction and performance testing for US highway vehicles, while ECE R90 harmonizes type-approval requirements across European member states and ISO 3996 establishes international baseline specifications for rubber brake hoses. Regulatory tightening on brake fluid compatibility and impulse fatigue cycling is elevating qualification costs and compressing the supplier base to manufacturers with in-house validation laboratories. Stakeholders must monitor evolving UN ECE proposals for expanded brake system cyber-physical integration standards that could redefine hose-electronic interface requirements in connected vehicle architectures.
Market Dynamics
DOT FMVSS 106 enforcement intensity is compressing replacement cycles for commercial vehicle brake hose assemblies, forcing fleet operators to accelerate maintenance spend and reshaping aftermarket inventory velocity across North American distribution channels.
Growth Catalysts
- FMVSS 106 Compliance Mandates:US Department of Transportation inspection protocols are shortening replacement intervals for heavy-duty truck brake lines, creating sustained aftermarket pull through authorized service networks.
- Hydraulic Assembly Upgrades:German OEM specification revisions for passenger vehicle brake systems are elevating multi-layer braided hose adoption in original equipment manufacturing.
- Performance Motorcycle Demand:PTFE-lined brake hose architectures are penetrating racing and premium two-wheeler segments where volumetric expansion control commands specification priority.
Market Restraints
- Synthetic Rubber Price Volatility:EPDM and chloroprene feedstock cost fluctuations are compressing margin stability for compound-dependent manufacturers without captive polymer production.
- Validation Laboratory Concentration:In-house impulse fatigue and brake fluid compatibility testing capabilities concentrate among integrated Tier-1 suppliers, elevating qualification barriers for independent producers.
- Metallic Hose Substitution:Stainless steel brake line assemblies are displacing rubber variants in heavy machinery applications where crush resistance and UV degradation tolerance outweigh installed cost sensitivity.
Strategic Opportunities
- Asset-Light Equipment Leasing:Hydraulic assembly machinery rental models are lowering capital barriers for Tier-2 manufacturers seeking OEM qualification without fixed asset commitment.
- Connected Vehicle Interface Standards:UN ECE proposals for brake system cyber-physical integration are creating specification white space for hose-electronic sensor convergence in advanced driver assistance architectures.
- Indian Two-Wheeler Export Growth:Motorcycle brake line demand from Southeast Asian and African markets is expanding specification opportunities for multi-layer braided architectures.
Industry Challenges
- ISO 3996 Certification Timelines:International rubber brake hose standard validation protocols are extending product launch cycles, compressing first-mover advantage windows for new material formulations.
- Legacy Fleet Maintenance Backlogs:Commercial vehicle operators with deferred hose replacement histories are overwhelming authorized service capacity, creating quality control risks in rushed aftermarket installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brake Hoses Market |
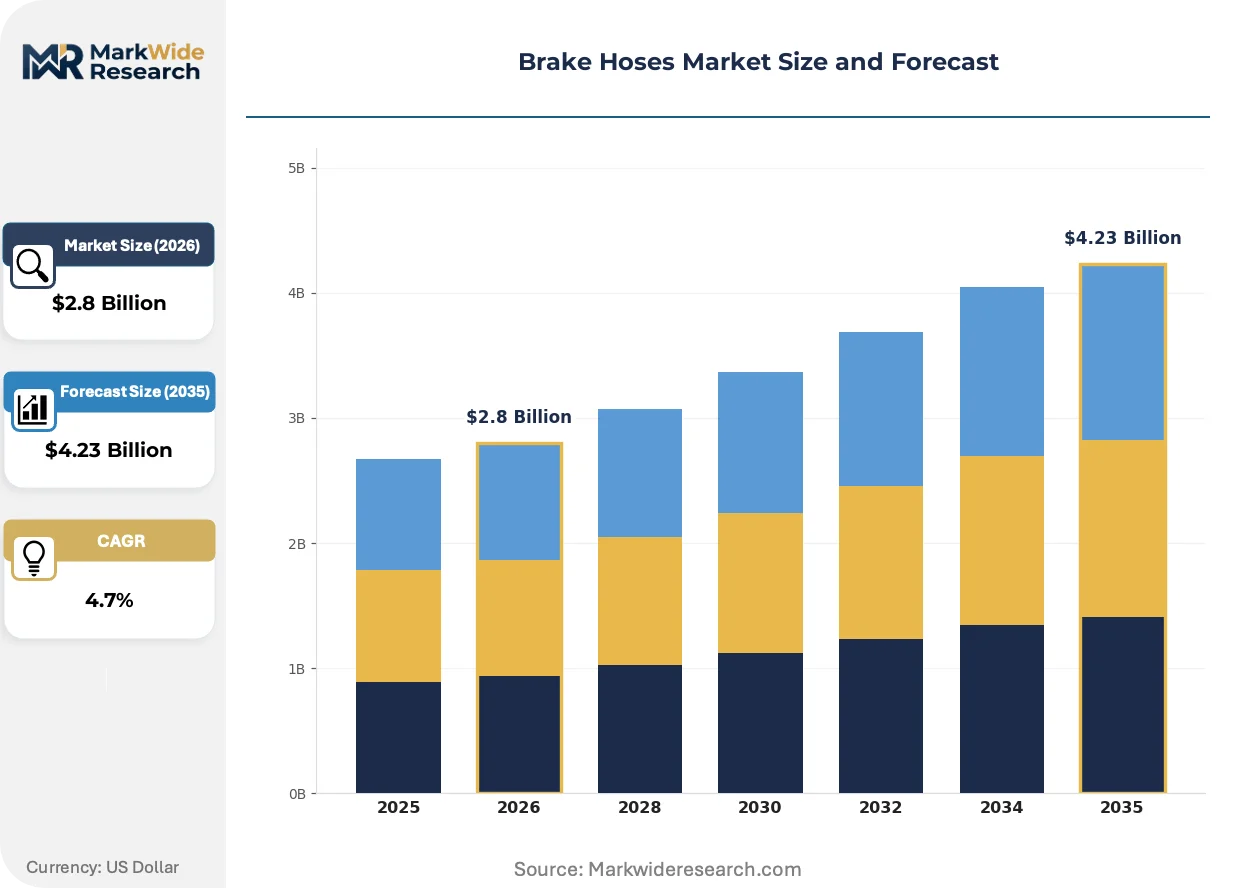
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Hoses, Metallic Hoses, PTFE Hoses, Silicone Hoses End User: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy Machinery Sales Channel: OEMs, Aftermarket, Retail, Online Platforms Installation Type: Fixed Installation, Removable Installation, Standard Fit, Custom Fit |
| Companies Covered | Sumitomo Riko Company Limited, Hutchinson S.A., Continental AG, Hitachi Metals Ltd., Dayco IP Holdings LLC, Gates Corporation, Trelleborg AB, Nichirin Co. Ltd., Parker-Hannifin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brake Hoses Market Strategic Shifts
Material science advances and regulatory test protocol evolution are converging to redefine brake hose performance benchmarks, with specification migration toward lower-expansion architectures and integrated sensing capabilities.
PTFE-lined brake hose construction is migrating from niche racing applications toward broader performance motorcycle and premium passenger vehicle segments. The fluoropolymer inner tube delivers superior volumetric stability under thermal cycling compared to conventional elastomeric constructions. OEM engineering teams in Germany and Japan are specifying PTFE architectures for brake-by-wire systems where pedal feel precision is migrating from driver preference to safety-critical system requirement.
REACH chemical substance restrictions are compelling reformulation of brake hose outer cover compounds across European supply chains. ECHA candidate list substances including certain phthalate plasticizers and short-chain chlorinated paraffins face authorization sunset dates, forcing compounders to validate replacement chemistries without compromising abrasion resistance or ozone degradation tolerance. German KBA type-approval timelines are extending as manufacturers submit revised material safety data sheets for ECE R90 homologation.
Fleet maintenance procurement is consolidating around authorized dealer networks with integrated diagnostic and hose replacement capabilities. Independent repair shops are losing share in commercial vehicle brake service as telematics-enabled predictive maintenance platforms route work to OEM-captive facilities. This channel compression is most visible in US long-haul trucking corridors where DOT inspection compliance documentation requirements favor integrated service providers with direct FMVSS 106 test record access.
Brake Hoses Market Segmentation
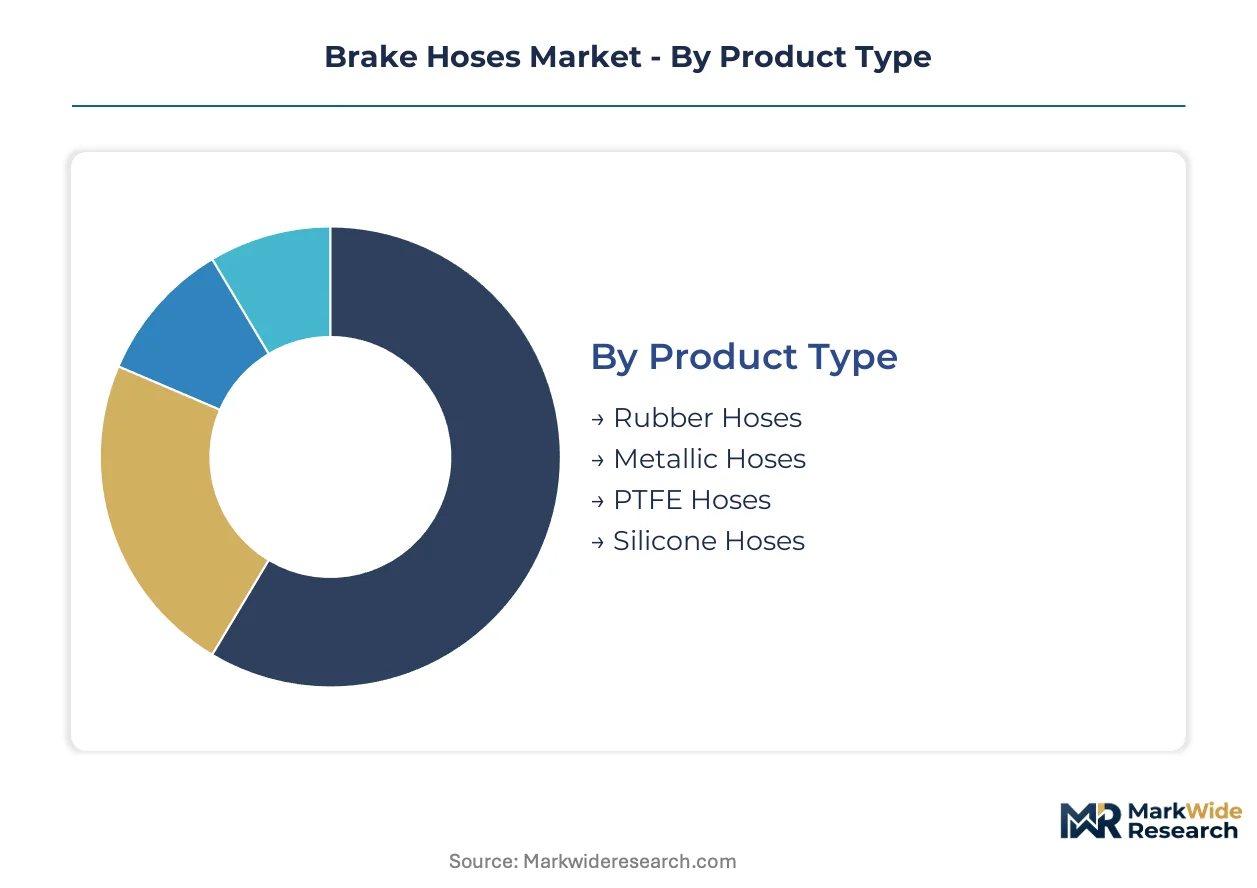
Brake hose segmentation reveals distinct performance requirements across material architectures and regulatory environments. Specification divergence between OEM supply contracts and aftermarket replacement cycles creates tiered margin structures that reward compound expertise and validation capabilities.
Product Type:
Cost tier differentiation separates legacy elastomer constructions from fluoropolymer and metallic alternatives serving premium specifications.
- Rubber Hoses:Multi-layer elastomer constructions with braided fiber or steel reinforcement dominate passenger car assemblies. Demand concentrates in Germany where OEM specification upgrades for hydraulic brake lines are accelerating amid ECE R90 harmonization.
- Metallic Hoses:Stainless steel assemblies deliver crush resistance and UV degradation tolerance for heavy machinery applications. Demand concentrates in North American mining and construction equipment where DOT FMVSS 106 compliance documentation favors integrated service providers.
- PTFE Hoses:Fluoropolymer inner tubes reduce volumetric expansion for brake-by-wire precision in performance motorcycles.
- Silicone Hoses:High-temperature stability serves auxiliary fluid transfer in racing and modified vehicle segments.
Rubber hoses hold installed capacity. PTFE hoses are rotating up the share rankings.
End User:
Application severity divides specification requirements between consumer mobility and industrial duty cycles.
- Commercial Vehicles:Heavy-duty truck brake lines face compressed replacement intervals under intensified US DOT inspection protocols. Fleet telematics-enabled predictive maintenance is routing work toward OEM-captive service networks with direct FMVSS 106 test record access.
- Passenger Cars:Hydraulic assembly specifications are elevating multi-layer braided hose adoption in German OEM manufacturing. ECE R90 type-approval timelines are extending as manufacturers submit revised material safety data sheets.
- Motorcycles:Multi-layer braided architectures dominate Asian export markets for two-wheeler brake line specifications.
- Heavy Machinery:Metallic hose variants concentrate where crush resistance and UV degradation tolerance outweigh installed cost sensitivity.
Commercial vehicles hold installed capacity. Motorcycles are rotating up the share rankings.
Sales Channel:
Customer type determines qualification barriers and margin capture across captive supply agreements versus fragmented distribution.
- OEMs:Long-term supply contracts concentrate volume around validated compound formulations with in-house impulse fatigue testing capabilities. German KBA homologation requirements favor manufacturers with captive polymer compounding operations.
- Aftermarket:Commercial vehicle brake hose replacements carry elevated inventory velocity driven by mandatory periodic inspection intervals. Fleet maintenance procurement is consolidating around authorized dealer networks with integrated diagnostic capabilities.
- Retail:Consumer-facing channels serve DIY replacement demand for passenger car applications.
- Online Platforms:Digital procurement is penetrating independent repair shop sourcing for standard fit specifications.
OEMs hold installed capacity. Aftermarket is rotating up the share rankings.
Installation Type:
Volume characteristics separate standardized high-run production from engineered-to-order configurations.
- Fixed Installation:Permanent mounting configurations dominate heavy machinery and commercial vehicle assemblies where service access is planned around maintenance intervals.
- Removable Installation:Quick-connect architectures facilitate fleet maintenance efficiency in authorized service networks.
- Standard Fit:Catalog-specified dimensions serve high-volume aftermarket replacement cycles across passenger car and motorcycle segments.
- Custom Fit:Engineered-to-order hydraulic assemblies address specialized racing and modified vehicle requirements.
Fixed installation holds installed capacity. Removable installation is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEM specification upgrades command premium pricing leverage over North American aftermarket replacement cycles, creating a transatlantic margin asymmetry that rewards compound expertise in European supply contracts while compressing returns in US fleet service networks.
United States
Commercial vehicle fleet expansion and intensified NHTSA enforcement of DOT FMVSS 106 protocols are accelerating brake hose replacement schedules. The Department of Transportation inspection documentation requirements favor integrated service providers with direct test record access. Detroit-Windsor automotive corridor facilities concentrate hydraulic assembly capacity for heavy-duty truck applications.
Germany
OEM specification revisions for passenger vehicle brake systems are elevating multi-layer braided hose adoption in original equipment manufacturing. KBA type-approval timelines extend as manufacturers submit revised material safety data sheets for ECE R90 homologation. Stuttgart engineering clusters drive hydraulic line architecture decisions for premium vehicle platforms.
China
Domestic commercial vehicle production scales and MIIT safety standard harmonization are expanding brake hose demand across heavy-truck and bus segments. GB standards alignment with international specifications elevates qualification requirements for export-oriented manufacturers. Yangtze River Delta industrial zones concentrate synthetic rubber compounding capacity for automotive supply chains.
Japan
Performance motorcycle brake line specifications and METI industrial standards are sustaining demand for multi-layer braided architectures in two-wheeler export markets. JIS certification protocols maintain quality benchmarks for Asian OEM supply relationships. Nagoya manufacturing clusters anchor precision braiding equipment capabilities for regional tier-one suppliers.
India
Two-wheeler export growth to Southeast Asian and African markets is expanding specification opportunities for multi-layer braided brake line architectures. BIS automotive component standards are tightening material compliance requirements for domestic and export-bound production. Tamil Nadu automotive corridors concentrate hose assembly operations for motorcycle OEM supply contracts.
Brake Hoses Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in a tiered supply structure where captive polymer compounding and in-house validation capabilities separate premium OEM suppliers from aftermarket-dependent competitors. The market consolidates around integrated Tier-1 manufacturers with backward control over elastomer formulation and impulse fatigue testing infrastructure. Three archetypes dominate: captive compounders with KBA homologation expertise, asset-light assemblers leveraging leased hydraulic equipment, and PTFE specialists serving performance motorcycle niches. Competitive positioning hardens through M&A capture of validation laboratory assets and strategic partnerships around REACH-compliant compound reformulation.
Within the captive compounder tier, Continental AG and Gates Corporation exemplify manufacturers sustaining margin control through in-house polymer operations, while Nichirin Co. Ltd. occupies a specialized position in multi-layer braided architectures for two-wheeler specifications. Sumitomo Riko Company Limited represents Japanese engineering integration across rubber and metal composite constructions. These companies anchor distinct competitive vectors: European OEM supply agreements, North American heavy-duty aftermarket channels, and Asian export motorcycle markets respectively.
| Leading Market Players |
|---|
| Sumitomo Riko Company Limited |
| Hutchinson S.A. |
| Continental AG |
| Hitachi Metals Ltd. |
| Dayco IP Holdings LLC |
| Gates Corporation |
| Trelleborg AB |
| Nichirin Co. Ltd. |
| Parker-Hannifin Corporation |
| Others |
Value Chain & Pricing Dynamics
EPDM and chloroprene feedstock price volatility determines both margin compression in standard rubber hose tiers and the geographic reconfiguration of compounding capacity toward captive polymer operations in Germany and China.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across European supply agreements. Three-tier pricing separates KBA-homologated premium formulations from standard ECE R90 grades and economy aftermarket specifications. Cost compression in standard rubber tiers intensifies because synthetic rubber price volatility erodes compounder margins. Fleet operators in North American aftermarket channels exhibit highest price sensitivity, while German OEM procurement teams prioritize qualification reliability over unit cost.
Supply Chain Analysis
Export-control restrictions on fluoropolymer precursor chemicals limit PTFE liner flows from Chinese manufacturers to European hose assemblers. Raw material sourcing draws from German synthetic rubber compounding clusters, Japanese precision braiding equipment suppliers, and Chinese EPDM feedstock producers. Single-source vulnerability concentrates in validated compound formulations held by Tier-1 integrated manufacturers. Distribution runs through OEM-captive service networks for commercial vehicle fleets and authorized dealer channels for passenger car aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat defensive story where DOT FMVSS 106 and ECE R90 homologation requirements create switching costs that entrench qualified suppliers.
For Market Incumbents: Insulate qualification advantages by deepening backward integration into captive polymer compounding and expanding in-house impulse fatigue testing capacity. Metallic hose substitution in heavy machinery applications threatens rubber variant margins, making certification investment in stainless steel architectures a critical defensive lever. For New Entrants and Emerging Players: Asset-light hydraulic assembly equipment leasing models in Southeast Asian motorcycle export corridors represent the most penetrable entry point. Indian two-wheeler OEM supply contracts offer specification white space for multi-layer braided architectures. A go-to-market angle through regional tier-two distributor partnerships bypasses direct OEM qualification barriers. For Investors and Strategic Acquirers: REACH chemical substance restriction deadlines reshape the acquisition landscape toward compounders with validated replacement chemistry pipelines. Long-term viability centers on manufacturers with demonstrated ECHA compliance pathways. The signal to watch is KBA type-approval timeline extensions that favor incumbent laboratory infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Polymer Compounding Expansion | Continental AG and Gates Corporation sustain margin control through in-house EPDM formulation. |
| PTFE Architecture Qualification | Nichirin Co. Ltd. dominates motorcycle brake-by-wire specifications across Asian export markets. |
| REACH-Compliant Compound Reformulation | ECHA candidate list substances force validation of phthalate-free outer cover chemistries. |
| Validation Laboratory Acquisition | Integrated Tier-1 suppliers concentrate ISO 3996 impulse fatigue testing capabilities. |
| Fleet Telematics Integration | OEM-captive service networks capture commercial vehicle brake hose replacement demand. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement leads, aftermarket service network managers, and regulatory affairs specialists at KBA and NHTSA, then refined against customs trade data, vehicle production databases, SEC filings from listed automotive suppliers, and ECHA substance restriction notifications. Bottom-up segment sizing triangulated with top-down market validation.
Demand-supply balance modeling across material architecture, end-use severity, and sales channel dimensions structured volume projections over the analysis window. CAGRs derived from segment-level growth rate reconciliation with macro automotive production forecasts. Industry-specific inputs included DOT FMVSS 106 enforcement intensity indices and ECE R90 homologation pipeline tracking.
Practitioners should monitor synthetic rubber feedstock price movements and REACH authorization sunset dates for early signals of margin compression or compound reformulation requirements. Material shifts in UN ECE cyber-physical integration standards or stainless steel substitution rates in heavy machinery would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Boat Trailers Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
Crash Lock Box Market
Vehicle Components
Rail Wheel Market
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
Industrial Gearbox Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Heavy Vehicles Suspension Anti-Vibration Components Market
Vehicle Components
Motorcycle Monoshock Suspension Market
Vehicle Components
Wheel Speed Sensor Market
Vehicle Components
Rail Wheel and Axle Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
Mechanical Control Cables Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Freight Railcar Parts Market
Vehicle Components
Bus and Coach Suspension Bearing Components Market