
 Motorcycle Monoshock Suspension Market | 2026-2036
Motorcycle Monoshock Suspension Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Monoshock Suspension Market Analytics
Aftermarket tuning and refurbishment revenue is reshaping profit distribution across the value chain. SHOWA CORPORATION leverages its captive OEM relationships with Honda and Kawasaki to sustain high-volume production of electronically controlled dampers. Öhlins Racing dominates the premium racing and track-day segment, where its TTX technology anchors pricing power. KYB Corporation competes aggressively in the mid-tier street motorcycle category through cost-optimized cartridge designs.
A motorcycle monoshock suspension is a single rear damper-and-spring unit, typically featuring a gas-charged twin-tube or mono-tube architecture with piston diameters between 40 mm and 50 mm, that manages rear wheel kinematics while reducing unsprung mass compared to twin-shock layouts. The assembly integrates a coil spring or air spring with a hydraulic damper valved for rebound and compression control, serving the primary purpose of maintaining tire contact patch stability across uneven surfaces. By application, the racing segment commands the highest unit margins due to bespoke valving and telemetry integration, while the off-road category records the fastest volume growth as enduro and hard-adventure motorcycles gain share. By vehicle type, sportbike applications remain mature with replacement-cycle demand, whereas adventure motorcycles concentrate emerging OEM specification upgrades.
The US NHTSA and the EPA regulate motorcycle emissions and safety equipment, indirectly mandating weight-reduction strategies that favor monoshock architectures over heavier twin-shock alternatives. In Europe, the EU Green Deal and REACH compliance frameworks constrain hydraulic fluid chemistry and material sourcing, compelling suppliers to reformulate seal compounds and piston coatings. India's BIS certification and the Automotive Research Association of India set durability benchmarks for shock absorbers that OEMs must meet for type approval. Stakeholders should monitor the divergence between electronic suspension adoption timelines in developed markets versus mechanical upgrade cycles in emerging economies.
Market Dynamics
The motorcycle monoshock suspension market pivots on the collision between Euro 5-driven unsprung mass reduction mandates and the divergent adoption timelines for electronic adjustability across developed versus emerging economies. Manufacturers must reconcile premium electronic specification in Europe and North America with cost-constrained mechanical architectures dominating South Asian and Latin American production.
Growth Catalysts
- REACH-compliant hydraulic fluids:European chemical regulations are accelerating seal compound reformulation, creating first-mover advantages for suppliers with validated low-friction piston coatings.
- Enduro motorcycle specification:Hard-adventure and enduro segments are pulling longer-travel monoshock designs into OEM standard fitment, expanding addressable unit volumes beyond traditional sportbike replacement cycles.
- India:Commuter-to-performance upgrades and premium two-wheeler export growth are simultaneously driving aftermarket refurbishment and factory-installed electronic suspension volumes.
Market Restraints
- Steel and aluminum price volatility:Coil spring and damper body input costs fluctuate with commodity markets, compressing margin stability for mid-tier cartridge producers.
- Japanese damper supply concentration:SHOWA and KYB collectively control captive OEM relationships with major Japanese motorcycle manufacturers, limiting market access for independent European suppliers.
- Gas-charged twin-tube displacement:Mono-tube architectures with larger piston diameters are displacing legacy twin-tube designs, stranding tooling investments at smaller regional manufacturers.
Strategic Opportunities
- Brazilian hard-adventure segment:Underpenetrated electronic suspension fitment in Latin America's largest motorcycle market creates white space for cost-optimized semi-active damper introductions.
- Telemetry-integrated racing dampers:Convergence of CAN-bus motorcycle electronics with cloud-based suspension tuning apps is opening subscription revenue streams alongside hardware sales.
- India's PLI scheme for auto components:Production-linked incentives for advanced automotive parts are drawing foreign damper manufacturers to establish localized assembly, reducing import duty exposure.
Industry Challenges
- Electronic suspension calibration engineering:Scarce talent pools for mechatronics integration and ride-algorithm development are constraining product launch timelines at second-tier suppliers.
- BIS type-approval duration:India's durability testing protocols for shock absorbers extend certification cycles, delaying market entry for new entrants despite manufacturing readiness.
- Legacy twin-shock replacement compatibility:Retrofit monoshock conversions for vintage motorcycle platforms require custom linkage fabrication, fragmenting aftermarket service standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Monoshock Suspension Market |
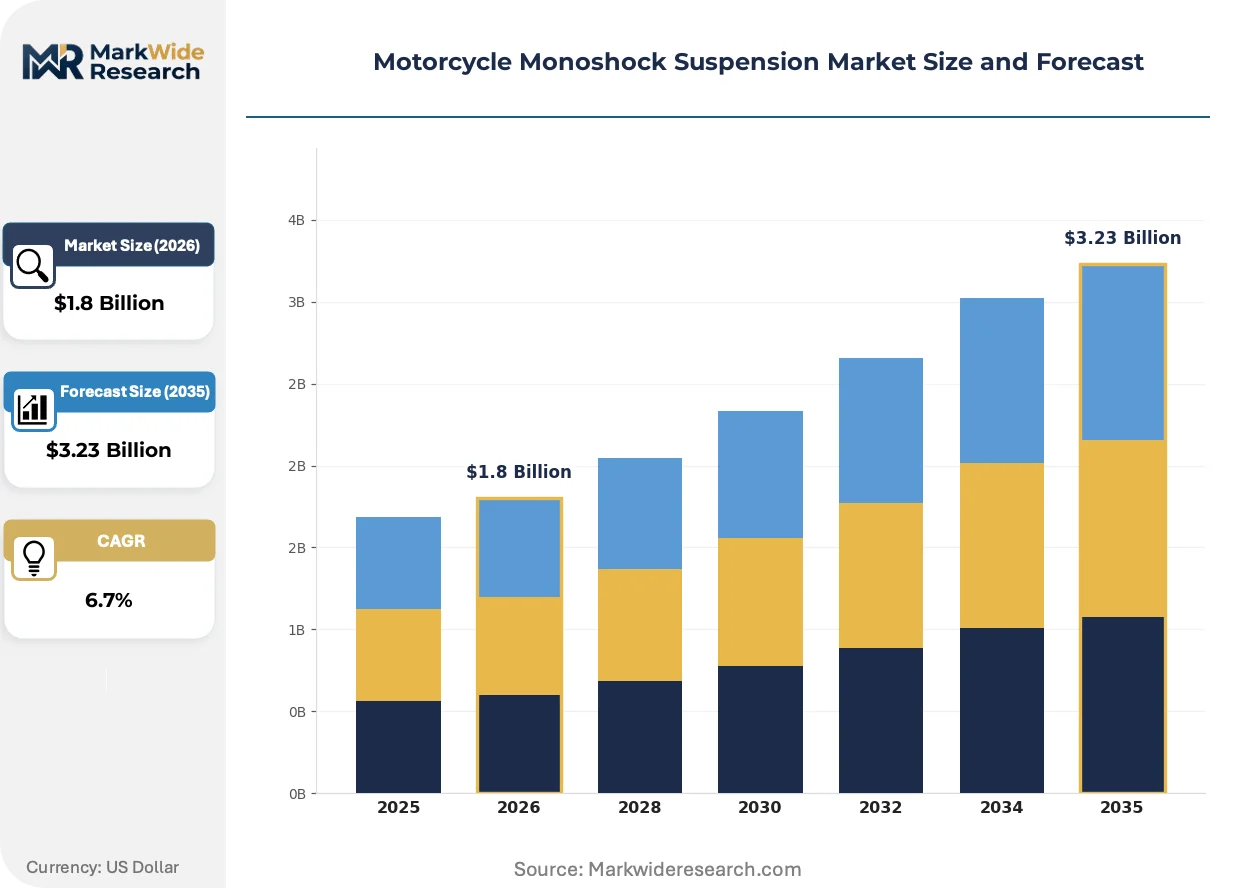
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Spring, Damper, Assembly, Kit Application: Street, Off-Road, Racing, Touring Vehicle Type: Sportbike, Cruiser, Dirt Bike, Adventure Motorcycle End User: OEM, Aftermarket, Custom Builders, Enthusiasts |
| Companies Covered | SHOWA CORPORATION, Öhlins Racing, Duroshox, KYB Corporation, Endurance Technologies Limited, Nitron Racing Shocks, Chongqing Chuandong Shock Absorber Manufacturing Co., Ltd., TFX Suspension Technology, Marzocchi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Monoshock Suspension Market Evolving Landscape
Active suspension technology is hybridizing with connected vehicle architectures, compressing the traditional boundary between mechanical damper production and software-enabled ride control. This convergence is redrawing supplier capability requirements and procurement criteria across motorcycle categories.
Semi-active damper valving is hybridizing magnetorheological fluid control with conventional hydraulic architectures to enable real-time compression and rebound adjustment without mechanical linkage complexity. Adventure motorcycle OEMs in Germany and Italy are adopting these systems as standard fitment on flagship models. The technology is hybridizing supplier value chains, forcing traditional damper manufacturers to acquire embedded software competencies or cede specification control to tier-one electronics integrators.
The EU Green Deal's material sourcing constraints are compelling reformulation of hydraulic seal elastomers and piston surface treatments to eliminate restricted phthalate plasticizers and perfluorinated compounds. Suppliers serving European OEMs must now dual-qualify REACH-compliant and legacy formulations, bifurcating production lines. Racing and track-day segments are absorbing the highest compliance costs, passing through price premiums that standard street motorcycle categories cannot sustain.
Aftermarket refurbishment is displacing new-unit replacement in mature motorcycle markets as independent workshops build specialized monoshock rebuilding capabilities. Germany's KBA-registered tuning specialists and California's race-focused suspension labs are capturing service revenue that OEM parts channels previously monopolized. This pattern concentrates in regions with high vintage motorcycle registration density and established track-day cultures, compressing new-damper sales velocity in North America and Western Europe.
Motorcycle Monoshock Suspension Market Segmentation
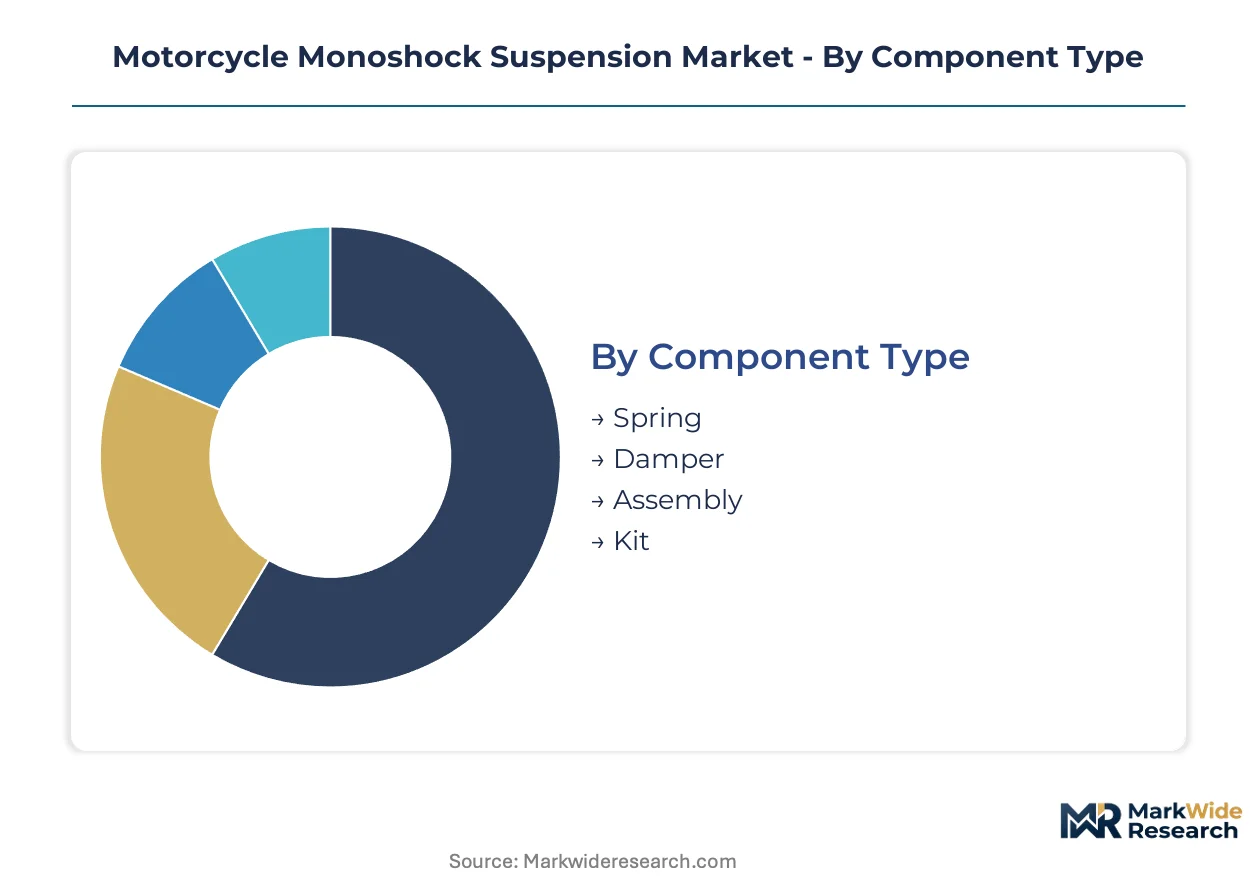
Monoshock suspension procurement patterns diverge sharply across component hierarchies and end-user channels. Component-level sourcing decisions, application-specific durability requirements, and vehicle-platform engineering specifications each create distinct margin structures and supplier qualification barriers.
Component Type:
Cost tier stratification determines supplier positioning across the four component categories, with assembly and kit suppliers capturing integrated value while spring and damper specialists compete on unit economics.
- Spring:Coil springs in chrome-silicon or titanium alloys dominate high-performance applications, with wire diameter and active coil count calibrated to rider weight and travel requirements. Demand concentrates in India's aftermarket refurbishment sector, where commuter-to-performance upgrades drive replacement cycles.
- Damper:Hydraulic dampers with twin-tube or mono-tube architectures incorporate piston valving for rebound and compression control, with gas-charged designs commanding premium positioning. European OEMs specify REACH-compliant seal compounds and low-friction piston coatings under EU Green Deal material constraints.
- Assembly:Pre-configured spring-damper units reduce installation complexity for OEM fitment and high-volume aftermarket channels.
- Kit:Complete linkage-inclusive packages serve custom builders and racing teams requiring geometry optimization.
Assembly commands the established base. The steepest expansion runs through damper.
Application:
Application-specific duty cycles create divergent engineering priorities across street, off-road, racing, and touring use cases, with thermal management and contamination resistance driving specification splits.
- Street:Urban and highway motorcycles prioritize ride comfort and longevity over extreme performance, with sealed cartridge designs reducing maintenance intervals. Volume concentrates in India's commuter and premium export segments, where BIS durability certification shapes supplier selection.
- Off-Road:Enduro and motocross applications demand extended travel lengths, progressive spring rates, and robust dust sealing against abrasive environments. Hard-adventure motorcycle OEMs in Germany and Italy are pulling longer-travel designs into standard fitment.
- Racing:Track-day and competition motorcycles integrate telemetry-ready dampers with remote reservoir architectures for thermal stability under sustained high-load conditions.
- Touring:Long-distance motorcycles emphasize load-leveling capabilities and electronic adjustability for varying passenger and luggage configurations.
Street retains the volume anchor. Off-road is climbing the fastest.
Vehicle Type:
Platform engineering requirements across sportbike, cruiser, dirt bike, and adventure motorcycle categories determine linkage geometry, travel envelope, and unsprung mass targets.
- Sportbike:Clip-on handlebar ergonomics and steep steering head angles demand compact, high-rate dampers with minimal travel. Replacement-cycle demand dominates mature markets as vintage sportbike refurbishment extends serviceable fleet age.
- Cruiser:Low-slung chassis architectures with limited suspension travel prioritize plush initial stroke compliance over sport-oriented damping control.
- Dirt Bike:Lightweight frames and long-travel linkages require robust damping force across extended piston strokes, with air spring alternatives gaining share in competitive enduro segments.
- Adventure Motorcycle:Dual-sport capability requirements drive specification complexity, with semi-active electronic adjustability becoming standard on flagship models from German and Italian OEMs. Euro 5 emission standards have accelerated unsprung mass reduction priorities that favor advanced monoshock architectures.
Sportbike holds the replacement revenue base. Adventure motorcycle is gaining share fastest.
End User:
Customer type determines procurement channel structure, with OEM relationships requiring type-approval compliance and aftermarket channels emphasizing inventory breadth and technical support capabilities.
- OEM:Factory fitment contracts demand validated durability testing, just-in-sequence delivery, and electronic integration capabilities for CAN-bus connected dampers. SHOWA CORPORATION and KYB Corporation leverage captive relationships with Japanese manufacturers to secure high-volume supply agreements.
- Aftermarket:Independent distribution channels serve replacement and upgrade demand, with specialized rebuild services capturing service revenue in Germany and California. India's PLI scheme for auto components is drawing foreign manufacturers to localized assembly.
- Custom Builders:Low-volume fabrication shops require linkage fabrication services and geometry consultation for non-standard applications.
- Enthusiasts:DIY installers and track-day participants drive direct-to-consumer sales of performance-tuned dampers and rebuild kits.
OEM secures the volume foundation. Aftermarket is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Brazil exhibit acute price sensitivity, absorbing cost-optimized mechanical dampers while German and Italian OEMs absorb premium electronic suspension with minimal demand elasticity. This bifurcation shapes supplier portfolio allocation across geographies.
United States
Track-day culture and vintage motorcycle refurbishment concentrate demand in California and the Southeast, where independent suspension labs capture service revenue. NHTSA safety equipment regulations indirectly mandate weight-reduction strategies favoring monoshock architectures. The Pacific Northwest hosts specialized rebuild workshops serving enthusiast segments.
Germany
Adventure motorcycle OEMs specify semi-active electronic dampers as standard fitment on flagship models, pulling advanced suspension technology into volume production. EU Green Deal material constraints compel REACH-compliant seal compound reformulation. KBA-registered tuning specialists in Bavaria dominate aftermarket refurbishment channels.
India
Commuter-to-performance upgrades and premium two-wheeler export growth simultaneously drive aftermarket refurbishment and factory-installed electronic suspension volumes. BIS certification and ARAI durability testing protocols extend type-approval timelines for new entrants. Manufacturing clusters in Maharashtra and Tamil Nadu draw foreign damper producers under the PLI scheme for auto components.
Italy
Hard-adventure motorcycle specification upgrades accelerate OEM demand for longer-travel monoshock designs with electronic adjustability. REACH compliance frameworks constrain hydraulic fluid chemistry, compelling dual-qualification of seal formulations. Industrial concentration in the Emilia-Romagna region anchors racing and track-day damper development.
Brazil
Underpenetrated electronic suspension fitment in Latin America's largest motorcycle market creates white space for cost-optimized semi-active damper introductions. ANVISA regulates automotive component safety standards affecting aftermarket import channels. São Paulo-based distributors serve as gateways for Asian damper manufacturers targeting South American expansion.
Motorcycle Monoshock Suspension Market Competitive Landscape
Capability concentration sits with premium-tier specialists commanding telemetry integration and bespoke valving expertise; scale advantage sits with high-volume producers serving captive OEM relationships. The market structures around three archetypes: electronics-integrated system suppliers, racing-focused premium specialists, and cost-optimized cartridge manufacturers. Consolidation pressures emerge from mono-tube architecture displacement of legacy twin-tube designs. Geographic expansion and technology licensing represent the dominant competitive vectors.
Within the electronics-integrated tier, SHOWA CORPORATION and KYB Corporation represent scale-driven Japanese producers with established OEM supply positions. Öhlins Racing exemplifies the premium racing specialist archetype, anchoring high-margin track-day and competition segments through technology differentiation. These three companies illustrate the capability-scale divergence shaping procurement decisions across motorcycle categories.
| Leading Market Players |
|---|
| SHOWA CORPORATION |
| Öhlins Racing |
| Duroshox |
| KYB Corporation |
| Endurance Technologies Limited |
| Nitron Racing Shocks |
| Chongqing Chuandong Shock Absorber Manufacturing Co., Ltd. |
| TFX Suspension Technology |
| Marzocchi |
| Others |
Value Network & Pricing Analysis
Japanese damper supply concentration in SHOWA and KYB feeds directly into margin capture at the OEM tier, where captive relationships lock in volume premiums and constrain price competition for independent European suppliers.
Pricing Analysis
Aftermarket refurbishment and rebuild services anchor lifetime value in mature markets, with independent workshops in Germany and California capturing service revenue that OEM parts channels previously controlled. Three-tier pricing structure across premium, standard, and economy levels separates telemetry-integrated racing dampers from mid-tier street cartridges and cost-optimized mechanical units. Price differentiation rests on certification grade and electronic integration complexity. Cost compression in mid-tier cartridges is intensifying because steel and aluminum input volatility erodes margin stability. India's commuter segment exhibits acute price sensitivity, while German adventure motorcycle OEMs absorb premium electronic suspension with minimal demand elasticity.
Supply Chain Analysis
Export-control restrictions on magnetorheological fluid formulations and embedded suspension control software limit technology transfer to certain manufacturing jurisdictions. Manufacturing gravity centers on Japan, India, and Germany, with component sourcing drawing from Chinese steel forging, Italian precision machining, and Southeast Asian seal compound production. Raw material dependencies include chrome-silicon spring wire, hydraulic fluid base stocks, and REACH-compliant elastomer formulations. Single-source vulnerability concentrates in electronic damper valve suppliers serving semi-active architectures. Distribution runs through OEM just-in-sequence delivery, aftermarket distributor networks, and direct-to-consumer racing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechatronics engineering talent scarcity constrains product development timelines, creating competitive moats for suppliers with established ride-algorithm development teams and embedded software capabilities.
For Market Incumbents: Pre-empt second-tier supplier encroachment by acquiring telemetry integration startups and securing exclusive semiconductor sourcing for CAN-bus damper controllers. Backward integration into seal compound formulation insulates margin from REACH compliance cost pass-through. Capacity addition in Maharashtra and Tamil Nadu manufacturing clusters defends volume position in India's PLI-subsidized production environment.
For New Entrants and Emerging Players: Brazil's underpenetrated hard-adventure electronic suspension fitment represents the most penetrable entry point for cost-optimized semi-active damper introductions. India's aftermarket refurbishment sector offers white-space opportunity for specialized rebuild service networks targeting commuter-to-performance upgrades. Go-to-market execution should anchor on distributor partnerships with São Paulo-based channels serving South American expansion.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive component platforms seeking suspension technology bolt-ons to complete chassis system offerings. Five-to-ten year viability hinges on software-defined vehicle integration trajectory and electronic suspension adoption curves in emerging economies. Watch for inflection in India's PLI scheme disbursement rates as foreign damper manufacturers commit localized assembly capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Software Acquisition | Captures ride-algorithm capabilities essential for semi-active damper specification control. |
| Seal Compound Backward Integration | Insulates margin from EU Green Deal material constraint cost pass-through. |
| PLI-Aligned India Manufacturing | Reduces import duty exposure in the fastest-growing OEM and aftermarket volume cluster. |
| Telemetry-Integrated Product Launch | Opens subscription revenue streams alongside hardware sales in racing segments. |
| Brazilian Distributor Partnership | Establishes gateway presence in Latin America's largest underpenetrated electronic suspension market. |
Research Methodology
Initial hypotheses were tested against primary input from damper engineering directors, OEM platform specification leads, aftermarket distributor principals, and racing team technical managers and refined through secondary validation against customs trade data, ARAI type-approval filings, SEC 10-K disclosures from listed suppliers, and vehicle production databases. Bottom-up unit volume estimates triangulated with top-down value projections derived from component bill-of-materials analysis.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning component type, application duty cycle, vehicle platform architecture, and end-user procurement channel. CAGRs were computed from year-over-year growth rate progression applied to base-year validated estimates. Industry-specific forecast inputs included Euro 5 unsprung mass reduction mandates and electronic suspension adoption curve assumptions by regional market maturity.
Macroeconomic conditions sit as an overlay; deviation in steel and aluminum commodity indices, semiconductor availability, or emission regulation enforcement stringency would shift the trajectory. Forecasts reflect documented assumptions about technology adoption timelines and regulatory implementation schedules. Material shifts in REACH compliance scope or India's PLI scheme eligibility criteria would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Car Modification Market
Vehicle Components
2 Wheeler Fuel Tank Market
Vehicle Components
Chassis Leveling Valves Market
Vehicle Components
Gas-Powered Chainsaw Market
Vehicle Components
Railway Brake Pads Market
Vehicle Components
Freight Railcar Parts Market
Vehicle Components
Autonomous Trains Components Market
Vehicle Components
Two-Wheeled Containers Market
Vehicle Components
Steering Tie Rod Market
Vehicle Components
Automotive Steering Shaft Market
Vehicle Components
Intelligent Rubber Tracks Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Wheel Loaders Market
Vehicle Components
Automotive Wheel Speed Sensor Market
Vehicle Components
Steel and Rubber Tracks Market
Vehicle Components
Bicycle Lights Market