
 Heavy Vehicles Suspension Anti-Vibration Components Market | 2026-2036
Heavy Vehicles Suspension Anti-Vibration Components Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Vehicles Suspension Anti-Vibration Components Market Analytics
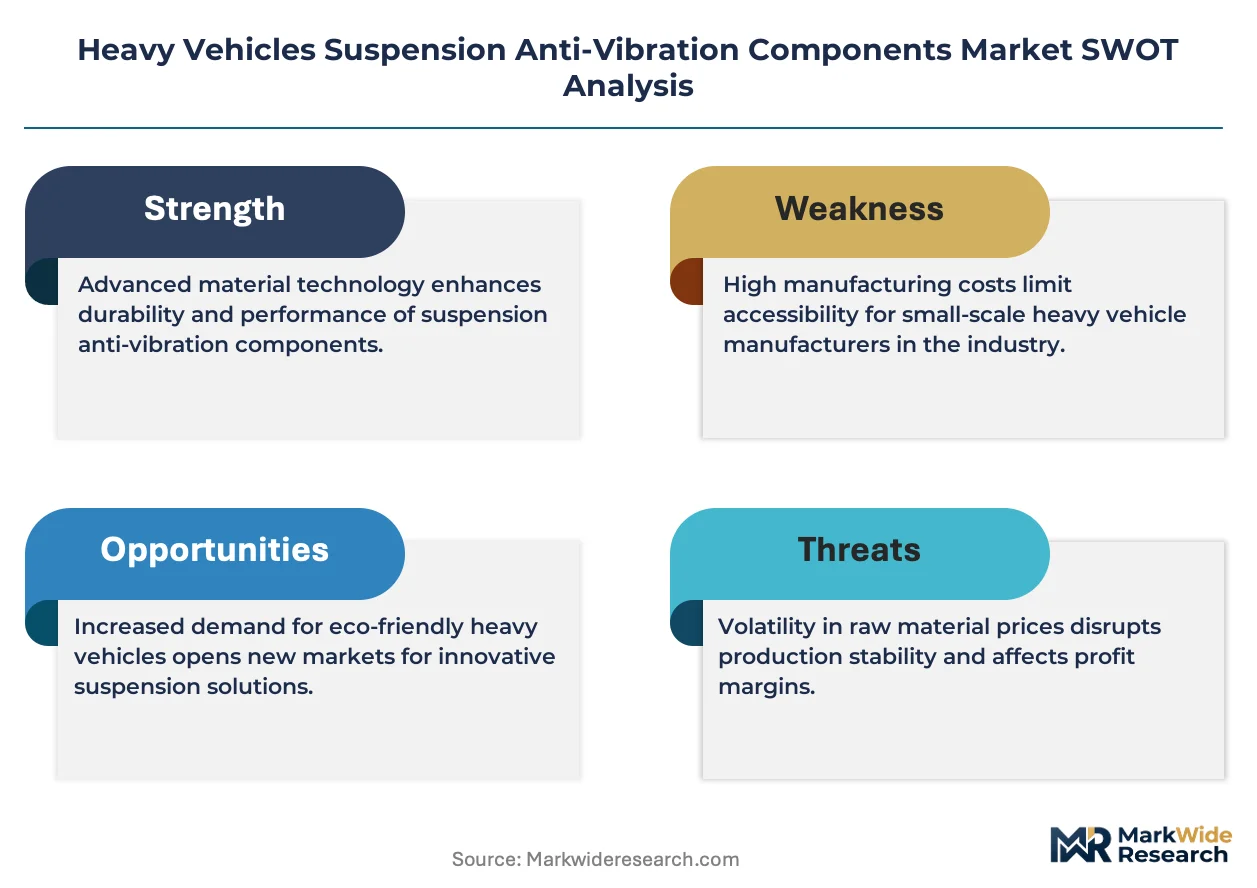
Euro VI compliance is recalibrating the cost-of-entry calculus for suspension component suppliers serving European heavy vehicle OEMs. Continental AG leverages its integrated rubber-to-metal bonding capabilities to anchor premium bushing contracts with German truck manufacturers. ZF Friedrichshafen AG sustains technology leadership in adaptive damping systems through deep R&D investment in mechatronic valve architectures. Tenneco Inc. competes on manufacturing scale, operating multi-continent production footprints that reduce logistics exposure for North American and Asian OEMs.
Heavy vehicles suspension anti-vibration components are engineered subsystems—typically comprising elastomeric bushings, pneumatic air springs, hydraulic dampers, and steel-composite coil springs manufactured through vulcanization, coil winding, and precision forging processes—that isolate chassis from road-induced oscillations to protect payloads, extend frame life, and maintain driver ergonomics across commercial duty cycles. Air springs and adaptive dampers are capturing the fastest growth as fleet operators prioritize cargo integrity and fuel efficiency, while traditional steel coil springs remain the mature volume anchor in emerging-market price-sensitive segments. Rubber and polyurethane material formulations command the widest margin pools where suppliers differentiate through proprietary compound recipes certified to OEM durability benchmarks.
EPA Phase 2 greenhouse gas standards and NHTSA fuel efficiency mandates in the United States, alongside Euro VI emission-efficiency linkages administered by the European Commission, are collectively tightening product standards and accelerating lightweight material substitution in suspension architectures. China's MIIT dual carbon goals and GB standards for commercial vehicle energy consumption are reshaping import certification requirements and local sourcing ratios for foreign suppliers. Stakeholders must monitor how regulatory convergence on durability-testing protocols and recycled-content thresholds will reshape supplier qualification timelines and capital allocation across major production basins.
Market Dynamics
Air spring systems are compressing replacement cycles for traditional steel coil architectures as fleet operators prioritize cargo protection and driver retention metrics over upfront component costs.
Growth Catalysts
- EPA Phase 2 fuel efficiency mandates:NHTSA-aligned greenhouse gas standards in the United States are forcing OEMs toward lighter suspension materials that reduce vehicle mass and improve fleet compliance scores.
- Long-haul freight expansion:E-commerce fulfillment networks are extending average haul distances, amplifying vibration-induced fatigue damage and accelerating wear-part replacement schedules.
- Elastomeric compound advances:Proprietary rubber-to-metal bonding processes are extending bushing service intervals beyond traditional polyurethane formulations in high-duty-cycle applications.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply disruptions and climate-induced harvest variability are compressing margin predictability for vulcanized component manufacturers.
- Steel coil spring overhang:Mature stamping capabilities in emerging-market supplier bases are sustaining price competition that delays air spring penetration in cost-sensitive fleet segments.
- Euro VI certification timelines:Extended durability-testing protocols for emission-linked lightweighting are elongating new product qualification windows for European OEM supply contracts.
Strategic Opportunities
- MIIT dual carbon alignment:China's GB standards for commercial vehicle energy consumption are creating certification pathways for foreign suppliers with verified recycled-content suspension architectures.
- Adaptive damper convergence:Integration of mechatronic valve systems with telematics platforms is opening predictive maintenance revenue streams for component-software bundled offerings.
- Aftermarket channel digitization:Direct-to-fleet e-procurement platforms are disintermediating traditional distributor networks in North American independent operator segments.
Industry Challenges
- Mechatronics talent scarcity:Shortages of control systems engineers with hybrid mechanical-electrical competencies are constraining R&D velocity for smart damping architectures.
- Legacy chassis integration friction:Retrofit compatibility requirements for existing frame rail geometries are limiting design freedom for next-generation air spring mounting configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Vehicles Suspension Anti-Vibration Components Market |
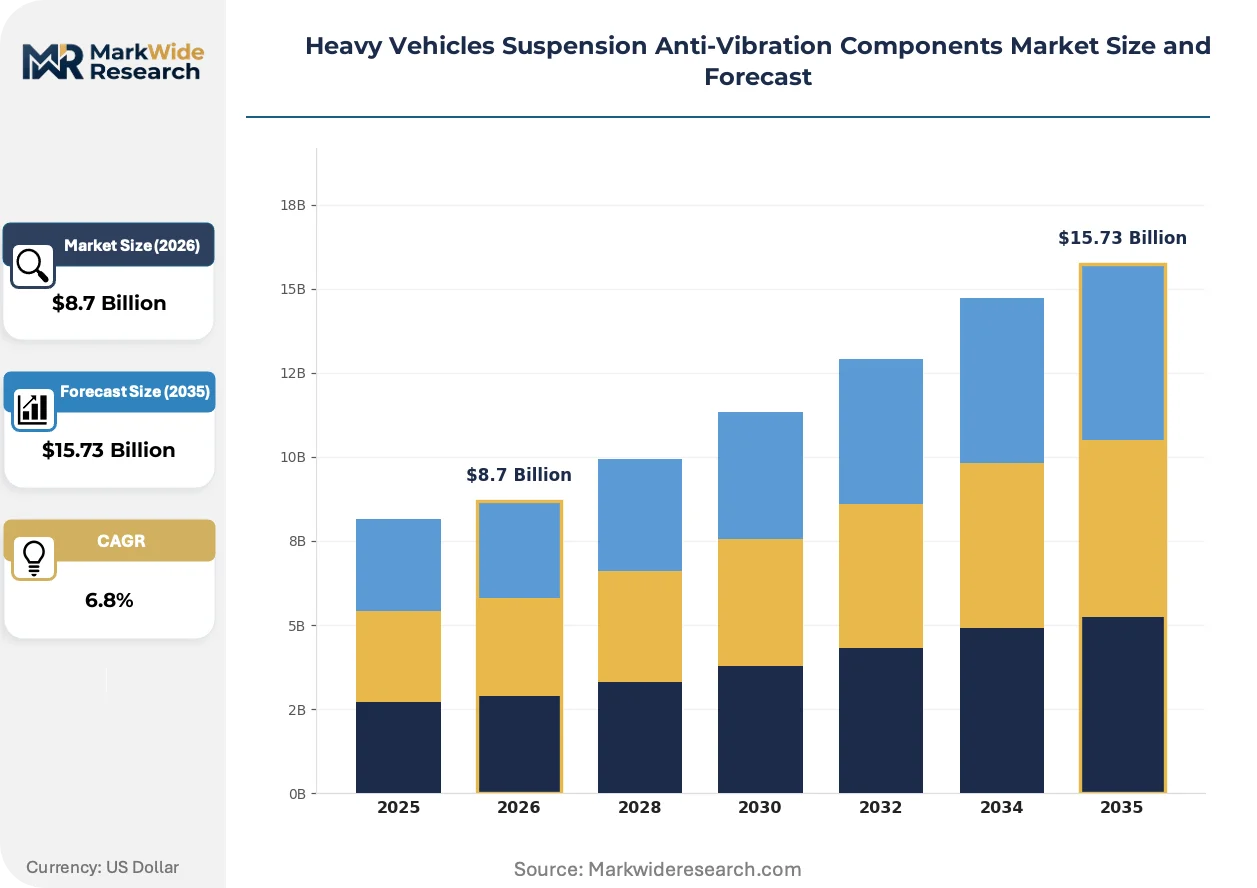
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shock Absorbers, Air Springs, Coil Springs, Bushings End User: Truck Manufacturers, Bus Manufacturers, Trailer Assemblers, Aftermarket Providers Material: Rubber, Steel, Composites, Polyurethane Technology: Traditional, Adaptive, Pneumatic, Hydraulic |
| Companies Covered | Hendrickson, SAF-Holland, ZF Friedrichshafen AG, Continental AG, Tenneco Inc., Firestone Industrial, Knorr-Bremse, Vibracoustic, Hutchinson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Vehicles Suspension Anti-Vibration Components Market Evolving Landscape
Material substitution and embedded sensorization are converging to transform suspension components from passive vibration isolators into active data-collection nodes that inform fleet maintenance decisions.
Magnetorheological fluid dampers are rewriting performance benchmarks for adaptive ride control by enabling millisecond-level viscosity adjustment without mechanical valve actuation. Premium coach operators in Germany and long-haul specialists in the United States are specifying these systems for driver retention programs. The technology is compressing the performance gap between air springs and hydraulic architectures in segments previously dominated by pneumatic solutions.
REACH recycled-content thresholds administered by ECHA are mandating post-consumer rubber incorporation rates that exceed current compound certification baselines. Compound suppliers serving Continental European OEMs are reformulating recipes to maintain Shore hardness ratings while integrating ground tire rubber feedstocks. Bus and coach manufacturers in Germany face the steepest compliance ramps as 2027 durability-verification deadlines approach.
Fleet procurement teams are consolidating supplier relationships around integrated chassis-system vendors capable of warrantying complete suspension modules rather than discrete components. This pattern is displacing independent bushing and spring specialists from specification lists at large North American and Chinese fleet operators. The shift is most pronounced in refrigerated transport segments where cargo-integrity guarantees require single-source accountability for vibration performance.
Heavy Vehicles Suspension Anti-Vibration Components Market Segmentation
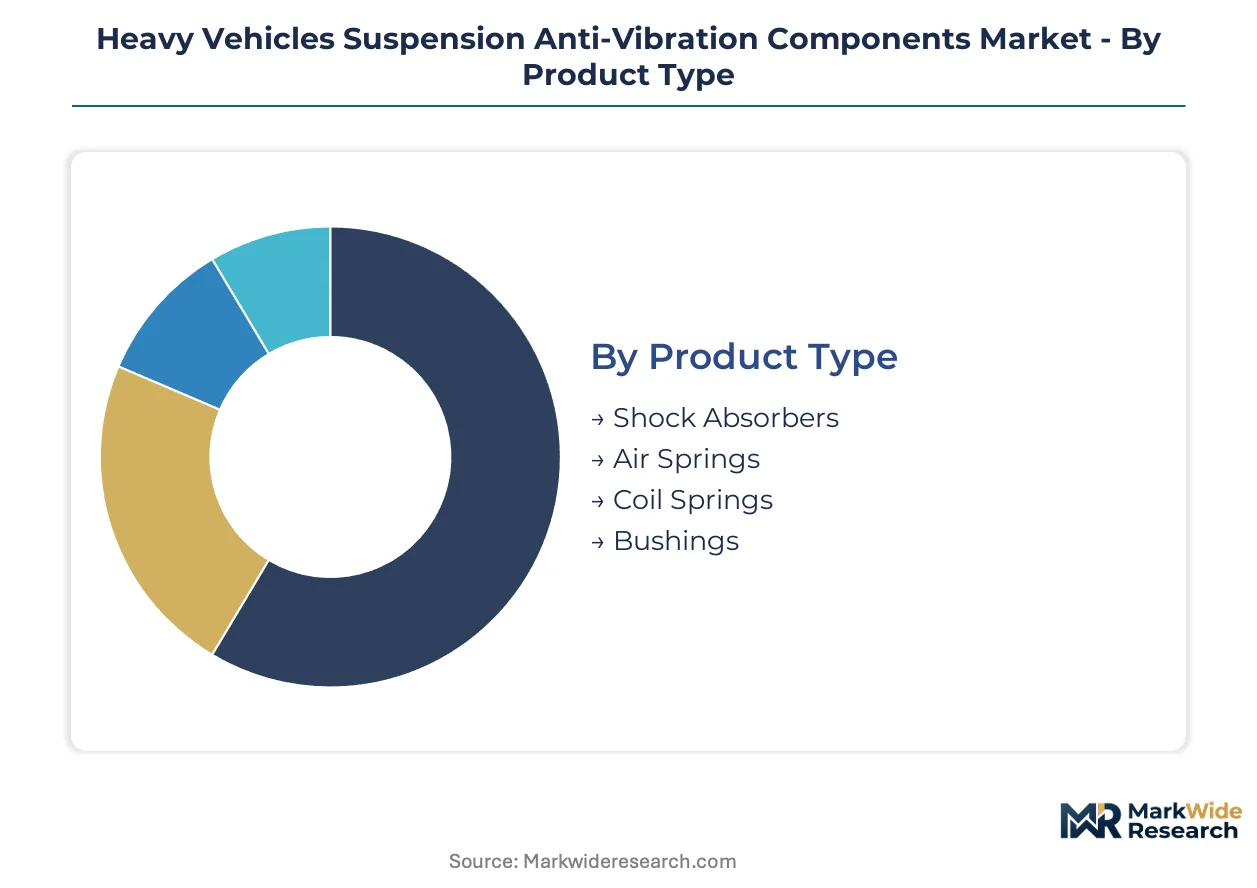
Segmentation in heavy vehicle suspension anti-vibration components reveals how technology choices cascade through procurement budgets and regulatory compliance strategies. Fleet operators and OEMs prioritize different performance thresholds across product categories, creating distinct margin architectures that suppliers must navigate.
Product Type:
Volume concentration sits with mature steel architectures, while premium capture flows to adaptive pneumatic systems that command warranty premiums.
- Shock Absorbers:Hydraulic and twin-tube configurations dominate heavy-duty trucking specifications, with fleet operators in Germany specifying Sachs and ZF architectures for autobahn duty cycles. NHTSA safety mandates are accelerating replacement frequency in North American long-haul segments where driver retention metrics tie directly to ride quality scores.
- Air Springs:Pneumatic bellows manufactured through calendered rubber-to-cord bonding processes isolate chassis from road irregularities while enabling ride height adjustment for loading docks. Refrigerated transport operators across the United States specify these systems to protect temperature-sensitive pharmaceuticals from vibration-induced spoilage.
- Coil Springs:Hot-wound steel architectures from Indian and Brazilian forging houses sustain price competition in emerging-market bus chassis where acquisition cost outweighs lifecycle durability considerations.
- Bushings:Vulcanized rubber-to-metal bonding from Continental and Trelleborg facilities absorbs torsional loads in control arm and leaf spring eye applications.
Today's leader: Shock Absorbers. Tomorrow's challenger: Air Springs.
End User:
Customer type determines specification authority, with OEMs controlling initial fitment and fleet operators increasingly dictating replacement sourcing through telematics-informed procurement.
- Truck Manufacturers:Daimler Truck and Volvo Group chassis engineering teams specify integrated suspension modules rather than discrete components, consolidating supplier relationships around system-level warranty accountability. EPA Phase 2 compliance is forcing material lightweighting in Class 8 frame rail attachments.
- Bus Manufacturers:Electric city bus programs in Shenzhen and Hanover demand low-floor air suspension configurations with regenerative damping integration. Passenger comfort specifications from municipal transit authorities override upfront cost constraints.
- Trailer Assemblers:Dry van and refrigerated trailer builders in Indiana and Shandong source axle-mounted spring-damper combinations through tiered supplier networks.
- Aftermarket Providers:Independent distributors and direct-to-fleet e-procurement platforms serve owner-operator segments with replacement bushings and shock absorbers.
OEMs retain specification control. Aftermarket channels are gaining procurement influence fastest.
Material:
Compound formulation expertise separates margin tiers, with proprietary rubber recipes certified to OEM durability benchmarks commanding premium positioning.
- Rubber:Natural and synthetic elastomer blends processed through vulcanization dominate bushing and air spring construction, with suppliers managing Southeast Asian supply volatility through long-term plantation contracts.
- Steel:Hot-rolled coil feedstocks from integrated mills in China and India sustain cost-competitive coil spring production for price-sensitive fleet segments.
- Composites:Glass- and carbon-fiber reinforced polymers are penetrating upper control arm and stabilizer bar applications where mass reduction improves fuel efficiency compliance scores.
- Polyurethane:Castable formulations from Huntsman and BASF systems serve aftermarket performance segments with extended service interval claims.
Rubber formulations anchor current revenue. Composite substitution is climbing the fastest.
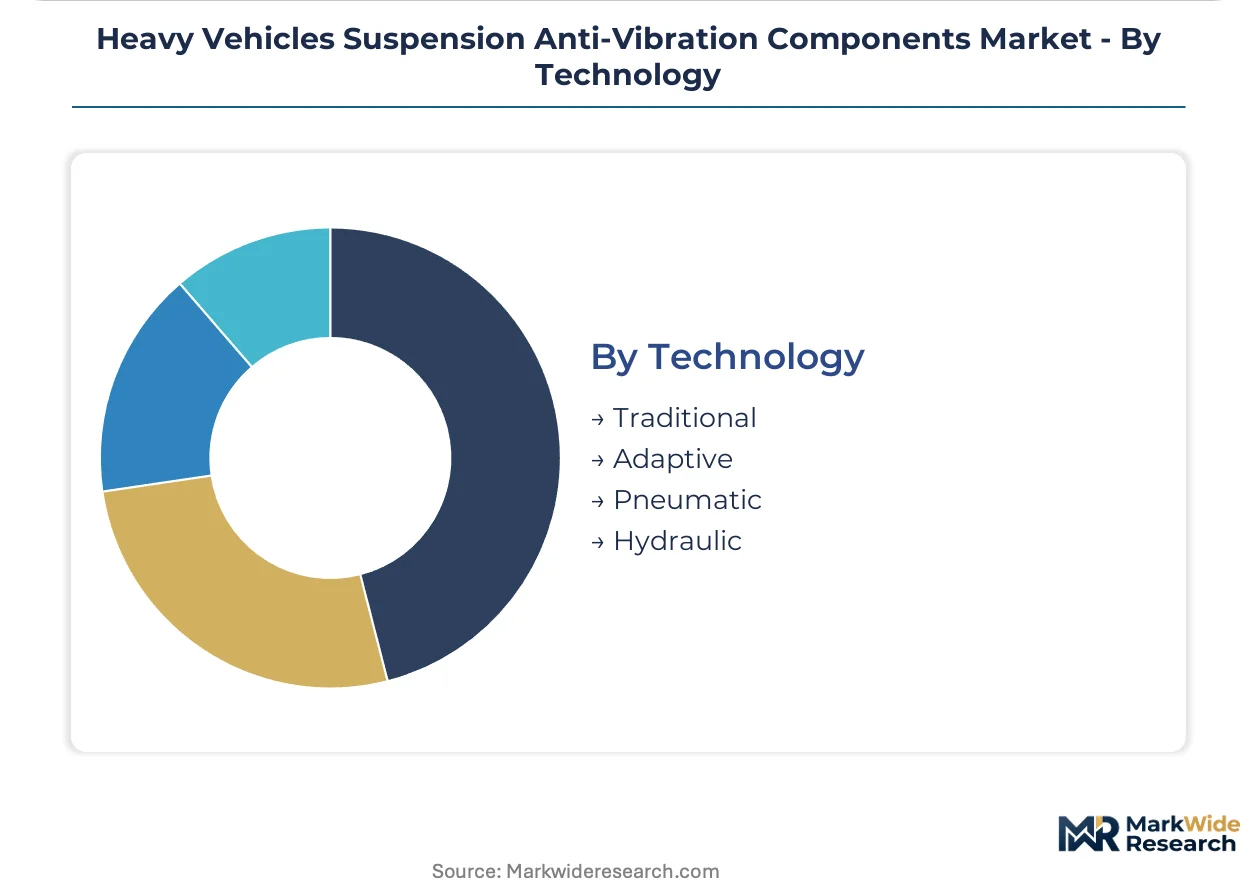
Technology:
Intelligence integration is redefining component boundaries, with sensor-embedded architectures enabling predictive maintenance revenue models.
- Traditional:Passive hydraulic and mechanical spring-damper combinations maintain volume dominance in emerging-market commercial vehicle production where electronic integration costs exceed fleet operator budgets.
- Adaptive:Mechatronic valve systems from ZF and Tenneco adjust damping force within milliseconds based on accelerometer and wheel position sensor inputs. Premium coach operators in Germany specify these architectures for driver wellness programs.
- Pneumatic:Electronically controlled air management systems with height sensors and solenoid valve blocks enable automatic leveling for variable cargo loads.
- Hydraulic:Magnetorheological fluid dampers from BWI Group and Delphi Technologies enable viscosity modulation without mechanical valve actuation, compressing performance gaps with air spring systems.
Traditional architectures hold volume leadership. Adaptive systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Stuttgart, Detroit, and Shanghai anchor suspension component innovation pipelines. Regulatory divergence across production basins is fragmentating supplier qualification timelines. Fleet procurement concentration in specific corridors is reshaping aftermarket distribution networks.
United States
Long-haul freight corridors through Indiana and Ohio sustain dense aftermarket demand for shock absorber replacement cycles. EPA Phase 2 greenhouse gas standards administered by NHTSA are accelerating lightweight material substitution in Class 8 truck suspensions. Detroit-area engineering centers host integrated chassis development programs linking OEM specification authority with tier-1 system suppliers.
Germany
Autobahn duty cycles and premium coach manufacturing in Bavaria drive specification of adaptive damping architectures. Euro VI emission-efficiency linkages enforced by the European Commission are extending durability-testing protocols for bushing and air spring certifications. Stuttgart and Munich anchor Continental AG and ZF Friedrichshafen AG development campuses where rubber-to-metal bonding and mechatronic valve R&D concentrate.
China
Commercial vehicle production clusters in Shandong and Hubei provinces sustain volume demand for steel coil spring architectures. MIIT dual carbon goals and GB standards for commercial vehicle energy consumption are mandating local sourcing ratios for foreign suspension suppliers. Shenzhen electric bus programs are specifying low-floor air suspension configurations with integrated regenerative damping.
India
Price-sensitive fleet operators in Maharashtra and Gujarat sustain cost-competitive procurement of traditional steel spring architectures. BIS certification requirements for commercial vehicle components are elongating import qualification windows for foreign elastomeric compound suppliers. Tamil Nadu forging houses anchor coil spring production for domestic bus chassis and export markets.
Brazil
Agricultural freight corridors through São Paulo and Minas Gerais generate replacement demand for heavy-duty suspension bushings. ANVISA-administered durability standards for commercial vehicle components are converging with Mercosur technical regulations. Campinas industrial parks host stamping and vulcanization facilities serving regional truck assemblers.
Heavy Vehicles Suspension Anti-Vibration Components Market Competitive Landscape
The competitive structure tilts toward integrated system suppliers capable of warrantying complete suspension modules rather than discrete components. Tier-1 automotive conglomerates with captive rubber compounding and precision forging capabilities occupy premium specification tiers. Mid-scale specialists compete on aftermarket channel penetration and fleet direct relationships. Dominant competitive moves include backward integration into elastomer compound formulation and geographic expansion through regional licensing arrangements.
Among German-based integrated suppliers, ZF Friedrichshafen AG and Continental AG exemplify the premium-system archetype through combined rubber-to-metal bonding and mechatronic control competencies. Tenneco Inc. represents the scale-driven manufacturing footprint model with multi-continent production positioning. These three anchors illustrate how specification authority concentrates with vendors capable of bridging OEM initial fitment and aftermarket replacement demand through unified product architectures.
| Leading Market Players |
|---|
| Hendrickson |
| SAF-Holland |
| ZF Friedrichshafen AG |
| Continental AG |
| Tenneco Inc. |
| Firestone Industrial |
| Knorr-Bremse |
| Vibracoustic |
| Hutchinson |
| Others |
Value Network & Pricing Analysis
Natural rubber futures indexed to the Tokyo Commodity Exchange cascade through vulcanization cost structures into three distinct pricing tiers for heavy vehicle suspension components, with Southeast Asian harvest volatility compressing margin predictability for compound manufacturers serving European and North American OEMs.
Pricing Analysis
Bundled system-level warranties versus unbundled discrete component sales split the pricing architecture across this market. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with Euro VI durability-verified air spring modules commanding substantial premiums over BIS-certified steel coil alternatives. Price erosion runs through emerging-market steel spring segments where Indian and Brazilian forging houses sustain cost competition. Fleet operators in long-haul refrigerated transport demonstrate lowest price sensitivity due to cargo-integrity guarantees, while owner-operator segments in Maharashtra and Gujarat exhibit highest elasticity.
Supply Chain Analysis
Workforce availability for precision rubber-to-metal bonding constrains capacity expansion in Stuttgart and Munich engineering clusters, while mechatronics talent scarcity limits adaptive damper production scaling in Detroit-area facilities. Supply concentrates in Germany, China, and the United States for integrated system manufacturing, with vulcanization feedstocks drawing from Southeast Asian plantations and hot-rolled steel coil resting on Chinese and Indian integrated mill output. Single-source vulnerability in natural rubber procurement presents structural risk given climate-induced harvest variability. Distribution runs through OEM direct supply contracts for initial fitment and tiered distributor networks for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as fleet procurement teams consolidate around integrated chassis-system vendors capable of warrantying complete suspension modules rather than discrete components, with adaptive pneumatic specifications displacing traditional steel architectures in premium segments.
For Market Incumbents: Deepen backward integration into proprietary elastomer compound formulation to defend margin position against REACH recycled-content threshold compliance costs. Secure long-term plantation contracts in Southeast Asia to mitigate natural rubber price volatility exposure. Expand mechatronics R&D hiring in Stuttgart and Detroit engineering clusters to address control systems engineer scarcity constraining smart damping development velocity.
For New Entrants and Emerging Players: Begin with aftermarket channel digitization in North American independent operator segments where direct-to-fleet e-procurement platforms are disintermediating traditional distributor networks. Target refrigerated transport fleet operators in the United States with cargo-integrity guaranteed air spring modules as the most penetrable application. Pursue certification pathway partnerships with established compound suppliers to accelerate Euro VI and EPA Phase 2 qualification timelines.
For Investors and Strategic Acquirers: Consolidation pressure builds where mechatronics talent scarcity and extended OEM qualification windows create scale advantages for integrated system vendors over discrete component specialists. Mid-cap rubber-to-metal bonding specialists with proven OEM relationships and verified recycled-content architectures represent priority acquisition targets across the projection horizon. Monitor MIIT dual carbon alignment progress as inflection indicator for Chinese market access expansion opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Compounding | Captures margin pools in proprietary rubber recipes certified to OEM durability benchmarks. |
| Mechatronics Talent Acquisition Programs | Addresses control systems engineer scarcity constraining adaptive damping R&D velocity. |
| Recycled-Content Compound Certification | Secures REACH compliance pathways for Continental European OEM supply contracts. |
| Direct-to-Fleet E-Procurement Platform Launch | Disintermediates traditional aftermarket distributor networks in North American segments. |
| Long-Term Natural Rubber Supply Contracts | Mitigates Southeast Asian harvest volatility exposure for vulcanized component manufacturers. |
Research Methodology
Multiple input streams — primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, and aftermarket service heads; secondary validation through vehicle production databases, customs and trade data, and SEC filings; and technical literature on elastomer compound formulations — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates.
Historical production volumes were cross-referenced against panel input from chassis engineering directors and fleet procurement managers to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, end user category, material formulation, and technology architecture, with CAGRs derived from regression analysis against commercial vehicle production forecasts and regulatory compliance timeline impacts. Industry-specific forecast inputs incorporated EPA Phase 2 fuel efficiency mandate stringency and Euro VI durability-testing protocol extensions.
Several conditions sit outside the modeled scope, including abrupt Southeast Asian natural rubber supply disruptions, unilateral tariff escalations affecting steel coil feedstock costs, and breakthrough advances in magnetorheological fluid damper cost structures. Forecasts reflect documented assumptions regarding fleet operator specification behavior and OEM qualification timeline norms. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Seating and Positioning Belts Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Canada Automotive Carbon Fiber Composites Market
Vehicle Components
Automotive Rubber Molded Components Market
Vehicle Components
Car Sunshade Market
Vehicle Components
South Africa Automotive Thermoplastic Polymer Composites Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
Idler Arm Market
Vehicle Components
Bicycle Lights Market
Vehicle Components
China Automotive Carbon Fiber Composites Market
Vehicle Components
Forestry Trailers Market
Vehicle Components
Global Truck and Trailer Landing Gear Market
Vehicle Components
Steer-by-Wire Road Wheel Actuator Modules Market
Vehicle Components
Rail Components Market
Vehicle Components
Hooklift Trailer Market
Vehicle Components
Forklift Seats Market