
 Global Automotive Brake Hose Market | 2026-2036
Global Automotive Brake Hose Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Brake Hose Market Intelligence
A divergence in material science, particularly between standard rubber and advanced PTFE or stainless steel braided hoses, is recalibrating the market's competitive structure. Continental AG leverages its extensive R&D in synthetic materials to serve the high-performance OEM segment. Parker Hannifin Corp specializes in high-pressure hydraulic applications across multiple industrial sectors, including automotive. Gates Corporation competes effectively in the aftermarket by offering a broad portfolio of reinforced rubber hoses for a wide range of vehicles.
An automotive brake hose is a flexible conduit designed to transmit hydraulic fluid pressure from the master cylinder to the brake calipers or wheel cylinders. These components must withstand high pressures, often exceeding 1,000 psi, and resist degradation from brake fluid and environmental factors. While traditional rubber hoses command the largest volume in the passenger vehicle aftermarket, PTFE and stainless steel braided hoses are gaining traction in performance and heavy-duty applications. OEM manufacturers prioritize long-term durability and compliance, whereas aftermarket providers focus on cost-effectiveness and performance upgrades.
Compliance with stringent safety standards, such as the US Federal Motor Vehicle Safety Standards (FMVSS) 106 and Europe's ECE regulations, is non-negotiable for market entry. These frameworks mandate specific burst strength, whip resistance, and material compatibility tests, directly influencing product design and manufacturing costs. The key decision for suppliers is whether to invest in materials for higher-temperature electric vehicle braking systems or to optimize cost structures for the legacy internal combustion engine aftermarket.
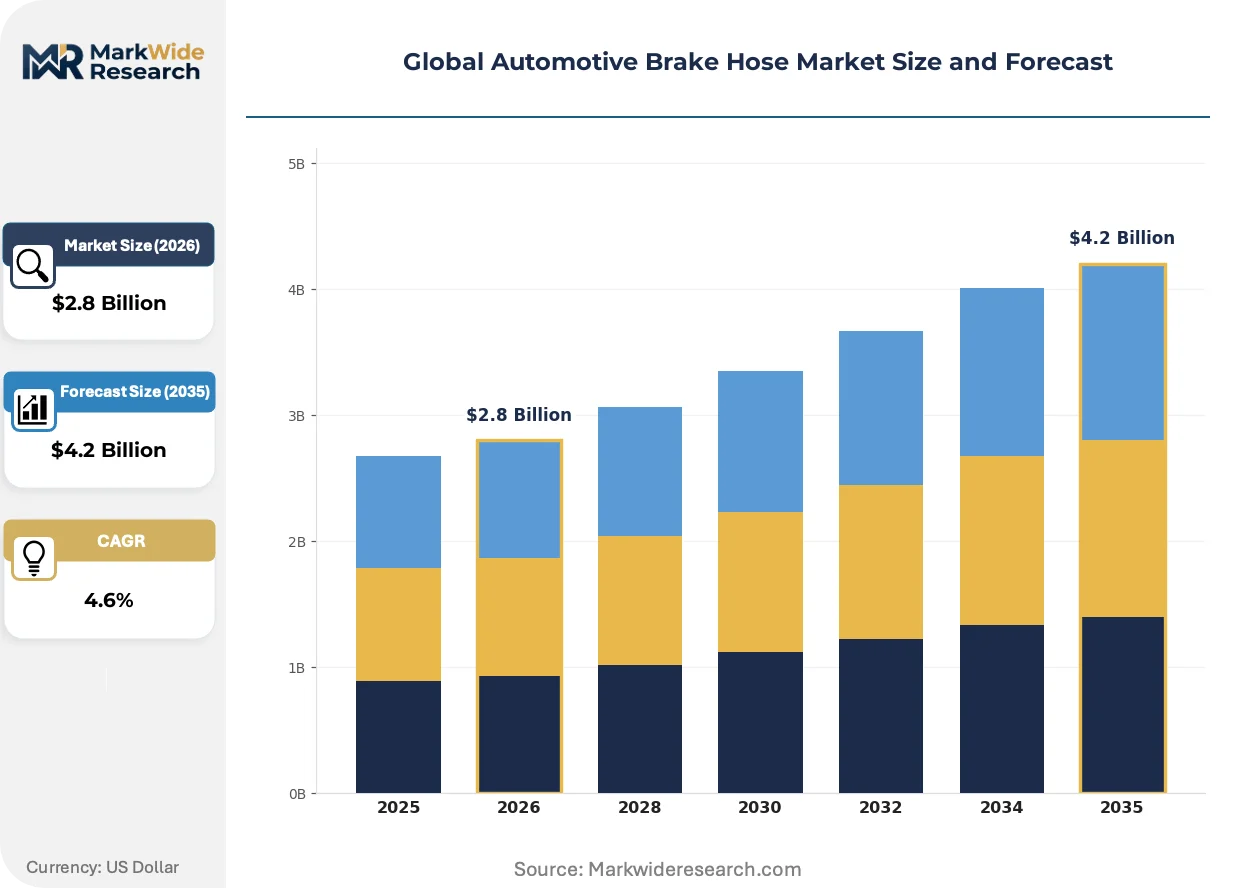
Market Dynamics
The dual demands of electric vehicle regenerative braking systems and the concentration of vehicle production in China are the central forces shaping material requirements and supply chain logistics for automotive brake hoses.
Growth Catalysts
- Commercial Vehicle Expansion:The growth of logistics and e-commerce globally increases the fleet size of commercial trucks and vans, which require more durable and frequent brake hose replacements than passenger cars.
- Stringent Safety Mandates:Regulations like the US FMVSS 106 and Europe's ECE framework compel the use of higher-performance, certified hoses, eliminating lower-quality options from OEM and regulated aftermarket segments.
- Material Science Advancement:The development of advanced synthetic rubber compounds and PTFE liners enables hoses to withstand higher temperatures, meeting the needs of modern ABS and ESC systems.
Market Restraints
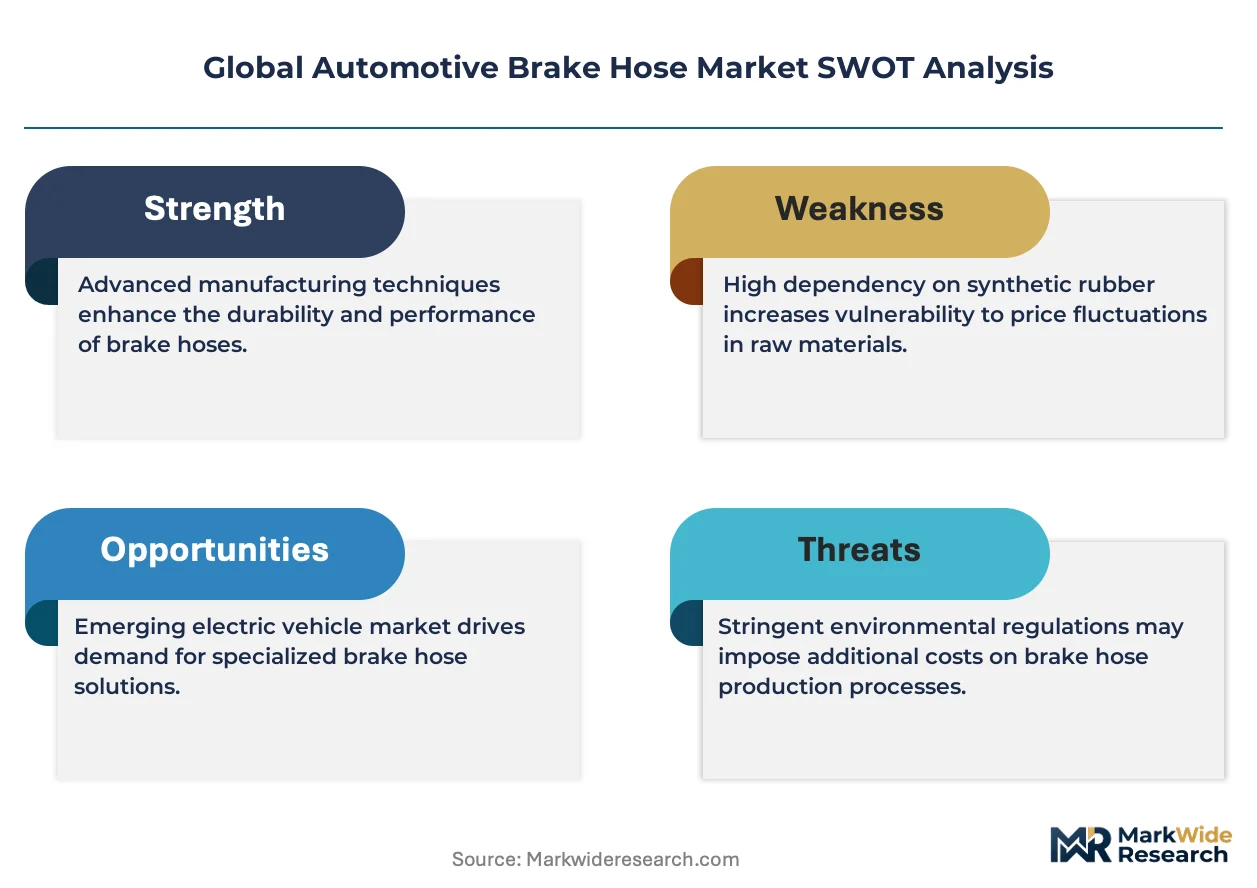
- Raw Material Volatility:Price fluctuations in synthetic rubber, steel for braiding, and specialized polymers like PTFE create margin pressure and complicate long-term supply contracts for manufacturers.
- Aftermarket Counterfeiting:The presence of low-cost, non-compliant counterfeit products in unregulated aftermarket channels, particularly in emerging economies, erodes brand value and poses a significant safety risk.
- High Capital for Compliance:The investment required for testing equipment to validate compliance with whip resistance and burst strength standards acts as a barrier to entry for smaller firms.
Strategic Opportunities
- EV-Specific Hoses:Developing hoses compatible with the specific chemical compositions of new brake fluids used in EV regenerative braking systems presents a significant design-in opportunity with automakers.
- Heavy-Duty Aftermarket Focus:Targeting the aftermarket for heavy-duty trucks and buses in North America and Europe with specialized, high-durability braided hoses offers a high-margin niche.
- Manufacturing in Mexico:Establishing production in Mexico provides a cost-effective manufacturing base with tariff-advantaged access to the large North American automotive assembly market via the USMCA.
Industry Challenges
- Global Supply Chain Synchronization:Coordinating just-in-time delivery of diverse hose specifications to automotive assembly plants in China, Germany, and the United States is a major logistical challenge.
- Legacy System Integration:Ensuring new material formulations remain compatible with the vast installed base of vehicles using traditional DOT 3 and DOT 4 brake fluids complicates aftermarket product portfolio management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Brake Hose Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reinforced Brake Hose, Braided Brake Hose, PTFE Brake Hose, Rubber Brake Hose, Stainless Steel Brake Hose Technology: High-Pressure Resistance, Anti-Corrosion, Heat Resistant, Flexible Design, Lightweight Construction End User: OEM Manufacturers, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers Application: Passenger Vehicles, Commercial Vehicles, Construction Equipment, Agricultural Machinery, Two-Wheelers |
| Companies Covered | Continental AG, Robert Bosch GmbH, Gates Corporation, Parker Hannifin Corp, Dayco IP Holdings LLC, TI Fluid Systems Plc, Sumitomo Riko Co., Ltd., NICHIRIN Co. Ltd., AGS Automotive Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Brake Hose Market Strategic Shifts & Innovations
Material science advancements are intersecting with new vehicle platform architectures. This forces a re-evaluation of hose performance beyond traditional hydraulic pressure containment, particularly concerning thermal management and fluid compatibility in next-generation braking systems.
Polytetrafluoroethylene (PTFE) lined hoses, often reinforced with stainless steel braiding, offer superior resistance to heat, chemical degradation, and expansion compared to traditional rubber. The performance and motorsport enthusiast segments are early adopters, seeking improved pedal feel and durability. This advanced construction is overtaking standard rubber hoses in high-performance OEM applications and premium aftermarket upgrades.
The US National Highway Traffic Safety Administration's FMVSS 106 standard sets rigorous testing protocols for brake hose assemblies, including tensile strength and whip resistance. These federal requirements directly influence material selection and manufacturing processes for all vehicles sold in the United States. The passenger car segment is most impacted, as compliance is non-negotiable for market access.
A behavioral shift in the passenger vehicle aftermarket is evident as owners increasingly select performance-oriented upgrade components over direct like-for-like replacements. This trend disrupts the traditional distributor model focused on standard rubber hoses, favoring online retailers and specialty installers who cater to this demand. This pattern is most visible in the North American and European car enthusiast communities.
Global Automotive Brake Hose Market Segmentation
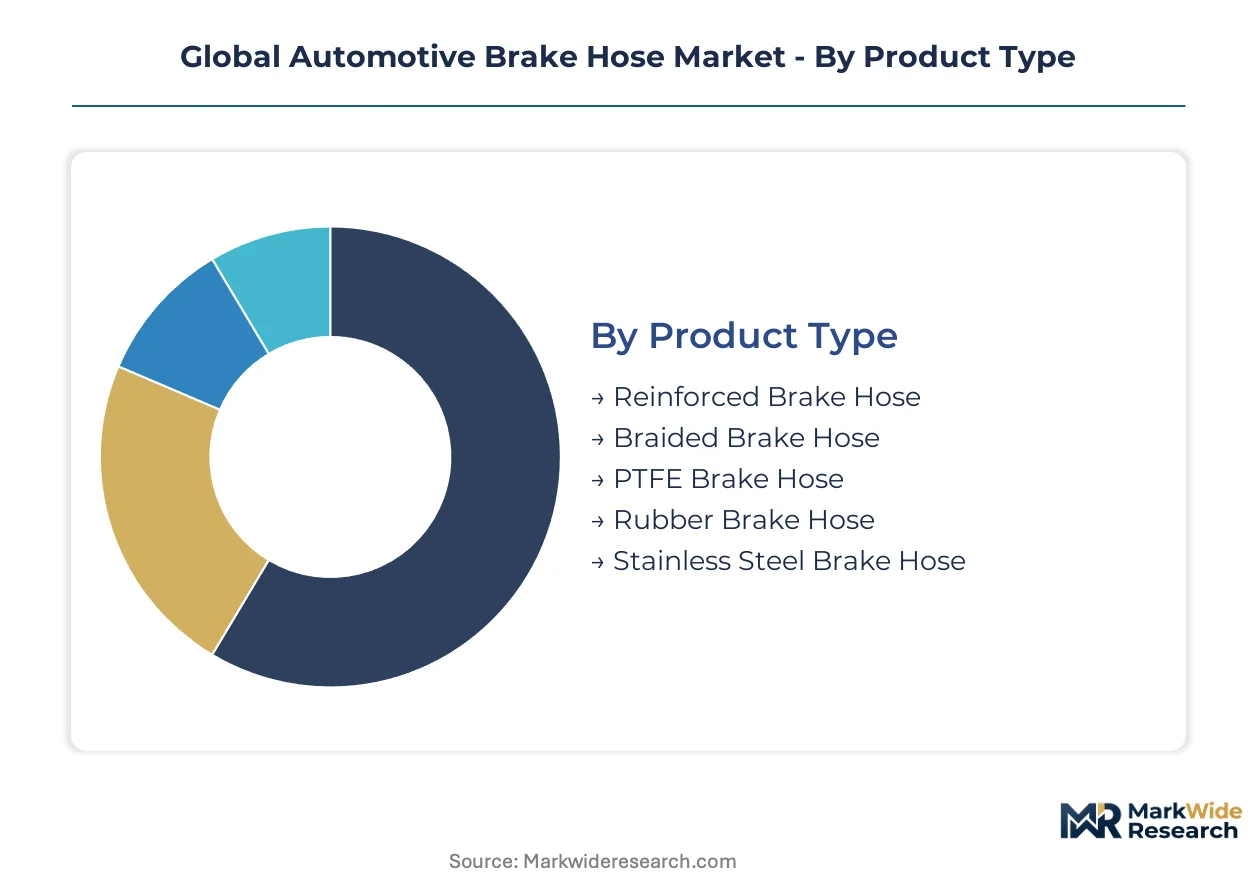
The automotive brake hose market delineates into distinct segments reflecting varied product specifications, technological requirements, and end-user demands. Understanding these classifications reveals the underlying forces driving material science advancements and strategic supply chain decisions. This segmentation provides clarity on where value creation and competitive differentiation occur.
Product Type:
The global supply of automotive brake hoses increasingly centers on materials offering superior performance characteristics, influencing product type availability across diverse vehicle platforms.
- PTFE Brake Hose:Polytetrafluoroethylene lined hoses provide exceptional chemical resistance and thermal stability, often reinforced with stainless steel braiding for burst strength. Demand concentrates within high-performance vehicle OEMs and the European motorsport aftermarket, driven by the need for consistent pedal feel and longevity.
- Rubber Brake Hose:Traditional rubber hoses, typically composed of synthetic elastomers like EPDM or SBR, offer flexibility and cost-effectiveness for standard applications. Demand is concentrating in the passenger vehicle aftermarket across China and North America, driven by their widespread use in legacy internal combustion engine vehicles.
- Braided Brake Hose:These hoses feature an external layer of woven material, often stainless steel, enhancing pressure resistance and reducing volumetric expansion.
- Reinforced Brake Hose:Incorporating internal textile or wire plies, reinforced hoses improve burst strength and minimize ballooning under hydraulic pressure.
- Stainless Steel Brake Hose:Characterized by an external stainless steel braid, these hoses offer superior abrasion resistance and a firmer brake pedal feel.
Today's leader: Rubber Brake Hose. Tomorrow's challenger: PTFE Brake Hose.
Technology:
Different vehicle applications necessitate specific technological attributes in brake hose design, ranging from extreme pressure handling to environmental resilience.
- High-Pressure Resistance:This technology ensures hoses can reliably withstand hydraulic pressures exceeding 1,000 psi, critical for modern braking systems like ABS and ESC. Demand is particularly pronounced in heavy-duty commercial vehicles and performance cars across North America, where braking forces are substantial.
- Heat Resistant:Hoses engineered for heat resistance maintain integrity under elevated temperatures generated by frequent braking or proximity to engine components. Electric vehicle platforms in Europe require these hoses for compatibility with regenerative braking systems and new brake fluid compositions.
- Anti-Corrosion:This feature protects the hose from degradation caused by brake fluids and external environmental factors, extending service life.
- Flexible Design:Engineers prioritize flexible designs to accommodate suspension travel and ease installation in complex vehicle architectures.
- Lightweight Construction:Reducing material mass contributes to overall vehicle weight savings, a key objective for electric vehicle platforms and fuel efficiency standards.
High-Pressure Resistance technology underpins core market requirements, while Heat Resistant solutions are expanding most quickly due to EV integration.
End User:
The diverse customer types within the automotive ecosystem dictate varying procurement strategies and product specifications for brake hose suppliers.
- OEM Manufacturers:These entities integrate brake hoses directly into new vehicle production lines, demanding high volumes, stringent quality control, and just-in-time delivery. Demand is heavily concentrated in China's automotive manufacturing hubs due to its massive vehicle production volume.
- Aftermarket Providers:This segment supplies replacement brake hoses for vehicles already in operation, focusing on broad compatibility, cost-effectiveness, and performance upgrades. North American and European aftermarket channels show significant demand for both standard replacements and performance-oriented braided hoses.
- Tier-1 Suppliers:These companies provide integrated braking system modules to OEMs, often sourcing specialized brake hoses from sub-suppliers.
- Vehicle Assemblers:Responsible for final vehicle assembly, these users integrate components from various suppliers, including brake hose assemblies.
OEM Manufacturers represent the largest volume segment, with Aftermarket Providers gaining share fastest through specialized performance offerings.
Application:
The volume and nature of vehicle production across different application segments directly influence the demand for specific brake hose types and their performance characteristics.
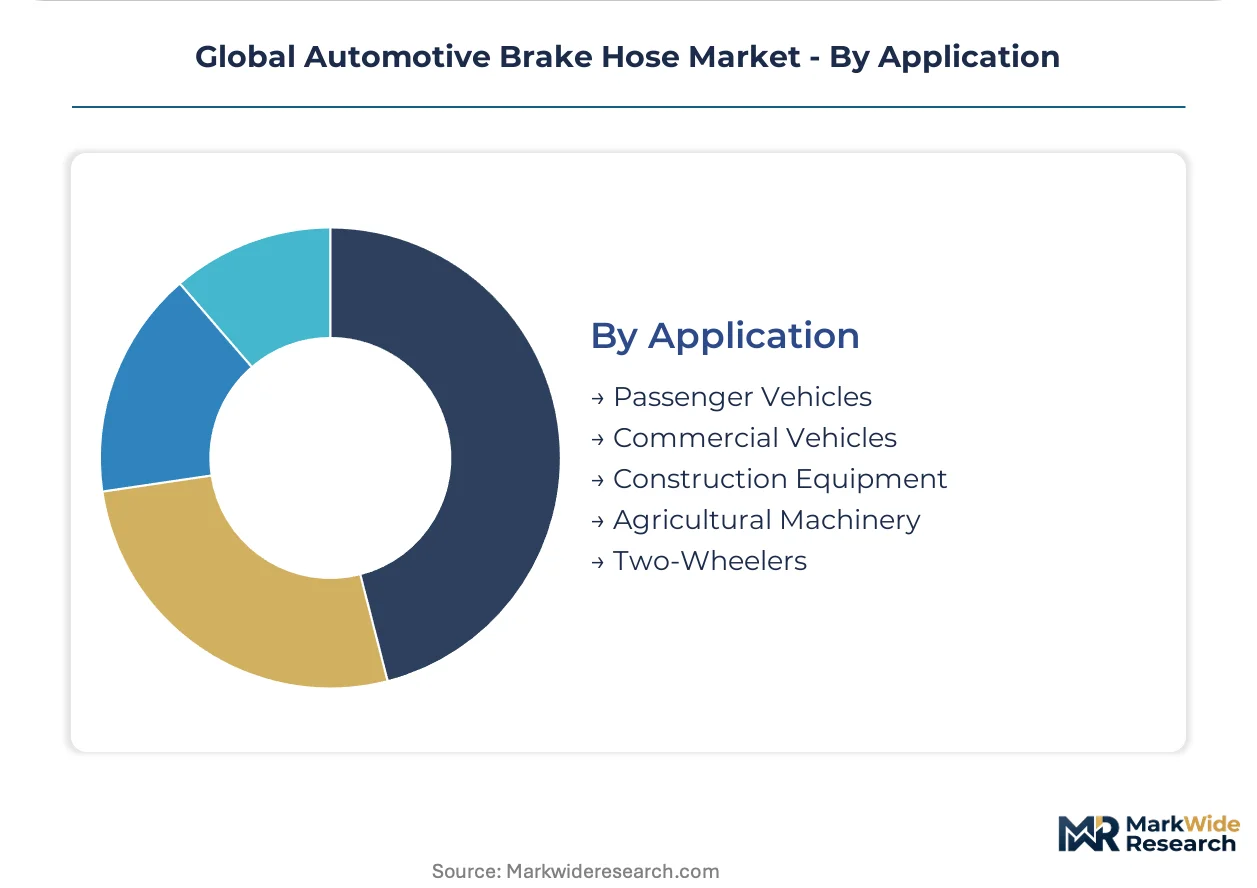
- Commercial Vehicles:This segment includes heavy-duty trucks, buses, and vans, requiring brake hoses with superior durability, pressure resistance, and longevity due to higher operating loads. Growth in global logistics and e-commerce drives significant demand for robust brake hose replacements and OEM installations in North America and Europe.
- Passenger Vehicles:Comprising cars and light trucks, this segment represents the largest volume market for brake hoses, balancing cost-effectiveness with safety and performance standards. The extensive installed base in China and the US generates consistent demand for both OEM and aftermarket hoses.
- Construction Equipment:Heavy machinery like excavators and loaders require brake hoses capable of extreme pressure, abrasion resistance, and temperature fluctuations.
- Agricultural Machinery:Tractors and other farm equipment utilize brake hoses designed for harsh outdoor environments and intermittent heavy-duty use.
- Two-Wheelers:Motorcycles and scooters require compact, flexible brake hoses, often with braided reinforcement for enhanced performance and safety.
Passenger Vehicles maintain the highest market volume, while Commercial Vehicles exhibit the steepest expansion trajectory due to fleet growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's expansive automotive manufacturing ecosystem drives significant demand for brake hoses, contrasting with the United States where aftermarket replacements for passenger and commercial vehicles sustain market volumes. European markets prioritize advanced material science for performance applications. These regional dynamics shape material requirements and supply chain strategies.
China
OEM manufacturers in China demand high volumes of brake hoses for new vehicle production. The country's GB standards dictate rigorous performance and safety requirements for these components. Automotive manufacturing hubs in regions like Shanghai continue to expand, attracting investment in advanced brake hose production facilities.
United States
The United States aftermarket for passenger and commercial vehicles generates substantial demand for replacement brake hoses. US Federal Motor Vehicle Safety Standards (FMVSS) 106 sets critical safety benchmarks for all brake hose assemblies. Manufacturing and distribution centers in the Midwest, particularly around Detroit, coordinate large-scale supply to the automotive sector.
Germany
German automotive OEMs, particularly in the high-performance segment, require advanced brake hoses for new vehicle platforms. Europe's ECE regulations impose strict material compatibility and durability standards. Research and development centers in areas such as Stuttgart focus on integrating heat-resistant hoses for electric vehicle braking systems.
Mexico
Mexico serves as a strategic manufacturing hub for automotive brake hoses, offering cost efficiencies. The USMCA trade agreement facilitates tariff-advantaged access to the vast North American automotive assembly market. Major automotive component suppliers establish production sites in regions such as Nuevo León to support local and export demand.
Japan
Japanese automotive manufacturers emphasize long-term durability and precision in brake hose specifications for new vehicles. The country's JIS standards define stringent testing protocols for all critical automotive components. Production facilities located in regions like Aichi Prefecture focus on delivering advanced rubber and PTFE hoses to major carmakers.
Global Automotive Brake Hose Market Key Industry Players
Top-tier vendors anchor the global automotive brake hose market, while a diverse array of specialized manufacturers and regional providers compete for niche segments. The market structure exhibits consolidation at the OEM supply level, transitioning to fragmentation within the aftermarket. Strategic archetypes include integrated system suppliers, material science innovators, and cost-effective aftermarket specialists. Companies primarily engage in strategic partnerships for technology transfer and capacity expansion to meet diverse global demand.
Integrated system suppliers, such as German-based Continental AG, exemplify the broad portfolio approach to automotive components. US-headquartered Gates Corporation occupies a strong position within the aftermarket, offering a wide range of replacement hoses. Japanese manufacturer Sumitomo Riko Co., Ltd. represents a key player in advanced material development for OEM applications. These companies collectively illustrate the tiered nature of competition, balancing high-performance requirements with cost-effectiveness across different vehicle segments.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Gates Corporation |
| Parker Hannifin Corp |
| Dayco IP Holdings LLC |
| TI Fluid Systems Plc |
| Sumitomo Riko Co., Ltd. |
| NICHIRIN Co. Ltd. |
| AGS Automotive Solutions |
| Others |
Cost & Logistics Intelligence
A clear performance bifurcation between standard rubber and advanced PTFE/braided hoses manifests in both pricing and supply chain configurations. OEM manufacturers prioritize certified, long-term durability, influencing higher contract pricing, while the aftermarket seeks cost-effectiveness and performance upgrades.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity rubber hoses due to economies of scale. The dominant pricing structure remains per-unit transactional, heavily influenced by raw material costs. Price differentiation stems from certification level, such as FMVSS 106 compliance, and the brand premium commanded by established OEM suppliers. Pricing softness reflects competition from lower-cost aftermarket alternatives, especially in emerging economies. Aftermarket providers exhibit higher price sensitivity compared to OEM manufacturers, who prioritize supply security and quality.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand, particularly in China and Germany, ensuring just-in-time delivery. Geographic supply concentration for raw materials draws from Southeast Asia for synthetic rubber and from global steel producers for braiding. Raw material dependencies include synthetic rubber compounds, steel for braiding, and specialized polymers like PTFE. A structural supply chain risk is raw material volatility, creating margin pressure for manufacturers. Aftermarket distribution runs through a fragmented network of regional distributors and online retailers in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive brake hose market is a late-cycle quality story, driven by a demand shift toward higher-performance, heat-resistant specifications for electric vehicles.
For Market Incumbents:Anticipate continued material science shifts toward PTFE and braided constructions. Invest in R&D for EV-specific hose chemistries compatible with regenerative braking systems to counter the threat from specialized material innovators. Deepen vertical integration into advanced polymer production to control costs and secure supply of critical materials. Consolidate market share in the commercial vehicle segment by offering high-durability solutions, leveraging existing OEM relationships.
For New Entrants and Emerging Players:Performance-oriented vehicle enthusiasts represent an underserved buyer archetype seeking superior braking feel and durability. Target the heavy-duty aftermarket in North America with specialized, high-durability braided hoses, a high-margin niche. A compelling go-to-market angle involves direct-to-consumer sales through online specialty platforms, bypassing traditional distributor models. Focus on achieving FMVSS 106 certification for premium products to gain credibility swiftly.
For Investors and Strategic Acquirers:Consolidation pressure builds where material science advancements create competitive advantages for integrated players. The long-term viability of the market remains strong, driven by global vehicle fleet expansion and regulatory mandates. Target mid-sized, specialized manufacturers with proprietary PTFE or braided hose technology for their intellectual property and established OEM design-ins. The signal to watch is the market share growth of EV-compatible hose suppliers within Tier-1 automotive systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in EV-specific material R&D | Ensures compatibility with new brake fluids and thermal demands of electric vehicle platforms. |
| Expand commercial vehicle aftermarket presence | Captures robust demand from fleet operators requiring durable, high-performance replacement hoses. |
| Establish manufacturing hubs in Mexico | Provides cost-effective production and tariff-advantaged access to the North American automotive market. |
| Acquire specialized PTFE hose manufacturers | Secures advanced material expertise and intellectual property for high-performance applications. |
| Strengthen digital sales channels | Reaches performance-oriented aftermarket consumers directly, bypassing traditional distribution networks. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. The methodology combines in-depth primary interviews with industry stakeholders and rigorous secondary validation. Stakeholders include OEM platform engineers, Tier-1 procurement leads, aftermarket distributors, and material science R&D directors. Secondary data sources encompass automotive production databases, regulatory filings (FMVSS, ECE), and trade association reports, triangulated with bottom-up and top-down market sizing.
The analytical framework employs a rate-of-change decomposition to project market evolution across the analysis window. Segmentation dimensions modeled include product type, technology, end-user, application, and regional production clusters. Compound annual growth rates were derived from historical data analysis and projected future trends, incorporating inputs such as electric vehicle penetration rates and commercial fleet expansion forecasts.
Underlying measurement precision varies by segment; OEM and commercial vehicle applications carry tighter precision than the fragmented aftermarket. Forecasts reflect assumptions regarding regulatory stability and technological adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Needle Roller Bearings Market
Automotive Parts
Global Automotive Leaf Spring Market
Automotive Parts
Global Automotive Plastic Fuel Tank Market
Automotive Parts
Electric Power Steering System (EPS) Market
Automotive Parts
Global Automotive Muffler Tip Market
Automotive Parts
Thailand Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
Vehicle Jump Starter Market
Automotive Parts
China Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Timing Belt Market
Automotive Parts
Brazil Automotive Airfilters Market
Automotive Parts
Motorcycle Battery Chargers Market
Automotive Parts
Russia Automotive Actuators Market
Automotive Parts
Automotive Intercooler Market
Automotive Parts
Automotive Hydraulic Filters Market
Automotive Parts
Plastic Fuel Tanks Market