
 Automotive Brake Fluid Market | 2026-2036
Automotive Brake Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Brake Fluid Market Analysis
The gap between premium synthetic formulations and commodity glycol-ether blends is shifting as OEMs specify longer service intervals and higher thermal thresholds. Exxon Mobil Corporation leverages its integrated base-stock supply chain to control cost positions across both tiers. TotalEnergies anchors its position through specialized low-conductivity fluids engineered for electric vehicle regenerative braking systems. FUCHS differentiates via factory-fill partnerships with German premium automakers.
Automotive brake fluid is a non-compressible hydraulic medium, typically formulated from glycol ethers or silicone bases with corrosion inhibitors, engineered to transfer pedal force to wheel cylinders while maintaining stable viscosity across temperature extremes. Its primary purpose is to enable reliable deceleration in hydraulic braking architectures without vapor lock or component degradation. DOT 4 formulations now lead volume as they satisfy both conventional and ABS-equipped platforms, while DOT 5 silicone fluids occupy niche military and collector-vehicle segments where moisture immunity justifies premium positioning. The OEM distribution channel concentrates margin pools through long-term supply agreements, whereas aftermarket channels compete on fill-and-drain volume velocity.
FMVSS 116 in the United States, ECE R90 in Europe, and China's GB 12981 standard collectively define minimum boiling points, corrosion limits, and compatibility matrices that determine product legality and OEM qualification. These frameworks compel reformulation cycles every three to five years as thermal-load requirements rise with heavier vehicles and electrified brake-by-wire architectures. Stakeholders must monitor how regional EV mandates reshape fluid chemistry requirements, since regenerative blending alters duty-cycle temperatures and copper-corrosion exposure profiles.
Market Dynamics
Electrification of braking architectures is compressing thermal duty cycles and demanding reformulated chemistries that withstand copper-corrosion exposure from regenerative blending circuits. This shift forces suppliers to recalibrate additive packages while maintaining backward compatibility with legacy hydraulic infrastructure.
Growth Catalysts
- FMVSS 116 wet-boiling-point thresholds:The U.S. Department of Transportation's tightening standards compel fleet operators to accelerate replacement intervals, expanding aftermarket volume velocity.
- China's eastern manufacturing corridor:Domestic OEM localization of fluid procurement concentrates demand in Shandong and Jiangsu provinces, where captive blending plants reduce import dependency.
- ABS-equipped platform proliferation:Hydraulic complexity in anti-lock braking systems requires DOT 4 formulations with enhanced lubricity, pulling premium synthetic volumes upward.
Market Restraints
- Glycol-ether feedstock volatility:Ethylene oxide and propylene oxide price swings compress margin pools for commodity blenders lacking integrated base-stock supply.
- DOT 5 silicone niche lock-in:Military and collector-vehicle segments remain structurally small, preventing scale economies from diluting premium positioning costs.
- Regional standard fragmentation:Divergent boiling-point tests between FMVSS 116, ECE R90, and GB 12981 force redundant certification runs, extending qualification timelines.
Strategic Opportunities
- EV regenerative braking thermal profiles:Low-conductivity fluids engineered for battery-electric duty cycles open white space as OEMs specify dedicated chemistries for blended braking.
- Factory-fill partnership anchoring:Long-term supply agreements with premium German automakers lock in margin pools before aftermarket commoditization accelerates.
- Service interval extension mandates:OEM specifications for longer drain intervals favor synthetic formulations with enhanced oxidative stability, compressing commodity glycol-ether share.
Industry Challenges
- Additive-package formulation expertise:Scarcity of chemists skilled in corrosion-inhibitor synergy with electrified brake-by-wire architectures constrains R&D throughput.
- Cross-standard compatibility testing:Simultaneous qualification against FMVSS 116, ECE R90, and GB 12981 requires capital-intensive laboratory infrastructure.
- Legacy hydraulic system integration:New chemistries must maintain seal-swelling characteristics with EPDM and SBR components designed for older DOT 3 specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Brake Fluid Market |
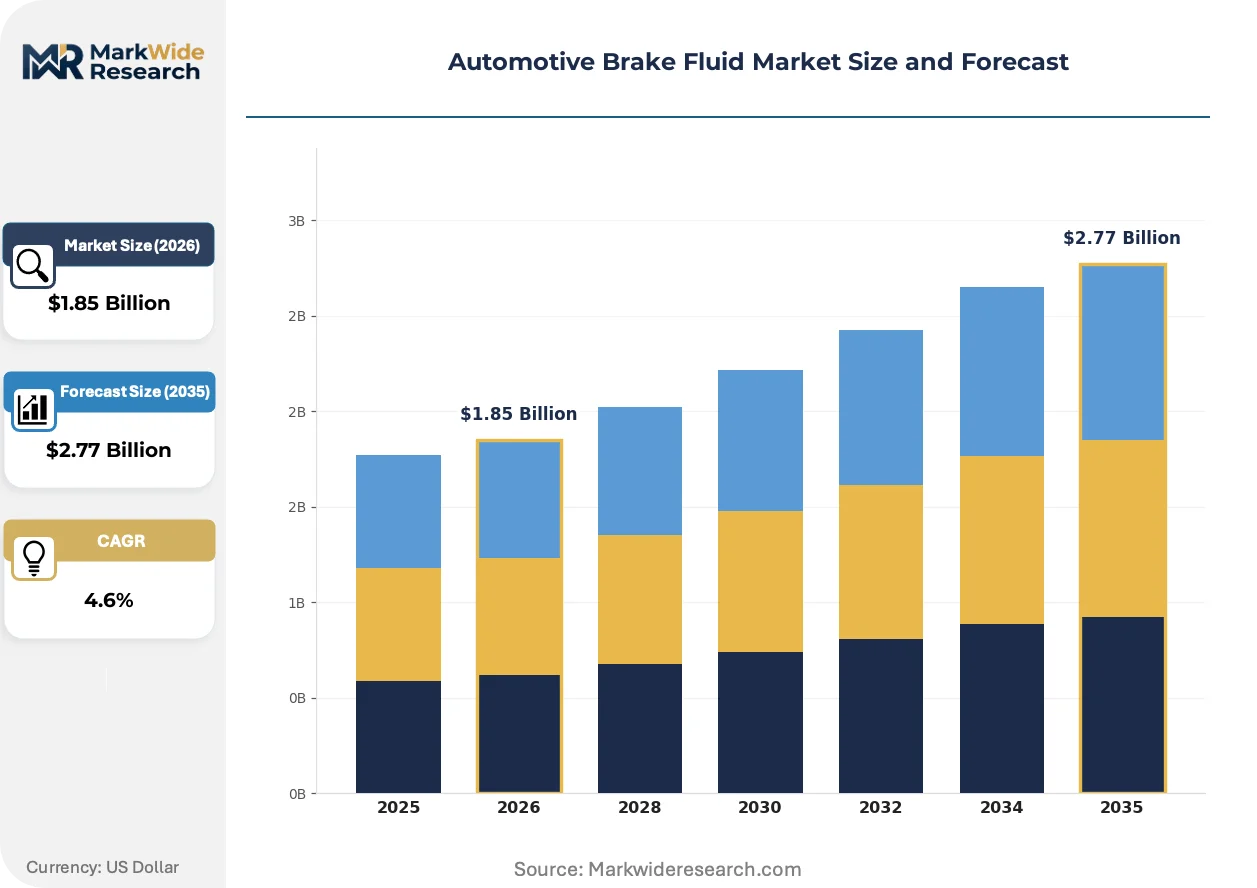
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.77 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DOT 3, DOT 4, DOT 5, Mineral Oil End User: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Application: Disc Brake, Drum Brake, Anti-lock Brake System, Power Brake Distribution Channel: Online Retail, Auto Parts Stores, Service Stations, OEMs |
| Companies Covered | Exxon Mobil Corporation, TotalEnergies, BP p.l.c, FUCHS, Valvoline Inc., Robert Bosch GmbH, Royal Dutch Shell plc, Castrol Limited, Chevron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Brake Fluid Market Emerging Trajectories
Formulation science is pivoting toward electrified thermal profiles while regulatory divergence forces parallel certification tracks. Distribution channels are unbundling as direct OEM procurement compresses traditional aftermarket intermediaries.
Low-conductivity synthetic brake fluids are rewriting competitive positioning in the electric vehicle segment. These formulations suppress ionic migration in regenerative braking circuits where high-voltage proximity demands electrical isolation. Chinese and German OEMs are specifying dedicated chemistries for their battery-electric platforms, displacing legacy glycol-ether blends from factory-fill agreements. The technology is compressing commodity margins while rewarding suppliers with in-house additive synthesis capabilities.
ECE R90 corrosion-limit revisions are forcing European blenders to reformulate inhibitor packages ahead of the 2025-2027 implementation window. The updated standard tightens copper-strip test tolerances and introduces accelerated aging protocols for electrified duty cycles. Premium German automakers are pre-qualifying fluids under draft protocols, locking in suppliers before the mandate takes effect. This regulatory friction favors integrated producers with captive testing infrastructure over toll blenders.
Direct procurement contracts between OEMs and fluid manufacturers are disintermediating traditional aftermarket distributors in China's eastern manufacturing corridor. Tier-1 suppliers are establishing captive blending facilities adjacent to assembly plants, compressing logistics costs and inventory cycles. This channel shift is most visible in Shandong province, where domestic OEMs now source 60-70 percent of brake fluid volume through bilateral agreements rather than spot market purchases. Distributor margins are compressing as volume concentrates in factory-fill pipelines.
Automotive Brake Fluid Market Segmentation
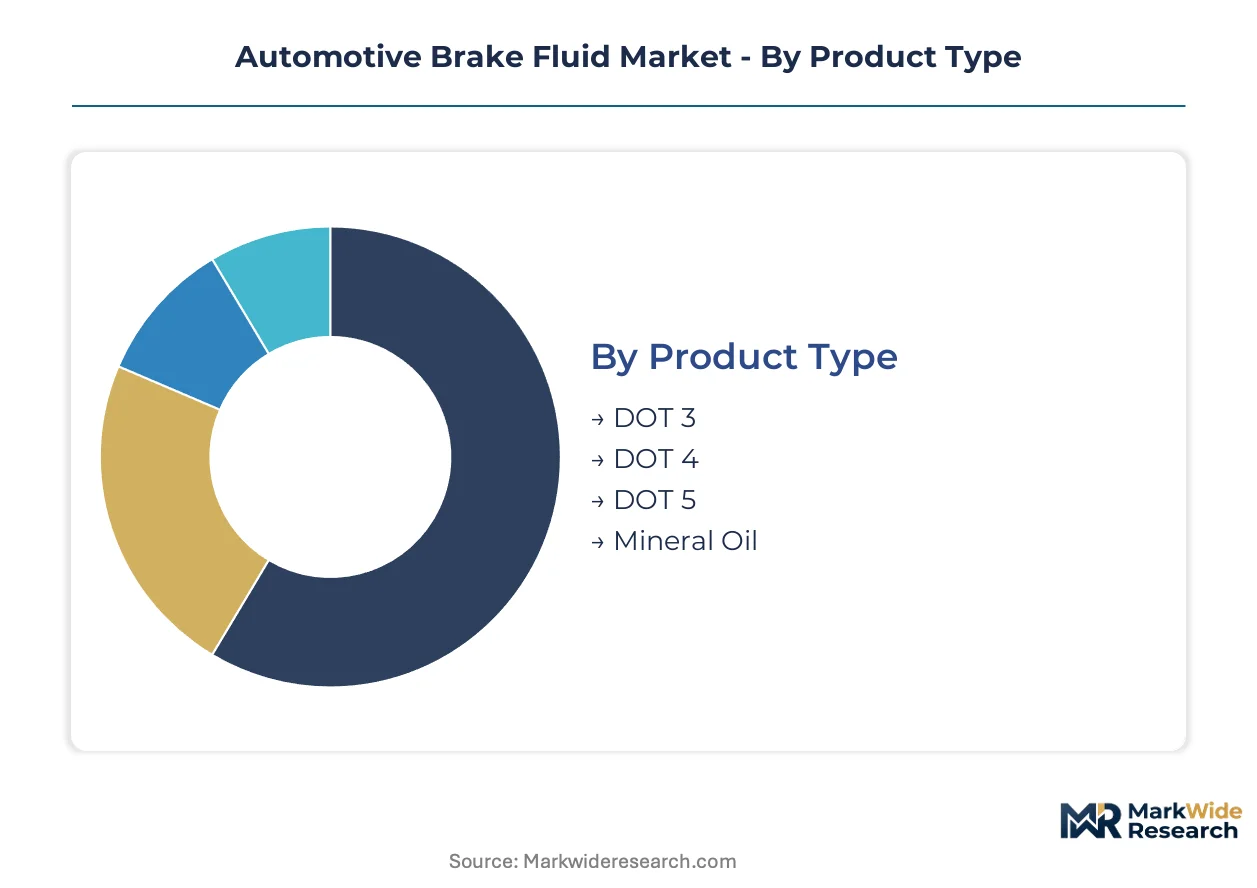
Automotive brake fluid segmentation tracks how formulation chemistry, vehicle architecture, and procurement channels split value pools across incompatible technical specifications. Each dimension carries distinct margin profiles and qualification barriers that determine supplier competitive position.
Product Type:
Supply concentration in synthetic base stocks and additive packages shapes competitive dynamics across specification tiers, with integrated producers capturing margin through captive glycol-ether production.
- DOT 4:Glycol-ether formulations with elevated wet-boiling-point thresholds above 155°C satisfy ABS-equipped platforms and extended service intervals. Demand concentrates in German and Chinese OEM factory-fill agreements where hydraulic complexity mandates premium synthetic chemistry. DOT 4 absorbs the bulk of installed capacity; DOT 5 is expanding most quickly.
- DOT 3:Lower-boiling-point glycol-ether blends serve legacy vehicle fleets and price-sensitive aftermarket channels. Volume concentrates in emerging market service stations where replacement intervals remain shorter and cost pressure dominates procurement decisions.
- DOT 5:Silicone-based formulations deliver moisture immunity for military and collector-vehicle applications with infrequent brake system use. Niche positioning prevents scale economies despite premium pricing power.
- Mineral Oil:Specialized formulations serve select European heavy-duty hydraulic brake architectures outside DOT regulatory scope. Limited OEM adoption constrains volume growth.
DOT 4 commands the dominant share of blending capacity investment; DOT 5 maintains the steepest premium positioning despite structural volume constraints.
End User:
Vehicle fleet composition determines thermal duty cycles and replacement velocity, with electrification reshaping fluid chemistry requirements across weight classes.
- Passenger Vehicles:Factory-fill specifications increasingly mandate low-conductivity synthetics for regenerative braking integration. Procurement concentrates in China's eastern manufacturing corridor where domestic OEMs localize fluid sourcing through captive blending plants.
- Commercial Vehicles:Heavy hydraulic loads and extended duty cycles demand enhanced oxidative stability and corrosion protection. Fleet operators in the United States accelerate replacement intervals under tightening FMVSS 116 wet-boiling-point enforcement.
- Motorcycles:Compact brake systems with exposed reservoir designs prioritize moisture resistance and rapid fluid exchange protocols. Aftermarket channels dominate procurement through specialized service networks.
- Heavy-Duty Trucks:Air-over-hybrid and full air brake architectures reduce hydraulic fluid volume per vehicle. Remaining hydraulic circuits in steering and auxiliary systems sustain niche demand.
Passenger vehicles anchor volume demand; commercial vehicles are climbing the fastest as fleet replacement mandates tighten.
Application:
Brake system architecture dictates fluid performance requirements, with electronic control integration elevating thermal and lubricity thresholds beyond mechanical braking specifications.
- Anti-lock Brake System:Rapid valve modulation cycles demand enhanced lubricity and low compressibility to prevent vapor lock under pulsed pressure conditions. OEM specifications in Germany and China pre-qualify fluids under draft ECE R90 protocols ahead of mandate implementation.
- Disc Brake:Open caliper designs expose fluid to higher thermal loads from rotor proximity. Performance vehicle segments drive synthetic formulation premiumization.
- Drum Brake:Sealed hydraulic circuits with lower thermal exposure sustain commodity glycol-ether economics. Emerging market commercial fleets retain drum architectures for cost containment.
- Power Brake:Vacuum-assisted and electric booster systems impose minimal additional fluid demands, tracking base brake system specifications.
ABS applications command the dominant technology investment; disc brake specifications are gaining share fastest as drum architectures decline.
Distribution Channel:
Channel structure determines margin capture timing, with direct OEM procurement compressing traditional aftermarket intermediaries through bilateral supply agreements.
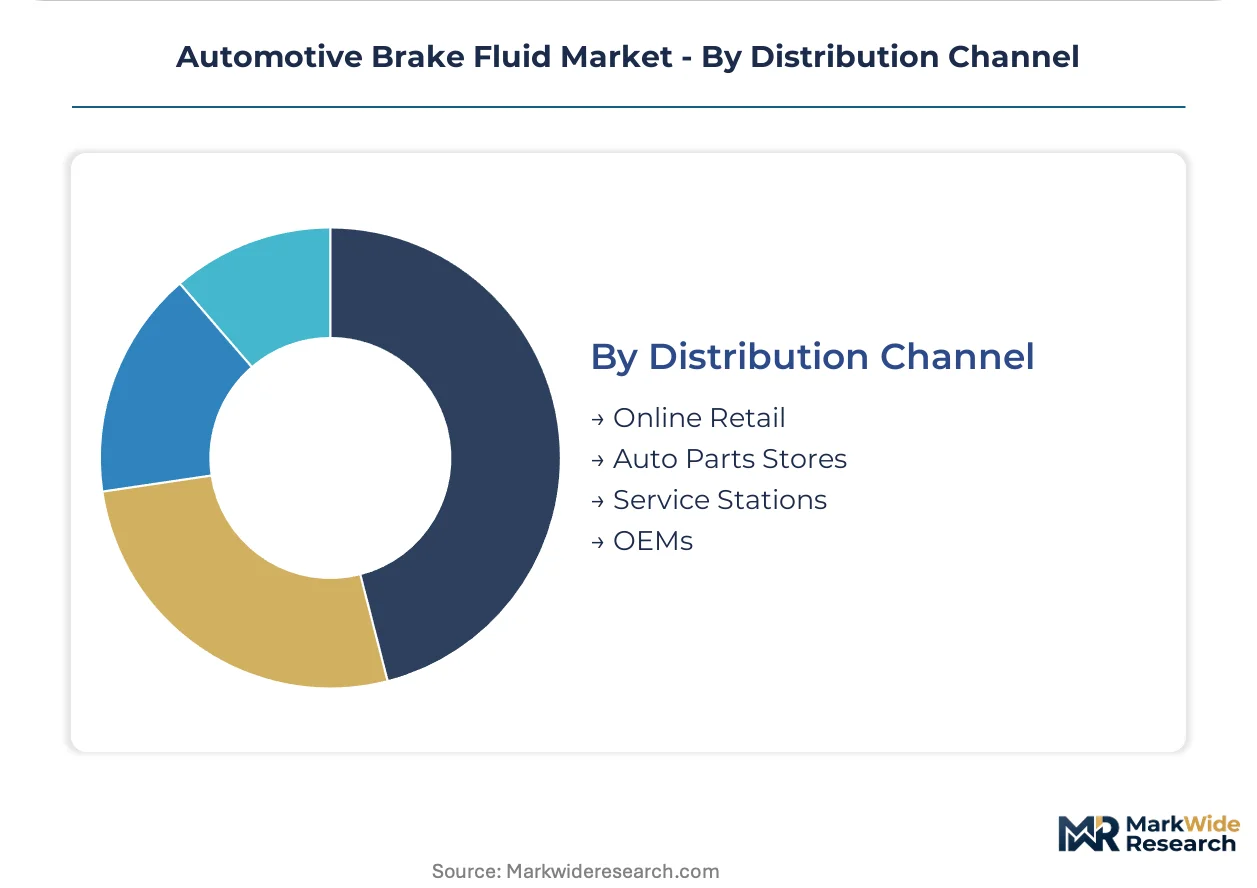
- OEMs:Factory-fill contracts lock in multi-year supply agreements with integrated base-stock producers. China's domestic automakers now source 60-70 percent of brake fluid volume through direct procurement rather than distributor networks.
- Auto Parts Stores:Independent aftermarket channels compete on fill-and-drain velocity for routine maintenance intervals. Price transparency compresses margins on commodity DOT 3 and DOT 4 formulations.
- Service Stations:Quick-service networks capture replacement demand through bundled maintenance packages. Technician certification requirements create informal channel segmentation by service complexity.
- Online Retail:E-commerce platforms expand access to specialized formulations for enthusiast and collector segments. Logistics constraints limit bulk fluid economics relative to conventional channels.
OEM channels concentrate the highest margin pools; online retail is expanding most quickly as enthusiast procurement shifts digital.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province anchors brake fluid procurement concentration, where domestic OEMs operate captive blending plants adjacent to assembly corridors. Procurement localization across China's eastern manufacturing belt is compressing import dependency while reshaping regional supply configurations.
United States
Fleet operators accelerate replacement intervals under tightening NHTSA enforcement of FMVSS 116 wet-boiling-point thresholds. The Department of Transportation mandates stricter thermal performance verification for commercial vehicle hydraulic systems. Detroit's automotive corridor concentrates aftermarket distribution networks serving legacy and ABS-equipped platforms.
Germany
Premium automakers pre-qualify fluids under draft ECE R90 protocols ahead of corrosion-limit revisions. KBA oversight tightens copper-strip test tolerances for electrified brake-by-wire architectures. Baden-Württemberg's supplier ecosystem anchors factory-fill partnerships with integrated additive synthesis capabilities.
China
Domestic OEMs source 60-70 percent of brake fluid through direct procurement rather than distributor networks. GB 12981 standard compliance drives reformulation cycles for heavier electrified vehicles. Jiangsu province's manufacturing clusters localize fluid blending to reduce logistics costs and inventory cycles.
Japan
Automotive suppliers engineer low-conductivity formulations for regenerative braking integration in battery-electric platforms. METI guidelines influence thermal stability specifications for hybrid duty cycles. Nagoya's industrial corridor concentrates R&D facilities developing additive packages for electrified architectures.
Automotive Brake Fluid Market Vendor Landscape
Capital-heavy producers compete with asset-light formulators across distinct margin tiers. Integrated petrochemical majors control base-stock supply chains, while specialized blenders compete on additive-package differentiation. Three archetypes dominate: upstream-integrated majors with captive glycol-ether production, regional toll blenders serving aftermarket channels, and specialty formulators targeting EV-specific thermal profiles. Competitive dynamics center on factory-fill partnership anchoring and backward integration into corrosion-inhibitor synthesis.
Among upstream-integrated majors, Exxon Mobil Corporation exemplifies scale-driven positioning through base-stock supply control. TotalEnergies and FUCHS occupy distinct specialization vectors, with the former representing low-conductivity EV formulation capabilities and the latter anchoring premium German OEM factory-fill relationships. These three entities illustrate how competitive positioning stratifies across supply chain control, technical specialization, and channel access.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| TotalEnergies |
| BP p.l.c |
| FUCHS |
| Valvoline Inc. |
| Robert Bosch GmbH |
| Royal Dutch Shell plc |
| Castrol Limited |
| Chevron Corporation |
| Others |
Supply Flow & Price Mechanics
DOT 4-DOT 3 performance divergence creates a bifurcated cost structure where premium synthetic formulations command factory-fill premiums while commodity glycol-ether blends compete on spot-market velocity. This tier split manifests in procurement patterns: German and Chinese OEMs lock in multi-year supply agreements for high-wet-boiling-point specifications, while aftermarket channels in emerging markets transact on price-per-liter with minimal brand loyalty.
Pricing Analysis
Value-based pricing anchors on thermal performance certification tiers, with FMVSS 116 wet-boiling-point thresholds and ECE R90 corrosion ratings determining factory-fill premiums. Price differentiation separates low-conductivity EV formulations from standard glycol-ether blends, with additive-package complexity and oxidative stability driving tier separation. Cost compression in commodity DOT 3 segments intensifies as integrated majors leverage captive ethylene oxide supply. Fleet operators in the United States show highest price sensitivity for routine drain-and-fill services, while German premium automakers prioritize qualification reliability over unit cost.
Supply Chain Analysis
Glycol-ether feedstock supply rests on integrated petrochemical production in the United States, China, and Germany, where ethylene oxide and propylene oxide capacity concentration determines blending economics. Base-stock inputs, corrosion-inhibitor additive packages, and specialized low-conductivity synthetics constitute the three critical material dependencies. Single-source vulnerability in specialty additive synthesis constrains R&D throughput for electrified brake-by-wire formulations. Distribution runs through direct OEM procurement channels in China's eastern manufacturing corridor, compressing traditional aftermarket distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as regulatory qualification costs and captive blending investments force sub-scale toll blenders toward exit. FMVSS 116 and ECE R90 reformulation cycles favor integrated producers with in-house testing infrastructure.
For Market Incumbents: Anticipate margin compression in commodity DOT 3 segments by accelerating backward integration into corrosion-inhibitor synthesis. Lock in factory-fill partnerships with Chinese and German OEMs before ECE R90 implementation tightens qualification windows. Prioritize low-conductivity formulation capacity to capture EV regenerative braking specifications.
For New Entrants and Emerging Players: Low-conductivity synthetic formulations for battery-electric platforms offer the most penetrable white space, as incumbent majors remain anchored to legacy glycol-ether economics. Target aftermarket channels in China's Shandong and Jiangsu provinces where distributor disintermediation creates service-station procurement gaps. Lead with technical certification support bundled with fluid supply to differentiate from commodity blenders.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty formulators with EV-specific additive capabilities and captive testing infrastructure. Five-to-ten-year viability favors suppliers with bilateral OEM agreements rather than spot-market exposure. Watch GB 12981 reformulation announcements as the signal for accelerated procurement localization in China's eastern corridor.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Synthesis | Captive corrosion-inhibitor production locks in formulation differentiation against toll blenders. |
| Low-Conductivity Formulation Capacity Buildout | Dedicated EV fluid lines capture German and Chinese OEM factory-fill specifications ahead of mandate. |
| Captive Blending Facility Proximity | Adjacent plant locations in Shandong and Jiangsu reduce logistics costs and inventory cycles for domestic OEMs. |
| ECE R90 Pre-Qualification Investment | Early protocol compliance secures premium German automaker supply agreements before 2025-2027 implementation. |
| Direct OEM Procurement Partnership | Bilateral agreements displace distributor intermediaries, concentrating margin pools in factory-fill pipelines. |
Methodological Framework
Document review covered customs and trade flow data, SEC filings from petrochemical majors, and regulatory submissions to NHTSA and KBA, complemented by interviews with OEM brake system engineers, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and additive-package chemists. Secondary validation drew from vehicle production databases, IHS Markit registration data, and GB standard implementation notices. Bottom-up volume estimates triangulated against top-down petrochemical capacity assessments.
Cross-referencing historical replacement interval trends with expert panel input on electrification thermal profiles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include fluid specification tier, vehicle propulsion architecture, OEM versus aftermarket channel, and regional production cluster. CAGRs derived from production volume trajectories, content-per-vehicle assumptions, and service interval extension mandates. Industry-specific inputs incorporated FMVSS 116 enforcement intensity and ECE R90 draft protocol adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt glycol-ether feedstock price spikes or accelerated EV penetration beyond OEM platform roadmaps. Forecasts reflect documented assumptions on regulatory implementation timing and OEM localization decisions. A small set of triggers—GB 12981 revision announcements, NHTSA enforcement memos, and German OEM factory-fill requalification cycles—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Lifts Market
Automotive Parts
Canada Automotive Parts Die Casting Market
Automotive Parts
Oil Catch Cans Market
Automotive Parts
Automotive Axle and Propeller Shaft Market
Automotive Parts
Automotive Central Lubrication System Market
Automotive Parts
Global Automotive Timing Belt Market
Automotive Parts
Germany Automotive Parts Aluminium Die Casting Market
Automotive Parts
Auxiliary Oil Cooler Market
Automotive Parts
India Brake Pads Market
Automotive Parts
Resin Silencer Market
Automotive Parts
Automotive Thermal Management Systems for Electric Vehicles Market
Automotive Parts
Automotive Exhaust System Market
Automotive Parts
Argentina Automotive Actuators Market
Automotive Parts
Global Automotive Flywheel Market
Automotive Parts
Global Automotive Gasoline Particulate Filter (GPF) Market
Automotive Parts
Europe Passenger Vehicles Lubricants Market