
 Mechanical Control Cables Market | 2026-2036
Mechanical Control Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Mechanical Control Cables Market Analysis
Maintenance and overhaul service contracts are decoupling pure hardware sales from long-term revenue streams across the mechanical control cables sector. Triumph Group leverages captive MRO networks to sustain aftermarket attachment rates on military actuator lines. Curtiss-Wright Corporation anchors North American defense demand through proprietary cable assembly protocols for rotary-wing platforms. Elliott Manufacturing specializes in custom push-pull configurations for off-highway equipment, competing on engineering response speed rather than unit cost.
Mechanical control cables are flexible or rigid force-transmission elements, typically constructed from stranded stainless steel or carbon steel wire encased in nylon or PVC conduits, designed to relay linear or rotary motion between operator input and controlled mechanisms. They serve as critical linkage components in environments where electronic actuation faces reliability constraints from electromagnetic interference, temperature extremes, or fail-safe redundancy requirements. Push-pull cables occupy the dominant share of aerospace and industrial applications due to their bidirectional load capacity and sealing adaptability. Bowden cables retain strong positions in automotive throttle and brake systems where cost-efficient rotary-to-linear conversion remains essential. Stainless steel material grades command premium positioning in marine and corrosive-environment deployments where salt spray resistance and fatigue life determine replacement cycles.
FAA airworthiness standards and EASA CS-25 certification frameworks mandate dual-mechanical backup channels for flight-critical controls, preserving baseline demand even as fly-by-wire systems advance. EPA emissions enforcement and NHTSA functional safety requirements in the United States sustain mechanical throttle cable specifications in commercial vehicle categories where electronic migration proceeds gradually. Stakeholders must monitor regulatory divergence between FAA and EASA on cable fatigue testing protocols, as harmonization gaps will shape qualification costs and supplier eligibility across transatlantic programs.
Market Dynamics
Fly-by-wire redundancy mandates are preserving mechanical control cable demand even as primary flight controls electrify, creating a bifurcated procurement environment where legacy mechanical systems coexist with emerging electronic architectures across aerospace platforms.
Growth Catalysts
- FAA-EASA harmonization pressure:Dual-certification requirements for flight-critical backup systems are expanding addressable market scope for qualified cable assemblies serving transatlantic aerospace programs.
- Stainless steel grade advancement:Enhanced fatigue-life alloys are extending replacement intervals in marine and offshore deployments where corrosion resistance determines total cost of ownership.
- Defense platform modernization:Rotary-wing and tactical vehicle procurement cycles are sustaining demand for push-pull configurations with battlefield-hardened sealing specifications.
Market Restraints
- Specialized steel input volatility:Stranded wire rod pricing fluctuations compress margin stability for manufacturers lacking long-term metallurgical supply agreements.
- Regional supplier concentration:Precision manufacturing clusters in southern Germany create geographic vulnerability for European automotive and aviation supply chains.
- Electronic actuation substitution:Solid-state motor controllers are displacing mechanical throttle linkages in passenger vehicle segments where cost reduction outweighs redundancy requirements.
Strategic Opportunities
- Urban air mobility emergence:eVTOL developers require mechanical backup channels for piloted and autonomous flight configurations, opening new specification categories.
- Remanufacturing service expansion:Circular economy directives in the European Union incentivize cable refurbishment programs that decouple revenue from virgin material throughput.
- Hybrid-electric propulsion integration:Powertrain architectures combining electric motors with mechanical governors create novel cable routing and load specification demands.
Industry Challenges
- Specialized technician scarcity:Precision cable assembly and terminal swaging skills are aging out of the workforce faster than vocational training programs replenish capacity.
- Qualification timeline compression:Accelerated aircraft development cycles strain traditional FAA certification protocols for mechanical control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mechanical Control Cables Market |
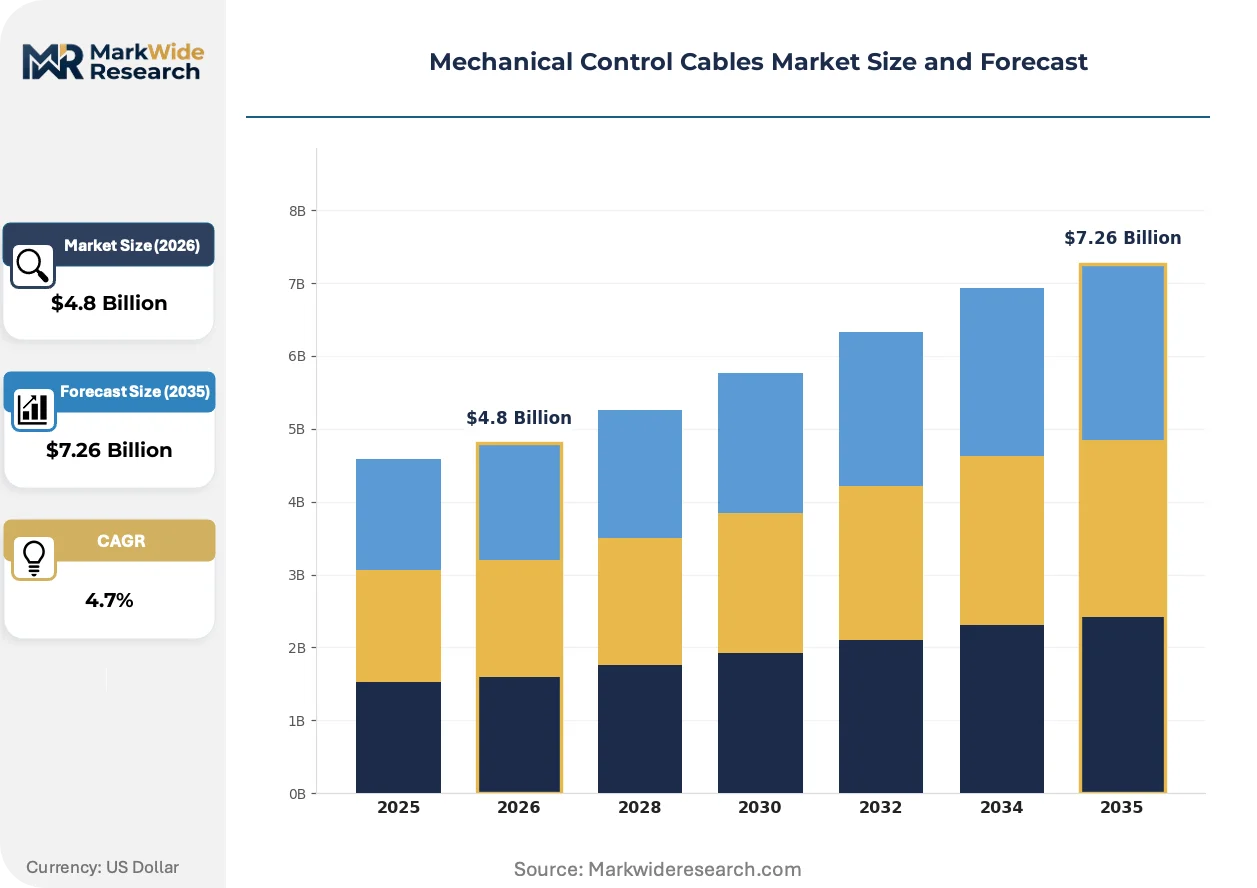
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Push-Pull Cables, Bowden Cables, Throttle Cables, Control Rods Application: Aerospace, Automotive, Marine, Industrial Machinery End User: Manufacturers, OEMs, Aftermarket, Repair Shops Material: Stainless Steel, Nylon, PVC, Copper |
| Companies Covered | Crane Aerospace & Electronics, Triumph Group, Elliott Manufacturing, Orscheln Products, Curtiss-Wright Corporation, Cablecraft Motion Controls, AeroControlex, TE Connectivity, Küster Holding GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mechanical Control Cables Market Emerging Trajectories
Material science advances and regulatory redundancy mandates are reshaping mechanical control cable specifications across aerospace, automotive, and industrial verticals. Three developments are restructuring competitive positioning and procurement patterns.
Carbon fiber reinforced polymer (CFRP) core cables are converging with traditional steel architectures to reduce weight in aerospace applications where every kilogram translates to fuel burn. Tier-1 suppliers are qualifying hybrid constructions for secondary flight control surfaces. This convergence is compressing the performance gap between mechanical backup systems and primary electronic actuators.
REACH substance restrictions are forcing reformulation of PVC and nylon conduit compounds used in cable jacketing across European supply chains. Manufacturers are accelerating bio-based polymer qualification to maintain CE marking eligibility. Automotive throttle cable producers serving export markets are dual-tracking material certifications to prevent market access disruption.
Aftermarket unbundling is separating hardware sales from inspection and replacement services across commercial aviation MRO networks. Airlines are negotiating flight-hour-based maintenance agreements that transfer inventory risk to cable suppliers. This shift is most visible in North American and Middle Eastern carrier procurement where fleet standardization enables volume service contracts.
Mechanical Control Cables Market Segmentation
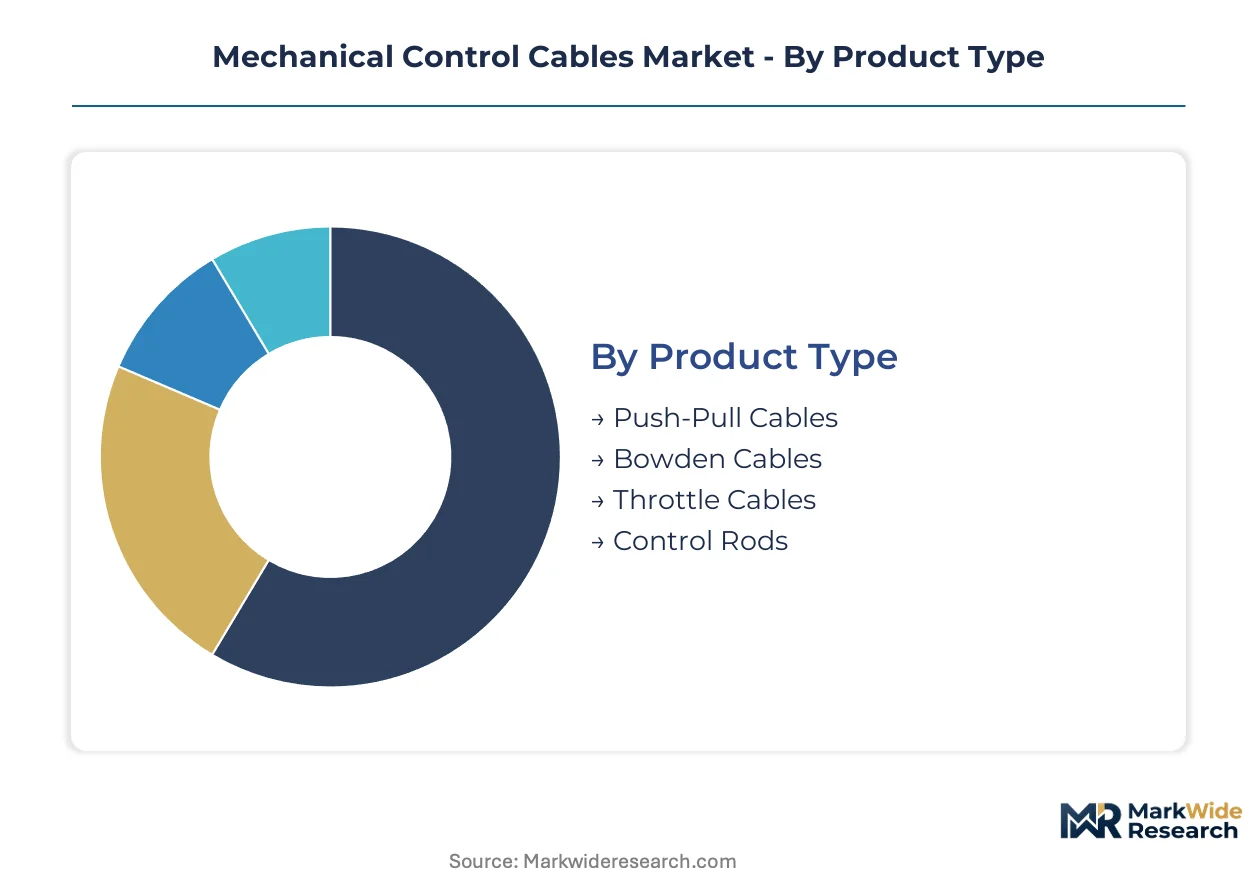
Mechanical control cable procurement varies sharply by performance specification, environmental exposure, and regulatory compliance tier. Buyers prioritize material grade and sealing architecture over unit cost in safety-critical applications, while cost sensitivity dominates in non-regulated industrial segments.
Product Type:
Application complexity and load directionality determine specification selection, with bidirectional force transmission commanding premium engineering margins.
- Push-Pull Cables:Stranded steel wire cores encased in sealed conduits enable linear force transmission in both tension and compression. Aerospace OEM procurement for flight control backup systems concentrates demand in Germany and the United States, where FAA-EASA dual certification requirements sustain premium pricing.
- Bowden Cables:Flexible steel cables sliding within stationary housings convert rotary motion to linear displacement. Automotive throttle and brake applications in Germany and Japan retain substantial volumes despite gradual electronic substitution in passenger vehicles.
- Throttle Cables:Specialized Bowden variants with temperature-resistant jackets maintain commercial vehicle demand under EPA emissions enforcement.
- Control Rods:Rigid linkages for precision positioning serve industrial automation and marine steering where deflection tolerance approaches zero.
Volume sits with Bowden Cables; growth tilts toward Push-Pull Cables.
Application:
Regulatory intensity and replacement cycle frequency create four distinct demand environments with divergent margin profiles.
- Aerospace:FAA airworthiness directives and EASA CS-25 certification frameworks mandate dual-mechanical backup channels for flight-critical controls. Fly-by-wire redundancy requirements preserve baseline demand even as primary systems electrify.
- Automotive:NHTSA functional safety requirements and EPA emissions standards sustain mechanical throttle specifications in commercial vehicle categories where electronic migration proceeds gradually.
- Marine:Salt spray exposure and fatigue life requirements favor stainless steel grades with extended replacement intervals.
- Industrial Machinery:Cost-driven procurement in non-regulated environments favors nylon and PVC conduit configurations with shorter service life expectations.
Revenue concentrates in Aerospace; expansion accelerates most quickly in Marine applications.
End User:
Procurement authority and inventory risk allocation distinguish four customer categories with opposing contract structures.
- Manufacturers:Tier-1 suppliers integrating cable assemblies into larger systems negotiate volume commitments with metallurgical supply agreements.
- OEMs:Original equipment manufacturers in aerospace and defense specify custom push-pull configurations with battlefield-hardened sealing requirements.
- Aftermarket:Airlines and fleet operators are shifting toward flight-hour-based maintenance agreements that transfer inventory risk to cable suppliers.
- Repair Shops:Fragmented demand for replacement cables in automotive and marine segments operates on spot purchasing with minimal brand loyalty.
Contract value aggregates with OEMs; margin expansion favors Aftermarket service bundling.
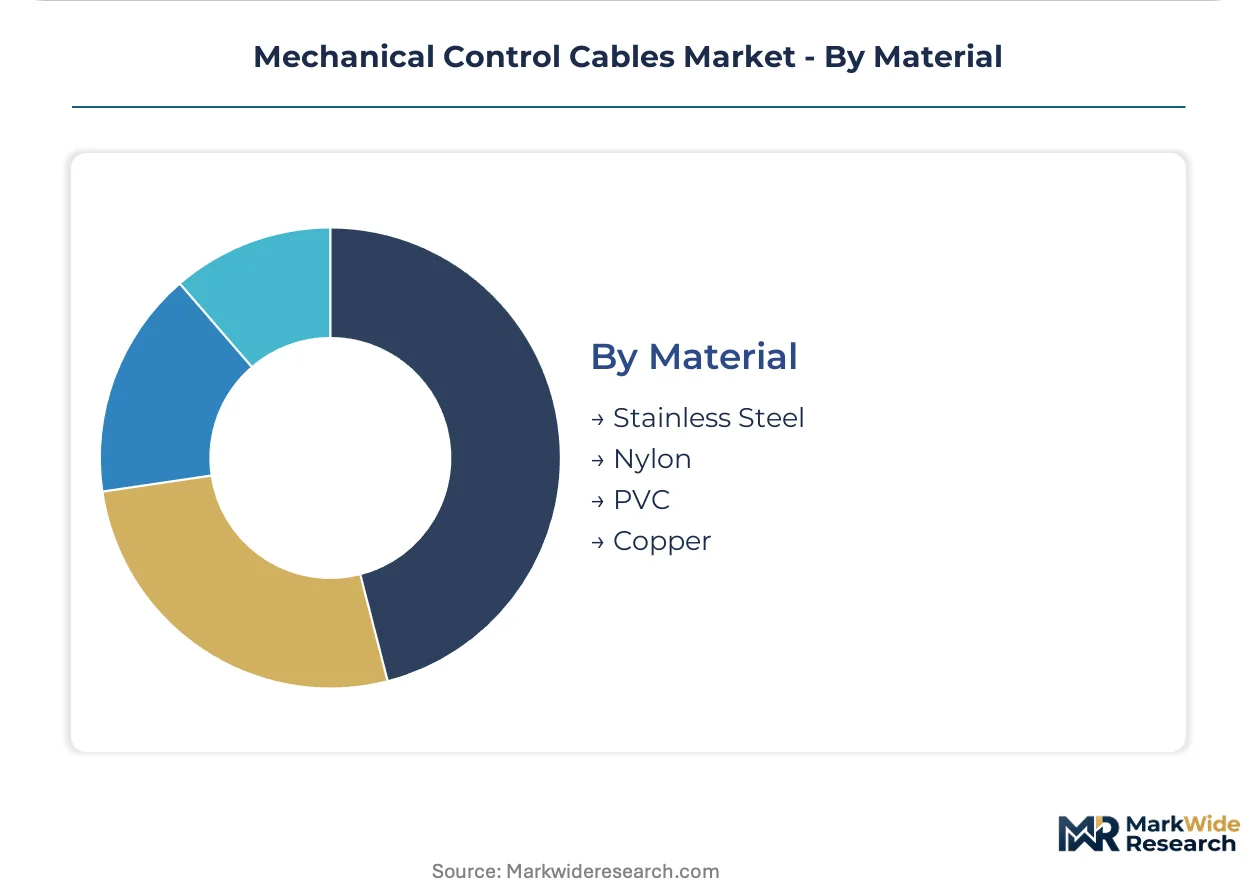
Material:
Corrosion resistance, fatigue life, and jacket flexibility requirements drive material selection with significant cost stratification.
- Stainless Steel:Austenitic and precipitation-hardened grades command premium positioning in marine and corrosive-environment deployments where salt spray resistance determines replacement cycles.
- Nylon:Lightweight jacketing compounds face REACH substance restriction pressures, forcing bio-based polymer qualification to maintain CE marking eligibility.
- PVC:Cost-efficient jacketing retains automotive throttle cable applications despite environmental regulatory headwinds in European supply chains.
- Copper:Specialized electrical-mechanical hybrid cables serve niche applications requiring conductivity alongside mechanical force transmission.
Stainless Steel dominates value capture; Nylon confronts steepest reformulation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and the United States while consumption spreads across aerospace hubs in France, Japan, and emerging defense markets. This geographic split creates trade flows of precision cable assemblies crossing regulatory jurisdictions with divergent certification protocols. Suppliers navigate FAA-EASA harmonization gaps while serving OEM procurement networks concentrated in specific industrial corridors.
Germany
Precision manufacturing clusters in Baden-Württemberg and Bavaria anchor European supply chains for automotive and aviation cable assemblies. REACH substance restrictions force rapid reformulation of PVC and nylon jacketing compounds to maintain CE marking eligibility. Stuttgart and Munich host Tier-1 supplier engineering centers where Küster Holding coordinates metallurgical sourcing agreements across the continent.
United States
FAA airworthiness directives sustain demand for dual-mechanical backup channels across commercial and defense platforms. NHTSA functional safety requirements preserve mechanical throttle specifications in commercial vehicle categories. Wichita, Kansas and the Connecticut aerospace corridor concentrate fabrication capacity serving Boeing and Lockheed Martin procurement programs.
France
Airbus supply chain integration drives specification development for fly-by-wire redundancy systems at Toulouse and Nantes manufacturing sites. EASA CS-25 certification frameworks mandate fatigue testing protocols that exceed FAA baselines in certain load cycle categories. The country's national aerospace regulator enforces cable assembly traceability standards that shape supplier qualification timelines.
Japan
Automotive OEM procurement from Toyota and Honda sustains Bowden cable volumes despite gradual electronic throttle migration. METI industrial standards govern precision terminal swaging tolerances for safety-critical applications. Nagoya and Osaka industrial zones concentrate stamping and wire-forming capacity serving domestic and Southeast Asian export markets.
United Kingdom
Defense platform modernization for rotary-wing aircraft sustains push-pull cable demand at BAE Systems supplier networks. The country's national aviation regulator maintains distinct fatigue testing documentation requirements that create qualification friction with FAA-accepted data packages. Midlands manufacturing corridors retain specialized terminal assembly skills amid broader industrial restructuring.
Mechanical Control Cables Market Vendor Landscape
Top-tier vendors anchor aerospace and defense certification tiers, while mid-scale fabricators compete on engineering response speed for industrial and automotive segments. The market structures around three strategic archetypes: integrated systems houses with captive MRO networks, precision specialists focusing on custom push-pull configurations, and volume producers serving cost-sensitive automotive throttle applications. Competitive moves concentrate on backward integration into metallurgical supply agreements and geographic expansion through qualification transfers across FAA-EASA jurisdictions.
Within the integrated systems tier, Triumph Group and Curtiss-Wright Corporation exemplify vendors combining manufacturing scale with aftermarket service bundling. Elliott Manufacturing occupies a position among specialists competing on custom engineering velocity rather than unit cost. Küster Holding GmbH anchors European precision fabrication capacity. These three company structures represent distinct competitive vectors: service-integrated, engineering-responsive, and regionally concentrated manufacturing.
| Leading Market Players |
|---|
| Crane Aerospace & Electronics |
| Triumph Group |
| Elliott Manufacturing |
| Orscheln Products |
| Curtiss-Wright Corporation |
| Cablecraft Motion Controls |
| AeroControlex |
| TE Connectivity |
| Küster Holding GmbH |
| Others |
Supply Flow & Price Mechanics
Precision terminal swaging specialists in the English Midlands and southern Germany command wage premiums that compress margin spreads between aerospace-grade stainless steel assemblies and commodity automotive Bowden cables. Labor-cost differentials between these certified technician clusters and emerging industrial zones in eastern Europe widen pricing-tier spreads across the mechanical control cables sector.
Pricing Analysis
Margin tightening in aerospace push-pull configurations reflects FAA-EASA dual-certification qualification costs and stainless steel grade premiums. Contract-based long-term offtake dominates OEM procurement, with price differentiation hinging on certification tier and after-sales service bundling. Cost-down pressure on automotive throttle cables accelerates because electronic throttle substitution shrinks addressable volume. Fleet operators and repair shops exhibit highest price sensitivity; defense OEMs and commercial aviation MRO networks show lowest.
Supply Chain Analysis
Stranded stainless steel wire rod supply rests on German, Japanese, and South Korean metallurgical producers with precipitation-hardening capacity. Specialty polymer jacketing compounds and precision terminal fittings constitute critical component dependencies. Single-source vulnerability concentrates in southern Germany's precision manufacturing clusters, where REACH substance restrictions threaten material access. Distribution runs through Tier-1 supplier networks directly into aerospace and automotive OEM assembly plants, with aftermarket channels serving fragmented repair shop demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical control cables market consolidation accelerates as electronic actuation substitution and specialized technician scarcity force sub-scale fabricators toward exit or acquisition.
For Market Incumbents: Anticipate electronic throttle displacement in passenger vehicles by deepening captive MRO service networks that lock in aftermarket revenue streams. Pursue backward integration into stainless steel wire rod supply agreements to buffer metallurgical price volatility. Certification investment in FAA-EASA harmonized fatigue testing protocols defends position against emerging European specialists. For New Entrants and Emerging Players: Urban air mobility eVTOL developers represent the most penetrable white-space target, given their unmet demand for lightweight mechanical backup channels with novel load specifications. Marine stainless steel replacement intervals in corrosive environments offer second entry point with lower certification barriers. Go-to-market through engineering partnership rather than price competition, as custom push-pull configuration velocity trumps unit cost in aerospace procurement. For Investors and Strategic Acquirers: Re-rating potential sits with precision specialists possessing FAA-EASA dual-certification and captive technician training pipelines, given urban air mobility order flow as catalyst. Long-term viability favors acquisition targets with installed base attachment through flight-hour-based maintenance contracts. Watch eVTOL prototype flight test schedules as inflection indicator for mechanical backup channel specification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallurgical Supply | Captive stainless steel wire rod agreements insulate margin stability against rod pricing volatility. |
| Dual-Certification Investment | FAA-EASA harmonized qualification opens transatlantic aerospace procurement to qualified assemblers. |
| Flight-Hour Service Contract Expansion | Airline MRO bundling transfers inventory risk from carrier to supplier while locking recurring revenue. |
| eVTOL Specification Development | Urban air mobility backup channel demand creates novel cable routing and load category opportunities. |
| Technician Training Pipeline Construction | Precision swaging and terminal assembly skills scarcity makes captive workforce development a defensive moat. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with aerospace procurement managers, automotive Tier-1 supplier engineers, MRO service directors, and precision cable assembly technicians. FAA airworthiness directive databases, EASA certification registries, and stainless steel trade flow statistics provided demand-side validation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Data-stream reconciliation applied product-type, application, material grade, and end-user segmentation dimensions throughout the forecast period. CAGRs derived from elasticity-adjusted demand projections incorporating fly-by-wire penetration rates, defense platform modernization cycles, and REACH regulatory compliance costs. Stainless steel grade substitution patterns and aftermarket service contract attachment rates served as industry-specific forecast inputs.
Caveats apply where electronic actuation substitution acceleration, metallurgical supply disruption, or FAA-EASA harmonization delays could materially shift the outlook. Forecasts reflect documented assumptions on technician workforce replenishment and eVTOL commercialization timelines. A small set of named triggers—eVTOL first commercial flights, REACH substance restriction enforcement actions, and stranded wire rod price spikes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
UK Automotive Carbon Fiber Composites Market
Vehicle Components
Headlight Market
Vehicle Components
Idler Arm Market
Vehicle Components
Anchorage Connector Market
Vehicle Components
EGR Valve Market
Vehicle Components
Automotive Aftermarket Shock Absorbers Market
Vehicle Components
Airport Ground Support Vehicle Market
Vehicle Components
Bicycle Chain Tensioner Market
Vehicle Components
Bicycle Lights Market
Vehicle Components
Vehicle Trailer Hitch Market
Vehicle Components
Oil Filter Elements Market
Vehicle Components
Bicycle Chain Device Market
Vehicle Components
Global Fuel Tank and Delivery System Market
Vehicle Components
Europe Trailer Axle Market
Vehicle Components
Locomotive Pantographs Market
Vehicle Components
Air Suspension Market