
 Wheel Speed Sensor Market | 2026-2036
Wheel Speed Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Wheel Speed Sensor Market Analytics
Buyer concentration among Tier-1 suppliers is shifting as vehicle assemblers consolidate their vendor bases and demand direct sensor integration capabilities. Bosch leverages its integrated braking systems portfolio to anchor long-term supply contracts with European OEMs. Continental competes through in-house semiconductor capabilities that reduce dependency on external chip suppliers. Denso Corporation specializes in Hall Effect sensor architectures for hybrid powertrain applications across Asian vehicle platforms.
A wheel speed sensor detects rotational velocity at individual wheel positions through magnetic, optical, or inductive principles, typically operating within temperature ranges of minus forty to one hundred fifty degrees Celsius and generating pulse signals proportional to wheel rotation frequency for transmission to anti-lock braking and electronic stability control modules. Hall Effect Sensors dominate OEM fitments due to their immunity to electromagnetic interference and compatibility with silicon-based integration, while active sensor configurations are displacing passive designs in electric vehicle platforms where real-time wheel slip data feeds regenerative braking algorithms. Installation type segmentation reveals hub-mounted variants retain the largest volume share, though brake-mounted configurations are gaining ground in compact electric vehicle architectures seeking reduced unsprung mass.
NHTSA mandates electronic stability control on all light vehicles sold in the United States, directly specifying wheel speed sensor performance thresholds for system certification. ECE Regulation thirteen in Europe harmonizes braking system requirements across member states, while China's GB standards for commercial vehicle safety equipment accelerate domestic sensor qualification protocols. Stakeholders must monitor evolving functional safety standards under ISO 26262 as autonomous driving architectures demand higher-integrity wheel speed data for path-planning algorithms.
Market Dynamics
Passenger vehicle electrification is restructuring procurement relationships as OEMs consolidate sensor suppliers capable of direct integration with regenerative braking systems and autonomous driving architectures.
Growth Catalysts
- Electrification mandates:Germany and China have enacted aggressive vehicle electrification programs that mandate sensor architectures compatible with hybrid and battery-electric powertrains. Tier-1 suppliers are accelerating qualification of Hall Effect sensors for these platforms.
- Active sensor architectures:Active wheel speed sensors are displacing passive designs across electric vehicle platforms where real-time wheel slip data feeds regenerative braking algorithms and traction control systems.
- Functional safety requirements:ISO 26262 automotive safety integrity levels are mandating higher-integrity wheel speed data for path-planning modules in autonomous driving systems, expanding sensor specification requirements.
Market Restraints
- Semiconductor supply concentration:Hall Effect sensor production depends on silicon wafer supply chains concentrated in East Asian foundries, creating vulnerability to geopolitical disruptions and capacity constraints.
- Raw material cost volatility:Neodymium and other rare earth elements essential for magnetic sensing elements face price instability tied to Chinese export policy fluctuations.
- Passive sensor substitution:Legacy passive inductive sensors retain cost advantages in emerging market commercial vehicle segments, slowing premium sensor adoption in price-sensitive applications.
Strategic Opportunities
- India commercial vehicle safety expansion:India's BIS certification requirements for commercial vehicle braking systems are accelerating domestic sensor qualification protocols, creating entry points for qualified suppliers.
- Sensor-fusion integration:Convergence of wheel speed data with lidar and radar inputs for autonomous driving architectures is creating demand for multi-protocol sensor modules with standardized outputs.
- Aftermarket channel digitization:E-commerce platforms for automotive replacement parts are disintermediating traditional distributor networks in North American and European repair markets.
Industry Challenges
- Embedded software expertise gaps:Sensor manufacturers face acute shortages of firmware engineers capable of developing ASIL-compliant signal processing algorithms for functional safety certification.
- Legacy system integration complexity:Retrofitting active sensor architectures into existing ABS and ESC platforms requires extensive recalibration of control module parameters, extending development timelines.
- IP fragmentation in magnetic sensing:Patent thickets around Hall Effect signal conditioning circuits are creating licensing complexity for new entrants seeking to compete with established semiconductor suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheel Speed Sensor Market |
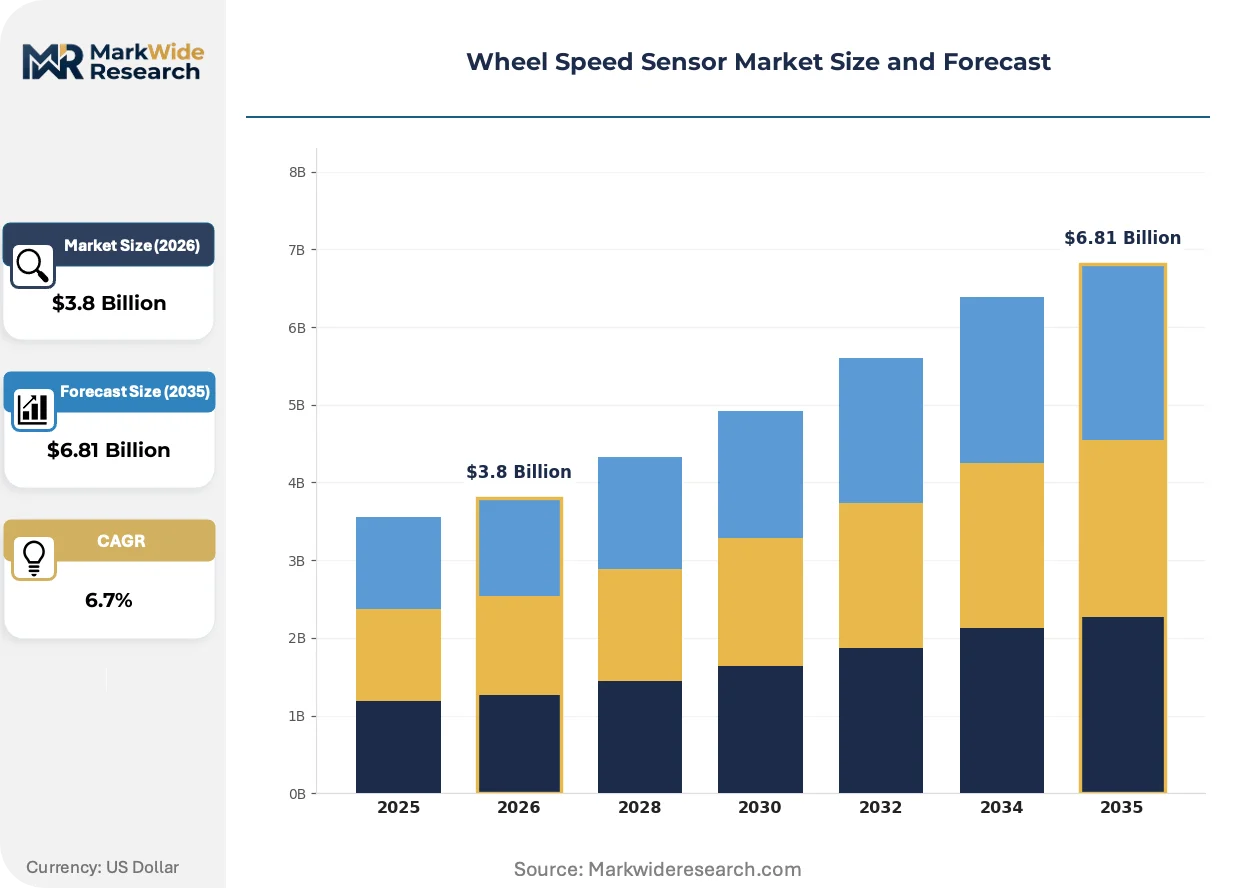
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Sensors, Optical Sensors, Hall Effect Sensors, Inductive Sensors Technology: Active Sensors, Passive Sensors, Analog Sensors, Digital Sensors End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation Type: Hub-Mounted, Brake-Mounted, Transmission-Mounted, Chassis-Mounted |
| Companies Covered | Hella, Hitachi Metals, Bosch, TE Connectivity, WABCO, Continental, Denso Corporation, NTN, ZF Friedrichshafen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheel Speed Sensor Market Evolving Landscape
Silicon integration and magnetic sensing advances are compressing sensor form factors while expanding data output capabilities for next-generation vehicle control systems.
Integrated magnetic sensing arrays are automating wheel speed detection through monolithic Hall Effect chips that combine sensing elements, analog-to-digital conversion, and digital signal processing in single packages. European and Asian OEMs are specifying these devices for 2027 platform launches to reduce wiring harness complexity. This integration is automating the elimination of external signal conditioning modules, collapsing tier counts in sensor supply chains.
ECE Regulation thirteen harmonizes braking system requirements across European member states, mandating minimum wheel speed sensor performance thresholds for electronic stability control certification. The regulation's test protocols specify electromagnetic immunity standards that favor active sensor architectures over legacy passive designs. German and French vehicle assemblers are responding by pre-qualifying only Hall Effect-based suppliers for 2026 platform awards.
Consolidated vendor sourcing is compressing supplier lists as vehicle assemblers reduce their Tier-1 sensor procurement relationships from multiple vendors to single-source or dual-source arrangements. Direct sensor integration capabilities—combining mechanical packaging with control module communication—are displacing component-only suppliers in European and North American OEM qualification processes. This concentration is most visible in Germany's automotive manufacturing clusters, where Bosch and Continental have secured multi-year supply agreements through integrated braking system portfolios.
Wheel Speed Sensor Market Segmentation
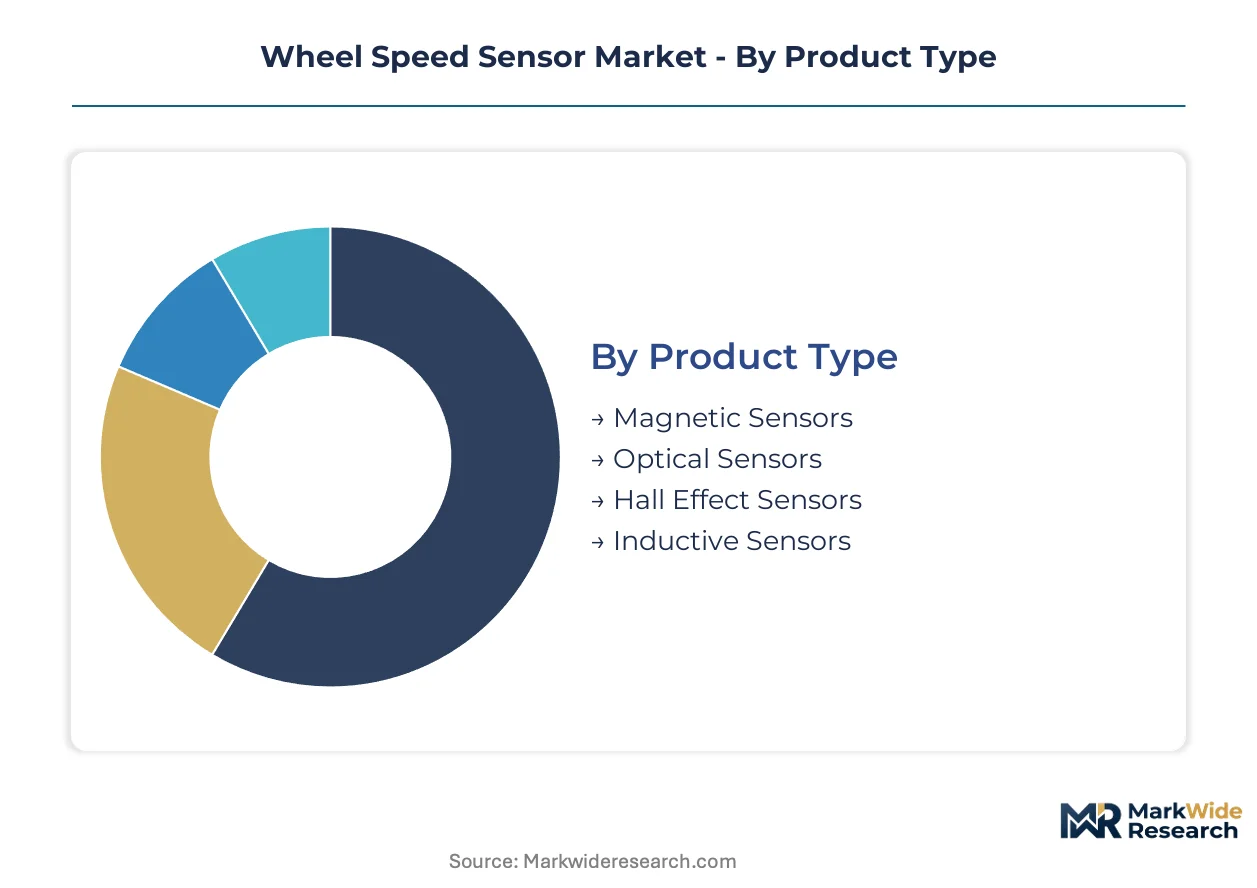
Wheel speed sensor procurement patterns diverge sharply across sensing technologies and installation architectures. Tier-1 suppliers and OEMs prioritize different performance specifications, creating distinct competitive arenas within each segment category.
Product Type:
Buyers differentiate primarily by electromagnetic immunity requirements and silicon integration feasibility for their target vehicle platforms.
- Hall Effect Sensors:These sensors leverage semiconductor-based magnetic field detection to deliver pulse signals immune to electrical interference. German and Chinese electrification programs specify Hall Effect architectures for regenerative braking compatibility, displacing legacy alternatives in premium vehicle segments.
- Inductive Sensors:Operating through electromagnetic induction between toothed tone wheels and sensing coils, these devices dominate cost-sensitive commercial vehicle applications. India's BIS certification protocols for heavy-duty braking systems sustain procurement volumes for inductive variants in domestic truck manufacturing.
- Magnetic Sensors:General-purpose magnetic sensing elements serve auxiliary wheel speed detection in non-critical chassis monitoring applications.
- Optical Sensors:Photoelectric detection principles find limited adoption in specialized motorsport and research vehicle platforms requiring ultra-high resolution.
Hall Effect Sensors lead volumes today; Optical Sensors are gaining share fastest in niche performance applications.
Technology:
Architecture selection hinges on real-time data processing requirements and integration complexity with electronic control modules.
- Active Sensors:Self-powered designs incorporating internal signal conditioning electronics feed digital wheel speed data directly to ABS and ESC modules. Active architectures are displacing passive alternatives across electric vehicle platforms where regenerative braking algorithms demand continuous slip monitoring.
- Digital Sensors:Binary output formats eliminate analog-to-digital conversion latency in autonomous driving path-planning systems. Japanese OEMs specify digital interfaces for sensor-fusion architectures combining wheel speed with lidar inputs.
- Passive Sensors:Simple inductive coils generating alternating voltage signals retain cost advantages in emerging market commercial fleets.
- Analog Sensors:Continuous voltage output variants persist in legacy ABS retrofit applications and aftermarket replacement channels.
Active Sensors command the largest installed base; Digital Sensors are expanding most quickly in next-generation autonomous platforms.
End User:
Procurement authority concentrates differently across direct vehicle manufacturing versus component system integration.
- Tier-1 Suppliers:Bosch, Continental, and Denso dominate sensor sourcing decisions through integrated braking system portfolios. These suppliers qualify Hall Effect and active sensor architectures for multi-year OEM supply contracts spanning German and Asian vehicle platforms.
- OEMs:Direct manufacturer procurement is accelerating as vehicle assemblers consolidate vendor bases and demand sensor-to-control-module integration capabilities. European OEMs now pre-qualify only suppliers offering combined mechanical packaging with digital communication protocols.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations source sensors through Tier-1 specified bill-of-materials with limited direct procurement autonomy.
- Aftermarket Providers:E-commerce platforms and traditional distributor networks serve replacement demand in North American and European repair markets.
Tier-1 Suppliers control the largest procurement volumes; OEM direct sourcing is climbing the fastest as vendor consolidation accelerates.
Installation Type:
Mounting location selection trades off unsprung mass reduction against signal accuracy and service accessibility.
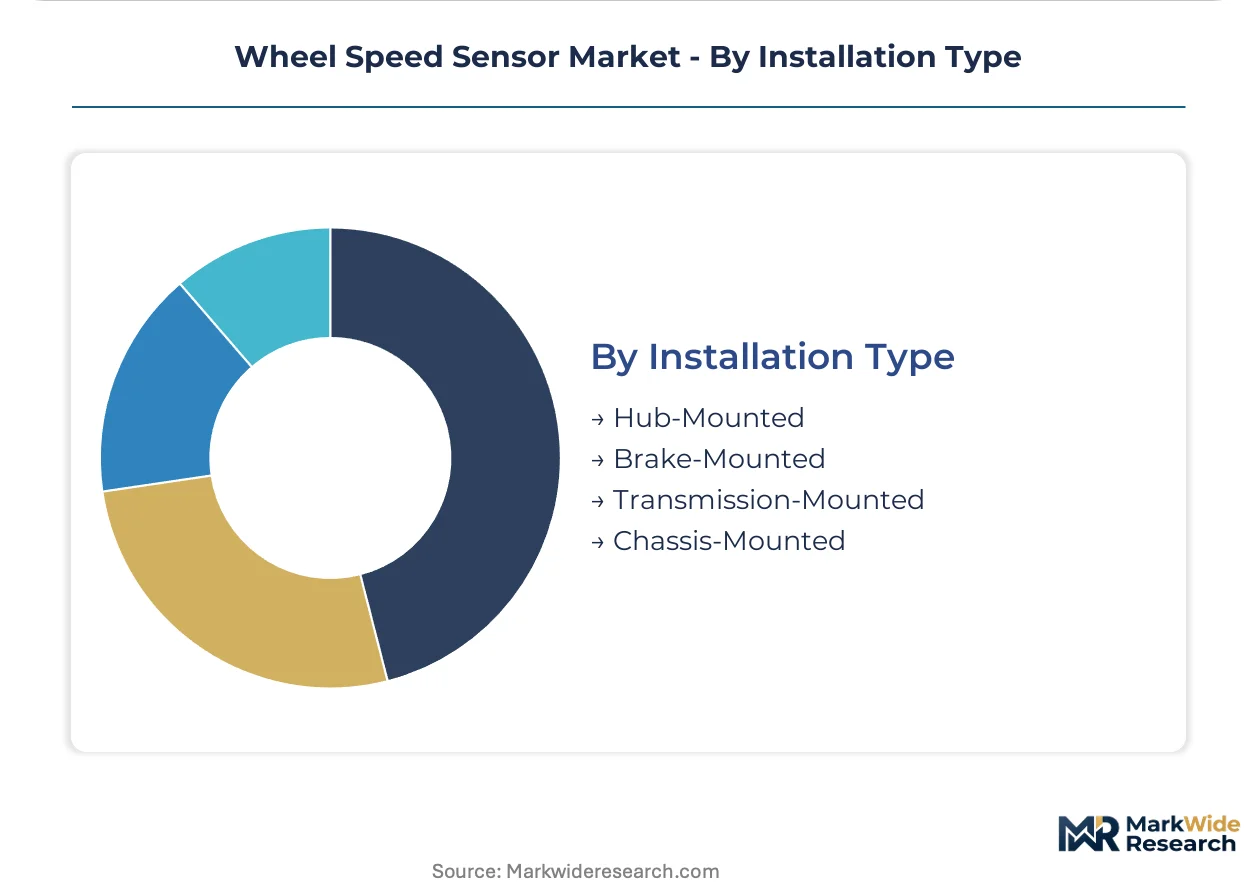
- Hub-Mounted:Direct integration into wheel bearing assemblies delivers the most accurate rotational velocity measurement for ABS and ESC systems. Hub-mounted configurations retain dominant volume share across German and Japanese passenger vehicle manufacturing clusters.
- Brake-Mounted:Proximity mounting to brake rotors enables compact packaging in compact electric vehicle architectures seeking reduced unsprung mass. Chinese EV manufacturers specify brake-mounted variants for urban mobility platforms.
- Transmission-Mounted:Driveshaft speed detection serves all-wheel-drive torque vectoring applications and transfer case control systems.
- Chassis-Mounted:Frame-integrated sensing supports commercial vehicle stability monitoring and trailer braking synchronization.
Hub-Mounted sensors lead volumes today; Brake-Mounted configurations are gaining share fastest in electric vehicle architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive engineering talent clusters in Germany, Japan, and the United States anchor sensor development capabilities, while manufacturing scale concentrates in China's industrial corridors and India's emerging commercial vehicle hubs.
Germany
NHTSA-equivalent KBA mandates electronic stability control certification thresholds that specify Hall Effect sensor performance for OEM homologation. The country's dual carbon goals accelerate electrification procurement from integrated braking system suppliers. Stuttgart and Munich manufacturing clusters host Tier-1 development centers where Bosch and Continental anchor multi-year supply contracts.
China
GB standards for commercial vehicle safety equipment and passenger vehicle electrification programs drive sensor qualification at domestic OEMs. MIIT regulations harmonize braking system architectures across state-owned and private vehicle assemblers. Shanghai and Guangzhou automotive corridors concentrate procurement decisions for Hall Effect and active sensor configurations in battery-electric platforms.
United States
NHTSA mandates electronic stability control on all light vehicles, directly specifying wheel speed sensor performance thresholds for system certification. The IRA's clean vehicle credits accelerate domestic EV manufacturing scale-up. Detroit and Southeast automotive clusters concentrate Tier-1 supplier engineering resources for integrated ABS and ESC module development.
Japan
METI industrial policy supports hybrid powertrain sensor development through JIS standard harmonization with international functional safety protocols. Denso Corporation anchors Hall Effect specialization for Asian vehicle platforms. Nagoya and Tokyo metropolitan manufacturing zones concentrate precision sensor fabrication for export-oriented OEM supply chains.
India
BIS certification requirements for commercial vehicle braking systems accelerate domestic sensor qualification protocols for heavy-duty truck manufacturers. The PLI scheme for automotive components attracts Tier-1 supplier localization investments. Pune and Chennai industrial corridors concentrate brake system integration capacity for domestic and export market supply.
Wheel Speed Sensor Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across sensor architecture development and braking system integration. The vendor base organizes around three strategic archetypes: integrated system suppliers with captive semiconductor capabilities, component specialists with magnetic sensing IP, and diversified automotive electronics conglomerates with multi-product portfolios. Capacity expansion and strategic partnerships dominate competitive moves as suppliers position for electrification-driven procurement consolidation.
Among German-based integrated system suppliers, Bosch and Continental exemplify the diversified conglomerate archetype with braking system portfolios spanning sensor-to-control-module integration. Denso Corporation represents the Asia-focused specialist tier with concentrated expertise in Hall Effect architectures for hybrid and electric powertrain applications. These three anchors occupy positions across the supplier consolidation spectrum as OEMs reduce vendor bases and demand direct integration capabilities.
| Leading Market Players |
|---|
| Hella |
| Hitachi Metals |
| Bosch |
| TE Connectivity |
| WABCO |
| Continental |
| Denso Corporation |
| NTN |
| ZF Friedrichshafen |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between ASIL-D qualified Hall Effect sensors and commodity inductive variants manifests in divergent pricing power and supply chain sourcing strategies. European OEMs pre-qualifying only Hall Effect suppliers for ESC certification concentrate procurement among semiconductor-integrated Tier-1s, while Indian commercial vehicle assemblers sustain parallel sourcing channels for cost-optimized passive alternatives.
Pricing Analysis
Capacity additions in China's automotive corridors are reshaping price floors for standard-grade wheel speed sensors as domestic foundries expand silicon wafer output. Three-tier pricing structure across premium, standard, and economy levels reflects ASIL certification grade, volume scale, and after-sales bundling intensity. Cost compression in economy-tier inductive sensors intensifies because of Indian BIS certification timelines compressing supplier margins. Fleet operators in emerging markets exhibit highest price sensitivity; German OEMs demonstrate lowest sensitivity due to functional safety liability exposure.
Supply Chain Analysis
Dual-sourcing requirements from Bosch and Continental mandate multi-supplier qualification for Hall Effect die production across Taiwan, South Korea, and Germany. Raw material flows draw from Chinese rare earth processing for magnetic elements, Japanese precision substrate manufacturing, and German automotive-grade packaging. Single-source vulnerability concentrates in East Asian foundry capacity for signal conditioning ASICs. Distribution runs through Tier-1 braking system integrators directly to OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory value through NHTSA's electronic stability control mandate, which permanently embeds wheel speed sensors in light vehicle homologation pathways.
For Market Incumbents: To counter semiconductor supply concentration risks, Bosch and Continental should anchor captive wafer supply through backward integration into German and Asian foundry partnerships, while accelerating ASIL-D certification investments to lock out commodity sensor competitors from premium platform awards. For New Entrants and Emerging Players: Capture India's BIS certification acceleration for commercial vehicle braking systems by establishing Pune or Chennai-based testing partnerships, targeting fleet operator price sensitivity through inductive sensor qualification at 30-40% below Hall Effect landed cost. For Investors and Strategic Acquirers: Consolidation pressure builds where embedded software expertise gaps exceed functional safety certification demand, favoring acquisition of firmware engineering boutiques with ISO 26262 track records over pure hardware component specialists. The signal to watch is Tier-1 supplier qualification list compression rates in German and Chinese OEM sourcing decisions.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Locks out commodity competitors from European ESC platform sourcing decisions. |
| Silicon Foundry Partnership | Reduces dependency on Taiwan wafer supply for Hall Effect signal conditioning chips. |
| India BIS Qualification Protocol | Opens commercial vehicle aftermarket channel for cost-optimized inductive variants. |
| Sensor-Fusion Module Development | Captures autonomous driving architecture procurement through lidar integration capability. |
| Aftermarket E-Commerce Platform | Disintermediates traditional distributor networks in North American repair markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distribution heads, and semiconductor foundry account managers with secondary validation against NHTSA homologation databases, ECE Regulation 13 compliance filings, vehicle production registries, and SEC 10-K disclosures from listed automotive electronics suppliers. Bottom-up sensor shipment estimates and top-down braking system market sizing were triangulated for convergence.
Segment-weighting applied propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster dimensions across the analysis window. CAGRs derived from regression modeling against electrification program timelines and regulatory mandate phase-in schedules. Forecast inputs included IHS Markit vehicle registration trajectories and MIIT battery-electric production targets.
Semiconductor supply disruptions, rare earth export policy shifts, and autonomous driving timeline accelerations are the dominant revision risks to modeled sensor demand. Deviation in ISO 26262 functional safety adoption rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Saudi Arabia Refrigerated Trailer Market
Vehicle Components
Italy Automotive Composites Market
Vehicle Components
Electric Wheelchair Market
Vehicle Components
Mobile Liquid Tanks Market
Vehicle Components
Steering Column Module Market
Vehicle Components
Intelligent Rubber Tracks Market
Vehicle Components
Mechanical Control Cables Market
Vehicle Components
Motorcycle Connectors Market
Vehicle Components
Electric Vehicles Component Market
Vehicle Components
Steer-by-Wire Road Wheel Actuator Modules Market
Vehicle Components
Charge Air Coolers Market
Vehicle Components
RV Battery Market
Vehicle Components
Railway Brake Pads Market
Vehicle Components
China Automotive Carbon Fiber Composites Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
Off-Highway Diesel Engine Market