
 Vehicle-To-X Products Market | 2026-2036
Vehicle-To-X Products Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle-To-X Products Market Analytics
China is narrowing its V2X module supply gap through domestic 5G base station co-deployment and automotive foundry partnerships. Qualcomm Technologies leverages its Snapdragon Automotive platform to dominate C-V2X chipset design for premium OEM programs. NXP Semiconductors anchors European supply security through its automotive-qualified DSRC and UWB portfolio. Continental specializes in integrated V2X roadside unit manufacturing for German autobahn digitization projects.
Vehicle-To-X products encompass onboard communication units, roadside infrastructure, and cloud-based management platforms that enable real-time data exchange between vehicles, infrastructure, pedestrians, and power grids, typically operating across 5.9 GHz ITS spectrum bands with sub-100 millisecond latency requirements. Their primary purpose centers on collision avoidance, traffic flow optimization, and bidirectional energy transfer in electrified transport networks. V2G applications within Energy Management command the deepest margin pools as utility-backed aggregation contracts monetize grid stabilization services. DSRC technology retains entrenched positions in North American safety-critical deployments while 5G cellular V2X captures the fastest expansion trajectory in Chinese and Korean smart city frameworks. Fleet Operators represent the most concentrated end-user investment channel as logistics operators quantify fuel and downtime reductions from predictive traffic routing.
FCC spectrum allocations for ITS services and NHTSA proposed connected-vehicle mandates shape North American hardware certification requirements and deployment timelines. ETSI standards in Europe and MIIT GB specifications in China create divergent compliance pathways that fragment module interoperability and raise engineering overhead for multi-region suppliers. Stakeholders must monitor regulatory convergence negotiations between regional standards bodies to anticipate whether unified V2X protocol frameworks emerge or parallel certification ecosystems persist.
Market Dynamics
The Vehicle-To-X Products Market is being fundamentally restructured by the coexistence of DSRC and C-V2X communication protocols, forcing suppliers to engineer dual-mode hardware architectures that satisfy divergent regional certification requirements without sacrificing unit economics.
Growth Catalysts
- NHTSA Connected-Vehicle Mandates:Proposed safety protocols in the United States are compressing DSRC module certification timelines and creating immediate procurement pull from automotive OEMs preparing for compliance deadlines.
- 5G Base Station Co-Deployment:China's MIIT GB specifications enable cellular V2X infrastructure to piggyback on existing telecommunications rollout, reducing standalone roadside unit capital requirements for municipal operators.
- Fleet Operator Aggregation Models:Logistics providers are deploying predictive traffic routing systems that monetize fuel and downtime reductions through real-time V2I data feeds.
Market Restraints
- Semiconductor Supply Concentration:Advanced V2X chipset fabrication remains concentrated in Germany, Japan, and South Korea, exposing module assemblers to geopolitical disruption and foundry allocation constraints.
- Spectrum Licensing Friction:Divergent FCC, ETSI, and MIIT allocations for 5.9 GHz ITS services force multi-region suppliers to maintain parallel hardware variants, inflating engineering overhead and inventory carrying costs.
- DSRC-C-V2X Protocol Uncertainty:The absence of unified global standards is delaying procurement decisions by risk-averse fleet operators awaiting regulatory clarity on technology obsolescence timelines.
Strategic Opportunities
- V2G Grid Stabilization Contracts:Utility-backed energy management platforms in electrified transport networks offer margin-rich aggregation services that monetize bidirectional power transfer from commercial EV fleets.
- Smart City Integration:Korean municipal frameworks are embedding C-V2X roadside units into urban digital infrastructure, creating bundled procurement channels that combine traffic management with public safety applications.
- UWB-Converged Positioning:The integration of ultra-wideband with V2X communication stacks is enabling centimeter-level pedestrian detection capabilities that differentiate premium safety modules.
Industry Challenges
- Multi-Protocol Firmware Complexity:Engineering teams must maintain simultaneous DSRC and C-V2X software stacks within single hardware units, straining embedded systems talent pools and extending validation cycles.
- Sub-100 Millisecond Latency Certification:Safety-critical deployment approvals require exhaustive real-world testing across variable radio propagation environments, creating bottlenecks at third-party validation laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle-To-X Products Market |
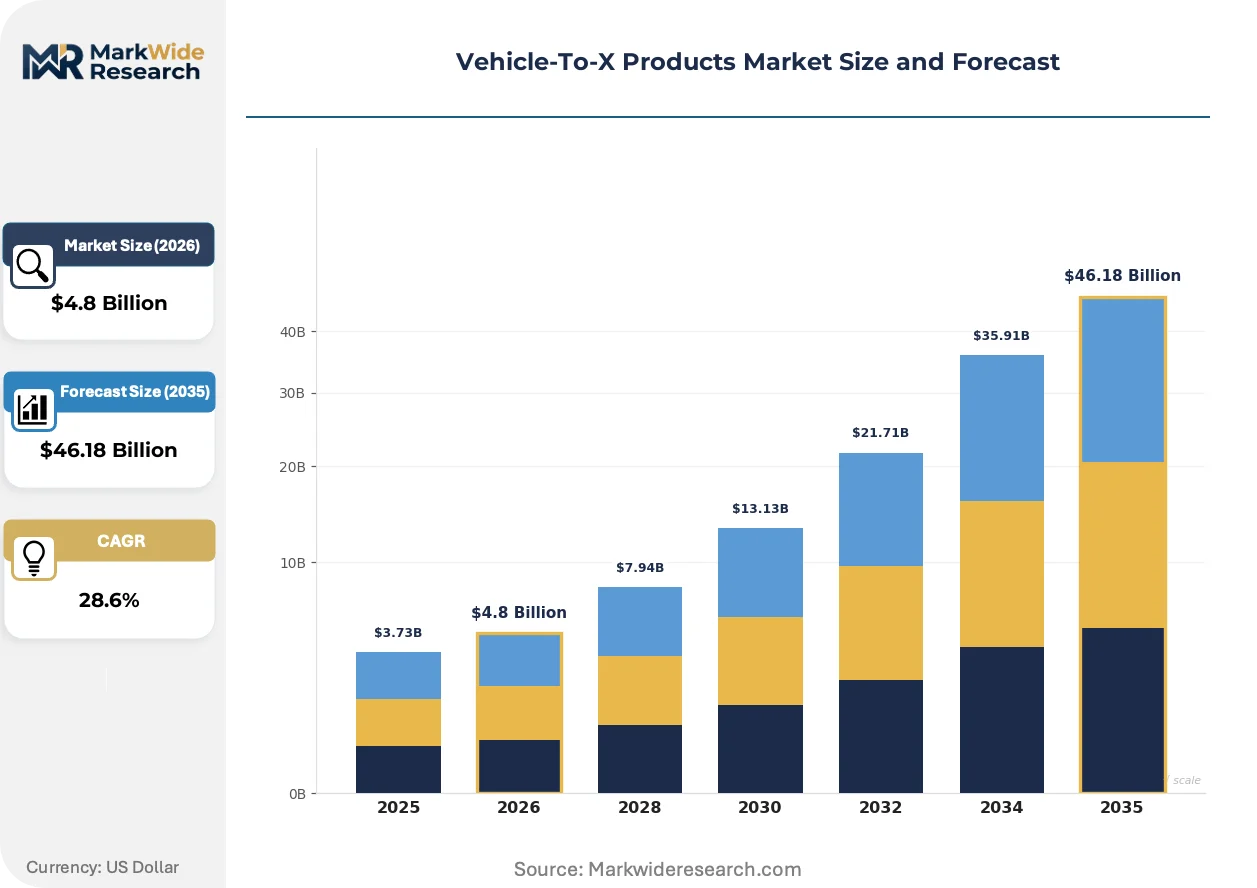
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: V2G, V2V, V2I, V2P Technology: Dedicated Short-Range Communications, LTE, 5G, DSRC Application: Smart Parking, Fleet Management, Traffic Management, Energy Management End User: OEMs, Transportation Authorities, Fleet Operators, Urban Planners |
| Companies Covered | Qualcomm Technologies, Autotalks, Continental, NXP Semiconductors, Infineon Technologies, Robert Bosch, Harman International, STMicroelectronics, Renesas Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle-To-X Products Market Evolving Landscape
Communication hardware architectures are converging around software-defined radio platforms that enable post-deployment protocol reconfiguration, reducing stranded asset risk for infrastructure investors facing uncertain regulatory outcomes.
Dual-mode V2X chipsets is hybridizing legacy DSRC compliance with C-V2X scalability in a single silicon package. Tier-1 suppliers are adopting these flexible architectures to hedge against regional standard divergence. The technology is compressing hardware lifecycle costs by eliminating the need for complete roadside unit replacement when jurisdictions switch protocol preferences.
ETSI's harmonized standards framework for cooperative intelligent transport systems is mandating interoperability testing across member states. The regulation is forcing module suppliers to maintain Brussels-based certification facilities. German autobahn digitization projects are experiencing accelerated procurement timelines as KBA-type approval pathways align with EU-wide mutual recognition principles.
Fleet procurement patterns are gravitating toward performance-based service contracts where V2X infrastructure providers guarantee specific traffic efficiency or safety outcome metrics. Municipal transportation departments are displacing traditional capital expenditure models with subscription-based roadside unit deployments. This shift is most pronounced in North American logistics corridors where private operators underwrite infrastructure costs in exchange for priority data access rights.
Vehicle-To-X Products Market Segmentation
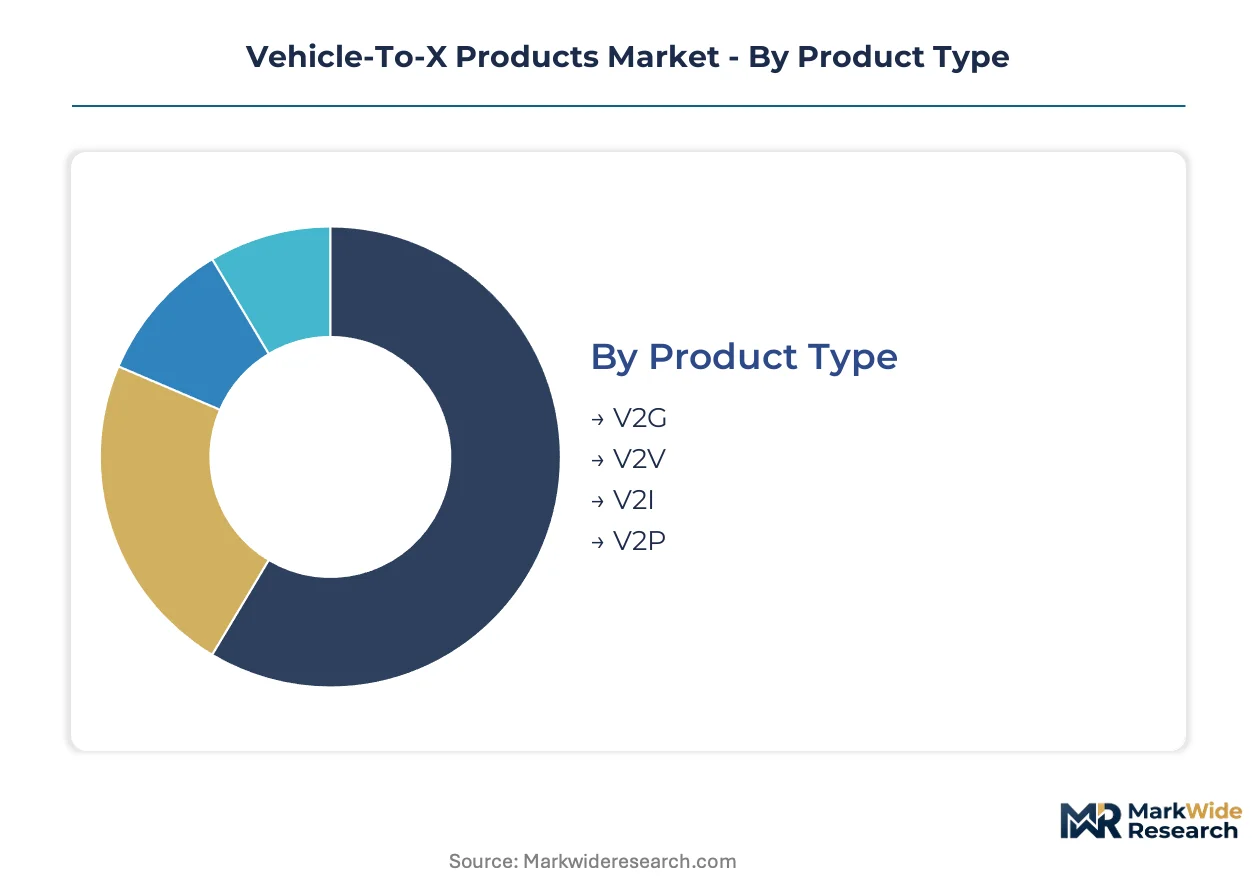
Segmentation in the Vehicle-To-X Products Market reveals divergent procurement cycles and margin structures across communication protocols and deployment contexts. Understanding these distinctions enables suppliers to align R&D roadmaps with the replacement timelines and certification requirements of distinct buyer categories.
Product Type:
Replacement cycles vary sharply across V2X product categories, with energy-facing hardware turning over fastest due to grid-interconnection standard evolution while pedestrian-facing systems endure longest.
- V2G:Bidirectional power transfer units enabling EV-to-grid energy exchange incorporate power electronics rated for 10-15 year lifecycles but face accelerated replacement pressure from evolving IEEE 2030.5 interoperability mandates. Fleet operators in California and Texas are aggregating V2G capacity under utility demand-response contracts that require firmware-upgradeable hardware architectures.
- V2V:Vehicle-to-vehicle communication modules operating on 5.9 GHz ITS spectrum implement basic safety message broadcasting for collision avoidance. NHTSA proposed mandates are compressing procurement timelines for passenger vehicle OEMs preparing compliance-ready model year introductions.
- V2I:Roadside-to-vehicle data exchange systems integrate with traffic signal controllers and highway sensors. Municipal transportation departments in Germany and South Korea are bundling V2I deployments with smart city infrastructure refresh programs.
- V2P:Pedestrian-to-vehicle alerting systems utilizing UWB and camera fusion for vulnerable road user detection. European pedestrian safety regulations are driving integration into premium vehicle platforms.
V2V modules dominate installed base through early DSRC deployments. V2G hardware is where expansion concentrates as electrified commercial fleets scale.
Technology:
Technology selection in V2X architectures directly determines certification pathway, spectrum access rights, and backward compatibility obligations for infrastructure investors.
- Dedicated Short-Range Communications:IEEE 802.11p-based radio systems with sub-50 millisecond latency for safety-critical applications. DSRC retains entrenched positions in North American deployments under FCC 5.9 GHz allocations despite C-V2X encroachment.
- LTE:Cellular-based V2X utilizing 4G infrastructure for non-safety traffic efficiency applications. LTE-V2X serves as a transitional technology in Chinese smart city pilots awaiting full 5G standalone deployment.
- 5G:New Radio-based C-V2X enabling network-sliced ultra-reliable low-latency communication for autonomous coordination. South Korean operators are deploying 5G-V2X along the K-City testbed corridor outside Seoul.
- DSRC:Legacy term for early-generation dedicated short-range implementations now converging with standardized IEEE 802.11bd enhancements. Japanese expressway operators continue DSRC-based ETC-V2X integration for tolling and hazard alerting.
DSRC anchors legacy infrastructure commitments. 5G C-V2X is climbing the fastest as cellular ecosystem scale advantages compound.
Application:
Application segmentation exposes divergent buyer sophistication and outcome-measurement maturity across municipal, commercial, and energy-sector deployment contexts.
- Smart Parking:V2I-enabled vacancy detection and automated payment systems reducing urban curb-search traffic. Barcelona and Singapore municipal authorities are procuring integrated parking-management platforms with embedded C-V2X roadside units.
- Fleet Management:Predictive routing and platooning coordination for logistics operators quantifying fuel and labor savings. North American trucking corridors are seeing performance-based service contracts where infrastructure providers guarantee specific efficiency improvements.
- Traffic Management:Signal phase and timing optimization through real-time vehicle flow data. German autobahn digitization projects under KBA oversight are accelerating procurement of ETSI-compliant cooperative systems.
- Energy Management:Grid stabilization and peak shaving through aggregated EV bidirectional power transfer. Utility-backed aggregation platforms in California and Texas are monetizing frequency regulation services from commercial fleet V2G capacity.
Traffic Management dominates public-sector procurement volumes. Energy Management is gaining share fastest as electrification policy incentives deepen.
End User:
End-user segmentation reveals distinct procurement authority structures, technical specification control, and replacement cycle predictability across the V2X value chain.
- OEMs:Automotive manufacturers integrating onboard units into vehicle electrical architectures with multi-year model cycle commitments. Premium German and Korean OEMs are dual-sourcing DSRC and C-V2X modules to hedge regulatory uncertainty.
- Transportation Authorities:Government agencies procuring roadside infrastructure through public tender processes with extended deployment timelines. ETSI harmonized standards are enabling EU-wide mutual recognition that compresses KBA-type approval durations.
- Fleet Operators:Commercial logistics providers deploying private V2I networks for corridor-specific efficiency gains. Performance-based contracts are displacing capital expenditure models in North American freight corridors.
- Urban Planners:Municipal departments embedding V2X within comprehensive smart city digital infrastructure. Korean municipal frameworks are creating bundled procurement channels combining traffic management with public safety applications.
Transportation Authorities anchor roadside unit installed base. Fleet Operators are where procurement pattern innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced V2X chipset fabrication concentrates in Germany, Japan, and South Korea, exposing module assemblers to geopolitical disruption while China's domestic foundry partnerships narrow supply gaps.
United States
NHTSA connected-vehicle mandates compress DSRC certification timelines for passenger vehicle OEMs preparing compliance-ready model year introductions. FCC 5.9 GHz spectrum allocations shape hardware certification requirements across variable radio propagation environments. California and Texas fleet operators aggregate V2G capacity under utility demand-response contracts requiring firmware-upgradeable architectures.
Germany
KBA-type approval pathways align with ETSI harmonized standards enabling EU-wide mutual recognition that compresses procurement timelines for autobahn digitization projects. ETSI interoperability testing mandates force module suppliers to maintain Brussels-based certification facilities. Bavaria and Baden-Württemberg anchor Continental's integrated roadside unit manufacturing for cooperative intelligent transport systems.
China
MIIT GB specifications enable cellular V2X infrastructure to piggyback on existing 5G telecommunications rollout, reducing standalone roadside unit capital requirements for municipal operators. Domestic automotive foundry partnerships narrow V2X module supply gaps through 5G base station co-deployment. Yangtze River Delta and Pearl River Delta clusters concentrate smart city pilot programs awaiting full 5G standalone deployment.
South Korea
Korean municipal frameworks embed C-V2X roadside units into urban digital infrastructure, creating bundled procurement channels combining traffic management with public safety applications. Seoul Capital Area operators deploy 5G-V2X along the K-City testbed corridor outside Seoul enabling network-sliced ultra-reliable low-latency communication. Busan-Ulsan industrial corridors concentrate automotive OEM integration programs for premium safety modules.
Japan
METI industrial policy supports DSRC-based ETC-V2X integration for expressway tolling and hazard alerting across aging infrastructure refresh programs. Japanese expressway operators continue legacy DSRC commitments while evaluating 5G C-V2X migration pathways. Chubu and Kansai manufacturing clusters anchor Renesas Electronics automotive-qualified chipset production for domestic OEM supply security.
Vehicle-To-X Products Market Competitive Landscape
Semiconductor specialists and automotive Tier-1 suppliers split the market between silicon-level protocol innovation and systems integration for roadside deployment. The vendor base organizes around three strategic archetypes: fabless chipset designers with cellular ecosystem leverage, diversified automotive electronics conglomerates with manufacturing scale, and specialized communication module vendors with dual-protocol firmware capabilities. Competitive positioning hardens through strategic partnerships bridging silicon design with municipal infrastructure procurement channels, while geographic diversification of foundry relationships defends against supply concentration risk.
Within the fabless chipset tier, Qualcomm Technologies and NXP Semiconductors exemplify divergent regional standard hedging strategies. Continental occupies a position anchoring European supply security through integrated roadside unit manufacturing. Among diversified automotive electronics suppliers, Robert Bosch and Harman International sit within the premium vehicle platform integration segment. STMicroelectronics and Infineon Technologies represent European semiconductor fabricators with automotive-qualified portfolio breadth. The competitive dynamic centers on dual-mode hardware architectures that satisfy divergent DSRC and C-V2X certification requirements without sacrificing unit economics across multi-region deployment contexts.
| Leading Market Players |
|---|
| Qualcomm Technologies |
| Autotalks |
| Continental |
| NXP Semiconductors |
| Infineon Technologies |
| Robert Bosch |
| Harman International |
| STMicroelectronics |
| Renesas Electronics |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta foundry clusters anchor global V2X module assembly capacity, concentrating silicon sourcing leverage among Qualcomm Technologies, NXP Semiconductors, and Infineon Technologies. This geographic concentration translates into tiered procurement power where automotive OEMs with multi-year platform commitments command preferential allocation during foundry constraint periods.
Pricing Analysis
NHTSA connected-vehicle mandates dictate the pricing tier structure across North American DSRC module procurement. Three-tier pricing structure across premium, standard, and economy levels separates safety-critical vehicle platforms from commercial fleet retrofits and aftermarket installations. Cost compression in standard-tier modules is intensifying because Chinese domestic foundry partnerships are narrowing supply gaps. Fleet operators exhibit the highest price sensitivity due to thin logistics margins, while premium German OEMs prioritize certification reliability over unit cost.
Supply Chain Analysis
TSMC, Samsung Foundry, and GlobalFoundries hold the dominant contract-manufacturing capacity for automotive-qualified V2X chipsets. Advanced node fabrication draws from Taiwan, South Korea, and Germany, with backend assembly and test operations anchored in Malaysia and Vietnam. Single-source vulnerability concentrates around 5G NR modem silicon where Qualcomm Technologies maintains design leadership. Distribution runs through Tier-1 automotive electronics suppliers who integrate modules into vehicle electrical architectures and roadside infrastructure packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator procurement consolidation is shifting bargaining power toward logistics providers capable of aggregating corridor-scale V2I network commitments. Transportation authority fragmentation across municipal jurisdictions leaves infrastructure vendors exposed to elongated sales cycles.
For Market Incumbents: Harden dual-protocol firmware architectures against C-V2X standard dominance scenarios by maintaining parallel DSRC validation capabilities. Invest in Brussels-based certification facilities to compress ETSI interoperability testing timelines. Defensive consolidation through captive foundry relationships in Germany and South Korea reduces exposure to Taiwan Strait disruption risk. For New Entrants and Emerging Players: Pursue V2G aggregation software platforms serving Texas and California utility demand-response markets where incumbent automotive Tier-1s lack deep grid interconnection expertise. The most penetrable segment lies in commercial EV fleet energy management where firmware-upgradeable hardware architectures remain undersupplied. A direct utility partnership model bypasses OEM procurement gatekeepers entirely. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized communication module vendors with dual-protocol firmware capabilities over diversified automotive electronics conglomerates with manufacturing scale. Long-term viability hinges on software-defined radio architectures that enable post-deployment protocol reconfiguration. Watch for regulatory convergence signals between FCC, ETSI, and MIIT standards bodies as the primary inflection indicator for hardware obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mode Chipset Architecture | Qualcomm Technologies and NXP Semiconductors hedge regulatory uncertainty through flexible silicon designs. |
| Utility-Backed V2G Aggregation | California and Texas fleet operators monetize grid stabilization services under FERC Order 2222 frameworks. |
| ETSI Certification Facility Investment | Continental and Robert Bosch compress KBA-type approval durations through Brussels-based interoperability testing. |
| 5G Base Station Co-Deployment | China's MIIT GB specifications reduce standalone roadside unit capital requirements for municipal operators. |
| Performance-Based Service Contracts | North American logistics corridors displace capex models with guaranteed traffic efficiency outcome metrics. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC spectrum allocation dockets, ETSI harmonized standards documentation, and NHTSA proposed rulemaking records. Primary interviews engaged Tier-1 supplier procurement directors, OEM platform engineers, transportation authority program managers, and utility demand-response specialists. Secondary validation drew from SEC 10-K automotive electronics disclosures, MIIT GB specification filings, and vehicle production databases. Bottom-up module shipment estimates triangulated against top-down infrastructure investment forecasts.
Forecast inputs span communication protocol adoption curves, regulatory mandate implementation timelines, and fleet electrification penetration across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, application context, and end-user procurement authority. CAGRs derived from S-curve technology diffusion patterns adjusted for regional standard divergence risk. Industry-specific inputs incorporate 5G base station deployment schedules and IEEE 2030.5 interoperability mandate evolution.
Sensitivities concentrate around DSRC-C-V2X protocol resolution timelines and semiconductor foundry allocation constraints. Forecasts reflect assumptions regarding regulatory convergence negotiations and utility tariff structure evolution for V2G services. Cross-checking against IHS Markit vehicle registration data and hyperscaler 5G capex disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Trailers and Semi-Trailers Market
Vehicle Components
Bicycle Brake Cable Market
Vehicle Components
Air Brake Reservoirs Market
Vehicle Components
Tow Tractor Market
Vehicle Components
Headlight Market
Vehicle Components
Self Loading Trailer Market
Vehicle Components
Idler Arm Market
Vehicle Components
Motor Lamination Market
Vehicle Components
Automotive Exhaust Gas Sensor Market
Vehicle Components
Engine Mounting Brackets Market
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market
Vehicle Components
Wheelhouse Liner Market
Vehicle Components
Italy Automotive Glass Fiber Composites Market
Vehicle Components
Electric Vehicles Component Market
Vehicle Components
GCC Automotive Connectors Market
Vehicle Components
High Precision Heavy Load Bearings Market