
 Automotive Hoses Market | 2026-2036
Automotive Hoses Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Hoses Market Analytics
A widening capability gap in extrusion-to-assembly integration is rotating competitive advantage toward firms with captive polymer compounding. Continental AG leverages its in-house rubber formulation network to secure OEM qualification cycles. Gates Corporation anchors its position through backward integration into high-performance elastomer development. Sumitomo Riko Company Limited differentiates via advanced vibration-damping hose architectures for hybrid powertrains.
Automotive hoses are flexible tubular conveyances engineered from reinforced elastomeric or thermoplastic compounds, typically rated for operating pressures from vacuum to several hundred bar and temperature ranges spanning minus forty to over two hundred degrees Celsius, designed to transport fluids, gases, or thermal media within vehicle systems. Rubber hoses retain dominant share in fuel and cooling circuits due to cost-efficient swell resistance and established OEM validation protocols, though thermoplastic hoses are displacing legacy constructions in weight-sensitive electric vehicle battery thermal loops where permeation control and geometric flexibility command premium positioning. Hydraulic hoses within brake system applications sustain stable replacement demand while silicone hoses capture niche growth in high-performance aftermarket segments.
EPA tailpipe and evaporative emission standards, EU REACH chemical restrictions, and China's GB standards for fuel system permeation collectively mandate multi-layer barrier constructions and fluoropolymer liner adoption. NHTSA brake hose integrity regulations enforce dynamic pressure cycling and corrosion resistance benchmarks that elevate testing-stage capital requirements for market access. Stakeholders must monitor regulatory divergence between California Air Resources Board zero-emission vehicle thermal loop specifications and emerging EU battery thermal management standards to align R&D pipelines with divergent certification pathways.
Market Dynamics
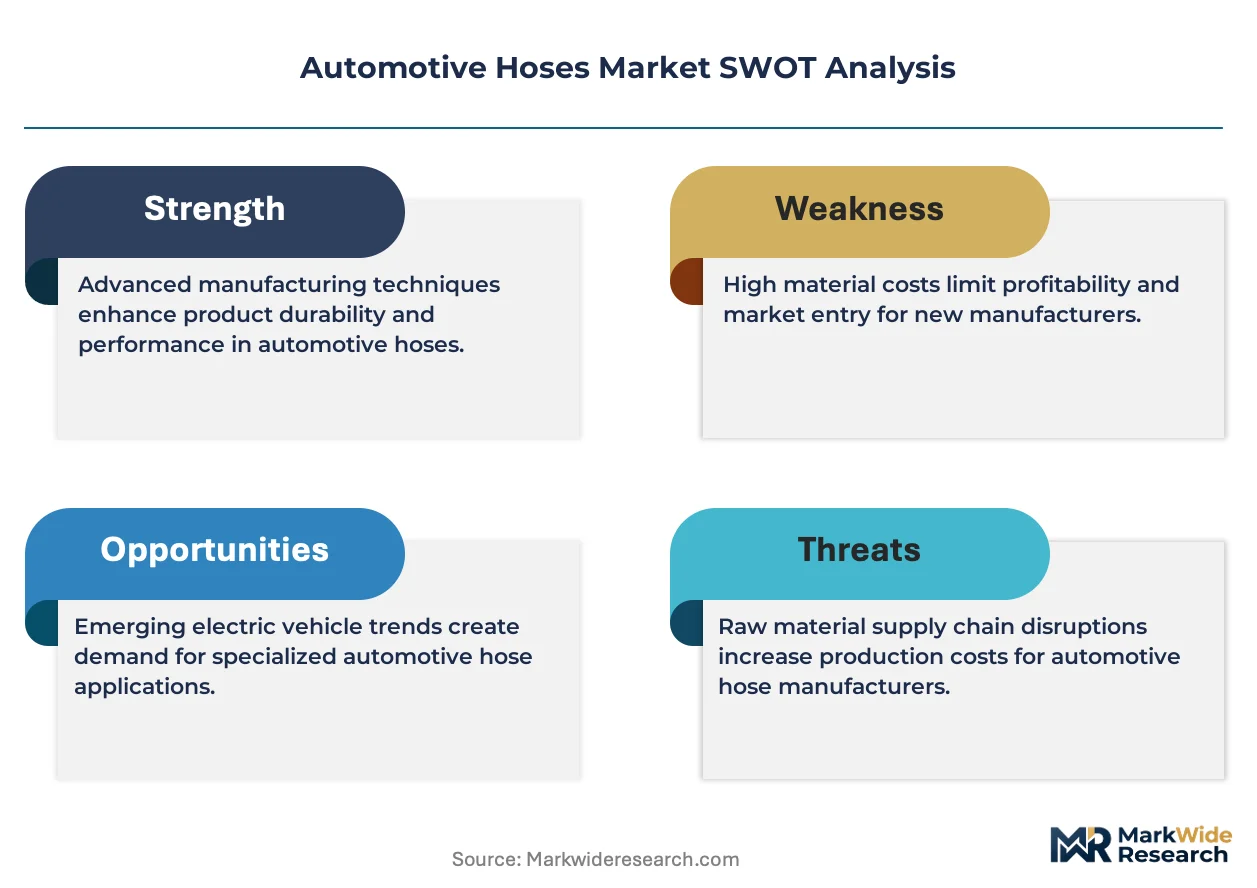
Electric vehicle thermal management architectures are forcing material transitions across hose supply chains, as multi-layer barrier constructions replace single-wall rubber in battery cooling circuits and fluoropolymer liners penetrate high-voltage loop applications.
Growth Catalysts
- EPA Fuel-Efficiency Mandates:Tailpipe and evaporative emission standards tighten permeability thresholds, compelling OEM adoption of advanced barrier hose constructions in fuel system architectures.
- EU F-Gas Regulation:Refrigerant containment requirements accelerate demand for low-permeation thermal loop hoses in electric vehicle battery management systems.
- China's Dual Carbon Goals:NEV production quotas and thermal efficiency targets drive localized sourcing of high-performance elastomer compounds for domestic OEM supply chains.
Market Restraints
- Fluoropolymer Feedstock Concentration:PTFE and FKM resin supply concentrates among limited chemical producers, exposing hose manufacturers to input cost volatility and allocation constraints.
- OEM Validation Cycle Duration:Multi-year qualification protocols for brake and fuel system hoses extend time-to-revenue for new material entrants and elevate working capital requirements.
- REACH Chemical Restrictions:ECHA substance of very high concern listings threaten phthalate plasticizer availability in flexible PVC hose compounds, forcing reformulation investments.
Strategic Opportunities
- India NEV Thermal Infrastructure:Domestic battery assembly capacity expansion creates demand for localized hose production serving Tata Motors and Mahindra electric platforms.
- Solid-State Battery Cooling:Next-generation cell architectures requiring dielectric fluid circulation open specification windows for chemically resistant thermoplastic hose constructions.
- Subscription Fleet Maintenance:Commercial vehicle uptime contracts favor predictive hose replacement programs, shifting volume toward authorized service channel partnerships.
Industry Challenges
- Compounding Expertise Scarcity:Formulation chemists capable of balancing permeation resistance, flexibility, and cost in multi-layer constructions command premium compensation and limited availability.
- Cross-Border Certification Divergence:NHTSA brake hose integrity testing protocols, ECE R90 homologation requirements, and China's GB standards create fragmented approval pathways for common product families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Hoses Market |
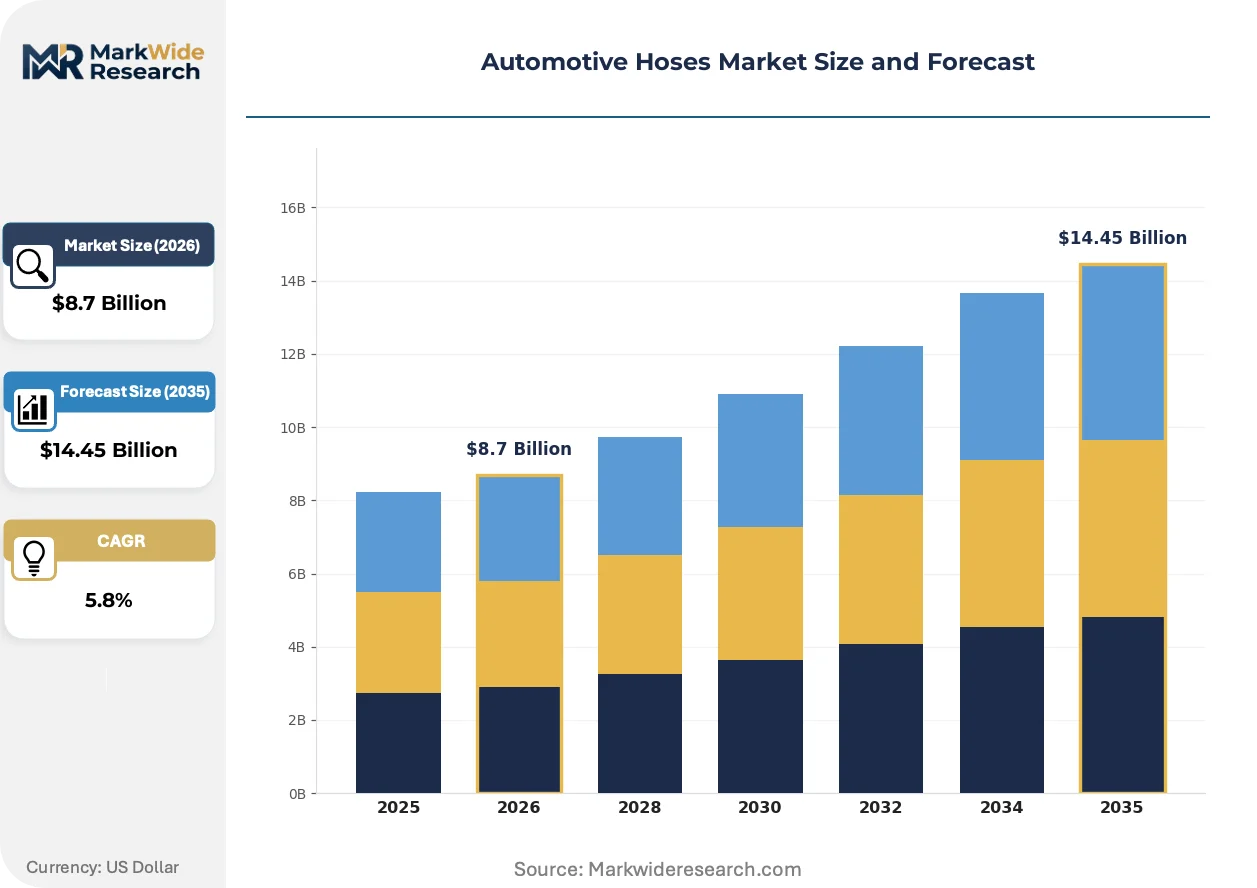
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Hoses, Rubber Hoses, Thermoplastic Hoses, Hydraulic Hoses Application: Cooling System, Fuel System, Brake System, Exhaust System End User: OEMs, Aftermarket, Commercial Vehicles, Passenger Cars Manufacturing Stage: Extrusion, Molding, Assembly, Testing |
| Companies Covered | Sumitomo Riko Company Limited, Continental AG, Gates Corporation, Parker Hannifin Corp, TI Fluid Systems plc, Tianjin Pengling Group Co., Ltd., Cooper Standard Automotive Inc., Nichirin Co., Ltd., Toyoda Gosei Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Hoses Market Evolving Landscape
Material science advances and regulatory stringency are compressing product lifecycles while opening specification windows for novel constructions. Three interconnected developments are restructuring competitive positioning.
Thermoplastic elastomer hoses are displacing conventional rubber constructions in weight-critical electric vehicle battery thermal loops. OEMs specify these constructions for geometric flexibility and permeation control in high-voltage cooling circuits. The shift compresses established rubber compounders' share in fastest-growing application segments.
EU F-Gas Regulation phase-down schedules tighten refrigerant containment requirements across automotive HVAC and battery thermal systems. Hose suppliers must validate barrier layer adhesion and long-term fatigue resistance under accelerated aging protocols. German OEMs lead specification adoption, with Chinese NEV manufacturers tracking implementation timelines for export compliance.
Fleet operators now bundle hose replacement into total cost of ownership contracts rather than sourcing through fragmented aftermarket channels. Commercial vehicle lessors consolidate procurement through direct manufacturer agreements with predictive maintenance data integration. North American heavy-duty truck segments exhibit this pattern most prominently, with European logistics operators following.
Automotive Hoses Market Segmentation
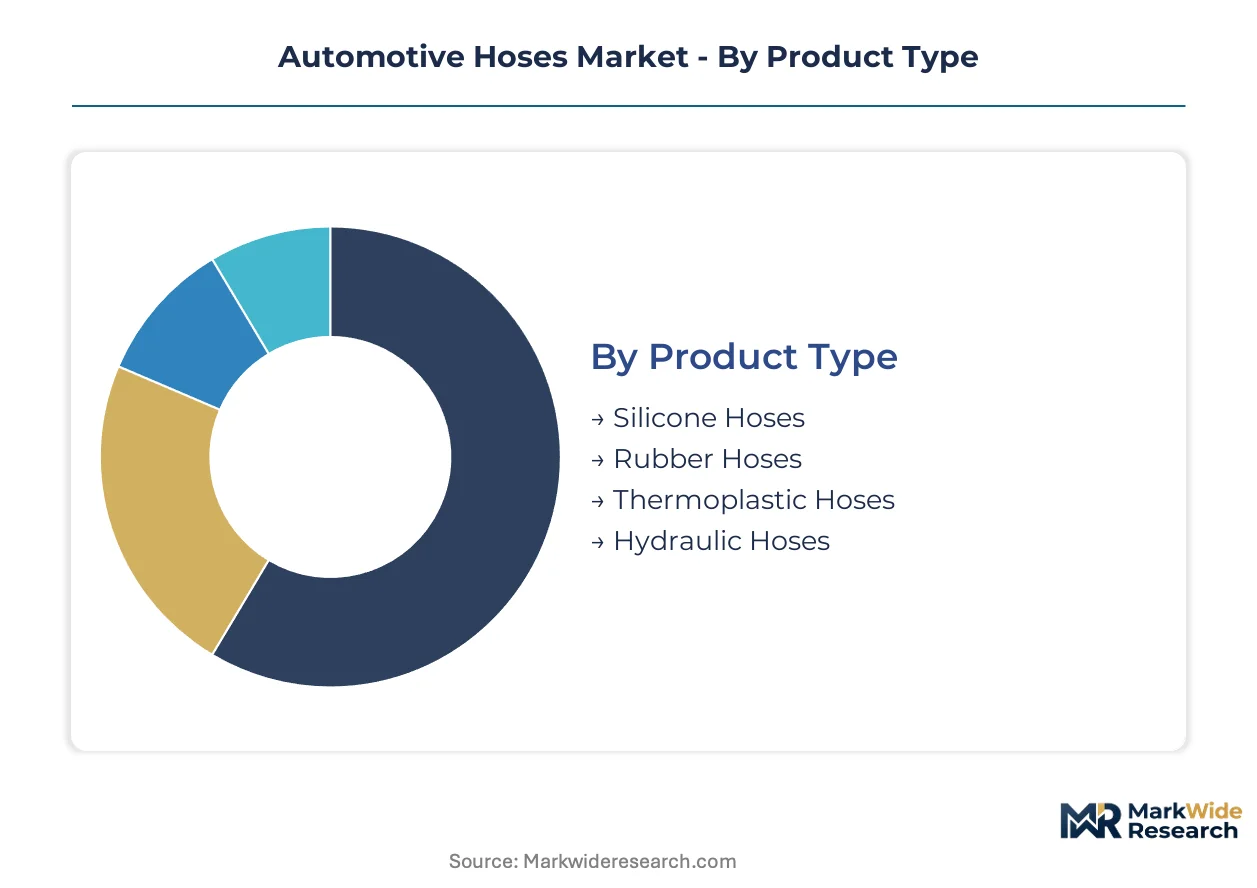
Automotive hose specifications diverge sharply between legacy internal combustion architectures and emerging electric vehicle thermal systems. Material selection, barrier layer complexity, and validation protocols vary by product category and end-use, creating distinct competitive arenas within the supply chain.
Product Type:
Domestic production concentrates rubber and silicone constructions in Germany, China, and the United States, while thermoplastic hose demand is export-led toward European and North American EV battery manufacturers.
- Rubber Hoses:Reinforced elastomeric constructions with textile or wire braiding dominate fuel and cooling circuits in conventional powertrains. OEMs in Stuttgart and Detroit specify these for cost-efficient swell resistance against hydrocarbon exposure, though EPA permeability thresholds are forcing multi-layer upgrades.
- Thermoplastic Hoses:Nylon or fluoropolymer-based constructions deliver geometric flexibility and permeation control in high-voltage battery thermal loops. Chinese NEV manufacturers source these for weight reduction in export-compliant platforms serving EU F-Gas Regulation requirements.
- Silicone Hoses:High-temperature resistant formulations capture aftermarket performance segments and select OEM turbocharger applications.
- Hydraulic Hoses:Steel-reinforced elastomeric tubes sustain brake system replacement demand under NHTSA integrity regulations.
Rubber hoses hold the largest share; momentum sits with thermoplastic constructions in battery thermal management.
Application:
Cost tier separation is pronounced: cooling and fuel systems command premium barrier specifications, while exhaust applications face commoditization pressure from stainless steel substitution.
- Cooling System:Hoses circulate coolant through engine blocks, radiators, and increasingly through battery thermal management loops. German OEMs specify multi-layer barrier constructions for electric vehicle platforms, with Chinese manufacturers scaling comparable specifications for domestic NEV production.
- Fuel System:Low-permeation constructions with fluoropolymer liners contain gasoline and diesel under EPA evaporative emission standards. Suppliers face reformulation pressure as ECHA substance restrictions threaten conventional plasticizer availability.
- Brake System:Dynamic pressure-rated hydraulic hoses must withstand corrosion and fatigue under NHTSA cycling protocols.
- Exhaust System:Flexible connectors and gas recirculation hoses face displacement by metal alternatives in high-temperature zones.
Fuel system applications absorb the highest specification investment; cooling systems are climbing the fastest on thermal management complexity.
End User:
Volume concentration favors OEM supply agreements with multi-year qualification cycles, while aftermarket channels fragment across service networks and direct fleet procurement.
- OEMs:Direct supply to vehicle manufacturers demands validated compound formulations and geometric customization for platform-specific routing. Tier 1 suppliers in Japan and Germany anchor qualification relationships spanning brake, fuel, and thermal system architectures.
- Passenger Cars:High-volume production drives standardization in hose specifications across compact through luxury segments.
- Commercial Vehicles:Fleet operators consolidate procurement through uptime contracts with predictive replacement scheduling.
- Aftermarket:Fragmented service channel demand concentrates in brake hose replacement and performance silicone upgrades.
OEM supply holds the largest share; fleet-driven commercial vehicle procurement is expanding most quickly on subscription maintenance models.
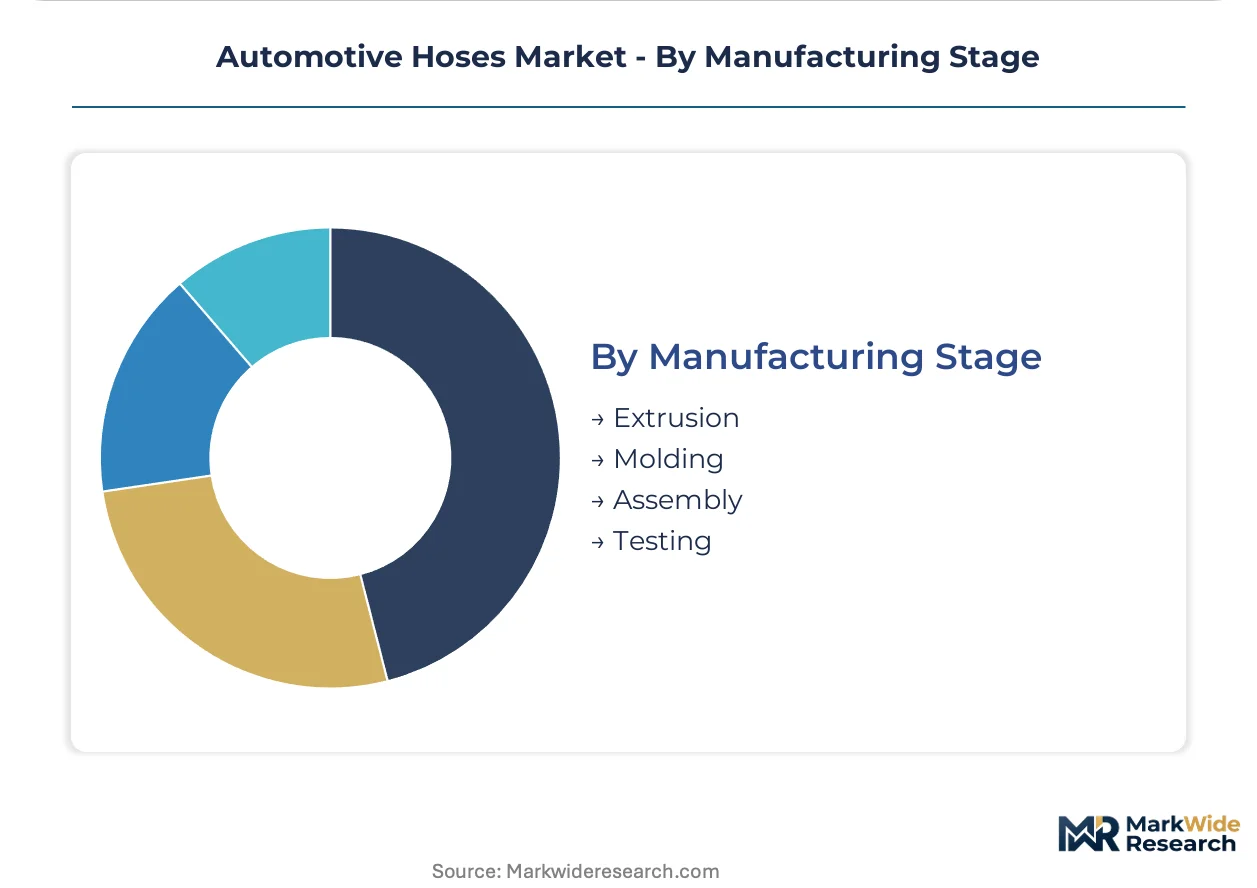
Manufacturing Stage:
Margin capture concentrates upstream in compounding and extrusion, where formulation expertise creates defensible positions, while assembly and testing face automation-driven cost compression.
- Extrusion:Continuous profile production from compounded elastomer or thermoplastic resin determines barrier layer integrity and geometric precision. Captive compounding capabilities in Germany and the United States differentiate suppliers serving EPA and EU regulatory specifications.
- Testing:Dynamic pressure cycling, permeation measurement, and accelerated aging validation enforce capital-intensive compliance gates.
- Molding:Complex geometry formation for connector integration and branch configurations.
- Assembly:End fitting attachment and multi-layer construction bonding complete finished hose production.
Extrusion holds the largest share; integrated testing capabilities are gaining share fastest on regulatory stringency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany sources multi-layer barrier constructions for thermal management, while China scales domestic elastomer compounding for NEV platforms, and the United States enforces permeability thresholds through EPA mandates that diverge from EU F-Gas Regulation timelines.
Germany
Stuttgart OEMs specify fluoropolymer-lined hoses for battery cooling circuits in premium electric platforms. KBA enforces ECE R90 homologation requirements that validate dynamic pressure cycling integrity. Bavarian rubber compounders supply captive formulations to anchor qualification relationships with domestic vehicle manufacturers.
China
Domestic NEV production quotas drive localized sourcing of thermoplastic hose constructions for export-compliant battery thermal loops. MIIT GB standards for fuel system permeation mandate barrier layer adoption comparable to EPA thresholds. Yangtze River Delta manufacturers scale extrusion capacity to serve BYD and CATL supply chains.
United States
Detroit OEMs demand multi-layer fuel hoses under EPA evaporative emission standards tightening through 2027. NHTSA brake hose integrity regulations enforce corrosion resistance benchmarks that elevate testing-stage capital requirements. Michigan-based compounders maintain backward integration into high-performance elastomer development for platform-specific routing.
Japan
Hybrid powertrain architectures sustain demand for vibration-damping hose constructions with specialized reinforcement geometries. METI carbon neutrality targets accelerate material transitions in domestic thermal management supply chains. Nagoya-area manufacturers anchor Tier 1 supplier relationships spanning brake, fuel, and cooling system specifications.
India
Tata Motors and Mahindra electric platforms create demand for localized hose production serving battery assembly capacity expansion. BIS standards for automotive fluid conveyance systems are converging toward EU permeability benchmarks. Maharashtra industrial corridors attract compounding investments to reduce import dependence on fluoropolymer resin feedstocks.
Automotive Hoses Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive polymer compounding capabilities separating premium qualification holders from assembly-dependent competitors. Market access demands multi-year OEM validation cycles that extend time-to-revenue for new material entrants. Three archetypes dominate: vertically integrated compounders with in-house rubber formulation networks, extrusion-to-assembly specialists with geometric customization expertise, and regional fabricators serving aftermarket replacement channels. Competitive moves concentrate on backward integration into resin compounding and predictive fleet maintenance partnerships.
Among Japanese manufacturers, Sumitomo Riko Company Limited and Toyoda Gosei Co. Ltd. exemplify the vibration-damping specialization archetype for hybrid powertrain applications. German-based Continental AG anchors the integrated compounder tier with captive formulation capabilities. Gates Corporation represents North American backward integration into high-performance elastomer development. Tianjin Pengling Group Co., Ltd. occupies a position among Chinese regional fabricators scaling capacity for domestic NEV thermal infrastructure.
| Leading Market Players |
|---|
| Sumitomo Riko Company Limited |
| Continental AG |
| Gates Corporation |
| Parker Hannifin Corp |
| TI Fluid Systems plc |
| Tianjin Pengling Group Co., Ltd. |
| Cooper Standard Automotive Inc. |
| Nichirin Co., Ltd. |
| Toyoda Gosei Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Thermoplastic elastomer substitution for conventional rubber compounds simultaneously relocates production gravity toward Yangtze River Delta extrusion clusters and compresses margin capture for compounders lacking captive resin supply. This material transition rewards suppliers with backward integration into fluoropolymer feedstock while exposing assembly-dependent fabricators to PTFE allocation volatility.
Pricing Analysis
Aftermarket service contracts and predictive replacement programs now generate superior lifetime value compared to original equipment sales. Three-tier pricing structure across premium barrier specifications, standard multi-layer constructions, and economy rubber grades stratifies the market, with EPA permeability mandates widening spreads between certified and uncertified tiers. Pricing pressure stems from fluoropolymer resin concentration among limited chemical producers, with Chinese NEV manufacturers exhibiting highest price sensitivity and German premium OEMs least.
Supply Chain Analysis
Just-in-time delivery preferences dominate OEM supply agreements, though strategic stockpiling of fluoropolymer resins is emerging among qualified Tier 1 suppliers. Manufacturing concentrates in Germany, China, and the United States, with feedstock supply anchored in Japan and the United States for high-performance elastomers. Single-source vulnerability runs through PTFE resin allocation, while distribution feeds from direct manufacturer agreements with fleet operators and fragmented aftermarket service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle thermal management complexity represents a high-growth disruption, with EU F-Gas Regulation phase-down schedules forcing material transitions across battery cooling architectures.
For Market Incumbents: Compound formulation expertise advantages through captive polymer compounding investments in Germany and Michigan production corridors. Secure qualification relationships with Stuttgart and Detroit OEMs before NEV platform standardization locks in supplier specifications, as thermoplastic displacement threatens rubber compounder share in fastest-growing segments. For New Entrants and Emerging Players: Differentiate on solid-state battery dielectric fluid compatibility and localized India production serving Tata Motors and Mahindra thermal infrastructure expansion. Target Maharashtra industrial corridor compounding investments to reduce fluoropolymer import dependence, leveraging BIS standard convergence toward EU permeability benchmarks as qualification pathway. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed extrusion-to-assembly specialists lacking upstream resin compounding capabilities. Long-term viability hinges on backward integration completion within a multi-year window, with acquisition focus on Bavarian and Yangtze River Delta compounders possessing OEM validation relationships. Watch for EU battery thermal management standard divergence from CARB zero-emission vehicle specifications as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Compounding | Captive resin supply secures allocation priority with German OEMs facing EU F-Gas compliance deadlines. |
| Predictive Fleet Maintenance Partnerships | Direct agreements with North American heavy-duty truck lessors consolidate aftermarket volume away from fragmented channels. |
| Solid-State Battery Thermal Loop Qualification | Early validation for dielectric fluid compatibility opens specification windows before platform standardization crystallizes. |
| India NEV Supply Chain Localization | Maharashtra production corridors reduce landed cost for domestic battery assembly serving Tata Motors platforms. |
| Multi-Region Certification Harmonization | Unified NHTSA-ECE R90-GB testing protocols compress time-to-revenue for new material entrants across regulatory clusters. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and compounding R&D directors converged on the working assumptions governing material transition timelines. Primary fieldwork combined with vehicle production databases, IHS Markit registration data, EPA emission standard filings, and SEC 10-K disclosures enabled bottom-up and top-down triangulation across the analysis window.
Segmentation dimensions modeled encompass propulsion architecture, barrier layer complexity, end-use application, and regional regulatory cluster. CAGRs were derived from production volume trajectories and content-per-vehicle assumptions across the projection horizon, with electric vehicle thermal management intensity and fluoropolymer adoption curves serving as primary forecast inputs.
Material uncertainties — fluoropolymer feedstock allocation constraints, regulatory divergence between EPA and EU F-Gas timelines, and solid-state battery commercialization schedules — sit outside the modeled envelope. Forecasts reflect assumptions about qualification cycle durations and OEM platform standardization patterns. Revision becomes warranted when regulatory stringency crosses thresholds that accelerate or delay multi-layer barrier adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Japan Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Smart Adaptive Headlights Market
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
Global Plastics for Passenger Cars Market
Automotive Parts
Sintered Silencer Market
Automotive Parts
Automotive Power Window Regulator Market
Automotive Parts
Tire Tread Cutting Machines Market
Automotive Parts
Automotive Brake Caliper Market
Automotive Parts
Norway Passenger Vehicles Lubricants Market
Automotive Parts
Off-Road Hoses Market
Automotive Parts
Fluid Couplings Market
Automotive Parts
North America Automotive Airfilters Market
Automotive Parts
Global Truck Refrigeration Unit Market
Automotive Parts
Brake Shoe Market
Automotive Parts
Electric Brake Booster Market