
 Bottle Sealing Wax Market | 2026-2036
Bottle Sealing Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Bottle Sealing Wax Market Intelligence
Custom color formulation and small-batch production is reconfiguring the margin pool away from bulk, uncolored wax sales. Blended Waxes Inc. leverages its scale in industrial wax to compete on cost for larger orders. In contrast, Custom Wax n' Seals specializes in bespoke solutions for craft distilleries and boutique wineries. Calwax LLC sustains a broad portfolio catering to both industrial and artisanal end-users.
Bottle sealing wax is a specialty formulation, typically a blend of paraffin, microcrystalline waxes, and polymers, designed for a specific melting point and peelable adhesion. Its primary purpose is to provide a tamper-evident seal and a premium aesthetic finish for bottled goods. The spirits bottles application commands the highest value due to demand for vibrant, custom colors. Within product types, synthetic wax formulations are gaining share over traditional natural wax due to superior color consistency and performance.
Regulations governing food-contact materials, such as those from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA), dictate permissible ingredients. The EU's REACH framework further scrutinizes the chemical composition of wax blends, influencing raw material sourcing for manufacturers. Producers must navigate the trade-off between using bio-based natural waxes for marketing appeal and synthetic alternatives for enhanced performance and color vibrancy.
Market Dynamics
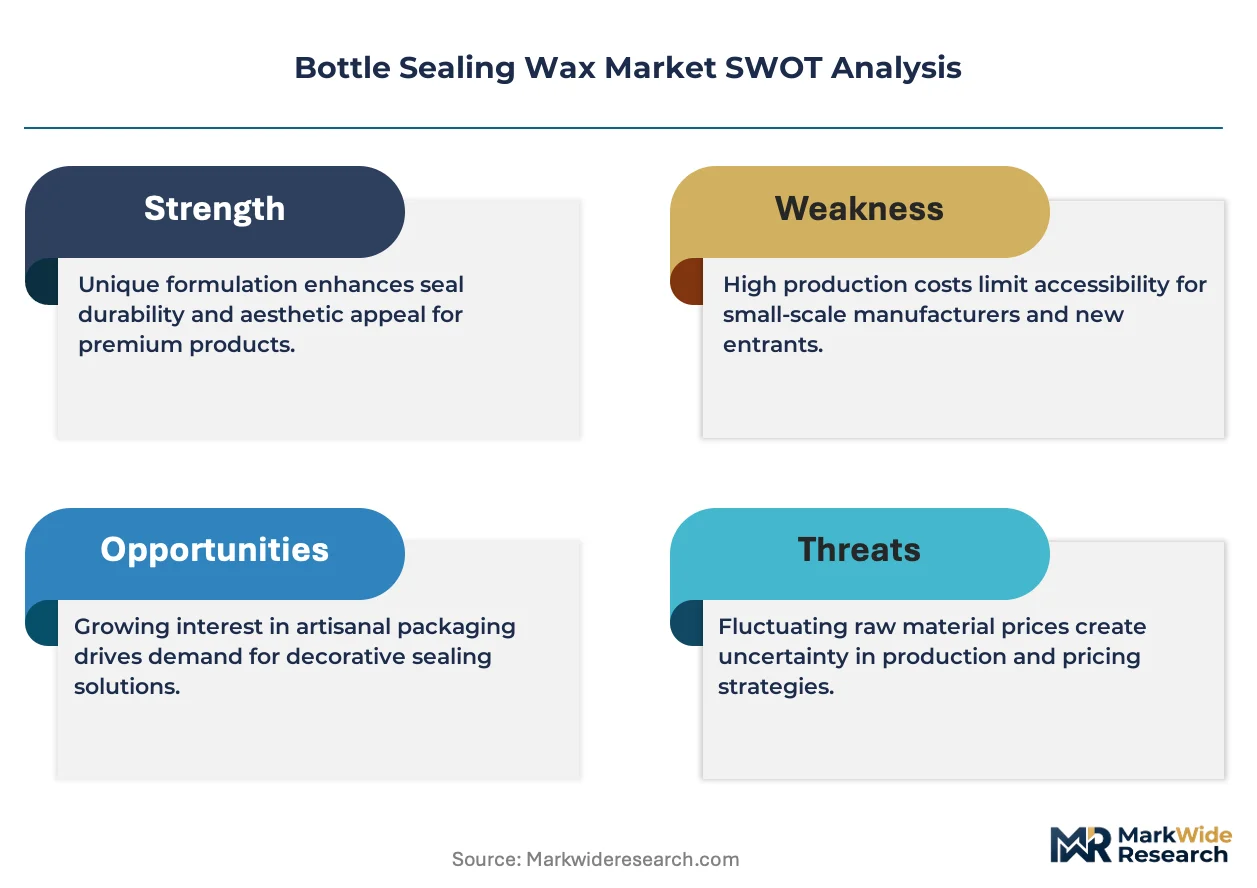
The central tension shaping the bottle sealing wax market is the conflict between the demand for vibrant, custom aesthetics in premium packaging and the increasing stringency of global food-contact material regulations, which limits raw material selection.
Growth Catalysts
- Premiumization in Beverages:The continued consumer shift toward premium and craft spirits and wines, particularly in established regions like Bordeaux and Tuscany, drives demand for differentiated, high-end packaging where sealing wax provides a key visual and tactile cue of quality.
- Synthetic Wax Formulations:Advances in synthetic wax blends offer superior color consistency, adhesion, and peelability compared to traditional natural waxes. This performance enhancement is critical for automated bottling lines and for achieving the bright, custom colors demanded by spirits brands.
- E-commerce Packaging:The growth of direct-to-consumer sales for wineries and distilleries elevates the need for tamper-evident seals that also contribute to a premium unboxing experience, making sealing wax a functional and marketing tool.
Market Restraints
- Input Cost Volatility:Prices for key raw materials, including petroleum-derived paraffin and microcrystalline waxes, are subject to fluctuations in global energy markets, creating margin pressure for manufacturers.
- Regulatory Compliance Burden:Navigating the complex and evolving chemical regulations, such as the EU's REACH framework and FDA food-contact notifications in the US, increases development costs and time-to-market for new formulations.
- Threat of Substitution:Alternative premium closure systems, including advanced ROPP caps with custom embossing and sophisticated synthetic corks, offer competing solutions for tamper evidence and brand differentiation, particularly in the high-volume wine segment.
Strategic Opportunities
- Emerging Craft Markets:Entering underpenetrated geographies with burgeoning craft beverage scenes, such as the distillery markets in Australia and Japan, presents significant growth potential for suppliers offering bespoke, small-batch solutions.
- Adjacent Market Expansion:Applying sealing wax technology to other luxury consumer goods, such as high-end cosmetics, perfumes, and gourmet food items like artisanal olive oil, opens new revenue streams beyond the core beverage sector.
- Bio-Based Formulations:Developing and marketing high-performance, peelable wax blends derived from certified bio-based or renewable sources can capture demand from brands focused on sustainability narratives, creating a new premium product tier.
Industry Challenges
- Small-Batch Production Complexity:Achieving precise color matching and consistent performance across numerous small, custom orders is an operational challenge that strains production scheduling and quality control, demanding specialized formulation expertise and flexible manufacturing processes.
- Food-Safe Pigment Sourcing:Securing a reliable supply of vibrant pigments that are also compliant with global food-contact regulations, like those from the EFSA in Europe, is a persistent challenge, particularly for unique or custom brand colors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottle Sealing Wax Market |
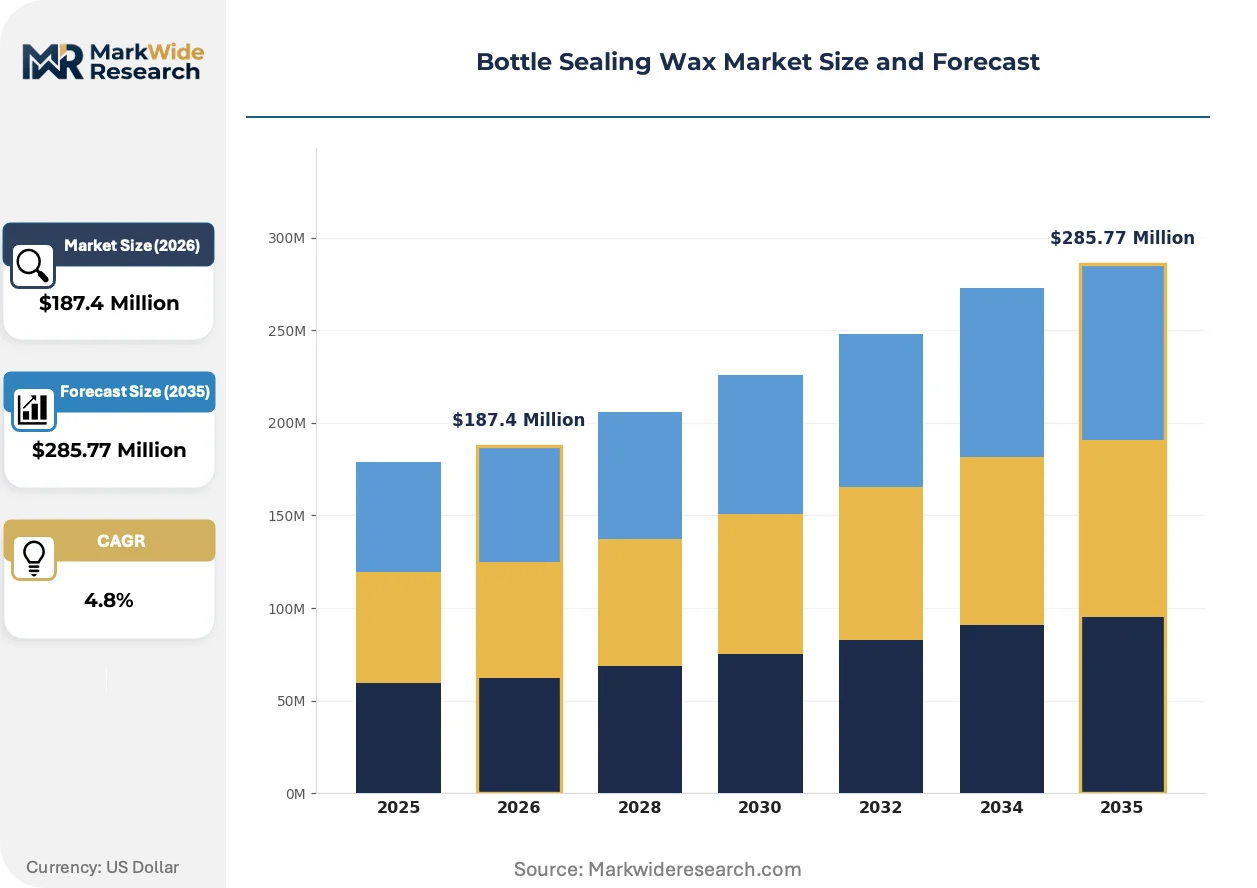
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Wax, Synthetic Wax, Hybrid Wax, Specialty Wax Application: Wine Bottles, Spirits Bottles, Olive Oil, Cosmetics Form: Granules, Blocks, Pellets, Sheets Color: Red, Green, Black, Gold |
| Companies Covered | The British Wax Refining Company Ltd, Australian Wax Co, Calwax LLC, Southwest Wax LLC, The Darent Wax Company Ltd, Blended Waxes Inc, Oakbank Products Limited, Custom Wax n' Seals, Westech Wax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottle Sealing Wax Market Strategic Shifts & Innovations
The market's evolution is defined by the intersection of material science and brand marketing, with a focus on developing formulations that meet both stringent performance requirements and rising consumer expectations for sustainability and aesthetic appeal.
Bio-Synthetic Blends
Bio-synthetic wax blends represent a significant product evolution, combining natural waxes like carnauba or soy with performance-enhancing synthetic polymers. Craft distilleries and boutique wineries are the primary adopters, seeking to align their packaging with sustainability marketing claims without sacrificing performance. This development is hybridizing the market by merging the ecological appeal of natural materials with the superior color vibrancy and consistency of synthetic formulations, creating a distinct high-value category.
Regulatory Scrutiny on Additives
Europe's REACH framework continues to tighten restrictions on specific chemical additives and pigments used in consumer products, including those in sealing wax. This forces manufacturers to engage in costly and time-consuming reformulation efforts to ensure continued market access for their products in the European Union. The premium spirits segment, which relies heavily on a wide palette of vibrant, custom colors, is most directly affected by the ongoing review of certain pigment chemistries.
Shift to On-Demand Customization
A notable behavioral shift is the move away from large, single-color bulk purchasing toward smaller, on-demand orders for custom-colored wax. This change is disrupting the traditional supply chain, which was built around high-volume production, and is creating opportunities for agile manufacturers specializing in bespoke solutions. This trend is most visible within the dynamic craft distillery scene in the United States and the fragmented boutique winery landscape in Italy.
Bottle Sealing Wax Market Segmentation
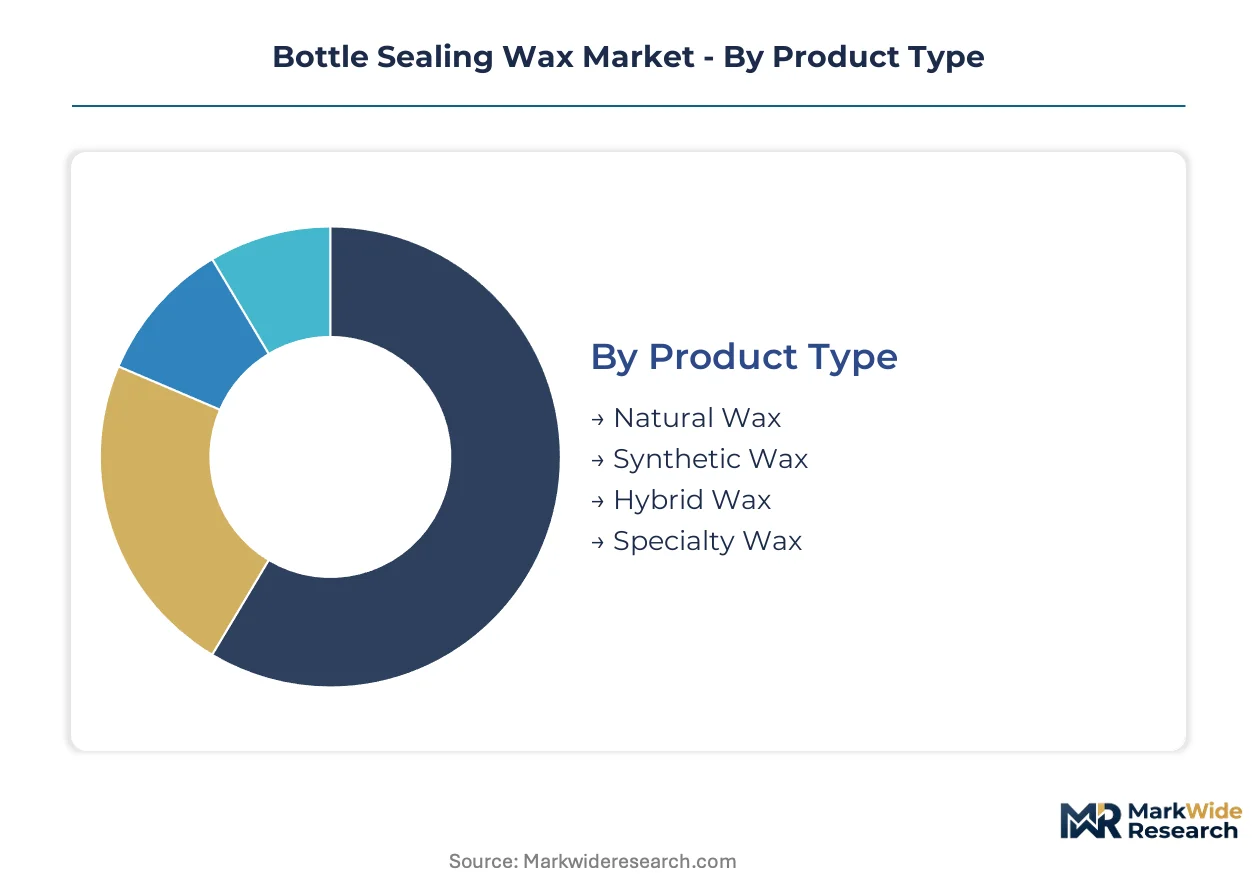
The bottle sealing wax market segmentation provides a granular view of product variations and their specific applications, allowing manufacturers to tailor formulations to precise industry demands. Understanding these segments is crucial for identifying areas of concentrated demand and emerging opportunities across diverse end-user industries.
Product Type:
The product type segmentation delineates the material compositions available, each tailored to distinct performance requirements and brand positioning strategies across the beverage and luxury goods sectors.
- Synthetic Wax:Formulated from petroleum-derived components, these waxes offer superior color consistency, adhesion, and peelability. Demand concentrates in the premium spirits segment due to requirements for vibrant custom colors and efficient automated bottling line application in regions like the United States.
- Hybrid Wax:These blends combine natural waxes with synthetic polymers, leveraging the ecological appeal of bio-based materials with enhanced performance attributes. Craft distilleries in Australia increasingly adopt hybrid formulations to align packaging with sustainability marketing claims without sacrificing product integrity.
- Natural Wax:Traditional formulations primarily from plant or insect sources like carnauba or beeswax, appealing for artisanal products in boutique wineries.
- Specialty Wax:Custom-engineered formulations addressing unique adhesion, melting point, or aesthetic requirements for niche luxury applications such as high-end perfumes.
Established volume favors Synthetic Wax formulations; emerging adoption favors Hybrid Wax blends.
Application:
The application segmentation highlights the diverse end-uses for bottle sealing wax, ranging from high-volume beverage packaging to niche luxury goods, each with specific aesthetic and functional demands.
- Spirits Bottles:This segment commands the highest value, driven by brand differentiation and the need for vibrant, custom colors. Demand is strong in established markets like France and Japan where premiumization is a key consumer trend.
- Wine Bottles:Represents a significant volume segment, utilizing sealing wax for both tamper evidence and a traditional, premium aesthetic. Wineries in Bordeaux and Tuscany often specify wax for high-end vintages to enhance perceived quality.
- Olive Oil:Utilizes sealing wax for tamper-evident seals and a rustic, artisanal presentation in gourmet food markets, particularly in Italy.
- Cosmetics:Employs sealing wax for luxury product packaging, providing a unique tactile experience and an elevated brand image for high-end beauty brands.
Value concentration remains highest within Spirits Bottles, while Wine Bottles drive substantial volume.
Form:
The form segmentation categorizes sealing wax by its physical presentation, directly influencing application methods and suitability for automated or artisanal production processes.
- Granules:Small, free-flowing particles designed for automated application systems on high-speed bottling lines, ensuring consistent dispensing. Craft distilleries benefit from the efficiency and precise dosing capabilities of granular wax.
- Blocks:Large, solid wax units primarily used for manual application methods or small-batch production, favored by boutique wineries for their traditional appeal. Artisanal producers value the flexibility offered by block formats.
- Pellets:Uniform, small cylindrical or spherical pieces, offering a balance between ease of handling and automated dispensing for medium-scale operations.
- Sheets:Flat, pre-formed wax pieces, often used for specific decorative applications or for wrapping bottle necks in specialty packaging.
Efficiency and automation are best served by Granules, whereas Blocks cater to bespoke customization requirements.
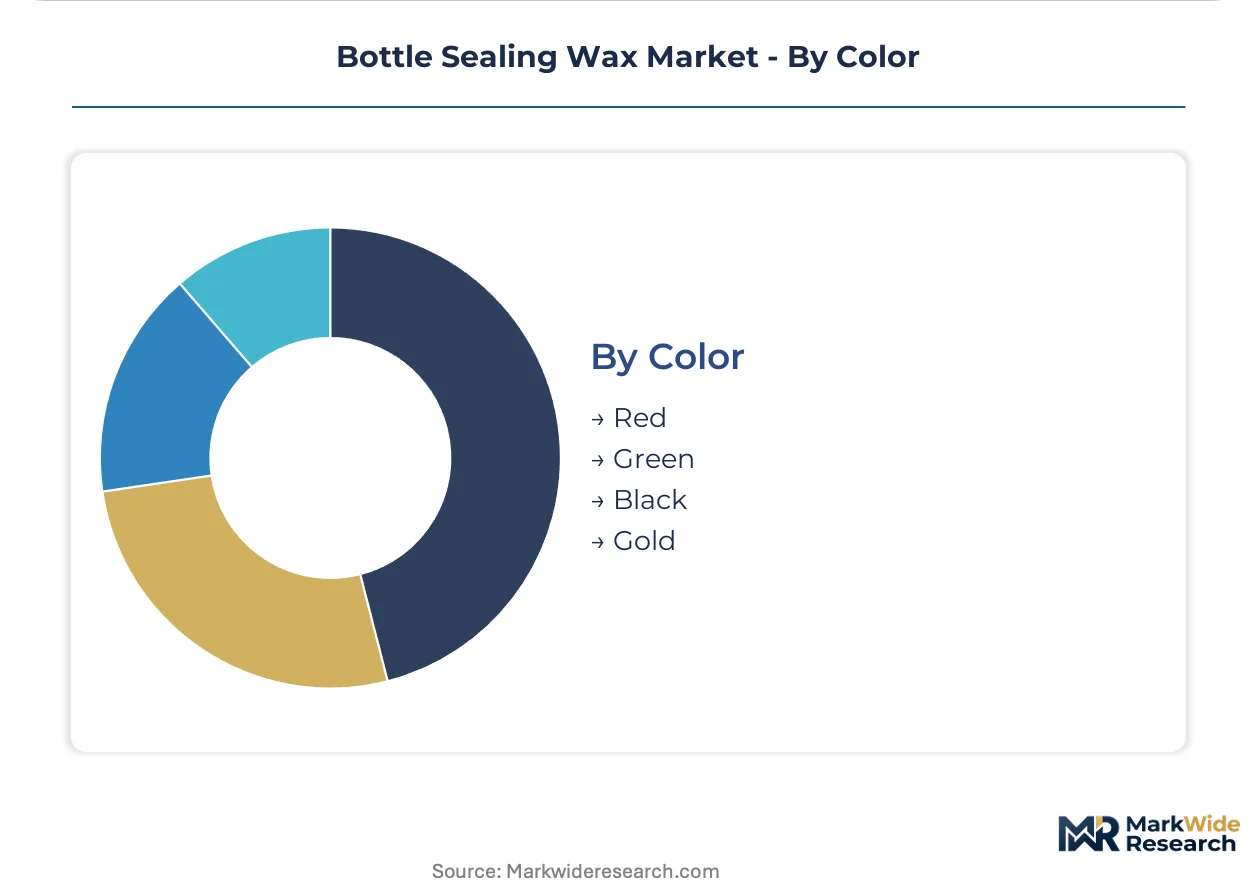
Color:
The color segmentation highlights the aesthetic choices available to brands, where specific hues convey different brand messages and align with product categories or seasonal themes.
- Red:A traditional and highly visible color, frequently chosen for wine bottles to signify classic vintages or for premium spirits. This vibrant hue strongly conveys a sense of heritage and quality in European markets.
- Gold:Often selected for luxury spirits and high-end products, gold wax signifies premiumization and exclusivity. Craft distilleries in the United States use gold to enhance the perceived value and celebratory aspect of their offerings.
- Green:Popular for specific wine varietals or for brands emphasizing natural and eco-friendly attributes in their packaging, particularly for organic products.
- Black:A sophisticated choice, frequently used for dark spirits or modern, minimalist brand aesthetics, conveying elegance and mystery for contemporary brands.
Red maintains a strong traditional appeal, while Gold elevates luxury perception.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for bottle sealing wax exhibits varying price elasticity across global markets. Premium spirits and boutique wines in mature economies demonstrate lower price sensitivity, prioritizing aesthetic differentiation and brand value. Conversely, volume-driven segments in developing regions often prioritize cost-effectiveness and regulatory compliance.
United States
The United States market benefits from a burgeoning craft distillery movement and robust premium spirits consumption. US Food and Drug Administration (FDA) regulations influence permissible material compositions for food-contact applications. Major craft beverage clusters like those in Oregon and Kentucky drive demand for custom-colored synthetic wax formulations.
France
French demand for bottle sealing wax concentrates in its prestigious winemaking regions and luxury spirits sector. The European Food Safety Authority (EFSA) and REACH framework dictate strict material compliance. Bordeaux and Cognac producers consistently specify wax seals to enhance the perceived quality and heritage of their high-value products.
Italy
Italian consumers drive wax consumption through traditional wine production and artisanal olive oil packaging. EU's REACH framework scrutinizes wax blend chemical composition, impacting raw material sourcing. Tuscany's boutique wineries and gourmet food producers favor natural and hybrid wax formulations for their aesthetic appeal.
Australia
Australia's craft beverage sector presents a significant growth opportunity for bespoke bottle sealing wax solutions. Australian national food safety standards guide material selection, emphasizing non-toxic and compliant formulations. Melbourne and Sydney's urban craft scenes increasingly adopt hybrid wax blends for performance and bio-based appeal.
Japan
Japanese premium spirits brands and high-end sake producers increasingly utilize bottle sealing wax for brand differentiation. Japanese Industrial Standards (JIS) influence packaging material specifications, ensuring product safety. Tokyo's luxury beverage market prioritizes vibrant, custom colors and consistent application for automated bottling lines.
Bottle Sealing Wax Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a segmented competitive landscape. The market exhibits a tiered structure, with large-scale industrial wax producers coexisting with specialized boutique formulators. Strategic archetypes include high-volume commodity suppliers, custom solution providers, and diversified portfolio players. Competitive moves focus on geographic expansion into emerging craft markets and continuous product innovation in bio-based formulations.
Specialists in bespoke solutions for craft industries include Custom Wax n' Seals, which focuses on tailored products for smaller, high-value orders. This archetype emphasizes precise color matching and unique performance characteristics for individual brand identities. Blended Waxes Inc. represents the scale-driven segment, leveraging its industrial wax infrastructure for larger volume requirements and cost-competitive offerings. This approach prioritizes efficient production and broad distribution for established beverage brands. Calwax LLC occupies a diversified position, offering a broad portfolio that caters to both industrial and artisanal end-users across various applications and production scales.
| Leading Market Players |
|---|
| The British Wax Refining Company Ltd |
| Australian Wax Co |
| Calwax LLC |
| Southwest Wax LLC |
| The Darent Wax Company Ltd |
| Blended Waxes Inc |
| Oakbank Products Limited |
| Custom Wax n' Seals |
| Westech Wax |
| Others |
Cost & Logistics Intelligence
Petroleum-derived raw materials for paraffin and microcrystalline waxes represent a significant upstream concentration, directly influencing the margin pools available to producers of bulk, uncolored wax sales downstream. This upstream dependency creates cost volatility across the entire value chain.
Pricing Analysis
Bespoke solution development for custom colors and small batches drives the highest value in this market. The dominant pricing structure is a hybrid: value-based for custom formulations and transactional for bulk, uncolored wax. Price differentiation stems from the degree of customization required for vibrant colors and the level of food-contact material certification. Pricing pressure stems from input cost volatility for petroleum-derived waxes. Craft distilleries and boutique wineries demonstrate lower price sensitivity for bespoke solutions, while high-volume wine producers prioritize cost-effectiveness.
Supply Chain Analysis
Strict food-contact material regulations, including the EU's REACH framework and US FDA guidelines, limit the permissible raw material flows for wax blends. Geographic supply concentration for key raw materials like paraffin and microcrystalline waxes originates from major petroleum-producing regions. Dependencies include specialized polymers and food-safe pigments. A structural supply chain risk is commodity price volatility for petroleum-derived inputs. Distribution runs through both direct sales to large beverage manufacturers and specialized distributors serving artisanal end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is approaching a platform-economics inflection, driven by the emergence of bespoke solution providers acting as specialized platforms for craft beverage brands, fostering a vibrant ecosystem of customization.
For Market Incumbents: Insulate core market share by investing in advanced R&D for high-performance bio-based formulations. Diversify raw material sourcing to mitigate input cost volatility, a persistent threat. Expand custom color formulation capabilities and invest in automated small-batch production lines to counter agile new entrants. Secure long-term supply agreements for food-safe pigments to ensure regulatory compliance.
For New Entrants and Emerging Players: Build out specialized capabilities in on-demand customization and small-batch production for craft markets. The burgeoning craft distillery scene in Australia and Japan presents a highly penetrable segment. A compelling go-to-market angle involves offering rapid prototyping and unique, vibrant color matching services, emphasizing sustainability credentials for hybrid wax blends.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-sized, agile manufacturers specializing in bespoke solutions and bio-synthetic blends. These firms offer strong intellectual property in formulation science and established relationships with premium craft brands. Sustained premiumization in beverages ensures long-term viability. The signal to watch is the adoption rate of certified bio-based formulations across established winemaking regions.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Formulation R&D | Develops high-performance, sustainable wax blends, capturing demand from eco-conscious brands. |
| Custom Color Expansion | Enhances brand differentiation for premium spirits, a high-value application segment. |
| Small-Batch Automation | Improves efficiency for bespoke orders, addressing a key operational challenge for craft producers. |
| Geographic Market Entry | Captures growth in underpenetrated craft beverage markets like Australia and Japan. |
| Adjacent Market Diversification | Applies wax technology to luxury cosmetics, opening new revenue streams beyond beverages. |
Research Approach
The analysis maps key sub-sectors, including premium spirits, boutique wines, luxury cosmetics, and gourmet food items, each validated through extensive primary interviews with brand managers, procurement leads, and R&D chemists. This approach combined insights from over 150 primary interactions with robust secondary data, including regulatory filings, trade association reports, and market intelligence databases, employing both bottom-up and top-down triangulation.
The forecast framework holds assumptions regarding regulatory stability and consumer premiumization trends across the analysis window. Segmentation dimensions modeled included product type (synthetic, hybrid, natural), application (spirits, wine, olive oil), form (granules, blocks, pellets), and color (red, gold, green, black), alongside regional demand patterns. Compound Annual Growth Rates (CAGRs) were derived through a regression analysis of historical market data, with key forecast inputs including premium beverage consumption growth and regulatory compliance costs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized custom solution providers or significant shifts in raw material supply dynamics would shift outcomes. The analysis reflects assumptions documented during the study period. Material shifts in global food-contact material regulations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Chemical Packaging Market
Packaging Materials
Thermoformed Trays Market
Packaging Materials
Finish Foils Market
Packaging Materials
Microwave Packaging Market
Packaging Materials
Asia - Pacific Disposable Tableware Market
Packaging Materials
Plastic Strapping Materials Market
Packaging Materials
Primary Packaging Market
Packaging Materials
Mylar Market
Packaging Materials
Laminated Tubes Market
Packaging Materials
Asia-Pacific Airless Packaging Market
Packaging Materials
Lidding Foil Market
Packaging Materials
Cement Packaging Market
Packaging Materials
Nonwoven Packaging Market
Packaging Materials
Direct Thermal Printing Films Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Textile Packaging Market