
 Smart Bottle Market | 2026-2036
Smart Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Bottle Market Intelligence
The shift towards asset-light manufacturing models, reliant on contract electronics assemblers, is narrowing the barrier to entry for new market participants. This dynamic allows digitally native brands to compete effectively against established consumer goods companies. Hidrate Spark leverages its early-mover advantage in hydration tracking software and app integration. LARQ differentiates through its proprietary UV-C sterilization technology embedded within the bottle cap, creating a premium health-focused niche.
A smart bottle is a reusable beverage container integrated with electronic components to monitor and report data, such as liquid intake or temperature. These devices typically incorporate sensors and wireless connectivity, like Bluetooth, to sync with a user's mobile application. Hydration tracking bottles constitute the largest product segment, driven by consumer interest in personal wellness. The corporate gifting application represents a high-margin opportunity, where branding and customization are key value propositions.
Market access requires adherence to electronics and material safety standards. Regulations like the FCC's rules on radio frequency emissions in the United States and the EU's CE marking for consumer electronics are critical hurdles. Materials in contact with beverages must also comply with guidelines from bodies such as the FDA. Future competitive advantage depends on balancing advanced feature integration with battery life optimization and data privacy assurances.
Market Dynamics
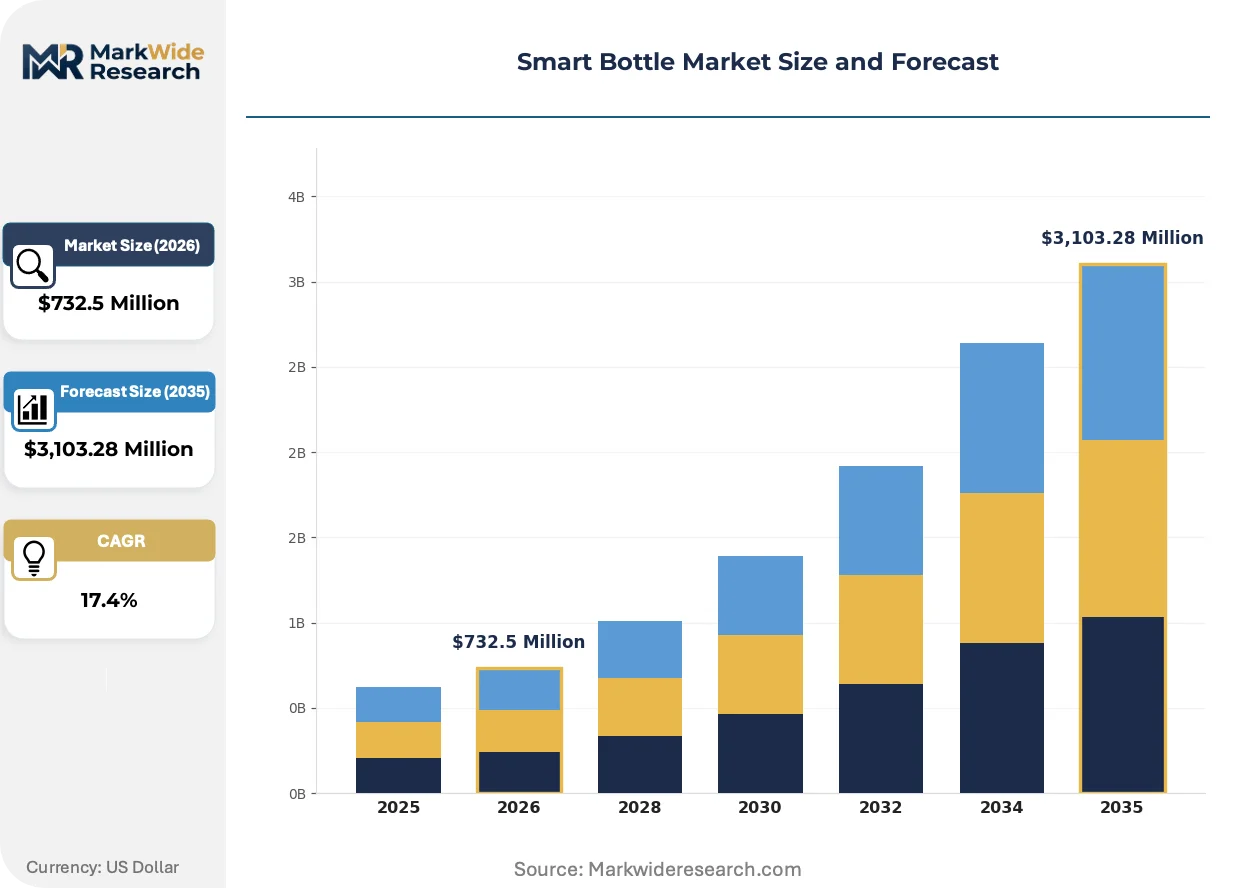
The convergence of personal health tracking and accessible contract electronics manufacturing defines the market structure. This allows new entrants to focus on software and user experience, challenging established consumer goods firms.
Growth Catalysts
- Bluetooth Low Energy (BLE):This standard's low power use extends battery life, critical for bottles requiring constant smartphone connectivity for hydration tracking.
- Corporate Gifting Channel:High-margin opportunities exist in corporate wellness, where firms buy branded bottles for employee health programs and promotions.
- Demand for Health Metrics:The trend of quantifying personal health, especially in fitness, drives adoption of devices that track daily water intake.
Market Restraints
- High Unit Price:The premium cost versus traditional bottles restricts adoption to a smaller consumer segment, limiting mass-market penetration.
- Power Dependency:The need for regular charging introduces an inconvenience and potential point of failure not found in conventional water bottles.
- Electronics Compliance:Products face complex end-of-life rules, like the EU's WEEE Directive, which increases manufacturer compliance costs.
Strategic Opportunities
- Health Ecosystem Integration:API partnerships with fitness apps embed hydration data into a user's digital health profile, increasing the bottle's utility.
- Water Quality Sensing:Adding sensors for contaminants creates a new value proposition around water safety and purification for health-conscious consumers.
- Geographic Expansion:Tech-savvy markets with a rising wellness focus, including South Korea and Australia, offer growth beyond current US-centric demand.
Industry Challenges
- Data Privacy and Security:Manufacturers must navigate complex data laws like GDPR to secure user health information, adding significant compliance overhead.
- Supply Chain Vulnerability:Dependency on specialized electronic components creates exposure to global semiconductor shortages and logistical disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bottle Market |
| Market Size in 2026 | $732.5 Million |
| Market Size in 2035 | $3,103.28 Million |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Water Bottles, Temperature Control Bottles, Hydration Tracking Bottles, UV Sterilization Bottles Connectivity: Bluetooth, Wi-Fi, NFC, RFID, LoRaWAN Application: Fitness & Wellness, Corporate Gifting, Outdoor Recreation, Healthcare Monitoring, Travel & Leisure End User: Fitness Enthusiasts, Corporate Clients, Outdoor Sportspeople, Medical Patients, Travelers |
| Companies Covered | Philips, Thermos, Hidrate Spark, NOERDEN, Zak Designs, LARQ, WaterH, CrazyCap, EQUA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bottle Market Strategic Shifts & Innovations
Product evolution is shifting from novelty gadgets toward integrated health tools, driven by software sophistication and new sterilization technologies. This change reflects a maturing market where verifiable health benefits are key differentiators.
In-cap UV-C LED technology provides water purification by neutralizing harmful microorganisms. Health-conscious consumers in the premium segment are the primary adopters. The core value proposition is migrating from passive data tracking to active on-the-go water sterilization, creating a new health-tech category.
Regulations for radio frequency emissions, like FCC Part 15 in the US and the EU's Radio Equipment Directive, are non-negotiable. Compliance requires rigorous, costly testing for all products using wireless technologies. This disproportionately impacts new entrants who must factor certification timelines and costs into their go-to-market strategy.
A significant demand-side shift involves the rise of direct-to-consumer (DTC) e-commerce, bypassing traditional retail. This model allows brands to control customer experience and data, engaging users through social media. This trend is most visible in the US, where brands build loyalty via app-centric ecosystems and subscriptions.
Smart Bottle Market Segmentation
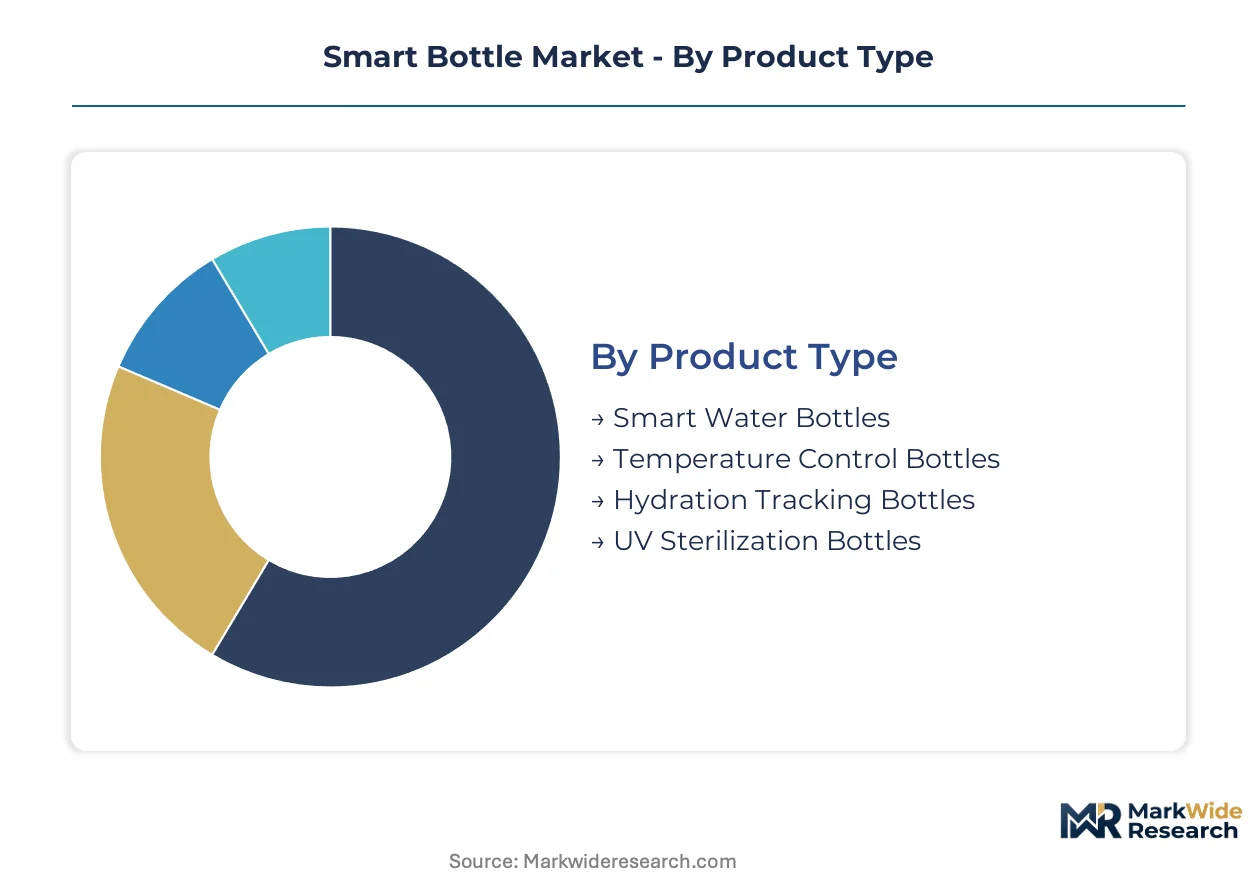
Market segmentation provides a granular view of the smart bottle ecosystem, highlighting distinct product offerings, underlying technologies, and target user groups. This structured breakdown allows for a precise understanding of demand drivers and competitive dynamics within specific niches.
Product Type:
The use-case spectrum for smart bottles ranges from simple hydration reminders to advanced sterilization and temperature control features.
- Hydration Tracking Bottles:These devices incorporate sensors to measure liquid intake and often sync data to a mobile application, providing personalized hydration goals. Demand is concentrating within the United States, driven by a strong consumer electronics market and a culture of health tracking.
- UV Sterilization Bottles:Featuring integrated UV-C LED technology, these bottles neutralize harmful microorganisms in water, offering a purification solution. Health-conscious consumers in premium segments are the primary adopters, seeking enhanced water safety.
- Smart Water Bottles:These are general-purpose bottles with basic electronic components, often providing simple reminders or temperature alerts.
- Temperature Control Bottles:These bottles maintain beverage temperature, catering to users who prefer drinks at specific warmth or coolness.
Established volume favors Hydration Tracking Bottles; emerging adoption favors UV Sterilization Bottles.
Connectivity:
Connectivity options vary widely in cost and complexity, influencing device functionality and user experience.
- Bluetooth:This wireless standard, particularly Bluetooth Low Energy (BLE), enables efficient, low-power communication between the bottle and a smartphone. Its low power use extends battery life, critical for bottles requiring constant smartphone connectivity.
- Wi-Fi:Wi-Fi connectivity offers higher data throughput and longer range than Bluetooth, enabling more complex data synchronization and potentially cloud-based features. Devices with Wi-Fi typically command a higher unit price due to increased component costs and power consumption.
- NFC:Near Field Communication facilitates quick, short-range data exchange, primarily used for pairing or quick data transfers without extensive setup.
- RFID:Radio-Frequency Identification tags allow for passive tracking or identification, useful in inventory management or specialized corporate applications.
- LoRaWAN:This long-range, low-power wide-area network protocol suits applications requiring extended battery life and broad geographic coverage, often for industrial or remote monitoring.
Bluetooth remains the prevalent connectivity standard; Wi-Fi integration signifies a premium feature set.
Application:
Customer type dictates the primary application of smart bottles, from individual health tracking to corporate wellness programs.
- Fitness & Wellness:This segment involves individuals using smart bottles to monitor hydration, supporting their exercise routines and overall health goals. The trend of quantifying personal health, especially in fitness, drives adoption.
- Corporate Gifting:Companies purchase branded smart bottles for employee health programs, client appreciation, or promotional events. This application represents a high-margin opportunity where branding and customization are key value propositions.
- Outdoor Recreation:Smart bottles with rugged designs and advanced features like water purification cater to hikers, campers, and outdoor enthusiasts.
- Healthcare Monitoring:In medical settings, smart bottles assist patients in adhering to prescribed fluid intake, particularly for conditions requiring strict hydration management.
- Travel & Leisure:Travelers seek features like sterilization or temperature control for convenience and health assurance on the go.
Fitness & Wellness applications generate substantial demand; Corporate Gifting offers a strategic high-value channel.
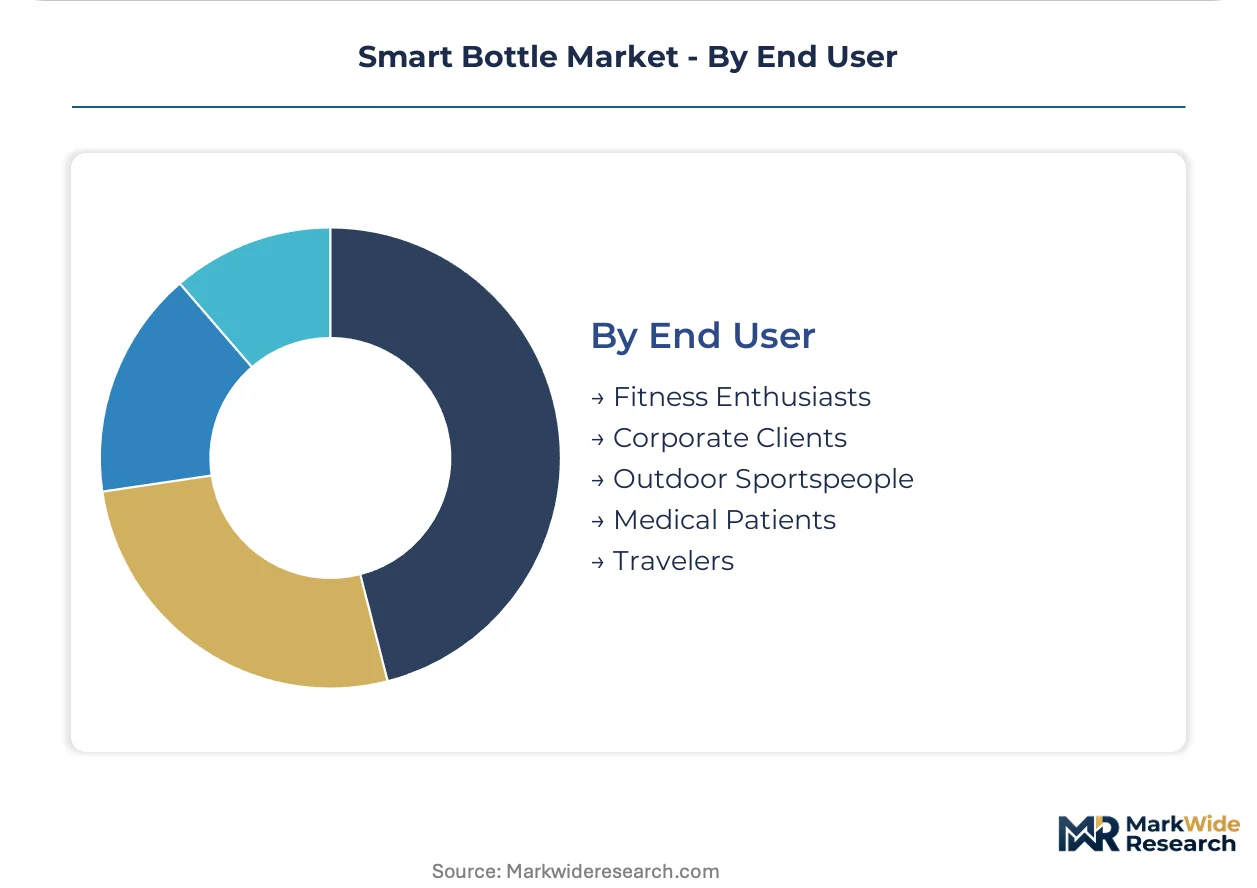
End User:
Supply concentration is influenced by the purchasing power and specific needs of distinct end-user groups.
- Fitness Enthusiasts:Individuals actively engaged in physical activities who prioritize personal health metrics, including precise hydration tracking. This group aligns directly with the demand for health metrics.
- Corporate Clients:Businesses and organizations procuring smart bottles in bulk for employee wellness initiatives or promotional activities. The corporate gifting channel provides a high-margin opportunity for manufacturers.
- Outdoor Sportspeople:Consumers participating in activities like hiking, cycling, or camping, requiring durable and often purification-enabled smart bottles.
- Medical Patients:Individuals with health conditions where consistent fluid intake is critical, often under the guidance of healthcare professionals.
- Travelers:Consumers seeking convenience and health assurance while traveling, valuing features like water purification or temperature control.
Fitness Enthusiasts constitute a large individual consumer base; Corporate Clients represent a significant bulk purchasing segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for smart bottles varies significantly, with premium models commanding higher margins in the United States compared to more price-sensitive markets like India. This disparity influences product development and market entry strategies for manufacturers. Demand for advanced features often justifies higher unit costs in developed economies.
United States
The United States exhibits robust demand for smart bottles, driven by a strong consumer electronics market and a pervasive health tracking culture. Manufacturers must comply with the FCC's rules on radio frequency emissions for wireless components. Innovation hubs in California foster new feature integration and software development for connected devices.
Germany
German consumers prioritize product quality and advanced engineering, fueling demand for premium smart bottles. Products require CE marking for market access and adhere to the WEEE Directive for electronic waste management. Major industrial centers like Munich drive research into durable materials and efficient power management.
South Korea
South Korea's tech-savvy population and early adoption of innovative gadgets create a receptive market for smart bottles. Electronic devices must obtain KC certification to ensure compliance with national safety and performance standards. Seoul's vibrant tech ecosystem pushes rapid iteration in design and connectivity.
Japan
Japanese consumers seek precision engineering and compact, aesthetically pleasing designs in their smart bottle purchases. Devices must comply with the Telecommunications Business Act for wireless communication and adhere to JIS standards for material quality. Tokyo serves as a significant hub for consumer electronics R&D, focusing on miniaturization and interfaces.
Australia
Australian consumers, driven by an active outdoor lifestyle, increasingly adopt smart bottles for hydration tracking and water purification. Wireless devices must meet ACMA regulations for radio equipment to operate legally within the country. Major metropolitan areas like Sydney and Melbourne are centers for fitness technology, integrating smart bottle data.
Smart Bottle Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical sensors and connectivity modules. The smart bottle market exhibits a tiered structure, with established consumer goods companies coexisting with agile digitally native brands. Strategic archetypes include technology-first innovators focusing on advanced features and lifestyle brands emphasizing design and user experience. Market players engage in strategic partnerships to integrate health ecosystems and pursue targeted acquisitions for intellectual property.
Specialists in hydration tracking technology, such as Hidrate Spark, exemplify the software-centric approach, leveraging app integration for user engagement and data visualization. LARQ occupies a position within the premium health-focused segment, emphasizing proprietary purification technology embedded in the bottle cap for enhanced water safety and differentiation. Philips, a global consumer electronics firm, represents the entry of established brands into the smart bottle space. These larger entities bring extensive manufacturing capabilities and broader consumer trust, often focusing on integrating smart features into existing product lines to capture diverse market segments.
| Leading Market Players |
|---|
| Philips |
| Thermos |
| Hidrate Spark |
| NOERDEN |
| Zak Designs |
| LARQ |
| WaterH |
| CrazyCap |
| EQUA |
| Others |
Cost & Logistics Intelligence
Global semiconductor shortages act as a critical risk vector, directly influencing pricing tier spreads across smart bottle models and shaping the industry's reliance on diversified contract manufacturing hubs. This dependency on specialized electronic components creates exposure to global supply fluctuations and logistics disruptions.
Pricing Analysis
Corporate Clients anchor the smart bottle market's pricing structure, favoring contract-based long-term offtake for bulk orders. Price differentiation stems from integrated UV-C sterilization technology and advanced app integration capabilities. Pricing softness currently runs through the basic smart bottle segment due to increased competition from new entrants. Fitness Enthusiasts exhibit higher price sensitivity compared to corporate buyers seeking branded customization and employee wellness solutions.
Supply Chain Analysis
Contract electronics assemblers, concentrated in China and South Korea, hold significant manufacturing capacity for smart bottle components. The supply chain draws from critical inputs like specialized sensors, Bluetooth Low Energy (BLE) modules, and food-grade plastics. Global semiconductor shortages represent a significant structural risk, impacting production timelines and costs. Distribution primarily runs through direct-to-consumer (DTC) e-commerce channels and corporate gifting programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart bottle market currently faces a capability gap, specifically in balancing advanced feature integration with long-term battery life optimization and robust data privacy assurances.
For Market Incumbents:Pre-empt digitally native brands by investing heavily in proprietary software development and API partnerships to deepen health ecosystem integration. Acquire smaller firms with specialized intellectual property in water quality sensing or advanced material science. Expand manufacturing capabilities in regions with stable regulatory environments to mitigate supply chain vulnerability. Prioritize adherence to evolving data privacy regulations like GDPR, leveraging a strong compliance track record as a competitive advantage.
For New Entrants and Emerging Players:Pursue niche applications such as healthcare monitoring for specific medical conditions or rugged outdoor recreation segments. Target tech-savvy markets with rising wellness focus, including South Korea and Australia, leveraging direct-to-consumer e-commerce for market entry. Differentiate through verifiable health benefits, like certified water purification, rather than just passive data tracking. Focus on user experience and seamless app integration to build early brand loyalty.
For Investors and Strategic Acquirers:The market sits at an early growth phase that favors technology-first innovators with strong software platforms or unique intellectual property. Long-term viability depends on firms that can scale manufacturing while ensuring compliance with stringent electronics and material safety standards. Acquisition targets should include companies with proven expertise in data privacy and security, or those holding key patents in sterilization or sensing technologies. Quarterly review of API partnership adoption rates and new material compliance certifications is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Software Specialists | Integrates advanced analytics and user experience capabilities into existing product lines. |
| Investment in UV-C LED R&D | Enhances water purification efficiency and reduces component costs for sterilization bottles. |
| Expansion of Corporate Gifting Channels | Captures high-margin opportunities through branded products for employee wellness programs. |
| Compliance with Global RF Regulations | Ensures market access in key regions like the US (FCC) and EU (CE marking). |
| Partnerships with Fitness Ecosystems | Embeds hydration data into broader digital health profiles, increasing bottle utility. |
Research Approach
Desk research of electronics industry reports, consumer wellness market data, and regulatory body filings preceded structured interviews with product development engineers, supply chain managers, and regulatory compliance officers. This approach combined primary insights with secondary validation, ensuring a comprehensive understanding of market dynamics. Both bottom-up and top-down triangulation methods were applied to refine market sizing and segmentation.
The forecast framework assumed stable technological advancements in Bluetooth Low Energy (BLE) and UV-C LED integration across the analysis window. Segmentation dimensions modeled included product type, connectivity, application, end-user, and key geographic regions. Compound annual growth rates were derived from historical data trends and projected adoption rates for smart bottle technologies. Consumer spending on personal wellness devices served as a critical forecast input.
Macroeconomic conditions sit as an overlay; deviation in global trade policies or raw material costs would shift the trajectory of smart bottle market expansion. Forecasts reflect assumptions regarding regulatory stability and consumer technology adoption. Quarterly review of consumer electronics sales data and material commodity prices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Packaging
Self Cooling Packaging Market
Smart Packaging
Digital Packaging Market
Smart Packaging
Intelligent Tamper-Proof Packaging Market
Smart Packaging
Smart Medication Packaging Market
Smart Packaging
Smart Label Market
Smart Packaging
Global Personalized Packaging Market
Smart Packaging
Smart Tag Packaging Market
Smart Packaging
Smart Retail Packaging Market
Smart Packaging
Global Nano Enabled Packaging Market
Smart Packaging
North America Smart Label Market
Smart Packaging
Smart Packaging Market
Smart Packaging
Smart Food Packaging Market
Smart Packaging
Global Spoil Detection-Based Smart Label Market