
 Bullet Bottles Market | 2026-2036
Bullet Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Bullet Bottles Market Outlook
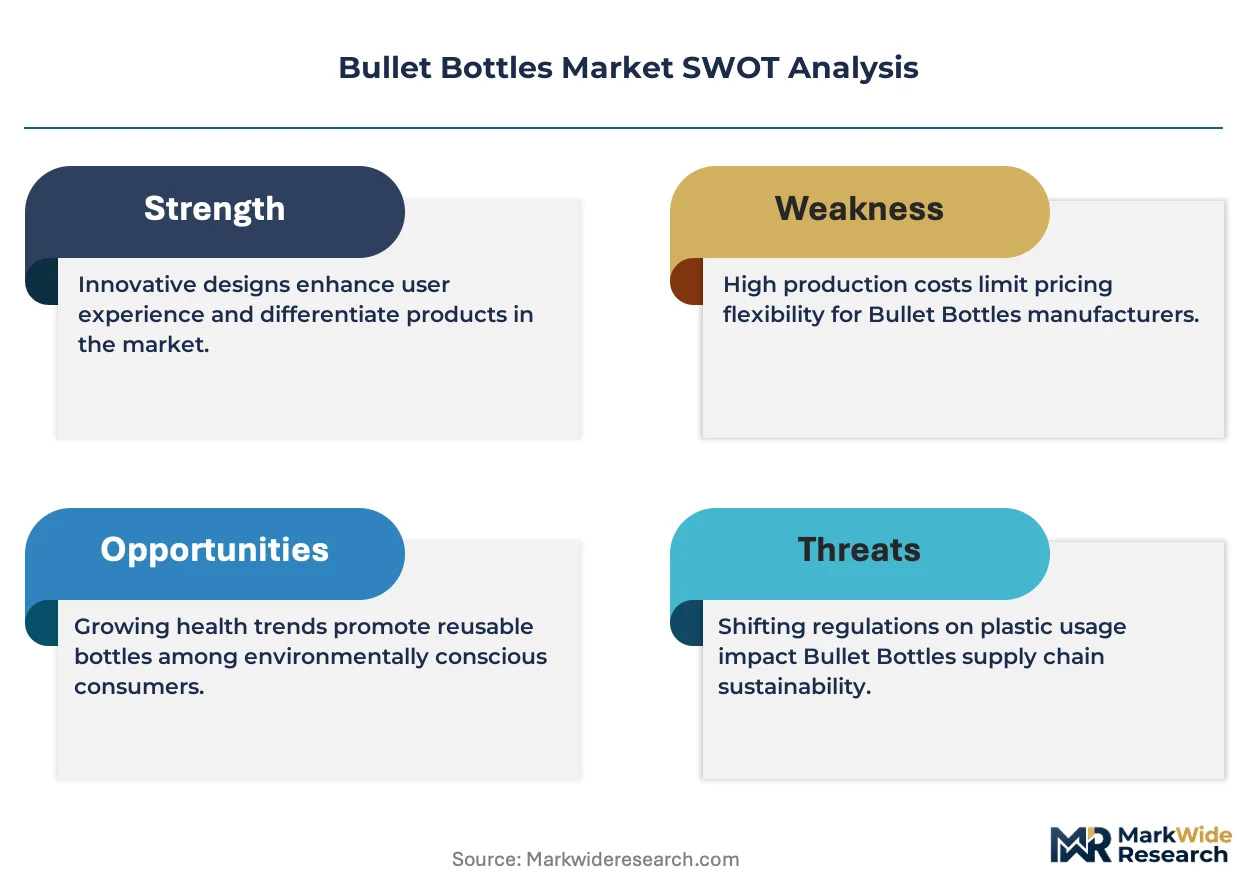
Capital-intensity divergence between blow-molding specialists and full-service packaging integrators is redrawing competitive boundaries in bullet bottles. Amcor leverages global manufacturing scale across multiple polymer platforms to serve multinational pharmaceutical clients. O. Berk anchors North American production with deep tooling libraries and rapid prototyping capabilities for custom bullet profiles. Comar differentiates through medical-grade cleanroom operations that sustain FDA-compliant output for sterile liquid formulations.
Bullet bottles are narrow-necked cylindrical containers with rounded shoulders, typically manufactured through injection blow molding or extrusion blow molding in PET, HDPE, or glass, designed for controlled dispensing of liquids, serums, and concentrated solutions. Pharmaceutical-grade HDPE and amber glass variants dominate current volume due to chemical stability requirements and light-blocking properties for photosensitive compounds. The cosmetics end-user segment leads absolute consumption as serum and essential oil brands adopt bullet profiles for premium shelf differentiation, while pump closure configurations represent the fastest-growing format as skincare brands prioritize measured dosing precision over traditional screw caps.
FDA 21 CFR Part 177 compliance governs indirect food and drug contact materials for US-bound bullet bottles, while REACH restricts phthalate plasticizers and heavy metal additives across European supply chains. EPA guidelines on recycled content thresholds are pressuring converters to validate post-consumer resin streams for pharmaceutical secondary packaging applications. Stakeholders must monitor evolving child-resistant certification standards from the CPSC and emerging state-level extended producer responsibility laws that could reshape material recovery economics for single-use bullet bottle formats.
Market Dynamics
Pharmaceutical serialization mandates and child-resistant certification requirements are compressing supplier qualification timelines while consolidating procurement toward pre-qualified molders with validated cleanroom operations.
Growth Catalysts
- REACH Substance Restrictions:European chemical compliance is filtering out non-compliant Asian suppliers, redirecting contract volumes toward certified European and North American converters with validated resin traceability systems.
- Serum Concentration in Cosmetics:Skincare brands are specifying bullet profiles for high-viscosity formulations, creating dedicated tooling demand that favors molder flexibility over commodity scale.
- Injection Blow Molding Precision:Tighter neck tolerances and wall-thickness control are enabling 0.5ml dose accuracy for ophthalmic applications, opening prescription-grade segments previously served by glass ampoules.
Market Restraints
- HDPE Resin Volatility:Feedstock fluctuations tied to naphtha cracking economics in the US Gulf Coast are compressing converter margins on fixed-price annual contracts.
- Single-Source Tooling Risk:Complex bullet shoulder geometries require proprietary mold designs that lock buyers into multi-year supplier relationships with limited second-source options.
- Glass Substitution Ceiling:Amber borosilicate retains dominance for parenteral light-sensitive biologics, capping polymer penetration in the highest-value pharmaceutical tier.
Strategic Opportunities
- Post-Consumer Recycled Content Mandates:California's extended producer responsibility framework is creating first-mover advantage for converters with FDA-validated rPET streams for secondary pharmaceutical packaging.
- Connected Closure Integration:Near-field communication chips embedded in pump dispensers are enabling adherence tracking for clinical trial supply chains, merging physical packaging with digital data capture.
- Contract Manufacturing Concentration in India:CDMO cluster expansion around Hyderabad and Ahmedabad is generating localized demand for regional blow-molding capacity with reduced import lead times.
Industry Challenges
- Cleanroom Operator Certification:ISO 14644-1 Class 7 compliance requires specialized technician training that outpaces vocational pipeline output in key manufacturing regions.
- Validation Timeline Compression:Pharmaceutical customers are demanding PPQ completion in 12-week windows that strain mold qualification protocols and resin stability testing cycles.
- Legacy ERP Integration:Serialization data exchange with customer SAP and Oracle systems requires custom middleware development that delays supplier onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bullet Bottles Market |
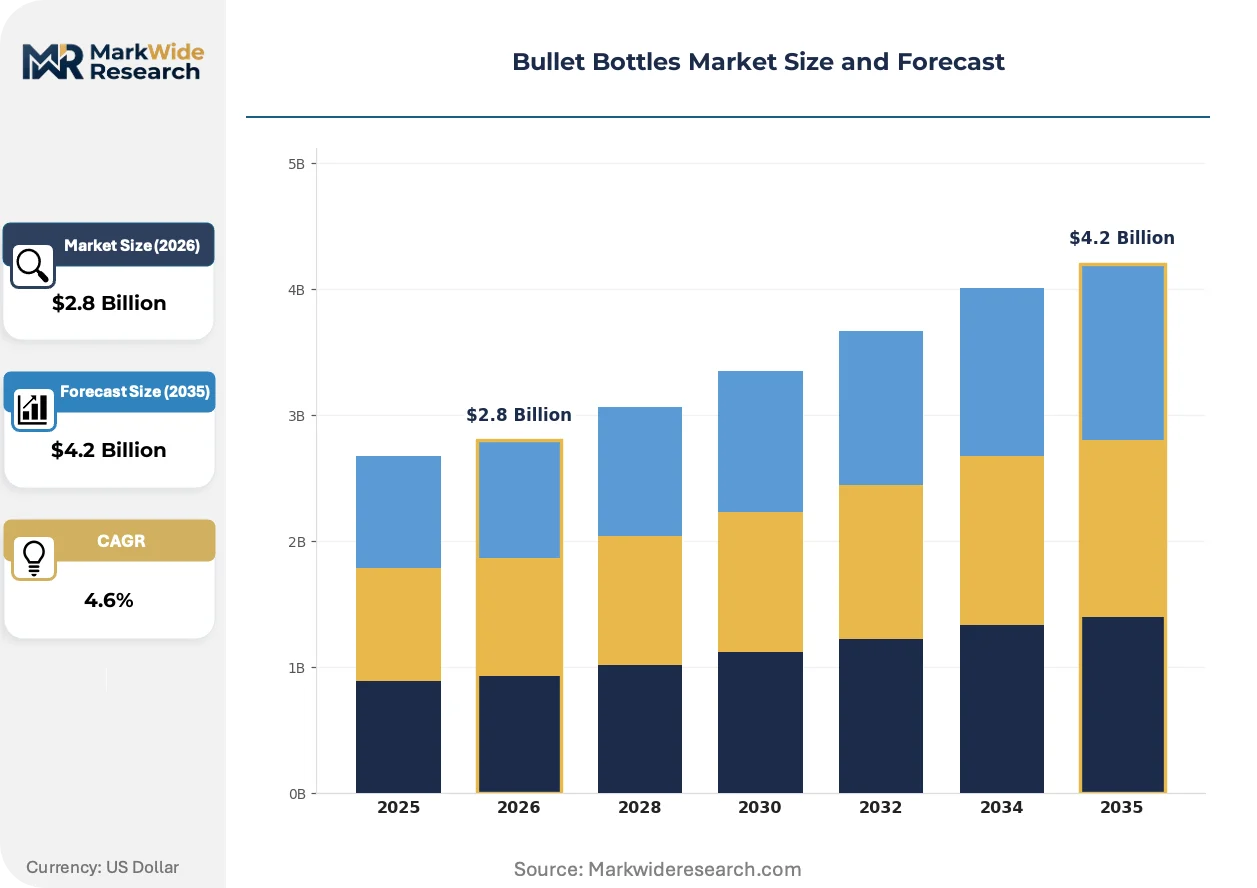
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass, Plastic, Aluminum, Stainless Steel Closure Type: Cork, Screw Cap, Pump, Spray End User: Cosmetics, Pharmaceuticals, Food & Beverage, Household Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Amcor, O. Berk, Comar, CKS Packaging, Plastic Bottles Inc, Novio Packaging Group, CL Smith Packaging, Carry, Maynard & Harris Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bullet Bottles Market Strategic Shifts
Material science advances and regulatory digitization are redefining performance benchmarks for bullet bottle specifications across pharmaceutical and cosmetics supply chains.
Multi-layer co-injection blow molding is displacing single-barrier constructions in oxygen-sensitive pharmaceutical applications. Specialty pharma contract packagers in Germany and Switzerland are qualifying these structures for peptide formulations with 24-month stability requirements. The technology is displacing conventional HDPE monolayer bottles in segments where headspace oxygen ingress previously mandated glass or aluminum overwrap.
EU MDR Annex I general safety and performance requirements are tightening biocompatibility documentation for all patient-contact packaging components. Converters must now supply extractables and leachables profiles that extend beyond traditional USP Class VI testing to cover novel polymer additives. Medical device manufacturers in Ireland and the Netherlands are responding by consolidating supplier bases toward partners with dedicated E&L analytical capabilities.
Direct-to-clinic distribution models are compressing traditional wholesale channels for clinical trial materials. Biopharma sponsors in Massachusetts and California are specifying shipper-integrated bullet bottle configurations that combine primary container, desiccant, and temperature indicator in single-SKU formats. This consolidation is most visible in oncology trial supply chains where patient kit complexity reduction accelerates site activation timelines.
Bullet Bottles Market Segmentation
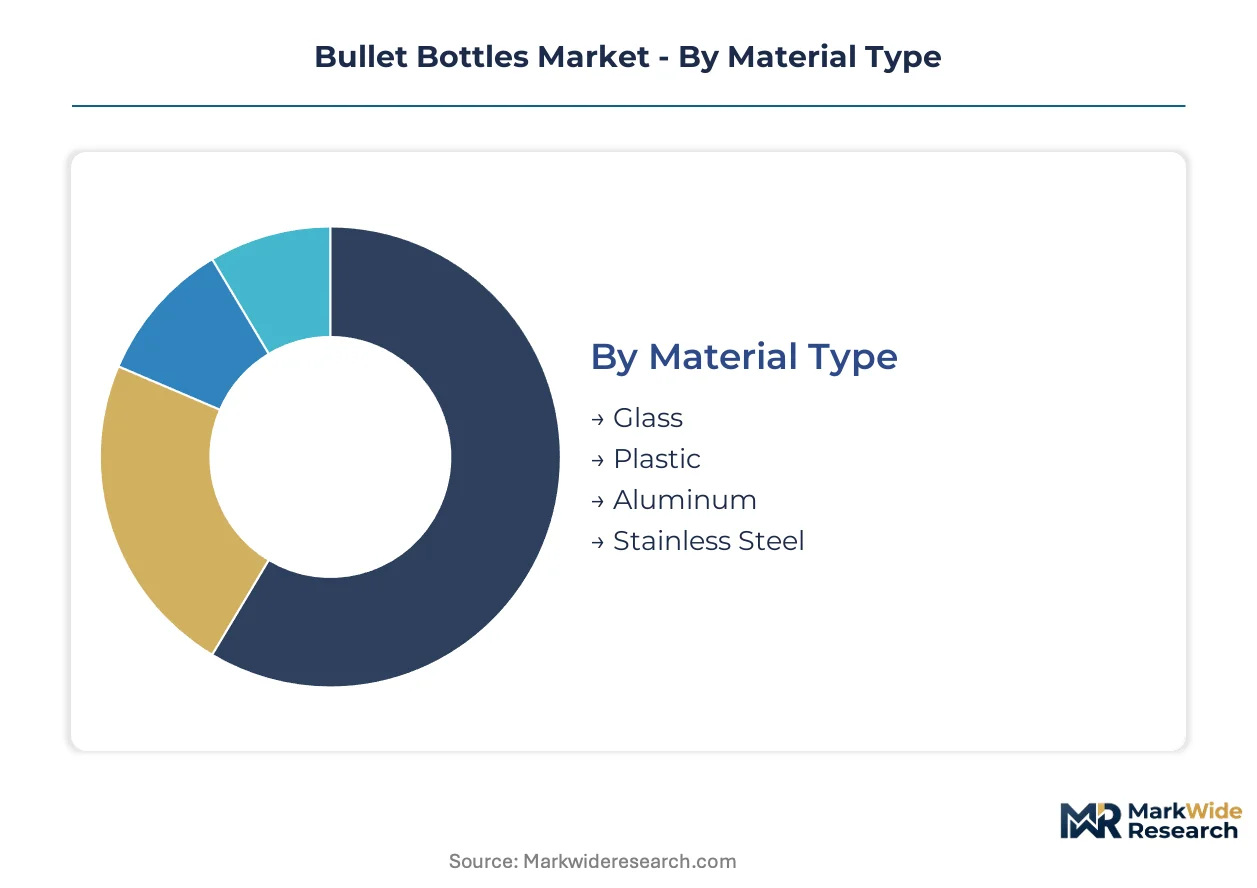
Bullet bottle procurement decisions cascade from material compliance requirements through closure functionality to end-use sterilization protocols. Each segmentation layer carries distinct regulatory, cost, and performance trade-offs that reshape supplier qualification criteria across pharmaceutical and cosmetics supply chains.
Material Type:
FDA 21 CFR Part 177 and REACH substance restrictions create divergent compliance pathways for each material substrate, filtering supplier bases by validated resin traceability or glass leachables documentation.
- Glass:Amber borosilicate and soda-lime formulations dominate parenteral and photosensitive pharmaceutical applications. FDA Type I/II/III classification systems and USP <660> surface durability testing govern supplier selection for sterile liquid formulations in the United States and Germany.
- Plastic:PET and HDPE variants produced through injection blow molding or extrusion blow molding command cosmetics volume due to design flexibility and weight advantages. REACH-compliant phthalate-free formulations are redirecting contract volumes toward certified European converters with validated additive traceability.
- Aluminum:Lightweight barrier protection for fragrance and essential oil segments with oxygen-sensitive headspace requirements.
- Stainless Steel:Premium durability positioning in reusable personal care and high-end household dispensing applications.
Plastic handles the majority of throughput; Glass is the fastest mover on share for regulatory-sensitive pharmaceutical tiers.
Closure Type:
Measured dosing precision and child-resistant certification requirements are elevating closure selection from commodity decision to formulation-critical specification.
- Pump:Metered-dose mechanisms enable 0.5ml accuracy for ophthalmic and serum applications. Skincare brands in California and Massachusetts specify pump configurations for high-viscosity formulations where screw caps risk contamination or dosing inconsistency.
- Screw Cap:Tamper-evident ring designs remain standard for oral liquid pharmaceuticals. FDA-compliant induction sealing validation and torque specification testing sustain demand across generic drug packaging in the United States.
- Cork:Premium positioning in artisanal essential oil and fragrance segments with natural material preference signaling.
- Spray:Fine-mist atomization for topical pharmaceutical and cosmetic toner applications requiring even coverage distribution.
Screw Cap retains volume leadership across price-sensitive pharmaceutical contracts; Pump is expanding most quickly as serum concentration climbs in cosmetics formulations.
End User:
Cleanroom certification requirements and extractables-leachables documentation intensity separate pharmaceutical procurement from cosmetics sourcing protocols.
- Cosmetics:Serum, essential oil, and high-viscosity skincare brands specify bullet profiles for premium shelf differentiation. Contract packagers in Germany and Switzerland are qualifying multi-layer co-injection structures for oxygen-sensitive peptide formulations with extended stability requirements.
- Pharmaceuticals:Sterile liquid formulations and ophthalmic applications demand ISO 14644-1 Class 7 cleanroom operations. FDA validation timelines and PPQ completion windows are compressing supplier qualification toward molders with pre-validated medical-grade capabilities.
- Food & Beverage:Flavor concentrate and sauce dispensing with indirect food contact compliance requirements.
- Household:Cleaning concentrate and personal care refill applications with durability and cost optimization priorities.
Cosmetics generates the largest absolute order volume; Pharmaceuticals is gaining share fastest as serialization mandates and child-resistant certification consolidate procurement toward qualified molders.
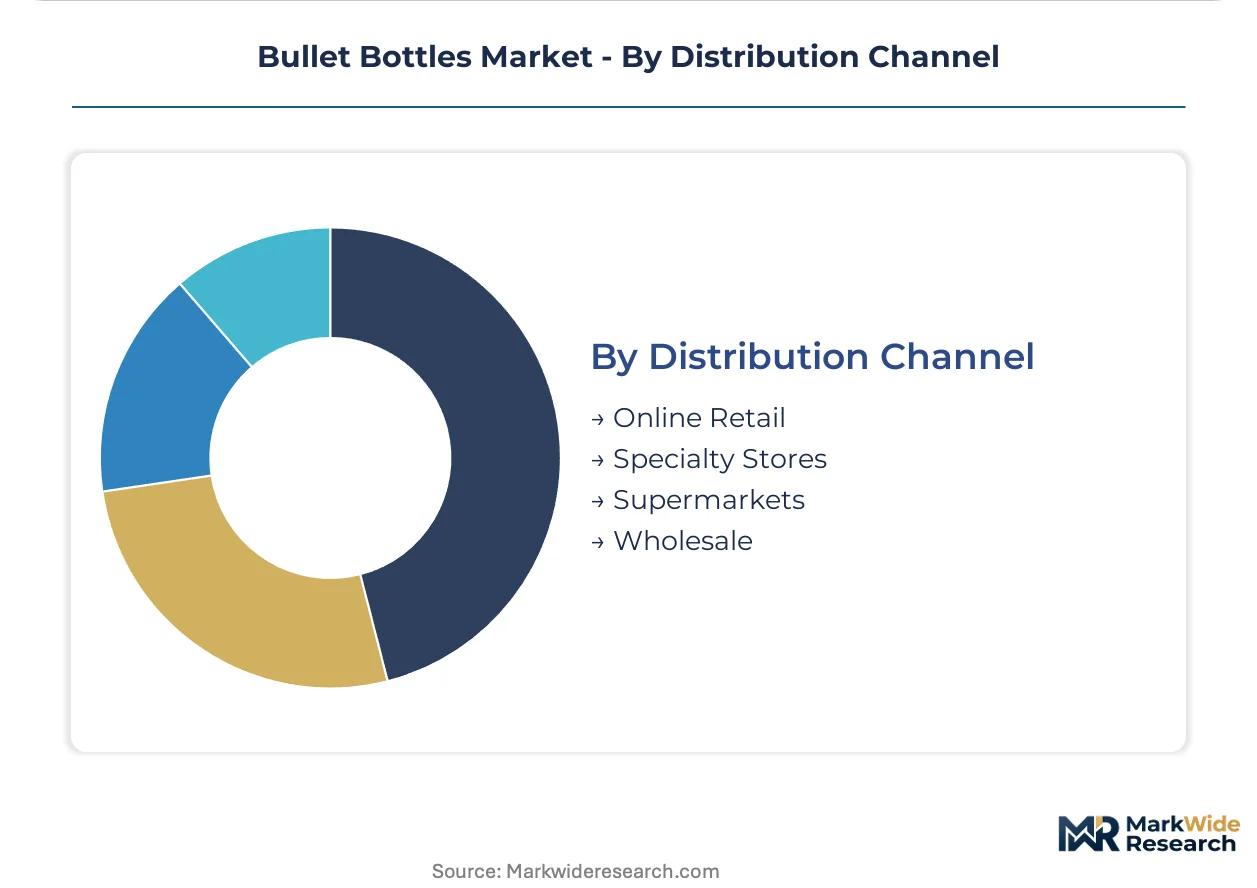
Distribution Channel:
Direct-to-clinic trial supply and e-commerce fulfillment are fragmenting traditional wholesale concentration with divergent packaging configuration requirements.
- Wholesale:Bulk pharmaceutical and cosmetics contract manufacturing supply with palletized logistics and extended payment terms.
- Specialty Stores:Premium cosmetics and fragrance positioning with display-ready secondary packaging requirements.
- Online Retail:Direct-to-consumer fulfillment demands shipper-integrated configurations combining primary container, desiccant, and temperature indicator in single-SKU formats for oncology trial supply chains in Massachusetts and California.
- Supermarkets:Mass-market household and personal care volume with price-competitive standard specifications.
Wholesale channels handle the majority of pharmaceutical throughput; Online Retail is climbing the fastest as biopharma sponsors compress site activation timelines through direct distribution models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for bullet bottles varies sharply by end-use tier. Pharmaceutical procurement in the United States and Germany tolerates premium pricing for validated cleanroom output, while cosmetics contract packagers in China and India face acute price compression on standard HDPE formats.
United States
FDA 21 CFR Part 177 compliance timelines and child-resistant certification requirements from the CPSC drive supplier consolidation toward pre-qualified molders. Massachusetts and California biopharma sponsors specify shipper-integrated bullet bottle configurations for direct-to-clinic trial distribution. The Greater Boston cluster concentrates demand for ophthalmic-grade injection blow molding with 0.5ml dose accuracy.
Germany
REACH substance restrictions on phthalate plasticizers and heavy metal additives filter contract volumes toward certified converters with validated resin traceability. The ECHA regulatory framework redirects sourcing from non-compliant Asian suppliers toward European molders. Specialty pharma contract packagers around Stuttgart and Munich qualify multi-layer co-injection structures for oxygen-sensitive peptide formulations.
China
NMPA medical device regulations and GB standards for pharmaceutical packaging materials tighten biocompatibility documentation requirements. Yangtze River Delta cosmetics manufacturers specify bullet profiles for serum and essential oil premium positioning. Contract packaging services cluster near Shanghai and Suzhou to serve domestic skincare brands with rapid tooling turnaround.
India
CDSCO pharmaceutical serialization mandates and child-resistant certification compress supplier qualification timelines toward validated cleanroom operators. CDMO cluster expansion around Hyderabad and Ahmedabad generates localized demand for regional blow-molding capacity. Gujarat-based converters target reduced import lead times for generic drug packaging contracts.
Switzerland
Swissmedic medical device regulations and EU MDR Annex I alignment sustain demand for extractables and leachables documentation beyond USP Class VI testing. Basel-area biopharma sponsors prioritize sterile liquid formulation packaging with ISO 14644-1 Class 7 compliance. The country's precision manufacturing heritage supports premium positioning for ophthalmic and parenteral applications.
Bullet Bottles Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in bullet bottle supply. Global packaging conglomerates leverage multi-polymer platforms and validated cleanroom networks to serve multinational pharmaceutical clients. Mid-scale regional molders compete on tooling flexibility and rapid prototyping for cosmetics custom profiles. The dominant competitive moves involve geographic expansion into CDMO clusters and portfolio diversification toward connected closure integration with near-field communication capabilities.
Among North American packaging specialists, Amcor Plc and O. Berk Company exemplify the integrated leader archetype through global manufacturing scale and deep tooling libraries respectively. Comar LLC occupies a position within the medical-grade specialist tier, representing validated cleanroom operations for FDA-compliant sterile liquid output. These three companies anchor the competitive structure across pharmaceutical and cosmetics end-use segments.
| Leading Market Players |
|---|
| Amcor |
| O. Berk |
| Comar |
| CKS Packaging |
| Plastic Bottles Inc |
| Novio Packaging Group |
| CL Smith Packaging |
| Carry |
| Maynard & Harris Plastics |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with annual volume commitments lock pharmaceutical buyers into fixed-price arrangements that shield converters from HDPE resin volatility while limiting procurement flexibility. These structures concentrate pricing power with molders holding validated cleanroom certifications near Massachusetts and Stuttgart manufacturing clusters.
Pricing Analysis
After-sales tooling maintenance and mold refurbishment contracts drive lifetime value beyond the initial container sale. Three-tier pricing structure across FDA-validated premium, REACH-compliant standard, and generic economy levels separates qualified pharmaceutical molders from commodity cosmetics suppliers. Pricing pressure stems from fixed-price annual contracts confronting Gulf Coast naphtha feedstock swings. Generic drug packagers in India exhibit highest price sensitivity; sterile liquid biologics sponsors in Switzerland tolerate premium positioning.
Supply Chain Analysis
China and Germany anchor injection blow molding capacity for bullet bottle production, with India emerging as regional supply for CDMO clusters around Hyderabad. Resin streams draw from US Gulf Coast petrochemical complexes and Middle Eastern naphtha crackers. Single-source tooling risk for proprietary shoulder geometries creates lock-in vulnerability. Distribution runs through contract packaging services clustered near pharmaceutical manufacturing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bullet bottles constitute a regulatory entrenchment moat where FDA validation timelines and child-resistant certification requirements create switching costs that protect qualified incumbents from commodity competition.
For Market Incumbents: Shield market position through backward integration into medical-grade resin compounding and captive mold fabrication capabilities. Expand cleanroom capacity in Gujarat to intercept Indian CDMO demand before import lead times disadvantage distant competitors. Certification investment in EU MDR Annex I compliance represents the critical defensive lever against emerging European specialists.
For New Entrants and Emerging Players: Anchor in the cosmetics serum segment where premium shelf differentiation tolerates higher per-unit pricing and shorter qualification windows. Target Yangtze River Delta contract packagers seeking rapid tooling turnaround for domestic skincare brands. Go-to-market positioning as flexible prototyping specialists with 4-week mold delivery outflanks integrated leaders on speed.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale regional molders with validated cleanroom infrastructure and established pharmaceutical customer relationships. Long-term viability hinges on serialization-ready capabilities and connected closure integration potential. Monitor California extended producer responsibility enforcement as inflection signal for rPET-validated acquisition targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO 14644-1 Class 7 operations unlock sterile liquid formulation contracts from Basel-area biopharma sponsors. |
| Post-Consumer Recycled Content Validation | FDA-compliant rPET streams secure first-mover positioning under California extended producer responsibility frameworks. |
| Connected Closure Integration | Near-field communication pump dispensers merge physical packaging with digital adherence tracking for clinical trial supply chains. |
| Regional Blow-Molding Footprint | Hyderabad and Ahmedabad proximity reduces import lead times for Indian CDMO generic drug packaging contracts. |
| Multi-Layer Co-Injection Qualification | Oxygen barrier structures displace glass for peptide formulations with 24-month stability requirements in German contract packaging. |
Study Parameters
Cross-validation between primary interviews with pharmaceutical packaging procurement managers, cosmetics brand supply chain directors, and blow-molding operations executives anchors the qualitative findings. Secondary validation draws from FDA 21 CFR filings, ECHA REACH substance restriction updates, CDSCO serialization mandate documentation, and customs trade data on polymer resin flows. Bottom-up capacity assessments at converter facilities triangulate against top-down demand modeling from end-use segment consumption patterns.
Sensitivity analysis around HDPE resin price scenarios and regulatory timeline compression stress-tests the analytical framework across the projection horizon. Segmentation dimensions modeled include material substrate, closure mechanism, end-use sterilization protocol, and regional regulatory cluster. CAGRs derive from weighted average growth rates across these segments calibrated to pharmaceutical serialization rollout pace and cosmetics serum formulation trends.
Material uncertainties — REACH substance restriction expansion, FDA validation timeline compression, naphtha cracking economics volatility — sit outside the modeled envelope. Forecasts reflect assumptions on cleanroom certification pipeline output and resin stability testing cycle durations. Recalibration cycles align with material shifts in extended producer responsibility enforcement and connected closure technology adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Graduated Sample Bottle Market
Beverage Packaging
Tumblers Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
PET Syrup Bottle Market
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
Foamer Bottle Market
Beverage Packaging
Disposable Tea Flask Market
Beverage Packaging
North America Soft Drinks Packaging Market
Beverage Packaging
Beverage Cans Market
Beverage Packaging
United States Aluminum Beverage Cans Market
Beverage Packaging
Can Sleeves Market
Beverage Packaging
Pop-Up Pourer Market
Beverage Packaging
Beverage Cups Market
Beverage Packaging
Cup Sleeves Market
Beverage Packaging
Combi Cans Market
Beverage Packaging
Self-Cleaning Bottle Market