
 Chemical Packaging Market | 2026-2036
Chemical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Packaging Market Intelligence
Asset-light leasing models for reusable intermediate bulk containers is reshaping competitive entry barriers in chemical packaging. Mauser Packaging Solutions leverages its closed-loop pooling network to sustain fleet density across industrial chemical corridors. Greif Inc. anchors North American drum supply through steel and plastic manufacturing scale. SCHUTZ GmbH & Co. KG dominates European IBC refurbishment with integrated blow-molding and steel cage production.
Chemical packaging encompasses engineered containment systems designed to store, transport, and dispense substances ranging from corrosive acids to volatile solvents, with specifications including UN certification for hazardous goods, permeation rates below regulatory thresholds, and compatibility with contents across pH extremes and temperature fluctuations. Drums and intermediate bulk containers capture the majority of volume in bulk chemical logistics, while bottles and smaller containers serve laboratory and specialty chemical segments where precise dosing and contamination control take priority. Plastic resins including HDPE and fluoropolymer composites lead material selection for corrosion resistance, though metal drums retain share in solvent categories where electrostatic discharge control matters.
EPA hazardous waste manifest rules and DOT 49 CFR transport regulations govern container performance in the United States, while REACH and the CLP Regulation in Europe mandate traceable substance classification and compatible packaging materials. These frameworks elevate testing documentation burdens and accelerate replacement cycles for non-compliant legacy inventory. Stakeholders must monitor evolving extended producer responsibility schemes and carbon border adjustments that will recalibrate material choices and regional sourcing patterns.
Market Dynamics
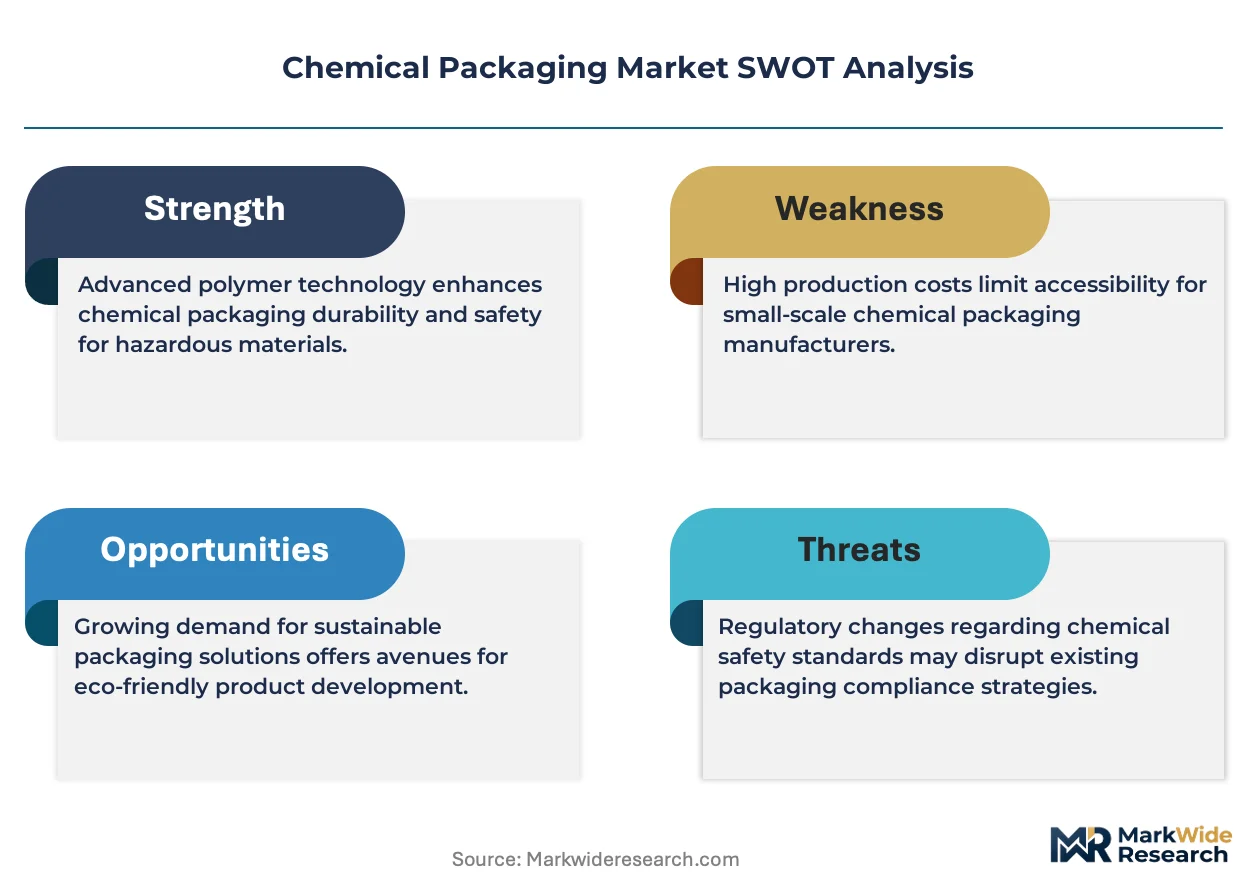
UN certification mandates and REACH compliance deadlines are compressing replacement cycles for legacy chemical containers while elevating barrier-layer specifications across industrial corridors.
Growth Catalysts
- REACH Phase-Out Deadlines:Europe's accelerated substance restrictions under ECHA guidance are forcing integrated producers to upgrade drum and IBC fleets, creating pull for fluoropolymer-lined formats.
- Specialty Agrochemical Expansion:Brazil's crop protection sector is scaling procurement of intermediate bulk containers certified for hazardous pesticide transport.
- Barrier Material Innovation:Multi-layer co-extrusion with ethylene vinyl alcohol cores is extending chemical resistance ranges, enabling HDPE formats to penetrate solvent categories historically served by steel.
Market Restraints
- Resin Input Volatility:HDPE and polypropylene price swings tied to naphtha-cracker economics compress margin visibility for blow-molding operations serving drum markets.
- Steel Cage Supply Concentration:Galvanized steel cage fabrication for IBCs clusters in China's Yangtze Delta, exposing European refurbishers to tariff and logistics friction.
- Permeation Testing Bottlenecks:UN-certified barrier validation requires 180-day organoleptic and chemical resistance protocols that extend new product launch timelines.
Strategic Opportunities
- Indonesian Chemical Corridor Buildout:Batang Integrated Industrial Park is attracting specialty chemical investments that will require localized IBC leasing infrastructure.
- Digital Pooling Platforms:RFID-tracked container fleets combined with blockchain custody records are enabling pay-per-use models that displace capital-intensive ownership.
- EU Carbon Border Adjustment:CBAM phase-in on imported steel and plastics is creating first-mover advantage for regional blow-molding and cage-fabrication capacity.
Industry Challenges
- Competency Gaps in Barrier Engineering:Formulation chemists capable of matching fluoropolymer lining systems to aggressive acid and solvent chemistries remain scarce in Southeast Asian manufacturing hubs.
- Legacy Fleet Retrofit Complexity:Existing HDPE drum molds lack the cooling-channel precision required for thinner-wall, higher-barrier designs, forcing complete asset replacement rather than modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Packaging Market |
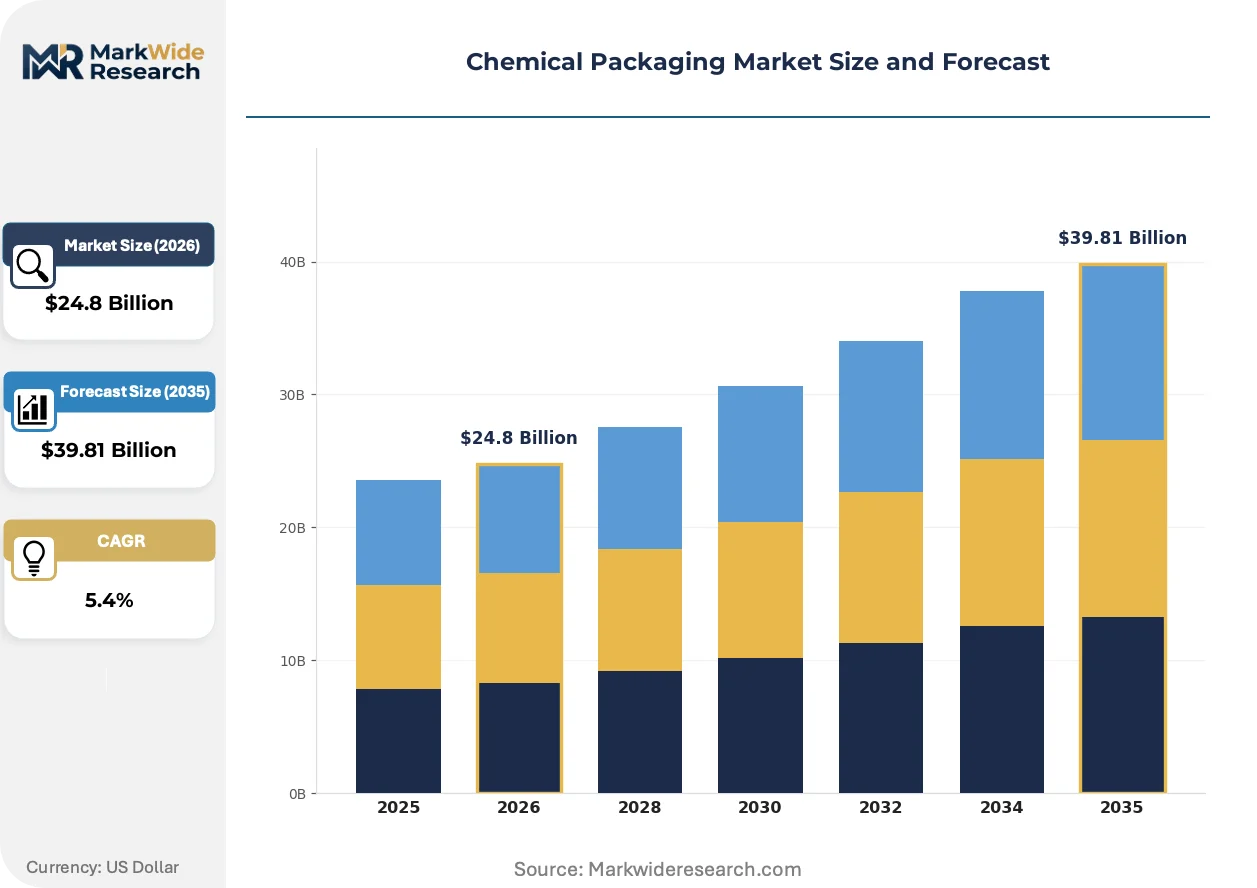
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $39.81 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Drums, Bottles, Containers Packaging Material: Glass, Plastic, Metal, Paper End Use Industry: Chemicals, Pharmaceuticals, Agriculture, Food Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Mauser Packaging Solutions, Greif Inc., Mondi Group, ProAmpac, Berry Global Inc., DS Smith Plc., Amcor plc, International Paper Company, SCHUTZ GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Packaging Market Strategic Shifts & Innovations
Smart container ecosystems and predictive logistics platforms are reconfiguring how chemical producers manage fleet utilization and regulatory traceability across dispersed supply networks.
Embedded RFID sensors combined with cloud-based fleet management software are digitizing custody tracking for hazardous material containers. Specialty chemical distributors in Germany's Rhine-Ruhr corridor are deploying these systems at scale to automate EPA manifest documentation and compress detention times at transloading facilities. The technology is digitizing compliance workflows that previously required manual inspection and paper-based chain-of-custody records.
REACH's updated restriction roadmap for per- and polyfluoroalkyl substances is accelerating substitution toward silicone-modified polyethylene and polyamide barrier layers. ECHA's 2023 restriction proposal on PFAS in industrial applications has triggered reformulation programs among European IBC producers serving agrochemical and pharmaceutical end-uses. The regulation is forcing material transitions in corrosion-resistant packaging ahead of comparable EPA action in the United States.
Leasing structures for reusable IBCs are displacing outright purchase models among mid-volume chemical processors. Food-grade and industrial chemical blenders in the US Gulf Coast are contracting with third-party pool operators to convert fixed container assets into variable operating expenditures. The shift is most pronounced among specialty chemical formulators facing working capital pressure from inventory-heavy business models.
Chemical Packaging Market Segmentation
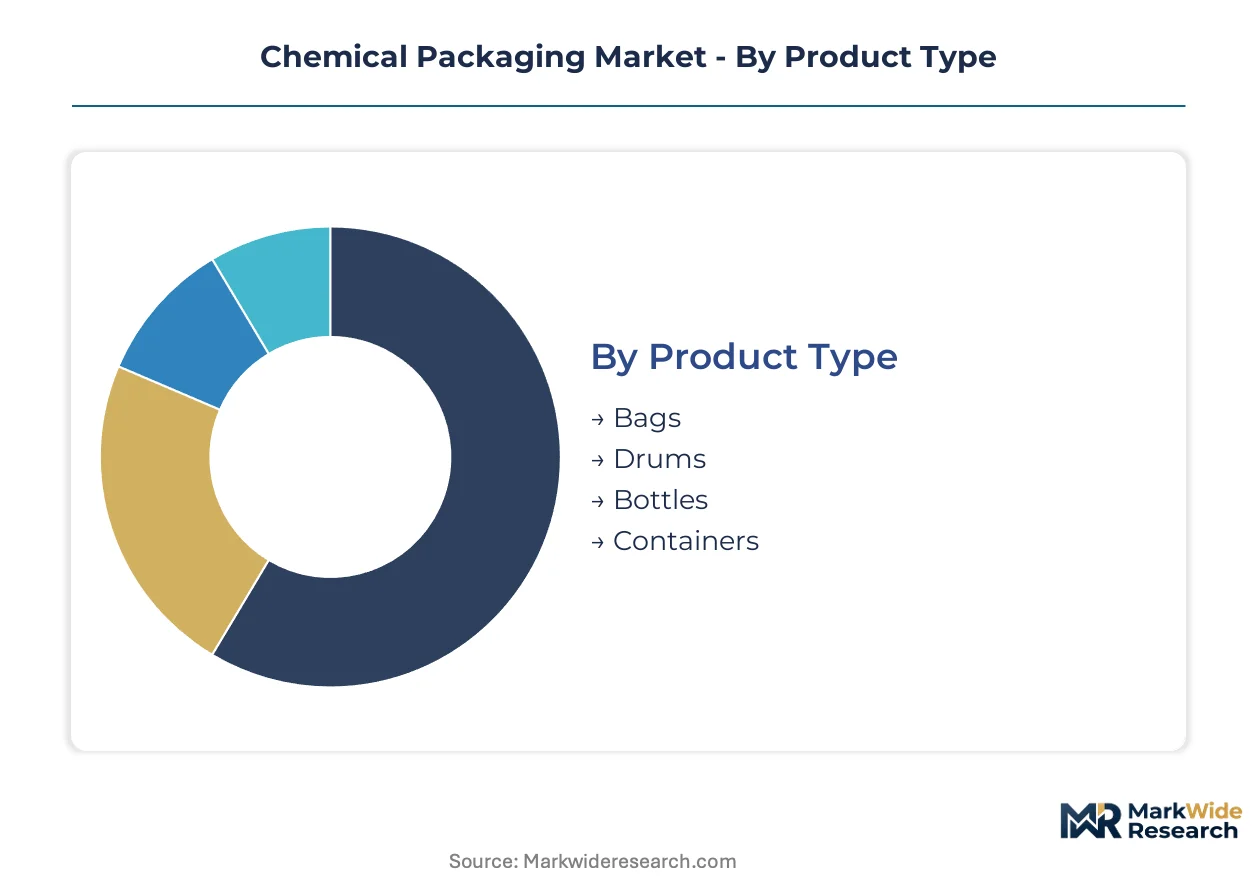
Chemical packaging segmentation reveals divergent service intensity requirements across product formats, with reusable IBC fleets demanding sophisticated refurbishment networks while single-use bottles prioritize rapid turnaround. Material compatibility testing and UN certification documentation create tiered aftermarket obligations that reshape profitability profiles by segment.
Product Type:
After-sales-service intensity varies dramatically across formats, with intermediate bulk containers requiring fleet management infrastructure and drums needing reconditioning networks to sustain reuse economics.
- Drums:Steel and fiber formats dominate bulk chemical logistics, with UN-certified reconditioning cycles extending asset life across five to seven rotations. Rhine-Ruhr chemical corridors source high volumes from integrated producers seeking closed-loop drum recovery programs.
- Containers:Intermediate bulk containers anchor specialty agrochemical distribution in Brazil and Southeast Asia, where galvanized steel cage refurbishment and HDPE bladder replacement create recurring service revenue streams tied to leasing models.
- Bottles:Laboratory and specialty chemical dispensing relies on fluoropolymer-lined and barrier-coated formats requiring minimal post-sale intervention beyond lot traceability documentation.
- Bags:Flexible intermediate bulk containers serve powder and granule chemicals where single-use economics eliminate refurbishment obligations but elevate specification consulting during procurement.
Drums hold the largest share; momentum sits with containers.
Packaging Material:
Material selection drives cost tier stratification, with fluoropolymer composites commanding premium positioning against commodity HDPE and steel alternatives.
- Plastic:HDPE and multi-layer co-extrusion formats with ethylene vinyl alcohol barrier cores are penetrating solvent categories historically served by steel, as Brazilian agrochemical distributors scale procurement of lighter-weight UN-certified alternatives.
- Metal:Cold-rolled steel drums retain dominance in solvent transport where electrostatic discharge control matters, with galvanized cage fabrication for IBCs clustering in China's Yangtze Delta and exposing European refurbishers to tariff friction.
- Glass:Borosilicate and amber glass formats serve pharmaceutical and high-purity chemical segments demanding inert contact surfaces and visible contamination detection.
- Paper:Multiwall paper bags with polyethylene liners capture dry chemical and powder applications where moisture barrier performance must balance disposability against regulatory sift-proof requirements.
Plastic commands volume leadership; fluoropolymer-lined formats are climbing the fastest.
End Use Industry:
Application-specific regulatory burdens create distinct margin profiles, with pharmaceutical packaging demanding validation documentation that agricultural formats escape.
- Chemicals:Industrial chemical producers in Germany's Rhine-Ruhr corridor drive demand for high-volume drum and IBC formats with REACH-compliant barrier specifications and traceable substance classification documentation.
- Agriculture:Brazil's crop protection sector is scaling procurement of UN-certified intermediate bulk containers for hazardous pesticide transport, with specialty agrochemical expansion creating pull for localized leasing infrastructure.
- Pharmaceuticals:cGMP-compliant containers with extractables and leachables validation command premium positioning, as EMA and FDA requirements elevate documentation burdens beyond industrial chemical norms.
- Food:Food-grade IBC leasing is gaining traction among US Gulf Coast blenders converting fixed assets to variable operating expenditures, though penetration remains below industrial chemical applications.
Chemicals anchors volume; agriculture is gaining share fastest.
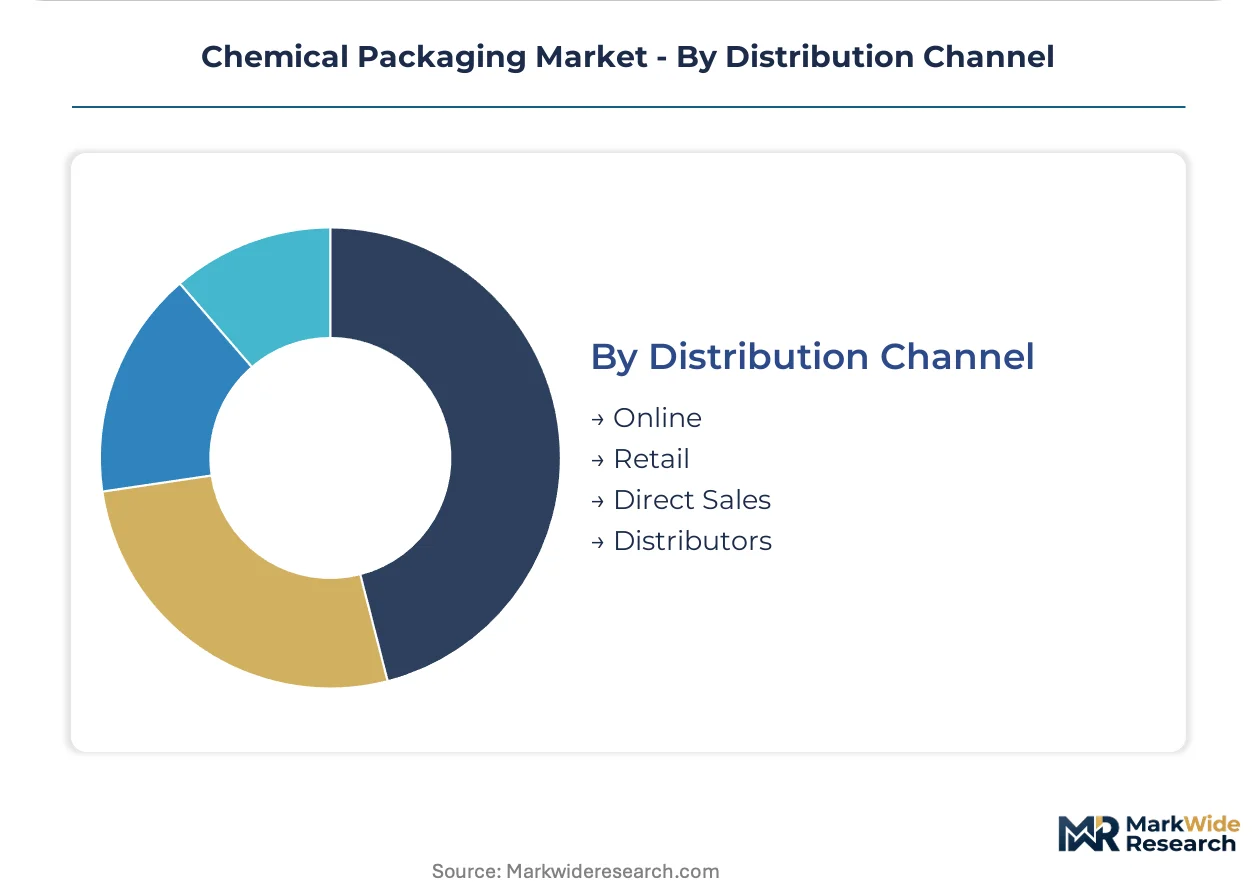
Distribution Channel:
Customer type determines procurement pattern complexity, with integrated producers favoring direct relationships and mid-volume processors accepting third-party pool intermediation.
- Distributors:Specialty chemical distributors in Germany are deploying RFID-tracked container fleets at scale to automate EPA manifest documentation and compress detention times at transloading facilities.
- Direct Sales:Large integrated producers along the Rhine-Ruhr corridor negotiate long-term drum and IBC supply agreements with dedicated refurbishment service tiers.
- Retail:Laboratory chemical suppliers and small-volume processors procure bottles and smaller containers through distributor networks with standardized UN certification packages.
- Online:Digital procurement platforms are emerging for standardized drum specifications, though hazardous material transport restrictions limit pure e-commerce penetration in IBC categories.
Distributors capture the largest share; direct sales retain margin leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance deadlines and EPA hazardous material rule revisions are compressing replacement cycles for legacy container fleets across major chemical producing economies. Substance restriction mandates in Europe and transport certification requirements in the Americas are elevating barrier-layer specifications and UN-certified procurement volumes.
Germany
Rhine-Ruhr chemical corridor producers drive demand for high-volume drum and IBC formats with integrated closed-loop recovery programs. ECHA substance restriction roadmaps under REACH are forcing fluoropolymer-lined container upgrades ahead of PFAS phase-outs. Leverkusen and Ludwigshafen clusters source heavily from regional blow-molding and steel cage fabrication networks.
United States
Gulf Coast specialty chemical blenders are converting fixed container assets to variable leasing expenditures through third-party pool operators. EPA hazardous waste manifest rules and DOT 49 CFR transport regulations govern barrier performance and documentation burdens. Houston and Baton Rouge corridors anchor North American drum supply through integrated steel and plastic manufacturing scale.
Brazil
Specialty agrochemical producers are scaling procurement of UN-certified intermediate bulk containers for hazardous pesticide distribution. ANVISA transport regulations align with international hazardous goods standards while creating localized certification requirements. São Paulo state crop protection formulators drive demand for lighter-weight HDPE alternatives to traditional steel formats.
China
Yangtze Delta galvanized steel cage fabrication clusters supply IBC refurbishment networks across Asia-Pacific, though tariff exposure creates logistics friction for European refurbishers. MEE environmental compliance standards and evolving GB hazardous materials transport codes are tightening domestic container performance thresholds. Shanghai chemical industry parks are localizing blow-molding capacity for regional agrochemical and industrial chemical segments.
Indonesia
Batang Integrated Industrial Park specialty chemical investments are creating demand for localized IBC leasing infrastructure and fleet management services. National hazardous goods transport regulations are aligning with ASEAN framework standards while preserving domestic certification requirements. Java-based chemical processors face competency gaps in barrier engineering for aggressive acid and solvent chemistries.
Chemical Packaging Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered market positions defined by fleet scale versus material innovation. Consolidation patterns favor asset-heavy operators with closed-loop pooling density and integrated refurbishment networks. Three archetypes dominate: scale-driven pool operators with geographic fleet density, material specialists commanding fluoropolymer and multi-layer barrier technology, and regional fabricators anchored to specific chemical corridors. Competitive moves concentrate on M&A to secure refurbishment capacity and strategic partnerships to embed RFID-tracked fleet management software.
Within the scale-driven pool operator tier, Mauser Packaging Solutions and Greif Inc. exemplify archetypes built on fleet density and manufacturing integration. SCHUTZ GmbH & Co. KG occupies a position representing European refurbishment specialization with captive blow-molding and steel cage production capabilities. These three entities anchor competitive positioning across the leasing-model transformation reshaping chemical packaging procurement patterns.
| Leading Market Players |
|---|
| Mauser Packaging Solutions |
| Greif Inc. |
| Mondi Group |
| ProAmpac |
| Berry Global Inc. |
| DS Smith Plc. |
| Amcor plc |
| International Paper Company |
| SCHUTZ GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
Tariff exposure between China's Yangtze Delta steel cage fabricators and European IBC refurbishers determines both pricing tier spreads and supply chain shape across the chemical packaging landscape. This friction elevates landed costs for galvanized cage components while compressing margin visibility for mid-tier blow-molding operations competing against integrated producers with captive supply.
Pricing Analysis
UN certification grade creates the primary spread between premium fluoropolymer-lined formats and commodity HDPE alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects barrier-layer complexity, with REACH-compliant multi-layer co-extrusion commanding substantial premiums over single-wall drums. Cost compression in standard-tier HDPE formats is intensifying because naphtha-cracker resin volatility erodes contract margin predictability. Mid-volume specialty chemical processors exhibit highest price sensitivity, while integrated Rhine-Ruhr producers prioritize certification reliability over unit economics.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculations for IBC refurbishment networks. Geographic supply concentration centers on China's Yangtze Delta for galvanized steel cages, Germany's Rhine-Ruhr corridor for blow-molding capacity, and the US Gulf Coast for integrated drum manufacturing. Raw material dependencies rest on HDPE and polypropylene resin flows from naphtha crackers, cold-rolled steel from integrated mills, and ethylene vinyl alcohol barrier films from specialty polymer producers. Distribution runs through third-party pool operators with RFID-tracked fleet management infrastructure displacing direct ownership models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chemical packaging operates as a defensive-moat market where regulatory entrenchment creates durable competitive positioning. UN certification requirements and REACH compliance deadlines erect switching costs that protect incumbent fleet density while constraining new entrant acceleration.
For Market Incumbents: Harden closed-loop pooling density through strategic refurbishment capacity additions in Indonesia's Batang corridor and Brazil's agrochemical hubs. Mauser Packaging Solutions and SCHUTZ GmbH & Co. KG demonstrate how integrated blow-molding and steel cage production defends against tariff-disrupted competitors. Prioritize fluoropolymer lining formulation capabilities ahead of ECHA PFAS restriction deadlines to capture upgrade cycles from legacy fleet displacement. For New Entrants and Emerging Players: Establish a beachhead in Indonesian IBC leasing infrastructure where localized fleet management services face supply gaps against incoming specialty chemical investments. Digital pooling platforms with blockchain custody records offer the most penetrable wedge, converting mid-volume processors from capital-intensive ownership to pay-per-use models. Target food-grade IBC segments along the US Gulf Coast where working capital pressure drives appetite for variable expenditure structures. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors asset-heavy operators with refurbishment network density. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Acquisition targets should demonstrate integrated barrier engineering capabilities and established UN certification protocols. The signal to watch is EU Carbon Border Adjustment implementation pace, which will recalibrate regional sourcing economics and first-mover advantage for localized blow-molding capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Cage Fabrication | Captive supply of galvanized cages insulates European refurbishers from Yangtze Delta tariff friction. |
| Fluoropolymer Barrier Reformulation Program | Silicone-modified polyethylene substitution ahead of ECHA PFAS restrictions secures REACH compliance continuity. |
| RFID-Tracked Fleet Management Platform | Blockchain custody records automate EPA manifest documentation and compress detention times at transloading facilities. |
| Indonesian IBC Leasing Infrastructure Buildout | Batang Integrated Industrial Park specialty chemical investments create localized demand for fleet management services. |
| Multi-Layer Co-Extrusion Capacity Expansion | Ethylene vinyl alcohol barrier cores enable HDPE formats to penetrate solvent categories historically served by steel drums. |
Research Approach
A spread of perspectives from plant managers at integrated chemical producers, procurement leads at specialty agrochemical distributors, technical R&D directors at blow-molding operations, and fleet operations heads at third-party pool operators converged on the working assumptions. These primary insights were cross-referenced against customs and trade data, Cefic industry reports, SEC 10-K filings from packaging manufacturers, and UN hazardous goods transport certification databases. Bottom-up volume modeling from individual product formats was reconciled with top-down corridor-level demand aggregation.
Demand-supply balance dynamics across the analysis window were assessed through capacity utilization tracking at Rhine-Ruhr blow-molding facilities and Yangtze Delta steel cage fabricators. Segmentation dimensions included packaging format tier, barrier material grade, end-use industry vertical, and regional production hub classification. CAGRs were derived from regression analysis of historical replacement cycle compression against regulatory deadline schedules, with fluoropolymer substitution rates and leasing model penetration serving as industry-specific forecast inputs.
Sensitivities concentrate around ECHA substance restriction timeline adjustments, EPA hazardous waste manifest rule revisions, and resin price volatility from naphtha-cracker economics. Forecasts reflect assumptions about REACH compliance enforcement consistency and ASEAN hazardous goods transport standardization pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Foil Laminates Market
Packaging Materials
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market
Packaging Materials
Die Cut Support Pads Market
Packaging Materials
Cement Packaging Market
Packaging Materials
Refrigerator Door Seal Gaskets Market
Packaging Materials
Anti-Scratch Film Market
Packaging Materials
Vacuum Packaging Market
Packaging Materials
Polystyrene Packaging Market
Packaging Materials
United States Single Use Packaging Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Asia - Pacific Disposable Tableware Market
Packaging Materials
Cold Chain Packaging Materials Market
Packaging Materials
Global Packaging Foams Market
Packaging Materials
Squeeze Tube Market
Packaging Materials
Global Thin Wall Packaging Market
Packaging Materials
Middle East and Africa Single-Use Packaging Market