
 Automated Tray Fill and Seal Machines Market | 2026-2036
Automated Tray Fill and Seal Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Tray Fill and Seal Machines Market Outlook
The capability gap between capital-heavy integrated systems builders and mid-tier assembly houses is collapsing as servo-driven sealing modules become commoditized. MULTIVAC leverages its in-house tooling foundry to control critical die-set supply chains. Robert Bosch anchors European pharmaceutical tray-sealing demand through validated clean-room configurations. JBT Corporation dominates North American protein processing with stainless-steel rotary fillers engineered for USDA washdown protocols.
Automated tray fill and seal machines integrate precision volumetric or gravimetric dosing heads with thermoformed cavity indexing and heat-seal or modified-atmosphere closure stations operating at 60-180 cycles per minute. These systems execute portion control, shelf-life extension, and retail-ready presentation for perishable goods across centralized and co-packing environments. Rotary fillers command the widest installed base in high-volume protein and dairy operations where throughput justifies footprint and capital commitment. Linear fillers gain share in mid-scale facilities retooling for SKU flexibility and rapid changeover between packaged meals and snack formats. Robotic technology represents the fastest-advancing segment as articulated-arm denesters and lidding-placers displace fixed automation in mixed-product lines.
FDA Title 21 CFR regulations governing food-contact substances and USDA FSIS sanitation requirements shape machine material specifications and cleanability design in the United States. The EU F-Gas Regulation and REACH compliance obligations drive refrigerant-sealed modified-atmosphere systems toward alternative gas architectures in European installations. Stakeholders must monitor evolving Extended Producer Responsibility frameworks across multiple jurisdictions as these rules increasingly mandate recyclable mono-material tray formats that constrain seal-bar compatibility and retrofit economics.
Market Dynamics
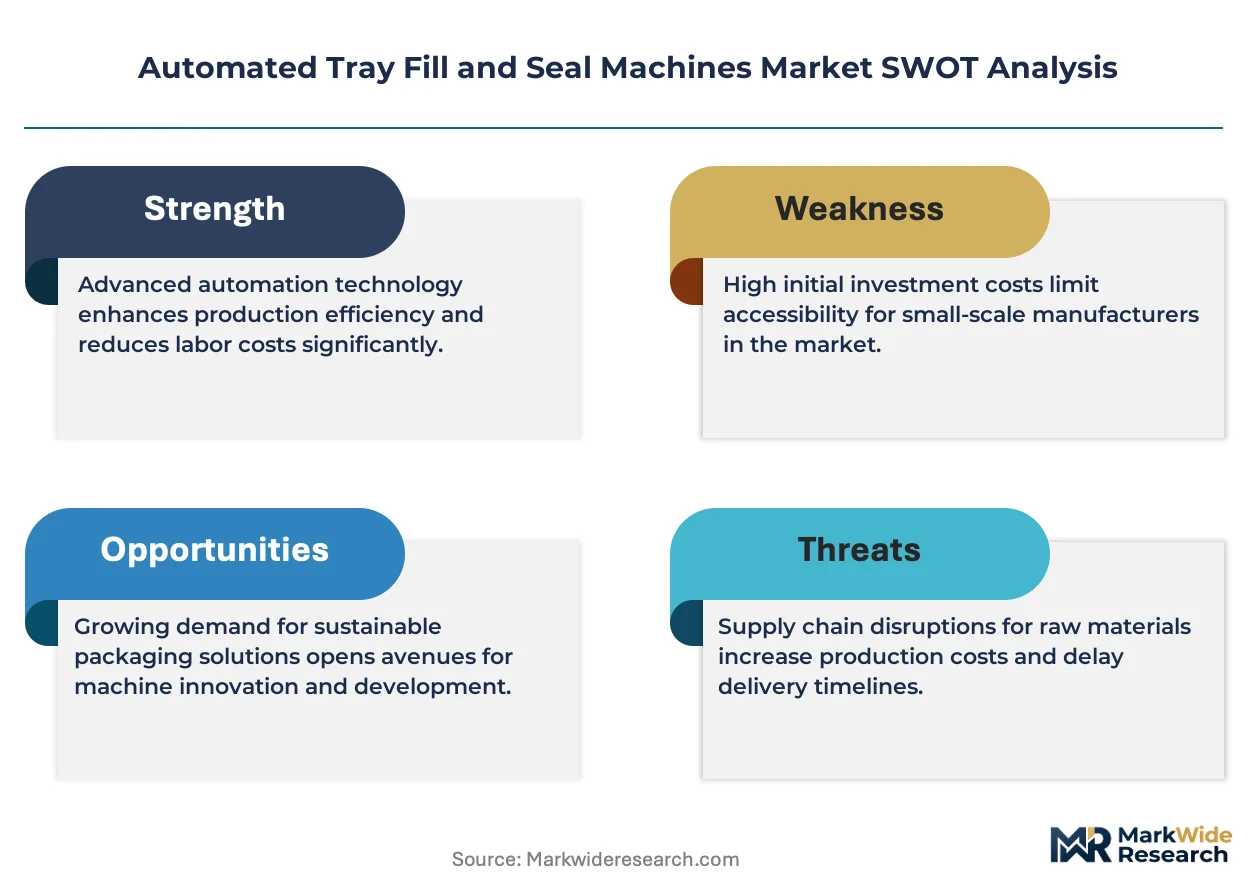
Servo-driven sealing modules are commoditizing precision motion control, collapsing the capability gap between integrated systems builders and mid-tier assembly houses while compressing equipment pricing bands across rotary and linear filler categories.
Growth Catalysts
- USDA FSIS washdown protocols:Protein processors in North America must upgrade to stainless-steel rotary fillers certified for sanitary design, forcing capital deployment into compliant equipment.
- Ready-to-eat meal automation:Food processors are automating portion-controlled packaging lines to meet retail demand for shelf-stable prepared foods with extended freshness windows.
- Modified-atmosphere sealing:Dairy and protein exporters in Germany, China, and Brazil are adopting gas-flush closure stations to preserve product integrity across extended cold-chain distribution.
Market Restraints
- Specialized die-set supply concentration:Critical tooling foundries in Central Europe control high-precision seal-bar manufacturing, creating single-source vulnerability for mid-tier machine builders.
- EU F-Gas refrigerant phase-down:The regulation is forcing immediate architectural redesign of MAP gas systems, adding engineering validation cycles and retrofit complexity.
- Film-substrate cost volatility:Multi-layer barrier films and lidding materials face petrochemical input price swings that compress OEM margin structures and deter long-term quoting.
Strategic Opportunities
- Brazilian protein export clusters:Untapped demand for high-throughput linear fillers exists in mid-scale beef and poultry co-packing facilities serving Mercosur trade corridors.
- Recyclable mono-material mandates:Extended Producer Responsibility frameworks across multiple jurisdictions are creating retrofit demand for seal-bar systems compatible with single-substrate tray formats.
- Robotic denesting convergence:Articulated-arm lidding-placers combined with machine vision are opening mixed-product lines previously uneconomical for fixed automation.
Industry Challenges
- Servomechatronics skill scarcity:The shortage of technicians capable of calibrating multi-axis sealing modules is extending commissioning timelines and inflating field service costs.
- Legacy PLC integration friction:Brownfield dairy and protein plants running proprietary control architectures face protocol incompatibility when retrofitting modern dosing heads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Tray Fill and Seal Machines Market |
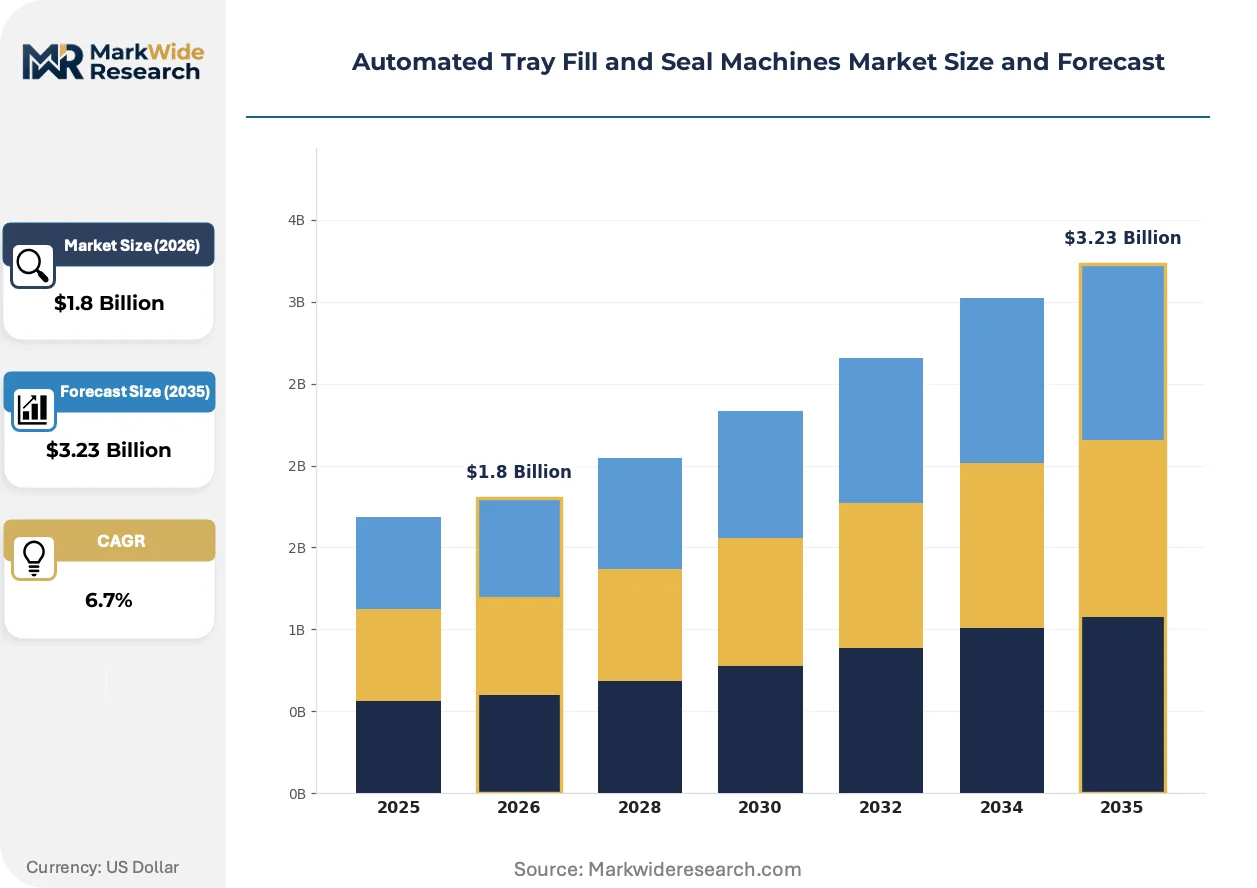
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Fillers, Rotary Fillers, Linear Fillers, Multi-Head Fillers End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Technology: Automatic, Semi-Automatic, Manual, Robotic Application: Packaged Meals, Snacks, Dairy Products, Confectionery |
| Companies Covered | MULTIVAC, ProMach, Robert Bosch, ULMA Packaging, Ilpra, Sealed Air, JBT Corporation, Webomatic, Marel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Tray Fill and Seal Machines Market Strategic Shifts
Equipment architecture is splitting between throughput-maximized rotary platforms and flexibility-optimized linear systems, with robotics bridging the gap in hybrid configurations. This divergence is reshaping how OEMs organize R&D, field service, and aftermarket parts logistics.
Articulated-arm robotic denesters and lidding-placers are bifurcating the automation landscape. Ready-to-eal meal processors with high SKU volatility are deploying these systems to eliminate fixed tooling changeover. The technology is compressing the economic viability threshold for mixed-product lines below 5,000-unit batch sizes.
The EU F-Gas Regulation is accelerating refrigerant-sealed modified-atmosphere system redesign. European protein and dairy processors must certify alternative gas architectures by specified phase-down milestones. Installations in Germany and export-oriented clusters are prioritizing nitrogen-dominant flush systems to preempt compliance risk.
Co-packing procurement is consolidating around outcome-based performance contracts. Mid-scale food brands are unbundling equipment ownership from throughput guarantees, pressuring OEMs to assume operational risk. This shift is most visible in North American protein processing, where processors defer capital in favor of per-unit packaging fees.
Automated Tray Fill and Seal Machines Market Segmentation
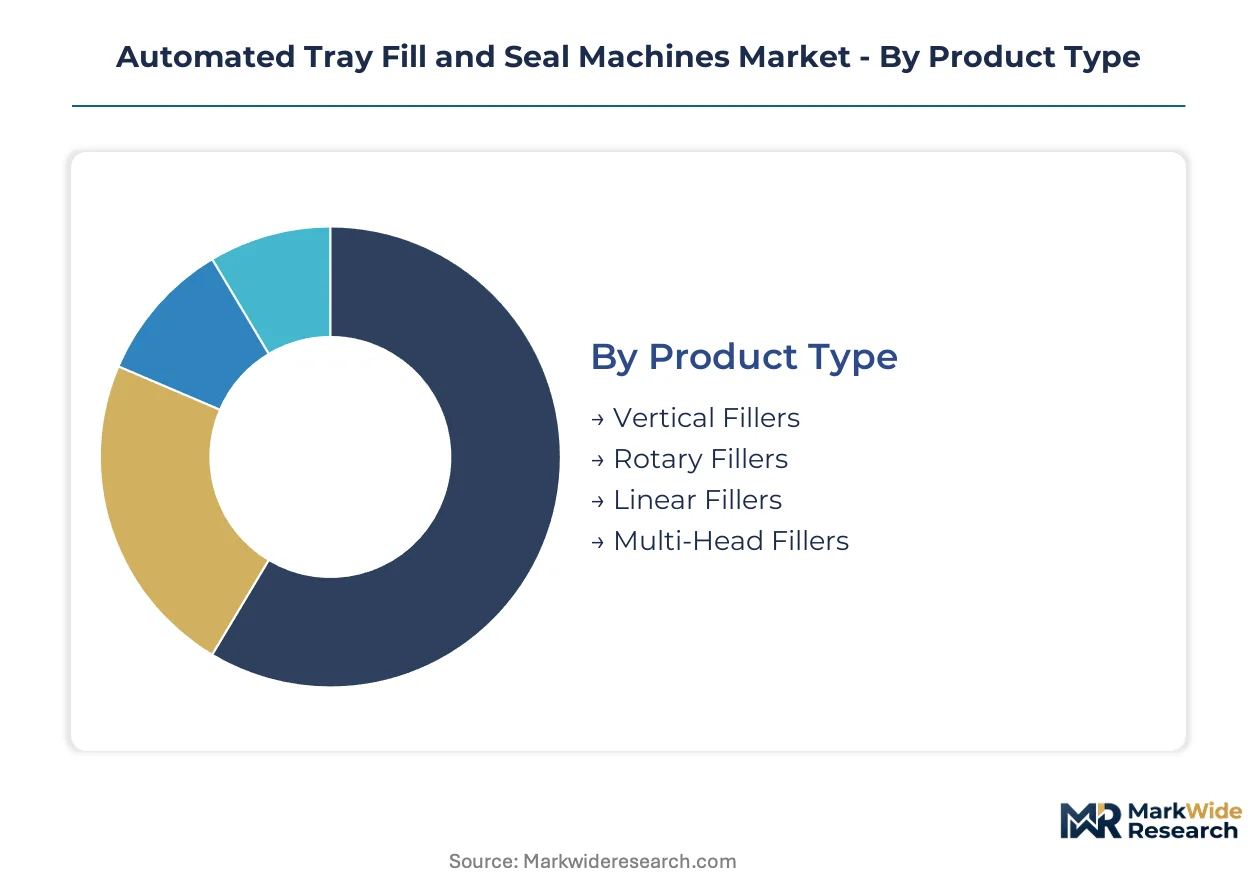
Machine architecture and automation intensity segment this market into distinct procurement tiers. Regulatory compliance requirements vary sharply across these boundaries, shaping capital allocation patterns for protein processors and pharmaceutical packagers.
Product Type:
FDA Title 21 CFR food-contact substance rules and USDA FSIS sanitary design mandates drive material specifications and cleanability architectures differently across filler geometries.
- Rotary Fillers:Circular indexing tables with 8-24 station configurations execute thermoformed cavity filling and heat-seal closure at 120-180 cycles per minute. High-volume beef and poultry processors in Brazil and Germany deploy these systems where throughput justifies footprint and capital commitment.
- Linear Fillers:In-line conveyor architectures with servo-driven indexing enable rapid changeover between SKU formats without mechanical retooling. Mid-scale ready-to-eat meal facilities in China favor this flexibility to accommodate volatile retail demand patterns.
- Vertical Fillers:Gravity-fed dosing heads positioned above forming stations suit free-flowing granular products. Snack and confectionery applications dominate procurement.
- Multi-Head Fillers:Simultaneous dispensing across parallel lanes targets high-speed dairy portioning. Yogurt and cheese processors specify these for cup-and-lid formats.
Rotary fillers handle the majority of throughput; linear fillers are the fastest mover on share.
End User:
Customer procurement scale and validation burden create three distinct commercial tiers with diverging margin profiles and service intensity requirements.
- Food & Beverage:Protein, dairy, and prepared meal processors generate the dominant equipment demand. USDA washdown certification and EU F-Gas Regulation compliance for modified-atmosphere systems shape specification sheets across North American and European installations.
- Pharmaceuticals:Clean-room validated tray-sealing for unit-dose packaging demands ISO 14644-1 compliance and FDA 21 CFR Part 11 electronic records. High barrier-to-entry segment with extended sales cycles.
- Cosmetics:Batch flexibility and rapid format changeover drive specification. Smaller lot sizes favor linear filler architectures with tool-less adjustment.
- Electronics:Anti-static materials and precision component placement requirements niche application. ESD-safe configurations with vision-guided placement.
Food and beverage commands absolute volume; pharmaceuticals delivers the steepest expansion trajectory on margin contribution.
Technology:
Automation sophistication tiers map directly to labor cost arbitrage and line integration complexity in target geographies.
- Automatic:Fully integrated systems with PLC-controlled dosing, indexing, and sealing sequences. Large-scale export-oriented protein clusters in Germany and Brazil standardize on this tier.
- Robotic:Articulated-arm denesters and lidding-placers with machine vision enable mixed-product lines below 5,000-unit economic thresholds. Ready-to-eat meal processors with high SKU volatility drive fastest adoption.
- Semi-Automatic:Operator-assisted loading with automated sealing cycles. Entry tier for mid-scale co-packers testing automation before full capital commitment.
- Manual:Foot-pedal or push-button actuated sealing for micro-scale operations. Limited to artisanal and startup food producers.
Automatic systems anchor installed base; robotic configurations are climbing the fastest on new order intake.
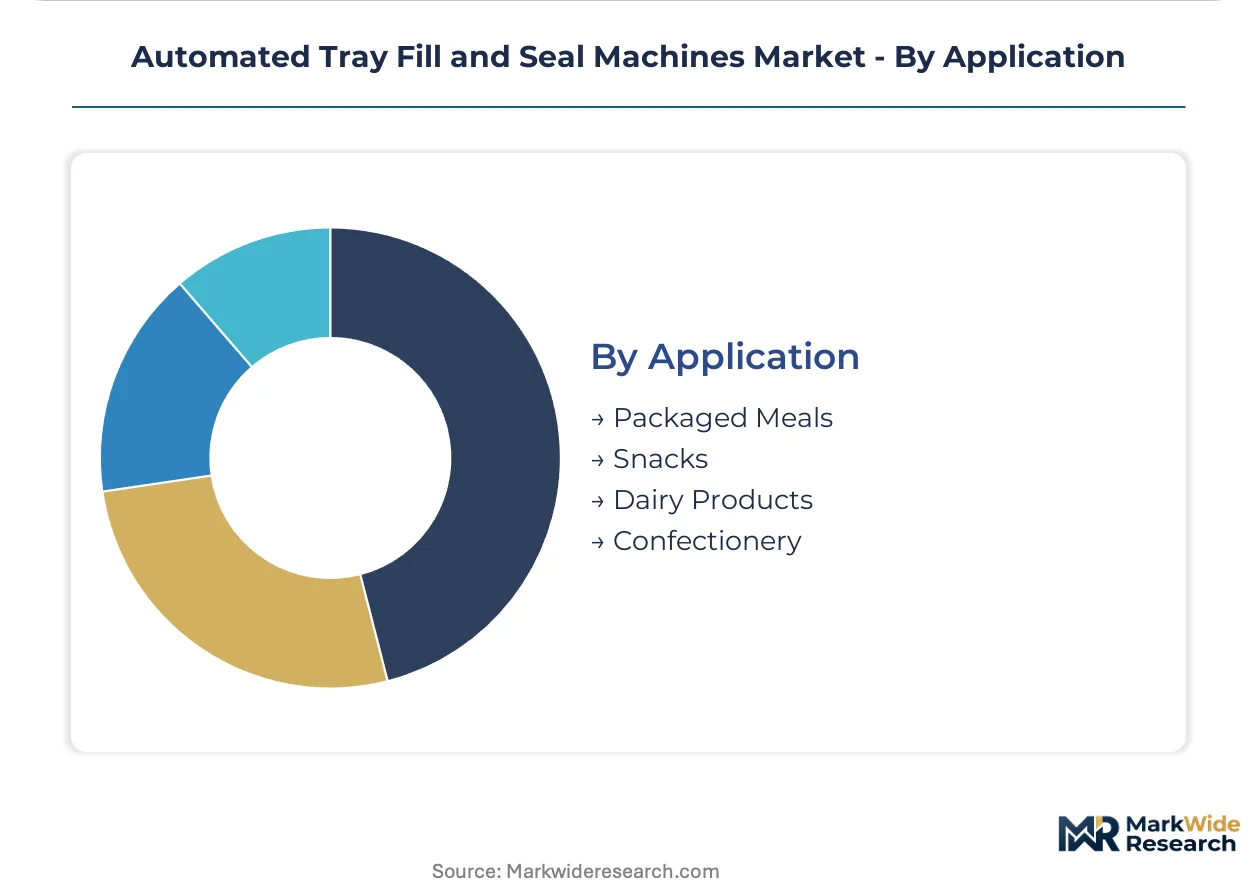
Application:
Product perishability and barrier requirements dictate modified-atmosphere gas selection and film substrate specifications.
- Packaged Meals:Ready-to-eat entrees with protein, starch, and vegetable components demand multi-gas flush systems to control microbial growth. Retail shelf-life extension targets drive capital deployment.
- Dairy Products:Yogurt, cheese, and fresh dairy formats require oxygen exclusion and carbon dioxide balance for spoilage prevention. European processors face F-Gas Regulation phase-down deadlines for refrigerant-sealed MAP systems.
- Snacks:Nitrogen flush for oxidative stability in chips, nuts, and baked formats. High-speed rotary fillers dominate this high-volume, lower-margin segment.
- Confectionery:Moisture barrier and temperature-controlled sealing for chocolate and sugar-based products. Seasonal demand patterns favor flexible linear architectures.
Packaged meals absorb the greatest equipment investment; dairy applications are gaining share fastest on regulatory-driven system replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment commands 15-20% price premiums over Chinese alternatives in export markets, while Brazilian protein processors absorb 30% higher landed costs for USDA-certified rotary fillers. This asymmetry shapes procurement patterns across protein, dairy, and ready-to-eat meal clusters.
United States
Protein processors in Nebraska and Iowa are replacing legacy fillers to meet USDA FSIS washdown mandates. FDA Title 21 CFR food-contact substance rules constrain seal-bar material selection. The Midwest beef and poultry corridor drives stainless-steel rotary system deployment.
Germany
Export-oriented dairy cooperatives in Bavaria and Lower Saxony are retrofitting modified-atmosphere systems ahead of EU F-Gas Regulation phase-down deadlines. REACH compliance obligations shape film-sealing chemistry specifications. The Münsterland cheese cluster anchors high-throughput linear filler demand.
China
Mid-scale ready-to-eal meal processors in Yangtze River Delta cities are automating portion-controlled lines for domestic retail chains. SAMR food-contact material standards parallel FDA frameworks. Shanghai and Suzhou concentrate servo-driven sealing module procurement.
Brazil
Beef and poultry exporters in São Paulo and Paraná are scaling MAP gas-flush capacity for Mercosur cold-chain distribution. ANVISA sanitary certification requirements mirror USDA protocols. The Seara and JBS processing clusters drive rotary filler investment.
India
Dairy cooperatives in Gujarat and Maharashtra are piloting automated cup-and-lid systems for extended shelf-life milk products. FSSAI packaging material regulations govern film-sealing operations. The Anand and Pune dairy belts concentrate semi-automatic to automatic tier upgrades.
Automated Tray Fill and Seal Machines Market Competitive Environment
Concentration sits with integrated systems builders controlling in-house tooling supply chains. The vendor base spans three tiers: capital-heavy rotary specialists, flexibility-optimized linear fabricators, and robotic subsystem integrators. Strategic moves center on die-set foundry acquisitions and servo module licensing agreements to compress delivery timelines.
Among European integrated builders, MULTIVAC and Robert Bosch exemplify the tooling-captive archetype through in-house die-set supply control. ULMA Packaging occupies a position within the flexibility-optimized tier. JBT Corporation anchors North American protein-processing demand. Sealed Air and Marel represent divergent specialization vectors in barrier materials versus protein system integration.
| Leading Market Players |
|---|
| MULTIVAC |
| ProMach |
| Robert Bosch |
| ULMA Packaging |
| Ilpra |
| Sealed Air |
| JBT Corporation |
| Webomatic |
| Marel |
| Others |
Value Chain & Pricing Dynamics
USDA FSIS washdown certification gates both supplier qualification and price differentiation simultaneously, as only stainless-steel rotary fillers with validated sanitary architectures command premium positioning in North American protein processing while uncertified alternatives face exclusion from procurement shortlists.
Pricing Analysis
Configured-to-order pricing for USDA-certified rotary fillers with custom die-sets commands spreads of 40-60% above standard catalog configurations. Three-tier pricing structure across premium certified, standard industrial, and economy semi-automatic levels stratifies the market. Cost compression in mid-tier linear fillers is intensifying because servo module commoditization erodes differentiation. Small-scale co-packers in India and Southeast Asia exhibit the highest price sensitivity, while export-oriented Brazilian beef processors absorb premiums for MAP gas-flush compatibility.
Supply Chain Analysis
Extended lead times for high-precision seal-bar tooling stretch 16-24 weeks, constraining OEM delivery commitments during demand surges. Critical die-set manufacturing concentrates in Germany, Austria, and Switzerland, with servo drives and motion controllers sourcing from Japan and Taiwan. Single-source vulnerability in Central European foundries threatens mid-tier builders lacking captive tooling capacity. Distribution runs through regional equipment distributors with aftermarket parts depots in São Paulo, Shanghai, and Chicago.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated tray fill and seal machines market represents a high-growth disruption as robotic denesting technology collapses the economic threshold for mixed-product lines below volumes previously reserved for fixed automation.
For Market Incumbents: Compound defensive positioning through captive die-set foundry acquisitions and servo module licensing agreements that compress delivery timelines. The threat of Chinese assembly houses with commoditized sealing technology demands backward integration into critical tooling supply chains. Certification investment in EU F-Gas Regulation-compliant MAP architectures anchors premium pricing in European dairy clusters. For New Entrants and Emerging Players: Lead with robotic subsystem integration targeting mid-scale ready-to-eat meal processors in China's Yangtze River Delta, where SKU volatility outstrips fixed automation economics. The most penetrable white-space sits in semi-automatic to automatic tier upgrades for Indian dairy cooperatives. A machine-vision-enabled lidding-placer module offered on an outcome-based performance contract bypasses capital-constrained buyer resistance. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European linear filler specialists lacking robotic integration capabilities. The five-to-ten year viability window favors platforms with installed base density in protein export corridors. Watch for EU Extended Producer Responsibility implementation timelines as the inflection signal for mono-material tray retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Die-Set Foundry Acquisition | Captive tooling supply secures delivery timelines for MULTIVAC and Bosch-tier builders against Asian competitors. |
| Robotic Denesting Integration | Articulated-arm lidding-placers with machine vision unlock mixed-product lines for ready-to-eat meal processors. |
| EU F-Gas Compliance Retrofit | Nitrogen-dominant MAP architectures preempt regulatory deadlines for German dairy export cooperatives. |
| Outcome-Based Performance Contracts | Per-unit packaging fees shift operational risk to OEMs in North American protein co-packing. |
| Servo Module Licensing Agreements | Technology transfer compresses R&D cycles for mid-tier assembly houses seeking rotary filler parity. |
Study Parameters
The analysis maps rotary filler, linear filler, robotic, and semi-automatic machine architectures, each validated through plant engineers at protein processing facilities, dairy cooperative technical directors, OEM procurement teams, and aftermarket service heads. Primary fieldwork combined with secondary validation from FDA Title 21 CFR filings, USDA FSIS equipment certification databases, EU F-Gas Regulation implementation schedules, and customs trade data for German and Chinese machinery exports. Bottom-up installation base estimates triangulate against top-down protein and dairy processing capacity figures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include machine architecture, automation technology tier, end-use application, and geographic regulatory cluster. CAGRs derive from equipment replacement cycles, capacity expansion plans, and regulatory-driven retrofit mandates. Forecast inputs incorporate servo module cost curves, film substrate petrochemical price indices, and Extended Producer Responsibility implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained protein export demand, stable refrigerant gas supply, or continued labor cost inflation in automated packaging would require recalibration. Forecasts reflect documented assumptions about technology adoption rates and regulatory phase-down schedules. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Automation
Automated Label Inspection Machines Market
Packaging Automation
Automatic Glue Machine Market
Packaging Automation
Packaging Automation Solutions Market
Packaging Automation
Robotic Packaging Machines Market
Packaging Automation
Automatic Labeling Machine Market
Packaging Automation
Fully Automatic Round Bottle Labeling Machine Market
Packaging Automation
Food Packaging Robotics Market
Packaging Automation
Automatic Capping Machine Market
Packaging Automation
Global Packaging Robot Market
Packaging Automation
Pre-Assembled Packaging Market
Packaging Automation
Middle East and Africa Packaging Automation Market
Packaging Automation
North America Contract Packaging Market
Packaging Automation
Automatic Die Cutting Machines Market
Packaging Automation
Automatic Strapping Machines Market
Packaging Automation
Automatic Powder Filling Machines Market
Packaging Automation
Packaging Automation Market