
 Nonwoven Packaging Market | 2026-2036
Nonwoven Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Packaging Market Intelligence
The direct-to-converter sales channel for specialized nonwoven fabrics is narrowing as large-scale producers expand their integrated offerings. Berry Global Inc. leverages its manufacturing footprint to serve multinational consumer goods clients. DuPont specializes in high-performance materials for demanding healthcare and industrial applications. Fitesa positions itself with customized solutions for hygiene and retail packaging sectors.
Nonwoven packaging comprises sheet or web structures bonded from fibers or filaments through thermal, chemical, or mechanical means. Manufacturing processes like spunbond and meltblown create materials with specific porosity and strength characteristics. Polypropylene remains the dominant material due to its versatility and cost-efficiency. Within product types, reusable bags show strong adoption in the retail sector, while protective packaging is critical for industrial goods.
Regulatory frameworks significantly influence material development and market access. The European Union's Single-Use Plastics Directive pushes for alternatives, while the US Food and Drug Administration (FDA) sets strict standards for food-contact packaging. These rules compel manufacturers to innovate with biodegradable fibers and recyclable designs. The key decision for producers involves balancing material performance against sustainability mandates and cost pressures.
Market Dynamics
The central tension between stringent circular economy regulations and the incumbent cost-performance advantages of polypropylene is defining market evolution. This dynamic compels producers to innovate in material science while managing supply chain economics for both legacy and next-generation fibers.
Growth Catalysts
- Healthcare Sector Demand:The need for sterile barrier systems in medical device and pharmaceutical packaging, particularly for single-use items, drives consumption of high-performance spunbond and meltblown materials that ensure product integrity and safety.
- Regulatory Mandates:Policies like the European Union's circular economy action plan are accelerating the development and adoption of nonwovens made from recycled content or biodegradable fibers as alternatives to conventional single-use plastics.
- Retail Modernization:The global expansion of organized retail, especially in Asian economies, sustains demand for reusable shopping bags, a primary application for durable polypropylene nonwovens, replacing traditional plastic and paper bags.
Market Restraints
- Input Cost Volatility:The market's heavy reliance on polypropylene makes it vulnerable to price fluctuations in crude oil and polymer resins, which can compress manufacturer margins and impact the cost-competitiveness against other materials.
- Technical Limitations:Standard nonwoven fabrics exhibit limited barrier properties against oxygen and moisture, restricting their use in certain food packaging applications that require extended shelf life, ceding share to multi-layer films.
- Substitution from Paper:In applications like e-commerce mailers and gift bags, paper-based alternatives are gaining traction due to consumer perceptions of higher sustainability and recyclability, posing a direct substitution threat to nonwoven counterparts.
Strategic Opportunities
- Bio-Based Polymers:There is a significant opportunity in commercializing nonwovens from bio-polymers like PLA and PHA, which can meet both performance needs and biodegradability requirements set by new environmental legislation.
- Industrial Protective Packaging:Under-penetrated applications exist in protective packaging for sensitive industrial goods, such as automotive parts and electronics, where nonwovens can provide customized abrasion resistance and cushioning.
- Smart Packaging Integration:Incorporating conductive fibers or sensors into nonwoven packaging creates opportunities for smart applications, such as monitoring temperature or humidity for high-value goods in the pharmaceutical or food supply chains.
Industry Challenges
- Recycling Infrastructure Gaps:A primary challenge is the lack of dedicated collection and recycling streams for post-consumer nonwoven packaging, particularly for products made from mixed materials or containing contaminants, leading to high landfill rates.
- Compliance Complexity:Navigating the fragmented and evolving landscape of food-contact safety regulations, such as differing standards between the US FDA and the European Food Safety Authority (EFSA), creates significant compliance costs and delays market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Packaging Market |
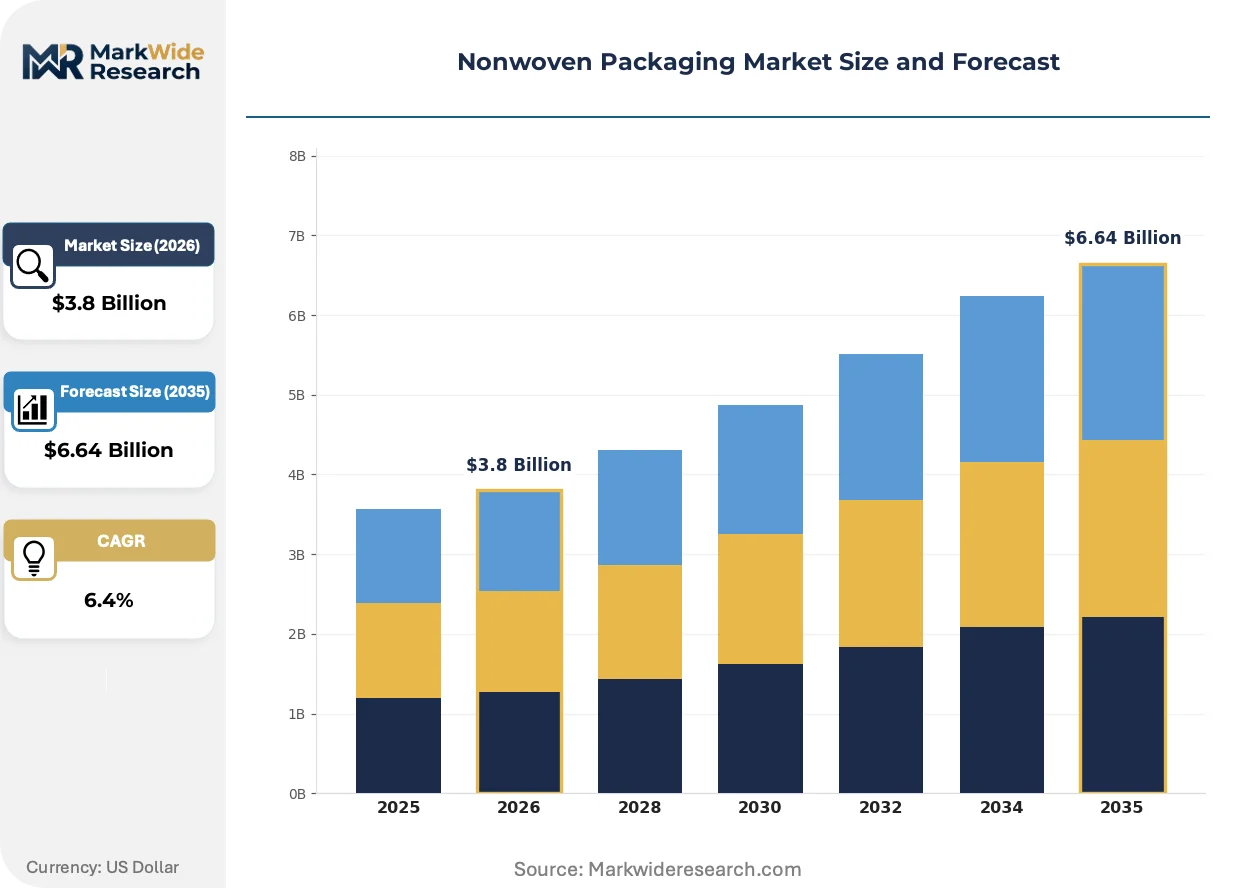
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Bags, Disposable Bags, Wrapping Materials, Protective Packaging Material: Polypropylene, Polyester, Biodegradable Fibers, Polyethylene End User: Food Industry, Healthcare, Retail, Consumer Goods Application: Medical Supplies, Grocery Packaging, Industrial Packaging, Agriculture |
| Companies Covered | Fitesa, DuPont, Berry Global Inc., Glatfelter, Johns Manville Corporation, Kimberly-Clark Corporation, Ahlstrom-Munksjö, Suominen Corporation, Freudenberg Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Packaging Market Strategic Shifts & Innovations
Material science is advancing on parallel tracks, simultaneously enhancing petroleum-based polymers while commercializing bio-based alternatives. This dual focus responds to operational cost pressures and intensifying sustainability mandates from regulators and brand owners.
Advanced material modeling software allows for the design of nonwoven structures with specific porosity and strength characteristics. R&D teams in specialty materials are adopting this approach to accelerate development cycles. This technology is virtualizing the expensive and slow process of physical prototyping, compressing the timeline from concept to commercial-grade fabric.
The European Union’s Single-Use Plastics Directive imposes strict rules on certain disposable items to curb marine litter. Its implementation forces a re-evaluation of nonwoven materials used in products like packaging for wet wipes or promotional bags. The hygiene and retail sectors are most affected, driving innovation in cellulosic fibers and mono-material designs that facilitate recycling.
A behavioral shift is visible as major consumer goods companies increasingly require Life Cycle Assessment (LCA) data from their packaging suppliers. This change elevates the procurement decision beyond simple unit cost, integrating sustainability metrics directly into sourcing criteria. The trend is most pronounced in the food, beverage, and personal care sectors in Europe.
Nonwoven Packaging Market Segmentation
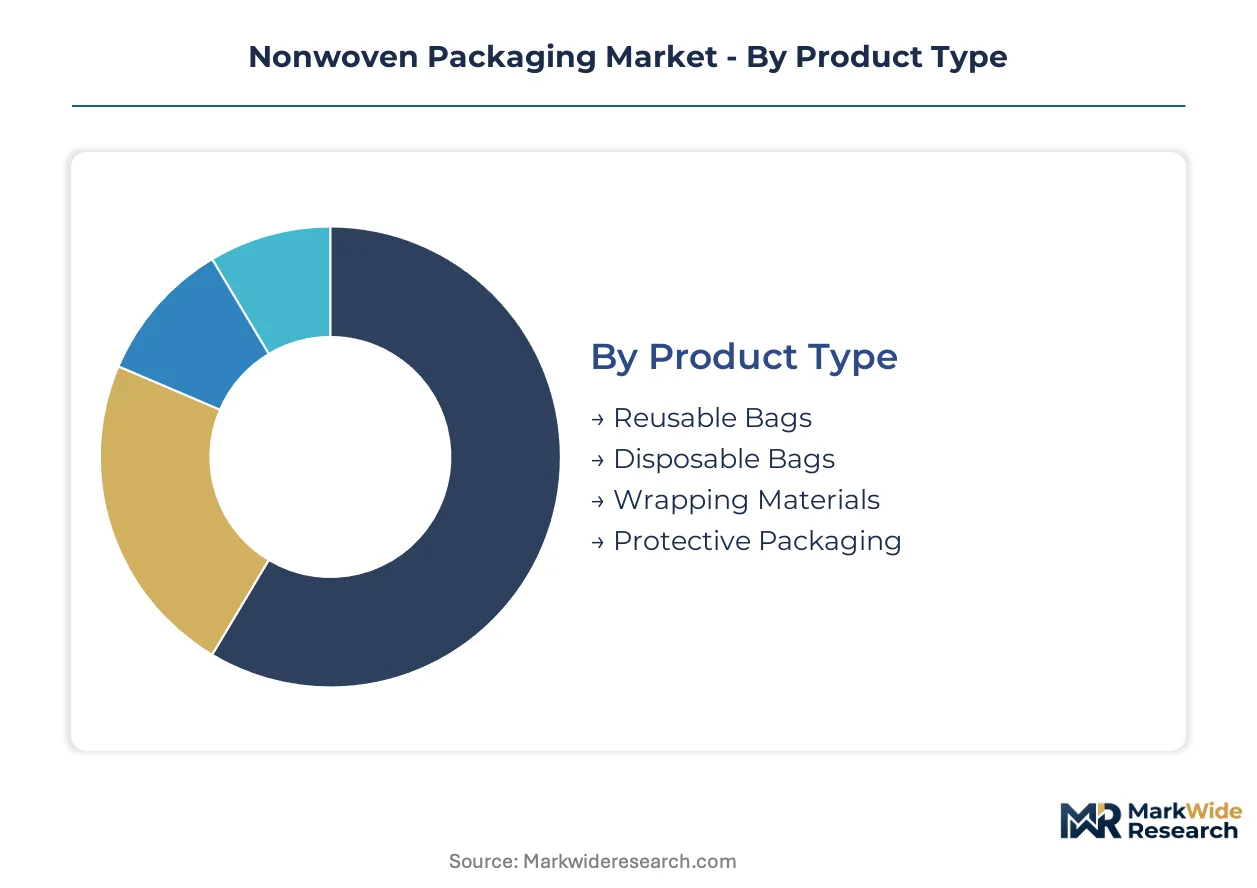
Understanding the nonwoven packaging market's segmentation reveals how diverse material properties and end-user requirements shape demand across various sectors. This granular view helps producers align product development with specific application needs and regulatory pressures. Different segments exhibit distinct growth patterns and competitive dynamics, influencing strategic investment decisions.
Product Type:
The intensity of after-sales service requirements often dictates the material specifications and design complexity within nonwoven product types, influencing procurement and supply chain relationships.
- Reusable Bags:These durable nonwoven structures, frequently made from polypropylene, offer an environmentally conscious alternative to single-use plastics. Retailers in Europe and North America increasingly adopt them to comply with sustainability mandates and enhance brand image.
- Disposable Bags:Designed for single-use applications, these nonwoven bags offer convenience where hygiene or rapid disposal is critical. Demand shifts towards biodegradable materials in the European Union.
- Wrapping Materials:Nonwoven wraps provide protection and breathability for industrial and consumer goods during transit. They offer a lightweight solution for textiles.
- Protective Packaging:Engineered nonwoven materials provide cushioning, abrasion resistance, and barrier properties for sensitive industrial components. Manufacturers in China and Germany utilize these for electronics and automotive parts, ensuring product integrity during shipping.
Reusable Bags hold the largest share; momentum sits with Protective Packaging.
Material:
The cost-tier positioning of nonwoven materials directly impacts their market adoption, with producers balancing raw material expense against performance requirements and regulatory compliance.
- Polypropylene:This synthetic polymer remains the dominant material for nonwoven packaging due to its versatility, cost-efficiency, and ease of processing. Its widespread use spans reusable bags and protective covers for industrial goods.
- Polyester:Known for strength and thermal stability, polyester nonwovens suit applications needing higher durability. It is used in specialized industrial and medical packaging.
- Biodegradable Fibers:Materials like PLA and PHA offer a sustainable alternative, designed to break down naturally after disposal. European Union regulations and consumer demand drive their adoption in disposable packaging and agricultural films.
- Polyethylene:Polyethylene nonwovens provide good barrier properties and flexibility for wrapping and protective films. Its cost-effectiveness supports various general-purpose packaging solutions.
Polypropylene currently holds the largest volume share, while Biodegradable Fibers are expanding most quickly.
End User:
The specific application requirements of each end-user industry dictate the functional properties and regulatory compliance standards for nonwoven packaging materials.
- Food Industry:This sector requires nonwoven packaging meeting strict food-contact safety regulations, such as from the US FDA. Applications include breathable wraps for produce.
- Healthcare:The healthcare sector demands sterile barrier systems for medical devices and pharmaceuticals, often utilizing high-performance spunbond and meltblown materials. These nonwovens ensure product integrity and patient safety in hospitals and clinics globally.
- Retail:The retail sector relies on nonwoven packaging for reusable shopping bags and promotional items, driven by consumer preference and sustainability mandates. Organized retail expansion in Asian economies sustains demand for durable polypropylene nonwovens.
- Consumer Goods:Nonwoven packaging provides protective and aesthetic solutions for various consumer products. Customization capabilities support brand differentiation and product safety.
The Healthcare sector represents a significant portion of demand, with notable growth observed in Retail.
Application:
The sheer volume of goods requiring packaging across different applications directly influences the scale of production and material selection within the nonwoven market.
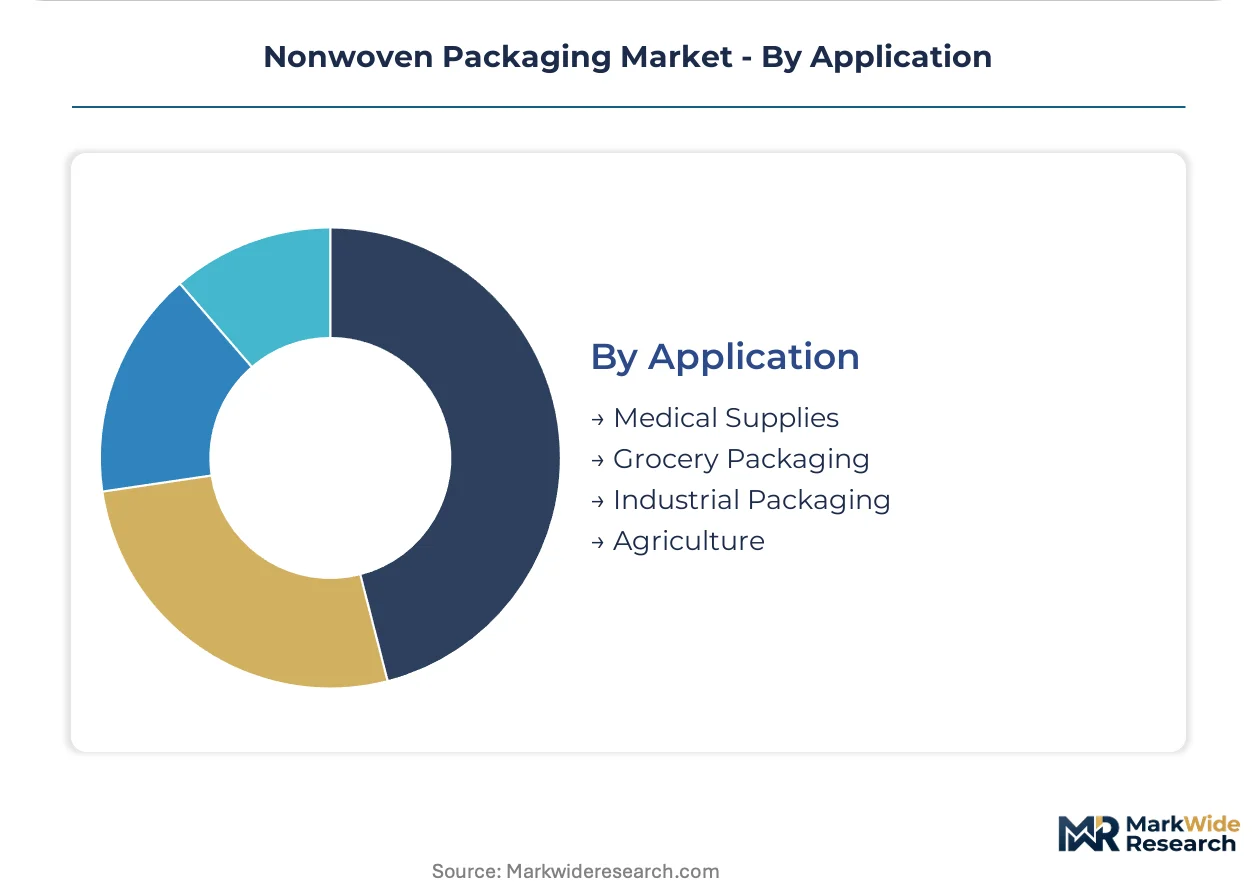
- Medical Supplies:Nonwovens provide sterile barrier packaging for single-use medical devices, surgical kits, and pharmaceuticals, crucial for patient safety. Demand is consistently high due to global healthcare expansion and stringent regulatory requirements.
- Grocery Packaging:This segment primarily includes reusable shopping bags and some disposable produce bags. It is driven by retail modernization and consumer preference.
- Industrial Packaging:Nonwovens offer protective solutions for sensitive industrial goods like automotive parts, electronics, and heavy machinery. They provide cushioning, abrasion resistance, and moisture protection during storage and transport.
- Agriculture:Nonwoven applications include crop covers, seed blankets, and protective nets. These enhance plant growth and protect against pests, improving yields.
While Grocery Packaging constitutes a foundational base, Industrial Packaging is emerging as a critical growth area.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global network of container shipping lanes and logistics hubs underwrites the widespread distribution of nonwoven packaging materials. These critical infrastructure assets facilitate the movement of raw materials and finished goods across continents. This enables manufacturers to serve diverse end-user markets efficiently.
United States
Demand for sterile medical packaging and consumer goods drives the nonwoven market in the United States. The US FDA sets stringent standards for food-contact materials, influencing material innovation. Manufacturing clusters in states like North Carolina and South Carolina actively develop advanced nonwoven fabrics for various applications.
Germany
The healthcare sector and automotive industry sustain significant demand for specialized nonwoven packaging in Germany. European Union regulations, such as the Single-Use Plastics Directive, compel manufacturers toward sustainable alternatives. The Rhine-Ruhr region, a major industrial hub, focuses on high-performance materials and protective solutions.
China
China's vast consumer goods market and industrial base generate substantial demand for both reusable bags and protective packaging. The dual carbon goals are pushing for more sustainable packaging solutions across various industries. Manufacturing zones in the Yangtze River Delta concentrate on high-volume production of nonwoven materials for domestic and export markets.
India
The expanding organized retail sector and a growing healthcare infrastructure are driving consumption of nonwoven packaging in India. The Bureau of Indian Standards (BIS) formulates quality and safety guidelines for packaging materials. Industrial corridors around Mumbai and Chennai are seeing increased investment in nonwoven manufacturing facilities.
Japan
Demand for high-performance nonwovens in electronics packaging and hygiene products characterizes the Japanese market. METI initiatives encourage innovation in advanced materials and sustainable manufacturing processes. The Kanto region, including Tokyo, remains a hub for research and development into sophisticated nonwoven applications.
Nonwoven Packaging Market Key Industry Players
On the supply side, the industry is moderately concentrated, with a few large-scale producers alongside numerous specialized manufacturers. Strategic archetypes include diversified material suppliers, high-performance fabric specialists, and integrated packaging solution providers. Competitive moves center on capacity expansion to meet demand and strategic partnerships for material innovation. Portfolio diversification into sustainable offerings also remains a significant competitive action.
Among large-scale producers, Berry Global Inc. leverages its extensive manufacturing footprint to serve multinational consumer goods clients, emphasizing scale and breadth of offering. DuPont exemplifies a high-performance material specialist, focusing on demanding healthcare and industrial applications that require advanced barrier properties. Fitesa positions itself with customized solutions for hygiene and retail packaging sectors, representing a focus on specific end-user needs and tailored product development. These companies demonstrate diverse approaches to market penetration and value creation within the nonwoven packaging space.
| Leading Market Players |
|---|
| Fitesa |
| DuPont |
| Berry Global Inc. |
| Glatfelter |
| Johns Manville Corporation |
| Kimberly-Clark Corporation |
| Ahlstrom-Munksjö |
| Suominen Corporation |
| Freudenberg Group |
| Others |
Cost & Logistics Intelligence
Overcapacity in China's nonwoven production facilities drives competitive pricing strategies and influences supplier behavior to gain market share.
Pricing Analysis
Volume-based discount tiering structures define pricing across the nonwoven packaging market. Price differentiation stems from material quality, such as FDA-compliant grades for healthcare, and the complexity of customization for industrial applications. Pricing softness stems from intense competition among polypropylene nonwoven producers, particularly for commodity grades. Retail sector buyers exhibit high price sensitivity for reusable bags, while healthcare clients prioritize performance over cost for sterile packaging.
Supply Chain Analysis
Large-scale nonwoven producers like Berry Global Inc. and Fitesa hold significant manufacturing capacity, influencing upstream material procurement. Nonwoven material production concentrates in China, the United States, and Germany. The supply chain relies heavily on polypropylene and polyester resins, making it vulnerable to input cost volatility. Downstream distribution primarily runs through direct-to-converter channels and specialized industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nonwoven packaging market is entering a cyclical recovery, driven by renewed consumer spending and industrial output post-pandemic.
For Market Incumbents: Build a regulatory compliance moat by investing in advanced certifications like US FDA food-contact approval and EU Single-Use Plastics Directive alternatives. This move counters the threat of evolving sustainability mandates and strengthens market access. Deepen vertical integration into bio-based polymer production to mitigate input cost volatility. Focus R&D on high-performance materials for demanding healthcare applications.
For New Entrants and Emerging Players: Underpenetration in emerging Asian economies, particularly India's expanding retail sector, offers significant market entry opportunities. Target specialized protective packaging for electronics and automotive parts, where customization and performance differentiate offerings. A go-to-market angle involves partnering with local distributors who possess established supply networks. Focus on biodegradable fiber solutions aligned with regional sustainability goals.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized nonwoven manufacturers with strong intellectual property in bio-based materials or advanced barrier technologies. The long-term viability favors companies able to balance performance with sustainability mandates over the next decade. Acquisition targets should possess established supply chains for high-growth segments like medical supplies or industrial protective packaging. The signal to watch is the acceleration of large-scale bio-polymer commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Bio-based Nonwovens | Increases supply of sustainable alternatives to meet EU regulatory mandates for packaging. |
| R&D for Enhanced Barrier Properties | Addresses technical limitations in food packaging, expanding market applications for nonwovens. |
| Strategic Partnerships with Retailers | Secures long-term contracts for reusable bags, leveraging organized retail expansion in Asia. |
| Investment in Recycling Infrastructure | Reduces landfill rates for post-consumer nonwoven packaging, improving circularity metrics. |
| Certification for Food-Contact Materials | Opens access to the food industry, meeting stringent US FDA and EFSA standards. |
Research Approach
Operator-level perspectives from nonwoven plant managers, procurement leads in healthcare, retail category buyers, and material science R&D directors anchored the qualitative base. This involved primary interviews combined with secondary validation from industry reports, government regulations like the EU Single-Use Plastics Directive, and corporate sustainability disclosures. The approach utilized bottom-up data collection triangulated with top-down market sizing.
Scenario bracketing provided a robust framework for projecting market evolution across the analysis window. The analytical framework modeled nonwoven packaging across product types, materials, end-users, and application. CAGRs were derived through regression analysis of historical trends and projected growth drivers. Forecast inputs included polymer resin prices and global healthcare spending trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large-scale producers or bio-polymer innovators would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and raw material availability. Quarterly review of polymer resin indices and new regulatory announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
GCC Disposables (Single-Use) Packaging Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
Europe Consumer Packaging Market
Packaging Materials
Cold Form Foil Market
Packaging Materials
Liquid Encapsulation Market
Packaging Materials
Global Packaging Foams Market
Packaging Materials
United States Single Use Packaging Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Thailand Packaging Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Cold Seal Films Market
Packaging Materials
Skin Packaging Market
Packaging Materials
Card Films Market
Packaging Materials
Protein Packaging Market
Packaging Materials
EPE Liner Market