
 Textile Packaging Market | 2026-2036
Textile Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Packaging Market Analysis
Food industry procurement is shifting toward fiber-based bulk containers that replace single-use plastic in grain and produce logistics. LC Packaging International BV leverages its European manufacturing footprint to supply certified food-contact woven polypropylene sacks to agricultural exporters. Mondi Group anchors its position through integrated kraft and specialty paper operations that feed hybrid textile-paper packaging lines. Conitex Sonoco competes with vertically controlled sewing and coating facilities across Latin American and Asian markets.
Textile packaging encompasses woven, non-woven, and knitted fiber constructions engineered for load-bearing transport, moisture buffering, and printed brand communication in supply chains. Woven polypropylene dominates shipping applications due to tensile strength exceeding 50 N per tape and resistance to UV degradation during extended outdoor storage. Non-woven bags are capturing branding and eco-friendly packaging segments as retailers specify lower grammage, stitch-bonded constructions for consumer-facing reuse programs. Cotton and jute materials sustain premium positioning in agricultural bulk storage where breathability prevents condensation damage to seed and pulse cargoes.
REACH in Europe and FDA food-contact regulations in the United States restrict residual chemical content in textile fibers destined for consumable goods transport. ISO 22000 and HACCP-aligned manufacturing protocols are becoming baseline requirements for suppliers seeking access to multinational food processor approved-vendor lists. Stakeholders must monitor evolving extended producer responsibility frameworks and bio-based content verification standards that will determine material eligibility and market access across major importing jurisdictions.
Market Dynamics
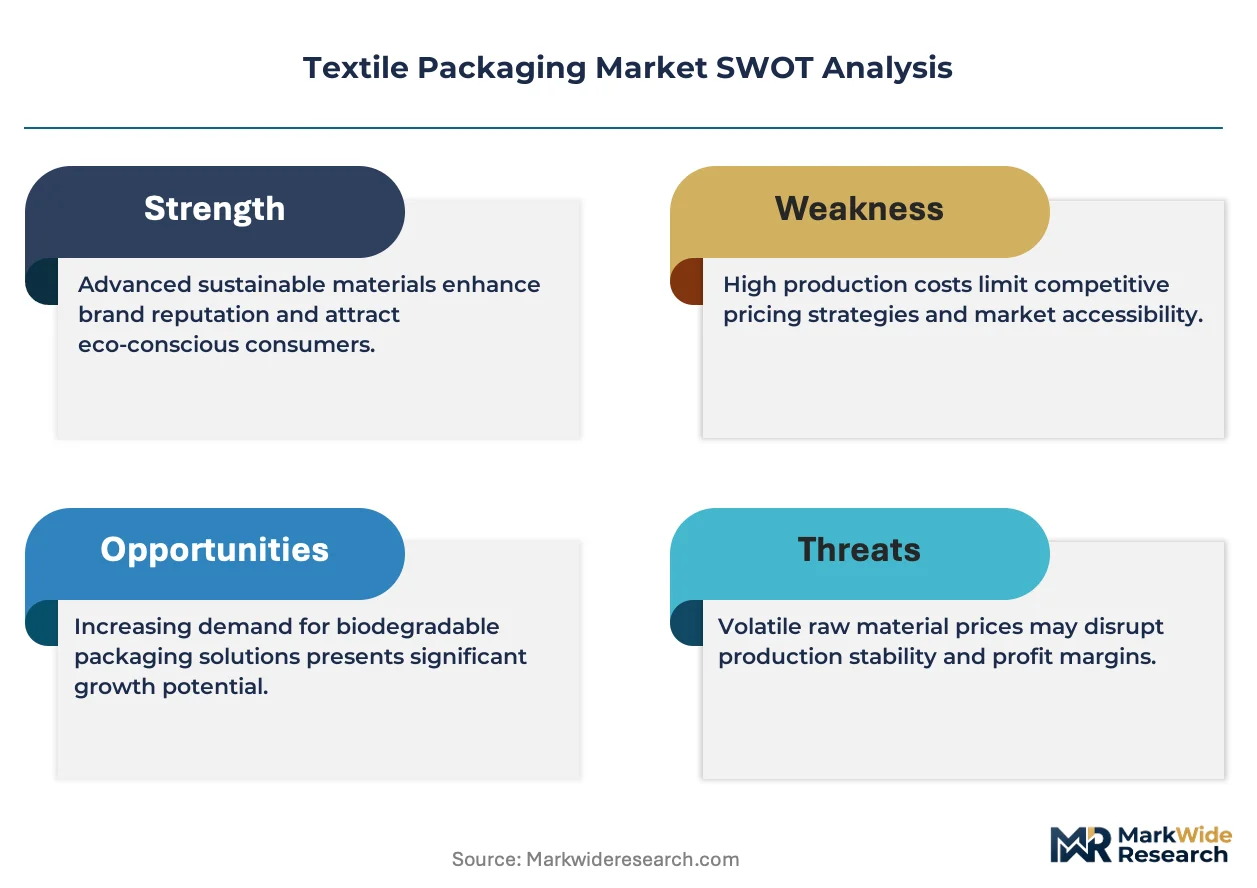
Food-contact certification requirements are compressing supplier margins while amplifying demand for traceable fiber sourcing across agricultural and retail supply chains.
Growth Catalysts
- REACH chemical migration limits:European ECHA enforcement is disqualifying uncertified woven polypropylene from grain export logistics, redirecting procurement toward compliant suppliers.
- Jute breathability specifications:Seed and pulse handlers in Bangladesh and India specify natural fiber sacks for moisture-sensitive bulk storage, sustaining premium positioning for traditional materials.
- Reusable container mandates:Retailers in Germany and France are embedding woven transport containers into closed-loop produce distribution systems.
Market Restraints
- Polypropylene resin volatility:Woven tape manufacturers face margin compression when propylene feedstock prices spike, squeezing mid-tier converters without captive polymer supply.
- Single-origin jute concentration:Bangladesh and West Bengal supply over 80 percent of export-grade jute fiber, creating geographic vulnerability to monsoon crop variability.
- Coating chemistry restrictions:FDA 21 CFR limitations on fluorinated treatments block certain moisture barriers from US food-contact applications.
Strategic Opportunities
- Brazilian agricultural export expansion:Soybean and coffee shippers are qualifying South Asian woven suppliers for FOB container stuffing operations at Santos and Paranaguá.
- EU Green Deal bio-content verification:Mass-balance certification for recycled polypropylene feedstock opens premium pricing tiers for circular-economy-compliant bulk bags.
- Non-woven retail branding convergence:Stitch-bonded PET shopping bags are capturing supermarket private-label programs as reusable alternatives to conventional plastic carryout.
Industry Challenges
- ISO 22000 audit backlog:Certification body capacity constraints are extending HACCP-aligned facility approval timelines for Asian converters seeking European food-processor vendor status.
- Legacy sewing automation gaps:Woven sack finishing requires skilled operator intervention for bottom-seam integrity, limiting throughput scaling at facilities without robotic closing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Packaging Market |
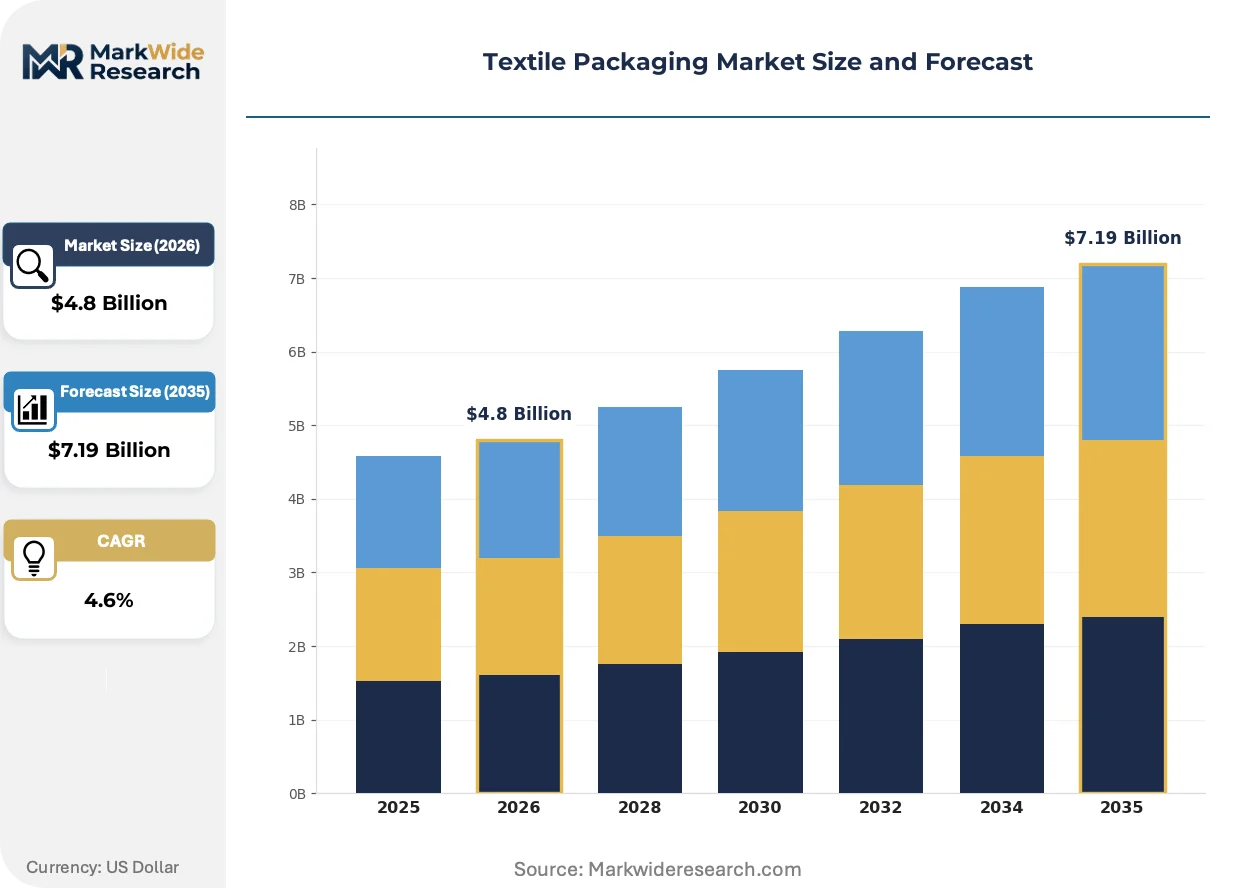
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Bags, Non-Woven Bags, Textile Rolls, Sacks End User: Food Industry, Textile Industry, Agriculture, Retail Material: Cotton, Jute, Polypropylene, Polyester Application: Shipping, Bulk Storage, Branding, Eco-Friendly Packaging |
| Companies Covered | LC Packaging International BV, T&B Containers Ltd., Conitex Sonoco, Mondi Group, Raptis Pax Pty. Ltd., Sonvigo SA, Coveris Holding SA, International Paper Company, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Packaging Market Emerging Trajectories
Active material science development is redefining performance benchmarks for load-bearing fiber constructions while regulatory chemistry restrictions force formulation pivots across coating and lamination operations.
Co-extruded multilayer woven tapes with embedded UV stabilizers and anti-static additives are absorbing demand from fertilizer and chemical shippers requiring extended outdoor storage durability. Agricultural cooperatives in the US Corn Belt and Ukrainian grain corridors specify these constructions for 12-month field exposure. The technology is absorbing volume that previously migrated to rigid intermediate bulk containers in certain bulk-density applications.
EU F-Gas Regulation phase-down schedules are pressuring fluorocarbon-based moisture barrier coatings out of food-contact textile specifications. Lamination suppliers are pivoting toward bio-based polyurethane and starch-derived alternatives with comparable WVTR performance. European woven converters with in-house coating lines are absorbing reformulation costs faster than toll-coating dependent competitors, reshaping tier-1 supplier rankings.
Consolidated produce distributors are mandating RFID-tagged reusable bulk containers for traceability compliance. German and Dutch vegetable handling cooperatives specify woven polypropylene macro-bins with embedded UHF inlays for automated warehouse tracking. This specification is compressing spot-market purchasing of unbranded, untraceable transport packaging in favor of multi-year rental programs with asset-recovery obligations.
Textile Packaging Market Segmentation
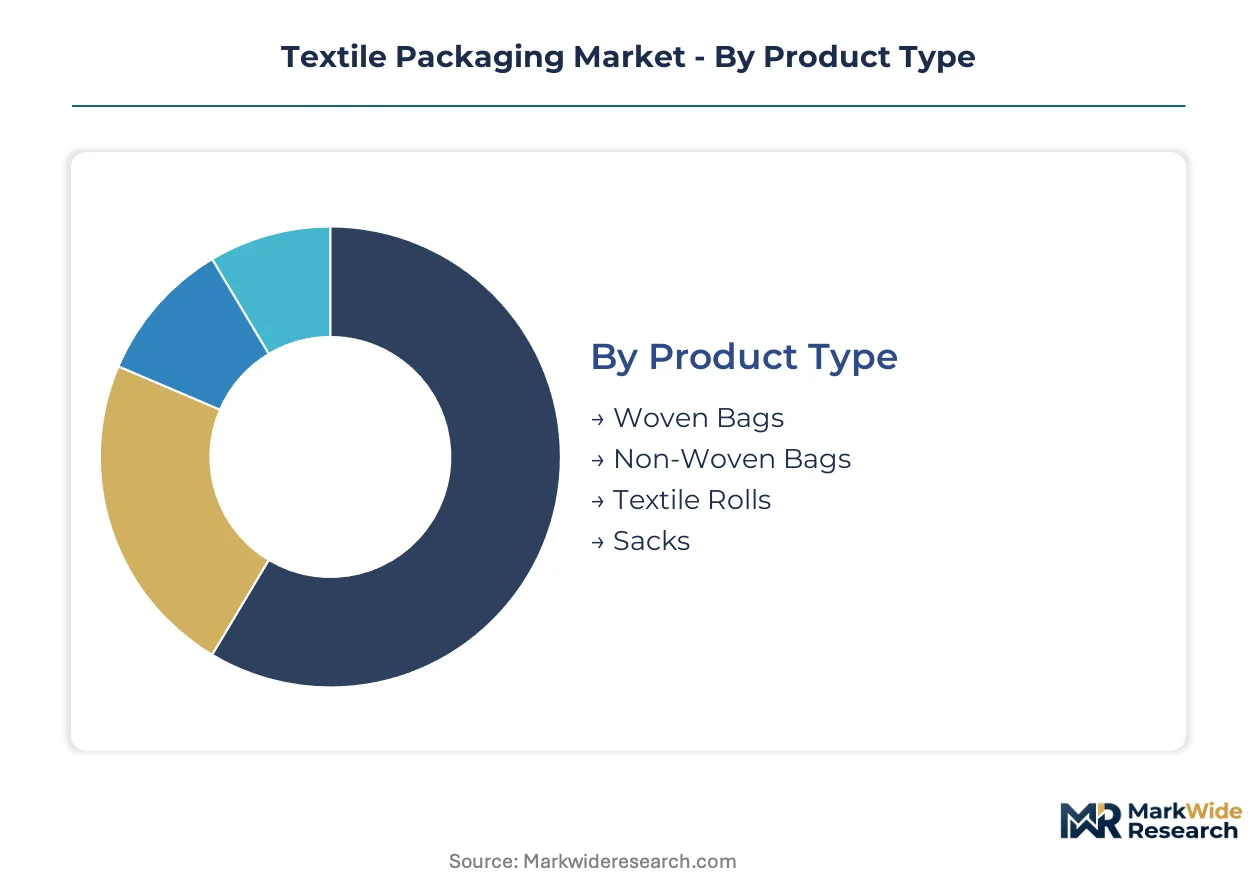
Textile packaging procurement decisions hinge on load-bearing requirements, regulatory compliance tiers, and circular-economy mandates that vary sharply across food-contact and industrial applications. Material specifications and construction methods determine which segments capture premium pricing versus commodity volume.
Product Type:
Buyers select constructions based on tensile load thresholds and reuse cycle durability.
- Woven Bags:Cross-hatched polypropylene or polyester tapes deliver tensile strength exceeding 50 N per strip for fertilizer and grain transport. REACH-compliant food-contact grades command premium positioning from European agricultural exporters.
- Non-Woven Bags:Stitch-bonded or spunbond constructions at lower grammage serve retail branding and reusable shopping programs. German supermarket chains specify these for closed-loop produce distribution.
- Textile Rolls:Continuous woven or non-woven sheeting enables custom fabrication of protective wraps and pallet covers for industrial machinery.
- Sacks:Traditional sewn-bottom constructions in cotton or jute sustain bulk seed and pulse storage across Bangladesh and Indian agricultural cooperatives.
Woven bags lead on scale; non-woven bags lead on momentum.
End User:
Regulatory intensity and traceability requirements create divergent margin profiles across customer verticals.
- Food Industry:FDA 21 CFR and REACH compliance mandates restrict residual chemical content in fibers destined for grain and produce logistics. ISO 22000 certification has become baseline for multinational food processor approved-vendor lists.
- Agriculture:Breathable jute and cotton specifications prevent condensation damage to moisture-sensitive seed cargoes. Indian and Bangladeshi export grain handlers specify natural fiber sacks for extended bulk storage.
- Retail:Reusable container mandates in France and Germany embed woven transport containers into closed-loop distribution systems with asset-recovery obligations.
- Textile Industry:Protective wrapping and in-process material handling drive demand for textile rolls with anti-static and UV-stabilized properties.
Food industry procurement concentrates premium spend; agriculture maintains the deepest volume base.
Material:
Feedstock chemistry and geographic sourcing concentration determine supply security and price volatility exposure.
- Polypropylene:Co-extruded multilayer tapes with embedded UV stabilizers absorb demand from fertilizer shippers requiring 12-month outdoor storage durability. Propylene resin price spikes squeeze converter margins without captive polymer supply.
- Jute:Bangladesh and West Bengal supply over 80 percent of export-grade fiber, creating geographic vulnerability to monsoon crop variability. Seed handlers specify jute breathability for moisture-sensitive bulk storage.
- Cotton:Natural fiber positioning serves premium agricultural applications where fiber purity meets organic certification requirements.
- Polyester:Higher tenacity and chemical resistance specifications serve industrial chemical and mineral transport applications.
Polypropylene dominates volume throughput; jute maintains the steepest expansion trajectory in sustainable packaging mandates.
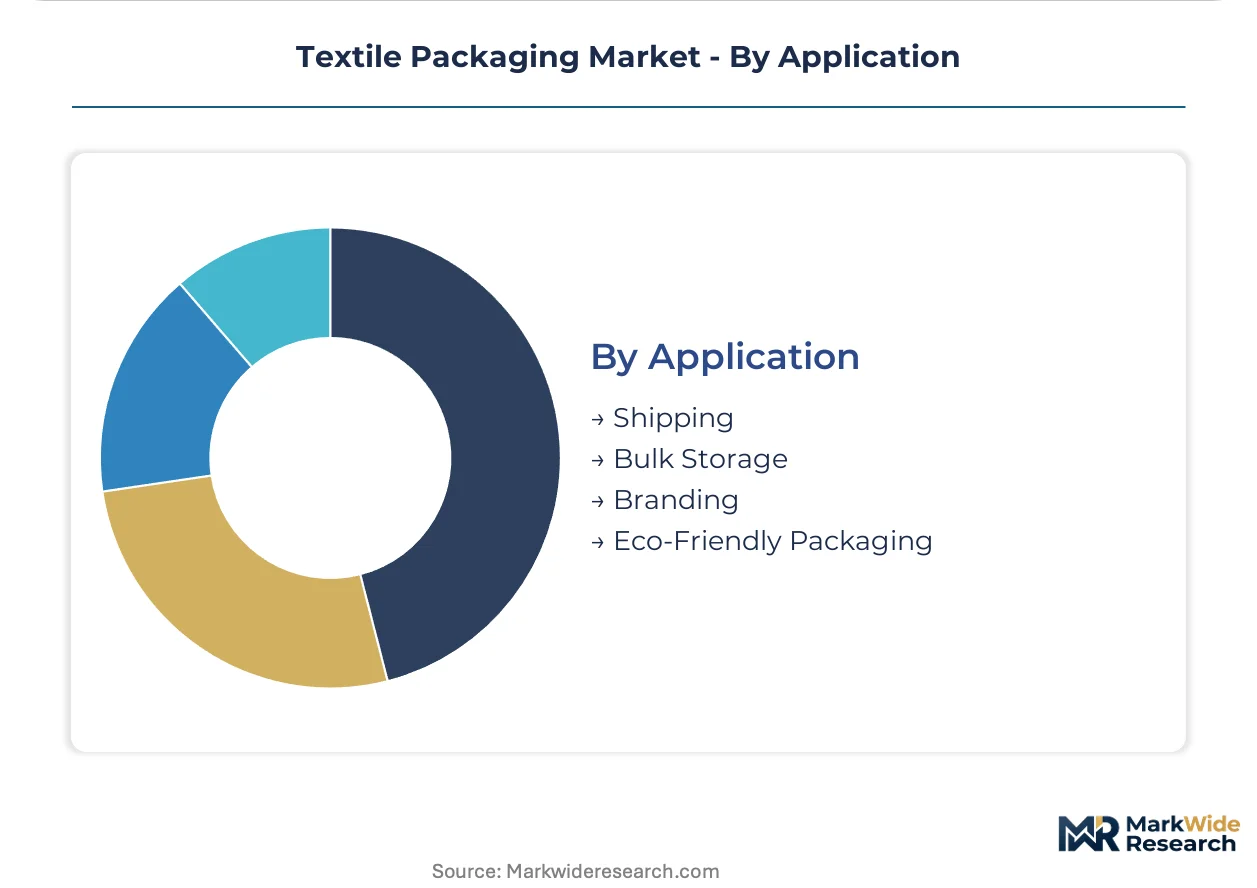
Application:
Performance specifications and regulatory exposure segment value capture across use cases.
- Shipping:Load-bearing woven constructions with RFID traceability tags satisfy German and Dutch vegetable cooperative mandates for automated warehouse tracking.
- Bulk Storage:Extended outdoor exposure requirements drive specification of UV-stabilized, co-extruded tape constructions in US Corn Belt and Ukrainian grain corridors.
- Eco-Friendly Packaging:Bio-based polyurethane and starch-derived barrier coatings replace fluorinated treatments under EU F-Gas Regulation phase-down schedules.
- Branding:Lower-grammage non-woven bags with printed surface communication serve supermarket private-label reusable programs.
Shipping commands the highest compliance investment; eco-friendly packaging gains share fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting textile packaging production toward jurisdictions with lower compliance costs, even as European food-contact standards reshape procurement specifications worldwide.
Germany
German vegetable cooperatives in Lower Saxony mandate RFID-tagged woven polypropylene macro-bins for automated warehouse tracking. The EU Green Deal's bio-content verification requirements are accelerating mass-balance certification adoption among domestic converters. Stuttgart-area machinery suppliers are deploying robotic sewing systems to address bottom-seam integrity bottlenecks.
United States
Corn Belt agricultural cooperatives specify UV-stabilized co-extruded woven tapes for 12-month field exposure in grain logistics. FDA 21 CFR restrictions on fluorinated moisture barriers are blocking certain coating chemistries from food-contact applications. Chicago-area distributors are qualifying South Asian woven suppliers for FOB container stuffing operations.
India
Export grain handlers in Maharashtra and Gujarat specify breathable jute and cotton sacks for moisture-sensitive seed and pulse cargoes. FSSAI alignment with ISO 22000 protocols is becoming baseline for multinational food processor vendor approval. Kolkata's jute mill cluster is consolidating sewing and coating capacity to meet European REACH compliance deadlines.
Bangladesh
Dhaka-based exporters dominate global jute fiber supply for agricultural bulk storage applications. Monsoon crop variability in the Ganges Delta creates recurring supply security concerns for international buyers. Chittagong port infrastructure expansions are reducing container stuffing turnaround times for woven sack shipments.
Brazil
Soybean and coffee shippers at Santos and Paranaguá are qualifying South Asian woven suppliers for agricultural export logistics. ANVISA food-contact material rules are tightening parallel to FDA specifications for chemical migration limits. São Paulo-state converters are investing in co-extruded multilayer tape capacity to capture fertilizer shipper demand.
Textile Packaging Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated paper-packaging conglomerates commanding premium positioning in food-contact certification tiers while regional sewing operations capture commodity agricultural volume. Market structure tilts toward consolidation at the top, where coating and lamination capabilities create vendor stickiness, and fragmentation at the mid-tier among toll-converters without captive polymer supply. Three archetypes dominate: European REACH-certified specialists with in-house coating lines, Asian vertically integrated jute processors, and paper-based packaging conglomerates with hybrid textile-paper offerings. Capacity expansion and strategic partnerships represent the dominant competitive moves, as certification backlogs and automation gaps constrain organic growth.
Within the European specialist tier, LC Packaging International BV and Mondi Group occupy positions anchored by integrated manufacturing footprints and food-contact certification depth. Conitex Sonoco exemplifies the Latin American-Asian bridge archetype, with naming conventions suggesting vertically controlled sewing and coating facilities across multiple emerging markets. These three entities represent distinct strategic postures: REACH compliance leadership, hybrid material integration, and geographic diversification through controlled manufacturing networks.
| Leading Market Players |
|---|
| LC Packaging International BV |
| T&B Containers Ltd. |
| Conitex Sonoco |
| Mondi Group |
| Raptis Pax Pty. Ltd. |
| Sonvigo SA |
| Coveris Holding SA |
| International Paper Company |
| Smurfit Kappa |
| Others |
Supply Flow & Price Mechanics
Co-extruded multilayer tape adoption is compressing unit economics for UV-stabilized woven constructions while simultaneously consolidating procurement leverage among fertilizer shippers in the US Corn Belt and Ukrainian grain corridors. This production-method transition concentrates volume with converters possessing in-house extrusion lines, squeezing toll-dependent competitors on both cost and supply security.
Pricing Analysis
Distributor margins on REACH-certified woven polypropylene sacks absorb certification premiums before reaching European agricultural exporters. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22000-certified food-contact grades from industrial fertilizer specifications and unbranded commodity sacks. Cost compression in standard-tier polypropylene tape runs through propylene feedstock volatility, which converters without captive polymer supply cannot hedge. Agricultural cooperatives in India and Bangladesh exhibit highest price sensitivity on jute and cotton sacks, while German vegetable cooperatives accept premium positioning for RFID-traceable reusable containers.
Supply Chain Analysis
Single-source vulnerability sits with Bangladesh and West Bengal for export-grade jute fiber, where monsoon crop variability disrupts seed handler procurement cycles annually. Polypropylene resin draws from petrochemical complexes in China, South Korea, and the US Gulf Coast, with woven tape production clustered in India, China, and Turkey. Tariff exposure on Chinese woven sack imports into Brazil and the European Union threatens margin structures for South Asian exporters. Distribution runs through agricultural cooperatives and produce handling consortiums in Germany, the Netherlands, and the US Midwest, with direct OEM relationships bypassing traditional distributor layers for volume grain contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in textile packaging rests on REACH compliance premiums and automation-driven cost compression in sewing operations, with robotic bottom-seam systems reducing labor intensity at European and Brazilian facilities.
For Market Incumbents: Hedge against polypropylene resin volatility through backward integration into extrusion capacity or long-term offtake agreements with petrochemical suppliers. Defend tier-1 positioning by accelerating ISO 22000 certification timelines ahead of Asian converter backlog resolution, as European food-processor approved-vendor lists harden entry barriers. For New Entrants and Emerging Players: Capture white-space in Brazilian soybean and coffee export logistics, where ANVISA alignment gaps create qualification windows for South Asian suppliers with FDA-equivalent documentation. Target non-woven retail branding programs in German and French supermarket chains seeking closed-loop reusable alternatives, leveraging stitch-bonded PET constructions with lower capital intensity than woven tape extrusion. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Asian toll-converters without captive coating lines or certification depth, where consolidation premiums accrue to buyers with REACH-compliant European assets. Long-term viability favors vertically controlled sewing and coating networks spanning Latin American and Asian markets, with inflection signals visible in EU Green Deal bio-content verification adoption rates among mass-balance certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Sewing Automation | Stuttgart-area machinery deployments address bottom-seam integrity bottlenecks at European converters. |
| Mass-Balance Certification | EU Green Deal bio-content verification opens premium pricing tiers for circular-economy-compliant bulk bags. |
| Coating Line Integration | In-house bio-based polyurethane lamination absorbs reformulation costs faster than toll-dependent competitors. |
| RFID Traceability Embedding | German vegetable cooperatives mandate UHF inlays for automated warehouse tracking compliance. |
| Jute Mill Consolidation | Kolkata cluster integration targets European REACH deadlines with vertically controlled sewing capacity. |
Methodological Framework
Coverage spans Germany, the United States, India, Bangladesh, and Brazil, with primary inputs from each market through interviews with plant managers at woven converters, procurement leads at agricultural cooperatives, regulatory affairs specialists, and distribution channel partners. Secondary validation draws from ECHA enforcement disclosures, FDA 21 CFR filings, FSSAI alignment protocols, customs and trade data, and SEC filings from integrated packaging conglomerates. Bottom-up volume modeling triangulates against top-down demand aggregation from end-use sector consumption patterns.
Granularity-level modeling disaggregates volume and value across the projection horizon by product type, material chemistry, end-user vertical, and regional regulatory cluster. CAGRs derive from segment-specific growth trajectories weighted by base-year share, with explicit modeling of REACH compliance adoption curves, jute crop yield variability, and polypropylene resin price elasticity. Industry-specific forecast inputs include fertilizer shipper inventory cycles, German reusable container mandate implementation timelines, and Brazilian agricultural export qualification windows.
Propylene feedstock price spikes, monsoon disruption severity in the Ganges Delta, and ISO 22000 certification body capacity constraints are the dominant revision risks that could compress or extend growth trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Postal Packaging Market
Packaging Materials
Cold Chain Packaging Materials Market
Packaging Materials
EPE Liner Market
Packaging Materials
Packaging Supplies Market
Packaging Materials
US Packaging Market
Packaging Materials
Asia-Pacific Solar Control Window Films Market
Packaging Materials
Neoprene Coffee Sleeves Market
Packaging Materials
Stick Packaging Market
Packaging Materials
North America Single-Use Packaging Market
Packaging Materials
Insulated Box Liner Market
Packaging Materials
Organic Substrate Packaging Material Market
Packaging Materials
Hygiene Packaging Market
Packaging Materials
Primary Packaging Market
Packaging Materials
Myanmar Packaging Market
Packaging Materials
Lubricant Packaging Market
Packaging Materials
Thermoformed Skin Packaging Market