
 Laminated Tubes Market | 2026-2036
Laminated Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Laminated Tubes Market Outlook
European extrusion capacity expansion is realigning supply dynamics for multilayer barrier structures. Amcor Plc leverages its integrated film operations to control substrate quality across tube production. CCL Industries Inc. anchors North American pharmaceutical tube supply through specialized cleanroom manufacturing. Hoffmann Neopac AG differentiates via precision decoration capabilities serving premium cosmetic brands.
Laminated tubes are cylindrical containers fabricated from coextruded or adhesive-bonded multilayer webs, typically combining polyethylene, aluminum foil, and polypropylene in structures ranging from five to seven layers, designed to provide oxygen and moisture barrier protection for viscous or paste products. Squeeze tubes dominate personal care dispensing due to controlled product evacuation and shelf appeal, while specialty tubes command premium positioning in pharmaceutical applications where child-resistant closures and exact dosing mechanisms justify higher unit economics. Composite material constructions are displacing monolayer alternatives as brands pursue simultaneous reduction in caliper weight and enhancement of barrier performance.
FDA regulations governing pharmaceutical primary packaging materials directly shape laminate composition requirements and extractables testing protocols for U.S.-market tubes. REACH compliance across the European Union constrains adhesive chemistries and colorant formulations, compelling reformulation investments by laminate suppliers. ISO 15378 certification for medicinal product packaging has become a de facto market access threshold rather than a voluntary quality marker. Stakeholders must monitor evolving extended producer responsibility frameworks, as these will determine whether post-consumer laminate recovery investments become competitive necessities or optional sustainability premiums.
Market Dynamics
Pharmaceutical packaging specifications are tightening laminate barrier requirements as sensitive biologics and hygroscopic formulations displace traditional small-molecule drugs in development pipelines, forcing substrate suppliers to recalibrate oxygen transmission rate targets.
Growth Catalysts
- REACH chemical restrictions:ECHA's evolving substance restrictions on phthalates and heavy metal pigments are accelerating migration toward compliant adhesive systems and mineral-based colorants in European tube production.
- Oral care dispensing:Toothpaste and gel formulations are converting from rigid containers to collapsible laminates as brands pursue shelf differentiation and controlled-dose evacuation.
- German manufacturing concentration:Cosmetic contract packers in Baden-Württemberg and North Rhine-Westphalia are consolidating procurement around regional extrusion specialists to reduce logistics exposure.
Market Restraints
- Aluminum foil supply volatility:Rolling mill capacity constraints in Southern Europe are transmitting price instability through the five-to-seven-layer substrate stack.
- Monolayer polyethylene substitution:Budget personal care brands in mass retail channels are reverting to simpler barrier structures despite inferior product protection.
- ISO 15378 certification timelines:Pharmaceutical tube qualification protocols are extending new supplier onboarding to 18-24 months, freezing out smaller converters.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO-aligned tube suppliers can capture formulation packaging for generics destined to regulated markets through mutual recognition agreements.
- Child-resistant closure integration:Mechanical engineers are embedding push-and-turn mechanisms directly into laminate shoulder designs for pediatric safety compliance.
- Post-consumer laminate recovery:The EU Packaging and Packaging Waste Regulation's 2030 recycled content mandates are creating first-mover advantage for converters with pilot delamination facilities.
Industry Challenges
- Multilayer coextrusion expertise:Thin-gauge aluminum foil handling and adhesive lamination precision require operators with 5-10 years of specialized experience, creating hiring bottlenecks.
- Cleanroom capital intensity:Pharmaceutical-grade tube production requires ISO Class 7 environments and continuous particle monitoring, demanding seven-figure facility investments.
- Legacy printing press integration:Gravure and flexographic decoration lines from the 2010s lack the registration accuracy required for premium cosmetic brand specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laminated Tubes Market |
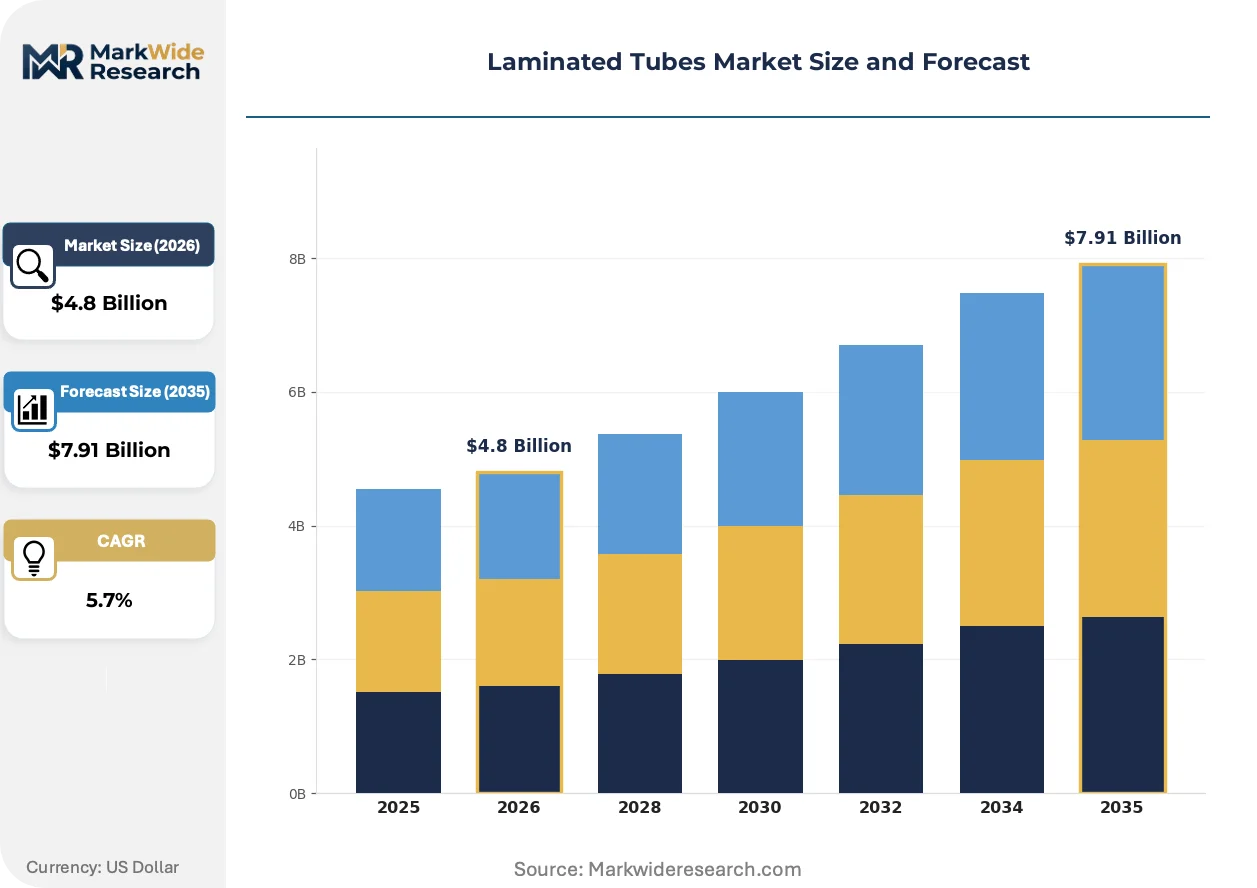
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tubes, Squeeze Tubes, Rigid Tubes, Specialty Tubes Material: Plastic, Aluminium, Paper, Composite End User: Cosmetics, Pharmaceuticals, Food & Beverage, Household Products Application: Personal Care, Oral Care, Packaging, Industrial Use |
| Companies Covered | Alltub Group, CCL Industries Inc., Amcor Plc, Berry Global Group Inc., Huhtamäki Oyj, EPL Limited, Hoffmann Neopac AG, Montebello Packaging Inc., Albea Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laminated Tubes Market Strategic Shifts
Substrate engineering and regulatory compliance are converging to redefine competitive advantage in barrier packaging, with sustainability mandates now dictating material selection as forcefully as performance specifications.
Ethylene vinyl alcohol copolymer is consolidating its position as the preferred oxygen barrier layer in high-performance pharmaceutical tubes, replacing metallized films in applications requiring transparent sidewalls for content visibility. Oncology and biologic drug packagers are specifying EVOH concentrations above 8% by layer weight. This migration is compressing demand for aluminum-intensive structures in segments where electromagnetic detection and patient inspection outweigh absolute barrier performance.
The EU Packaging and Packaging Waste Regulation is mandating extended producer responsibility frameworks that will require tube manufacturers to finance post-consumer collection and sorting infrastructure by 2025. Laminate converters are responding with design-for-recycling protocols that standardize polymer combinations and eliminate incompatible adhesive chemistries. Pharmaceutical applications face the steepest compliance burden, as multi-material barrier requirements conflict with mono-material recyclability targets.
Brand procurement departments are consolidating supplier panels from 15-20 converters to 3-5 strategic partners capable of delivering integrated decoration, barrier engineering, and regulatory documentation. Premium cosmetic houses in France and Germany are awarding five-year sole-source contracts with volume guarantees and joint development clauses. This concentration is most visible in oral care, where multinational brand owners are eliminating regional tube suppliers in favor of continental-scale partners with captive film extrusion.
Laminated Tubes Market Segmentation
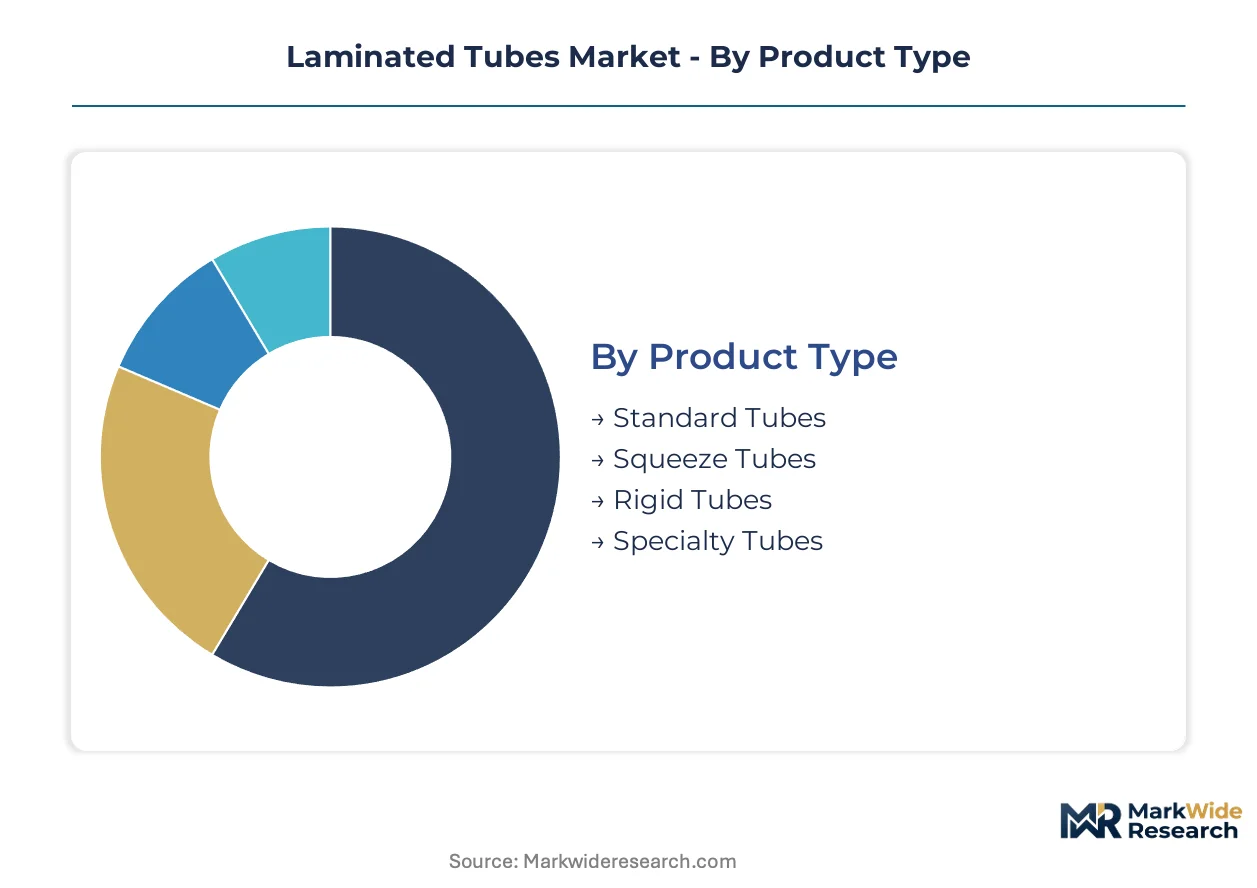
Laminated tube specifications vary dramatically across end-use applications, with pharmaceutical barrier requirements, cosmetic decoration standards, and food-contact compliance each demanding distinct substrate engineering. Procurement teams segment suppliers by technical capability clusters rather than commodity pricing, reflecting the specialized nature of multilayer coextrusion.
Product Type:
Tube construction geometry determines barrier performance, dispensing mechanics, and decoration surface area, with squeeze functionality commanding premium positioning in personal care.
- Standard Tubes:Five-layer polyethylene-aluminum-polypropylene structures serve mass-market personal care where cost efficiency outweighs absolute barrier specifications. Demand concentrates in German cosmetic contract manufacturing, where Baden-Württemberg packers prioritize logistics consolidation with regional extruders.
- Squeeze Tubes:Collapsible multilayer webs with controlled memory properties enable precise product evacuation and shelf differentiation. Oral care brands in Germany are converting rigid toothpaste containers to this format, driving volume concentration in North Rhine-Westphalia.
- Rigid Tubes:Structural sidewalls maintain dimensional stability for high-viscosity industrial sealants and construction adhesives.
- Specialty Tubes:Child-resistant shoulders and exact-dosing mechanisms justify premium unit economics in pharmaceutical applications.
Mature deployment sits with Standard Tubes. Newer deployment is concentrated in Specialty Tubes.
Material:
Substrate selection balances oxygen transmission rates against recyclability mandates, with regulatory pressure forcing reformulation investments across the value chain.
- Plastic:Polyethylene and polypropylene dominate personal care through cost-efficient monolayer and coextruded structures. Budget brands in mass retail channels are reverting to simpler barrier constructions despite inferior product protection.
- Aluminium:Thin-gauge foil layers provide electromagnetic detection capability and absolute moisture barriers for pharmaceutical applications. Southern European rolling mill capacity constraints are transmitting price instability through five-to-seven-layer substrate stacks.
- Paper:Fiber-based outer webs serve sustainability-positioned cosmetic brands seeking tactile differentiation.
- Composite:EVOH-enhanced multilayer structures displace metallized films where transparent sidewalls enable patient inspection of contents.
Volume leadership belongs to Plastic substrates. Steepest expansion trajectory is occurring in Composite materials.
End User:
Regulatory intensity varies sharply across customer segments, with pharmaceutical qualification protocols extending supplier onboarding to 18-24 months.
- Cosmetics:Premium decoration capabilities and precision shoulder engineering command sole-source contracts from French and German brand houses. Procurement consolidation is eliminating regional suppliers in favor of continental-scale partners with captive film extrusion.
- Pharmaceuticals:ISO 15378 certification and cleanroom manufacturing requirements create steep barriers to entry. CDSCO-aligned Indian suppliers are capturing formulation packaging for generics destined to regulated markets through mutual recognition agreements.
- Food & Beverage:Migration from rigid containers to flexible formats remains limited by oxygen barrier requirements for oxygen-sensitive formulations.
- Household Products:Industrial sealants and adhesives prioritize structural rigidity over collapsible convenience.
Revenue concentration rests with Cosmetics. Regulatory complexity is highest in Pharmaceuticals.
Application:
Application-specific performance requirements dictate laminate layer counts, with oncology and biologic packaging driving EVOH concentration targets above 8% by layer weight.
- Personal Care:Shelf differentiation and controlled-dose evacuation prioritize squeeze functionality and gravure decoration accuracy.
- Oral Care:Toothpaste and gel formulations are converting from rigid containers to collapsible laminates as multinational brand owners consolidate supplier panels.
- Packaging:Generic barrier protection for viscous products spans multiple end-use segments with variable specification intensity.
- Industrial Use:High-viscosity adhesives and sealants demand rigid sidewall construction and chemical resistance.
Procurement volume clusters in Oral Care. Technical specification intensity peaks in Personal Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum rolling mill capacity in Southern Europe anchors substrate supply for multilayer tube manufacturers. Converter procurement clusters around extrusion specialists in Germany and cosmetic contract packers in France. REACH compliance timelines and EVOH barrier adoption rates vary sharply across national regulatory environments.
Germany
Cosmetic contract packers in Baden-Württemberg and North Rhine-Westphalia drive demand for five-to-seven-layer squeeze tubes as oral care brands abandon rigid containers. ECHA substance restrictions on phthalates compel adhesive reformulation investments by laminate suppliers. Regional extrusion specialists near Stuttgart consolidate procurement relationships to reduce logistics exposure for pharmaceutical and personal care clients.
United States
FDA pharmaceutical primary packaging regulations shape laminate composition requirements and extractables testing protocols for domestic tube suppliers. Oncology and biologic drug developers specify EVOH barrier layers above 8% concentration, displacing metallized films in transparent sidewall applications. Cleanroom manufacturing investments concentrate in New Jersey and Pennsylvania corridor facilities serving branded pharmaceutical clients.
India
CDSCO-aligned tube suppliers capture formulation packaging contracts for generics destined to regulated European and North American markets through mutual recognition agreements. Domestic pharmaceutical production expansion drives demand for ISO 15378-certified laminate converters. Gujarat and Maharashtra-based contract manufacturers consolidate procurement around regional extrusion partners with dedicated pharmaceutical-grade production lines.
France
Premium cosmetic houses in Île-de-France award five-year sole-source tube contracts with volume guarantees and joint development clauses. ANSM pharmaceutical packaging guidelines constrain adhesive chemistries and colorant formulations for domestic-market products. Gravure decoration specialists near Paris differentiate through precision registration capabilities serving luxury skincare and fragrance brands.
Switzerland
Swissmedic certification requirements create steep barriers for non-European tube suppliers seeking access to domestic pharmaceutical packaging contracts. Precision engineering clusters around Basel support child-resistant closure integration into laminate shoulder designs. Alpine-region converters leverage proximity to German and French cosmetic brand headquarters for premium decoration and barrier engineering services.
Laminated Tubes Market Competitive Environment
Global majors compete with regional champions across barrier engineering and pharmaceutical certification capabilities. The vendor base stratifies into three tiers: integrated film extruders with captive tube production, specialized converters with cleanroom pharmaceutical capabilities, and regional decorators serving mass-market personal care. Strategic moves concentrate on M&A for extrusion capacity and five-year sole-source contracts with volume guarantees.
Within the integrated-film tier, Amcor Plc and Berry Global Group Inc. exemplify upstream control over substrate quality through captive polyethylene and polypropylene operations. CCL Industries Inc. and Hoffmann Neopac AG occupy positions as specialized converters where ISO 15378 certification and precision decoration capabilities anchor pharmaceutical and premium cosmetic relationships respectively.
| Leading Market Players |
|---|
| Alltub Group |
| CCL Industries Inc. |
| Amcor Plc |
| Berry Global Group Inc. |
| Huhtamäki Oyj |
| EPL Limited |
| Hoffmann Neopac AG |
| Montebello Packaging Inc. |
| Albea Group |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up European converters exercise pricing discipline through captive film extrusion assets, linking supply security to multi-year sole-source contracts with volume guarantees that lock in margin protection against aluminum foil volatility.
Pricing Analysis
Warranty and service bundling separates pharmaceutical-grade suppliers from commodity converters, with ISO 15378-certified cleanroom production and extractables documentation commanding premium positioning. Three-tier pricing structure across premium, standard, and economy levels reflects barrier performance, decoration precision, and regulatory certification intensity. Cost compression in mass-market personal care is intensifying because budget brands revert to monolayer polyethylene despite inferior protection. Oral care procurement teams exhibit highest price sensitivity, while oncology drug packagers prioritize barrier assurance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Southern European aluminum rolling mills, where capacity constraints transmit instability through five-to-seven-layer substrate stacks. Converter procurement draws from Germany, France, and Switzerland for extrusion and finishing, with raw material dependencies centering on polyethylene resin, thin-gauge aluminum foil, and EVOH barrier polymers. Tariff exposure on Chinese substrate components presents structural risk for non-integrated converters. Distribution runs through regional extrusion specialists serving contract packers in Baden-Württemberg and North Rhine-Westphalia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EVOH copolymer barrier technology is displacing metallized aluminum structures in pharmaceutical applications, creating transition-phase arbitrage for converters with coextrusion expertise and transparent-sidewall qualification.
For Market Incumbents: Deploy backward integration into captive EVOH film production to defend against specialty converters capturing oncology and biologic packaging contracts. Consolidate procurement relationships with German cosmetic contract packers through five-year volume guarantees. Offset aluminum foil volatility via long-term offtake agreements with Southern European rolling mills. For New Entrants and Emerging Players: Cosmetic brand procurement departments present the most penetrable channel, as premium houses consolidate supplier panels and seek alternative decoration specialists with gravure precision. Target Indian pharmaceutical exporters needing CDSCO-aligned tube supply for regulated-market generics. Establish go-to-market positioning through mutual recognition agreement expertise. For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO 15378-certified mid-cap converters in Germany and Switzerland facing cleanroom capital intensity pressures. Five-to-ten-year viability hinges on delamination facility investments for EU Packaging and Packaging Waste Regulation compliance. Watch EVOH adoption rates in transparent pharmaceutical tubes as inflection signal for aluminum displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Film Extrusion | Captive barrier layer production insulates Amcor and Berry from metallized film supply constraints. |
| Cleanroom Capacity Expansion | ISO Class 7 investments in New Jersey corridor position CCL Industries for oncology drug packaging growth. |
| Design-for-Recycling Protocol Development | Standardized polymer combinations enable Hoffmann Neopac to meet EU extended producer responsibility mandates. |
| Child-Resistant Closure Integration | Mechanical engineering partnerships in Basel support Swissmedic-certified pediatric safety compliance. |
| Indian Pharmaceutical Export Alignment | CDSCO certification investments capture formulation packaging for generics destined to EMA-regulated markets. |
Study Parameters
Document review covered customs and trade data, SEC filings from packaging converters, and ECHA substance restriction databases, complemented by interviews with laminate extrusion plant managers, pharmaceutical procurement leads, cosmetic brand packaging directors, and gravure decoration specialists. Secondary validation drew from FDA pharmaceutical packaging guidance, REACH compliance documentation, and ISO 15378 certification registries. Bottom-up volume modeling triangulated against top-down industry association estimates.
Segment-level outputs across the analysis window reflect product type, material substrate, end-user industry, and regional regulatory cluster dimensions. CAGRs were derived from trend extrapolation anchored to historical extrusion capacity utilization and pharmaceutical pipeline conversion rates. Forecast inputs incorporated EVOH barrier adoption curves and EU Packaging and Packaging Waste Regulation implementation timelines.
Caveats apply where aluminum rolling mill capacity expansions, REACH substance restriction amendments, or biologic drug formulation shifts could materially shift the outlook. Forecasts reflect assumptions about regulatory compliance cost pass-through and brand procurement consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
PET Packaging Market
Packaging Materials
Refrigerator Door Seal Gaskets Market
Packaging Materials
Fiber Lids Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Plastic Strapping Materials Market
Packaging Materials
Cushion Case Liner Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
Insulated Box Liner Market
Packaging Materials
Squeeze Tube Market
Packaging Materials
Finish Foils Market
Packaging Materials
Punnet Packaging Market
Packaging Materials
Strapping Materials Market
Packaging Materials
Cork Packaging Market
Packaging Materials
Thermal Insulation Packaging Market
Packaging Materials
Child Resistant Zipper Market
Packaging Materials
Tube Packaging Market