
 Meter-Mix Dispensing Machine Market | 2026-2036
Meter-Mix Dispensing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Meter-Mix Dispensing Machine Market Insights
Asset-light leasing models for precision dispensing equipment is rewriting competitive entry barriers for mid-tier manufacturers. Nordson leverages its captive technology ecosystem to sustain premium positioning in electromechanical systems. Graco anchors North American supply through extensive distributor networks. Henkel competes by integrating adhesive chemistry with dispensing hardware, blurring traditional supplier boundaries.
A meter-mix dispensing machine precisely proportions, blends, and delivers multi-component reactive materials through controlled flow dynamics at pressures ranging from 5 to 3,000 psi, serving industrial bonding and sealing operations. Pneumatic systems dominate high-volume automotive lines where cycle speed governs throughput, while electromechanical variants capture electronics applications demanding micron-level repeatability. Sealants applications in aerospace airframe assembly command elevated margin pools due to certification rigor and low supplier density.
EPA emissions standards and REACH substance restrictions directly shape machine design by mandating closed-loop material handling and reduced solvent flushing cycles. FDA oversight of medical device manufacturing imposes validation protocols that filter out non-specialist vendors. OEM procurement teams must weigh total cost of ownership against compliance readiness when qualifying dispensing system suppliers.
Market Dynamics
Automotive electrification and miniaturized electronics assembly are compressing tolerance windows for adhesive deposition, forcing machine builders to recalibrate around sub-millimeter repeatability and closed-loop process verification.
Growth Catalysts
- EPA volatile organic compound limits:German and US automotive plants are retrofitting lines with closed-loop meter-mix systems to eliminate solvent flushing cycles and meet tightening emissions thresholds.
- Electronics micro-assembly clusters:Precision dispensing demand concentrates in South Korean and Taiwanese semiconductor packaging facilities where die-attach adhesives require 50-micron placement accuracy.
- Two-component polyurethane chemistry:Advanced structural adhesives for composite bonding in aerospace applications require precise ratio control that only modern meter-mix equipment can deliver.
Market Restraints
- Specialized servo motor supply:Electromechanical dispensing heads depend on precision motion components concentrated in Japanese and German supply chains, creating procurement bottlenecks.
- Fluoropolymer seal cost volatility:Perfluoroelastomer O-rings and static seals face input cost swings tied to fluorspar mining concentration in China and Mexico.
- REACH substance authorization delays:Uncertainty around adhesive hardener chemistries awaiting ECHA evaluation is freezing capital expenditure decisions at European Tier-1 suppliers.
Strategic Opportunities
- India automotive component manufacturing:PLI scheme incentives for advanced chemistry cells and electric vehicle assembly are creating first-mover openings for precision dispensing system deployment.
- Medical device validation protocols:FDA 21 CFR Part 11 compliance requirements for electronic records are filtering out generalist equipment vendors and creating margin pools for specialized suppliers.
- Cloud-connected process analytics:Integration of IoT sensors with predictive maintenance algorithms is enabling outcome-based service contracts that capture recurring revenue streams.
Industry Challenges
- Multi-physics simulation expertise:Shortage of engineers capable of modeling non-Newtonian fluid dynamics, thermal curing kinetics, and precision motion control simultaneously is constraining R&D throughput.
- ISO 9001 and ISO 13485 dual certification:Medical device manufacturers require suppliers to maintain quality management systems across both general and medical-specific standards, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meter-Mix Dispensing Machine Market |
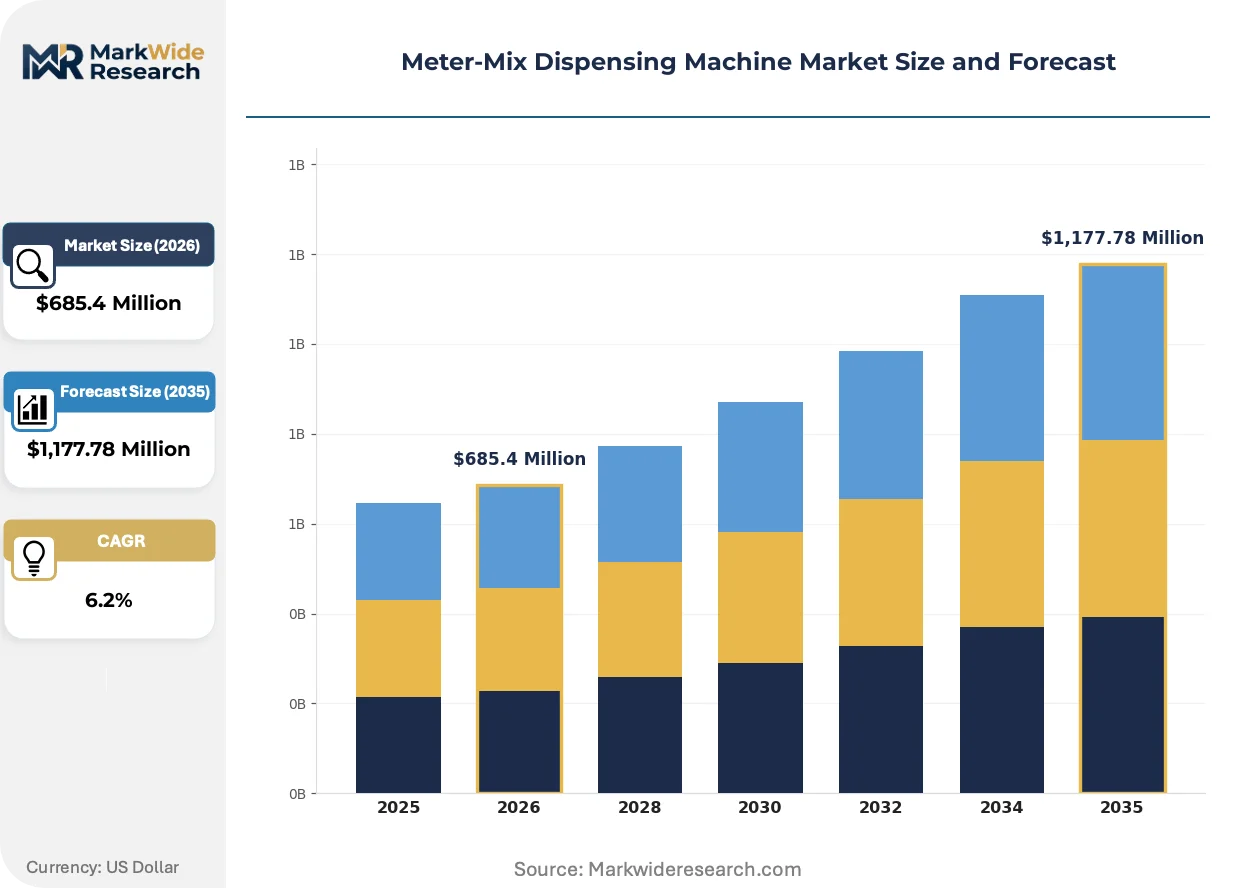
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Pneumatic, Hydraulic, Manual Industry Vertical: Automotive, Aerospace, Electronics, Construction Application: Adhesives, Sealants, Coatings, Foams End User: Manufacturers, Distributors, Contractors, OEMs |
| Companies Covered | Nordson, Graco, Henkel, INTERTRONICS, EXACT Dispensing Systems, METER MIX SYSTEMS LTD., Ulbrich, Pozzi Industries Group, Mahr Metering Systems Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meter-Mix Dispensing Machine Market Trends and Innovations
Real-time process verification and adaptive control architectures are displacing fixed-parameter dispensing, enabling machines to self-correct for material viscosity drift and substrate variability without operator intervention.
Vision-guided dispensing systems is digitizing quality assurance by embedding high-speed cameras and machine learning defect detection directly into the deposition head, eliminating downstream inspection stations. Automotive battery pack manufacturers in Michigan and Stuttgart are adopting these integrated systems at pilot scale. The technology is compressing total line footprint while raising first-pass yield thresholds beyond 99.5 percent.
REACH substance restrictions on isocyanate-containing formulations are forcing adhesive suppliers to reformulate two-component systems around novel curing chemistries. Machine builders must redesign mixing chambers and static mixers to accommodate higher-viscosity, faster-cure materials without premature polymerization. European aerospace sealant applications are experiencing the most acute equipment requalification burden as ECHA evaluates additional candidate list substances.
Asset-light equipment leasing is displacing capital purchase models among mid-tier electronics contract manufacturers in Malaysia and Vietnam. Third-party financing entities are taking residual value risk on precision dispensing systems, bundling maintenance and software updates into per-unit production fees. This shift is fragmenting buyer decision-making authority between procurement teams and operations managers.
Meter-Mix Dispensing Machine Market Segmentation
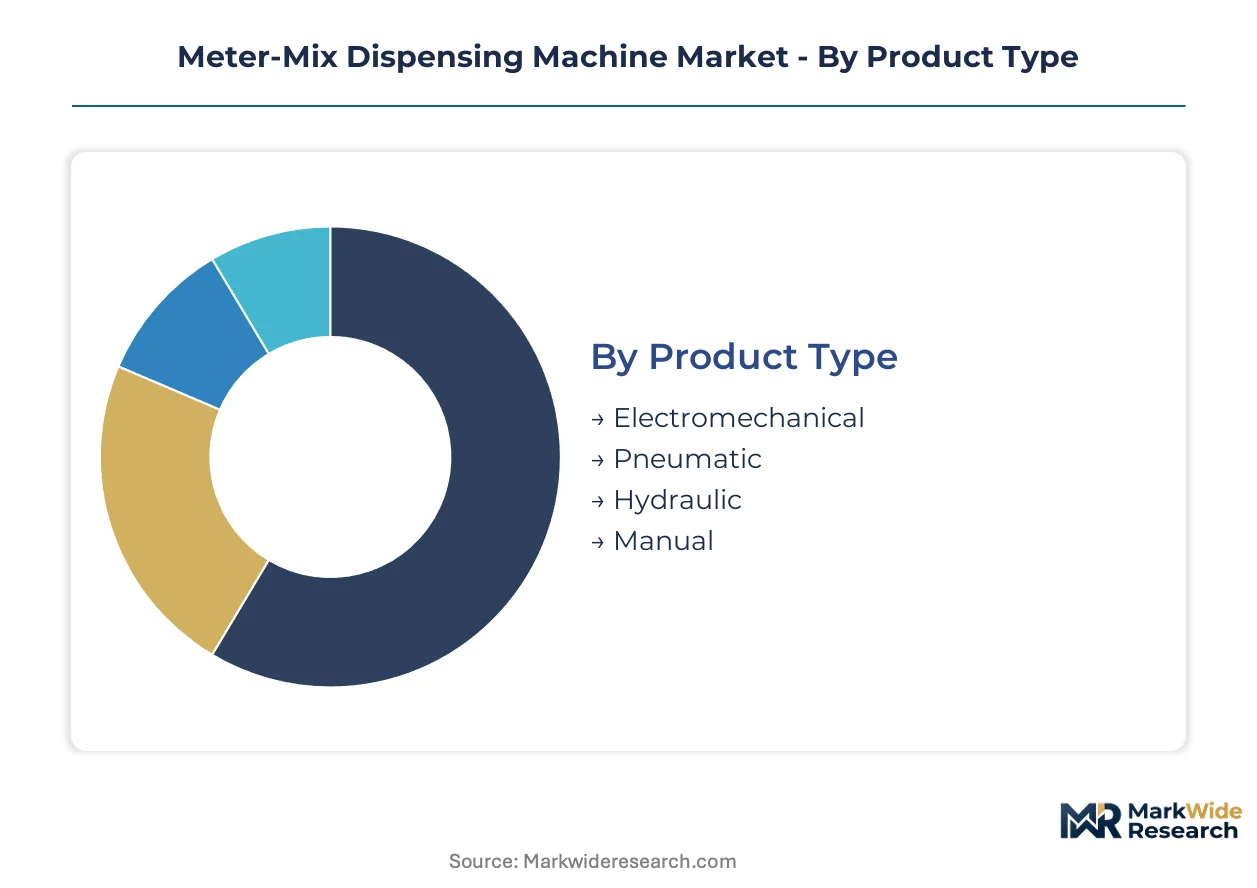
Differentiation across product types and industry verticals determines service contract structures and spare parts revenue streams. Precision requirements in electronics and aerospace segments command premium maintenance agreements that sustain margins beyond initial equipment sales.
Product Type:
After-sales-service intensity varies dramatically across drive technologies, with electromechanical systems requiring specialized technician deployment and pneumatic equipment demanding more frequent but less skilled intervention.
- Electromechanical:Servo-driven dispensing heads achieve micron-level repeatability through closed-loop position feedback. South Korean semiconductor packaging facilities specify these systems for die-attach applications requiring 50-micron placement accuracy under FDA validation protocols.
- Pneumatic:Compressed-air actuation delivers high-speed cycling for automotive body-in-white adhesive lines. German OEM plants in Stuttgart and Wolfsburg retrofit these systems to meet EPA volatile organic compound limits through reduced solvent flushing cycles.
- Hydraulic:High-force actuation suits thick-gap filling in marine and heavy equipment applications. Maintenance intervals concentrate around seal replacement and fluid monitoring.
- Manual:Hand-operated systems serve low-volume prototyping and repair operations. Distributor networks in Southeast Asia stock these for construction field applications.
By volume, Pneumatic leads. By growth pace, Electromechanical is expanding most quickly.
Industry Vertical:
Margin structures diverge sharply across end-use sectors, with aerospace certification rigor supporting elevated pricing and automotive scale driving volume-based equipment leasing.
- Automotive:Battery pack assembly lines in Michigan and Stuttgart adopt vision-guided dispensing for structural bonding of composite enclosures. EPA emissions compliance mandates closed-loop material handling that eliminates solvent exposure.
- Aerospace:Airframe sealant applications require equipment qualified to AS9100 standards with full batch traceability. Low supplier density in this segment sustains premium positioning for specialized vendors.
- Electronics:Miniaturized assembly in Taiwanese and South Korean clusters demands sub-millimeter repeatability. Cloud-connected process analytics enable predictive maintenance contracts.
- Construction:Field-deployed systems for structural glazing and waterproofing emphasize portability and rapid setup. Contractor procurement favors rental models over capital purchase.
By installed base, Automotive dominates. By margin expansion, Aerospace is gaining share fastest.
Application:
Material chemistry directly shapes machine configuration, with reactive two-component systems demanding precise ratio control and single-component materials permitting simpler delivery architectures.
- Adhesives:Structural bonding in automotive electrification requires precise control of epoxy and polyurethane chemistries. REACH substance restrictions on isocyanate formulations force mixing chamber redesigns.
- Sealants:Aerospace applications command elevated margins due to certification documentation and low supplier density. Perfluoroelastomer seal cost volatility creates procurement risk.
- Coatings:Conformal coating in electronics protects circuit boards from moisture and thermal cycling. Viscosity drift compensation requires adaptive control systems.
- Foams:Two-component polyurethane systems expand for thermal insulation and gap filling. Mixing head design prevents premature polymerization in high-reactivity formulations.
By revenue concentration, Adhesives leads. By technology upgrade cycles, Sealants shows the steepest expansion trajectory.
End User:
Procurement authority fragmentation distinguishes capital equipment purchasers from production-fee-based users, with leasing intermediaries reshaping traditional vendor relationships.
- Manufacturers:Integrated production facilities in Germany and the United States specify equipment with IoT connectivity for predictive maintenance. Total cost of ownership calculations weigh energy consumption and downtime reduction.
- Distributors:Equipment resellers and rental fleet operators manage residual value risk across multiple customer segments. Software update bundling creates recurring revenue streams.
- Contractors:Construction and field service operators prioritize equipment mobility and rapid deployment. Third-party financing entities absorb capital burden through per-project leasing.
- OEMs:Original equipment manufacturers integrate dispensing systems into turnkey production lines. Dual ISO 9001 and ISO 13485 certification requirements extend supplier qualification timelines.
By decision-making authority concentration, Manufacturers lead. By contract structure innovation, Contractors are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA volatile organic compound limits and India's PLI scheme for electric vehicle assembly are redirecting capital expenditure toward precision dispensing infrastructure across multiple manufacturing jurisdictions.
United States
Automotive battery pack manufacturers in Michigan and Ohio are retrofitting adhesive lines with closed-loop meter-mix systems to eliminate solvent flushing cycles under EPA emissions thresholds. FDA 21 CFR Part 11 validation protocols for medical device manufacturing filter out generalist equipment vendors. The Southeast manufacturing corridor spanning Tennessee and South Carolina concentrates new electronics assembly capacity.
Germany
OEM plants in Stuttgart and Wolfsburg are expanding automated adhesive deposition for composite bonding in electric vehicle platforms. REACH substance restrictions on isocyanate-containing formulations force mixing chamber redesigns and equipment requalification. The Baden-Württemberg industrial cluster hosts specialized aerospace sealant applications requiring AS9100-certified equipment.
China
Dual carbon goals and MIIT industrial upgrading directives accelerate closed-loop material handling adoption in automotive and electronics manufacturing. Fluorspar mining concentration creates input cost volatility for perfluoroelastomer seals. The Yangtze River Delta semiconductor packaging facilities specify electromechanical dispensing heads for 50-micron placement accuracy.
South Korea
MFDS validation requirements and semiconductor packaging expansion drive demand for micron-level repeatability in die-attach adhesive applications. Cloud-connected process analytics enable predictive maintenance contracts among Busan-Ulsan manufacturing clusters. The Seoul Capital Area concentrates precision electronics assembly demanding sub-millimeter tolerance windows.
India
PLI scheme incentives for advanced chemistry cells and electric vehicle assembly create first-mover openings for precision dispensing system deployment. BIS standards alignment for industrial equipment extends supplier qualification timelines. The Tamil Nadu and Maharashtra automotive corridors attract meter-mix equipment leasing models from mid-tier contract manufacturers.
Meter-Mix Dispensing Machine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where captive adhesive chemistry, distributor network density, and technology ecosystem integration define competitive position. The vendor base separates into three strategic archetypes: integrated adhesive-dispensing suppliers, precision electromechanical specialists, and pneumatic system volume providers. M&A activity targets complementary sensor and motion control capabilities, while geographic expansion through distributor partnerships anchors regional supply security.
Among the integrated chemistry-hardware tier, Henkel occupies a position exemplifying adhesive-dispensing convergence. Nordson and Graco represent distinct competitive vectors within electromechanical and pneumatic system domains respectively, with each anchoring different performance-tier segments. These three companies illustrate how technology ecosystem breadth, regional distribution depth, and captive material science capabilities create differentiated competitive positioning.
| Leading Market Players |
|---|
| Nordson |
| Graco |
| Henkel |
| INTERTRONICS |
| EXACT Dispensing Systems |
| METER MIX SYSTEMS LTD. |
| Ulbrich |
| Pozzi Industries Group |
| Mahr Metering Systems Corp. |
| Others |
Pricing and Supply Chain Analysis
Stuttgart's automotive adhesive manufacturing cluster concentrates precision dispensing capacity for European OEM electrification programs, translating upstream component scarcity into sustained pricing power for certified system integrators serving EPA-compliant retrofit cycles.
Pricing Analysis
Certification level (ISO 13485/FDA-grade versus standard industrial) creates the primary spread between equipment tiers. Three-tier pricing structure across premium electromechanical, standard pneumatic, and economy manual systems reflects validation burden and after-sales bundling intensity. Pricing pressure stems from mid-tier electronics contract manufacturers in Malaysia and Vietnam adopting asset-light leasing models that compress capital equipment margins. Tier-1 automotive OEMs in Germany and the United States exhibit lowest price sensitivity due to total cost of ownership calculations weighing downtime reduction against acquisition cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for fluoropolymer seal components. Precision servo motors concentrate in Japanese and German manufacturing clusters, while perfluoroelastomer O-rings draw from Chinese and Mexican fluorspar processing. Single-source vulnerability around specialized motion control components creates procurement bottlenecks for electromechanical dispensing head assembly. Distribution runs through Graco's North American distributor networks and Nordson's captive technology ecosystem for premium electromechanical systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from adhesive-dispensing convergence strategies that blur traditional equipment-chemistry boundaries and threaten standalone hardware margins.
For Market Incumbents: Insulate core electromechanical positioning through backward integration into precision motion control components, reducing exposure to Japanese and German servo motor supply bottlenecks. Deepen FDA 21 CFR Part 11 validation capabilities to filter out generalist competitors in medical device manufacturing segments. Cloud-connected process analytics represent the critical capability gap requiring defensive investment against outcome-based service contract competitors.
For New Entrants and Emerging Players: Mid-tier contract manufacturers in Tamil Nadu and Maharashtra automotive corridors represent the most penetrable entry point for asset-light equipment leasing models absorbing residual value risk. Third-party financing entities bundling maintenance and software updates into per-unit production fees offer a go-to-market angle that fragments traditional procurement authority. Target construction field applications in Southeast Asia where distributor networks stock manual systems for rapid deployment.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision electromechanical specialists with captive adhesive chemistry integration capabilities over standalone pneumatic volume providers. Long-term viability rests on outcome-based revenue streams from predictive maintenance contracts rather than transactional equipment sales. Watch for REACH substance authorization delays freezing European capital expenditure as the inflection signal indicating equipment requalification burden winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motion Control | Reduces servo motor supply vulnerability from Japanese and German concentration. |
| FDA Validation Protocol Investment | Creates margin pools in medical device manufacturing by filtering generalist vendors. |
| Cloud-Connected Process Analytics | Enables predictive maintenance contracts capturing recurring revenue from Busan-Ulsan clusters. |
| Asset-Light Leasing Model Expansion | Third-party financing absorbs residual value risk for mid-tier Malaysian contract manufacturers. |
| REACH-Compliant Mixing Chamber Redesign | Captures equipment requalification demand from European aerospace sealant applications. |
Research Methodology
Cross-validation between equipment OEM procurement interviews and adhesive supplier technical disclosures anchors the qualitative findings. Primary fieldwork engaged plant engineers at automotive battery pack facilities in Michigan and Stuttgart, procurement leads at Taiwanese semiconductor packaging operations, aftermarket service heads at distributor networks, and technical R&D directors at adhesive formulators. Secondary validation drew from EPA emissions compliance filings, REACH substance authorization databases, FDA 510(k) equipment clearances, and MIIT industrial upgrading directives. Bottom-up unit economics triangulate against top-down manufacturing capacity assessments.
Calibration against historical equipment shipment patterns and retrofit cycle timing refines projection accuracy across the analysis window. Segmentation dimensions include drive technology tier, industry vertical certification requirements, material chemistry reactivity class, and regional regulatory cluster stringency. CAGRs derive from installed base growth rates weighted by aftermarket service intensity. Forecast inputs incorporate PLI scheme incentive trajectories and ECHA evaluation timelines for isocyanate-containing formulations.
Practitioners should monitor REACH substance authorization delays and fluorspar mining output volatility for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Shrink - Sleeve Wrapping Machinery Market
Packaging Machinery
Enveloping & Stacking Machine Market
Packaging Machinery
Poly Bagging Machines Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Side Load Case Packing Machines Market
Packaging Machinery
Automatic Thermoforming Vacuum Machine Market
Packaging Machinery
Thermal Laminating Machine Market
Packaging Machinery
Twist Tie Machines Market
Packaging Machinery
Filling Machinery Market
Packaging Machinery
Vial Filling and Capping Machines Market
Packaging Machinery
Barcode Labeller Machine Market
Packaging Machinery
Capping Machine Market
Packaging Machinery
Pallet Stretch Wrapping Machines Market
Packaging Machinery
Sack Fillers Market
Packaging Machinery
Lamination Systems Market
Packaging Machinery
Tea Packing Machine Market