
 Cement Packaging Market | 2026-2036
Cement Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Cement Packaging Market Intelligence
The rise of large-scale infrastructure developers and ready-mix concrete producers as primary buyers is redrawing the competitive landscape for cement packaging. This shift favors suppliers with extensive logistical capabilities and bulk packaging formats. Holcim Group leverages its global footprint to serve multinational construction firms with standardized packaging solutions. In contrast, Votorantim Cimentos specializes in regional supply chains, particularly in Latin America, while HeidelbergCement AG competes through its integrated model, controlling both cement production and its packaging requirements.
Cement packaging encompasses materials and containers engineered to protect cement from moisture, air, and contamination during transport and storage. These solutions, often multi-ply paper or woven plastic bags, must meet specific strength requirements to prevent breakage and material loss. Within material types, plastic is gaining share over paper due to superior durability and weather resistance. The bags segment continues to dominate packaging types, although bulk container solutions are expanding for large infrastructure and ready-mix concrete end users.
Regulatory frameworks are increasingly focused on sustainability and material safety in cement packaging. The EU's REACH regulation governs chemical substances used in plastic packaging, while ISO standards define performance and testing criteria for cement sacks globally. These rules influence material selection and disposal practices for manufacturers. Consequently, suppliers must decide whether to invest in recyclable single-material packaging or focus on higher-performance, multi-material designs to meet divergent customer and regulatory demands.
Market Dynamics
The concentration of purchasing power among large-scale infrastructure developers and ready-mix concrete producers is the central force shaping the cement packaging market. This demand-side consolidation favors suppliers capable of providing high-volume, durable, and logistically efficient packaging solutions.
Growth Catalysts
- National Infrastructure Programs:Large-scale construction initiatives, particularly in countries like India, create sustained, high-volume demand for cement packaging that can withstand long-distance transport and varied storage conditions, as mandated by national development goals.
- Material Performance Upgrades:The transition from paper sacks to woven polypropylene (WPP) bags is driven by the latter's superior tear strength and moisture resistance, which significantly reduces material loss during handling and storage in humid climates.
- Sustainability Regulations:Policies under frameworks like the EU Green Deal encourage the use of recyclable and single-material packaging, creating demand for innovative plastic and paper solutions that meet both performance and environmental criteria.
Market Restraints
- Input Cost Volatility:The price of polypropylene and polyethylene resins, key raw materials for plastic bags, is directly linked to fluctuating global crude oil prices, creating margin pressure and pricing uncertainty for packaging manufacturers.
- Bulk Substitution:The adoption of bulk transportation systems, such as silos and tanker trucks by high-volume end-users like ready-mix concrete plants, directly displaces the need for bagged cement, capping market growth in that segment.
- Logistical Bottlenecks:Delivering packaged cement to remote or poorly accessible construction sites incurs high transportation costs and complex logistical planning, acting as a structural barrier for suppliers without extensive distribution networks.
Strategic Opportunities
- Smart Packaging Integration:Incorporating QR codes or RFID tags onto cement bags offers opportunities for enhanced traceability, inventory management, and anti-counterfeiting measures, providing a value-added service for large construction projects.
- Closed-Loop Recycling Models:Establishing partnerships with major construction firms to collect, clean, and reprocess used WPP bags presents an opportunity to create a circular supply chain and meet corporate sustainability mandates.
- African Market Expansion:Targeting emerging infrastructure projects across various African nations provides a significant geographic growth opportunity, as these projects require durable packaging suited for challenging logistical environments.
Industry Challenges
- Recycling Infrastructure Deficits:The absence of widespread, cost-effective collection and recycling facilities for post-consumer cement bags, especially those contaminated with cement residue, remains a primary operational hurdle to achieving circular economy goals.
- Capital-Intensive Production Shifts:The transition from manufacturing traditional multi-ply paper sacks to woven polypropylene bags requires substantial capital investment in new extrusion, weaving, and printing machinery, posing a barrier for smaller producers.
- Performance Standard Divergence:Navigating the differences between global ISO standards for cement sacks and specific regional or national performance requirements complicates product design, testing, and export strategies for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cement Packaging Market |
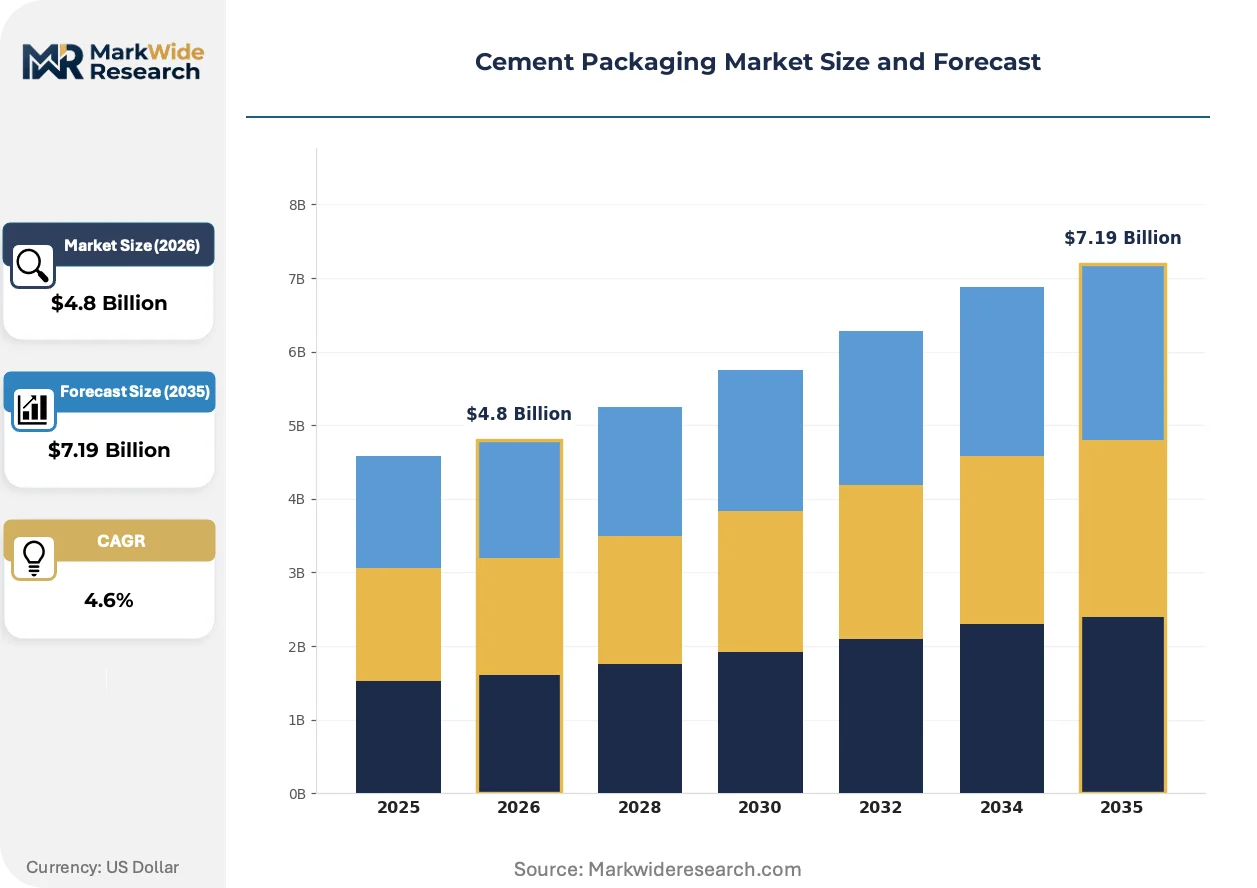
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bags, Containers, Bulk, Pails Material Type: Plastic, Paper, Fiberboard, Metal End User: Construction, Infrastructure, Ready-Mix Concrete, Research Distribution Channel: Direct Sales, Online Sales, Retail, Distributor |
| Companies Covered | Cemex SAB de CV, China National Building Material (CNBM), Holcim Group, Ash Grove Cement Company, Buzzi Unicem SpA, LafargeHolcim Ltd., CRH plc, Votorantim Cimentos, HeidelbergCement AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cement Packaging Market Strategic Shifts & Innovations
Innovation in cement packaging is driven by the twin demands for enhanced worksite efficiency and improved environmental sustainability. This creates a market where material science and digital technologies are being applied to solve long-standing challenges of waste and product integrity.
Advanced bag designs, such as self-dissolving or pulpable sacks, offer a significant evolution in packaging technology. Ready-mix concrete producers and on-site construction teams are adopting these solutions to reduce packaging waste and labor costs associated with bag disposal. This technology is bifurcating the market between low-cost commodity bags and higher-value, process-integrated packaging that becomes part of the final product mix.
Regulatory frameworks like the EU's REACH and the proposed Packaging and Packaging Waste Regulation (PPWR) are setting new benchmarks for material safety and circularity. These rules compel manufacturers to verify chemical compositions and increase the use of recycled content. The European packaging segment is most affected, accelerating investment in mono-material polypropylene bags that simplify recycling compared to composite paper-plastic alternatives.
A shift from transactional, spot-market purchasing toward long-term, integrated supply agreements is altering buyer behavior. This model often bypasses traditional building material distributors, favoring direct relationships between packaging suppliers and large-scale cement producers or construction firms. The trend is most prominent for megaprojects in the Middle East and Southeast Asia, where supply chain predictability is a critical success factor.
Cement Packaging Market Segmentation
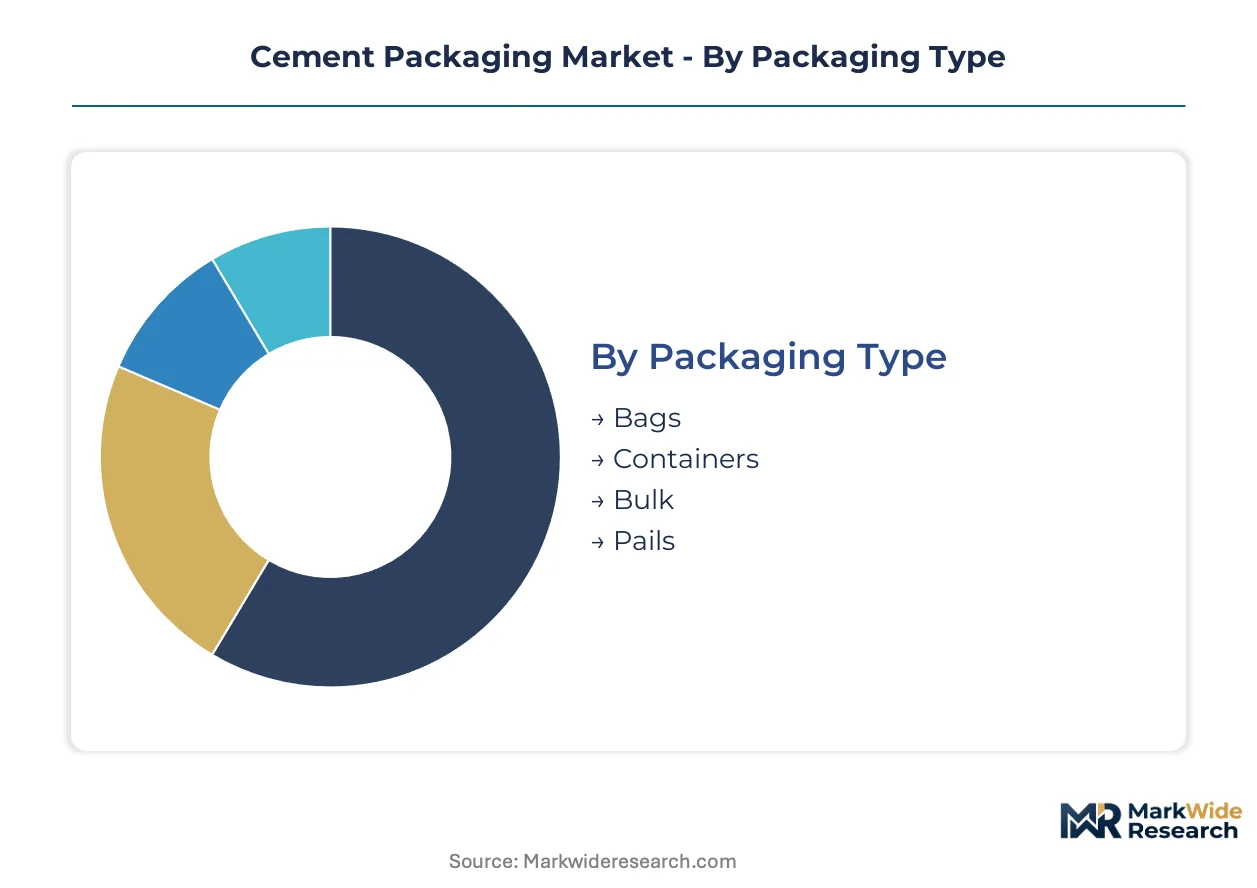
The Cement Packaging Market segmentation reveals how specialized solutions address diverse industrial requirements. Understanding these distinctions helps suppliers align product development with specific end-user demands and logistical challenges. This analysis delineates key areas of product differentiation and market concentration.
Packaging Type:
The choice of packaging type often dictates the distribution channel, reflecting the scale and logistical sophistication of the end-user.
- Bags:These refer to multi-ply paper or woven polypropylene sacks, typically holding 25kg or 50kg of cement. Demand concentrates in retail construction projects and smaller contractors across India, driven by ease of manual handling and widespread availability.
- Bulk:This segment includes large-volume solutions like silos, tanker trucks, and flexible intermediate bulk containers (FIBCs). Large infrastructure developers and ready-mix concrete producers in the Middle East utilize bulk formats for cost-effective, high-volume material transfer.
- Containers:These are specialized shipping containers or larger reusable bins designed for intermodal transport of cement.
- Pails:Smaller, rigid plastic or metal containers used for specialty cement products or repair kits, primarily in DIY and niche applications.
Bags dominate the installed base for cement packaging. Bulk solutions are where expansion concentrates for high-volume applications.
Material Type:
Material selection for cement packaging is primarily governed by performance requirements related to moisture protection, strength, and environmental impact.
- Plastic:Encompasses woven polypropylene (WPP) and polyethylene (PE) bags, known for superior moisture resistance and tear strength. Asia-Pacific construction projects increasingly favor plastic due to challenging weather conditions and long-distance transportation needs.
- Paper:Includes multi-ply kraft paper sacks, often with a plastic liner, providing breathability and traditional appeal. European markets still utilize paper bags, especially for specialized cement types, driven by established supply chains and recycling initiatives.
- Fiberboard:Used for smaller, specialized containers or secondary packaging, offering rigidity and stackability for specific product lines.
- Metal:Primarily for pails or drums holding highly specialized or moisture-sensitive cement additives, ensuring maximum product integrity.
Plastic materials are gaining share due to their durability. Paper remains significant for its established presence and evolving sustainable options.
End User:
End-user categories are differentiated by their purchasing volume and specific logistical demands for cement packaging.
- Construction:This segment includes general building contractors and residential developers who often purchase bagged cement through retail or distributors. Demand in Southeast Asian urban development projects requires diverse packaging sizes for varied site conditions.
- Ready-Mix Concrete:Producers require high volumes of cement, often delivered in bulk, directly to their batching plants. North American ready-mix operations prioritize efficient bulk transfer systems to minimize material handling costs and accelerate production.
- Infrastructure:Encompasses large-scale public works projects like roads, bridges, and dams, demanding durable packaging for bulk or high-volume bagged cement.
- Research:Laboratories and academic institutions requiring small quantities of specialized cement for material testing and experimental applications.
Ready-Mix Concrete and Infrastructure segments drive bulk packaging innovation. General Construction remains a primary consumer of traditional bagged formats.
Distribution Channel:
The supply chain configuration for cement packaging varies significantly based on the scale of the customer and product type.
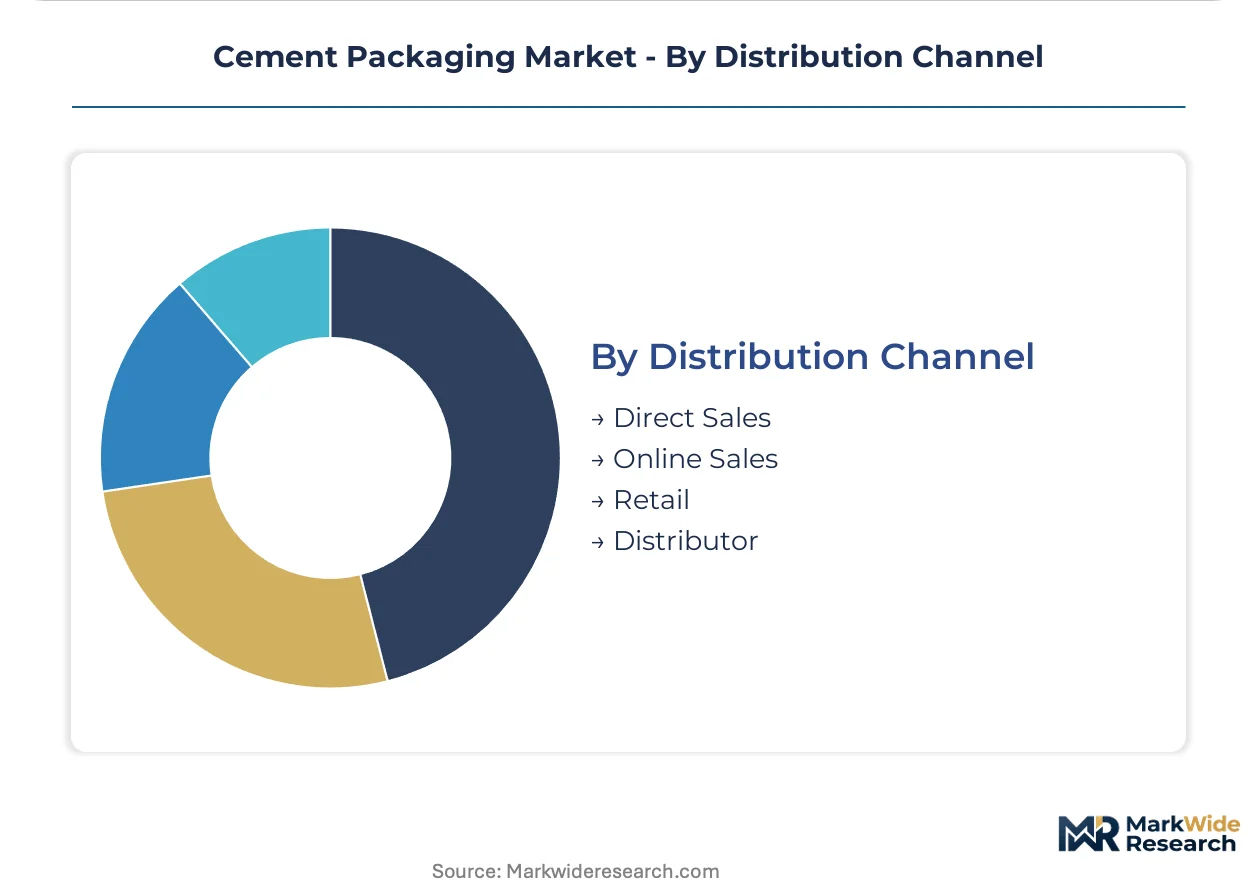
- Direct Sales:Packaging manufacturers engage directly with large cement producers or major construction firms for high-volume, customized orders. This channel is prevalent for megaprojects in the Middle East, ensuring consistent supply and technical support.
- Distributor:Independent distributors and building material suppliers stock and deliver packaged cement to smaller contractors and retail outlets. This channel serves fragmented markets across Europe, providing regional accessibility and inventory management.
- Online Sales:Emerging channel for specialized cement products or smaller quantities, often targeting DIY consumers or niche industrial buyers.
- Retail:Hardware stores and building supply centers selling bagged cement directly to individual consumers and small-scale contractors.
Direct Sales streamlines procurement for large-scale operations. The Distributor channel continues to facilitate broad market reach and regional availability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging solutions from East Asian manufacturers often supply the burgeoning infrastructure projects across Southeast Asia. This dynamic trade flow ensures a consistent supply of durable packaging materials. Demand for cement packaging is particularly high in regions undertaking extensive national development initiatives.
India
India's national infrastructure programs create sustained, high-volume demand for cement packaging. The country's national development goals mandate robust packaging for long-distance transport and varied storage conditions. Major construction hubs like Mumbai and Delhi-NCR drive the need for diverse packaging solutions.
China
China's rapid urbanization and extensive Belt and Road Initiative projects fuel substantial demand for cement packaging. The nation's dual carbon goals encourage the adoption of more sustainable and recyclable packaging materials. Industrial clusters in the Yangtze River Delta focus on high-volume, efficient packaging for large-scale construction.
United States
The United States experiences consistent demand from residential and commercial construction, alongside significant infrastructure upgrade projects. Environmental Protection Agency (EPA) regulations influence material safety and disposal practices for packaging. Growing metropolitan areas in Texas and Florida require efficient packaging logistics for expanding urban developments.
Germany
German construction prioritizes sustainable building practices and high-quality renovation projects, impacting packaging material choices. The EU Green Deal and REACH regulation compel manufacturers to develop recyclable and chemically compliant packaging solutions. Industrial regions like North Rhine-Westphalia focus on specialized packaging for diverse construction needs.
United Arab Emirates
The United Arab Emirates drives demand through ambitious megaprojects, including new cities and tourism infrastructure. Local building standards and environmental regulations shape the requirements for durable and often bulk packaging formats. Major urban centers such as Dubai and Abu Dhabi require reliable, high-volume packaging for continuous development.
Cement Packaging Market Key Industry Players
Player mix skews toward a tiered structure, encompassing globally integrated entities, specialized regional providers, and locally focused manufacturers. This market configuration favors suppliers adept at handling large volumes and offering logistically efficient solutions. Strategic archetypes include multinational conglomerates, regional specialists, and integrated cement producers. Dominant competitive moves involve geographic expansion into emerging markets and portfolio diversification to include both bulk and bagged formats.
Among globally integrated producers, Holcim Group leverages its extensive footprint to meet multinational construction firm requirements. Votorantim Cimentos exemplifies a regional specialist, focusing on supply chains predominantly in Latin America. HeidelbergCement AG represents an integrated model, controlling both cement production and its associated packaging needs. These companies anchor different segments of the market by offering solutions tailored to varied scales and geographical demands.
| Leading Market Players |
|---|
| Cemex SAB de CV |
| China National Building Material (CNBM) |
| Holcim Group |
| Ash Grove Cement Company |
| Buzzi Unicem SpA |
| LafargeHolcim Ltd. |
| CRH plc |
| Votorantim Cimentos |
| HeidelbergCement AG |
| Others |
Cost & Logistics Intelligence
The EU's REACH regulation and ISO standards gate both supply qualification and price differentiation, particularly for advanced cement packaging. These frameworks influence material sourcing and production costs, directly impacting market pricing.
Pricing Analysis
The pricing gap between traditional multi-ply paper sacks and woven polypropylene (WPP) bags reflects distinct material and production costs. Commodity spot pricing prevails for standard paper bags, while contract-based long-term offtake agreements are common for higher-performance WPP solutions. Price differentiation stems from material quality, customization level for branding, and geographic delivery costs. Input cost volatility, particularly for polypropylene resins, creates margin pressure, making large infrastructure developers and ready-mix concrete producers least price-sensitive for bulk solutions, while small contractors and retail buyers are most sensitive to bagged cement costs.
Supply Chain Analysis
Port congestion and container availability directly influence inbound logistics costs for raw materials like polypropylene resins. Geographic supply concentration for these resins centers on China, India, and other East Asian manufacturing hubs. The supply chain relies on polypropylene and polyethylene resins, alongside kraft paper pulp, as key raw material dependencies, making commodity price volatility, tied to global crude oil prices, a significant structural risk. Distribution runs primarily through direct sales to large cement producers and construction firms, complemented by distributors and retail channels for smaller buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cement packaging market is experiencing high-growth disruption, driven by the emergence of self-dissolving and pulpable bags. These advanced solutions are fundamentally altering waste management and labor efficiency on construction sites.
For Market Incumbents: Compound existing global footprints by accelerating investment in woven polypropylene (WPP) bag production facilities, particularly in emerging markets like Africa. Mitigate the threat of bulk substitution by developing hybrid packaging solutions that offer both bagged convenience and bulk-like efficiency for specific project phases. Leverage integrated models to control material sourcing for mono-material WPP bags, addressing sustainability regulations like the EU Green Deal. Prioritize R&D into advanced material science to maintain performance leadership against new entrants.
For New Entrants and Emerging Players: Certification fast-tracks for sustainable materials, such as those meeting ISO 14021 for recycled content, offer a strategic entry point for new players. Target the underpenetrated African market with durable, weather-resistant WPP bags suited for challenging logistical environments. Focus on niche specialty cements or DIY applications with innovative, smaller-format packaging that simplifies handling and reduces waste. A go-to-market angle emphasizing circularity and digital traceability, using QR codes, can differentiate offerings from established commodity suppliers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across advanced packaging material production, presenting opportunities for strategic investment in the cement packaging market. Long-term viability is strong, driven by sustained global infrastructure development over the next 5-10 years. Seek acquisition targets among specialized woven polypropylene manufacturers with strong R&D in mono-material designs or smart packaging technology firms. The adoption rate of closed-loop recycling models for WPP bags is a critical signal to watch as an inflection indicator for circular economy integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expands woven polypropylene production to meet rising demand from large infrastructure projects. |
| Green Manufacturing Transition | Aligns production processes with sustainability regulations, reducing environmental impact of packaging materials. |
| Long-term Supply Agreements | Secures stable demand and predictable revenue streams with major cement producers and construction firms. |
| Product Launch: Advanced Bags | Introduces self-dissolving or pulpable sacks, reducing on-site waste and labor for end-users. |
| Geographic Expansion: Africa | Penetrates high-growth African markets with durable packaging solutions for infrastructure development. |
Research Approach
A spread of perspectives from cement producers, packaging manufacturers, large infrastructure developers, and ready-mix concrete plant managers converged on the working assumptions for this analysis. Primary interviews with these industry stakeholders provided qualitative insights, which were then validated through secondary research. This included national infrastructure reports, trade association statistics, material science journals, and regulatory filings. A combination of bottom-up data aggregation and top-down market sizing ensured comprehensive coverage.
Packaging Type, Material Type, End User, Distribution Channel, and material performance grade constituted the segmentation dimensions modeled across the analysis window. The analytical framework integrated historical growth rates with projected future trends derived from regression analysis. Compound Annual Growth Rates (CAGRs) were calculated based on volume and value projections. Key industry-specific forecast inputs included infrastructure spending forecasts and raw material price trends.
Decision-makers should treat outputs as directional under the base assumptions of stable geopolitical conditions and consistent regulatory enforcement; material deviation would warrant model refresh. Forecasts reflect these documented assumptions. Unforeseen technological breakthroughs in bulk handling or rapid shifts in global trade policies represent significant risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Greaseproof Sheets Market
Packaging Materials
Thermal Lamination Films Market
Packaging Materials
Sealed Wax Packaging Market
Packaging Materials
Cargo Moisture Control Products Market
Packaging Materials
Thailand Packaging Market
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Neoprene Coffee Sleeves Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Packaging Inserts Market
Packaging Materials
China Packaging Market
Packaging Materials
Floppy Disk Liner Market
Packaging Materials
Plastic Strapping Materials Market
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Textile Packaging Market
Packaging Materials
Expendable Packaging Market
Packaging Materials
Nonwoven Packaging Market